
 Loan Brokers Market | 2026-2036
Loan Brokers Market Size, Share, and Industry Trends Forecast 2026-2036
Loan Brokers Market Foresight
Commission-based origination services is shifting toward flat-fee and subscription pricing models as borrowers demand cost transparency. Rocket Mortgage leverages its proprietary technology platform to automate pre-approval workflows and reduce cycle times. United Wholesale Mortgage anchors its competitive position through exclusive broker partnerships and same-day underwriting capabilities. Fairway Independent Mortgage specializes in government-backed loan products, sustaining volume through FHA and VA channel expertise.
Loan brokers function as intermediaries connecting borrowers with capital providers, earning fees through origination, processing, and placement activities while managing documentation, rate shopping, and compliance verification across multiple lender networks. Residential service type dominates transaction volume due to persistent home purchase and refinancing activity, though commercial placement commands superior per-deal economics. First-time buyers within customer type segments show elevated conversion rates through digital onboarding tools, while wholesale distribution channel relationships determine broker access to competitive rate sheets and expedited closing timelines.
The US Consumer Financial Protection Bureau enforces Loan Originator Compensation rules under Regulation Z, limiting broker steering incentives and reshaping fee structures. State-level licensing requirements administered through the Nationwide Multistate Licensing System create compliance barriers that favor capitalized multi-state operators over single-location brokers. Stakeholders must monitor emerging state usury caps and federal fair lending enforcement patterns that could restrict product availability or alter broker-lender economic arrangements.
Market Dynamics
Digital origination platforms are compressing broker margins while simultaneously expanding addressable borrower pools through automated underwriting and instant rate comparison tools.
Growth Catalysts
- Sun Belt Migration:Population inflows into Texas, Florida, and Arizona are elevating residential origination volumes and broker commission pools in these high-growth corridors.
- Regulation Z Compliance:The US Consumer Financial Protection Bureau's compensation disclosure mandates are accelerating industry consolidation toward scaled, compliant operators.
- API-First Lender Connectivity:Real-time pricing feeds from wholesale lenders are reducing borrower shopping friction and shortening broker conversion cycles.
Market Restraints
- Interest Rate Volatility:Federal Reserve policy uncertainty is compressing refinancing activity and destabilizing broker revenue predictability across origination channels.
- License Fragmentation:State-level NMLS requirements create compliance cost barriers that disadvantage single-location brokers against multi-state platforms.
- Direct Lender Disintermediation:Rocket Mortgage and similar captive retail channels are capturing borrower relationships that previously flowed through independent brokers.
Strategic Opportunities
- Small Business Credit Gap:Underpenetrated Main Street lending represents expansion potential as digital platforms simplify SBA and alternative commercial origination workflows.
- Subscription Pricing Models:Flat-fee advisory structures are emerging as borrower preference shifts away from opaque commission-based compensation.
- Same-Day Underwriting:Automated verification partnerships with credit bureaus and asset aggregators enable broker differentiation through compressed closing timelines.
Industry Challenges
- Data Security Compliance:Gramm-Leach-Bliley Safeguards Rule updates require broker investment in encryption, access controls, and incident response infrastructure.
- Talent Acquisition:Licensed originator shortages in high-volume states are inflating compensation costs and constraining broker capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Loan Brokers Market |
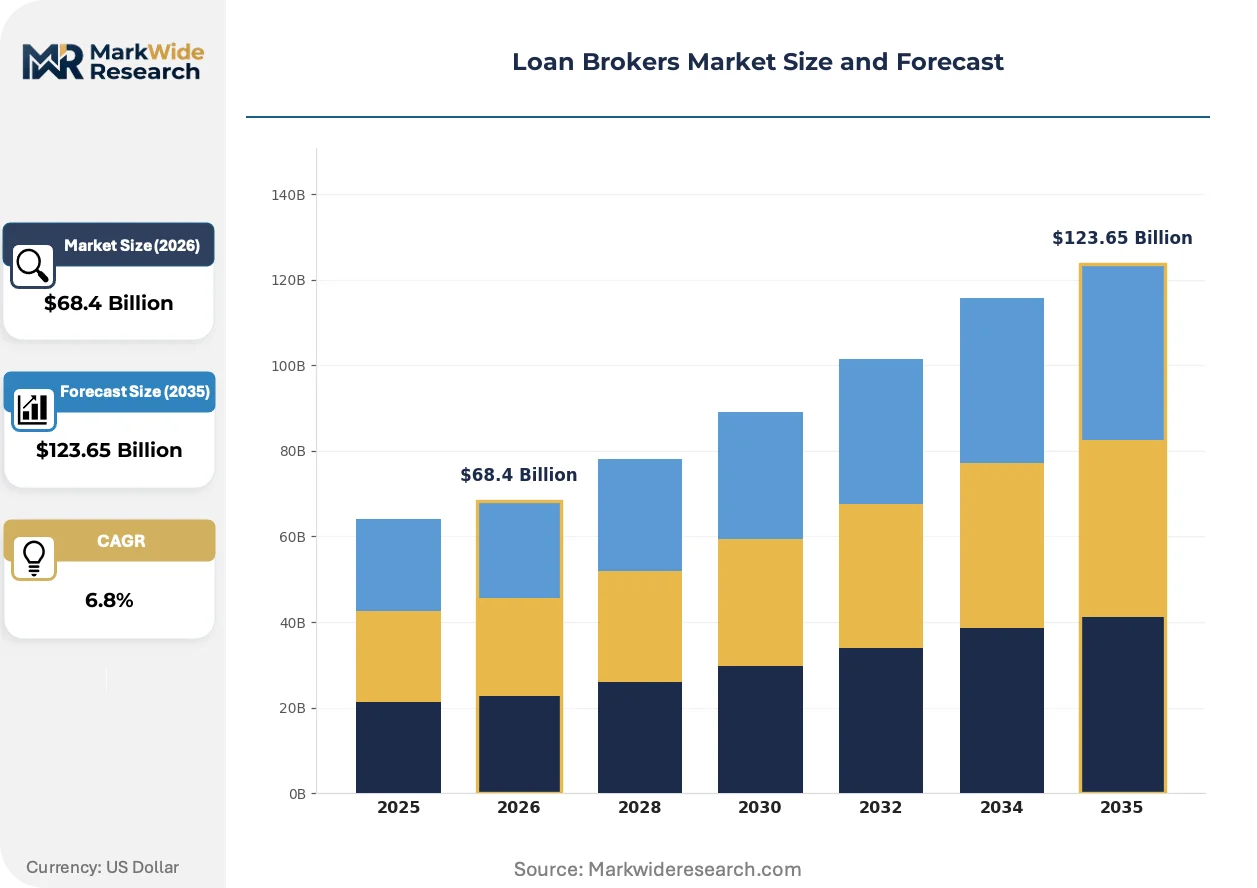
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential, Commercial, Auto, Personal Customer Type: First-Time Buyers, Refinancers, Investors, Entrepreneurs Loan Type: Fixed-Rate, Variable-Rate, FHA, VA Distribution Channel: Online, In-Person, Referral, Wholesale |
| Companies Covered | Fairway Independent Mortgage, Newmark, United Wholesale Mortgage, Berkadia, CBRE, Rocket Mortgage, Guild Mortgage, Option One Lending Inc., CrossCountry Mortgage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Loan Brokers Market Shifts & Advancements
Automation is restructuring how borrowers discover, compare, and commit to loan products, with technology vendors and regulatory bodies simultaneously reshaping broker economics and operational requirements.
Artificial intelligence-powered document classification is rewriting how brokers process income verification and asset documentation. First-time homebuyers and self-employed borrowers are adopting these tools fastest due to complex paperwork requirements. The technology is compressing processor headcount needs while elevating error rates as a competitive differentiator among broker platforms.
The US Consumer Financial Protection Bureau continues refining Loan Originator Compensation rules under Regulation Z. These updates limit steering incentives and force fee structure transparency across broker-lender arrangements. Wholesale distribution channels face the steepest compliance adaptation costs as they renegotiate economic splits with originator networks.
Borrower preference for rate transparency is fragmenting traditional referral-based acquisition models. Digital comparison marketplaces and direct-to-consumer platforms are displacing realtor and builder referral dominance in high-volume purchase markets. This shift is most pronounced in Arizona, Nevada, and Colorado where tech-savvy inbound migrants bypass established broker relationships.
Loan Brokers Market Segmentation
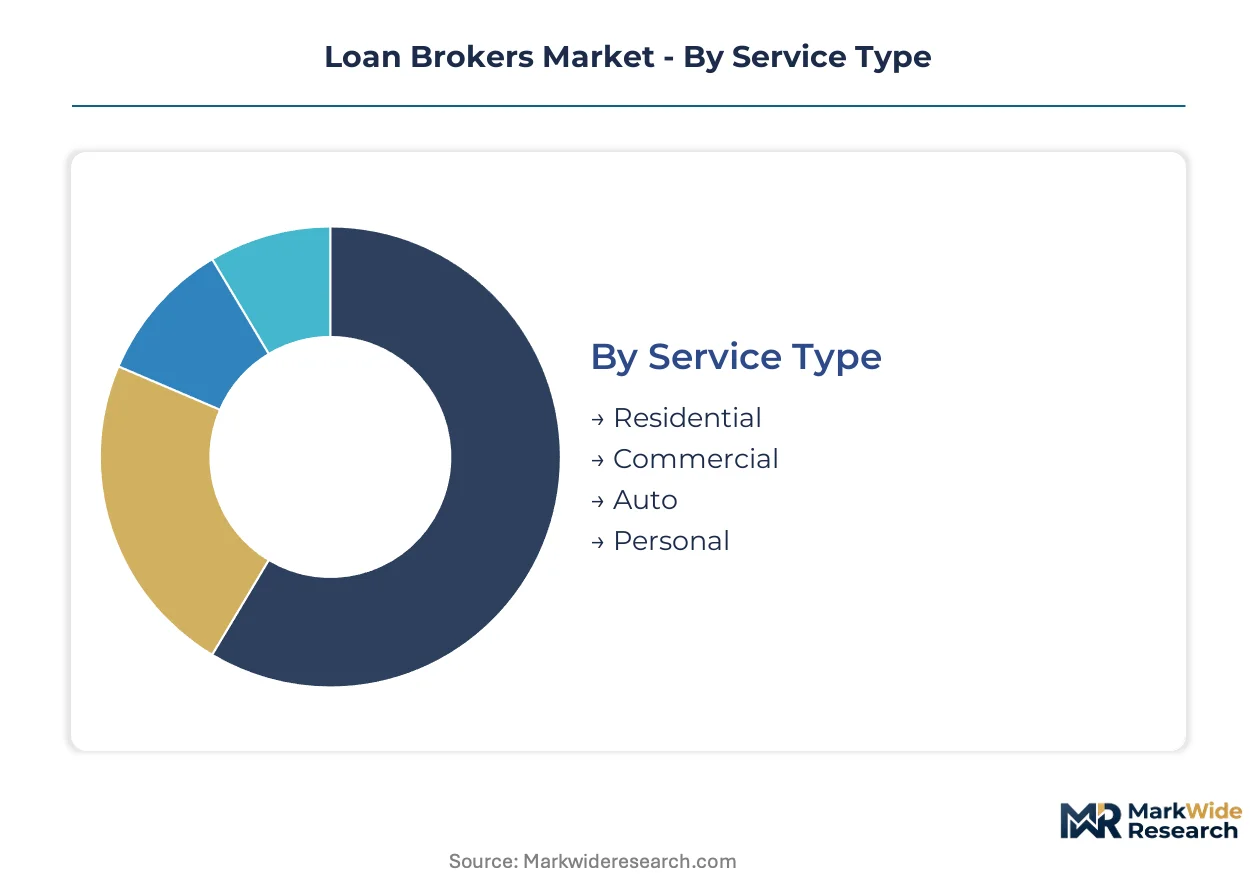
Loan broker segmentation reveals how service specialization, borrower profiles, and channel economics create distinct operational models. Understanding these divisions helps stakeholders allocate technology investments and compliance resources across divergent margin structures and regulatory exposures.
Service Type:
Upgrade cycles in broker technology platforms favor operators who can amortize automation costs across higher transaction volumes or superior per-deal economics.
- Residential:Purchase and refinance placement for single-family and multi-family housing dominates transaction counts. Sun Belt states including Texas, Florida, and Arizona concentrate origination volume as inbound migration sustains housing demand.
- Commercial:Office, retail, industrial, and multifamily property financing commands elevated fees per placement. Entrepreneurs and real estate investors in high-growth corridors drive demand as SBA and conventional workflows digitize.
- Auto:Vehicle purchase and lease arrangement services connect borrowers with captive finance companies and independent lenders.
- Personal:Unsecured debt consolidation and specialty purpose loans round out broker service portfolios with faster processing cycles.
Volume placements concentrate in Residential; the faster expansion belongs to Commercial.
Customer Type:
Cost tier differentiation separates brokers serving price-sensitive mass-market borrowers from those capturing premium fees through complex financial situations.
- First-Time Buyers:Entry-level purchasers navigating FHA and low-downpayment programs require extensive documentation guidance. Digital onboarding tools from credit bureaus and asset aggregators compress conversion cycles for this segment.
- Refinancers:Rate-sensitive homeowners seeking term or cash-out restructuring generate volume spikes during Federal Reserve easing cycles. Interest rate volatility destabilizes revenue predictability for brokers dependent on this cohort.
- Investors:Real estate professionals pursuing portfolio leverage or fix-and-flip capital access specialized non-owner-occupied products.
- Entrepreneurs:Small business owners accessing SBA and alternative commercial credit represent underpenetrated expansion territory for digitized origination platforms.
First-Time Buyers generate the highest conversion rates through automated tools; Entrepreneurs offer the steepest expansion trajectory as platforms simplify commercial workflows.
Loan Type:
Application-specific expertise determines broker access to wholesale rate sheets and expedited underwriting partnerships.
- Fixed-Rate:Thirty-year and fifteen-year amortizing products with locked interest exposure dominate purchase market preferences. Borrowers in high-migration Sun Belt corridors favor payment certainty amid economic uncertainty.
- Variable-Rate:Adjustable products tied to index movements attract rate-risk-tolerant borrowers and short-term holders. Initial rate discounts compete against long-term fixed alternatives in rising rate environments.
- FHA:Government-insured programs with reduced downpayment requirements serve credit-constrained first-time purchasers.
- VA:Veteran benefit programs with zero-down structures and competitive pricing sustain volume through specialized broker expertise.
Fixed-Rate products anchor transaction volume; FHA placements are climbing the fastest as entry-level affordability constraints intensify.
Distribution Channel:
Margin structures diverge sharply between high-touch relationship models and technology-enabled self-service platforms.
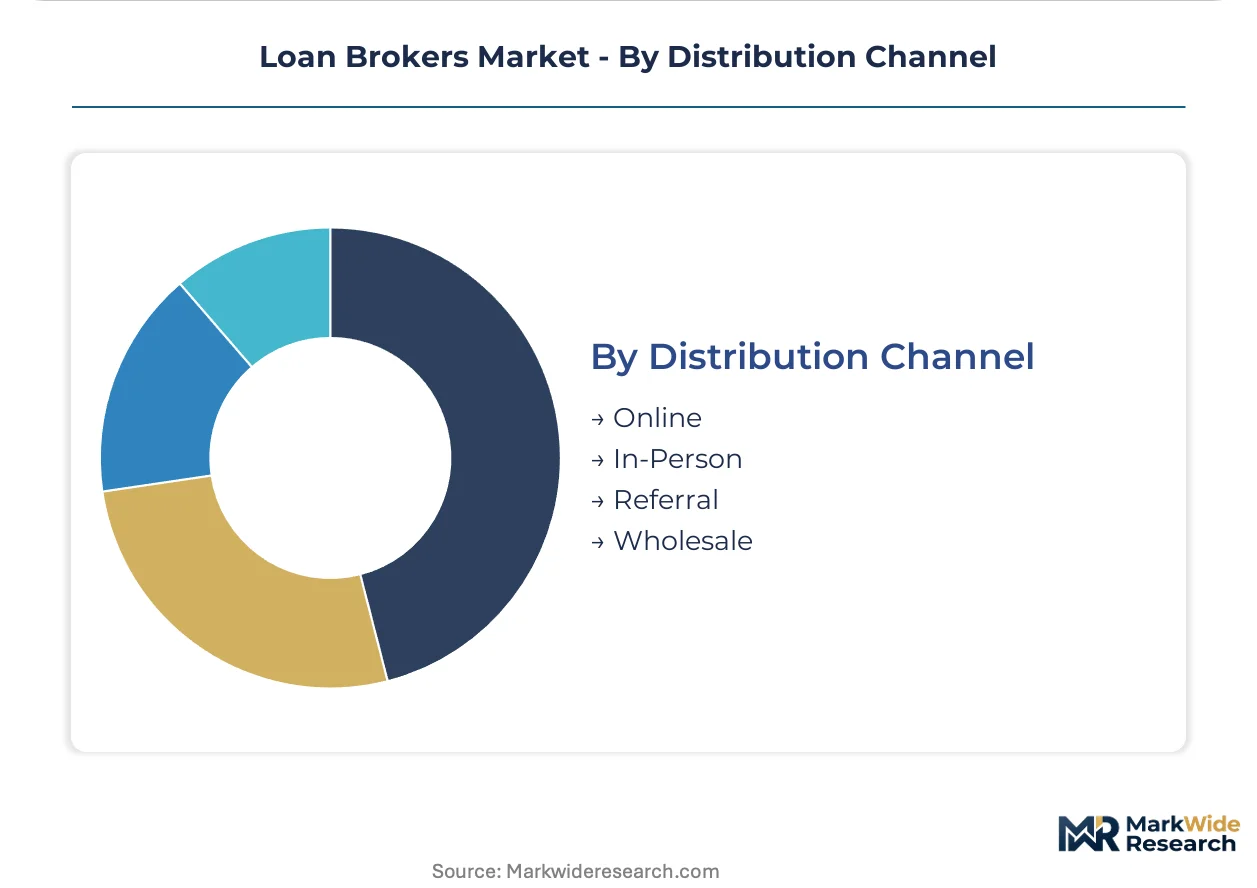
- Online:Digital comparison marketplaces and direct-to-consumer interfaces reduce borrower shopping friction. Tech-savvy inbound migrants in Arizona, Nevada, and Colorado bypass traditional referral relationships through these channels.
- In-Person:Branch-based and home-visit origination maintains relevance for complex documentation situations and relationship-dependent borrowers.
- Referral:Realtor and builder-directed lead flow faces displacement as digital transparency fragments traditional acquisition dominance.
- Wholesale:Exclusive broker partnerships with lenders provide access to competitive rate sheets and same-day underwriting capabilities.
Wholesale relationships determine competitive positioning for established brokers; Online channels are gaining share fastest among younger and inbound-migrant demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates the majority of loan origination volume, while Canada and Australia concentrate broker activity in major metropolitan corridors. Broker penetration varies sharply by regulatory environment and wholesale lender network density.
United States
Sun Belt migration into Texas, Florida, and Arizona sustains residential origination demand. The Consumer Financial Protection Bureau enforces Regulation Z compensation disclosure rules that favor scaled, multi-state operators. Dallas-Fort Worth and Houston anchor the nation's highest-volume wholesale broker clusters.
Canada
Major urban centers in Ontario and British Columbia concentrate mortgage broker activity amid constrained housing supply. The Financial Consumer Agency of Canada supervises broker conduct under federal mortgage regulations. Toronto and Vancouver host the dominant independent broker networks serving purchase and refinance flows.
Australia
Sydney and Melbourne drive mortgage broker volume through broker-originated home loan market share above 60 percent. The Australian Securities and Investments Commission administers licensing and best-interest duty obligations. Queensland's southeast corridor represents the fastest-expanding origination territory for digital-enabled broker platforms.
United Kingdom
London and Southeast England concentrate mortgage advisory activity amid elevated property values and complex income documentation. The Financial Conduct Authority regulates broker advice standards and commission disclosure. Manchester and Birmingham emerge as secondary hubs where technology-enabled brokers capture first-time buyer segments.
Germany
Low homeownership rates and conservative lending culture constrain broker penetration relative to Anglo-Saxon markets. BaFin supervises mortgage credit regulations under EU Consumer Credit Directive implementation. Munich and Frankfurt host specialized brokers serving high-net-worth and expatriate borrower segments.
Loan Brokers Market Competitive Landscape
Top-tier vendors anchor wholesale and direct-to-consumer distribution, while mid-tier regional specialists compete on relationship depth and product specialization. The market structure tilts toward consolidation as technology investment requirements and compliance scale advantages compound. Three archetypes dominate: technology-integrated direct lenders, wholesale-exclusive broker networks, and government-product specialists. Competitive moves center on exclusive partnership arrangements and same-day underwriting capability investments.
Among technology-integrated direct lenders, Rocket Mortgage exemplifies the automated pre-approval workflow archetype. United Wholesale Mortgage occupies a position within the wholesale-exclusive tier, anchoring broker network relationships. Fairway Independent Mortgage represents the government-product specialist archetype, with FHA and VA channel expertise distinguishing its positioning.
| Leading Market Players |
|---|
| Fairway Independent Mortgage |
| Newmark |
| United Wholesale Mortgage |
| Berkadia |
| CBRE |
| Rocket Mortgage |
| Guild Mortgage |
| Option One Lending Inc. |
| CrossCountry Mortgage |
| Others |
Supply & Pricing Matrix
Licensed originator concentration in high-volume Sun Belt states compresses compensation costs for digital-enabled platforms while inflating fees for relationship-dependent incumbents, widening pricing-tier spreads between technology-integrated and traditional broker models.
Pricing Analysis
Margin tightening in commission-based tiers reflects digital platform compression as automated underwriting tools reduce borrower acquisition costs. Three-tier pricing structure across premium advisory, standard placement, and economy self-service levels separates brokers by documentation complexity and speed-to-close guarantees. Cost-down pressure on traditional commission models accelerates because API-first lenders bypass broker markups through direct rate feeds. First-time buyers exhibit highest price sensitivity; investors and entrepreneurs demonstrate lowest sensitivity due to complex financing requirements.
Supply Chain Analysis
Freight costs for document courier services and notary networks vary sharply across wholesale lender distribution footprints. Technology infrastructure concentrates in the United States, Canada, and Australia where regulatory frameworks support digital origination platforms. Raw material dependencies center on credit bureau data feeds, cloud computing capacity, and compliance software licenses. Single-source vulnerability sits with dominant credit scoring aggregators. Distribution runs through wholesale lender networks, direct-to-consumer platforms, and referral partnerships with real estate professionals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The loan broker market occupies a technology-transition phase where AI-powered document classification and automated underwriting partnerships are displacing legacy processor-heavy workflows.
For Market Incumbents: Acquire licensed originator talent pools in Texas, Florida, and Arizona to secure capacity in high-migration corridors facing talent shortages. Consolidate compliance infrastructure across multi-state NMLS requirements to neutralize regulatory cost advantages of scaled competitors. Direct lender disintermediation by Rocket Mortgage and similar platforms threatens independent broker volume; defensive API integrations with wholesale lenders preserve rate sheet access.
For New Entrants and Emerging Players: Technology-first automated verification partnerships with credit bureaus and asset aggregators enable same-day underwriting differentiation against incumbent cycle times. Underpenetrated small business credit gaps in Main Street lending offer expansion territory as SBA workflows digitize. White-space concentration sits with entrepreneur segments in high-growth Sun Belt metros; go-to-market positioning through subscription pricing models captures borrower preference shifts away from opaque commissions.
For Investors and Strategic Acquirers: Re-rating potential sits with scaled multi-state operators given Regulation Z compliance consolidation favoring capitalized platforms over single-location brokers. Long-term viability frames around technology-enabled cost structures and exclusive wholesale partnerships sustaining margin defensibility. Watch Federal Reserve policy trajectory as inflection signal for refinancing volume volatility affecting broker revenue predictability.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Lender Integration | Real-time pricing feeds from United Wholesale Mortgage and similar wholesale channels reduce borrower shopping friction. |
| Same-Day Underwriting Capability | Automated verification partnerships with credit bureaus compress closing timelines and differentiate broker platforms. |
| Subscription Pricing Launch | Flat-fee advisory structures capture borrower preference shifts away from opaque commission-based compensation models. |
| Multi-State License Consolidation | NMLS compliance scale advantages favor capitalized operators over fragmented single-location broker networks. |
| Small Business Credit Platform | Digitized SBA and alternative commercial origination workflows address underpenetrated Main Street lending gaps. |
Research Methodology
Multi-period observation of origination volume trends, broker compensation structures, and regulatory enforcement patterns anchored the trend analysis, supplemented by interviews with wholesale lender executives, independent broker operators, compliance officers, and technology platform vendors. Secondary validation drew from NMLS licensing databases, Consumer Financial Protection Bureau enforcement releases, SEC filings from publicly traded mortgage platforms, and state-level origination volume reports. Bottom-up transaction counting across service type and customer segments triangulated against top-down market sizing from macroeconomic housing indicators.
Input-output matrices modeled relationships between Federal Reserve policy trajectories, Sun Belt migration flows, and digital platform adoption rates across the projection horizon. Segmentation dimensions included service type, customer profile, loan product category, and distribution channel complexity. CAGRs derived from regression analysis of historical origination cycles against demographic and interest rate variables. Industry-specific forecast inputs incorporated wholesale lender rate sheet dynamics and Regulation Z compliance cost trajectories.
Several conditions sit outside the modeled scope, including extreme interest rate volatility scenarios, federal usury cap legislation, and wholesale lender consolidation events. Forecasts reflect documented assumptions about technology adoption curves and regulatory enforcement intensity. Stakeholders should weight assumptions against their own operating context and risk tolerance for revenue predictability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
US Auto Loan Market
Loans and Leasing
Europe Auto Loan Market
Loans and Leasing
Vehicle Leasing Market
Loans and Leasing
Global Commercial Loan Software Market
Loans and Leasing
Global Financial Leasing Market
Loans and Leasing
Peer-To-Peer Lending Market
Loans and Leasing
Canada Home Equity Lending Market
Loans and Leasing
Global Automotive Fleet Leasing Market
Loans and Leasing
Mortgage Lending Market
Loans and Leasing
France Car Loan Market
Loans and Leasing
South Korea Car Loan Market
Loans and Leasing
Housing Finance Market
Loans and Leasing
Brazil Car Loan Market
Loans and Leasing
E-Scooter Financing Market
Loans and Leasing
Car Leasing Market
Loans and Leasing
Qatar Mortgage/Loan Brokers Market