
 Global Mortgage Lender Market | 2026-2036
Global Mortgage Lender Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mortgage Lender Market Outlook
First-time buyers is reorganizing demand composition across the mortgage lending landscape. Rocket Mortgage leverages proprietary digital underwriting engines to compress closing timelines. JPMorgan Chase sustains balance-sheet depth for jumbo and portfolio retention strategies. Wells Fargo anchors correspondent lending relationships with regional banks and credit unions.
A mortgage lender is a financial institution or intermediary that originates, funds, and services loans secured by real property, typically evaluating borrower creditworthiness through debt-to-income ratios, loan-to-value thresholds, and collateral appraisal protocols. Its commercial purpose centers on generating interest income while managing prepayment risk, default exposure, and duration mismatches through origination fees and secondary market sales. Fixed rate products dominate origination volumes in low-rate environments where borrowers seek payment certainty, while online platforms represent the fastest-growing delivery model as fintech infrastructure reduces per-loan acquisition costs. Conventional loans occupy the deepest margin pools due to standardized underwriting and government-sponsored enterprise eligibility.
FHA guidelines in the United States, Basel III standards from the Bank for International Settlements, and EU Mortgage Credit Directive frameworks collectively shape capital reserves, consumer disclosure requirements, and product suitability standards across jurisdictions. These regulations constrain leverage ratios, mandate stress-testing protocols, and standardize comparison metrics that directly influence lender product design and geographic market access. Stakeholders must monitor central bank rate trajectories and housing affordability indices to calibrate origination mix between purchase and refinance cycles.
Market Dynamics
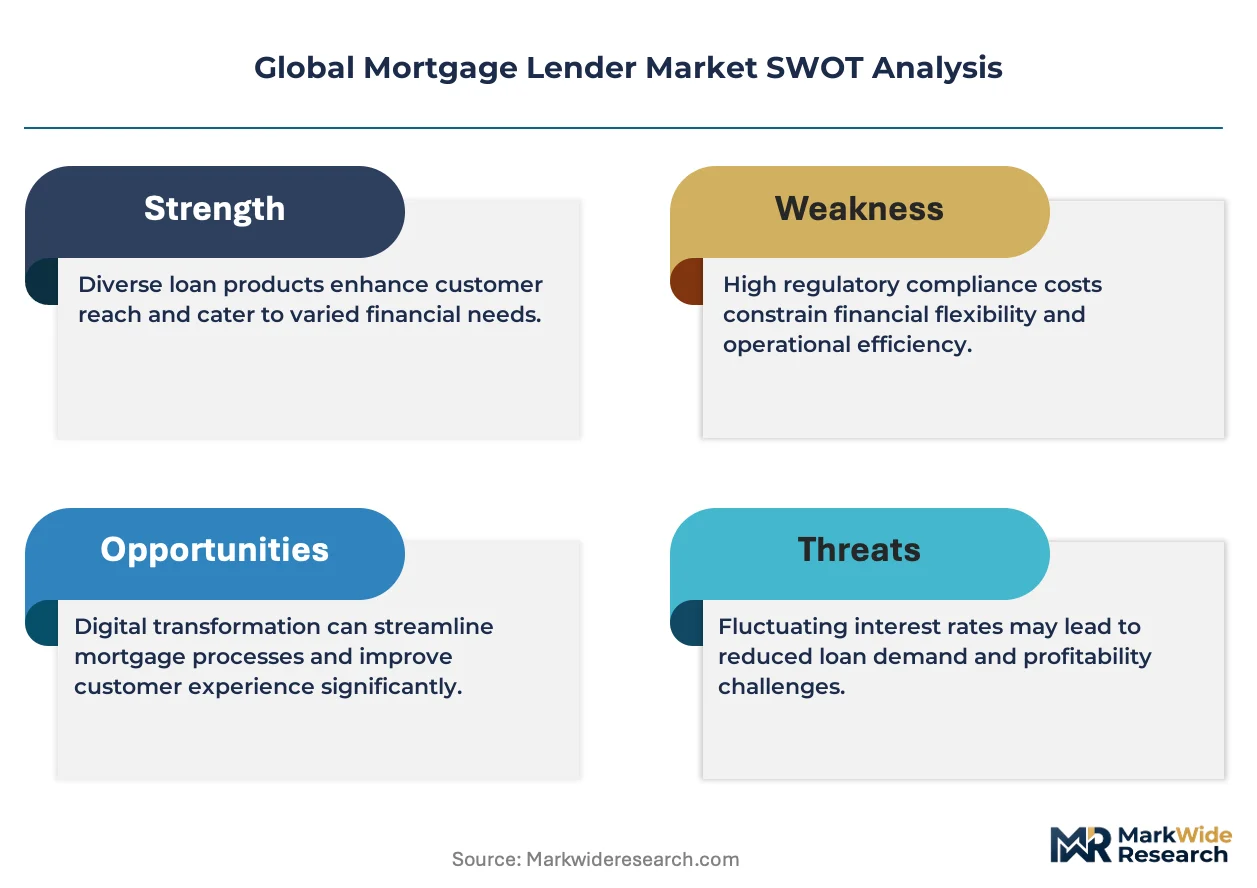
Digital underwriting infrastructure is compressing origination timelines while Basel III capital adequacy frameworks force lenders to restructure risk-weighted asset portfolios, creating divergent competitive paths between balance-sheet-heavy and originate-to-sell business models.
Growth Catalysts
- FHA Streamline Refinance Programs:US government-sponsored liquidity facilities sustain secondary market depth for government-insured products, expanding credit access for borrowers with elevated loan-to-value ratios.
- API-First Origination Stacks:Open banking protocols enable real-time income verification and automated asset documentation, slashing per-loan processing labor hours.
- First-Time Buyer Demographics:Millennial and Gen Z household formation concentrates demand in entry-level purchase mortgages, reshaping product mix toward lower down-payment structures.
Market Restraints
- Duration Mismatch Risk:Fixed-rate portfolio retention exposes lenders to interest rate volatility that compresses net interest margins when funding costs rise.
- Appraiser Capacity Bottlenecks:Licensed residential appraiser shortages in the United States extend closing timelines and elevate borrower cancellation rates.
- Basel III Output Floor Constraints:Standardized approach capital requirements limit internal ratings-based optimization for mortgage exposures, elevating regulatory capital charges.
Strategic Opportunities
- India's Housing for All Mandate:Credit-linked subsidy schemes and priority sector lending quotas create origination volume tailwinds for lenders establishing presence in tier-2 and tier-3 cities.
- Embedded Finance Distribution:Property technology platforms and real estate marketplaces integrate mortgage pre-qualification at point of listing discovery, capturing borrower intent upstream.
- EU Green Mortgage Standards:Energy performance certificate-linked pricing differentials reward lenders originating against energy-efficient collateral with reduced risk weights.
Industry Challenges
- Legacy Core System Modernization:Decades-old loan origination software architectures impede real-time data integration with fintech point solutions, requiring expensive middleware layers.
- Qualified Mortgage Documentation Burden:Ability-to-repay rule compliance demands extensive verification workflows that inflate operational costs for non-depository lenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mortgage Lender Market |
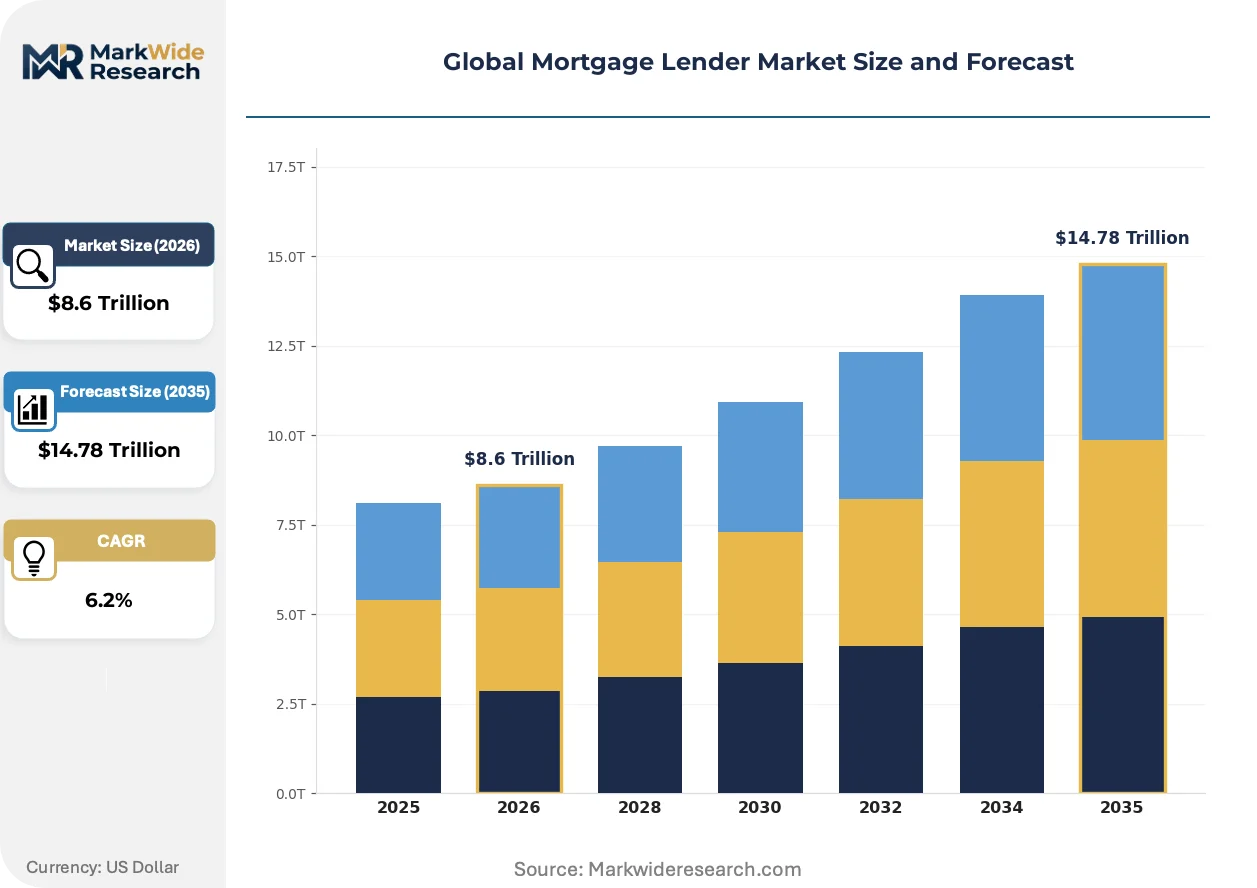
| Market Size in 2026 | $8.6 Trillion |
| Market Size in 2035 | $14.78 Trillion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fixed Rate, Adjustable Rate, Interest Only, FHA Loans Customer Type: First-time Buyers, Refinancers, Investors, Commercial Clients Offering: Conventional Loans, VA Loans, Jumbo Loans, Subprime Loans Delivery Model: Online Platforms, Traditional Banks, Credit Unions, Mortgage Brokers |
| Companies Covered | United Wholesale Mortgage, Rocket Mortgage, CrossCountry Mortgage, Bank of America, JPMorgan Chase, Wells Fargo, China Zheshang Bank, Mitsubishi UFJ Financial Group, BNP Paribas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mortgage Lender Market Strategic Shifts
Artificial intelligence and alternative data ingestion are fragmenting traditional credit assessment methodologies, splitting the market between conventional FICO-dependent underwriting and machine-learning-driven approval engines.
Automated valuation models are bifurcating property appraisal workflows. Desktop valuation algorithms leverage multiple listing service data and public records to estimate collateral value without physical inspection. Portfolio lenders and government-sponsored enterprises adopt hybrid appraisal waivers for low-risk refinance transactions. This technology is compressing appraisal turn times from weeks to hours while generating regulatory scrutiny over algorithmic bias and geographic coverage gaps.
The EU Mortgage Credit Directive's cross-selling restrictions constrain how lenders bundle ancillary insurance and payment protection products with origination. Member state competent authorities enforce standardized annual percentage rate disclosure formats that facilitate direct product comparison. Non-bank lenders in Germany and France respond by unbundling product components and competing on transparent fee structures rather than integrated package pricing.
Self-service borrower portals displace loan officer-mediated application intake. First-time buyers in the United Kingdom and Australia initiate pre-approval requests through mobile-optimized interfaces that guide document upload and income verification. This channel shift concentrates volume with lenders investing in conversational AI for application support, while traditional branch-dependent institutions face customer acquisition cost disadvantages in purchase-heavy markets.
Global Mortgage Lender Market Segmentation
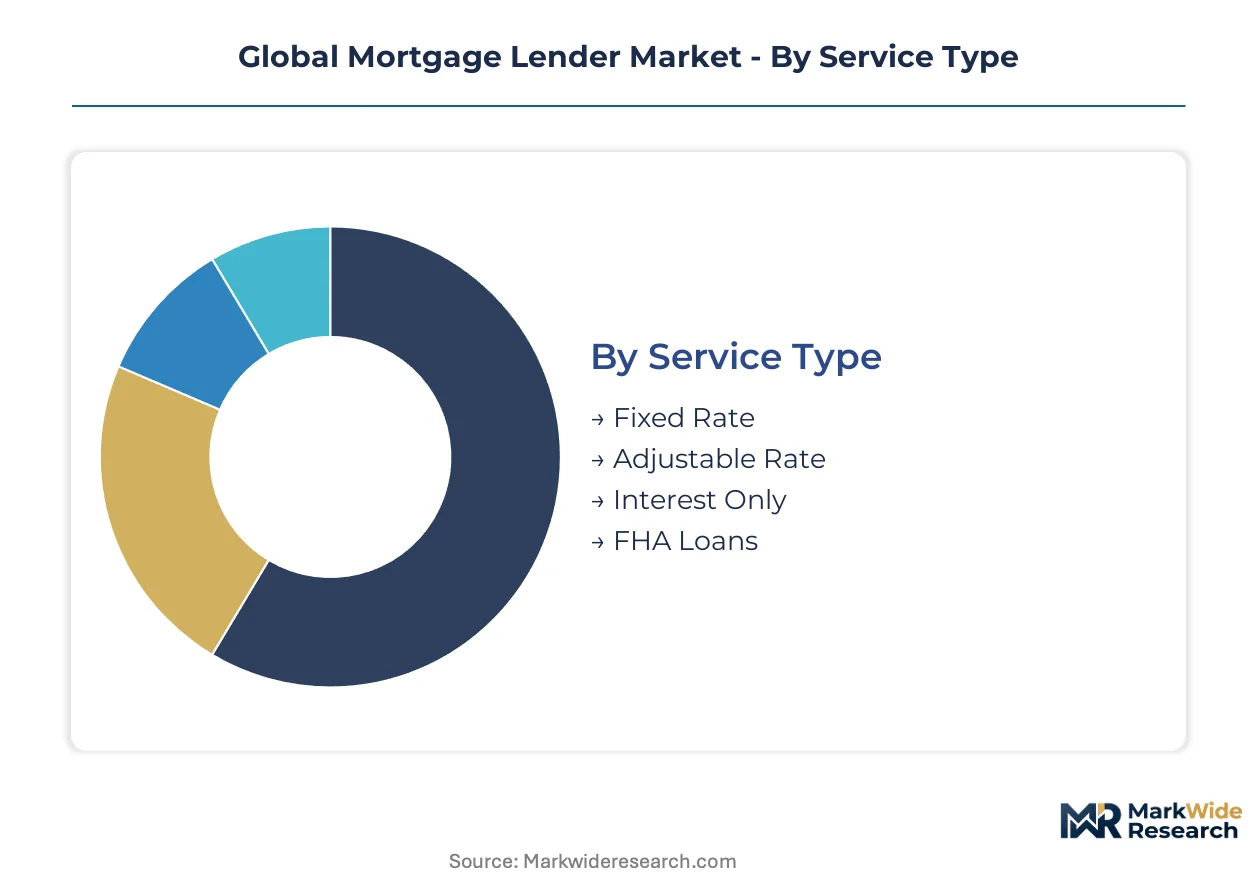
Segmentation in mortgage lending reveals how capital allocation, regulatory treatment, and borrower risk profiles diverge across product structures. Lenders optimize origination mix by balancing duration risk, government guarantee eligibility, and servicing retention economics.
Service Type:
Fixed-rate products face intensifying substitution pressure from adjustable-rate alternatives as central bank rate volatility reshapes borrower preference cycles.
- Fixed Rate:Long-duration instruments lock borrowing costs across 15- to 30-year maturities, insulating households from rate volatility. Demand concentrates in the United States among first-time buyers seeking payment certainty, though duration mismatch risk elevates lender hedging costs.
- Adjustable Rate:Hybrid and pure-variable structures reset periodically against benchmark indices like SOFR or Euribor. Borrowers in Germany and the United Kingdom favor these for lower initial carrying costs, accepting repricing risk for improved near-term affordability.
- Interest Only:Amortization-deferred structures require balloon principal repayment, common among buy-to-let investors in Australia and commercial property acquirers.
- FHA Loans:Government-insured products with elevated loan-to-value ceilings serve credit-constrained borrowers through mortgage insurance premiums.
Fixed Rate anchors the volume base while Adjustable Rate gains share at the steepest rate.
Customer Type:
Cost-tier stratification separates acquisition economics, with first-time buyers commanding premium per-loan investment against lifetime value calculations.
- First-time Buyers:Entry-level purchasers with limited equity contribution and thin credit files. Digital onboarding platforms in the United Kingdom compress origination friction for this cohort, though debt-to-income scrutiny remains stringent.
- Refinancers:Existing homeowners seeking rate reduction or cash extraction. Rate-sensitive volume collapses when central bank tightening eliminates rate-arbitrage incentives.
- Investors:Non-owner-occupied purchasers face higher down-payment requirements and rate spreads. Australian prudential regulators impose serviceability buffers on investor lending to contain systemic risk.
- Commercial Clients:Income-producing property developers and corporate real estate acquirers. Loan structures emphasize debt-service coverage ratios over personal credit metrics.
Refinancers dominate transaction velocity in low-rate environments while First-time Buyers sustain origination floors through cyclical downturns.
Offering:
Margin concentration tracks guarantee eligibility, with government-sponsored enterprise conforming products commanding tighter spreads than portfolio-retained alternatives.
- Conventional Loans:Private-market instruments meeting standardized underwriting criteria. Fannie Mae and Freddie Mac eligibility in the United States enables deep secondary market liquidity and reduced capital charges.
- VA Loans:Veteran-targeted products with zero-down-payment structures and funding fee financing. Department of Veterans Affairs guarantees eliminate private mortgage insurance requirements.
- Jumbo Loans:Balance-sheet-retained exposures exceeding conforming loan limits. Super-prime borrower profiles and manual underwriting sustain wider net interest margins.
- Subprime Loans:Non-qualified mortgage products for borrowers outside standard credit boxes. Ability-to-repay rule compliance demands enhanced documentation and litigation reserves.
Conventional Loans generate the deepest origination volumes while Jumbo Loans deliver the widest risk-adjusted spreads.
Delivery Model:
Supply concentration favors deposit-funded institutions with balance-sheet capacity, though fintech infrastructure is fragmenting customer acquisition pathways.
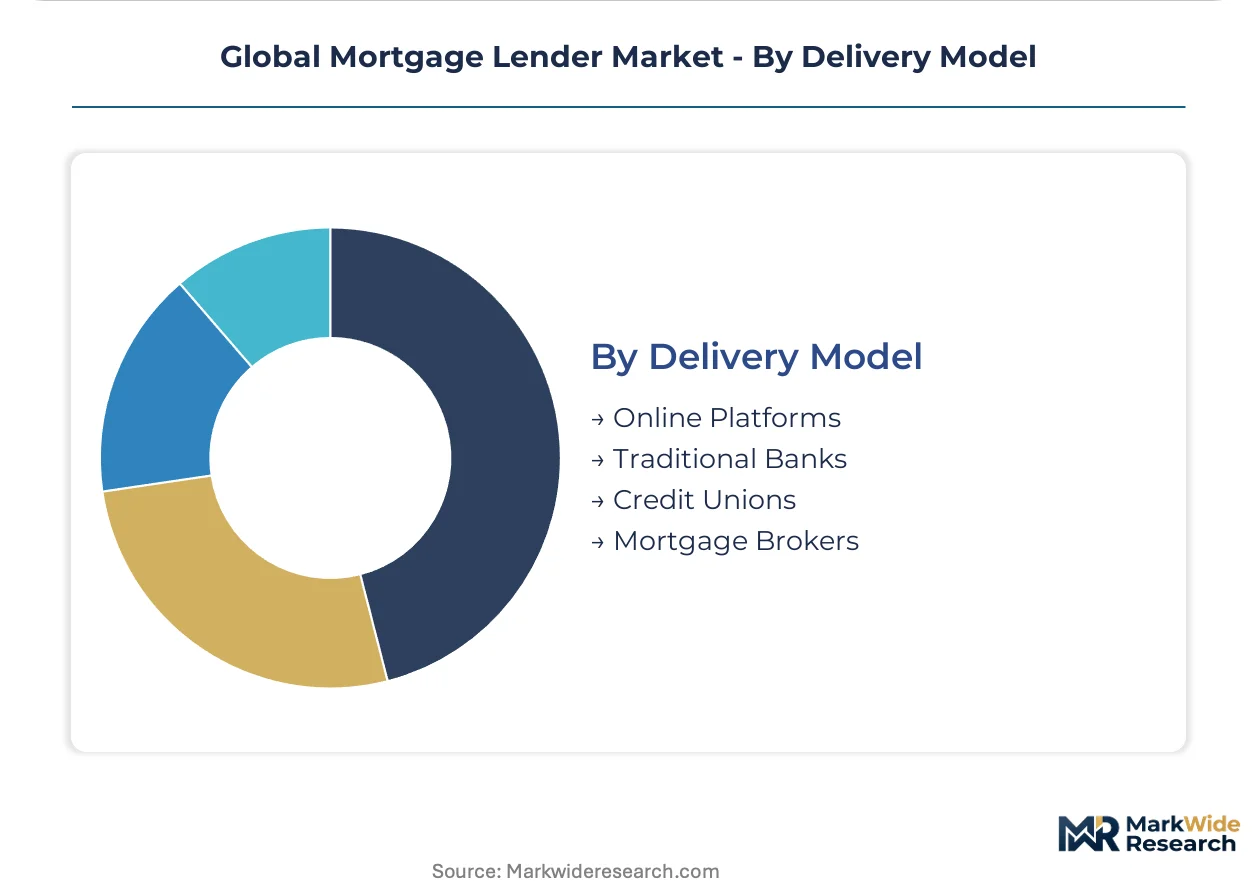
- Online Platforms:API-native lenders leveraging automated underwriting and direct-to-consumer marketing. Rocket Mortgage and similar operators in the United States achieve sub-30-day closing timelines through proprietary decision engines.
- Traditional Banks:Full-service institutions with integrated deposit bases and servicing operations. Branch networks retain advantage among older demographics and complex jumbo transactions.
- Credit Unions:Member-owned cooperatives with tax-advantaged structures and community charter concentrations. Portfolio retention strategies dominate over originate-to-sell economics.
- Mortgage Brokers:Intermediary channels aggregating wholesale lender products. Compensation disclosure rules under the Dodd-Frank Act constrain yield-spread premium structures.
Traditional Banks retain the largest serviced portfolio balances while Online Platforms climb the fastest in purchase-market share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border capital flows from United States institutional investors into European covered bond markets sustain secondary market liquidity for mortgage-backed securities, while Asian banking conglomerates channel deposits into Australian and Canadian residential lending.
United States
Fannie Mae and Freddie Mac guarantee structures dominate conforming loan origination, absorbing credit risk from depository institutions. The Federal Housing Finance Agency calibrates loan limit thresholds annually, directly influencing jumbo-conforming boundaries. Dallas-Fort Worth metroplex lenders deploy automated underwriting platforms to capture inbound migration-driven purchase demand.
Germany
Pfandbrief-covered bond issuance anchors long-term funding for residential mortgage portfolios, offering investors dual recourse to issuer and collateral pool. BaFin enforces strict matching requirements between asset and liability durations. Frankfurt-based mortgage banks concentrate origination through bauspar savings-linked products in Rhineland and Bavaria housing markets.
United Kingdom
Building societies retain mutual ownership structures that prioritize member deposits over wholesale funding dependence. The Prudential Regulation Authority stress-tests lender resilience against interest rate shocks and unemployment spikes. London and Southeast England command premium pricing for buy-to-let products amid constrained rental supply.
Australia
Major banks dominate broker-originated flow through upfront and trail commission structures that align intermediary incentives. The Australian Prudential Regulation Authority imposes serviceability buffers above advertised rates to contain household leverage. Sydney and Melbourne metropolitan corridors concentrate high-loan-to-value origination among first-time purchasers.
India
Housing finance companies and scheduled commercial banks compete for priority sector lending quota fulfillment through affordable housing products. The Reserve Bank of India regulates risk weights for residential mortgage exposures based on loan-to-value brackets. Mumbai and Bengaluru urban agglomerations drive origination volume through credit-linked subsidy scheme uptake.
Global Mortgage Lender Market Competitive Environment
Listed leaders compete with private specialists across balance-sheet capacity and origination velocity. Deposit-funded banking conglomerates retain servicing portfolios and jumbo exposures, while non-bank lenders pursue originate-to-sell economics through government-sponsored enterprise execution. Three archetypes dominate: integrated money-center banks with correspondent networks, direct-to-consumer digital platforms with proprietary underwriting engines, and wholesale-focused intermediaries aggregating broker-originated volume. Competitive intensity centers on technology licensing partnerships and servicing rights acquisitions.
Among United States-based originators, Rocket Mortgage exemplifies the digital-first archetype through API-native application infrastructure, while United Wholesale Mortgage anchors the wholesale channel through broker relationship density. JPMorgan Chase occupies a position within the integrated banking tier, combining deposit funding with portfolio retention capacity. CrossCountry Mortgage represents the distributed retail model through branch-level loan officer networks.
| Leading Market Players |
|---|
| United Wholesale Mortgage |
| Rocket Mortgage |
| CrossCountry Mortgage |
| Bank of America |
| JPMorgan Chase |
| Wells Fargo |
| China Zheshang Bank |
| Mitsubishi UFJ Financial Group |
| BNP Paribas |
| Others |
Value Chain & Pricing Dynamics
Long-term fixed-rate mortgage locks anchor borrower payment certainty while simultaneously exposing lenders to duration risk that compresses net interest margins when central bank tightening elevates funding costs. This contract structure concentrates pricing power with deposit-funded institutions capable of holding originated loans to maturity, while originate-to-sell operators face secondary market spread volatility.
Pricing Analysis
Digital-first versus legacy-branch pricing gaps widen as API-native lenders compress per-loan acquisition costs through automated underwriting engines. Three-tier pricing structure across premium jumbo, standard conforming, and economy government-insured tiers reflects borrower credit quality and guarantee eligibility. Price differentiation centers on loan-to-value thresholds and debt-to-income ratios, with first-time buyers commanding premium servicing investments against lifetime value calculations. Pricing pressure stems from central bank rate volatility that eliminates refinance arbitrage opportunities. Investors demonstrate highest price sensitivity to rate spreads, while first-time buyers prioritize down-payment accessibility over basis point optimization.
Supply Chain Analysis
Thirty-day rate lock inventory cycles and appraisal capacity bottlenecks extend closing timelines from application to funding. Origination supply concentrates in the United States, Germany, and Australia, where regulatory frameworks and secondary market depth sustain lender participation. Raw material dependencies include FICO scoring data, multiple listing service property records, and government-sponsored enterprise guarantee capacity. Single-source vulnerability to licensed residential appraiser shortages threatens transaction velocity. Distribution runs through correspondent banking networks, mortgage broker intermediaries, and direct-to-consumer digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mortgage servicing rights and ancillary insurance attach rates expand recurring revenue streams faster than origination fee income, transforming lender economics toward relationship-based retention models.
For Market Incumbents: Compound defensive positioning through correspondent network consolidation and proprietary digital underwriting engine licensing to non-bank originators. Balance-sheet-heavy institutions face margin compression from fintech-driven origination cost transparency. Vertical integration into servicing rights acquisitions locks in long-duration fee streams. For New Entrants and Emerging Players: Differentiate on embedded finance distribution partnerships with property technology platforms capturing borrower intent at listing discovery. India's tier-2 and tier-3 cities present underpenetrated origination volume against Housing for All mandate subsidies. API-first origination stacks enable rapid market entry without legacy core system migration burdens. For Investors and Strategic Acquirers: Capital is best deployed toward digital-native lenders with servicing portfolio scale and proprietary data assets for machine-learning underwriting refinement. Long-term viability favors operators with diversified funding models resilient to central bank rate cycles. Watch Federal Housing Finance Agency loan limit adjustments as inflection indicators for jumbo-conforming boundary shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Servicing Rights Acquisition | Locks in recurring fee income insulated from origination cycle volatility. |
| API-First Origination Platform | Compresses closing timelines through automated asset verification protocols. |
| Embedded Finance Partnership | Captures borrower intent upstream via real estate marketplace integration. |
| Correspondent Network Expansion | Aggregates broker-originated volume without branch infrastructure investment. |
| Green Mortgage Certification | Accesses EU risk-weighting advantages for energy-efficient collateral pools. |
Study Parameters
A spread of perspectives from chief lending officers, mortgage servicing executives, regulatory compliance directors, and correspondent banking relationship managers converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, Federal Housing Finance Agency conservatorship reports, and European Banking Authority stress-test disclosures. Bottom-up origination volume triangulation against top-down macroeconomic housing affordability indices anchored the modeling framework.
Segmentation dimensions modeled include interest rate structure, customer archetype, guarantee eligibility, and delivery channel across the projection horizon. CAGRs were derived from trend extrapolation calibrated to central bank policy trajectory assumptions and household formation demographic projections. Basel III capital adequacy evolution and automated valuation model regulatory acceptance curves informed scenario-weighted outputs.
Forecasts assume regulatory continuity in US FHA guideline frameworks and EU Mortgage Credit Directive regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Asia-Pacific Syndicated Loans Market
Loans and Leasing
Japan Auto Loan Market
Loans and Leasing
Brazil Auto Loan Market
Loans and Leasing
Construction Equipment Finance Market
Loans and Leasing
Canada Student Loan Market
Loans and Leasing
Payday Loans Market
Loans and Leasing
Alternative Financing Market
Loans and Leasing
Alternative Lending Platform Market
Loans and Leasing
India Auto Loan Market
Loans and Leasing
Used Car Financing Market
Loans and Leasing
US Factoring Services Market
Loans and Leasing
US Mortgage/Loan Brokers Market
Loans and Leasing
Asia-Pacific Car Loan Market
Loans and Leasing
Commercial Lending Market
Loans and Leasing
Indonesia Mortgage/Loan Brokers Market
Loans and Leasing
Canada Mortgage/Loan Brokers Market