
 US Factoring Services Market | 2026-2036
US Factoring Services Market Size, Share, and Industry Trends Forecast 2026-2036
US Factoring Services Market Intelligence
API-driven underwriting is narrowing the gap between invoice submission and funding disbursement for US-based factors. Triumph Financial leverages proprietary freight payment data to anchor its transportation factoring portfolio. CIT Group Inc. competes through deep specialization in manufacturing and wholesale trade credit facilities. Wells Fargo extends its commercial banking relationships into structured receivables finance across large corporate segments.
US factoring services involve the purchase of accounts receivable at a discount, where the factor assumes collection risk and provides immediate liquidity against invoices typically aged 30 to 90 days. The practice functions as a working capital acceleration tool, replacing traditional bank credit lines for businesses with uneven cash conversion cycles. Recourse factoring dominates transaction volume among small and medium enterprises due to lower fee structures and reduced capital reserves required from providers. Non-recourse factoring commands premium pricing within transportation and healthcare services verticals where credit insurance layering protects against buyer default.
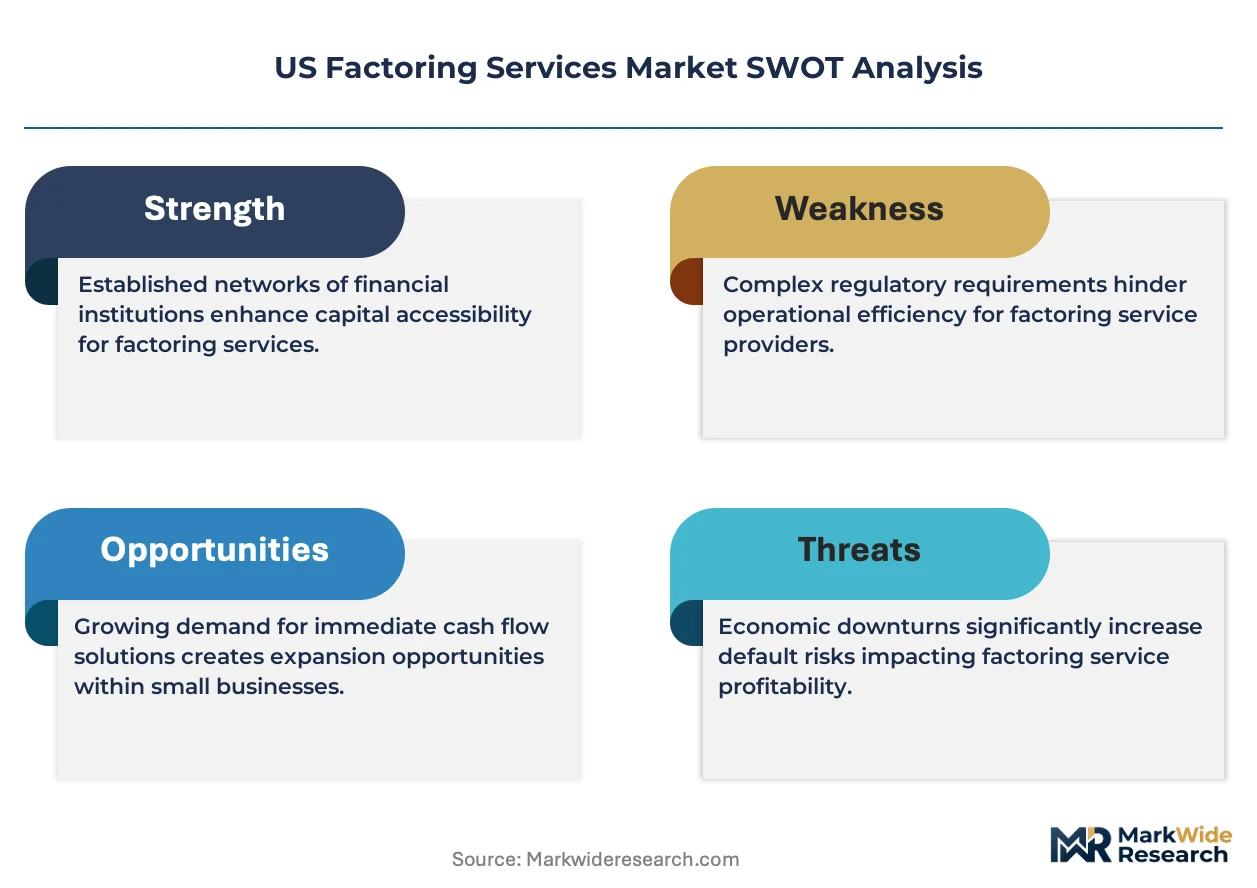
The Federal Reserve governs capital reserve requirements affecting factor liquidity deployment, while the Office of the Comptroller of the Currency supervises national bank entrants into factoring activities. State usury laws create patchwork compliance obligations that shape contract structuring and fee transparency across jurisdictions. Stakeholders must monitor evolving interpretations of the Uniform Commercial Code Article 9 as courts reassess perfection requirements for electronic receivables assignments.
Market Dynamics
The Federal Reserve's sustained restrictive posture on interest rates is compressing net interest margins across factoring portfolios, forcing providers to recalibrate fee structures and accelerate automation investments to preserve profitability.
Growth Catalysts
- Recourse factoring adoption:Small enterprises in manufacturing hubs across Ohio and Georgia are converting traditional bank credit lines to recourse arrangements, drawn by faster approval cycles and reduced collateral requirements.
- Uniform Commercial Code Article 9 modernization:Judicial interpretations clarifying electronic receivables perfection standards are reducing legal uncertainty for factors purchasing digital invoices.
- Transportation sector data integration:Freight payment telemetry from ELD systems is enabling real-time invoice verification, cutting due diligence timelines for trucking fleet financing.
Market Restraints
- State usury law fragmentation:Patchwork interest rate ceilings across Texas, New York, and California force factors to structure multi-jurisdictional contracts with variable fee schedules, elevating compliance overhead.
- Concentrated buyer credit risk:Heavy exposure to retail and automotive sector accounts receivable creates correlated default exposure during demand downturns in the Midwest manufacturing belt.
- Bank entrant competition:National banks leveraging balance sheet scale under OCC supervision can undercut independent factors on pricing for large corporate receivables programs.
Strategic Opportunities
- Healthcare services vertical expansion:Medical practice management groups in Florida and Arizona present underpenetrated demand for non-recourse factoring against commercial insurance receivables.
- API-first distribution partnerships:Embedded finance integrations with accounting software platforms like QuickBooks and Sage are opening direct origination channels to SMBs without traditional sales forces.
- Inflation Reduction Act energy credit monetization:Renewable project developers are seeking factoring against transferable tax credits, creating a receivables class with federal backing.
Industry Challenges
- Underwriting automation talent scarcity:Factors struggle to hire machine learning engineers capable of building predictive default models from sparse SMB credit data.
- Legacy core system migration:Established providers face multi-year ERP transitions to cloud-native architectures, delaying real-time portfolio analytics deployment.
- Electronic signature enforceability variance:State-level recognition standards for digital invoice assignments create documentation risks in collections litigation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Factoring Services Market |
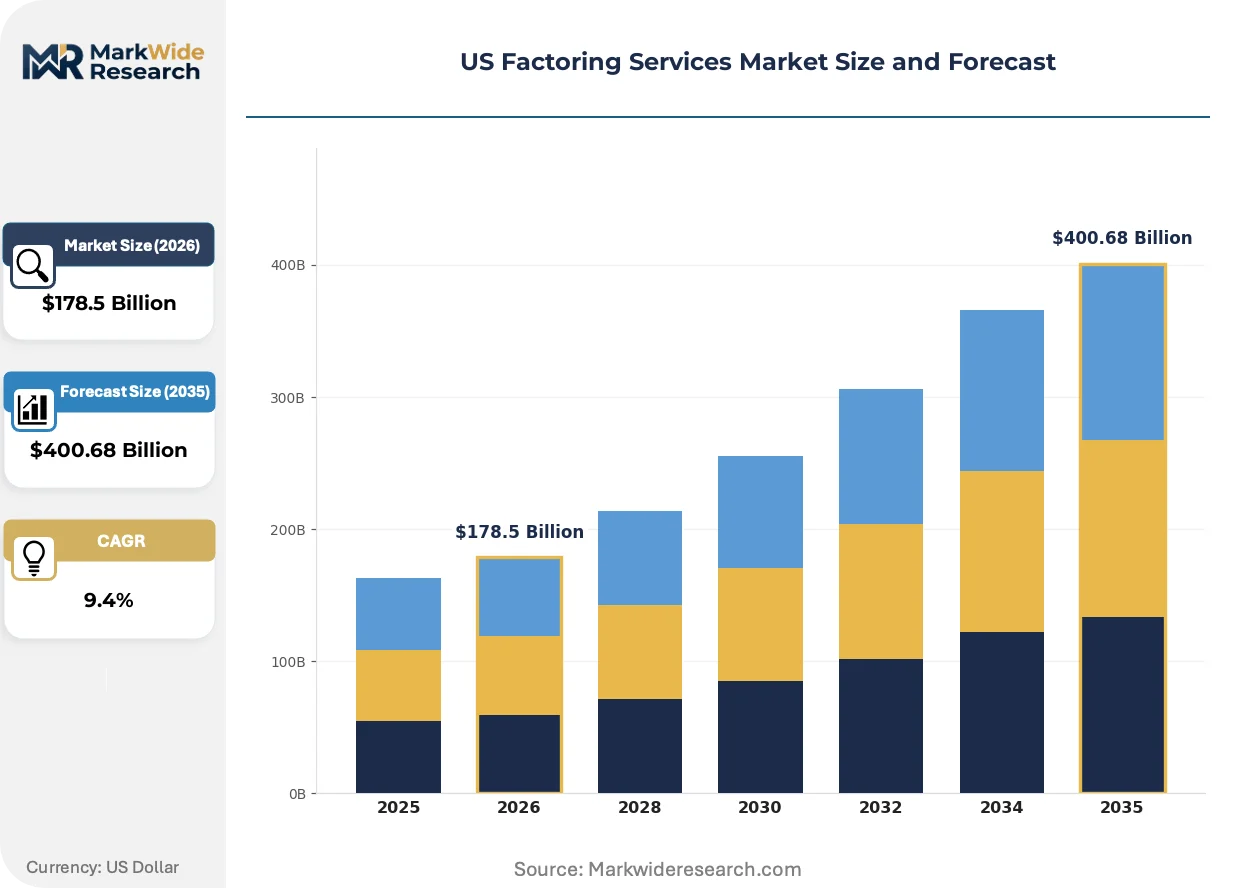
| Market Size in 2026 | $178.5 Billion |
| Market Size in 2035 | $400.68 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Recourse Factoring, Non-Recourse Factoring, Invoice Discounting, Spot Factoring Customer Type: Small Enterprises, Medium Enterprises, Large Corporations, Startups Industry Vertical: Manufacturing, Transportation, Wholesale Trade, Healthcare Services Contract Duration: Short-Term Contracts, Long-Term Contracts, Flexible Plans, One-Time Agreements |
| Companies Covered | CIT Group Inc., Triumph Financial, Inc., Bibby Financial Services, Inc., altLINE – The Southern Bank Company, eCapital Corp., RTS Financial Services, Inc, TCI Business Capital, Riviera Finance, Wells Fargo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Factoring Services Market Strategic Shifts & Innovations
Artificial intelligence is restructuring every layer of the factoring value chain, from origination scoring through collections prediction, compressing operational timelines and shifting competitive advantage toward data-rich platforms.
Machine learning-powered credit scoring is collapsing traditional manual underwriting timelines from days to minutes. Mid-market transportation factors are deploying these models at scale against freight broker payment histories. The compression is eliminating the speed advantage that previously justified premium pricing for expedited funding.
The Office of the Comptroller of the Currency has clarified national bank authority to purchase receivables without state lending license requirements. This regulatory interpretation enables chartered banks to compete directly with state-licensed factors across all fifty states. Independent factors in Illinois and Pennsylvania are responding by deepening specialization in industry verticals where bank credit committees lack expertise.
Buyers are unbundling working capital acceleration from full-service factoring relationships. Fleet operators in Tennessee and Alabama now procure invoice verification and collections as standalone SaaS modules, purchasing funding only during seasonal cash crunches. This pattern is fragmenting provider relationships and pressuring bundled fee structures.
US Factoring Services Market Segmentation
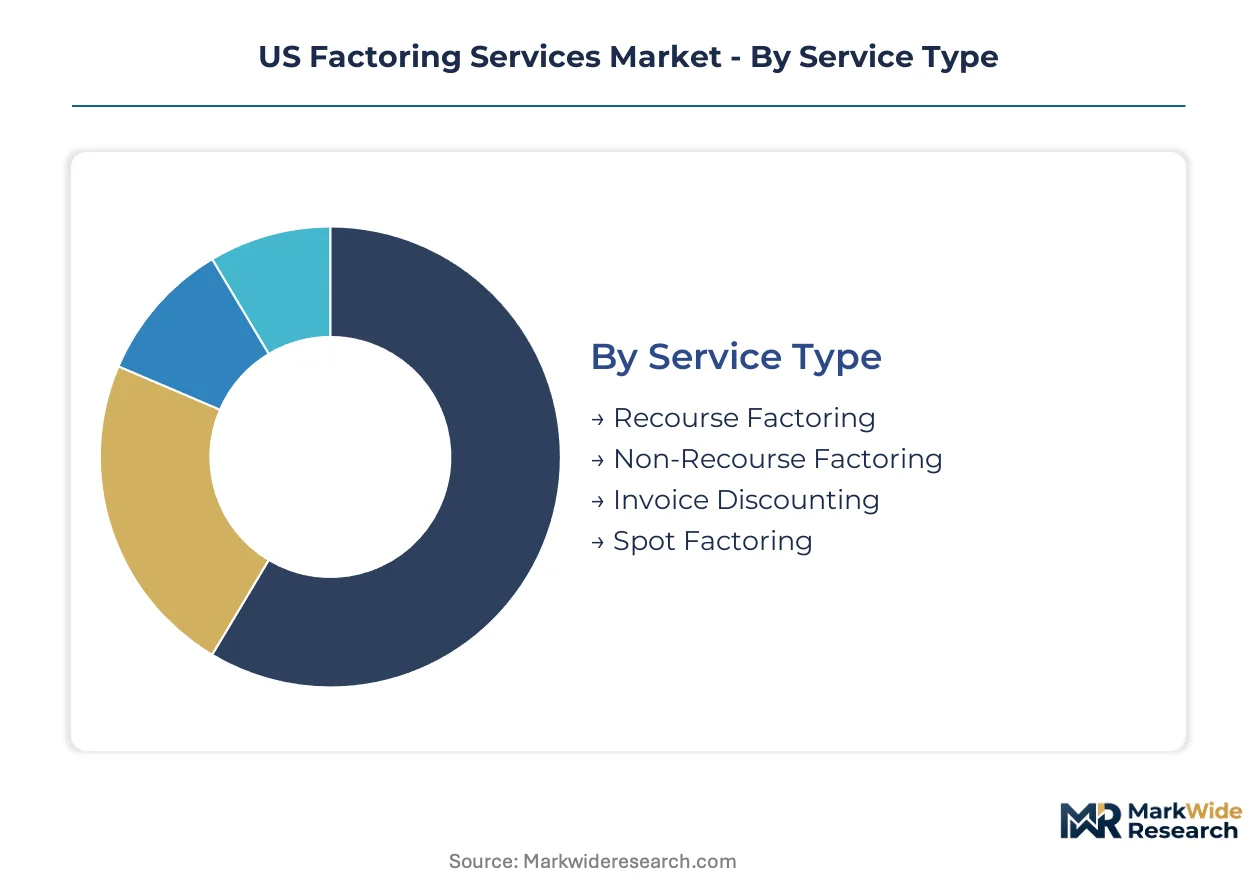
US factoring services fragment across four structural dimensions that determine risk allocation, pricing tiers, and operational workflows. Each segmentation axis reveals distinct liquidity needs and compliance obligations across the value chain.
Service Type:
Recourse and non-recourse structures anchor opposite ends of the risk-transfer spectrum, with hybrid models filling intermediate liquidity gaps.
- Recourse Factoring:The factor purchases receivables with the seller retaining default risk, enabling lower fee structures through collateralized seller obligations. Small enterprises in Ohio and Georgia manufacturing clusters favor this structure for its reduced documentation burden and faster approval cycles compared to traditional credit lines.
- Non-Recourse Factoring:Credit risk transfers entirely to the factor, requiring embedded insurance layering and rigorous buyer credit analysis. Transportation fleets operating across interstate corridors command premium pricing for this protection against shipper insolvency during freight market downturns.
- Invoice Discounting:Confidential arrangements where the seller retains collection responsibility while pledging receivables as loan collateral. Large wholesale distributors in the Southeast deploy this structure to mask liquidity needs from key buyers.
- Spot Factoring:Single-invoice transactions without ongoing contractual obligations. Healthcare practices in Florida utilize spot arrangements intermittently against delayed commercial insurance payments.
Established volume favors Recourse Factoring; emerging adoption favors Spot Factoring.
Customer Type:
Entity scale dictates collateral requirements, technology integration depth, and the feasibility of relationship-based versus transaction-based underwriting.
- Small Enterprises:Businesses with annual revenues below $10 million drive recourse factoring volume through QuickBooks-integrated origination channels. API-first providers capture this segment via automated bank account verification and real-time invoice parsing.
- Medium Enterprises:Regional manufacturers and distributors with $10-100 million revenues negotiate customized facility structures blending recourse and non-recourse tranches. These entities demand dedicated relationship managers and quarterly portfolio reviews.
- Large Corporations:Multi-divisional enterprises with centralized treasury functions procure structured receivables finance through competitive RFP processes. Wells Fargo and national bank competitors dominate this tier through balance sheet scale advantages.
- Startups:Venture-backed companies with limited operating history access factoring against contracted future revenues rather than aged receivables. Specialized fintech platforms serve this niche with equity-linked underwriting models.
Profit concentration sits with Medium Enterprises; volume expansion concentrates among Small Enterprises.
Industry Vertical:
Sector-specific payment cycles and counterparty credit profiles shape factor specialization and portfolio construction methodologies.
- Manufacturing:Original equipment suppliers and component fabricators in the Midwest generate 60-90 day invoice terms against automotive and industrial buyer networks. Factors deploy equipment appraisal expertise alongside receivables analysis for this collateral-heavy segment.
- Transportation:Trucking fleets and freight brokers present high-velocity, low-margin receivables requiring real-time verification through ELD telemetry integration. Triumph Financial anchors its portfolio here through proprietary freight payment data advantages.
- Wholesale Trade:Inventory-heavy distributors face seasonal working capital swings addressed through revolving factoring facilities tied to purchase order financing.
- Healthcare Services:Medical practices and specialty clinics factor against commercial insurance and Medicare receivables with 90-180 day collection horizons. Non-recourse structures dominate due to payer concentration risk and regulatory complexity.
Margin stability favors Manufacturing; steepest expansion trajectory appears in Healthcare Services.
Contract Duration:
Commitment length structures the economic relationship between factor and client, determining pricing predictability and operational investment amortization.
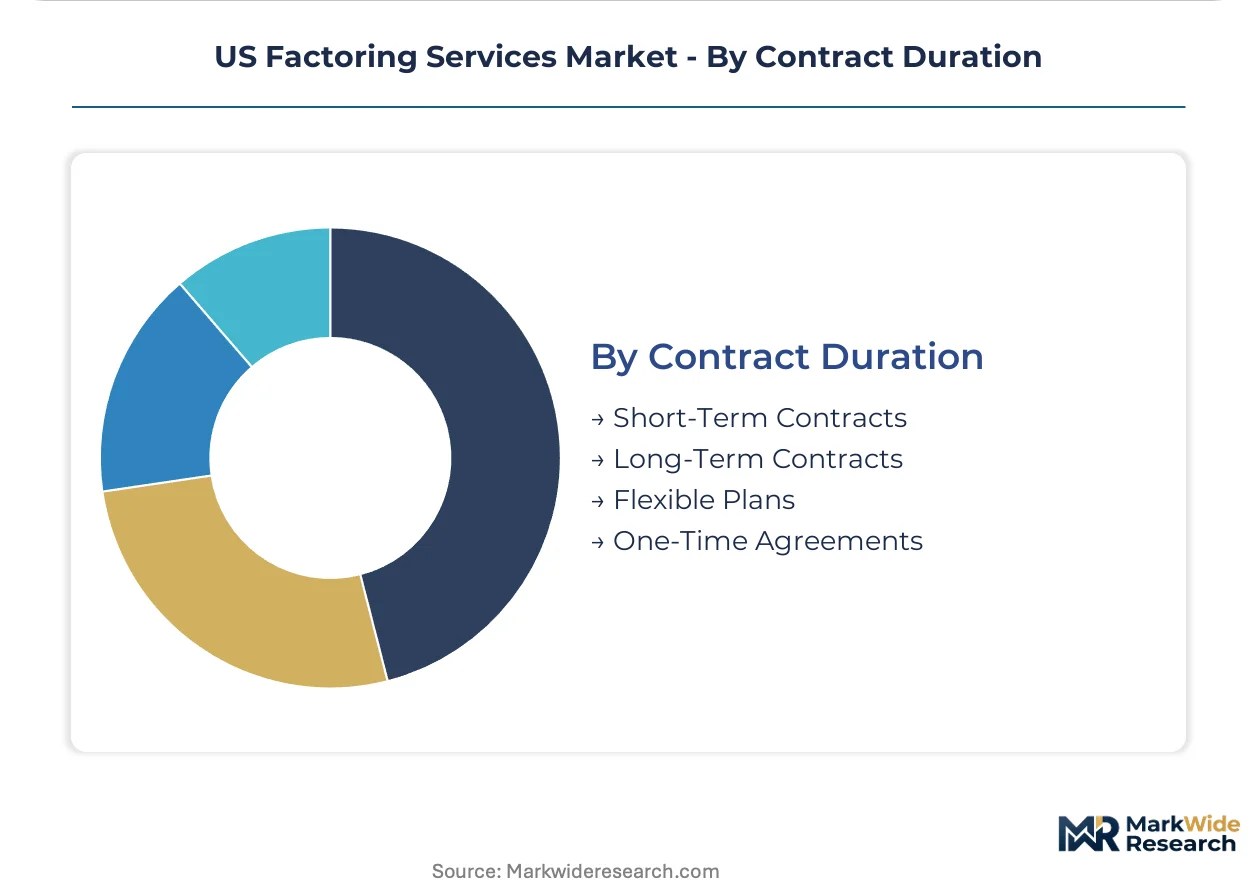
- Short-Term Contracts:Six-to-twelve month agreements with renewal options suit cyclical businesses facing predictable seasonal demand patterns. Agricultural equipment distributors in the Southeast utilize these structures around harvest financing windows.
- Long-Term Contracts:Multi-year facilities with committed credit lines and pricing floors provide certainty for capital-intensive manufacturing operations. These arrangements typically include annual portfolio reviews and covenant testing.
- Flexible Plans:Month-to-month structures with usage-based minimums accommodate businesses with irregular invoice generation. Technology service providers with project-based revenue favor this adaptability.
- One-Time Agreements:Single-transaction facilities for acquisition financing, distressed liquidity events, or strategic supplier transitions. Restructuring advisors broker these specialized engagements.
Revenue predictability favors Long-Term Contracts; origination efficiency favors Flexible Plans.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US factoring services flow through manufacturing export corridors linking Midwest automotive suppliers to Mexican assembly plants and Southeast distributors to Latin American trade partners. The Federal Reserve's interest rate policies create uneven liquidity conditions across state banking markets. Regional specialization clusters around transportation hubs, industrial belts, and healthcare corridors.
Midwest Manufacturing Belt
Ohio and Michigan automotive component suppliers drive recourse factoring volume against 60-90 day OEM payment terms. The Federal Reserve Bank of Chicago supervises regional capital reserve requirements affecting factor liquidity deployment. Cleveland and Detroit anchor concentrated demand from tier-two suppliers converting bank credit lines to invoice financing.
Southeast Transportation Corridor
Georgia and Tennessee trucking fleets generate high-velocity receivables requiring real-time verification through ELD telemetry integration. State usury laws in Georgia permit competitive fee structures absent in neighboring jurisdictions. Atlanta freight brokers command premium non-recourse pricing against shipper insolvency risk during freight market downturns.
Texas Energy and Trade Hub
Houston-based oilfield service contractors factor against extended payment terms from major operators. The Texas Finance Commission oversees state-licensed factor compliance with localized interest rate ceilings. Dallas-Fort Worth distribution centers serve as origination points for cross-border receivables into Mexican manufacturing supply chains.
Florida Healthcare Services Cluster
Miami and Tampa medical practices present underpenetrated demand for non-recourse factoring against commercial insurance receivables. State insurance regulations govern credit insurance layering for healthcare payer concentration risk. Orlando specialty clinics utilize spot factoring intermittently against delayed Medicare and commercial payment cycles.
California Technology and Logistics Nexus
Los Angeles and Long Beach port-dependent importers deploy invoice discounting to mask liquidity needs from Asian supplier networks. California's usury law restrictions force factors to structure multi-jurisdictional contracts with variable fee schedules. San Francisco Bay Area fintech platforms originate API-first factoring to venture-backed startups with limited operating history.
US Factoring Services Market Key Industry Players
On the supply side, the industry is tiered between national bank balance sheet players, independent vertical specialists, and API-first fintech platforms. The top tier commands large corporate structured receivables through relationship banking advantages. Mid-tier independents defend position through transportation, healthcare, and manufacturing specialization. Emerging fintech entrants compress origination timelines through accounting software integrations and automated underwriting. Dominant competitive moves include strategic partnerships with freight payment data providers and embedded finance distribution through SaaS platforms.
Among bank-affiliated factors, Wells Fargo occupies a position exemplifying commercial banking relationship extension into receivables finance. Triumph Financial anchors the transportation specialist archetype through proprietary freight payment data advantages. CIT Group Inc. sits within the manufacturing and wholesale trade specialization tier. These three represent distinct competitive vectors—balance sheet scale, vertical data integration, and industry credit expertise—that structure rivalry across customer segments.
| Leading Market Players |
|---|
| CIT Group Inc. |
| Triumph Financial, Inc. |
| Bibby Financial Services, Inc. |
| altLINE – The Southern Bank Company |
| eCapital Corp. |
| RTS Financial Services, Inc |
| TCI Business Capital |
| Riviera Finance |
| Wells Fargo |
| Others |
Cost & Logistics Intelligence
Federal Reserve interest rate volatility functions as the dominant risk vector, compressing net interest margins for factors while simultaneously forcing recalibration of fee structures and automation investments across the origination-to-collection workflow. This monetary policy uncertainty determines both the spread between recourse and non-recourse pricing tiers and the geographic concentration of factor liquidity deployment toward states with favorable usury law frameworks.
Pricing Analysis
The pricing gap between legacy manual underwriting platforms and API-first automated systems is collapsing traditional fee premiums. Three-tier pricing structure across premium non-recourse, standard recourse, and economy spot-factoring levels stratifies by credit insurance layering depth and buyer verification intensity. Pricing pressure stems from bank entrant balance sheet scale advantages under OCC supervision, which undercut independent factor rates for large corporate receivables. Small enterprises in Ohio and Georgia manufacturing clusters exhibit highest price sensitivity, while transportation fleets operating interstate corridors accept premium non-recourse rates for shipper insolvency protection.
Supply Chain Analysis
Regulatory fragmentation across Texas, New York, and California state usury laws dominates supply chain risk for multi-jurisdictional factors. Factor liquidity draws from Federal Reserve capital reserve requirements, commercial bank credit facility backstops, and private credit fund allocations. Documentation risk rests on state-level variance in electronic signature enforceability for digital invoice assignments. Distribution runs through embedded finance integrations with QuickBooks and Sage accounting platforms, direct sales forces targeting Midwest manufacturing belts, and freight payment data partnerships anchoring Southeast transportation corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US factoring services market rewards platforms possessing machine learning engineering capabilities capable of compressing underwriting timelines from days to minutes, yet talent scarcity constrains deployment velocity for established providers. This capability gap separates data-rich vertical specialists from legacy operators dependent on manual credit analysis.
For Market Incumbents: Entrench position through backward integration into proprietary freight payment telemetry and healthcare claims verification data streams, neutralizing fintech entrant speed advantages. Deepen API-first distribution partnerships with accounting software platforms to lock out emerging embedded finance competitors. Prioritize cloud-native core system migration to enable real-time portfolio analytics against bank-affiliated factors leveraging legacy infrastructure. For New Entrants and Emerging Players: Florida and Arizona healthcare services clusters present the most penetrable white-space for non-recourse factoring against commercial insurance receivables, with state insurance regulations creating defensible specialization barriers. Target QuickBooks-integrated origination channels for Ohio and Georgia small enterprises converting traditional bank credit lines. Pursue spot-factoring SaaS modularization to capture fleet operators unbundling working capital acceleration from full-service relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated platforms with proprietary data assets and embedded distribution. Long-term viability hinges on underwriting automation moats and regulatory compliance infrastructure spanning multi-jurisdictional usury law frameworks. Watch for inflection signals in OCC interpretations of national bank receivables purchasing authority that could accelerate independent factor acquisition by chartered institutions.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Development | Embedded finance integrations with QuickBooks and Sage compress origination timelines for SMB segments. |
| Vertical Data Partnership | Freight payment telemetry from ELD systems enables real-time invoice verification for transportation factors. |
| Healthcare Specialization Buildout | Non-recourse factoring against commercial insurance receivables taps underpenetrated Florida and Arizona demand. |
| Cloud-Native Core Migration | Real-time portfolio analytics deployment delays threaten competitive position against automated entrants. |
| Multi-Jurisdictional Compliance Infrastructure | State usury law variance across Texas, New York, and California elevates contract structuring overhead. |
Research Approach
Desk research of Federal Reserve regulatory filings, OCC supervisory guidance, Uniform Commercial Code Article 9 judicial interpretations, and state usury law statutes preceded structured interviews with factor portfolio managers, commercial bank receivables finance heads, freight broker credit officers, and healthcare practice management executives. Secondary validation drew from SEC 10-K disclosures of publicly traded factors, industry association operational surveys, and embedded finance platform integration documentation. Bottom-up transaction volume estimates and top-down macroeconomic liquidity condition assessments were triangulated to anchor market sizing.
The analytical framework held Federal Reserve interest rate trajectory and OCC regulatory interpretation stability as fixed boundary conditions across the projection horizon, while varying small enterprise credit demand intensity and transportation sector freight market cyclicality. Segmentation modeling incorporated service type, customer scale, industry vertical, and contract duration dimensions alongside geographic regulatory cluster differentiation. CAGRs were derived from trend extrapolation of recourse factoring adoption rates and API-first origination channel penetration, with healthcare services vertical expansion and inflation-linked energy credit monetization serving as demand-side scenario inputs.
Macroeconomic conditions sit as an overlay; deviation in Federal Reserve policy stance, freight market downturn severity, or healthcare payer concentration default rates would shift the trajectory. Forecasts reflect assumptions documented in the segmentation and regional outlook sections, with continuous validation against operating reality recommended as the discipline for managing projection uncertainty.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
India Used Car Financing Market
Loans and Leasing
Loan Brokers Market
Loans and Leasing
Debt Financing Market
Loans and Leasing
United States Material Handling Leasing and Financing Market
Loans and Leasing
France Auto Loan Market
Loans and Leasing
Europe Crowd Lending and Crowd Investing Market
Loans and Leasing
US Mortgage/Loan Brokers Market
Loans and Leasing
Europe Used Car Financing Market
Loans and Leasing
Global Automotive Rental and Leasing Market
Loans and Leasing
Loan Origination Software Market
Loans and Leasing
Invoice Factoring Market
Loans and Leasing
Auto Finance Market
Loans and Leasing
Digital Lending Platform Market
Loans and Leasing
India Car Loan Market
Loans and Leasing
Australia Used Car Financing Market
Loans and Leasing
Global Automotive Fleet Leasing Market