
 Brazil Auto Loan Market | 2026-2036
Brazil Auto Loan Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Auto Loan Market Insights
Securitization of auto loan receivables through FIDC structures is reshaping how non-bank lenders access institutional capital. BV Financeira leverages its captive finance origins to sustain deep dealership integration across Brazil's interior. Banco Pan competes through digital-first origination platforms that reduce branch dependency. Itau Unibanco anchors the premium segment with sophisticated risk-scoring models tied to payroll data.
An auto loan constitutes a secured consumer credit instrument collateralized by a vehicle title, typically structured with fixed or floating interest rates over twelve to eighty-four month amortization schedules, designed to facilitate durable goods acquisition while transferring residual value risk to the borrower. The product serves Brazil's mobility-dependent economy where personal vehicle ownership underpins employment access in sprawling metropolitan regions. New car financing commands the thickest margin pools due to manufacturer subsidies and lower default correlation, while used car loans exhibit faster volume acceleration as vehicle age thresholds for credit eligibility widen. Fixed rate products dominate risk-averse borrower preference, though hybrid structures gain traction among corporate clients managing interest rate exposure.
Banco Central do Brasil governs provisioning requirements and interest rate disclosure mandates under the Consumer Protection Code, while ANVISA regulates vehicle safety standards that indirectly affect loan-to-value calculations through depreciation schedules. The National Monetary Council sets capital reserve floors that constrain smaller lenders from scaling originations. Stakeholders must monitor how open banking data sharing protocols alter credit bureau dynamics and borrower screening economics.
Market Dynamics
Banco Central do Brasil's Resolution No. 4,893 is restructuring underwriting economics by mandating stricter debt-to-income thresholds and provisioning buffers, forcing lenders to recalibrate pricing models across São Paulo state's dense dealership corridors.
Growth Catalysts
- FIDC Securitization Structures:Non-bank lenders now tap institutional capital pools through receivables-backed securities, expanding origination capacity beyond traditional deposit bases.
- Logistics Fleet Expansion:E-commerce fulfillment networks across Brazil's interior are financing commercial vehicle acquisitions through captive finance arms tied to manufacturer distribution.
- Open Banking Protocols:Banco Central do Brasil's data-sharing mandates enable real-time credit bureau integration, compressing approval timelines for thin-file borrowers in peripheral metropolitan zones.
Market Restraints
- Interest Rate Volatility:Selic rate fluctuations transmit directly to floating-rate auto loan portfolios, squeezing net interest margins when monetary tightening accelerates.
- Depreciation Schedule Rigidity:ANVISA safety standard updates force premature vehicle write-downs, distorting loan-to-value ratios on collateral already deployed in existing contracts.
- Concentrated Manufacturing Geography:Vehicle assembly clusters in São Paulo state's ABC region create geographic credit exposure correlations during localized economic shocks.
Strategic Opportunities
- Northeast Corridor Penetration:Recife and Salvador metropolitan zones exhibit vehicle ownership gaps relative to income levels, presenting origination white space for digital-first platforms.
- Used Vehicle Credit Expansion:Widening age eligibility thresholds for collateral acceptance unlocks second-hand market volume without competing for manufacturer subsidy pools.
- Payroll-Linked Underwriting:Formal employment data integration through Banco Central do Brasil's instant payment infrastructure enables risk-scoring refinement for public sector borrowers.
Industry Challenges
- Legacy Core System Integration:Regional banks struggle to embed API-based credit decisioning into COBOL-based account platforms without multi-year transformation programs.
- Specialized Collections Talent Scarcity:Secured asset recovery expertise concentrates in São Paulo, leaving interior state operations dependent on third-party servicers with inconsistent collateral liquidation capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Auto Loan Market |
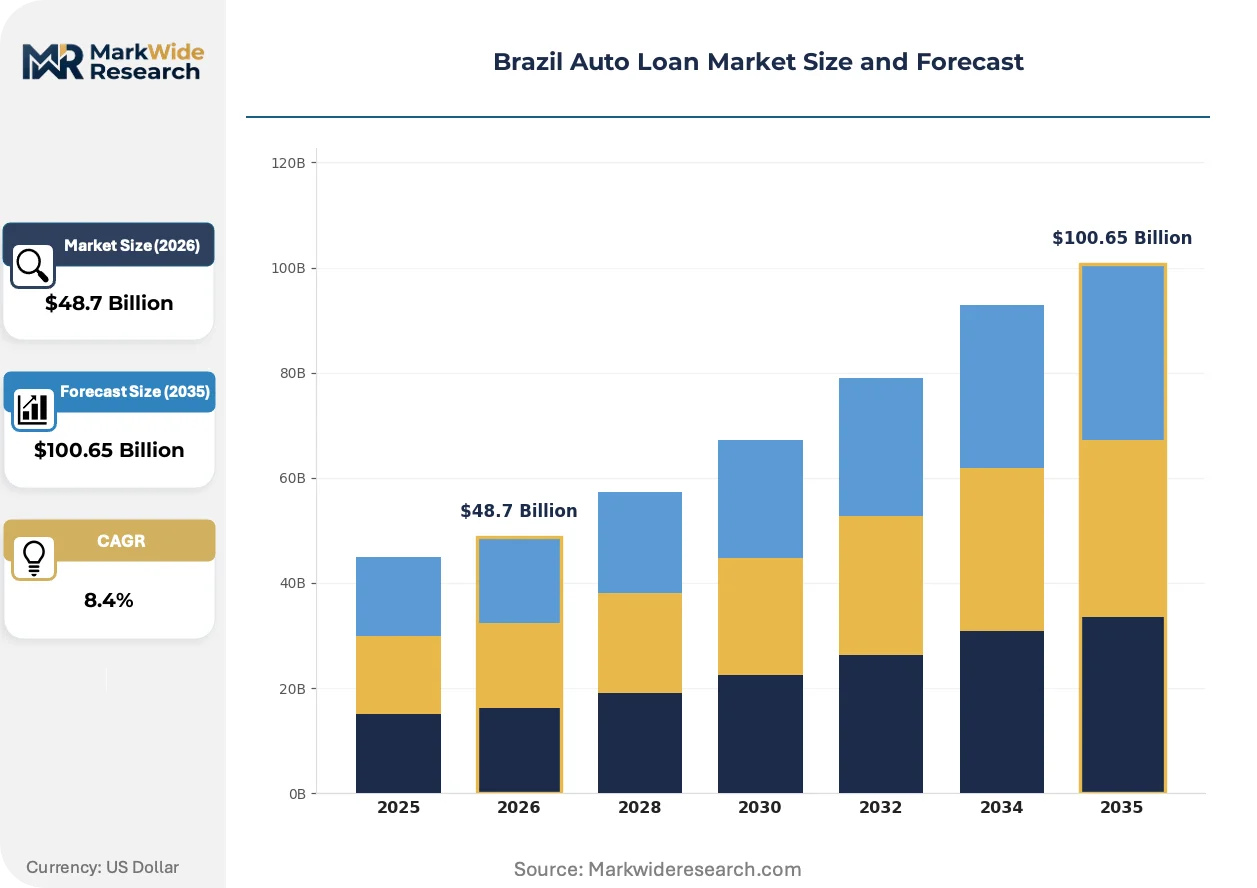
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: New Car, Used Car, Refinancing, Balloon Payment Customer Type: Individual Buyers, Dealerships, Fleet Operators, Corporate Clients Loan Duration: Short-term, Medium-term, Long-term, Flexible Terms Interest Rate Type: Fixed Rate, Variable Rate, Hybrid Rate, Promotional Rate |
| Companies Covered | Santander, BV Financeira, Banco do Brasil, Banco Safra, Banco Pan, Caixa Economica Federal, Itau Unibanco, Nubank, Banco Bradesco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Auto Loan Market Trends and Innovations
Digital origination platforms are compressing the traditional branch-dependent sales cycle, while regulatory data-sharing mandates and shifting collateral eligibility criteria are redefining how lenders construct borrower risk profiles across Brazil's heterogeneous credit markets.
Embedded finance APIs are hybridizing vehicle purchasing workflows by pre-qualifying buyers at point-of-sale terminals before dealership contact. São Paulo-based retail chains are deploying these interfaces across their automotive subsidiaries, collapsing the traditional 48-hour approval window to under ten minutes. This compression is eroding the branch-network advantage historically held by incumbent banks.
Banco Central do Brasil's open banking regulations are mandating standardized data portability across credit bureaus, forcing lenders to rebuild scoring architectures around real-time income verification rather than static registry queries. The industrial consequence is a shift toward subscription-based credit monitoring products that maintain borrower engagement post-origination. Fintech originators in Minas Gerais and Rio de Janeiro are responding fastest, leveraging lighter legacy burdens to re-platform.
Fleet procurement patterns are fragmenting across decentralized logistics subcontractors rather than consolidating under national operators, multiplying the number of small-ticket credit decisions lenders must process. Digital marketplaces connecting independent truck owners to cargo loads are embedding financing offers directly into dispatch platforms, bypassing traditional dealer intermediaries. This disintermediation is most visible along the BR-163 corridor linking Mato Grosso agricultural zones to Santos port infrastructure.
Brazil Auto Loan Market Segmentation
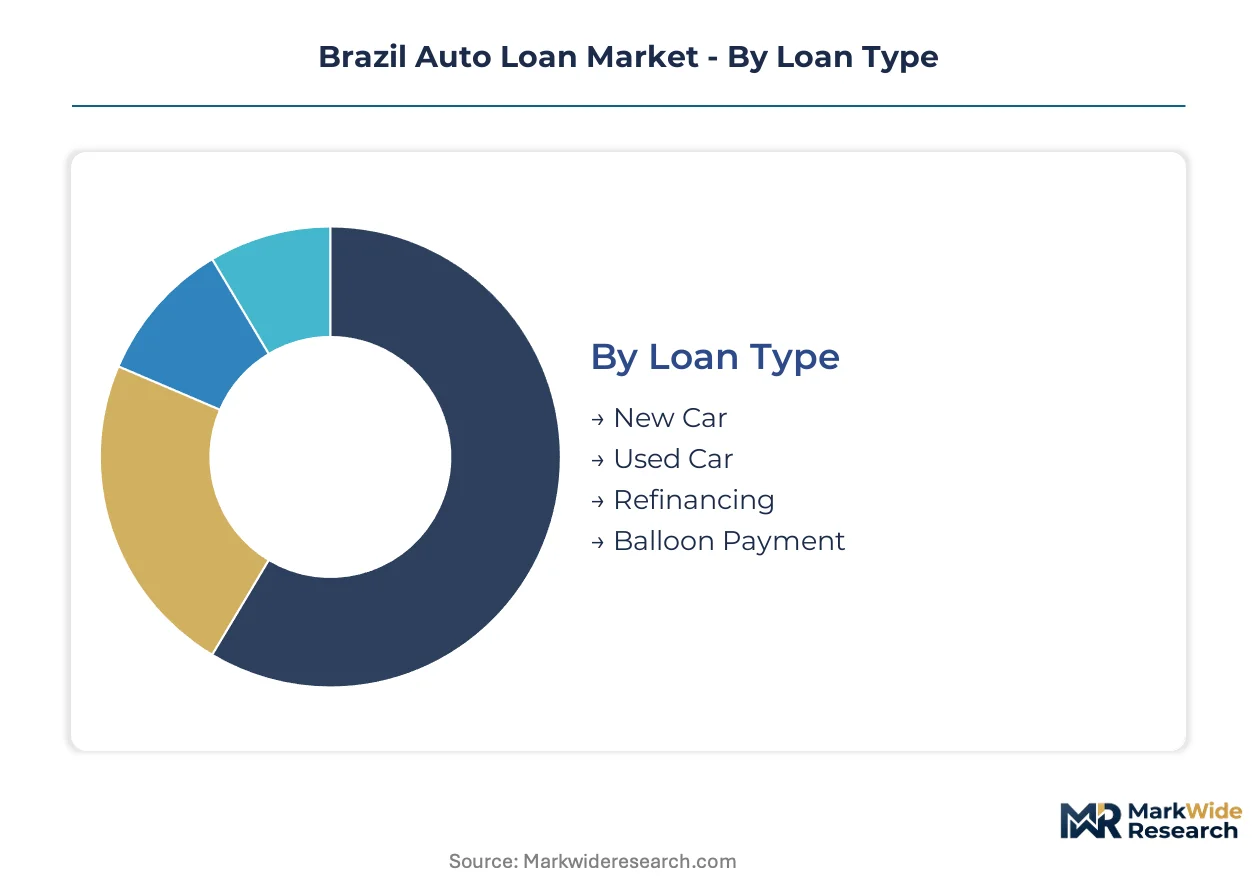
Auto loan segmentation in Brazil reflects the country's heterogeneous credit landscape, where formal employment density, vehicle depreciation curves, and manufacturer subsidy programs create divergent risk-return profiles across borrower categories. Lenders calibrate provisioning models and dealership commission structures around these segment boundaries, with Banco Central do Brasil's Resolution No. 4,893 imposing differential capital requirements based on loan duration and collateral type.
Loan Type:
New vehicle financing commands premium pricing through manufacturer captive finance subsidies, while used car and refinancing products serve credit-constrained borrowers outside São Paulo's formal employment belt.
- New Car:Captive finance arms structure these loans around manufacturer invoice subsidies and residual value guarantees, concentrating origination in São Paulo state's ABC industrial corridor where assembly plants cluster. Banco Central do Brasil's stricter loan-to-value caps under Resolution No. 4,893 compress margin pools here.
- Used Car:Collateral valuation depends on ANVISA safety standard compliance and regional depreciation schedules, with demand accelerating in Brazil's interior states where new vehicle penetration lags metropolitan benchmarks. Age eligibility thresholds are widening fastest in this segment.
- Refinancing:Existing collateral-backed restructuring for liquidity-constrained borrowers, typically triggered by Selic rate spikes or employment disruption.
- Balloon Payment:Structures residual value risk transfer to end-term, common in fleet procurement contracts along logistics corridors.
Established volume favors New Car; emerging adoption favors Used Car.
Customer Type:
Cost tier differentiation separates payroll-linked individual borrowers from commercial clients managing fleet depreciation across decentralized logistics networks.
- Individual Buyers:Salary-deductible credit dominates in formal employment zones, with Itau Unibanco's risk-scoring models leveraging instant payment infrastructure for public sector workers. Thin-file borrowers in peripheral metropolitan zones drive digital-first platform adoption.
- Fleet Operators:E-commerce fulfillment networks across Mato Grosso and Pará finance commercial vehicle acquisitions through captive arms, with procurement fragmenting across independent subcontractors rather than national consolidators.
- Dealerships:Inventory floorplan financing sustains working capital cycles for multi-brand networks in Brazil's interior.
- Corporate Clients:Structured fleet leases with maintenance bundling, concentrated in São Paulo state's logistics corridors serving Santos port infrastructure.
Margin stability favors Fleet Operators; volume expansion favors Individual Buyers.
Loan Duration:
Application-based structuring matches amortization schedules to vehicle economic life and borrower cash flow predictability across Brazil's interest rate cycles.
- Short-term:12-24 month structures for premium collateral and high-credit-score borrowers, minimizing Selic rate exposure.
- Medium-term:36-48 month standard for new vehicle purchases, balancing monthly payment affordability with residual value risk.
- Long-term:60-84 month products extend to used vehicle segments and income-constrained borrowers in Brazil's Northeast corridor, though Banco Central do Brasil's debt-to-income thresholds constrain origination here.
- Flexible Terms:Seasonal payment adjustments for agricultural and logistics clients with cyclical revenue patterns.
Risk-adjusted returns favor Medium-term; regulatory pressure concentrates on Long-term.
Interest Rate Type:
Maturity-based preferences separate risk-averse retail borrowers from corporate clients managing interest rate exposure through hybrid structures.
- Fixed Rate:Predominant among individual borrowers seeking payment certainty, with pricing indexed to pre-determined Selic rate assumptions at origination.
- Variable Rate:Direct Selic transmission squeezes net interest margins during monetary tightening cycles, concentrating in corporate refinancing products.
- Hybrid Rate:Fixed initial periods transitioning to variable structures, gaining traction among fleet operators managing medium-term interest rate exposure.
- Promotional Rate:Manufacturer-subsidized teaser rates for new vehicle launches, concentrated in captive finance originations.
Portfolio stability favors Fixed Rate; corporate hedging demand favors Hybrid Rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo state's industrial belt commands premium pricing power through dense dealership networks, while Brazil's Northeast corridor operates under thinner margin structures due to lower formal employment density and higher portfolio risk.
São Paulo
Vehicle assembly clusters in the ABC region generate captive finance volume through manufacturer-subsidized programs. Banco Central do Brasil's Resolution No. 4,893 imposes stricter debt-to-income thresholds here, compressing origination capacity for thin-file borrowers. Digital-first platforms are embedding pre-qualification APIs at point-of-sale terminals across dealership networks in São Paulo metropolitan zones.
Minas Gerais
Belo Horizonte's logistics subcontractors are fragmenting fleet procurement across independent truck operators rather than national consolidators. Banco Central do Brasil's open banking protocols enable real-time income verification for thin-file borrowers in peripheral metropolitan areas. Fintech originators headquartered here are re-platforming faster than legacy banks due to lighter COBOL-based system burdens.
Rio de Janeiro
Port infrastructure serving Santos competes with Rio's maritime terminals for commercial vehicle financing tied to cargo logistics. The National Monetary Council's capital reserve floors constrain smaller regional lenders from scaling originations in this market. Fleet operators along the BR-116 corridor linking Rio to São Paulo are deploying hybrid interest rate structures to manage Selic exposure.
Bahia
Salvador metropolitan zones exhibit vehicle ownership gaps relative to income levels, presenting origination white space for digital platforms. ANVISA safety standard updates force premature depreciation on collateral pools, distorting loan-to-value ratios for used vehicle segments. Agricultural revenue cycles in the interior drive demand for flexible payment structures among rural borrowers.
Paraná
Curitiba's manufacturing supply chain feeds component production into São Paulo assembly plants, generating ancillary commercial vehicle demand. The Consumer Protection Code mandates interest rate disclosure formats that increase compliance costs for non-bank lenders operating here. Regional banks struggle with legacy core system integration when embedding API-based credit decisioning platforms.
Brazil Auto Loan Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the origination stack. The market structures around three dominant archetypes: universal banks with payroll-linked underwriting infrastructure, captive finance arms tied to manufacturer distribution networks, and digital-native originators leveraging open banking data protocols. Competitive moves concentrate on API-based dealership integration and receivables securitization through FIDC structures.
Among Brazil-based lenders, Itau Unibanco, Banco Pan, and BV Financeira exemplify the three strategic archetypes. Itau Unibanco occupies the premium-tier position through sophisticated risk-scoring models tied to public sector payroll data. Banco Pan represents the digital-first vector, reducing branch dependency through platform-based origination. BV Financeira anchors the captive finance tier, sustaining deep dealership integration across Brazil's interior states through manufacturer-aligned distribution.
| Leading Market Players |
|---|
| Santander |
| BV Financeira |
| Banco do Brasil |
| Banco Safra |
| Banco Pan |
| Caixa Economica Federal |
| Itau Unibanco |
| Nubank |
| Banco Bradesco |
| Others |
Pricing and Supply Chain Analysis
The BR-163 corridor linking Mato Grosso agricultural zones to Santos port infrastructure concentrates freight cost dynamics that cascade through vehicle procurement pricing, with logistics subcontractor fragmentation amplifying price differentiation between captive finance-subsidized new vehicle tiers and thin-margin used collateral products across Brazil's interior states.
Pricing Analysis
The customization-premium spread separates manufacturer-configured fleet orders from standard retail products, with three-tier pricing structure across premium, standard, and economy levels anchored by captive finance subsidy pools, formal employment-linked payroll deduction eligibility, and geographic delivery cost differentials. Cost compression in the economy tier intensifies because digital-first originators compress origination economics without branch infrastructure. Fleet operators managing decentralized logistics subcontractors exhibit lowest price sensitivity; thin-file individual borrowers in Brazil's Northeast corridor demonstrate highest sensitivity to monthly payment thresholds.
Supply Chain Analysis
Supplier-financing facilities extended by component manufacturers to assembly plants in São Paulo state's ABC region create working capital dependencies that transmit through dealer floorplan arrangements to end-borrower pricing. Vehicle assembly draws from Brazil, Argentina, and Mexico production clusters; steel inputs, electronic control modules, and tire assemblies constitute critical component dependencies. Single-source vulnerability concentrates in semiconductor-dependent advanced driver-assistance systems. Distribution runs through captive finance-aligned dealership networks rather than independent broker channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward fragmented logistics subcontractors across Brazil's interior, eroding the volume concentration historically enjoyed by national fleet consolidators and forcing lenders toward micro-ticket underwriting capabilities.
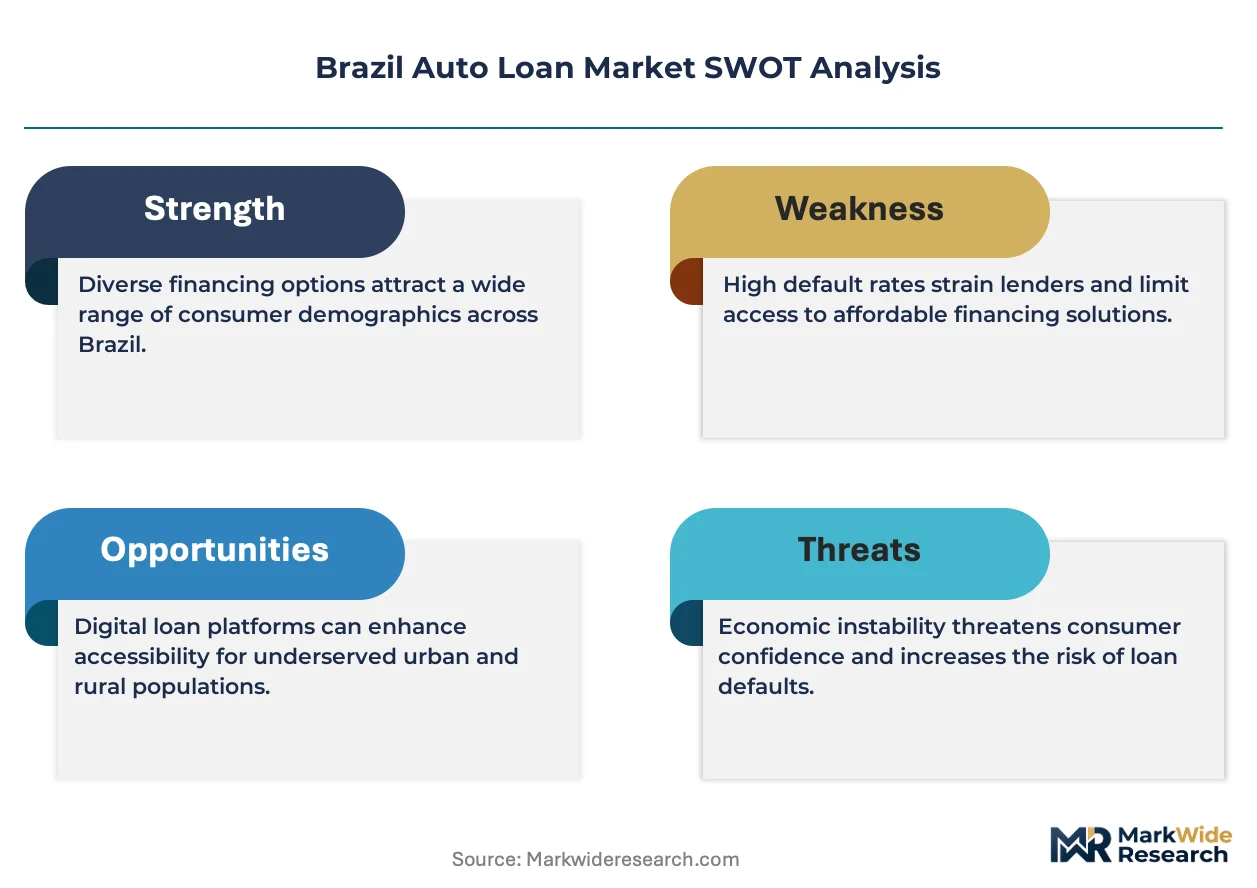
For Market Incumbents: Insulate core profitability by deepening API-based dealership integration before digital-native originators capture point-of-sale pre-qualification workflows, and accelerate payroll-linked underwriting infrastructure deployment to defend against open banking-enabled fintech scoring models. Banco Central do Brasil's Resolution No. 4,893 provisioning requirements threaten margin compression; vertical integration into collateral valuation services offers countervailing pricing power.
For New Entrants and Emerging Players: Mid-market used vehicle financing in Brazil's Northeast corridor represents the most penetrable entry point, with Salvador and Recife metropolitan zones exhibiting vehicle ownership gaps relative to income levels that bypass incumbent branch network density. Digital-first origination platforms embedding instant payment infrastructure verification enable thin-file borrower access without legacy COBOL system transformation costs.
For Investors and Strategic Acquirers: Banco Central do Brasil's open banking protocol implementation reshapes the acquisition landscape toward data-integrated originators with real-time credit bureau connectivity rather than deposit-dependent legacy lenders. Five-to-ten year viability favors platforms with receivables securitization capabilities through FIDC structures. The signal to watch is Selic rate trajectory compression enabling fixed-rate product margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| FIDC Securitization Structure Deployment | Non-bank lenders tap institutional capital pools beyond traditional deposit bases. |
| API-Based Dealership Integration | Pre-qualification at point-of-sale terminals collapses approval timelines to under ten minutes. |
| Payroll-Linked Underwriting Expansion | Instant payment infrastructure enables risk-scoring refinement for public sector borrowers. |
| Northeast Corridor Digital Penetration | Salvador and Recife zones offer origination white space with lower incumbent density. |
| Used Vehicle Collateral Age Threshold Widening | Second-hand market volume unlocks without competing for manufacturer subsidy pools. |
Research Methodology
A spread of perspectives from auto loan origination executives, dealership network managers, captive finance risk officers, and fintech platform engineers converged on the working assumptions underlying this analysis. Primary interviews combined with secondary validation from Banco Central do Brasil regulatory filings, ANVISA safety standard updates, National Monetary Council capital requirement disclosures, and vehicle registration databases. Bottom-up origination volume modeling and top-down credit penetration rate analysis provided triangulation.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning loan type, customer category, duration structure, and interest rate mechanism alongside regional formal employment density differentials. CAGRs derived from cohort-level vintage loss rate projections and origination capacity constraints. Selic rate path assumptions and open banking adoption curves constituted industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in monetary policy trajectory, agricultural commodity export revenues, or logistics sector employment would shift the trajectory. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Syndicated Loans Market
Loans and Leasing
Factoring Market
Loans and Leasing
Europe Automotive Finance Market
Loans and Leasing
Asia-Pacific Used Car Financing Market
Loans and Leasing
China Auto Loan Market
Loans and Leasing
Working Capital Loan Market
Loans and Leasing
Europe Syndicated Loans Market
Loans and Leasing
Alternative Financing Market
Loans and Leasing
Australia Automotive Financing Market
Loans and Leasing
Loan Origination Software Market
Loans and Leasing
Truck Financial Leasing Market
Loans and Leasing
Mexico Home Equity Lending Market
Loans and Leasing
Latin America Motorcycle Loan Market
Loans and Leasing
Used Car Financing Market
Loans and Leasing
US Auto Loan Market
Loans and Leasing
US Home Equity Lending Market