
 Unsecured Business Loans Market | 2026-2036
Unsecured Business Loans Market Size, Share, and Industry Trends Forecast 2026-2036
Unsecured Business Loans Market Analysis
Prime-grade unsecured credit standards are reorganizing how lenders assess borrower risk without collateral backing. Bank of America leverages its deposit base to pre-qualify existing business clients for uncollateralized lines of credit. Wells Fargo sustains regional branch networks that originate relationship-driven term loans to established firms. JPMorgan Chase competes through proprietary cash-flow analytics that replace traditional asset-based underwriting for small business applicants.
An unsecured business loan constitutes debt financing extended to commercial entities solely on creditworthiness and projected cash flows, with loan amounts typically ranging from ten thousand to five hundred thousand dollars and repayment periods spanning six months to five years. These instruments serve primarily to bridge liquidity gaps, finance inventory cycles, and fund operational expansion without encumbering fixed assets. Term loans and lines of credit together anchor the product mix, while merchant cash advances capture higher-risk segments at elevated pricing tiers. Start-up funding within application-purpose segmentation shows the steepest origination velocity, though working capital maintains the deepest margin pool through repeat borrowing behavior.
The Consumer Financial Protection Bureau shapes disclosure requirements for unsecured commercial credit products in the United States, while the Federal Reserve's stress-testing frameworks indirectly constrain bank willingness to hold uncollateralized exposures on balance sheets. The SEC oversees certain non-bank lending platforms that securitize originated receivables, adding compliance layers to fintech scaling strategies. Stakeholders must monitor how Basel III endgame capital rules recalibrate risk-weighted asset treatment for unsecured business exposures across chartered institutions.
Market Dynamics
Real-time cash-flow analytics is displacing collateral-based underwriting as the dominant risk assessment methodology, forcing lenders to rebuild core infrastructure around alternative data ingestion and algorithmic scoring engines.
Growth Catalysts
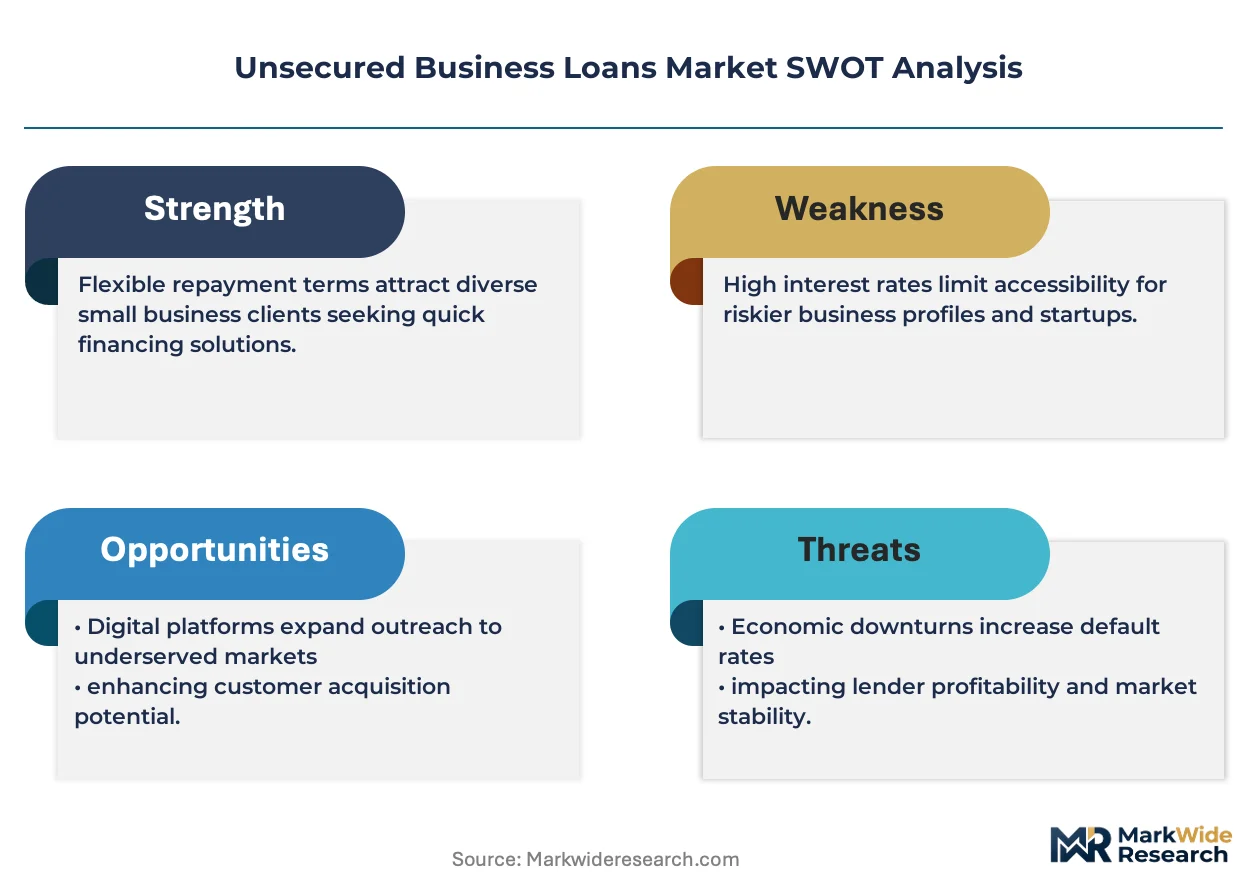
- Open Banking Frameworks:PSD2 in Europe and similar data-sharing mandates in Australia and Brazil are forcing incumbent banks to expose transaction histories, enabling fintech lenders to assess creditworthiness without traditional collateral verification.
- Embedded Finance:E-commerce platforms and payroll software providers are integrating uncollateralized working capital directly into merchant dashboards, capturing borrowers at their point of liquidity need.
- Cloud-Native Core Systems:Modern loan origination platforms built on AWS and Azure infrastructure are compressing deployment timelines from months to weeks for regional lenders.
Market Restraints
- Basel III Endgame Capital Rules:Proposed risk-weighting increases for unsecured commercial exposures are constraining large chartered banks' willingness to hold these loans on balance sheets.
- Funding Cost Volatility:Regional and community banks dependent on brokered deposits face margin compression when Federal Reserve policy shifts rapidly.
- Alternative Credit Substitution:Revenue-based financing and invoice factoring platforms are siphoning higher-risk borrowers who would otherwise qualify for unsecured term products.
Strategic Opportunities
- Underpenetrated Manufacturing Clusters:Industrial zones in Vietnam and Mexico host thousands of small suppliers lacking established banking relationships, creating first-mover advantages for digital lenders with local payment integrations.
- AI-Driven Behavioral Scoring:Machine learning models analyzing supply chain payment patterns and inventory turnover are unlocking credit access for businesses with thin traditional credit files.
- Real-Time Payments Infrastructure:FedNow and similar instant settlement systems are enabling daily repayment structures that reduce default risk through continuous cash-flow monitoring.
Industry Challenges
- Data Science Talent Scarcity:Lenders struggle to hire quantitative risk analysts capable of building and validating alternative credit models that satisfy model risk management requirements.
- Legacy Core Integration Complexity:Banks with decades-old loan servicing systems face multi-year migration timelines to connect modern origination platforms with existing general ledgers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unsecured Business Loans Market |
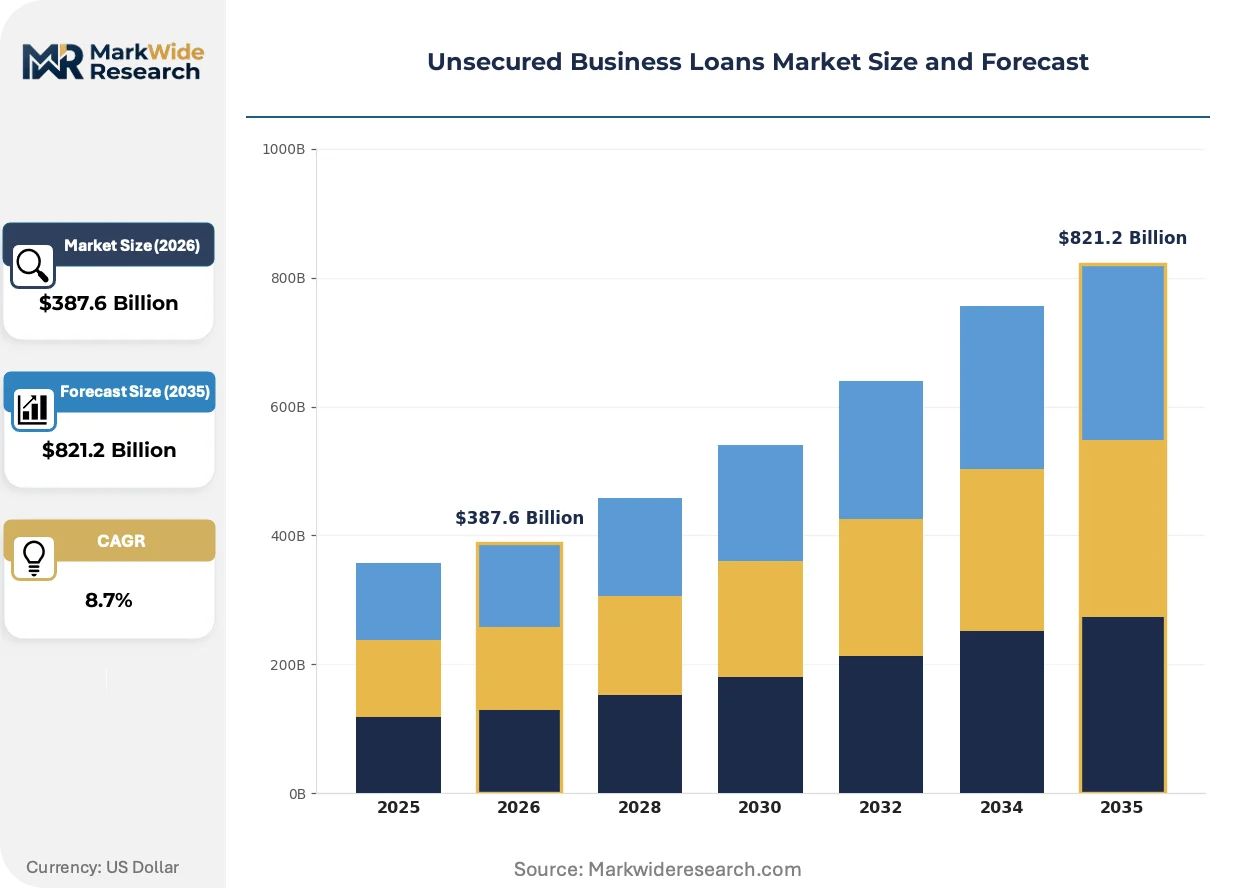
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Term Loans, Lines of Credit, Merchant Cash Advances, Business Credit Cards Application Purpose: Working Capital, Equipment Purchase, Debt Consolidation, Start-up Funding Industry Vertical: Retail, Hospitality, Healthcare, Construction Borrower Profile: Small Businesses, Start-ups, Established Firms, Non-profits |
| Companies Covered | Bank of America, Wells Fargo, American Express, Bluevine, JPMorgan Chase, HDFC Bank, Deutsche Bank, Funding Circle, Bank of China, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unsecured Business Loans Market Emerging Trajectories
Alternative data ingestion and machine learning scoring are compressing traditional underwriting timelines from weeks to minutes, fundamentally altering how lenders compete for borrower relationships.
Machine learning models analyzing real-time bank transaction feeds, payroll records, and accounting software APIs are displacing manual financial statement review and tax return verification. Mid-market fintech lenders deploy these systems most aggressively, capturing borrowers abandoned by banks with rigid collateral requirements. The structural consequence is margin compression for relationship-driven branch networks that cannot match decision speed.
The Consumer Financial Protection Bureau's Section 1033 rulemaking on consumer financial data rights is extending disclosure requirements toward small business credit products, forcing lenders to standardize pricing presentations and comparison tools. Origination platforms must now build compliance infrastructure that accommodates both consumer-style disclosures and commercial loan complexity. Fintech-bank partnerships face particular friction as they reconcile divergent compliance frameworks across shared balance sheets.
Small business owners increasingly demand integrated capital access within operational software rather than standalone banking relationships. Accounting platforms like QuickBooks and Xero are embedding pre-qualified credit lines that surface at invoice generation or payroll processing moments. This channel shift is most advanced in the United States and United Kingdom, where open banking infrastructure enables seamless data consent workflows between software providers and lenders.
Unsecured Business Loans Market Segmentation
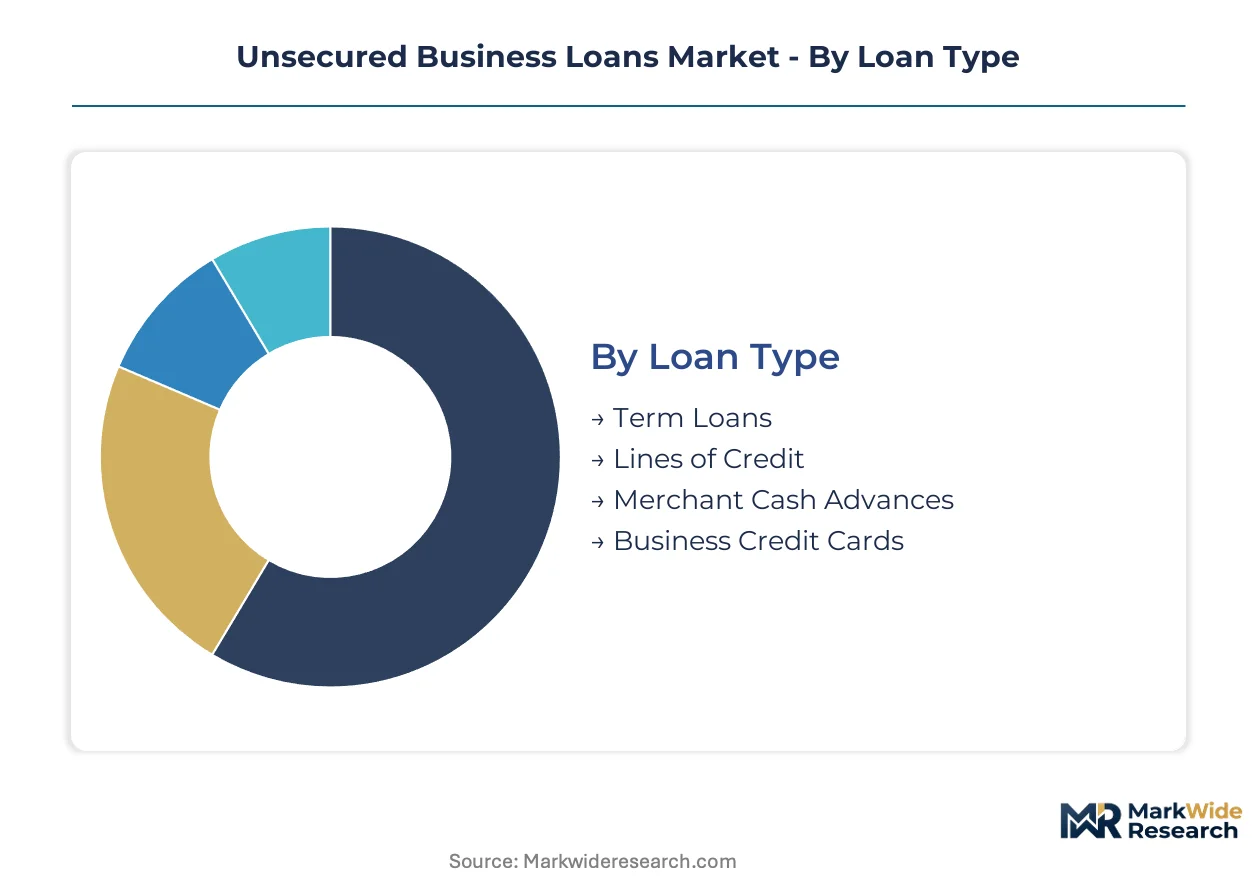
Unsecured business loan segmentation reveals how substitution pressures from alternative financing reshape competitive positioning across product categories. Lenders must align origination infrastructure with borrower risk profiles and liquidity timing preferences to defend margin pools.
Loan Type:
Merchant cash advances face the strongest substitution threat from revenue-based financing platforms, forcing traditional term products to differentiate through relationship pricing and covenant flexibility.
- Term Loans:Fixed-amount disbursements with scheduled amortization structures dominate equipment financing and expansion capital deployment. Demand concentrates among established firms in the United States seeking multi-year capital commitments without asset encumbrance, though Basel III endgame capital rules constrain bank willingness to hold these exposures.
- Lines of Credit:Revolving structures with draw-down flexibility serve seasonal inventory cycles and receivable gaps. Borrowers in retail and hospitality verticals favor these instruments for their interest-only payment periods, driving repeat utilization behavior that deepens lender-borrower data integration.
- Merchant Cash Advances:Future receivable purchases at factor rates appeal to businesses with inconsistent cash flow patterns. Fintech platforms displace traditional MCA originators through real-time sales data connectivity.
- Business Credit Cards:Revolving unsecured credit with rewards structures captures low-dollar, high-frequency borrowing needs. Corporate expense management platforms embed these products into spend control workflows.
Term loans anchor the volume base while lines of credit gain share at the steepest rate.
Application Purpose:
Cost tier differentiation separates working capital borrowers seeking rapid turnaround from expansion-focused applicants accepting longer underwriting cycles.
- Working Capital:Short-term liquidity bridges for payroll, inventory, and operational expenses constitute the deepest origination pool. Small businesses in cyclical industries favor these instruments for their rapid decision timelines, with embedded finance platforms capturing demand at point-of-need moments.
- Start-up Funding:Early-stage capital for unproven revenue models carries elevated default risk and pricing premiums. Fintech lenders with alternative data capabilities expand access for businesses lacking traditional credit histories, though regulatory scrutiny of fair lending algorithms intensifies.
- Equipment Purchase:Purpose-specific financing for machinery and technology assets competes directly with equipment leasing and secured term products.
- Debt Consolidation:Refinancing multiple obligations into single uncollateralized structures appeals to borrowers seeking payment simplification and rate reduction.
Working capital commands the widest origination bandwidth while start-up funding climbs fastest among application purposes.
Industry Vertical:
Volume concentration in retail and hospitality reflects these sectors' working capital intensity and limited fixed asset bases suitable for collateralization.
- Retail:Inventory-heavy operations with seasonal demand spikes drive consistent demand for revolving credit structures. E-commerce merchants increasingly access capital through platform-embedded lending partnerships that leverage real-time sales data for underwriting.
- Hospitality:Restaurants and hotels with irregular cash flow patterns favor flexible repayment structures tied to revenue performance. Merchant cash advance penetration remains highest in this vertical despite elevated cost of capital.
- Healthcare:Medical practices and clinics seek capital for technology upgrades and patient volume expansion, with revenue cycle characteristics supporting longer-term unsecured structures.
- Construction:Project-based contractors with bonded obligations and retention receivables present unique cash flow timing challenges that specialized lenders address through milestone-based disbursements.
Retail sustains the broadest borrower base while healthcare demonstrates the steepest expansion trajectory among verticals.
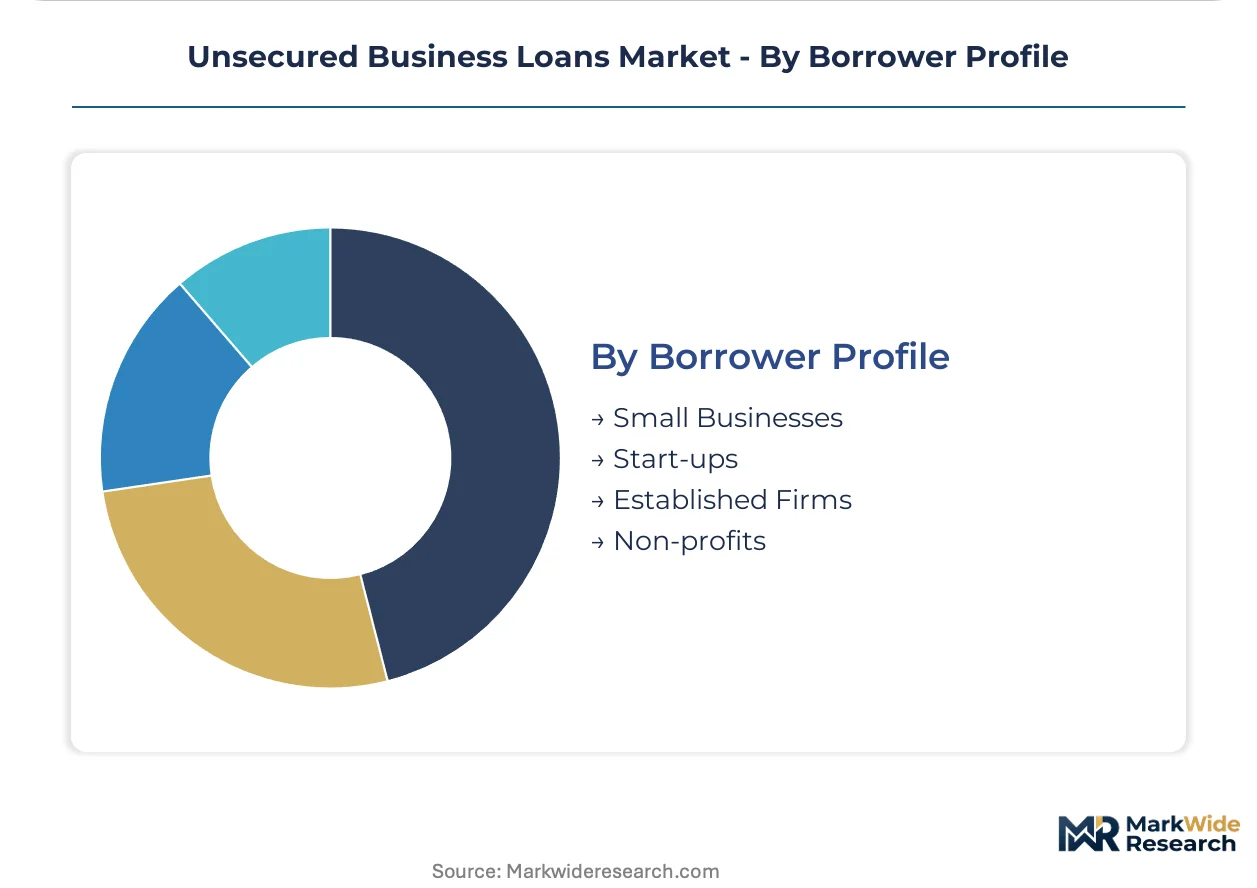
Borrower Profile:
Customer type stratification determines pricing power, with established firms commanding the most favorable terms and start-ups absorbing risk premiums that reflect information asymmetry.
- Small Businesses:Firms with under fifty employees generate the highest application velocity and represent the primary target for digital lending platforms. Open banking infrastructure enables these borrowers to demonstrate creditworthiness through transaction data rather than collateral assets.
- Established Firms:Mature enterprises with demonstrated cash flow histories access relationship-driven pricing from chartered banks. JPMorgan Chase and Bank of America compete aggressively for this segment through proprietary analytics and deposit-based pre-qualification.
- Start-ups:Pre-revenue and early-revenue ventures face limited traditional credit access, driving demand toward alternative lenders and revenue-based financing structures.
- Non-profits:Mission-driven organizations with restricted revenue streams require specialized underwriting approaches that assess grant funding stability and donor concentration risk.
Small businesses provide the deepest origination pool while established firms deliver the strongest unit economics through repeat borrowing and cross-sell opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chartered banks in the United States dominate origination capacity for unsecured commercial credit, while digital platforms in the United Kingdom and India accelerate market share capture through alternative data infrastructure. Regulatory divergence across major economies shapes competitive entry costs and borrower access patterns.
United States
Fintech-bank partnerships drive working capital access for underbanked small businesses across the Southeast and Southwest. The Consumer Financial Protection Bureau's Section 1033 rulemaking on data rights forces standardization in pricing disclosures. Dallas and Atlanta host expanding regional lender operations targeting Main Street borrowers with real-time underwriting.
United Kingdom
Open Banking mandates under PSD2 enable transaction-based credit assessments without collateral verification. The Financial Conduct Authority oversees embedded finance integrations between accounting software and lending platforms. London concentrates fintech origination platforms competing for SME market share through API-connected cash flow analytics.
Germany
Sparkassen and cooperative banks maintain relationship-driven term lending to Mittelstand firms with established credit histories. BaFin supervises digital lending platforms expanding into commercial credit products. The Rhine-Ruhr industrial corridor generates concentrated demand for inventory financing among manufacturing suppliers.
India
Account aggregator frameworks under RBI regulation enable consent-based financial data sharing for MSME credit scoring. The Reserve Bank of India's priority sector lending requirements push scheduled commercial banks toward uncollateralized small business exposure. Mumbai and Bangalore anchor fintech origination platforms serving tier-2 city manufacturing clusters.
China
Commercial banks face pressure from internet platforms leveraging payment data for merchant cash advance products. The People's Bank of China and National Financial Regulatory Administration tighten oversight of online lending rates and data usage. The Yangtze River Delta hosts the deepest concentration of SME borrowers accessing working capital through digital channels.
Unsecured Business Loans Market Vendor Landscape
Concentration sits with diversified financial holding companies that combine deposit bases with proprietary analytics infrastructure. The competitive structure spans three tiers: global money-center banks with relationship-driven origination, regional banks dependent on branch networks, and fintech platforms leveraging alternative data for automated underwriting. Dominant competitive moves include strategic partnerships between chartered banks and technology platforms, plus portfolio diversification into embedded finance distribution channels.
Within the global banking tier, JPMorgan Chase, Bank of America, and Wells Fargo anchor relationship-driven commercial lending through deposit-based pre-qualification and cash flow analytics. These institutions exemplify the incumbent archetype defending market position through regulatory compliance infrastructure and balance sheet scale. Among digitally native platforms, Bluevine and Funding Circle occupy positions representing the alternative data-driven underwriting model, competing on decision velocity rather than collateral requirements.
| Leading Market Players |
|---|
| Bank of America |
| Wells Fargo |
| American Express |
| Bluevine |
| JPMorgan Chase |
| HDFC Bank |
| Deutsche Bank |
| Funding Circle |
| Bank of China |
| Others |
Supply Flow & Price Mechanics
Cloud-native core systems replacing legacy loan origination infrastructure are simultaneously redrawing supply geography toward AWS and Azure data centers and compressing deployment cost structures for regional lenders. This substitution dynamic concentrates vendor power among hyperscale cloud providers while eroding pricing premiums previously commanded by on-premise software incumbents.
Pricing Analysis
The Consumer Financial Protection Bureau's Section 1033 rulemaking dictates the pricing tier structure for unsecured business credit products. Three-tier pricing structure across premium relationship-driven, standard algorithmic, and economy embedded-finance levels separates borrowers by data integration depth and underwriting speed. Price differentiation rests on cash-flow analytics sophistication and open banking connectivity, with premium tiers commanding spreads for covenant flexibility. Cost compression in the standard tier is intensifying because fintech platforms match bank decision velocity without branch overhead. Small businesses with thin credit files exhibit highest price sensitivity; established firms with deposit relationships show lowest.
Supply Chain Analysis
Inventory-light origination platforms compress capital deployment timelines from weeks to hours, eliminating traditional lead-time buffers. Supply concentrates in the United States, United Kingdom, and India, each anchoring distinct regulatory frameworks for data sharing and alternative credit scoring. Raw material dependencies include real-time payment infrastructure, accounting software APIs, and cloud compute capacity. Single-source vulnerability sits with hyperscale cloud providers hosting critical underwriting engines. Distribution runs through embedded finance partnerships with payroll and e-commerce platforms rather than standalone branch networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Unsecured business lending represents an early-cycle expansion story as open banking mandates and real-time payment infrastructure unlock credit access for previously collateral-dependent borrowers. Embedded finance integrations accelerate adoption velocity by surfacing capital at points of operational liquidity need.
For Market Incumbents: Shield deposit-based pre-qualification advantages through deeper cash-flow analytics integration and faster covenant restructuring. Incumbents must accelerate legacy core migration timelines to match fintech decision velocity. Vertical integration into proprietary data networks defends against alternative-scoring displacement.
For New Entrants and Emerging Players: Anchor in manufacturing supplier clusters across Vietnam and Mexico where banking relationships remain underdeveloped. Underpenetrated industrial zones with local payment integration gaps offer first-mover positioning. Revenue-based financing structures provide the most penetrable entry angle for borrowers with irregular cash flow patterns.
For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors acquirers with alternative data infrastructure and regulatory compliance scale. Long-term viability hinges on underwriting model performance through credit cycle stress. Acquisition target archetype: fintech platforms with proven behavioral scoring engines and embedded distribution partnerships. Watch FedNow adoption velocity as inflection indicator for daily-repayment product viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Open Banking Partnership | PSD2 and Section 1033 compliance unlocks transaction-data underwriting for thin-file borrowers. |
| Embedded Finance Integration | QuickBooks and Xero partnerships capture demand at invoice-generation moments. |
| AI-Driven Scoring Investment | Machine learning on supply chain payment patterns expands credit access without collateral. |
| Real-Time Payments Adoption | FedNow connectivity enables daily repayment structures reducing default risk exposure. |
| Regulatory Compliance Scale | CFPB disclosure infrastructure and Basel III capital treatment expertise creates barriers. |
Methodological Framework
The analysis maps term loan, line of credit, merchant cash advance, and business credit card segments, each validated through chief risk officers, digital lending platform executives, commercial banking relationship managers, and regulatory compliance leads. Primary interviews combined with secondary validation from SEC filings, Federal Reserve stress test disclosures, Consumer Financial Protection Bureau rulemaking records, and open banking implementation reports. Bottom-up origination volume estimates triangulated against top-down banking sector unsecured credit exposure data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include loan type, application purpose, industry vertical, and borrower profile tier. CAGRs derived from origination velocity trends, regulatory implementation timelines, and technology adoption curves. Forecast inputs incorporated open banking penetration rates and real-time payments infrastructure deployment.
Decision-makers should treat outputs as directional under sustained regulatory support for data sharing and stable funding cost environments; material deviation in Basel III endgame implementation or deposit market volatility would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Student Loan Market
Loans and Leasing
Syndicated Loans Market
Loans and Leasing
Working Capital Loan Market
Loans and Leasing
US Factoring Services Market
Loans and Leasing
Loan Brokers Market
Loans and Leasing
Battery Leasing Service Market
Loans and Leasing
US Auto Loan Market
Loans and Leasing
Europe Home Mortgage Finance Market
Loans and Leasing
Canada Home Equity Lending Market
Loans and Leasing
Australia Education Student Loans Market
Loans and Leasing
Europe Auto Loan Market
Loans and Leasing
Online Payday Loans Market
Loans and Leasing
Enterprise Asset Leasing Market
Loans and Leasing
Asia-Pacific Auto Loan Market
Loans and Leasing
Asia-Pacific Syndicated Loans Market
Loans and Leasing
Europe Syndicated Loans Market