
 India Student Loan Market | 2026-2036
India Student Loan Market Size, Share, and Industry Trends Forecast 2026-2036
India Student Loan Market Insights
Modular loan packaging—combining tuition coverage with living-expense buffers and device-financing add-ons—is restructuring how Indian families evaluate borrowing costs. State Bank of India leverages its rural branch network to anchor disbursement volumes in underserved districts. HDFC Credila differentiates through specialized underwriting for overseas-education aspirants. Avanse competes on co-branded partnerships with private universities and ed-tech platforms.
An education loan constitutes a term credit instrument extended to students or co-applicants to finance tuition, accommodation, examination fees, and ancillary academic costs, typically secured by parental guarantees or tangible collateral for amounts exceeding INR 7.5 lakh. Its primary commercial purpose channels household liquidity toward human-capital formation while generating interest income for lenders over moratorium-plus-repayment tenures. Government Subsidized Loans occupy the deepest margin pools through interest-subvention schemes and credit-guarantee backstops, while Non-Banking Financial Companies are capturing the fastest growth in flexible repayment structures tailored to gig-economy earners and vocational trainees. Undergraduate Students remain the volume anchor, though Professional Courses command superior ticket sizes and shorter moratorium periods.
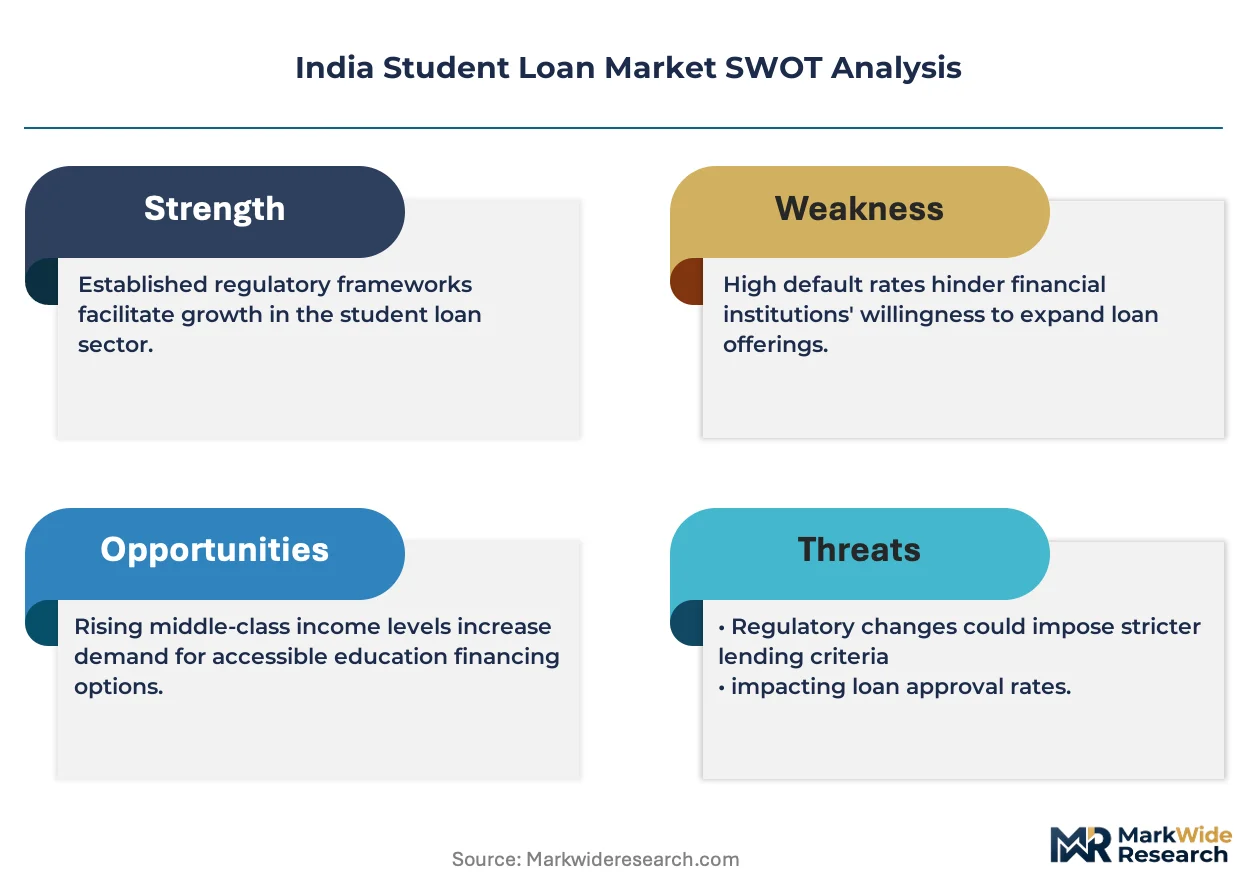
RBI's priority-sector lending mandates, CEA oversight of co-operative bank solvency, and the Finance Ministry's Interest Subsidy Scheme for Economically Weaker Sections collectively shape product design and eligibility thresholds across India's student-lending landscape. BIS data-security standards and RBI's digital-lending guidelines now govern how NBFCs and fintech intermediaries collect borrower consent and process co-applicant documentation. Stakeholders must monitor how the central bank's evolving exposure-norms for unsecured education credit affect capital-allocation decisions across public and private lending channels.
Market Dynamics
RBI's revised priority-sector lending norms are compressing credit allocation timelines and forcing domestic banks to rebalance portfolio weights toward education assets, fundamentally altering how lenders underwrite against human-capital collateral.
Growth Catalysts
- Priority-sector mandates:RBI's higher education credit quotas compel domestic banks to expand disbursement volumes in tier-2 and tier-3 cities, channeling institutional liquidity toward previously underserved borrower pools.
- Undergraduate enrollment density:Engineering and medical institution clusters in Maharashtra, Karnataka, and Tamil Nadu concentrate demand-pull, creating geographic anchors for ticket-size optimization and moratorium structuring.
- Interest subvention schemes:The Finance Ministry's Interest Subsidy Scheme for Economically Weaker Sections reduces effective borrowing costs, expanding addressable household segments beyond collateral-secured tiers.
Market Restraints
- Collateral requirements:Tangible asset backing for loans exceeding INR 7.5 lakh excludes asset-poor households, capping penetration in rural districts and among first-generation learners.
- Co-operative bank solvency risk:CEA oversight constraints limit channel depth in district-level markets where co-operative banks historically dominated education credit distribution.
- Moratorium compression:Professional courses command shorter repayment holidays, straining cash-flow matching for gig-economy earners and vocational trainees with irregular income streams.
Strategic Opportunities
- Modular loan packaging:Bundling tuition coverage with living-expense buffers and device-financing add-ons creates pricing differentiation and lifetime-value expansion for lenders serving domestic university segments.
- Overseas-education underwriting specialization:Tailored risk assessment for foreign-currency tuition obligations and visa-contingent repayment triggers opens margin pools beyond domestic institution coverage.
- Ed-tech platform integration:Embedded finance partnerships with private universities and online learning providers reduce acquisition costs and enable real-time enrollment verification.
Industry Challenges
- Digital consent architecture:BIS data-security standards and RBI's digital-lending guidelines impose documentation overhead on co-applicant verification, slowing disbursement velocity for fintech intermediaries.
- Exposure-norm uncertainty:Evolving central bank rules for unsecured education credit create capital-allocation ambiguity across public and private lending channels, complicating multi-year portfolio planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Student Loan Market |
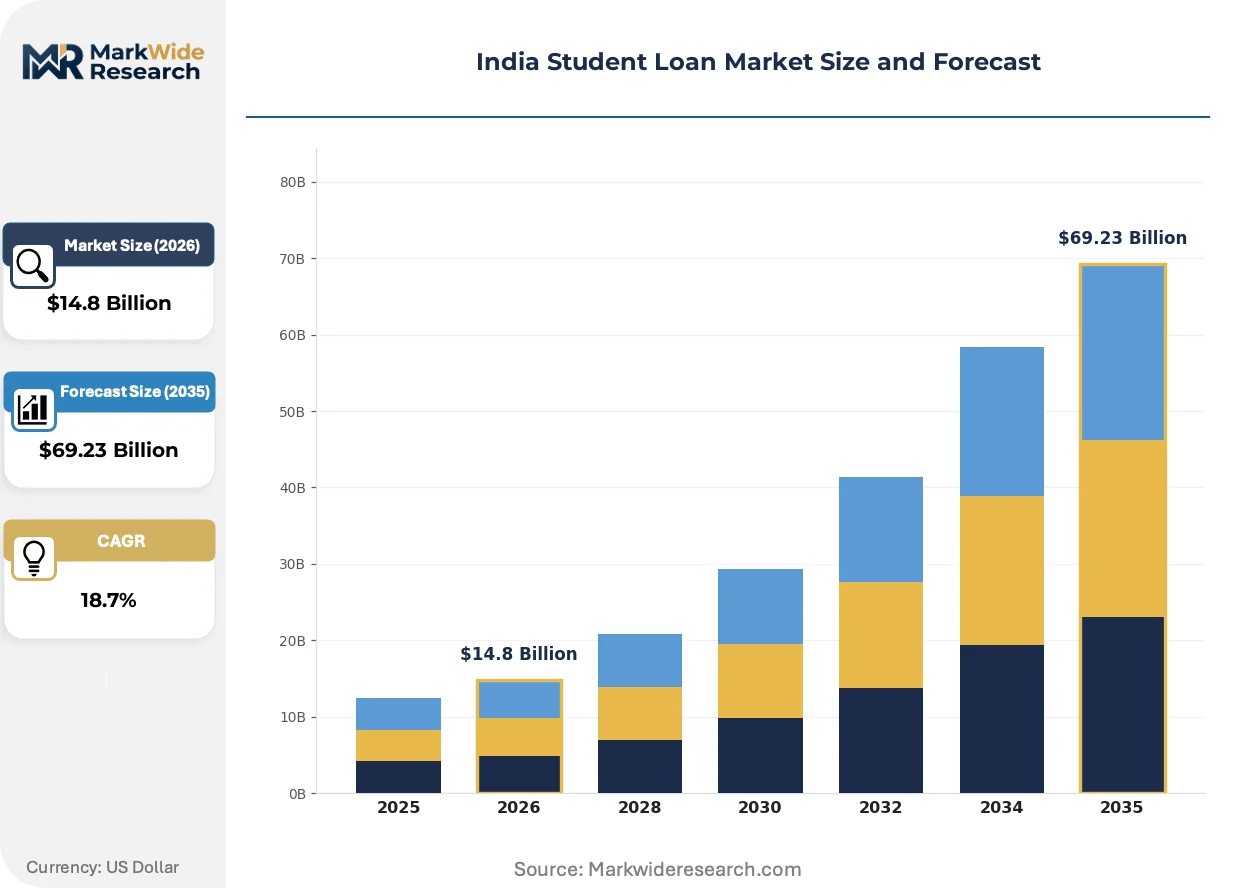
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $69.23 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Education Loan, Personal Loan, Government Subsidized Loan, Skill Development Loan End User: Undergraduate Students, Postgraduate Students, Professional Courses, Vocational Training Banking Institution: Private Banks, Public Sector Banks, Non-Banking Financial Companies, Cooperative Banks Repayment Structure: EMI, Interest-Only Payments, Lump Sum Payment, Flexible Repayment Plans |
| Companies Covered | State Bank of India, Union Bank of India, Bank of Baroda, Canara Bank, Punjab National Bank, HDFC Credila, Avanse, Propelld, Auxilo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Student Loan Market Trends and Innovations
Technology convergence and regulatory digitization are compressing origination timelines while reshaping how lenders segment borrowers by repayment capacity rather than collateral depth alone.
API-based credit decisioning is unifying income verification, academic enrollment checks, and co-applicant risk scoring into single-workflow origination platforms. Public sector banks and NBFCs are deploying these stacks to reduce turnaround from weeks to days. The structural consequence is unifying previously siloed data sources—tax records, university registries, and bureau scores—into real-time underwriting engines that compress cost-to-serve and expand eligibility beyond traditional collateral boundaries.
RBI's digital-lending guidelines now mandate granular borrower consent logs and co-applicant documentation trails for all algorithmic credit decisions. This regulatory architecture forces lenders to reengineer data pipelines and audit trails, raising compliance overhead but reducing dispute liability. NBFCs and fintech intermediaries face the steepest adaptation curve as they retrofit legacy collection mechanisms to meet BIS data-security standards.
Households are fragmenting loan procurement across multiple instruments—government-subsidized credit for tuition, personal loans for living expenses, and device financing for hardware—rather than accepting monolithic packages. This unbundling pressures lenders to compete on component pricing rather than bundled convenience. The pattern is most visible among undergraduate students in tier-2 cities, where digital comparison tools and aggregator platforms accelerate switching between specialized providers.
India Student Loan Market Segmentation
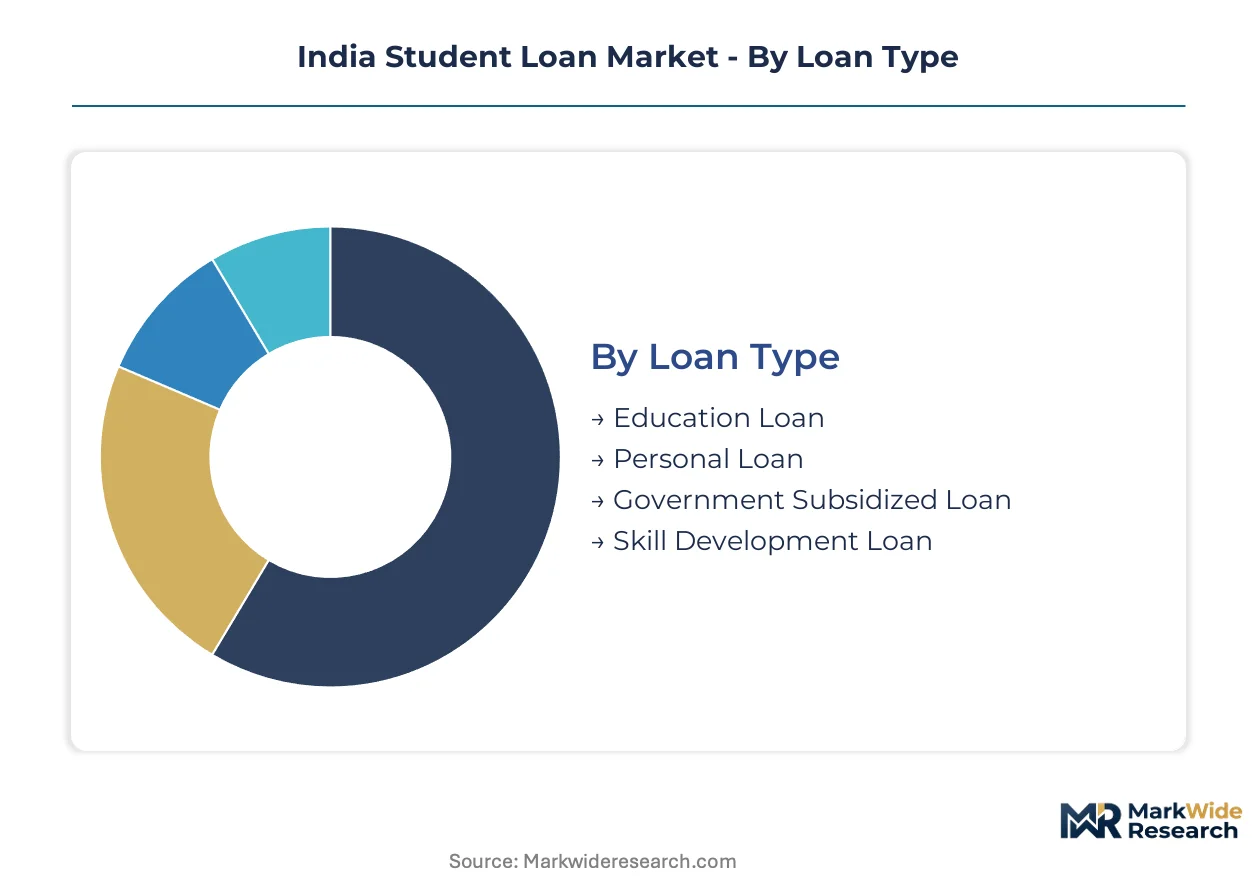
Segmentation in the India student loan market determines how lenders allocate capital, price risk, and structure moratoriums. Each dimension—loan instrument, borrower profile, channel type, and repayment mechanics—creates distinct underwriting protocols and margin profiles that shape competitive positioning.
Loan Type:
Standalone loan instruments serve discrete financing needs, while bundled products integrate tuition, living expenses, and device coverage into unified credit structures.
- Education Loan:A term credit instrument secured by parental guarantees or tangible collateral for amounts exceeding INR 7.5 lakh, covering tuition, accommodation, and examination fees. Demand concentrates in Maharashtra, Karnataka, and Tamil Nadu where engineering and medical institution density remains highest, with RBI priority-sector mandates compelling domestic banks to expand disbursement volumes.
- Government Subsidized Loan:Interest-subvention schemes backed by Finance Ministry guarantees reduce effective borrowing costs for Economically Weaker Sections. Penetration is deepest in rural districts and among first-generation learners where collateral requirements would otherwise exclude asset-poor households, though CEA oversight of co-operative bank solvency constrains channel depth in district-level markets.
- Personal Loan:Unsecured credit extended to students or co-applicants for ancillary academic costs outside formal education loan frameworks, typically carrying shorter tenures and higher interest rates.
- Skill Development Loan:Specialized financing for vocational trainees and gig-economy earners, structured around irregular income streams with compressed moratorium periods.
Volume placements concentrate in Education Loans; the faster expansion belongs to Government Subsidized Loans.
End User:
Borrower segmentation by academic stage determines ticket size, moratorium length, and co-applicant risk profiles.
- Undergraduate Students:The volume anchor across tier-2 and tier-3 cities, driving fresh disbursement volumes through modular loan packaging that bundles tuition coverage with living-expense buffers. Engineering and medical aspirants in Maharashtra, Karnataka, and Tamil Nadu generate concentrated demand-pull, while State Bank of India leverages its rural branch network to anchor volumes in underserved districts.
- Professional Courses:Command superior ticket sizes and shorter moratorium periods, straining cash-flow matching for borrowers with irregular income streams. HDFC Credila specializes in underwriting for this segment, particularly for overseas-education aspirants facing foreign-currency tuition obligations.
- Postgraduate Students:Typically combine government-subsidized credit for tuition with personal loans for living expenses, fragmenting procurement across multiple instruments.
- Vocational Training:Fastest-growing borrower pool as NBFCs capture market share through flexible repayment structures tailored to gig-economy earners, with Avanse competing via co-branded partnerships with ed-tech platforms.
Undergraduate Students anchor current disbursement volumes; Professional Courses are climbing the fastest on a value basis.
Banking Institution:
Channel type determines geographic reach, regulatory burden, and flexibility in repayment structuring.
- Public Sector Banks:Mandated by RBI priority-sector lending norms to maintain higher education credit quotas, compressing credit allocation timelines and forcing portfolio rebalancing toward education assets. State Bank of India deploys its rural branch network to dominate disbursement volumes in underserved districts.
- Non-Banking Financial Companies:Capture the fastest growth in flexible repayment structures, though BIS data-security standards and RBI digital-lending guidelines impose documentation overhead on co-applicant verification. API-based credit decisioning stacks reduce turnaround from weeks to days.
- Private Banks:Concentrate on premium borrower segments with established collateral profiles, competing on component pricing rather than bundled convenience.
- Cooperative Banks:Historically dominated education credit distribution in district-level markets, now constrained by CEA oversight of solvency risk that limits channel depth.
Public Sector Banks hold the deepest penetration; Non-Banking Financial Companies are gaining share fastest through digital origination platforms.
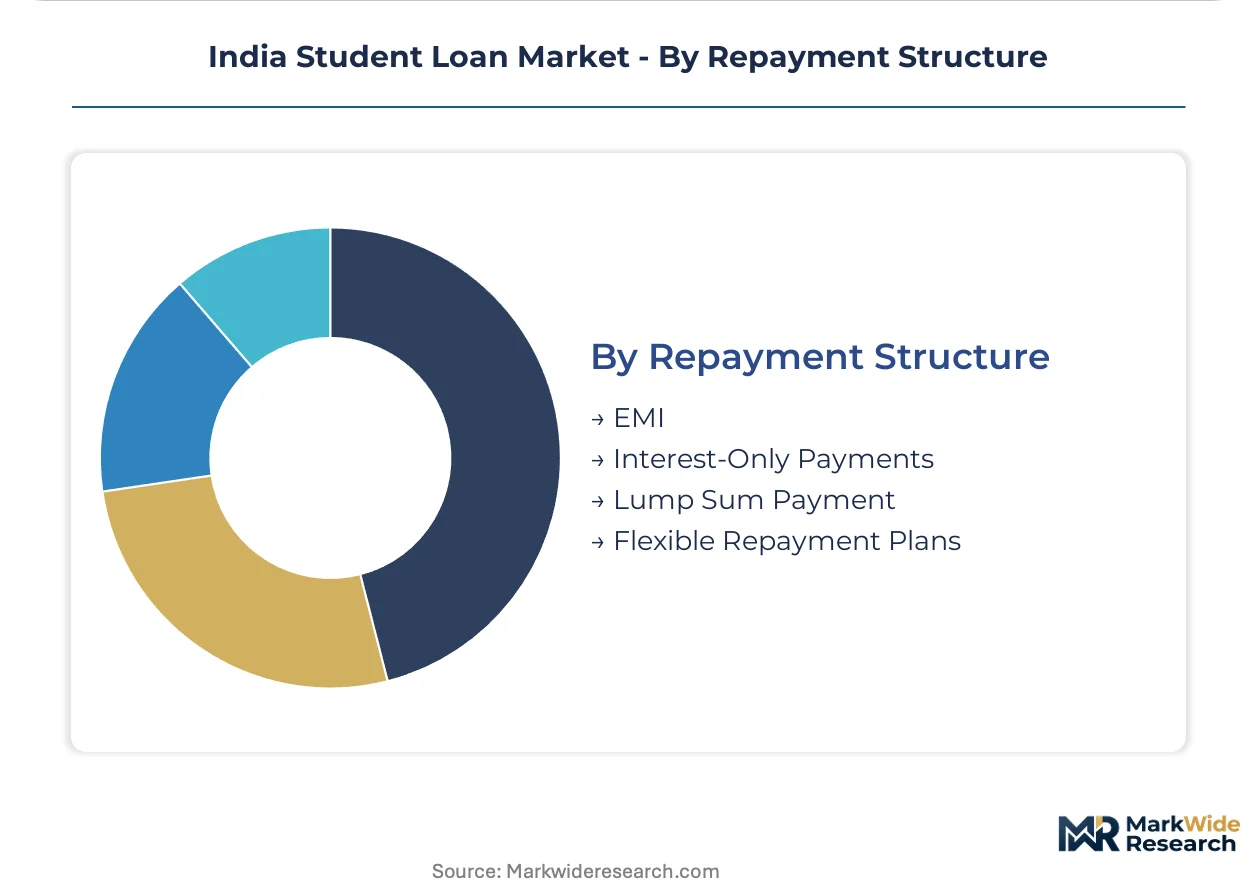
Repayment Structure:
Payment mechanics segment borrowers by cash-flow predictability and income regularity.
- EMI:Fixed monthly installments dominate conventional education loans, aligning with salaried co-applicants in formal employment. Public sector banks and NBFCs deploy API-based credit decisioning to verify income and compress origination timelines.
- Flexible Repayment Plans:Tailored to gig-economy earners and vocational trainees with irregular income streams, enabling income-contingent or seasonal payment schedules. NBFCs lead development of these structures, though evolving RBI exposure-norms for unsecured education credit create capital-allocation ambiguity.
- Interest-Only Payments:During study periods and initial moratorium phases, reducing immediate cash-flow burden on student borrowers.
- Lump Sum Payment:Typically requested by professional course graduates with concentrated signing bonuses or family liquidity events, more common in overseas-education segments.
EMI structures dominate current placements; Flexible Repayment Plans show the steepest expansion trajectory as NBFCs target gig-economy segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Disbursement volumes concentrate where engineering and medical institution density intersects with household borrowing capacity, while RBI mandates redistribute credit allocation toward previously underserved districts.
Maharashtra
Mumbai and Pune anchor the deepest education credit pools, with engineering college clusters driving ticket-size optimization. RBI priority-sector lending norms compel domestic banks to maintain higher education credit quotas across Marathwada and Vidarbha sub-regions. Nashik and Nagpur emerging as disbursement growth nodes as SBI deploys rural branch networks to capture first-generation learner segments.
Karnataka
Bengaluru's medical and technology institution density generates concentrated demand-pull for professional course financing. The state's digital infrastructure enables API-based credit decisioning stacks that compress origination timelines for NBFCs operating in Mysuru and Mangaluru satellite markets. Hubli-Dharwad corridor showing fastest disbursement velocity as co-branded partnerships with private universities expand.
Tamil Nadu
Chennai and Coimbatore engineering clusters sustain superior ticket sizes with shorter moratorium structures. CEA oversight of co-operative bank solvency constrains channel depth in Tiruchirappalli and Madurai district-level markets. Salem and Erode sub-regions experiencing fresh disbursement growth as modular loan packaging bundles tuition with device-financing add-ons.
Telangana
Hyderabad's pharmaceutical and technology training institutes create specialized underwriting demand for professional course segments. RBI digital-lending guidelines impose documentation overhead on co-applicant verification, slowing fintech intermediary velocity in Warangal and Nizamabad districts. Karimnagar and Khammam emerging as priority-sector mandate beneficiaries with expanded public sector bank presence.
Delhi-NCR
Overseas-education aspirants concentrate in the capital region, driving foreign-currency tuition obligation underwriting specialization. BIS data-security standards govern how NBFCs collect borrower consent across Gurugram and Noida digital lending operations. Faridabad and Ghaziabad sub-markets showing fragmented procurement patterns as households unbundle loan instruments across multiple providers.
India Student Loan Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across India's student lending architecture. Public sector banks leverage mandated priority-sector quotas and rural branch density to anchor volume positions in tier-2 and tier-3 cities. Three archetypes dominate: universal banks with government-backed distribution, NBFCs with digital origination platforms, and specialized education financiers with co-branded university partnerships. Competitive moves center on API-based credit decisioning deployment and modular product bundling that integrates tuition, living expenses, and device financing.
Among public sector universal banks, State Bank of India, Union Bank of India, and Bank of Baroda exemplify the scale-driven archetype that RBI mandates have fortified with compulsory education credit allocation. These institutions occupy positions defined by branch network depth rather than underwriting specialization. Within the NBFC tier, HDFC Credila and Avanse represent contrasting strategic postures—one anchored in overseas-education underwriting, the other in domestic co-branded platform integration.
| Leading Market Players |
|---|
| State Bank of India |
| Union Bank of India |
| Bank of Baroda |
| Canara Bank |
| Punjab National Bank |
| HDFC Credila |
| Avanse |
| Propelld |
| Auxilo |
| Others |
Pricing and Supply Chain Analysis
Captive integration of co-applicant verification and disbursement workflows anchors both operational scale and pricing power for lenders navigating RBI's digital-lending guidelines. This vertical control over documentation pipelines reduces per-unit origination costs while creating compliance moats that fintech intermediaries struggle to replicate.
Pricing Analysis
Margin tightening in unsecured education credit traces to evolving RBI exposure-norms that compress risk-adjusted returns for NBFCs. Three-tier pricing structure across collateral-secured, guarantor-backed, and unsecured tiers separates borrowers by asset depth and co-applicant profile. Price differentiation hinges on moratorium length and repayment flexibility, with gig-economy segments showing highest price sensitivity and overseas-education aspirants least. Cost-down pressure on digital origination accelerates because BIS data-security standards mandate audit-trail investments that smaller intermediaries cannot absorb.
Supply Chain Analysis
Hub-and-spoke distribution patterns concentrate credit decisioning in Mumbai, Bengaluru, and Hyderabad while satellite branches in tier-2 cities handle document collection and co-applicant verification. Geographic supply concentration centers on Maharashtra, Karnataka, and Tamil Nadu where engineering and medical institution density generates concentrated demand-pull. Raw material dependencies include credit bureau data from CICs, university enrollment registries, and tax-record verification APIs. Single-source vulnerability in co-operative bank channels—constrained by CEA solvency oversight—creates last-mile gaps in district-level markets. Distribution runs through public sector branch networks, NBFC digital platforms, and ed-tech embedded finance partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RBI's priority-sector lending mandates function as a cost-of-compliance barrier that fortifies incumbent positions while forcing new entrants to absorb capital-allocation constraints that domestic banks navigate through regulatory quota fulfillment.
For Market Incumbents: Lock in rural branch network advantages by deploying API-based credit decisioning stacks that compress turnaround times for co-applicant verification. Deepen modular loan packaging capabilities to capture lifetime value across tuition, living expenses, and device financing bundles. Counter fintech velocity threats by embedding enrollment verification directly into university partnerships, replicating Avanse's co-branded platform integration model. For New Entrants and Emerging Players: The price-point gap between collateral-secured public sector offerings and flexible NBFC structures opens white-space in vocational training and gig-economy segments. Target tier-2 city undergraduate markets where State Bank of India's branch density creates service gaps for digital-native borrowers. Penetrate through ed-tech platform partnerships that reduce acquisition costs and enable real-time enrollment verification, mirroring Propelld's embedded finance approach. For Investors and Strategic Acquirers: Exit pathways concentrate in NBFC acquisition by diversified financial conglomerates seeking digital origination capabilities. Long-term viability favors specialized underwriters with overseas-education expertise or co-branded university partnerships that generate recurring enrollment-linked volumes. Watch RBI's evolving exposure-norms for unsecured education credit as the signal for capital-allocation inflection across public and private lending channels.| Strategic Initiative | Industry Significance |
|---|---|
| API-Based Credit Decisioning Deployment | Unifies tax records, university registries, and bureau scores into real-time underwriting engines for NBFCs. |
| Modular Loan Packaging Expansion | Bundles tuition coverage with living-expense buffers and device-financing add-ons to capture lifetime borrower value. |
| Ed-Tech Platform Integration | Embedded finance partnerships with private universities reduce acquisition costs and enable enrollment verification. |
| Overseas-Education Underwriting Specialization | Tailored risk assessment for foreign-currency tuition obligations opens margin pools beyond domestic coverage. |
| Flexible Repayment Structure Development | Income-contingent schedules for gig-economy earners address cash-flow matching gaps in vocational segments. |
Research Methodology
Multi-period observation of disbursement volumes, moratorium default rates, and co-applicant risk profiles anchored the trend analysis, supplemented by interviews with public sector bank credit officers, NBFC underwriting heads, university finance administrators, and ed-tech platform partnership leads. Secondary validation drew from RBI priority-sector lending circulars, CEA cooperative bank solvency reports, BIS data-security standards, and Finance Ministry interest subvention scheme disclosures. Bottom-up branch-level volume estimates triangulated against top-down banking system credit flow data.
Segment-weighting approaches modeled loan type, end-user academic stage, banking institution channel, and repayment structure mechanics across the projection horizon. CAGRs derived from compounding annual disbursement trajectories adjusted for regulatory quota fulfillment rates and enrollment growth patterns. Industry-specific inputs included engineering and medical institution capacity expansion timelines, overseas-education visa approval velocities, and gig-economy income volatility indices.
Inputs from RBI regulatory filings and banking system credit data were available through the study window; gaps in real-time co-operative bank solvency metrics introduce uncertainty bands around district-level market penetration forecasts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Commercial Lending Market
Loans and Leasing
Europe Mortgage / Loan Broker Market
Loans and Leasing
Florida Digital Lending Market
Loans and Leasing
Digital Lending Market
Loans and Leasing
Canada Student Loan Market
Loans and Leasing
France Car Loan Market
Loans and Leasing
North America Motorcycle Loan Market
Loans and Leasing
Australia Automotive Financing Market
Loans and Leasing
India Auto Loan Market
Loans and Leasing
Housing Finance Market
Loans and Leasing
Japan Car Loan Market
Loans and Leasing
Japan Mortgage/Loan Brokers Market
Loans and Leasing
Montenegro Home Mortgage Finance Market
Loans and Leasing
Global Mortgage Lender Market
Loans and Leasing
United Kingdom Auto Loan Market
Loans and Leasing
Alternative Lending Market