
 Solar Lease Service Market | 2026-2036
Solar Lease Service Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Lease Service Market Outlook
Product bundling is shifting buyer choice in the Solar Lease Service Market as providers combine panel installation with battery storage, monitoring software, and maintenance into single monthly obligations. Sunrun leverages its Brightbox battery platform to differentiate lease offerings against standalone competitors. Sunnova Energy International anchors its growth strategy through long-term service contracts that extend beyond equipment installation into ongoing asset management. Trinity Solar competes on geographic density, concentrating installation crews in select metropolitan corridors to reduce customer acquisition costs.
A solar lease service constitutes a third-party financing arrangement where a provider retains system ownership and receives monthly payments from a host customer in exchange for electricity generation, typically structured over 20-25 year terms with performance guarantees and maintenance inclusion. The primary commercial purpose transfers capital risk from energy consumers to specialized financiers while capturing available tax incentives. Residential Leasing dominates transaction volume as homeowners seek bill stability without balance sheet impact, while Community Solar segments represent the fastest-growing structural category by enabling remote participation for renters and unsuitable rooftops. Commercial Leasing occupies mature margin pools where larger project scale and creditworthy offtakers reduce default risk.
The US Internal Revenue Service administers investment tax credit compliance that directly shapes lease pricing and provider profitability through safe harbor provisions. State-level public utility commissions regulate net metering tariffs that determine bill savings calculations underlying lease value propositions. The Federal Energy Regulatory Commission oversees interconnection standards affecting project timelines and customer fulfillment cycles. Stakeholders must monitor evolving state net metering reforms and utility rate design changes that could compress or expand the economic wedge between leased solar costs and retail electricity rates.
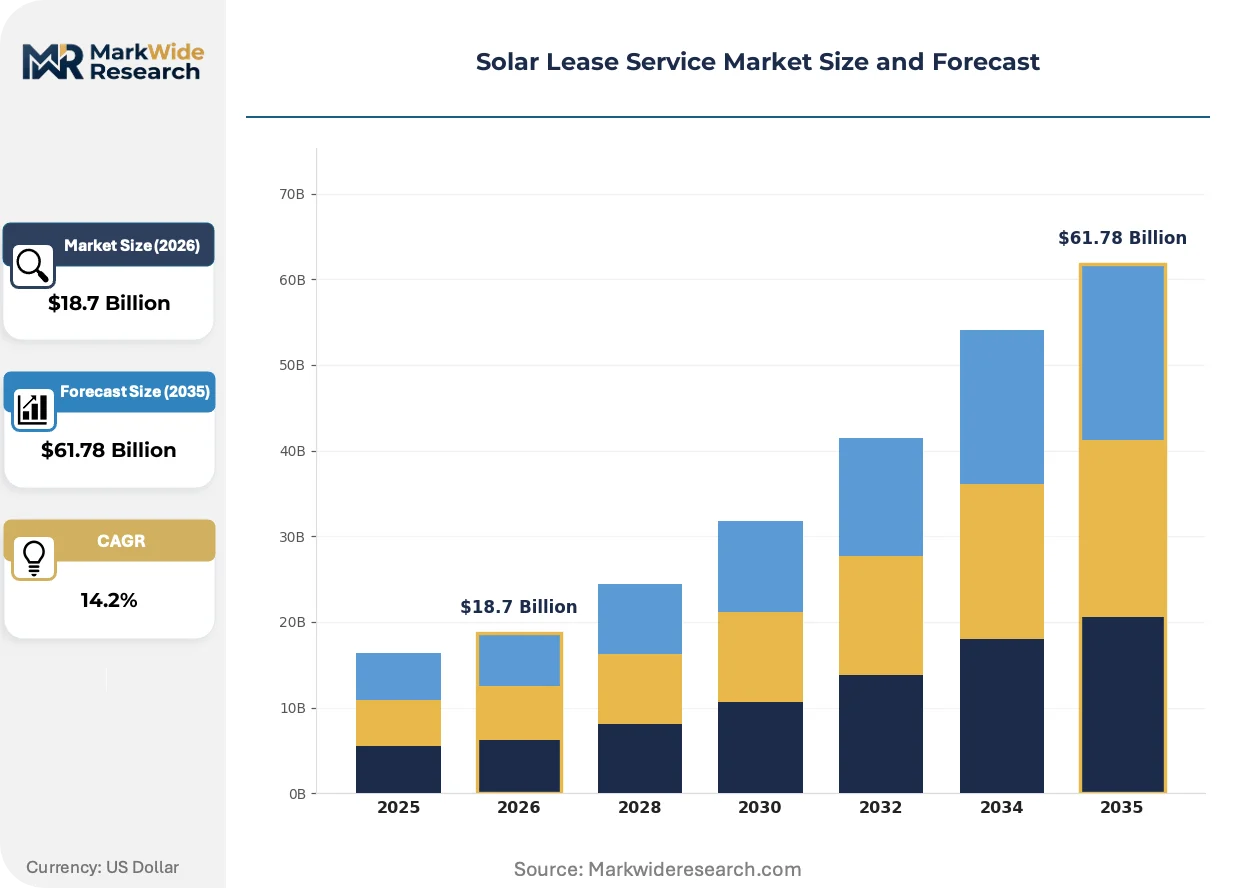
Market Dynamics
Zero-down lease structures are eliminating upfront capital barriers for residential homeowners, transferring system ownership risk to third-party financiers while capturing the IRA's extended investment tax credit provisions.
Growth Catalysts
- Investment Tax Credit Extension:The US Inflation Reduction Act's safe harbor provisions continue reshaping installer economics and consumer uptake patterns across sunbelt installations.
- High-Irradiance Geography Concentration:Texas, Florida, and Arizona utility rate structures maximize lease value propositions where retail electricity rates create favorable bill savings calculations.
- Community Solar Enablement:Remote participation structures allow renters and unsuitable rooftop owners to access leased solar generation without physical installation requirements.
Market Restraints
- Net Metering Tariff Compression:State-level public utility commission reforms in California and Nevada have reduced bill savings calculations underlying lease value propositions.
- Interconnection Queue Delays:Federal Energy Regulatory Commission standards create project timeline friction that extends customer fulfillment cycles and working capital requirements.
- Tax Equity Supply Concentration:Limited institutional investor appetite for solar tax credits concentrates financing dependence on a narrow pool of specialized financiers.
Strategic Opportunities
- Battery Storage Convergence:Pairing photovoltaic panels with lithium-ion storage systems creates new monthly revenue streams through backup power services and grid participation programs.
- Asset Management Contract Extension:Providers can capture ongoing service revenue beyond equipment installation through 20-25 year performance guarantee and maintenance obligations.
- Metropolitan Density Strategy:Concentrating installation crews in select urban corridors reduces customer acquisition costs and improves route efficiency for residential deployments.
Industry Challenges
- Electrical Contractor Talent Scarcity:NABCEP-certified installer shortages constrain deployment velocity in high-demand sunbelt markets where permit backlogs already extend project timelines.
- Utility Rate Design Uncertainty:Evolving time-of-use tariffs and demand charge structures complicate lease savings projections and customer acquisition messaging.
- Roof Condition Assessment Standardization:Inconsistent structural evaluation protocols across jurisdictions create underwriting friction and post-installation liability exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Lease Service Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential Leasing, Commercial Leasing, Community Solar, PPA Customer Type: Homeowners, Businesses, Government Entities, Nonprofits Technology: Photovoltaic, Concentrated Solar Power, Thin-Film Technology, Bifacial Modules Installation Model: Rooftop Installation, Ground-Mounted, Carport Systems, Floatovoltaics |
| Companies Covered | Sunrun, Sunnova Energy International, Sungevity, Trinity Solar, Palmetto Solar, Momentum Solar, Vision Solar, Freedom Forever, Sunlight Financial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Lease Service Market Strategic Shifts
Product bundling is actively reshaping competitive positioning as providers combine hardware installation with software monitoring and energy management into unified monthly obligations. Technology convergence and regulatory adaptation are compressing traditional service boundaries.
Machine learning-based performance monitoring is automating fault detection and predictive maintenance scheduling across distributed solar fleets. Residential lease providers deploy these platforms to reduce truck rolls and extend asset life. The technology is automating operational cost structures that previously required manual telemetry review and dispatch coordination.
The US Internal Revenue Service's safe harbor provisions for investment tax credit compliance continue evolving documentation requirements for lease financiers. These rules directly shape pricing structures and provider profitability through placed-in-service date verification. Commercial leasing segments face heightened scrutiny as transaction scale triggers more intensive audit protocols.
Homeowners increasingly evaluate solar leases against power purchase agreements based on total cost of ownership rather than monthly payment comparisons. This behavioral shift pressures providers to transparently disclose escalator clauses and buyout provisions. The pattern is most visible in California and Massachusetts markets where consumer financial literacy around energy contracts has matured.
Solar Lease Service Market Segmentation
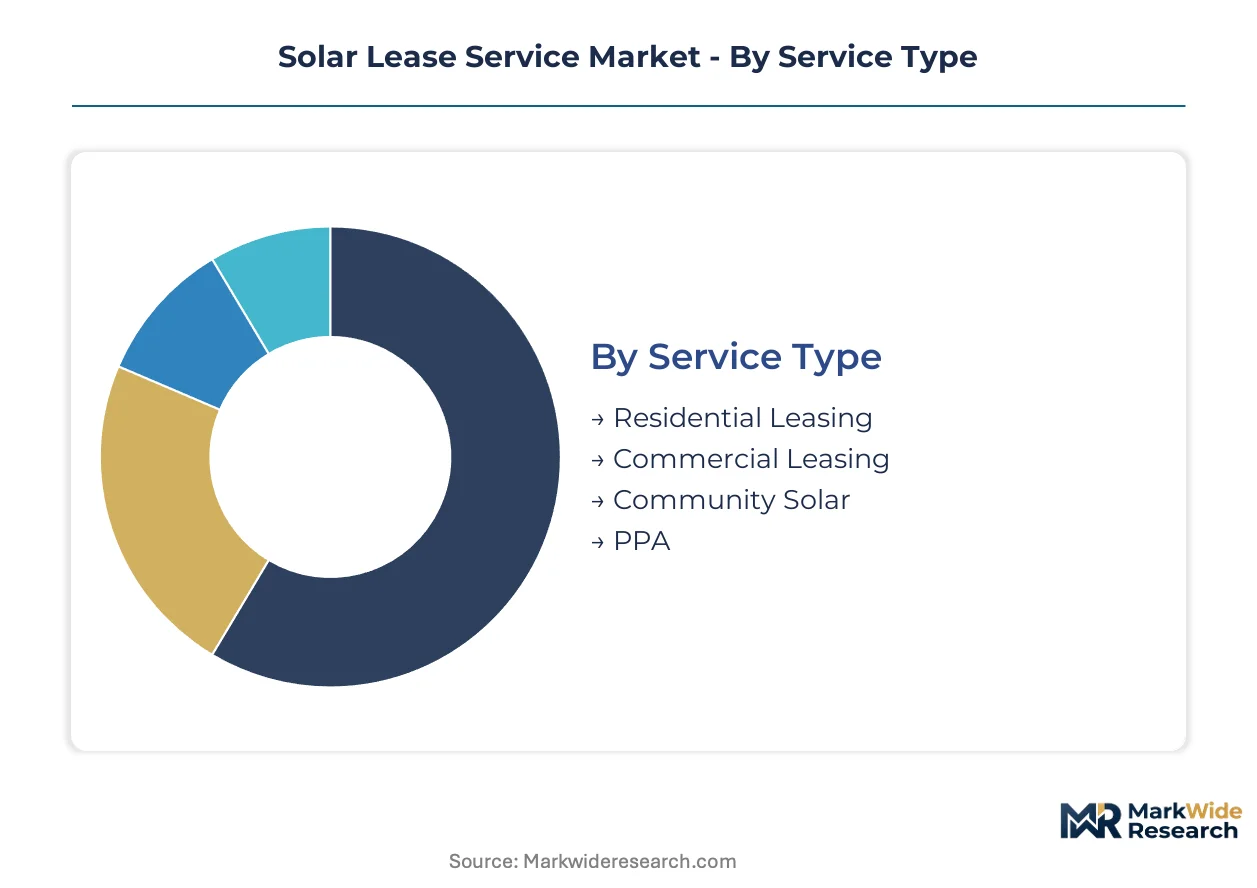
Lease structure variation creates fundamentally different risk-reward profiles across customer types and installation contexts. Providers must align capital deployment with segment-specific credit quality, regulatory exposure, and operational complexity.
Service Type:
Customer scale and ownership structure determine financing mechanics and tax incentive capture strategies.
- Residential Leasing:Individual homeowners contract for rooftop systems with 20-25 year terms, zero-down structures, and performance guarantees. Demand concentrates in Texas, Florida, and Arizona where high irradiance and elevated utility rates maximize bill savings calculations.
- Commercial Leasing:Corporate offtakers with investment-grade credit ratings access larger system scales and simpler interconnection logistics. Warehouse rooftops in California's Inland Empire and New Jersey's industrial corridors anchor deployment volumes.
- Community Solar:Remote participation models enable renters and unsuitable rooftop owners to subscribe to shared arrays. Subscription growth accelerates in states with virtual net metering frameworks.
- PPA:Power purchase agreements fix electricity rates per kilowatt-hour rather than equipment lease payments. Corporate sustainability commitments drive C&I uptake.
Residential Leasing leads volumes today; Community Solar is gaining share fastest.
Customer Type:
Credit underwriting standards and contract tenors vary sharply across borrower risk profiles.
- Homeowners:FICO score thresholds and debt-to-income ratios filter participation. Sunbelt states with high homeownership rates and elevated electricity bills produce the strongest application pipelines.
- Businesses:Commercial and industrial entities leverage balance sheet strength to negotiate preferential escalator clauses. Manufacturing facilities with flat rooftop profiles dominate procurement.
- Government Entities:Municipal and federal agencies access specialized financing through public-private partnerships. Federal procurement standards under the Federal Energy Management Program streamline compliance.
- Nonprofits:Tax-exempt status prevents direct ITC capture, requiring lease structures or third-party ownership. Schools and houses of worship represent concentrated demand.
Homeowners anchor transaction counts; Businesses command the largest average contract values.
Technology:
Module efficiency and degradation curves directly impact lease pricing and residual value assumptions.
- Photovoltaic:Crystalline silicon panels dominate installed capacity with proven 25-year performance warranties. Monocrystalline PERC technology commands premium positioning in residential deployments.
- Concentrated Solar Power:Utility-scale thermal systems with molten salt storage enable dispatchable generation. Deployment concentrates in southwestern US deserts with high direct normal irradiance.
- Thin-Film Technology:Cadmium telluride and copper indium gallium selenide modules offer temperature coefficient advantages in hot climates. First Solar's Series 6 platform anchors utility-scale adoption.
- Bifacial Modules:Dual-sided energy capture from reflected light boosts yields on highly reflective surfaces. Albedo-dependent performance creates site-specific value propositions.
Photovoltaic technology holds installed base dominance; Bifacial Modules are expanding most quickly in new capacity additions.
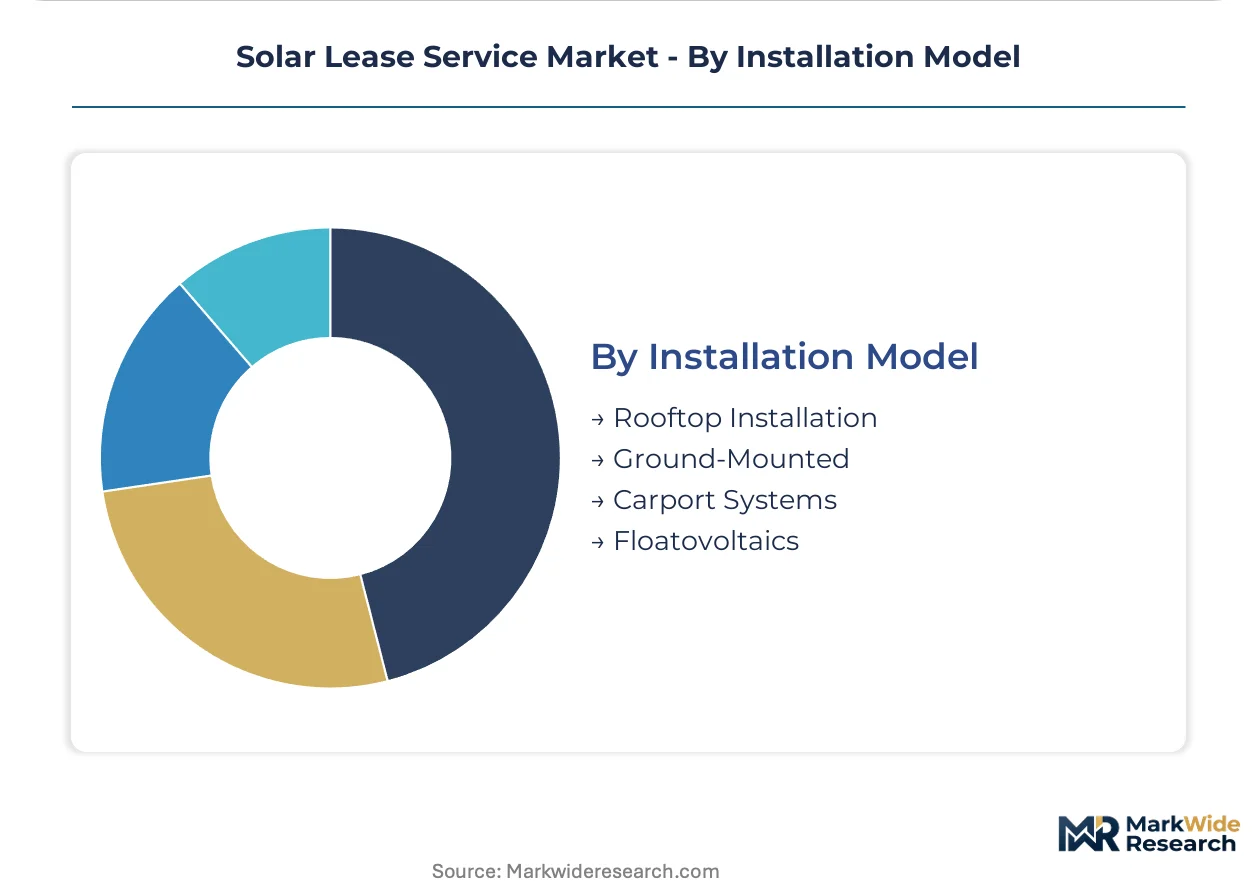
Installation Model:
Site constraints and land use regulations dictate structural configuration and permitting complexity.
- Rooftop Installation:Residential and commercial building-integrated systems minimize land requirements. Structural engineering assessments and roof condition warranties create underwriting friction.
- Ground-Mounted:Utility-scale arrays on vacant land achieve lowest per-watt installation costs. Interconnection queue delays at FERC-jurisdictional transmission nodes extend project timelines.
- Carport Systems:Dual-purpose structures generate electricity while providing vehicle shade. Corporate campus parking lots and retail centers in sunbelt metros anchor adoption.
- Floatovoltaics:Water-surface installations reduce evaporation and algae growth while conserving land. Reservoir-based projects in California and Florida face environmental review requirements.
Rooftop Installation leads deployment volumes; Floatovoltaics show the steepest expansion trajectory in niche applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The solar lease service industry traces its commercial scaling to the United States, where third-party ownership models first achieved mass-market penetration through California's early net metering frameworks and federal tax credit structures.
United States
Texas, Florida, and Arizona generate the strongest lease application pipelines due to elevated utility rates and high solar irradiance. The Inflation Reduction Act's investment tax credit extension through the IRS safe harbor provisions continues reshaping installer economics. Installers concentrate crews in Dallas-Fort Worth, Houston, and Phoenix metropolitan corridors to reduce customer acquisition costs.
Germany
Residential electricity rates exceeding 40 euro cents per kilowatt-hour drive homeowner interest in zero-down lease alternatives. The country's national energy regulator oversees grid interconnection standards that affect project fulfillment timelines. Bavaria and Baden-Württemberg anchor deployment volumes where south-facing rooftops maximize yield calculations.
Australia
High grid electricity costs and abundant solar resource availability create favorable lease economics for suburban homeowners. The national renewable energy regulator administers small-scale technology certificate programs that reduce effective system costs. Queensland and New South Wales concentrate installer activity along the Brisbane-Sydney coastal corridor.
India
Commercial and industrial entities increasingly adopt lease structures to bypass capital expenditure constraints while meeting renewable purchase obligations. The national electricity regulator and state-level public utility commissions govern net metering tariffs that determine savings calculations. Gujarat and Rajasthan host concentrated deployment activity in industrial zones surrounding Ahmedabad and Jaipur.
United Kingdom
Energy price volatility since 2022 has heightened residential interest in fixed-cost electricity alternatives. Ofgem regulates export tariff structures that influence lease provider revenue models. Southeast England and Greater London concentrate installer networks where roof ownership rates and electricity consumption patterns align favorably.
Solar Lease Service Market Competitive Environment
Premium-margin players sit above commodity-margin players across customer acquisition efficiency and balance sheet capacity dimensions. The vendor base clusters around three strategic archetypes: vertically integrated installers with captive financing arms, technology-agnostic financiers partnering with regional contractors, and software-enabled aggregators managing distributed asset portfolios. Consolidation pressure intensifies as customer acquisition costs rise and tax equity supply concentrates. Dominant competitive moves include geographic density strategies to reduce per-watt sales costs and battery storage bundling to extend contract tenors.
Within the integrated installer tier, Sunrun and Sunnova Energy International occupy positions as archetypal full-service providers combining equipment installation with long-term asset management. Trinity Solar exemplifies the geographic concentration strategy, anchoring operations in select metropolitan corridors to optimize crew routing efficiency. These three entities represent distinct capital deployment philosophies across the lease origination value chain.
| Leading Market Players |
|---|
| Sunrun |
| Sunnova Energy International |
| Sungevity |
| Trinity Solar |
| Palmetto Solar |
| Momentum Solar |
| Vision Solar |
| Freedom Forever |
| Sunlight Financial |
| Others |
Value Chain & Pricing Dynamics
NABCEP-certified installer scarcity in Texas and Arizona widens pricing spreads between premium full-service leases and economy contractor-direct offerings. Labor cost differentials between sunbelt metropolitan corridors and secondary markets compress margins at the standard tier while elevating premium positioning for providers with captive installation crews.
Pricing Analysis
Zero-down monthly subscription structures dominate residential solar lease pricing, separating bundled hardware-software-service packages from equipment-only arrangements. Price differentiation hinges on battery storage inclusion and monitoring platform sophistication, with backup power capability commanding substantial premiums. Cost compression in the standard tier intensifies as regional contractors undercut national brands on customer acquisition. Renters and first-time homeowners exhibit highest price sensitivity, while commercial offtakers with investment-grade credit prioritize performance guarantees over monthly payment minimization.
Supply Chain Analysis
NABCEP certification and state electrical licensing requirements gate installer supply, constraining deployment velocity in high-demand markets. Module supply concentrates in China, Malaysia, and Vietnam, with crystalline silicon cells and lithium-ion battery packs as critical inputs. Single-source vulnerability in tax equity financing creates working capital friction for lease originators. Distribution runs through vertically integrated installers with captive financing arms, technology-agnostic financiers partnering with regional contractors, and software-enabled aggregators managing distributed portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
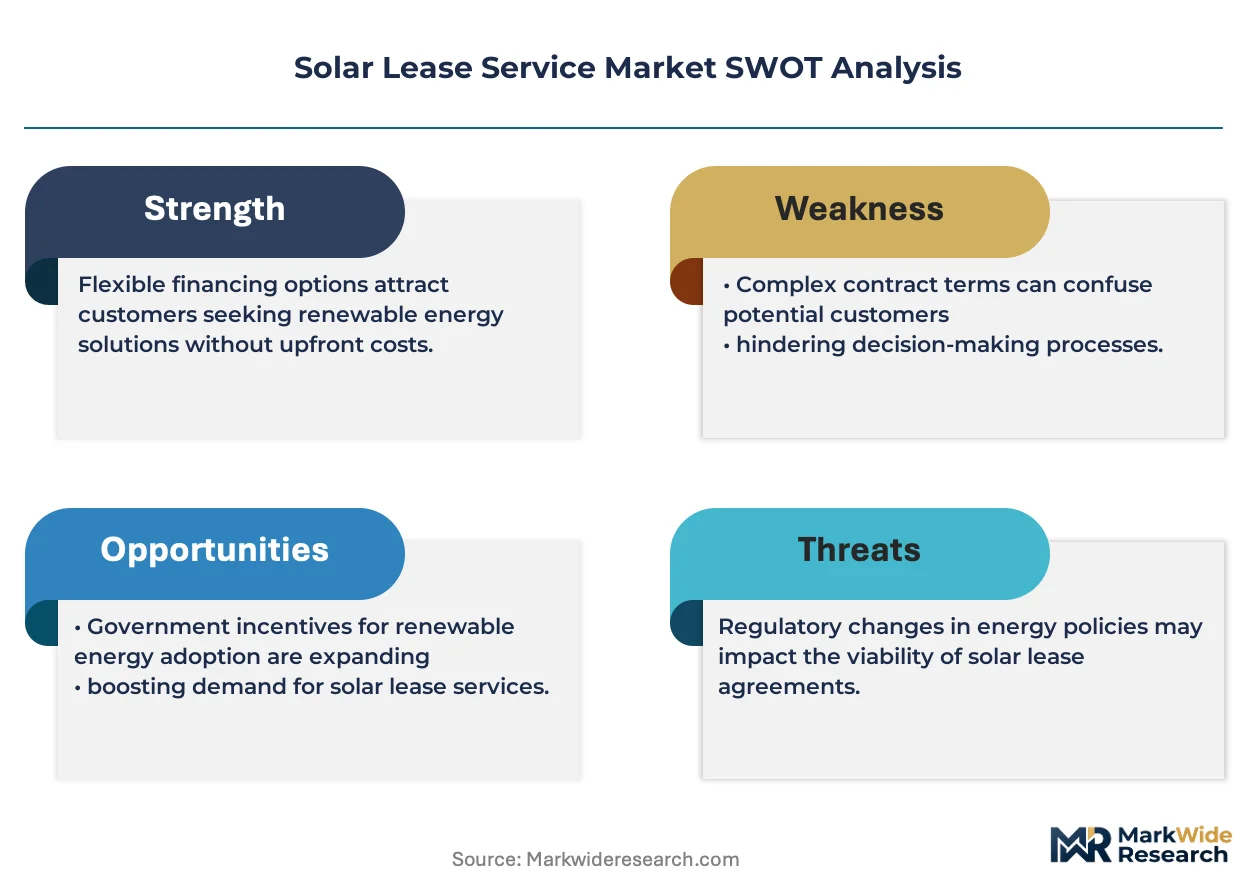
The solar lease service market functions as a geographic-arbitrage play where Texas utility rate structures and IRA tax credit provisions generate superior unit economics versus California's compressed net metering regimes. Providers must align capital deployment with irradiance-advantaged jurisdictions.
For Market Incumbents: Acquire NABCEP-certified installation crews in Dallas-Fort Worth and Phoenix corridors to defend route density against emerging regional contractors. Vertical integration into battery storage supply secures margin capture as lithium-ion pack costs fluctuate. State-level net metering reforms in California and Nevada threaten bill savings calculations underlying legacy lease portfolios. For New Entrants and Emerging Players: The Inflation Reduction Act's safe harbor provisions in the United States open a window for virtual power plant aggregators to capture grid services revenue beyond electricity generation. Community solar subscriptions for renters and unsuitable rooftop owners represent the most penetrable white-space segment. A software-first go-to-market angle automating customer acquisition and performance monitoring reduces capital intensity versus hardware-heavy incumbents. For Investors and Strategic Acquirers: Utility holding companies are the most active acquirer in this space, seeking distributed generation assets to meet renewable portfolio obligations. Long-term viability rests on 20-25 year contract tenors with escalator clauses that preserve real returns. Acquisition targets should demonstrate geographic density in sunbelt states with favorable rate design. Watch for material changes in state net metering reform timelines as the primary inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Storage Bundling | Brightbox and competing platforms create monthly revenue streams through backup power services and grid participation programs. |
| Metropolitan Density Concentration | Crew routing optimization in Dallas-Fort Worth and Houston reduces customer acquisition costs and improves installation velocity. |
| Virtual Power Plant Aggregation | Distributed battery fleets participate in FERC-jurisdictional wholesale markets through automated dispatch protocols. |
| Tax Equity Partnership Structuring | Safe harbor provisions require precise placed-in-service date documentation to preserve ITC capture for institutional investors. |
| Community Solar Subscription Scaling | Virtual net metering frameworks in New York and Massachusetts enable remote participation without physical rooftop installation. |
Study Parameters
Direct dialogue with solar lease origination executives, NABCEP-certified installation contractors, utility interconnection planners, tax equity investors, and state public utility commission staff grounded qualitative findings. Secondary validation drew from FERC interconnection queue data, EIA generation statistics, IRS safe harbor guidance documents, and state-level net metering docket filings. Bottom-up lease origination volume estimates triangulated against top-down installed capacity projections across the analysis window.
Segment-level outputs reflect modeled deployment across residential, commercial, community solar, and PPA structures by customer credit tier and technology configuration. CAGRs derived from regression analysis of historical origination volumes against utility rate trajectories, tax incentive schedules, and interconnection timeline assumptions. Forecast inputs incorporated irradiance-adjusted capacity factors, battery storage attachment rates, and evolving time-of-use tariff structures.
Revisions become necessary when state net metering reforms, utility rate design changes, or tax equity supply disruptions materialize. Forecasts reflect documented assumptions regarding IRA safe harbor continuity and FERC interconnection standard timelines. A model refresh is warranted upon material change in state-level public utility commission docket activity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Cash Advance Services Market
Loans and Leasing
Mexico Home Equity Lending Market
Loans and Leasing
Loan Brokers Market
Loans and Leasing
Asia-Pacific Mortgage/Loan Brokers Market
Loans and Leasing
Premium Finance Market
Loans and Leasing
Invoice Factoring Market
Loans and Leasing
Alternative Lending Market
Loans and Leasing
North America Mortgage/Loan Brokers Market
Loans and Leasing
Factoring Market
Loans and Leasing
Enterprise Asset Leasing Market
Loans and Leasing
Brazil Auto Loan Market
Loans and Leasing
United States Material Handling Leasing and Financing Market
Loans and Leasing
Asia-Pacific Auto Loan Market
Loans and Leasing
Digital Lending Market
Loans and Leasing
Student Loan Market
Loans and Leasing
South Korea Auto Loan Market