
 Global Industrial Distribution Market | 2026-2036
Global Industrial Distribution Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Distribution Market Foresight
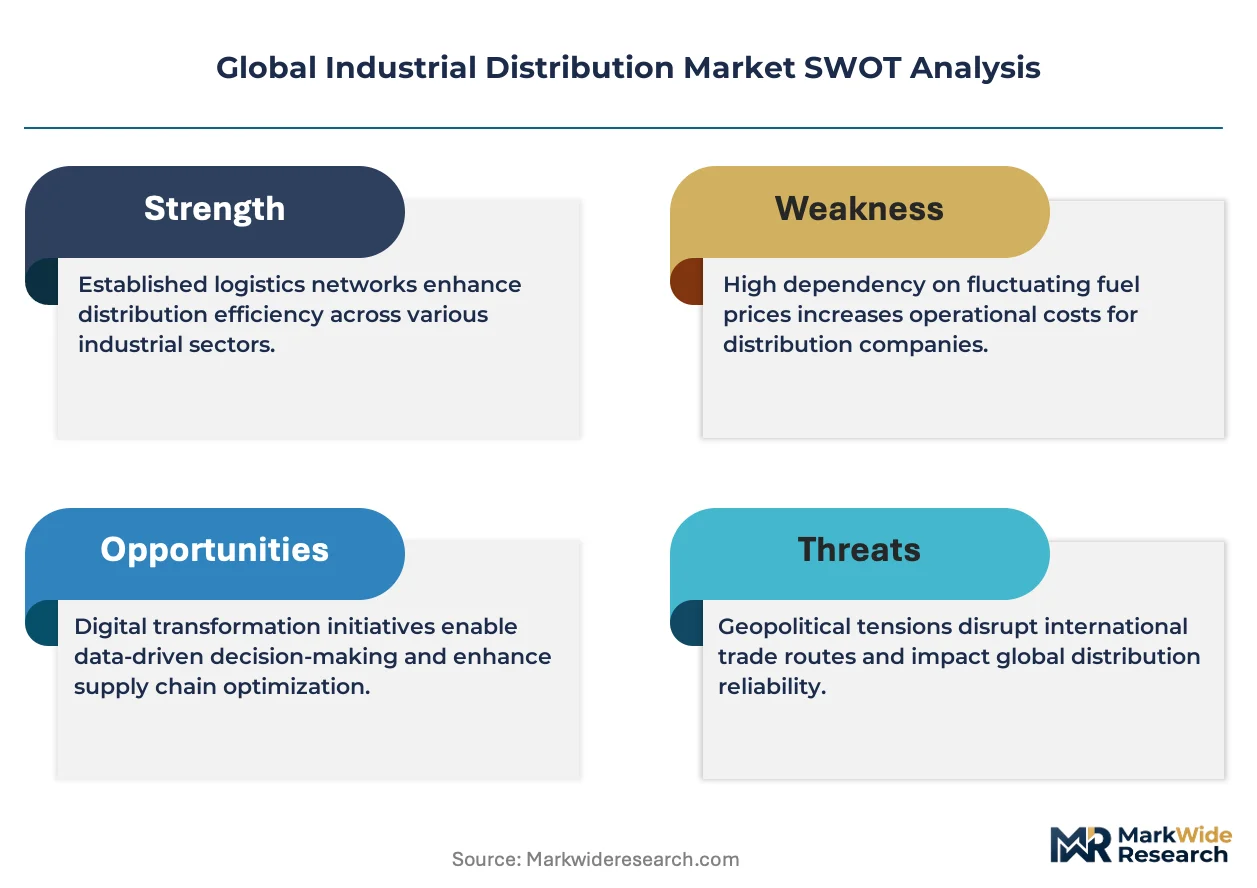
Composite polymers are broadening their displacement of metal fasteners and structural brackets in corrosion-sensitive environments. W.W. Grainger leverages its North American branch network to sustain same-day fulfillment density in manufacturing corridors. Applied Industrial Technologies anchors its position through specialized fluid power and conveyance expertise. Fastenal Company controls site-specific vending programs that embed inventory directly at customer facilities.
Industrial distribution encompasses the procurement, warehousing, and fulfillment of production inputs ranging from ANSI-rated safety equipment to ISO-classified hydraulic fittings with specified pressure tolerances. Its primary purpose is reducing customer working capital through vendor-managed inventory and technical specification support. Electrical Supplies and Mechanical Components occupy the deepest margin pools due to specification complexity and brand loyalty. E-Commerce channels represent the fastest-growing distribution pathway as procurement teams migrate from catalog-based ordering to integrated ERP purchasing portals.
FDA oversight of food-contact materials, EPA hazardous substance tracking, and OSHA personal protective equipment standards collectively elevate compliance documentation requirements across distributor inventories. REACH registration obligations in Europe and GB standards enforcement in China further fragment supplier qualification protocols. Stakeholders must monitor which regulatory jurisdictions will next mandate digital product passports and how certification costs will redistribute across distributor and manufacturer balance sheets.
Market Dynamics
ERP-integrated purchasing portals are compressing order cycles and forcing distributors to rebuild fulfillment infrastructure around real-time inventory visibility rather than static catalog positions.
Growth Catalysts
- EU Green Deal compliance mandates:REACH registration obligations and digital product passport requirements are creating certified-supplier premiums for distributors with documented chemical provenance.
- Automotive OEM consolidation:Germany's industrial corridor is concentrating procurement volumes with fewer distributors capable of same-day mechanical component fulfillment.
- Composite polymer substitution:Corrosion-resistant fasteners are displacing metal brackets in chemical processing and offshore infrastructure, expanding addressable SKU ranges for technical distributors.
Market Restraints
- Specialized warehousing capex:Temperature-controlled storage for EPA-tracked hazardous substances and FDA-regulated food-contact materials strains distributor balance sheets.
- Supplier concentration risk:Hydraulic fitting and electrical component production clusters in China expose distributors to GB standards enforcement delays and shipping volatility.
- Technical specification complexity:ISO-classified pressure tolerances and ANSI safety ratings require dedicated engineering support that erodes margin on standardized products.
Strategic Opportunities
- India manufacturing expansion:PLI scheme incentives for machinery and automotive production are creating first-mover advantages for distributors establishing BIS-certified inventory positions.
- Converged fluid power and conveyance systems:Integrated motion control packages combining hydraulics, pneumatics, and linear motion are opening specification-led revenue pools.
- Site-embedded inventory models:Vendor-managed vending programs at customer facilities lock out competitors through captive consumption data and replenishment automation.
Industry Challenges
- ERP integration complexity:Legacy procurement systems at industrial buyers resist API connections, forcing distributors to maintain parallel catalog and portal infrastructures.
- Certification timeline compression: REACH dossier updates and evolving EPA hazardous substance classifications demand continuous compliance staffing that mid-tier distributors struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Distribution Market |
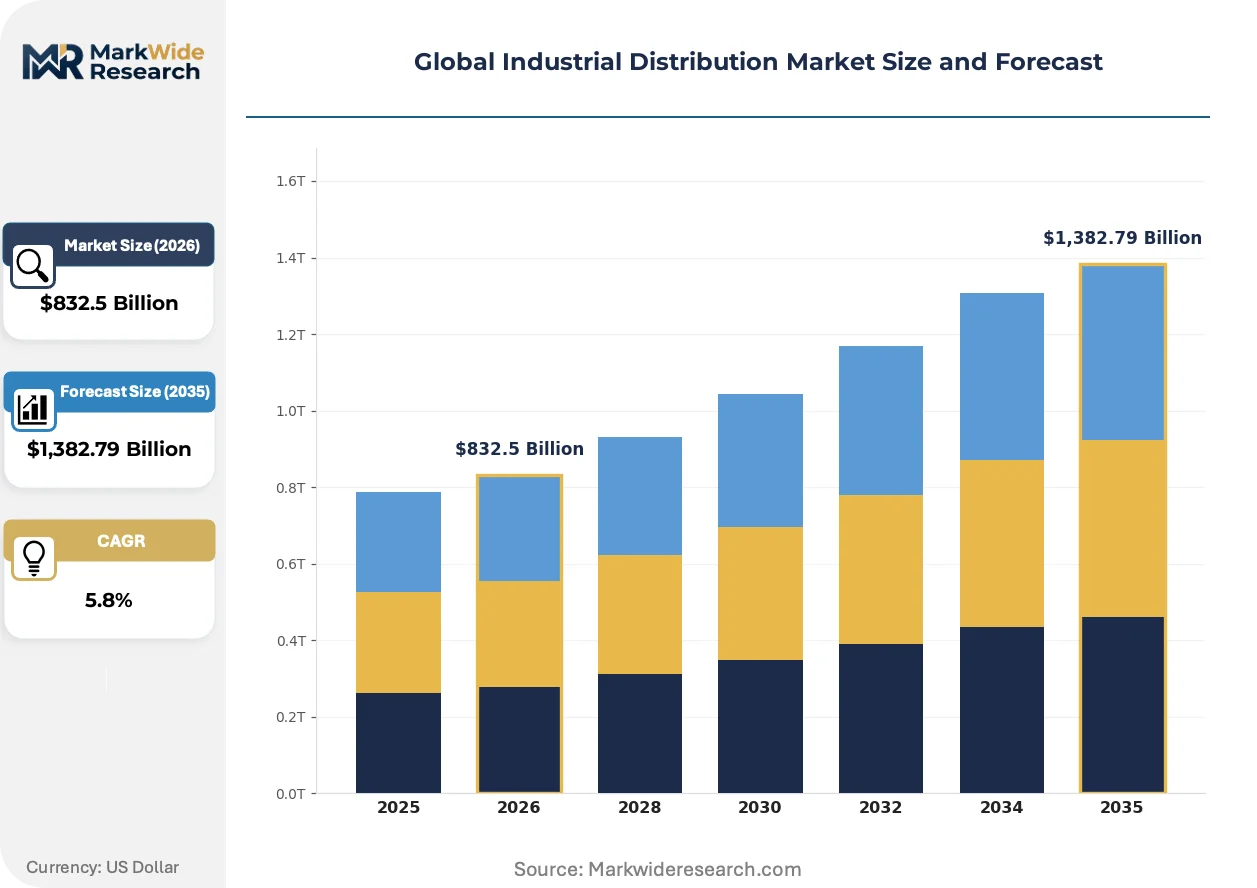
| Market Size in 2026 | $832.5 Billion |
| Market Size in 2035 | $1,382.79 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Components, Electrical Supplies, Hydraulics & Pneumatics, Safety Equipment, Fasteners, Tools Distribution Channel: Direct Sales, E-Commerce, Wholesale Distributors, Value-Added Resellers, Catalog Sales End User Industry: Manufacturing Plants, Construction Firms, Energy Producers, Aerospace Suppliers, Water Treatment Facilities Service Type: Inventory Management, Technical Support, Logistics & Warehousing, Procurement Services, After-Sales Assistance |
| Companies Covered | MSC Industrial Direct, Applied Industrial Technologies, W.W. Grainger, Global Industrial, Ferguson Enterprises, Fastenal Company, Rexel Group, Vallen Distribution, WESCO International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Distribution Market Shifts & Advancements
Digital infrastructure investments are bifurcating the competitive landscape between distributors with real-time inventory orchestration and those dependent on batch-processed fulfillment systems.
AI-powered demand forecasting is automating safety stock positioning across multi-echelon distribution networks. Automotive and machinery OEMs in Germany and the US Midwest are adopting these systems fastest. Distributors deploying predictive algorithms are compressing working capital cycles by 20-30% versus legacy reorder-point methods.
REACH registration obligations and the EU AI Act's supply chain transparency requirements are mandating granular chemical inventory documentation. Distributors must now maintain batch-level provenance records for all REACH-registered substances. The chemical and pharmaceutical verticals are responding by consolidating supplier relationships with distributors holding ECHA-certified data infrastructure.
Buyer organizations are unbundling after-sales technical support from product procurement. Maintenance teams at manufacturing plants now source engineering specification assistance separately from component purchasing. This pattern is most pronounced in North American automotive corridors where specialized fluid power consultants displace distributor field engineers for complex hydraulic system design.
Global Industrial Distribution Market Segmentation
Segmentation in industrial distribution reveals where capital requirements concentrate and how procurement patterns fragment across technical complexity tiers. Distributors must align infrastructure investments with the specific compliance, warehousing, and fulfillment demands of each segment cluster.
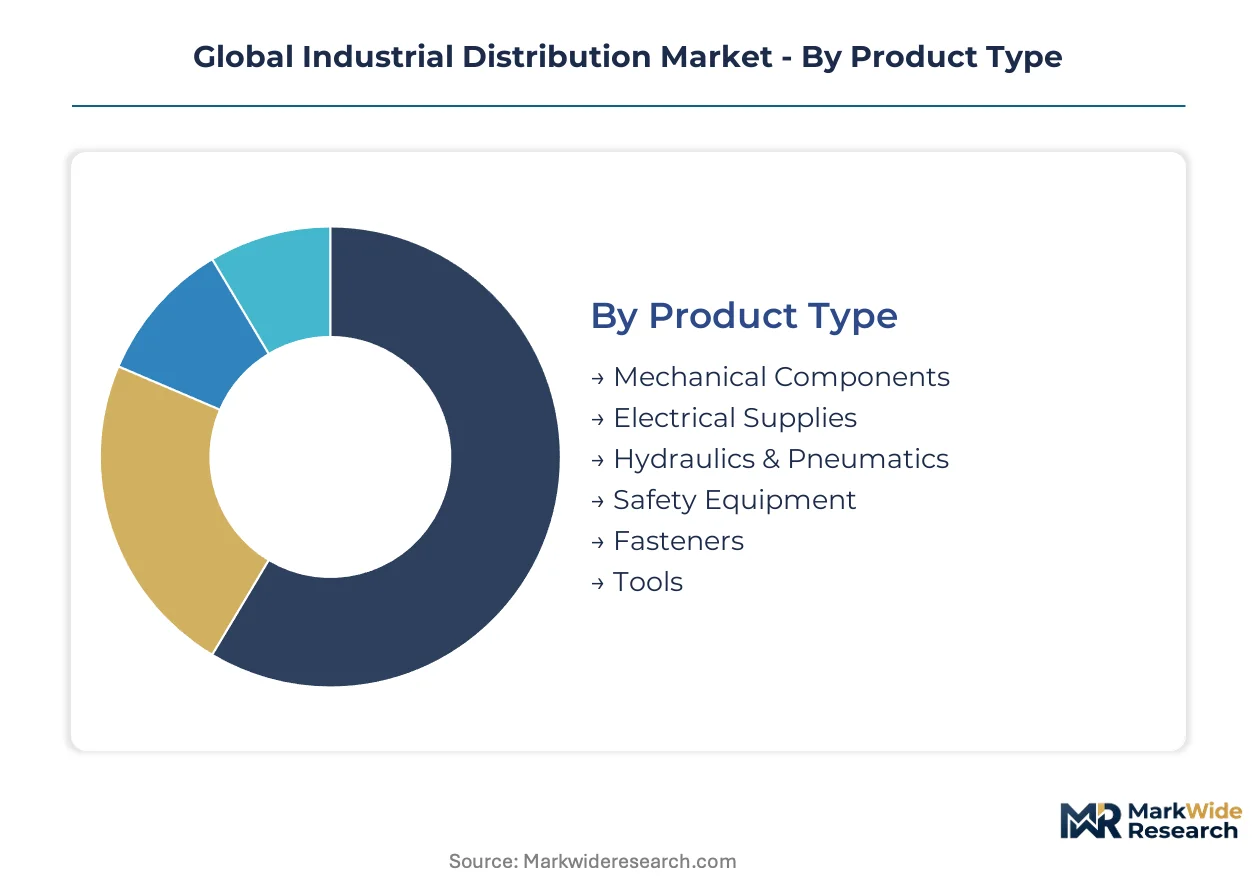
Product Type:
Capital intensity varies sharply across product categories, with hazardous material handling and temperature-controlled storage creating divergent balance sheet pressures.
- Mechanical Components:Includes bearings, gears, and linear motion systems requiring ISO-classified pressure tolerances and dimensional precision. Demand concentrates in Germany's automotive corridor where OEMs consolidate supplier relationships around same-day fulfillment capability. REACH documentation requirements elevate working capital for distributors maintaining batch-level provenance records.
- Electrical Supplies:Encompasses switchgear, cabling, and motor controls with ANSI and IEC certification requirements. Procurement volumes cluster with manufacturing plants across the US Midwest adopting ERP-integrated purchasing portals. Specification complexity sustains deeper margin pools than standardized mechanical products.
- Hydraulics & Pneumatics:Fluid power systems with specified pressure ratings and seal compatibility requirements.
- Safety Equipment:ANSI-rated and OSHA-compliant personal protective equipment with mandatory testing documentation.
- Fasteners:Composite polymer variants displacing metal brackets in corrosion-sensitive chemical processing environments.
- Tools:Precision measurement and power equipment with calibration traceability requirements.
Mechanical Components absorbs the bulk of installed capacity; Electrical Supplies is expanding most quickly through e-commerce channel migration.
Distribution Channel:
Channel selection determines fulfillment infrastructure requirements and customer lock-in mechanisms.
- E-Commerce:ERP-integrated purchasing portals enabling real-time inventory visibility and automated reordering. Manufacturing procurement teams in North America migrate fastest from catalog-based systems. Distributors must rebuild fulfillment infrastructure around API connectivity rather than static catalog positions.
- Direct Sales:Field-engineered relationships with dedicated specification support for complex hydraulic and electrical systems. Energy producers and aerospace suppliers in the US and Germany rely on direct channels for technical compliance documentation.
- Wholesale Distributors:Multi-brand aggregation serving mid-tier manufacturing plants with consolidated procurement.
- Value-Added Resellers:Specialized integration services combining fluid power, conveyance, and control components.
- Catalog Sales:Legacy print and digital catalogs maintaining parallel infrastructure for buyers resisting ERP integration.
Direct Sales captures the highest revenue per transaction; E-Commerce is climbing the fastest as procurement digitization accelerates.
End User Industry:
End-use concentration shapes geographic fulfillment density and regulatory compliance specialization.
- Manufacturing Plants:Automotive and machinery OEMs consolidating supplier relationships around vendor-managed inventory. Germany's industrial corridor and the US Midwest concentrate procurement volumes with distributors capable of technical specification support.
- Energy Producers:Oil, gas, and renewable infrastructure requiring corrosion-resistant fasteners and hazardous substance documentation. Offshore platforms drive composite polymer substitution for metal brackets.
- Construction Firms:Project-based procurement with volatile demand patterns and safety equipment certification requirements.
- Aerospace Suppliers:FAA and EASA traceability standards demanding batch-level documentation and specialized warehousing.
- Water Treatment Facilities:EPA-tracked chemical handling and FDA-regulated food-contact material compliance.
Manufacturing Plants dominates current procurement volumes; Energy Producers shows the steepest expansion trajectory through infrastructure replacement cycles.
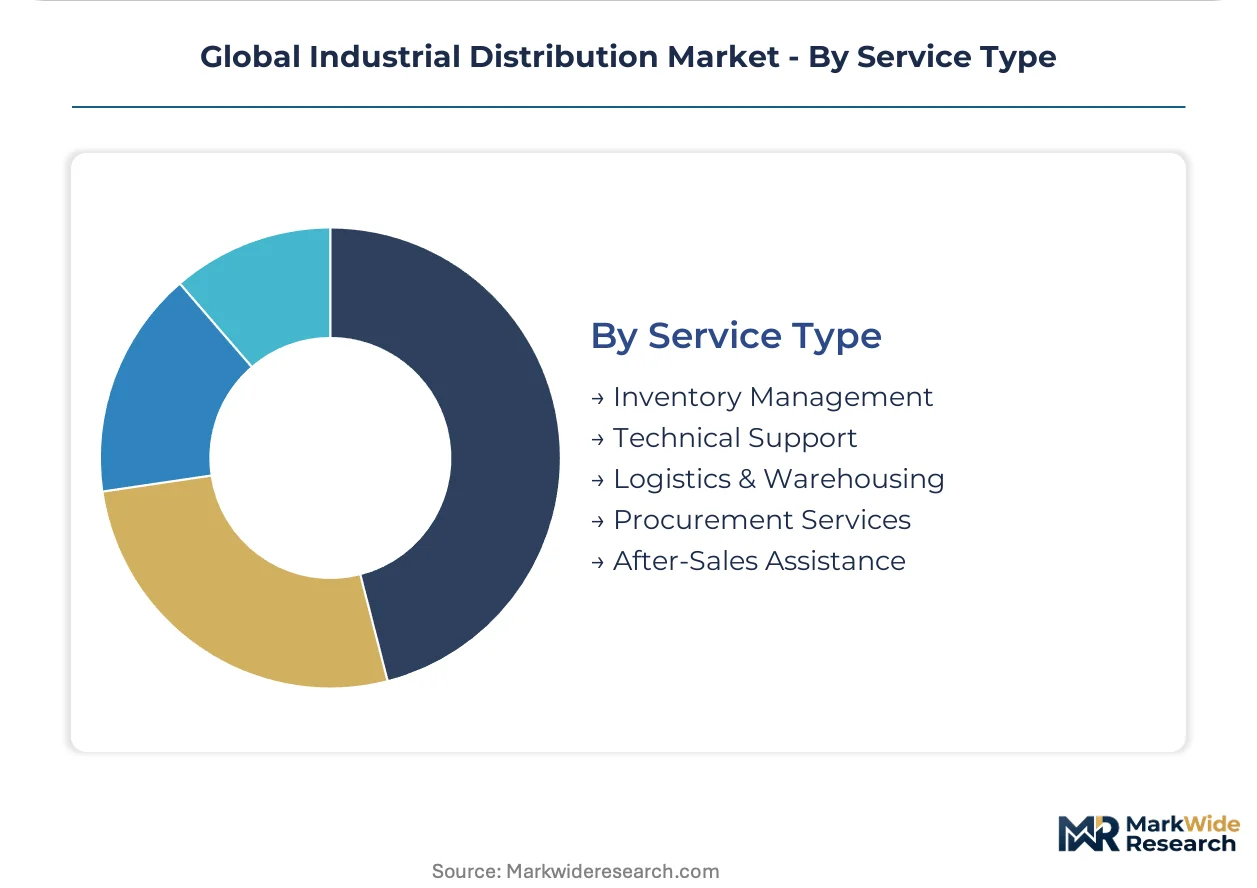
Service Type:
Service attachment rates determine margin sustainability and customer switching costs.
- Inventory Management:Vendor-managed programs embedding automated replenishment at customer facilities. Site-specific vending systems lock out competitors through captive consumption data capture.
- Technical Support:Engineering specification assistance for ISO-classified pressure systems and hydraulic design. North American automotive corridors increasingly unbundle this service from product procurement.
- Logistics & Warehousing:Temperature-controlled storage for EPA-tracked hazardous substances and FDA-regulated materials.
- Procurement Services:Consolidated sourcing and compliance documentation management for REACH and GB standards.
- After-Sales Assistance:Maintenance support and calibration services extending equipment lifecycle value.
Inventory Management holds the largest installed service base; Technical Support is gaining share fastest as specification complexity escalates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Mexico's northern border states concentrate automotive and electronics assembly, drawing procurement volumes toward distributors with cross-border fulfillment infrastructure.
United States
Automotive OEMs in Michigan and Ohio consolidate supplier relationships around same-day mechanical component fulfillment. OSHA and EPA hazardous substance tracking elevate compliance documentation requirements for distributors serving chemical processing plants. The US Midwest manufacturing corridor anchors vendor-managed inventory adoption, with procurement teams migrating fastest to ERP-integrated purchasing portals.
Germany
Machinery and automotive producers in Baden-Württemberg and Bavaria demand REACH-certified chemical provenance and batch-level documentation. The EU Green Deal and ECHA registration obligations create certified-supplier premiums for distributors with ECHA-certified data infrastructure. Stuttgart and Munich industrial clusters concentrate procurement volumes with technical distributors capable of fluid power specification support.
China
GB standards enforcement and MIIT industrial policy reshape supplier qualification protocols for hydraulic fitting and electrical component production. Dual carbon goals and MEE environmental compliance accelerate composite polymer substitution in corrosion-sensitive infrastructure. Yangtze River Delta manufacturing hubs expose distributors to shipping volatility and certification timeline compression.
India
PLI scheme incentives for machinery and automotive production create first-mover advantages for distributors establishing BIS-certified inventory positions. CDSCO and BIS regulatory alignment demands continuous compliance staffing that mid-tier distributors struggle to fund. Maharashtra and Gujarat industrial corridors concentrate procurement growth among manufacturing plants expanding MRO procurement through digital channels.
Japan
METI industrial digitization initiatives and JIS standards enforcement elevate technical specification complexity for ISO-classified pressure systems. Automotive and machinery OEMs in Nagoya and Osaka adopt AI-powered demand forecasting fastest, compressing working capital cycles. Kanto and Kansai manufacturing belts consolidate supplier relationships with distributors offering predictive inventory orchestration.
Global Industrial Distribution Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with technical distributors commanding premium positioning in specification-heavy mechanical and electrical categories while catalog-based wholesalers compete on fulfillment density. The vendor landscape organizes around three archetypes: North American branch-network operators with same-day fulfillment infrastructure, European REACH-certified specialists with chemical provenance documentation, and Asia-Pacific scale players leveraging production proximity to hydraulic and electrical component clusters. Consolidation pressure intensifies through strategic partnerships linking ERP-integrated portals with vendor-managed inventory programs, while geographic expansion targets India's PLI scheme corridors and Mexico's northern border assembly zones.
Within the North American branch-network tier, W.W. Grainger and Fastenal Company exemplify fulfillment-density strategies, with the former leveraging extensive branch infrastructure and the latter embedding site-specific vending programs at customer facilities. Applied Industrial Technologies occupies a position among fluid power and conveyance specialists, anchoring technical specification support for ISO-classified hydraulic systems. These three entities represent divergent competitive vectors: inventory proximity through physical presence, captive consumption data through embedded automation, and engineering-led specification capture in complex motion control applications.
| Leading Market Players |
|---|
| MSC Industrial Direct |
| Applied Industrial Technologies |
| W.W. Grainger |
| Global Industrial |
| Ferguson Enterprises |
| Fastenal Company |
| Rexel Group |
| Vallen Distribution |
| WESCO International |
| Others |
Supply & Pricing Matrix
Automotive OEM consolidation in Germany's industrial corridor demands same-day mechanical component fulfillment, forcing distributors to position inventory closer to manufacturing clusters and absorb premium logistics costs that compress margin on standardized products.
Pricing Analysis
Short lead-time premiums command pricing power in Germany's automotive corridor where machinery OEMs penalize delivery delays with supplier disqualification. Three-tier pricing structure across REACH-certified premium, ISO-compliant standard, and catalog-economy levels stratifies margin pools. Price differentiation hinges on batch-level provenance documentation and same-day fulfillment density. Pricing pressure stems from ERP-integrated portal transparency that exposes cost structures to procurement teams. Mid-tier manufacturing plants exhibit highest price sensitivity; aerospace suppliers show lowest due to FAA traceability requirements.
Supply Chain Analysis
REACH registration and ECHA certification gating elevates supplier qualification costs for chemical inventory documentation, filtering mid-tier distributors from European markets. Production clusters in China, Germany, and the United States anchor hydraulic fitting and electrical component supply. Raw material flows draw from specialty steel mills, polymer compounders, and copper smelters. Single-source vulnerability concentrates in Yangtze River Delta manufacturing hubs exposed to GB standards enforcement delays. Distribution runs through branch-network operators with vendor-managed inventory programs embedding automated replenishment at customer facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance costs construct a barrier-to-entry moat that rewards ECHA-certified distributors with certified-supplier premiums while straining balance sheets of undercapitalized competitors.
For Market Incumbents: Extend ECHA-certified data infrastructure to capture chemical and pharmaceutical vertical consolidation. Lock out competitors through captive consumption data from site-embedded vending programs. Build backward integration into temperature-controlled warehousing for EPA-tracked hazardous substances. Counter ERP portal transparency threats with proprietary demand forecasting algorithms that compress customer working capital cycles. For New Entrants and Emerging Players: India's PLI scheme for machinery and automotive production opens a window for first-mover BIS-certified inventory positions in Maharashtra and Gujarat corridors. Target mid-tier manufacturing plants migrating from catalog-based ordering to digital procurement channels. Exploit certification timeline compression gaps that incumbent distributors struggle to fund. Lead with converged fluid power and conveyance system integration services that unbundle technical support from product procurement. For Investors and Strategic Acquirers: Re-rating potential sits with REACH-certified specialists given EU Green Deal digital product passport mandates. Long-term viability favors distributors with real-time inventory orchestration infrastructure over batch-processed legacy operators. Monitor AI-powered demand forecasting adoption rates at Japanese automotive OEMs as inflection indicator for working capital compression advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Temperature-Controlled Warehousing | EPA hazardous substance tracking and FDA food-contact compliance elevate specialized storage from cost center to competitive moat. |
| ECHA-Certified Data Infrastructure Investment | REACH dossier updates and batch-level provenance records enable certified-supplier premiums in chemical and pharmaceutical verticals. |
| Site-Embedded Vending Program Expansion | Captive consumption data capture at customer facilities locks replenishment automation and excludes competitor access. |
| AI-Powered Demand Forecasting Deployment | Predictive algorithms at German and Japanese automotive OEMs compress working capital cycles versus legacy reorder-point methods. |
| PLI Corridor Establishment in India | BIS-certified inventory positions in Maharashtra and Gujarat manufacturing belts capture machinery and automotive procurement growth. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads validated demand-side patterns. Secondary sources included ECHA registration databases, EPA hazardous substance tracking systems, SEC 10-K distributor filings, and EU customs trade records. Bottom-up SKU-level demand modeling triangulated against top-down industrial production indices across the analysis window.
Data-stream reconciliation across procurement volume surveys, distributor inventory disclosures, and manufacturing capacity utilization statistics informed the analytical framework. Segmentation dimensions modeled encompass product type complexity tiers, distribution channel digital maturity, end-use industry concentration patterns, and regional regulatory enforcement intensity. CAGRs derived from trend extrapolation of ERP portal adoption curves and vendor-managed inventory penetration rates. Composite polymer substitution velocity and REACH compliance cost trajectories served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for AI-powered demand forecasting would alter the outlook for working capital compression advantages. Forecasts reflect assumptions regarding EU Green Deal implementation timelines and PLI scheme disbursement continuity. A model refresh is warranted upon material change in ECHA registration obligation enforcement intensity or GB standards revision schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Power Transmission Cables Market
Transmission and Distribution
North America DC Distribution Network Market
Transmission and Distribution
Distribution Lines and Poles Market
Transmission and Distribution
Southeast Asia Power Transmission and Distribution Market
Transmission and Distribution
Energy Cable Market
Transmission and Distribution
Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
India HVDC Transmission Systems Market
Transmission and Distribution
Electric Power Transmission and Distribution Equipment Market
Transmission and Distribution
Wireless Power Transmission Market
Transmission and Distribution
Europe Active Network Management Market
Transmission and Distribution
Mobile Substation Market
Transmission and Distribution
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
United States LNG Infrastructure Market
Transmission and Distribution
Australia High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Bulk Terminals Market
Transmission and Distribution
Heat Interface Unit Market