
 Underground Cabling EPC Market | 2026-2036
Underground Cabling EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Underground Cabling EPC Market Analysis
Germany's North Sea offshore wind landfall corridor build-out is rewriting procurement patterns for high-voltage direct current installations. Prysmian Group leverages its submarine-to-onshore cable integration capabilities to anchor large-scale EPC awards across the Baltic and North Sea regions. Larsen & Toubro dominates turnkey tunneling contracts in India and the Middle East through its specialized underground infrastructure division. Nexans competes on advanced cross-linked polyethylene insulation systems for 400 kV and above transmission ratings.
Underground Cabling EPC encompasses the engineering, procurement, and construction of subterranean power and telecommunications cable systems, typically involving trench depths of 1.2 to 3.5 meters, thermal backfill specifications, and direct-buried or duct-bank configurations designed to minimize electromagnetic interference and environmental exposure. The primary purpose is to deliver reliable electricity and data transmission while eliminating overhead line visual impact, weather vulnerability, and right-of-way constraints in dense urban and ecologically sensitive corridors. HVAC cable type deployments occupy the largest share of current contract value due to established utility procurement frameworks for alternating-current grid reinforcement. Fiber optic installations represent the fastest-expanding segment as 5G backhaul and smart grid communication networks drive parallel duct requirements alongside power cables. Infrastructure project type engagements concentrate the highest margin pools given their complexity, extended timelines, and integrated civil-electrical scope.
EU Green Deal implementation through REACH material compliance and CE marking for cable assemblies shapes product qualification requirements across European contracts. The US Inflation Reduction Act channels investment tax credits toward undergrounding projects in wildfire-prone Western states, with FERC interconnection queue reforms accelerating developer timelines. China's GB standards for 110 kV and above XLPE-insulated power cables, administered by SAMR, mandate localized testing protocols that influence foreign EPC bidding strategies. Stakeholders must monitor how divergent national certification regimes affect cross-border equipment sourcing and subcontractor qualification costs.
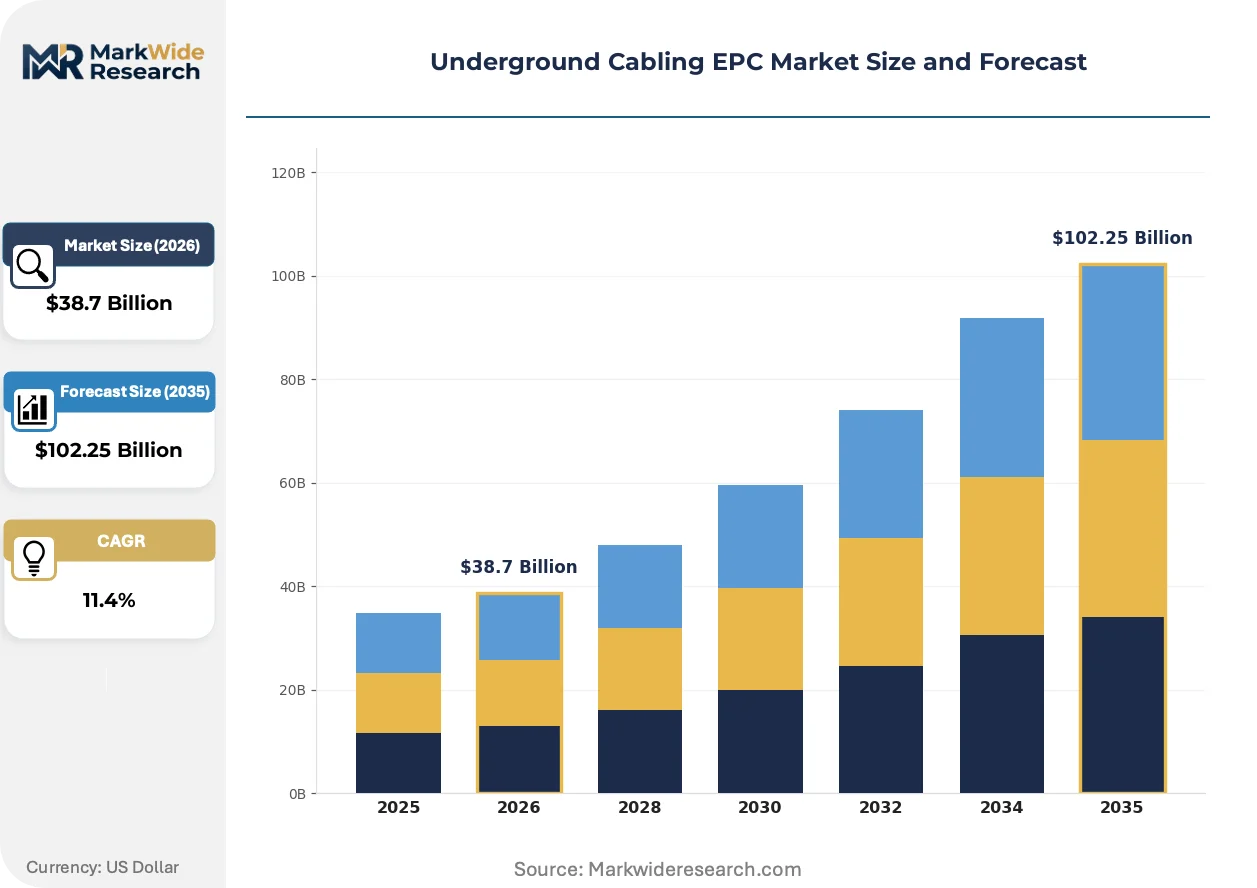
Market Dynamics
Grid hardening mandates under the EU Green Deal, US Inflation Reduction Act, and China's dual carbon targets are compressing project timelines while elevating technical qualification barriers for EPC contractors bidding on subterranean transmission corridors.
Growth Catalysts
- EU Green Deal implementation:REACH material compliance and CE marking requirements for cable assemblies are expanding contract scopes toward integrated civil-electrical delivery models across German and French offshore wind landfall projects.
- Utility-scale renewable interconnection:Offshore wind developers in the North Sea and Baltic regions are bundling submarine-to-onshore cable integration into single-source EPC awards to reduce interface risk.
- XLPE insulation advancement:Cross-linked polyethylene systems rated for 400 kV and above are unlocking higher-capacity underground corridors in dense urban environments where overhead right-of-way is unavailable.
Market Restraints
- Copper and aluminum price volatility:Raw material cost swings in commodity metals are compressing fixed-price contract margins and forcing escalation clauses into long-duration infrastructure engagements.
- Trenchless installation equipment scarcity:Specialized horizontal directional drilling rigs and micro-tunneling systems concentrate among a limited pool of European and Japanese equipment suppliers, creating bottleneck risk.
- GB standards localization:China's SAMR-mandated testing protocols for 110 kV and above XLPE-insulated cables impose redundant certification burdens on foreign EPC bidders seeking state grid contracts.
Strategic Opportunities
- India's urban undergrounding mandate:Smart city initiatives in Mumbai, Delhi, and Bengaluru are creating turnkey tunneling demand as municipal authorities eliminate overhead distribution in central business districts.
- 5G-fiber convergence:Parallel duct requirements for power and telecommunications cables in 5G backhaul corridors are enabling bundled EPC offerings that capture higher integrated margins.
- US wildfire resilience incentives:Investment tax credits under the Inflation Reduction Act for undergrounding in California, Oregon, and Washington are redirecting utility capex toward subterranean hardening projects.
Industry Challenges
- Thermal backfill engineering expertise:Specialized civil engineers capable of calculating soil thermal resistivity and designing optimized trench geometries remain scarce relative to project pipeline growth.
- FERC interconnection queue reforms:Accelerated developer timelines under US federal mandates are compressing EPC pre-construction phases and straining resource mobilization capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underground Cabling EPC Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Residential, Commercial, Industrial, Infrastructure Cable Type: HVAC, HVDC, Fiber Optic, Copper Installation Method: Tunneling, Trenching, Directional Drilling, Direct Burial Client Type: Utility Companies, Contractors, Government Agencies, Developers |
| Companies Covered | Prysmian Group, Larsen & Toubro, KEC International, Nexans, Sumitomo Electric Industries, Sterlite Power, Skanska, ZTT Group, MasTec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underground Cabling EPC Market Emerging Trajectories
Material science breakthroughs and procurement model evolution are redefining competitive differentiation in underground cabling EPC, shifting value capture toward integrated civil-electrical capabilities and advanced insulation technologies.
High-temperature superconducting (HTS) cable systems are emerging as a transformative solution for ultra-high-capacity urban corridors where conventional XLPE reaches thermal limits. Tokyo Electric Power and Korea Electric Power Corporation are piloting HTS installations in dense metropolitan substation links. This technology is rendering obsolete traditional capacity expansion through additional parallel circuits, compressing right-of-way requirements by 70 percent or more.
The EU F-Gas Regulation phase-down is accelerating adoption of dry-type cable terminations and gas-insulated switchgear alternatives in environmentally sensitive corridors. Industrial consequence includes forced retooling of jointing and termination subcontractor capabilities across German and Scandinavian projects. Offshore wind landfall installations in Denmark and the Netherlands are most affected, with developers now specifying fluorinated-gas-free equipment packages in tender documents.
Integrated design-build-finance-operate (DBFO) contracting is displacing traditional lump-sum EPC arrangements for multi-year transmission corridor programs. State grid corporations in China and regional utilities in Japan are consolidating decade-long undergrounding programs under single concession holders. This shift is most visible in Tokyo's Chiyoda and Minato wards, where TEPCO has awarded 15-year integrated service contracts replacing sequential project-by-project procurement.
Underground Cabling EPC Market Segmentation
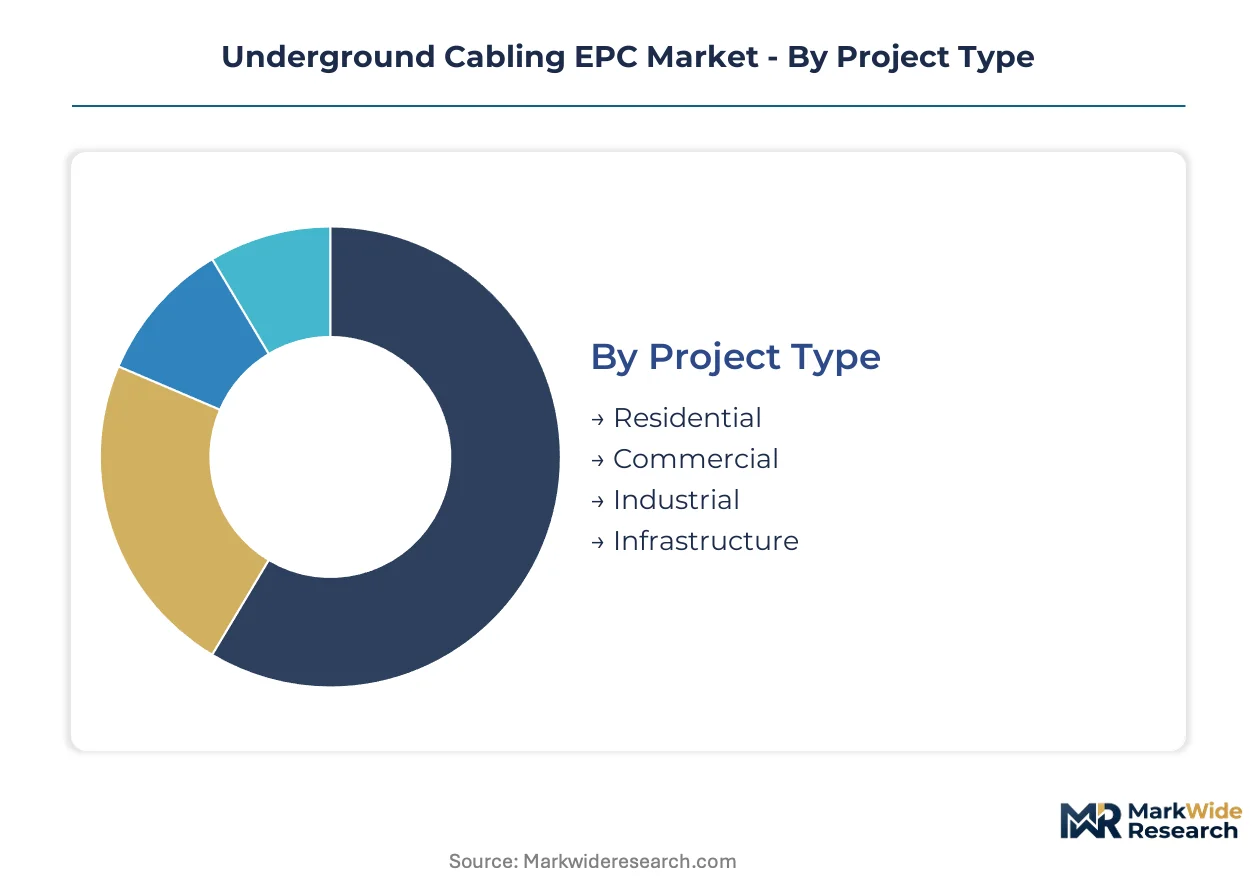
Segmentation in underground cabling EPC reveals divergent margin structures and mobilization requirements across project archetypes. Contract duration, technical complexity, and client procurement sophistication vary dramatically by category, shaping bidder qualification strategies and resource allocation priorities.
Project Type:
Residential contracts turn over fastest with standardized designs, while infrastructure programs stretch across multi-year horizons with bespoke engineering demands.
- Residential:Single-family and multi-unit dwelling connections utilize shallow trenching at 1.2-1.8 meter depths with standardized XLPE-insulated medium-voltage feeders. Municipal undergrounding mandates in dense Indian and Chinese urban cores are accelerating contract velocity for localized distribution upgrades.
- Infrastructure:Highway, rail, and airport corridor installations demand integrated civil-electrical scope spanning tunneling, thermal backfill engineering, and long-term maintenance protocols. Germany's North Sea offshore wind landfall corridors and Japan's metropolitan substation links concentrate the highest-value awards in this category.
- Commercial:Data center campuses and logistics parks require redundant power pathways with parallel fiber optic ducts for smart building integration.
- Industrial:Heavy manufacturing and petrochemical facilities specify armored cables with enhanced fire resistance and chemical immunity ratings.
Infrastructure dominates installed base value. Residential is where expansion concentrates fastest as urban densification accelerates.
Cable Type:
Cost tiers separate commodity conductors from specialized insulation systems commanding engineering premiums.
- HVAC:Alternating-current XLPE-insulated systems rated through 400 kV constitute the procurement volume foundation for grid reinforcement programs. Established utility frameworks across the United States, Germany, and Japan sustain predictable demand cycles for standardized ratings.
- Fiber Optic:Single-mode and multimode installations for 5G backhaul and smart grid communications require parallel duct engineering alongside power corridors. India's smart city initiatives and China's dual carbon monitoring networks are driving the steepest expansion trajectory in this segment.
- HVDC:High-voltage direct current submarine-to-onshore integration demands specialized converter stations and extruded insulation expertise.
- Copper:Low-voltage distribution and grounding applications persist in legacy urban networks despite aluminum substitution trends.
HVAC anchors procurement volume. Fiber optic is climbing the fastest as digital infrastructure converges with power grid hardening.
Installation Method:
Application context dictates method selection, with environmental sensitivity and right-of-way constraints driving technique differentiation.
- Tunneling:Micro-tunneling and cut-and-cover methods enable deep corridor placement beneath dense urban fabric and ecologically protected zones. TEPCO's 15-year integrated service contracts in Tokyo's Chiyoda and Minato wards exemplify long-term tunneling program consolidation.
- Directional Drilling:Horizontal directional drilling minimizes surface disruption for river crossings, rail alignments, and congested utility corridors. Equipment scarcity among European and Japanese rig suppliers creates bottleneck risk for project scheduling.
- Trenching:Open-cut excavation remains cost-preferred for greenfield suburban and rural deployments with minimal surface constraints.
- Direct Burial:Simplest method for low-voltage distribution in undeveloped terrain with favorable soil thermal properties.
Trenching holds the largest cumulative installed base. Directional drilling is gaining share fastest as urban surface constraints intensify.
Client Type:
Procurement sophistication and contract duration vary sharply across buyer categories, from standardized utility frameworks to bespoke government specifications.
- Utility Companies:State grid corporations and investor-owned utilities deploy multi-year capital programs with pre-qualified vendor pools and standardized technical specifications. China's SAMR-mandated GB testing protocols and Japan's METI-guided grid hardening roadmaps shape procurement parameters.
- Government Agencies:Municipal, state, and national authorities specify integrated DBFO arrangements for decade-long undergrounding mandates. US wildfire resilience programs under FERC interconnection reforms and EU Green Deal implementation are redirecting agency capex toward subterranean solutions.
- Contractors:Tier-1 EPC firms subcontract specialized installation segments, creating tiered supply structures for complex projects.
- Developers:Renewable energy and real estate developers bundle cabling into broader project financing with shorter decision cycles.
Utility companies dominate contract value. Government agencies are where procurement innovation concentrates as DBFO models displace traditional lump-sum arrangements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC interconnection queue reforms and the US Inflation Reduction Act anchor the dominant geography, compressing developer timelines while channeling investment tax credits toward wildfire resilience undergrounding across Western states.
United States
Wildfire-prone utilities in California, Oregon, and Washington are redirecting capital expenditure toward subterranean hardening projects under IRA incentives. FERC mandates accelerate pre-construction phases, straining contractor mobilization capabilities. Pacific Northwest corridor developments concentrate specialized trenchless installation demand.
Germany
North Sea offshore wind landfall corridors are rewriting procurement patterns for high-voltage direct current installations. EU Green Deal implementation through REACH material compliance and CE marking shapes product qualification requirements. Baltic and North Sea regions anchor submarine-to-onshore cable integration awards.
China
Dual carbon targets accelerate subterranean transmission build-outs in dense urban corridors. SAMR-mandated GB standards for 110 kV and above XLPE-insulated cables impose localized testing protocols. Yangtze River Delta metropolitan clusters drive integrated civil-electrical contract consolidation.
India
Smart city initiatives in Mumbai, Delhi, and Bengaluru create turnkey tunneling demand as municipal authorities eliminate overhead distribution. CEA guidelines shape technical specifications for urban undergrounding mandates. Maharashtra and Karnataka infrastructure programs concentrate specialized contractor deployment.
Japan
METI-guided grid hardening roadmaps sustain predictable demand cycles for standardized transmission ratings. Tokyo's Chiyoda and Minato wards exemplify 15-year integrated service contract consolidation replacing sequential procurement. Kanto metropolitan substation links concentrate high-value infrastructure awards.
Underground Cabling EPC Market Vendor Landscape
Integrated cable manufacturers and specialized infrastructure contractors split the market between material-technology control and civil-electrical execution capability. The vendor base concentrates among European and Asian conglomerates with captive insulation compound production or tunneling equipment fleets. Three archetypes dominate: vertically integrated cable producers, turnkey tunneling specialists, and regional EPC consolidators. Competitive moves center on submarine-to-onshore integration bundling and decade-long DBFO concession capture.
Among European integrated manufacturers, Prysmian Group and Nexans occupy positions exemplifying material-technology anchoring through advanced cross-linked polyethylene systems. Larsen & Toubro represents the turnkey tunneling specialist archetype, anchoring civil-electrical execution capabilities across South Asian and Middle Eastern corridors. These three entities illustrate how competitive positioning stratifies between insulation technology control and specialized installation expertise.
| Leading Market Players |
|---|
| Prysmian Group |
| Larsen & Toubro |
| KEC International |
| Nexans |
| Sumitomo Electric Industries |
| Sterlite Power |
| Skanska |
| ZTT Group |
| MasTec |
| Others |
Supply Flow & Price Mechanics
Shanghai's Yangtze River Delta cable manufacturing cluster anchors global XLPE insulation supply, with capacity utilization swings directly transmitting into EPC contractor procurement leverage. When regional polymer compounders run above 85 percent utilization, pricing power shifts decisively toward material suppliers and squeezes fixed-price infrastructure margins.
Pricing Analysis
European-North American price spreads for 400 kV HVDC cable systems now exceed 35 percent, driven by EU REACH compliance premiums and US IRA tax credit stacking. Three-tier pricing structure across premium, standard, and economy levels separates submarine-qualified installations from terrestrial distribution. Cost compression in standard-rated HVAC segments is intensifying because Chinese GB-certified producers are flooding procurement tenders. Municipal utilities in India and Southeast Asia exhibit highest price sensitivity, while German offshore wind developers prioritize technical qualification over unit economics.
Supply Chain Analysis
Extended payment terms now stretch 180-270 days for trenchless equipment lessors, with supply-chain finance facilities concentrating among Japanese and German rig manufacturers. Copper cathode supply draws from Chile, Peru, and Chinese smelter complexes, while XLPE compound production rests on South Korean and German petrochemical feedstocks. Single-source vulnerability runs through European horizontal directional drilling rig availability, where only three specialized manufacturers serve global demand. Distribution runs through tiered EPC prime-subcontractor structures with state grid corporations and integrated cable manufacturers at the apex.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards specialized civil-electrical execution capabilities that remain scarce relative to project pipeline expansion, with thermal backfill engineering expertise and trenchless installation fleets constituting critical bottlenecks that constrain contract fulfillment.
For Market Incumbents: Insulate margin structures by deepening backward integration into XLPE compound production and securing captive horizontal directional drilling capacity through equipment leasing subsidiaries. The threat of Chinese state-backed EPC consolidators bidding below cost on Belt and Road corridor projects demands defensive positioning through pre-qualified vendor status with EU and Japanese utilities. For New Entrants and Emerging Players: Establish a beachhead in India's smart city undergrounding mandates, where CEA technical specifications create qualification barriers lower than European CE-marking regimes but contract velocity exceeds 40 percent annual growth. Target turnkey tunneling subcontracts from tier-1 EPC primes rather than direct utility engagement, leveraging specialized micro-tunneling expertise as the go-to-market wedge. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated cable manufacturers with captive HVDC insulation capabilities and established submarine-to-onshore project track records. Long-term viability hinges on 5-10 year concession capture under DBFO contracting models displacing lump-sum EPC arrangements. Watch FERC interconnection queue processing velocity as the signal indicating whether US project timelines will compress or extend.| Strategic Initiative | Industry Significance |
|---|---|
| Submarine-to-Onshore Integration Capability | Bundled EPC awards reduce interface risk for North Sea offshore wind landfall corridors. |
| GB Standards Certification Investment | SAMR-mandated testing protocols unlock state grid contract eligibility in China. |
| Trenchless Equipment Fleet Expansion | Horizontal directional drilling rig scarcity creates scheduling bottleneck across European projects. |
| DBFO Concession Structuring | 15-year integrated service contracts in Tokyo's metropolitan wards displace sequential procurement. |
| Thermal Backfill Engineering Talent Acquisition | Specialized civil engineers capable of soil thermal resistivity calculation remain critically scarce. |
Methodological Framework
A standing panel of utility procurement officers, EPC project directors, trenchless equipment lessors, and cable manufacturer technical sales leads provided ongoing calibration across the primary research phase. This practitioner input combined with secondary validation from FERC interconnection queue filings, EU TSO development plans, SAMR GB standard updates, and IEA grid investment tracking. Bottom-up project pipeline aggregation and top-down regulatory spend analysis were triangulated against utility capital expenditure disclosures.
Scenario-bracketing framed low, baseline, and high cases across commodity price volatility, regulatory timeline acceleration, and equipment availability constraints throughout the forecast period. Segmentation dimensions modeled include cable type, installation method, project archetype, client procurement sophistication, and regional regulatory framework. CAGRs were derived from installed base growth rates and replacement cycle analysis, with specific inputs for offshore wind landfall corridor build-outs and urban undergrounding mandate enforcement.
Stress conditions across copper-aluminum price spreads, trenchless equipment utilization rates, and FERC queue processing timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding policy continuity for EU Green Deal implementation, US IRA incentive extension, and China's dual carbon target enforcement. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
India HVDC Transmission Systems Market
Transmission and Distribution
Flexible AC Transmission Systems Market
Transmission and Distribution
Digital Substation Market
Transmission and Distribution
Power Transmission Tower Market
Transmission and Distribution
Germany DC Distribution Network Market
Transmission and Distribution
Electrical Transmission Azimuth Thruster Market
Transmission and Distribution
South and Central America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Vapor Recovery Units Market
Transmission and Distribution
Heat Interface Unit Market
Transmission and Distribution
Europe Active Network Management Market
Transmission and Distribution
US HVDC Transmission System Market
Transmission and Distribution
Energy and Infrastructure Inertial Systems Market
Transmission and Distribution
Fixed Series Compensation Market
Transmission and Distribution
Energy Logistics Market
Transmission and Distribution
Japan High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
China High-Voltage Direct Current (HVDC) Transmission Systems Market