
 Global Mechanized Irrigation Systems Market | 2026-2036
Global Mechanized Irrigation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mechanized Irrigation Systems Market Outlook
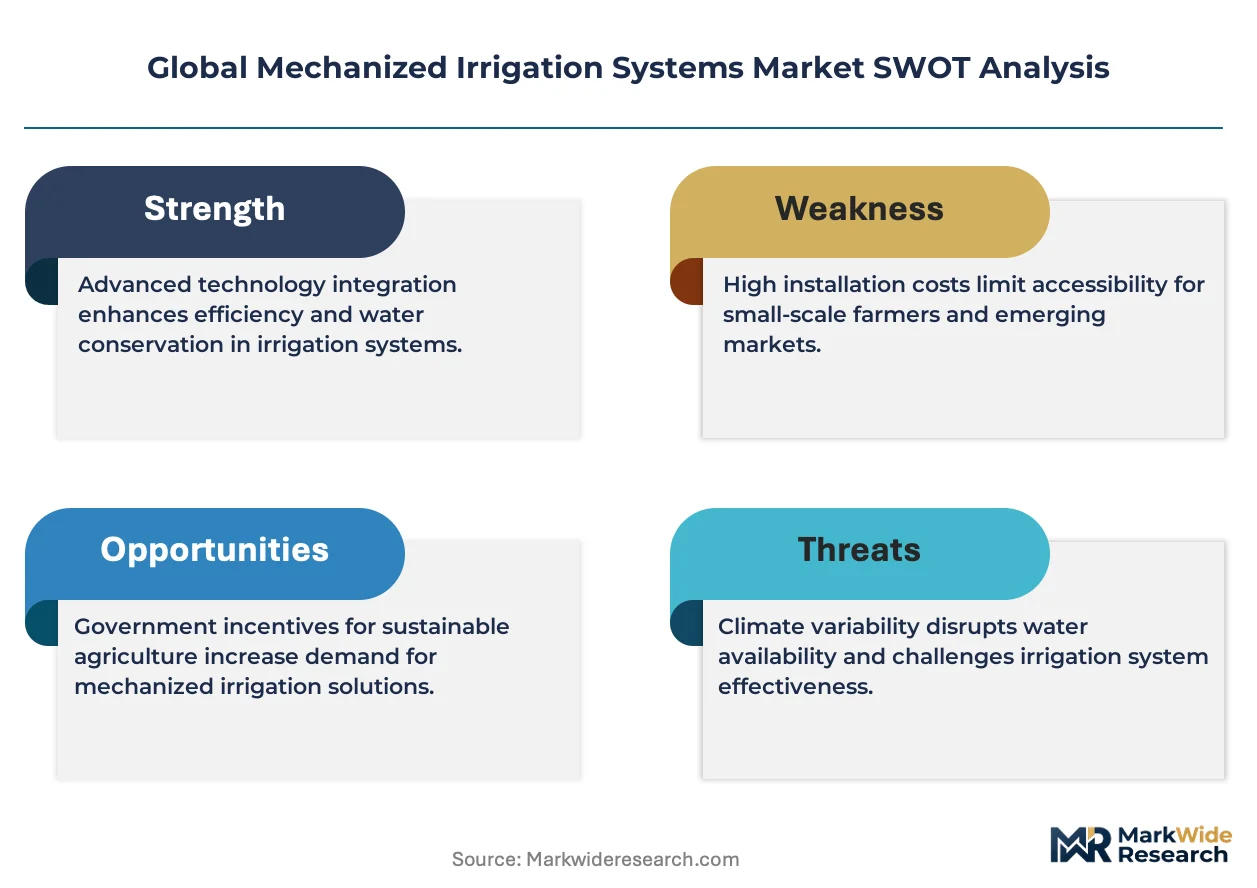
A skilled technician shortage across rural maintenance networks is unwinding service capacity in key agricultural corridors. Lindsay Corporation leverages its manufacturing scale to anchor North American center pivot supply chains. Valmont Industries sustains global reach through backward integration into steel structures and control systems. Jain Irrigation Systems Ltd. dominates South Asian drip technology with specialized polymer extrusion capabilities.
Mechanized irrigation systems are engineered assemblies of pumps, pipes, valves, and emitters designed to deliver controlled water volumes across defined crop zones, typically operating at pressures between 10 and 100 psi depending on technology type. These systems serve the primary commercial purpose of optimizing water-use efficiency and labor productivity in large-scale agricultural operations. Center pivot systems occupy the largest installed base among product categories, reflecting decades of proven performance on row-crop acreage. Sensor-based technology is expanding fastest as soil moisture and weather data integration reduces over-irrigation penalties. Variable rate irrigation commands premium positioning where field variability justifies precision water application.
The EPA enforces water discharge standards that shape equipment specifications in the United States, while REACH compliance in Europe restricts certain polymer additives used in drip tape manufacturing. Australia's Murray-Darling Basin Authority imposes extraction limits that directly drive retrofit demand for automated control systems. Stakeholders must monitor how fragmented national water policies reshape equipment certification requirements and cross-border technology transfer feasibility.
Market Dynamics
Water scarcity mandates from the EU Green Deal and Australia's Murray-Darling Basin Authority are compressing capital deployment timelines for precision irrigation retrofits across arid agricultural zones.
Growth Catalysts
- EU Green Deal farm-to-fork mandates:European agricultural producers face binding sustainability targets that accelerate sensor-based and variable rate technology upgrades across center pivot and drip installations.
- Center pivot systems:Decades of proven performance on row-crop acreage sustain the largest installed base among product categories, with arid-zone producers expanding coverage as water stress intensifies.
- Australia:Murray-Darling Basin water reforms push large-scale automation adoption, concentrating demand for mechanized systems with integrated control capabilities.
Market Restraints
- Steel price volatility:Center pivot and linear move systems depend on galvanized steel structures, exposing manufacturers and buyers to raw material cost swings that compress margin predictability.
- REACH polymer restrictions:European chemical regulations limit certain additives in drip tape manufacturing, forcing reformulation cycles that extend certification timelines and raise compliance costs.
- Skilled technician scarcity:Rural maintenance networks across key agricultural corridors face depleted service capacity, lengthening repair intervals and raising total cost of ownership for automated systems.
Strategic Opportunities
- India:Drip irrigation penetration remains below potential across water-stressed states, creating white space for polymer extrusion specialists to expand micro-irrigation coverage.
- Sensor-weather convergence:Integration of soil moisture probes with meteorological data streams enables predictive irrigation scheduling that commands premium positioning in variable rate segments.
- EPA discharge standards:United States water quality enforcement shapes equipment specifications, opening retrofit demand for filtration and control upgrades that meet evolving effluent limits.
Industry Challenges
- Control system integration:Retrofitting legacy center pivots with variable rate technology requires specialized firmware and hydraulic modifications that strain dealer technical capacity.
- Polymer certification delays:Drip tape manufacturers navigating REACH compliance face extended testing protocols that stall product launches and inventory positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mechanized Irrigation Systems Market |
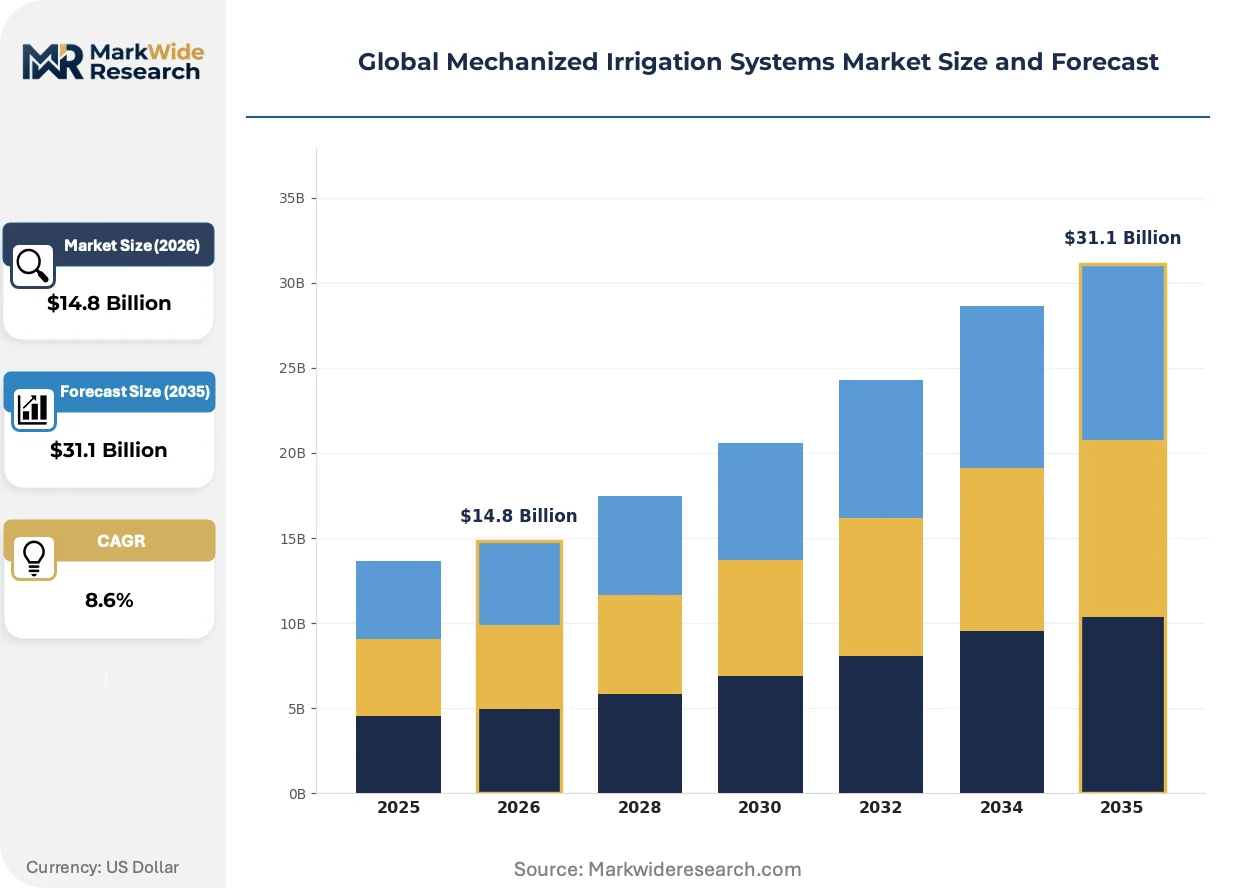
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sprinkler Systems, Drip Irrigation, Subsurface Irrigation, Center Pivot Technology: Automated Control, Sensor-Based, Remote Monitoring, Variable Rate Irrigation End User: Agricultural Producers, Greenhouses, Landscape Firms, Golf Courses Installation Type: On-Site, Modular, Custom-Built, Retrofit |
| Companies Covered | Lindsay Corporation, Nelson Irrigation Corporation, Valmont Industries, Jain Irrigation Systems Ltd., Rain Bird Corporation, The Toro Company, Rivulis Irrigation Ltd., T-L Irrigation Co., Netafim Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mechanized Irrigation Systems Market Strategic Shifts
Digital automation layers are restructuring how water is priced, scheduled, and delivered across large-scale agricultural operations, compressing the gap between sensing capability and actuation response.
Electro-hydraulic variable rate nozzles are supplanting fixed-orifice emitters in premium center pivot segments. Large-scale corn and soybean producers in the United States are retrofitting existing spans with zone-specific flow control at accelerating pace. This hardware shift is supplanting uniform application models, enabling field-scale water budgeting that aligns with aquifer depletion warnings.
REACH polymer restrictions in Europe are forcing drip tape manufacturers toward bio-based material formulations. ECHA substance evaluations have flagged plasticizers common in legacy products, triggering reformulation investments. South Asian exporters serving European horticultural markets are accelerating alternative polymer certification to maintain access.
After-sales service unbundling is fragmenting traditional dealer revenue models. Large farming cooperatives in Australia are contracting directly with telemetry providers for remote diagnostics, bypassing equipment distributors for system monitoring. This channel compression is most visible in the Murray-Darling Basin, where water trading platforms have cultivated sophisticated buyer sophistication around data-driven irrigation management.
Global Mechanized Irrigation Systems Market Segmentation
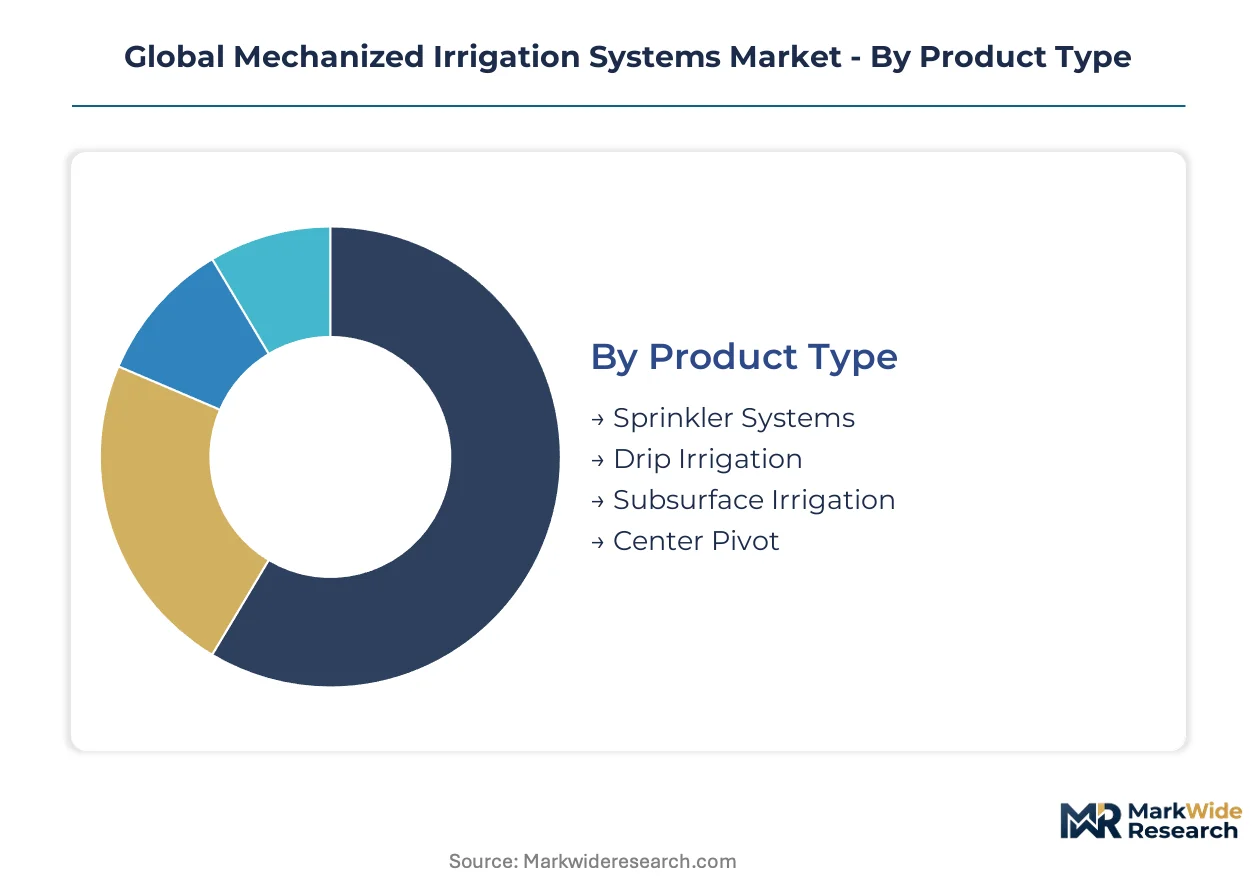
Segmentation in mechanized irrigation reveals how water delivery technologies align with distinct operational scales, regulatory environments, and capital deployment cycles. Channel strategies diverge sharply between commodity hardware sold through dealer networks and precision systems requiring direct manufacturer engagement for telemetry integration.
Product Type:
Equipment flows through agricultural dealerships for standardized hardware, while specialized polymer systems reach horticultural buyers via direct distribution partnerships with irrigation design firms.
- Center Pivot:Galvanized steel assemblies rotate around fixed anchor points, delivering pressurized water through elevated spans across quarter-section and larger fields. Australian broadacre operators in the Murray-Darling Basin are retrofitting thousands of these units with automation packages as extraction limits tighten under basin authority reforms.
- Drip Irrigation:Polymer tubing networks with pressure-compensating emitters deliver water directly to root zones through surface or subsurface placement. Indian agricultural producers across Maharashtra and Gujarat states are expanding micro-irrigation coverage as state-level subsidy programs reduce capital barriers for smallholder adoption.
- Sprinkler Systems:Fixed or portable riser assemblies distribute water through impact or gear-driven heads across orchards and field crops.
- Subsurface Irrigation:Buried drip lines or porous tubing placed below root zones minimize evaporative losses in high-value vegetable production.
Center Pivot dominates installed base. Drip Irrigation is where expansion concentrates.
Technology:
Cost tiers separate basic timer-based controls from premium systems integrating multiple data streams, with pricing stratifying across entry-level automation, mid-tier sensor integration, and enterprise-grade variable rate platforms.
- Sensor-Based:Soil moisture probes, weather stations, and crop canopy sensors feed algorithmic irrigation scheduling through wireless telemetry networks. Large-scale corn producers in the United States are deploying these systems most aggressively where aquifer depletion warnings from USGS monitoring trigger regulatory scrutiny under state-level groundwater management districts.
- Variable Rate Irrigation:Zone-specific flow modulation through electro-hydraulic nozzles enables field-scale water budgeting aligned with soil variability maps. Premium row-crop operations in Nebraska and Kansas are retrofitting legacy center pivots with this capability to optimize yields across variable topography while maintaining compliance with Republican River Compact allocations.
- Automated Control:Programmable logic controllers manage pump activation and valve sequencing based on preset schedules without external data integration.
- Remote Monitoring:Cellular or satellite telemetry enables off-site system oversight through web dashboards and mobile applications.
Automated Control captures volume leadership across developing markets. Variable Rate Irrigation is climbing the fastest as precision agriculture capital intensifies.
End User:
Customer type determines service intensity, with agricultural cooperatives demanding 24-hour response guarantees while landscape and recreational buyers prioritize aesthetic outcomes over yield optimization.
- Agricultural Producers:Broadacre and specialty crop operators seeking yield stability through optimized water stress management. Australian cotton and rice growers in the Murray-Darling Basin are consolidating procurement through water trading cooperatives that negotiate system-wide telemetry contracts bypassing traditional equipment dealers.
- Greenhouses:Controlled environment agriculture facilities requiring precise fertigation integration and humidity management through drip and misting systems. Dutch and Spanish protected horticulture operations are deploying sensor-based platforms most intensively where EU Green Deal nutrient management regulations mandate effluent monitoring.
- Landscape Firms:Commercial and municipal contractors installing irrigation for parks, corporate campuses, and residential developments.
- Golf Courses:Turf managers balancing playability with water conservation mandates through high-uniformity sprinkler coverage.
Agricultural Producers anchor procurement volume. Greenhouses are gaining share fastest as protected cropping expands.
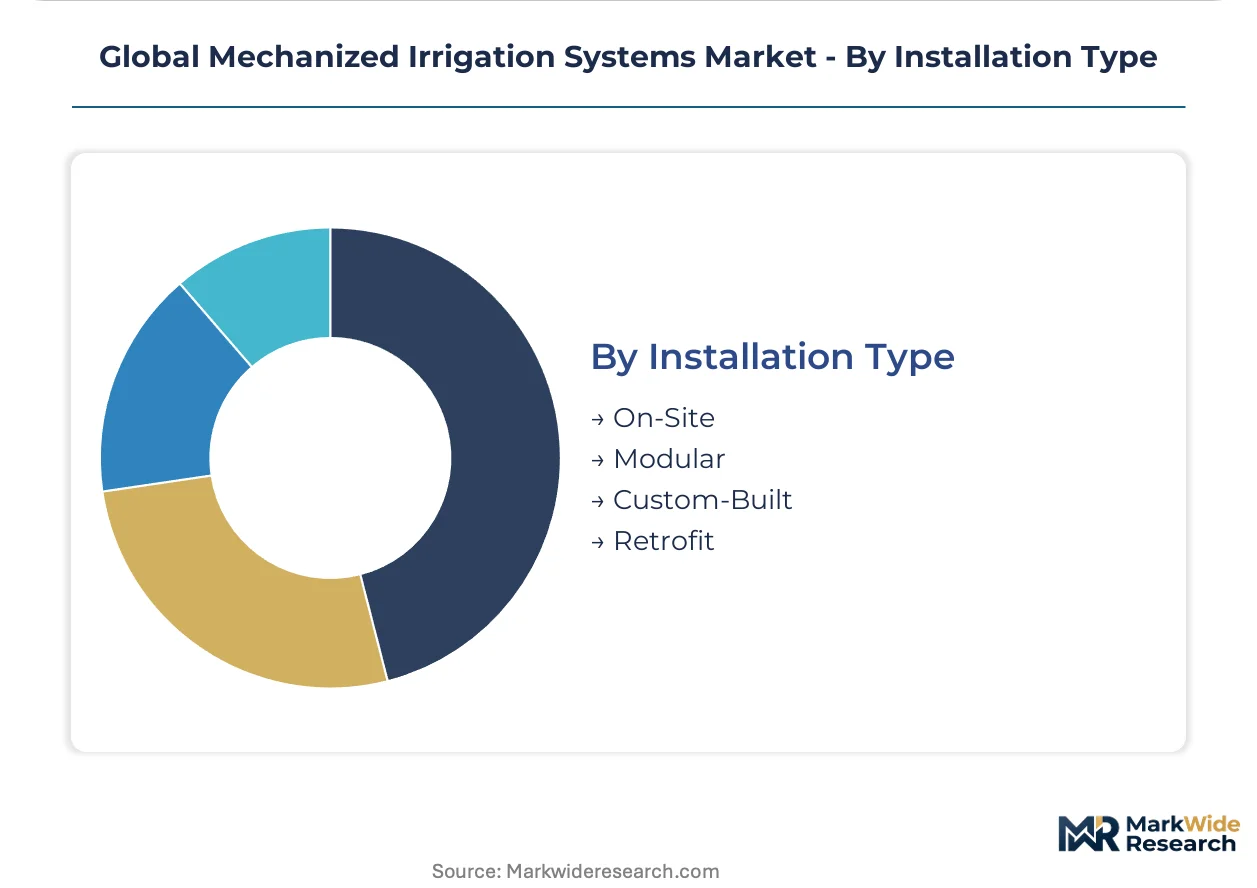
Installation Type:
Supply concentration favors modular platforms where component standardization enables rapid field assembly, while custom engineering retains margin in complex terrain applications.
- Retrofit:Automation and precision upgrades to existing center pivot and linear move infrastructure. United States growers across the High Plains are prioritizing this capital path where steel structure longevity extends system life beyond two decades while control technology obsolescence demands periodic refresh.
- Modular:Pre-engineered span sections and control packages enabling rapid deployment across standardized field geometries. Large farming cooperatives in Brazil's Cerrado region are favoring this approach where seasonal planting windows compress installation timelines.
- On-Site:Fully customized system assembly from component stock tailored to specific field contours and crop rotations.
- Custom-Built:Engineered-to-order solutions for irregular topography or specialized crop requirements requiring non-standard hydraulic design.
Retrofit commands immediate attention as installed base ages. Modular is where manufacturer capacity is concentrating for emerging market expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by water endowment and regulatory intensity. Australian producers prioritize telemetry integration under basin-wide extraction caps, while Indian smallholders respond to state subsidy programs for micro-irrigation hardware.
United States
Large-scale corn and soybean operators across Nebraska and Kansas drive center pivot retrofits with variable rate technology. EPA water discharge standards shape equipment specifications for filtration and control upgrades. The High Plains Aquifer region concentrates demand where Republican River Compact allocations enforce groundwater discipline.
Australia
Cotton and rice growers in the Murray-Darling Basin consolidate procurement through water trading cooperatives. The Murray-Darling Basin Authority imposes extraction limits that accelerate automation adoption. New South Wales and Victoria host the densest installed base of retrofitted center pivots with integrated control capabilities.
India
Maharashtra and Gujarat states expand drip irrigation coverage as water stress intensifies across Deccan Plateau agriculture. State-level subsidy programs reduce capital barriers for smallholder micro-irrigation adoption. Jain Irrigation Systems Ltd. anchors polymer extrusion supply chains from Jalgaon manufacturing clusters.
Germany
Precision horticulture operations in Bavaria and Baden-Württemberg deploy sensor-based platforms under EU Green Deal nutrient management mandates. REACH compliance restricts polymer additives in drip tape formulations. The Lower Saxony greenhouse belt concentrates protected cropping investment with fertigation integration requirements.
Brazil
São Paulo and Minas Gerais soybean producers favor modular center pivot deployment where seasonal planting windows compress installation timelines. Water pricing reforms in Cerrado irrigation districts accelerate capital deployment for efficiency upgrades. Large farming cooperatives negotiate direct telemetry contracts bypassing traditional equipment distribution.
Global Mechanized Irrigation Systems Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrated in steel fabrication and polymer extrusion capabilities. The upper tier commands supply chain security through captive manufacturing of structural components and control systems. Mid-tier specialists compete on regional service density and crop-specific application expertise. Dominant competitive moves include backward integration into raw material production and strategic partnerships with telemetry providers for remote diagnostics capability.
Among North American integrated manufacturers, Lindsay Corporation and Valmont Industries exemplify scale-driven archetypes with captive steel supply chains. Jain Irrigation Systems Ltd. represents the polymer specialization vector, anchoring South Asian drip technology capacity. Rivulis Irrigation Ltd. and Netafim Limited occupy positions within the precision application tier, while T-L Irrigation Co. and Nelson Irrigation Corporation exemplify regional fabrication specialists with concentrated dealer networks. Rain Bird Corporation, The Toro Company, and Lindsay Corporation sit within the diversified irrigation portfolio archetype, spanning residential through agricultural segments.
| Leading Market Players |
|---|
| Lindsay Corporation |
| Nelson Irrigation Corporation |
| Valmont Industries |
| Jain Irrigation Systems Ltd. |
| Rain Bird Corporation |
| The Toro Company |
| Rivulis Irrigation Ltd. |
| T-L Irrigation Co. |
| Netafim Limited |
| Others |
Value Chain & Pricing Dynamics
Electro-hydraulic variable rate nozzles displacing fixed-orifice emitters are simultaneously shifting procurement geography toward Nebraska and Kansas retrofit clusters while compressing margin structures for legacy hardware manufacturers unable to command precision premiums.
Pricing Analysis
Long-term offtake contracts dominate Australian cotton and rice cooperative procurement, locking in telemetry service bundles that bypass dealer markups. Three-tier pricing structure across premium variable rate, standard automated control, and economy timer-based systems stratifies by integration complexity and sensor density. Cost compression in economy tiers is intensifying because Indian state subsidy programs cap reimbursable hardware values. Smallholder agricultural producers in Maharashtra exhibit highest price sensitivity, while Murray-Darling Basin water trading cooperatives prioritize total cost of ownership over capital outlay.
Supply Chain Analysis
Inbound logistics costs through Los Angeles and Long Beach port congestion have elevated landed costs for Indian polymer extrusion exports serving European horticultural markets. Galvanized steel structures draw from captive mills in the United States and integrated foundries in China, while pressure-compensating emitters rest on specialized polymer formulation capabilities concentrated in Israel and India. Single-source vulnerability in electro-hydraulic nozzle servo motors creates procurement risk for variable rate system assemblers. Distribution runs through agricultural dealerships for standardized center pivot hardware and direct manufacturer engagement for telemetry-integrated precision platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as drone-based aerial irrigation prototypes attract venture funding for arid-zone specialty crop applications.
For Market Incumbents: Compound backward integration into polymer extrusion capabilities to neutralize REACH compliance cost disadvantages against bio-based formulation specialists. Anchor dealer service networks with certified technician training pipelines to offset rural maintenance capacity scarcity threatening aftermarket revenue streams.
For New Entrants and Emerging Players: EU Green Deal nutrient management certification fast-tracks market access for sensor-weather convergence platforms serving Dutch and Spanish protected horticulture operations. Target Maharashtra and Gujarat smallholder drip penetration gaps through state subsidy program alignment and village-level demonstration plot networks.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated manufacturers with captive steel supply chains and telemetry software stacks across the medium-term viability window. Monitor Republican River Compact enforcement intensity as inflection signal for High Plains Aquifer region retrofit demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Extrusion | REACH compliance cost insulation secures European horticultural market access against bio-based competitors. |
| Telemetry Service Unbundling | Murray-Darling Basin cooperative direct contracting fragments traditional dealer revenue models. |
| Variable Rate Retrofit Certification | EPA discharge standard alignment opens United States High Plains Aquifer region upgrade demand. |
| Technician Training Pipeline Investment | Rural maintenance network capacity scarcity threatens aftermarket service revenue capture. |
| Sensor-Weather Convergence Platform Launch | EU Green Deal nutrient management mandates create protected horticulture procurement pull. |
Study Parameters
The analysis maps center pivot, drip irrigation, sprinkler, and subsurface system categories, each validated through equipment procurement managers at agricultural cooperatives, aftermarket service directors at dealer networks, polymer formulation specialists at extrusion facilities, and control systems engineers at telemetry providers. Primary interview intelligence triangulates against customs trade data for steel and polymer imports, EPA discharge standard filings, EU ECHA substance evaluation databases, and Murray-Darling Basin Authority extraction limit records. Bottom-up installation unit aggregation and top-down agricultural capital expenditure benchmarking cross-validate volume estimates.
Consistency checks against external benchmarks confirmed projection outputs align with observed retrofit penetration rates and state subsidy program disbursement trajectories. The analytical framework models technology tier, crop type, installation mode, and regional water governance regime across the projection horizon. CAGRs derive from compounding annual installation growth adjusted for replacement cycle dynamics and regulatory mandate acceleration effects. Groundwater management district enforcement intensity and polymer certification timeline distributions serve as industry-specific forecast inputs.
Underlying assumptions cover stable steel price volatility ranges and REACH polymer restriction implementation timelines, with deviation risk concentrated in Republican River Compact renegotiation outcomes and EU Green Deal subsidy program continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Global Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Australia Irrigation Automation Market
Farm Equipment and Irrigations
Africa Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Agriculture Logistics Market
Farm Equipment and Irrigations
South America Irrigation Machinery Market
Farm Equipment and Irrigations
Fertigation Control System Market
Farm Equipment and Irrigations
Global Center Pivot Irrigation Systems Market
Farm Equipment and Irrigations
Solar Powered Irrigation System Market
Farm Equipment and Irrigations
Sprinkler Irrigation Market
Farm Equipment and Irrigations
Tractor Rental Market
Farm Equipment and Irrigations
India Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Irrigation Liner Market
Farm Equipment and Irrigations
Europe Irrigation Valves Market
Farm Equipment and Irrigations
United States Irrigation Valves Market
Farm Equipment and Irrigations
Global Irrigation Machinery Market
Farm Equipment and Irrigations
Hose Reel Irrigation Machine Market