
 Food and Beverage Packaging Market | 2026-2036
Food and Beverage Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Food and Beverage Packaging Market Insights
Smart packaging integration with QR-enabled traceability and active freshness monitoring is reshaping how food and beverage products are protected, tracked, and authenticated across supply chains. Amcor plc leverages its global manufacturing footprint to dominate high-barrier flexible films for protein and dairy applications. Tetra Pak International S.A. anchors its competitive position through aseptic carton technology leadership and captive recycling infrastructure in European dairy markets. Mondi differentiates by controlling integrated pulp-to-paperboard operations that sustain cost advantages in corrugated and kraft packaging segments.
Food and beverage packaging encompasses engineered containment systems manufactured from plastic resins, glass, metal alloys, or paper-based substrates, designed to preserve organoleptic properties, prevent microbial contamination, and extend shelf life through controlled barrier performance against oxygen, moisture, and light. Flexible packaging leads volume deployment in snack and ready-to-eat meal applications where lightweighting and format versatility reduce logistics costs and material intensity. Rigid plastic and glass formats retain margin concentration in premium beverage segments where brand differentiation through tactile and visual shelf presence commands price premiums. Paper-based corrugated and folding carton segments are accelerating fastest as food processors and retailers face mounting compliance obligations under extended producer responsibility frameworks.
The EU Green Deal and REACH regulations in Europe mandate recyclability targets and restricted substance thresholds that force material substitutions across plastic-intensive formats. The FDA governs food contact substance notifications in the United States, while China's SAMR enforces GB standards for packaging migration limits that condition market access for imported packaged goods. Stakeholders must monitor diverging regional compliance timelines and pre-emptively qualify alternative material platforms before regulatory phase-outs disrupt incumbent supply arrangements.
Market Dynamics
Extended producer responsibility frameworks are forcing material substitutions across plastic-intensive formats as regulators impose recyclability mandates and carbon accounting requirements on packaging producers.
Growth Catalysts
- EU Green Deal compliance deadlines:Beverage manufacturers accelerate fiber-based transitions to meet recyclability targets and avoid penalties under circular economy action plans.
- Smart packaging integration:QR-enabled traceability and active freshness monitoring expand adoption as retail chains demand supply chain transparency and authentication capabilities.
- German retail procurement:Supermarket chains and food processors concentrate demand for kraft and corrugated alternatives, creating pull-through for sustainable material platforms.
Market Restraints
- Resin cost volatility:Fossil-based polymer feedstock price swings compress margins for converters locked into long-term supply contracts with petrochemical suppliers.
- Technical barrier limitations:Fiber-based formats face oxygen and moisture transmission rate constraints that disqualify them from protein and dairy shelf-life requirements.
- REACH substance restrictions:ECHA's evolving restricted substance list forces reformulation of adhesives, coatings, and inks, extending qualification timelines.
Strategic Opportunities
- India's organized retail expansion:Modern trade penetration in tier-2 and tier-3 cities creates demand for aseptic and modified atmosphere packaging in dairy and beverages.
- Chemical recycling scale-up:Pyrolysis and depolymerization infrastructure investments enable food-grade recycled content qualification for flexible films.
- China GB standard alignment:SAMR's packaging migration limit enforcement opens compliance-advantaged positions for qualified foreign suppliers.
Industry Challenges
- Composting infrastructure gaps:Industrial composting facility scarcity limits end-of-life viability for certified biodegradable packaging, creating consumer confusion and greenwashing exposure.
- Multi-material separation complexity:Laminated flexible structures require specialized recycling streams that most municipal sorting facilities cannot process, undermining circular claims.
- Food contact notification backlogs:FDA's FCN review queue delays novel material approvals, freezing innovation pipelines for barrier coatings and bio-based additives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food and Beverage Packaging Market |
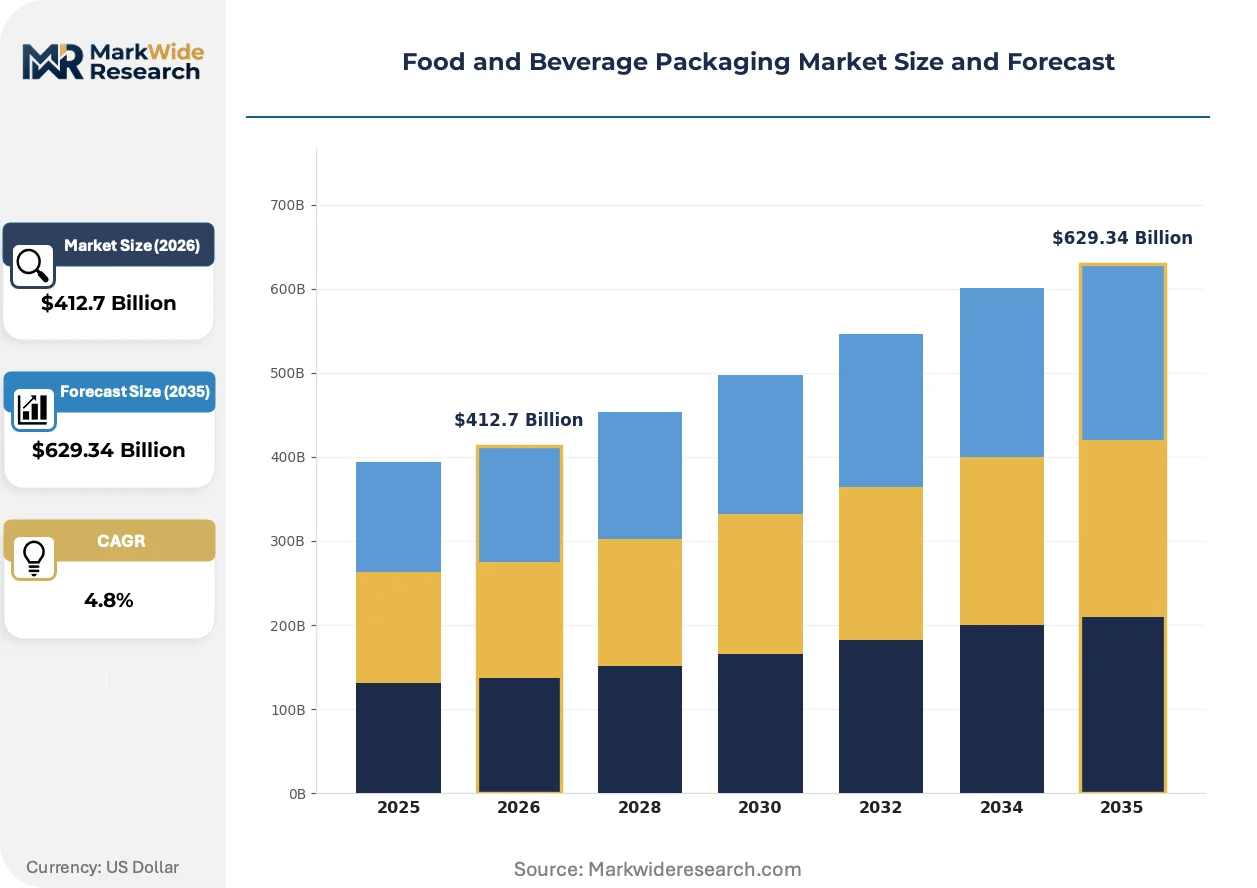
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $629.34 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flexible Packaging, Rigid Packaging, Corrugated Boxes, Pouches Material: Plastic, Glass, Metal, Paper End User: Beverage Manufacturers, Food Processors, Retailers, Catering Services Application: Ready-to-Eat Meals, Soft Drinks, Snacks, Fresh Produce |
| Companies Covered | Amcor plc, Sealed Air, Mondi, Tetra Pak International S.A., Huhtamaki, Berry Global Group, DS Smith, Smurfit Westrock, Graphic Packaging International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food and Beverage Packaging Market Trends and Innovations
Digital traceability layers and active barrier technologies are compressing traditional packaging value chains while regulatory compliance costs reshape competitive economics.
Blockchain-integrated smart labels are digitizing provenance verification and cold-chain monitoring for perishables. Pharmaceutical and premium food exporters adopt these systems fastest to satisfy buyer audit requirements and insurance conditions. The technology is digitizing documentation workflows, reducing dispute resolution costs and enabling parametric insurance products tied to real-time temperature data.
REACH substance restriction expansions are forcing systematic substitution of per- and polyfluoroalkyl substances in grease-resistant food contact materials. ECHA's restriction proposals target fluorinated barriers used in fast-food packaging and microwave popcorn bags. Paperboard converters serving European quick-service restaurant chains face compressed reformulation timelines and performance gaps from silicone and clay-based alternatives.
Direct-store-delivery models are compressing traditional distribution hierarchies in beverage and fresh categories. Branded manufacturers bypass wholesale tiers to capture margin and control shelf presence in convenience and foodservice channels. This rotation is most visible in North American carbonated soft drinks and European chilled juices, where route-to-market optimization now determines packaging format selection.
Food and Beverage Packaging Market Segmentation
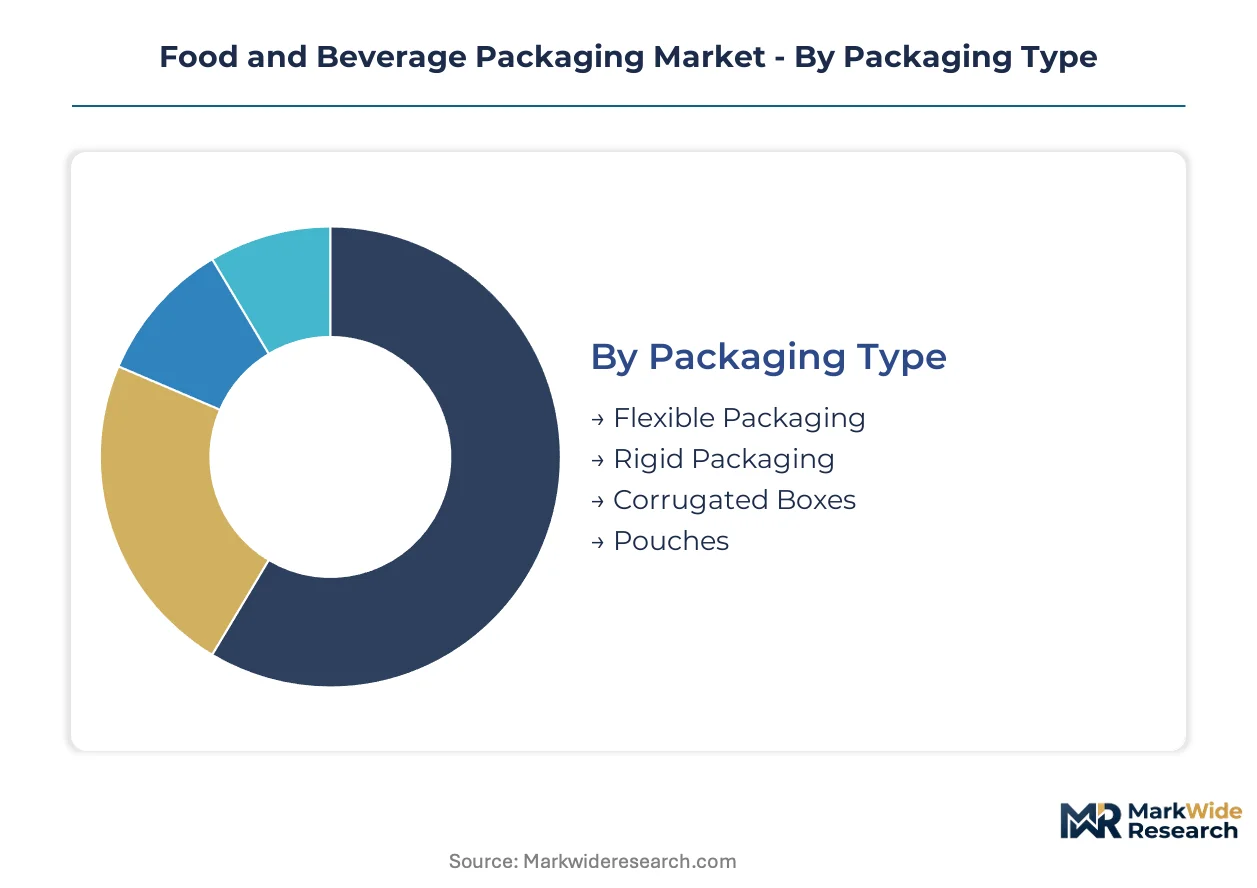
Packaging format selection determines barrier performance, logistics economics, and regulatory compliance trajectories across food and beverage supply chains. Material platforms and end-use specifications create divergent margin structures and capital intensity requirements for converters and brand owners.
Packaging Type:
Use cases span from ambient shelf-stable distribution to chilled last-mile delivery, with format choice driven by product perishability and retail channel requirements.
- Flexible Packaging:Multi-layer polymer films and laminates deliver oxygen and moisture barriers for snacks and frozen foods. German retailers are consolidating procurement around lightweight formats to meet EU Green Deal carbon accounting mandates.
- Rigid Packaging:Injection-molded containers and thermoformed trays provide structural protection for dairy and ready-to-eat meals. Beverage manufacturers in the United States favor PET bottles for their compatibility with existing recycling infrastructure and FDA food contact compliance pathways.
- Corrugated Boxes:Fiber-based secondary packaging dominates ambient grocery distribution.
- Pouches:Stand-up and flat pouch formats reduce material intensity for sauces and beverages.
The dominant share belongs to Flexible Packaging, while Pouches are closing the gap fastest.
Material:
Cost tiers separate commodity substrates from performance-engineered alternatives with specialized barrier certifications.
- Plastic:Polyethylene, polypropylene, and PET resins enable high-throughput conversion at scale. REACH substance restrictions on additives and the EU Green Deal recyclability targets are forcing European converters toward mono-material designs.
- Paper:Kraft and paperboard substrates carry renewable credentials and existing collection infrastructure. Food processors in Germany are accelerating adoption for dry goods and produce to satisfy extended producer responsibility frameworks.
- Glass:Inert barrier properties preserve flavor profiles for premium beverages.
- Metal:Aluminum and steel cans deliver absolute oxygen barriers for shelf-stable applications.
Plastic retains volume leadership, though Paper is expanding most quickly.
End User:
Customer type dictates specification complexity, with direct retail procurement driving standardization while foodservice maintains fragmented customization.
- Beverage Manufacturers:Scale buyers with dedicated packaging engineering teams and long-term supply agreements. Soft drink and bottled water producers in the United States are qualifying chemically recycled PET to meet voluntary sustainability commitments ahead of potential FDA guidance.
- Food Processors:Mid-scale operators balancing shelf-life extension with material cost control. German meat and dairy processors face compressed timelines to substitute fiber-based formats for expanded polystyrene trays under national packaging ordinances.
- Retailers:Private-label packagers and store-brand developers with sustainability scorecard requirements.
- Catering Services:Foodservice distributors with disposable packaging needs and limited reverse logistics.
Beverage Manufacturers command the largest procurement volumes, while Retailers are gaining negotiating leverage fastest.
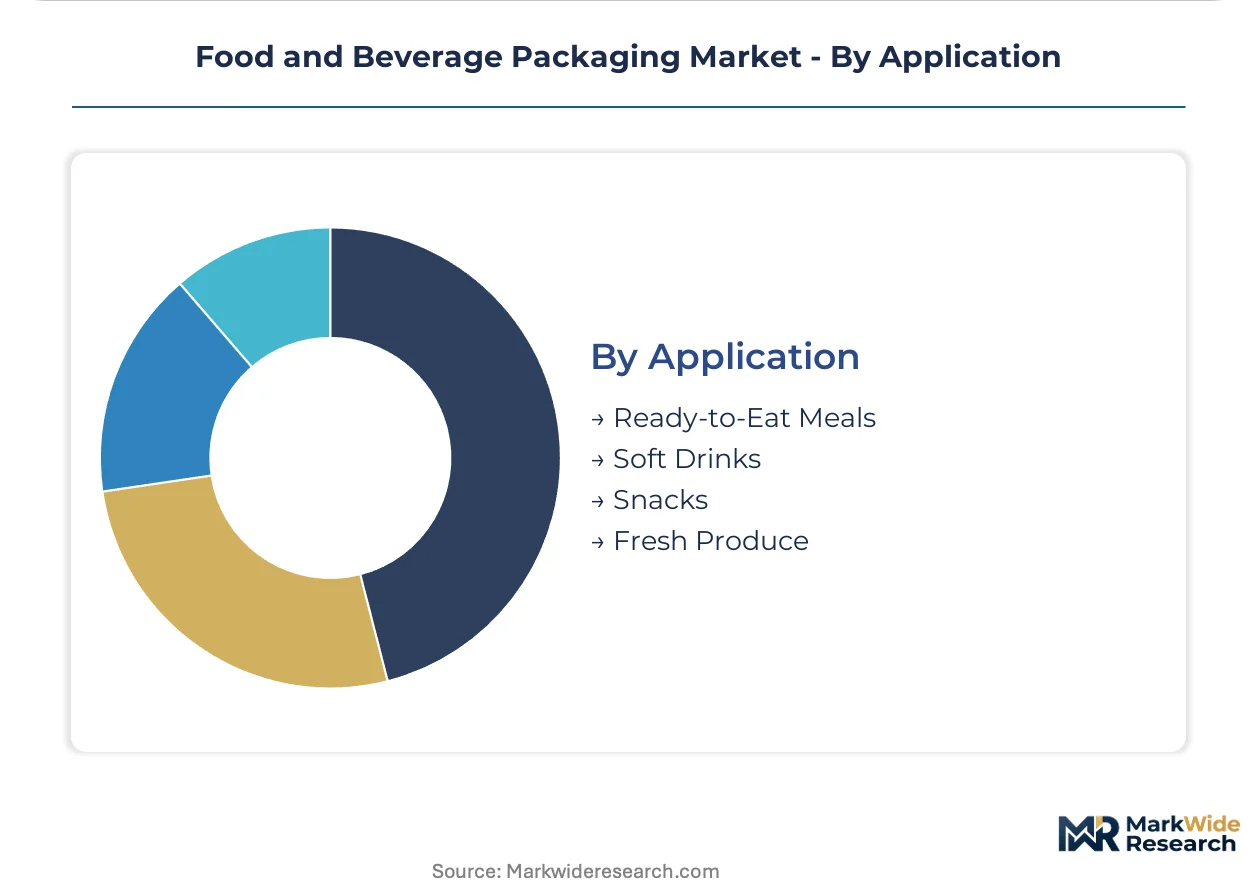
Application:
Application maturity separates established categories with optimized format standards from emerging segments with unresolved barrier-performance tradeoffs.
- Ready-to-Eat Meals:Modified atmosphere and vacuum packaging extend chilled shelf life for prepared foods. European retail chains are requiring QR-enabled traceability layers to satisfy EU Green Deal transparency mandates and reduce food waste liability.
- Soft Drinks:Carbonated and still beverage packaging with established PET and aluminum supply chains. Bottlers in Germany are piloting fiber-based bottles for water and juices to preempt regulatory phase-outs of single-use plastics.
- Snacks:Nitrogen-flushed flexible bags with high oxygen barriers for shelf-stable crisps and nuts.
- Fresh Produce:Breathable films and clamshells managing respiration rates for fruits and vegetables.
Soft Drinks anchor material demand, yet Ready-to-Eat Meals show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in food and beverage packaging tilt toward manufacturing hubs with strong converter bases and proximity to raw material sources. Import dependence concentrates in markets lacking integrated pulp or resin production, while export competitiveness clusters where regulatory alignment with EU and US standards enables cross-border supply contracts.
United States
Beverage bottlers and snack manufacturers drive flexible film consumption across the Midwest and Southeast. FDA food contact notification requirements govern barrier coating approvals, creating qualification bottlenecks for novel bio-based additives. The Dallas-Fort Worth corridor hosts major corrugated converting capacity serving retail distribution centers.
Germany
Retail chains and meat processors accelerate fiber-based tray adoption under national packaging ordinances. ECHA REACH substance restrictions force systematic substitution of fluorinated grease barriers in quick-service packaging. The Rhine-Ruhr industrial belt concentrates paperboard converting for European dairy and ready-meal exports.
China
Domestic dairy and beverage producers expand aseptic carton demand as cold-chain infrastructure penetrates tier-2 cities. SAMR enforces GB standards for packaging migration limits that condition market access for imported materials. The Yangtze River Delta anchors flexible film manufacturing for Asian processed food exports.
India
Modern trade expansion in tier-2 and tier-3 cities creates demand for modified atmosphere packaging in dairy and spices. FSSAI notification requirements for food contact materials extend qualification timelines for imported substrates. Gujarat and Maharashtra host emerging converting clusters serving domestic FMCG brands.
Brazil
Protein exporters and juice processors drive barrier film consumption for chilled distribution to domestic and European markets. ANVISA food contact regulations align with Mercosur technical standards, enabling regional supply integration. São Paulo state concentrates flexible packaging conversion for South American foodservice chains.
Food and Beverage Packaging Market Competitive Landscape
On the supply side, the industry is consolidating around integrated material producers with captive pulp or resin operations and global converting footprints. Tier-one players combine high-barrier technology portfolios with recycling infrastructure investments, while mid-scale specialists compete on regional responsiveness and custom format flexibility. Strategic archetypes separate integrated multinationals, regional converters with material science depth, and private-label fabricators with retail-direct relationships. Capacity expansion and M&A activity dominate competitive moves as firms acquire recycling assets and qualifying alternative material platforms ahead of regulatory phase-outs.
Within the integrated multinational tier, Amcor plc and Tetra Pak International S.A. exemplify scale-driven positioning through global manufacturing footprints and aseptic technology leadership respectively. Mondi occupies a position bridging integrated pulp-to-paperboard control with European sustainability compliance. Among flexible packaging specialists, Sealed Air and Berry Global Group sit within the barrier technology tier, while DS Smith and Smurfit Westrock represent corrugated consolidation plays with retail supply chain integration. Huhtamaki and Graphic Packaging International anchor the fiber-based foodservice and folding carton segments where regulatory tailwinds favor material transitions.
| Leading Market Players |
|---|
| Amcor plc |
| Sealed Air |
| Mondi |
| Tetra Pak International S.A. |
| Huhtamaki |
| Berry Global Group |
| DS Smith |
| Smurfit Westrock |
| Graphic Packaging International |
| Others |
Pricing and Supply Chain Analysis
Converter overcapacity in Southeast Asian flexible film manufacturing compresses margin capture across commodity resin-based formats, forcing suppliers toward specialty barrier grades and long-term offtake contracts with multinational beverage brands to defend pricing power.
Pricing Analysis
Current-generation mono-material polyethylene films trade at a discount to legacy multi-layer laminates, while next-generation bio-based barrier coatings command premiums pending FDA food contact qualification. Contract-based long-term offtake agreements dominate procurement between tier-one beverage manufacturers and resin suppliers, with price differentiation driven by volume scale and EU Green Deal recyclability certification tiers. Cost compression in standard flexible formats is intensifying because of fossil-based polymer feedstock volatility. Private-label retailers exhibit highest price sensitivity, while premium beverage brands with sustainability scorecards accept material premiums for certified fiber-based alternatives.
Supply Chain Analysis
Upstream feedstock concentration centers on Saudi Arabia, South Korea, and the United States for virgin polyethylene and polypropylene resins, with European converters increasingly sourcing from regional chemical recycling facilities. Pulp-to-paperboard supply draws from Scandinavian and Brazilian forestry operations, while specialty barrier coatings hinge on Japanese and German chemical producers. Single-source vulnerability persists in high-purity food-grade resin grades subject to REACH substance restrictions. Distribution runs through converter-direct relationships with beverage bottlers and food processors, bypassing traditional wholesale tiers in direct-store-delivery channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in integrated pulp-to-barrier-coating capabilities constrains European converters attempting fiber-based transitions under compressed EU Green Deal timelines, amplifying returns for asset owners with captive material science pipelines.
For Market Incumbents: Entrench market position through backward integration into chemical recycling assets and capacity expansion in Germany to serve retail chain procurement consolidation. Prioritize ECHA REACH pre-qualification programs for next-generation grease-resistant coatings before fluorinated substance phase-outs disrupt quick-service restaurant supply contracts. Channel control through exclusive direct-store-delivery agreements with beverage bottlers limits private-label encroachment. For New Entrants and Emerging Players: India's tier-2 and tier-3 modern trade penetration offers the most penetrable geographic entry point, with FSSAI notification requirements creating compliance moats against unqualified imports. Target modified atmosphere packaging for dairy and spice processors lacking domestic converter relationships. Pursue joint-venture structures with established FMCG brands to bypass extended qualification timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among converters with multi-year supply agreements tied to EU Green Deal compliance deadlines, offering visibility through regulatory transition periods. Long-term viability favors asset-light specialists with proprietary barrier coating intellectual property over capital-intensive resin producers exposed to feedstock volatility. Monitor ECHA restricted substance list expansion announcements as inflection indicators for forced material substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Scale-Up | Pyrolysis infrastructure investments enable FDA food-grade recycled content qualification for flexible films. |
| Backward Integration into Pulp Supply | Captive forestry operations insulate paperboard converters from Nordic supply tightness and carbon accounting penalties. |
| Smart Packaging Platform Launch | QR-enabled traceability layers satisfy EU Green Deal transparency mandates while capturing retail data monetization. |
| Long-Term Supply Agreement | Multi-year offtake contracts with German retail chains lock in volume ahead of fiber-based tray procurement consolidation. |
| Regulatory Pre-Qualification Investment | Early REACH substance substitution programs secure quick-service restaurant relationships before fluorinated barrier phase-outs. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with packaging procurement directors at beverage manufacturers, sustainability officers at retail chains, and technical directors at flexible film converters; and secondary validation against FDA food contact substance notifications, ECHA REACH restriction proposals, EU trade customs data, and SEC filings from listed packaging producers. Bottom-up triangulation across converter capacity announcements and top-down demand modeling from food processor production data anchored volume estimates.
Forecast inputs include resin price trajectory assumptions, EU Green Deal implementation pace across member states, and penetration rates for chemical recycling infrastructure. Segmentation dimensions span packaging format, material substrate, end-user archetype, and application shelf-life requirements. CAGRs derive from regression analysis of historical volume elasticities against GDP and food processing output, cross-referenced with regulatory deadline impacts on forced material substitution.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated pulp-to-paperboard specialists or petrochemical-backed recycling ventures would shift outcomes beyond modeled ranges. Cross-checking against EU Packaging and Packaging Waste Directive enforcement variance and SAMR GB standard alignment progress is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Honey Packaging Market
Food Packaging
PCR Packaging for Food and Beverages Applications Market
Food Packaging
North America Frozen Food Packaging Market
Food Packaging
Latin America Canned Food Packaging Market
Food Packaging
Chilled Food Packaging Market
Food Packaging
Egg Cartons Market
Food Packaging
Pet Food Packaging Market
Food Packaging
Burger Boxes Market
Food Packaging
Lightweight Food Container Market
Food Packaging
Fresh Food Packaging Market
Food Packaging
Spreads and Toppings Packaging Market
Food Packaging
Hot-Fill Food Packaging Market
Food Packaging
North America PET Food Packaging Market
Food Packaging
Ambient Food Products Packaging Market
Food Packaging
On the Go Food Packaging Market
Food Packaging
Wooden Cutlery Market