
 United States Commercial Dishwasher Market | 2026-2036
United States Commercial Dishwasher Market Size, Share, and Industry Trends Forecast 2026-2036
United States Commercial Dishwasher Market Analytics
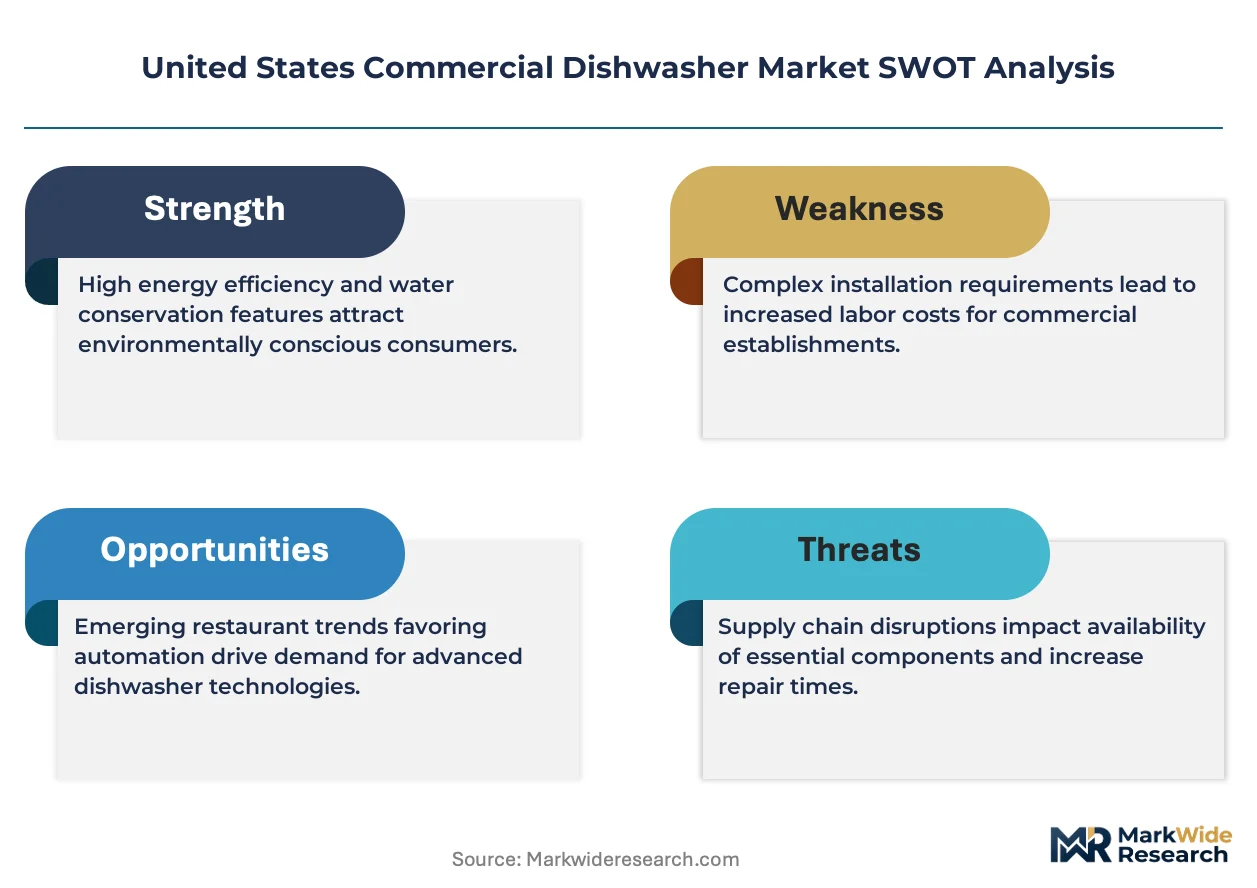
A shortage of certified commercial kitchen technicians is redrawing equipment procurement priorities across the foodservice sector. Hobart leverages its domestic manufacturing footprint to sustain shorter lead times for institutional buyers. Jackson WWS anchors its position through specialized conveyor systems for high-volume operations. Ecolab competes by bundling warewashing chemistry with equipment leases, tightening customer lock-in.
United States Commercial Dishwasher equipment encompasses stationary and conveyor-based machines engineered to sanitize foodservice utensils through high-temperature wash cycles exceeding 180°F or chemical sanitizing agents, typically constructed from 300-series stainless steel to withstand continuous alkaline detergent exposure. The primary commercial purpose centers on compliance with FDA Food Code sanitation standards while minimizing labor hours in back-of-house operations. Conveyor systems dominate capital expenditure flows among hotel and cafeteria operators processing thousands of covers daily. Energy Efficient technology commands premium positioning as utility rebate programs tighten payback thresholds for standard models. Chemical Sanitizing configurations occupy niche demand among operations with limited electrical infrastructure or lower throughput requirements.
DOE appliance efficiency standards and EPA WaterSense specifications shape product development roadmaps, forcing redesigns around reduced water consumption per rack. OSHA workplace safety protocols influence operator training and machine guarding specifications across institutional installations. Stakeholders must monitor state-level utility incentive shifts and evolving FDA Food Code amendments to calibrate portfolio and pricing strategies.
Market Dynamics
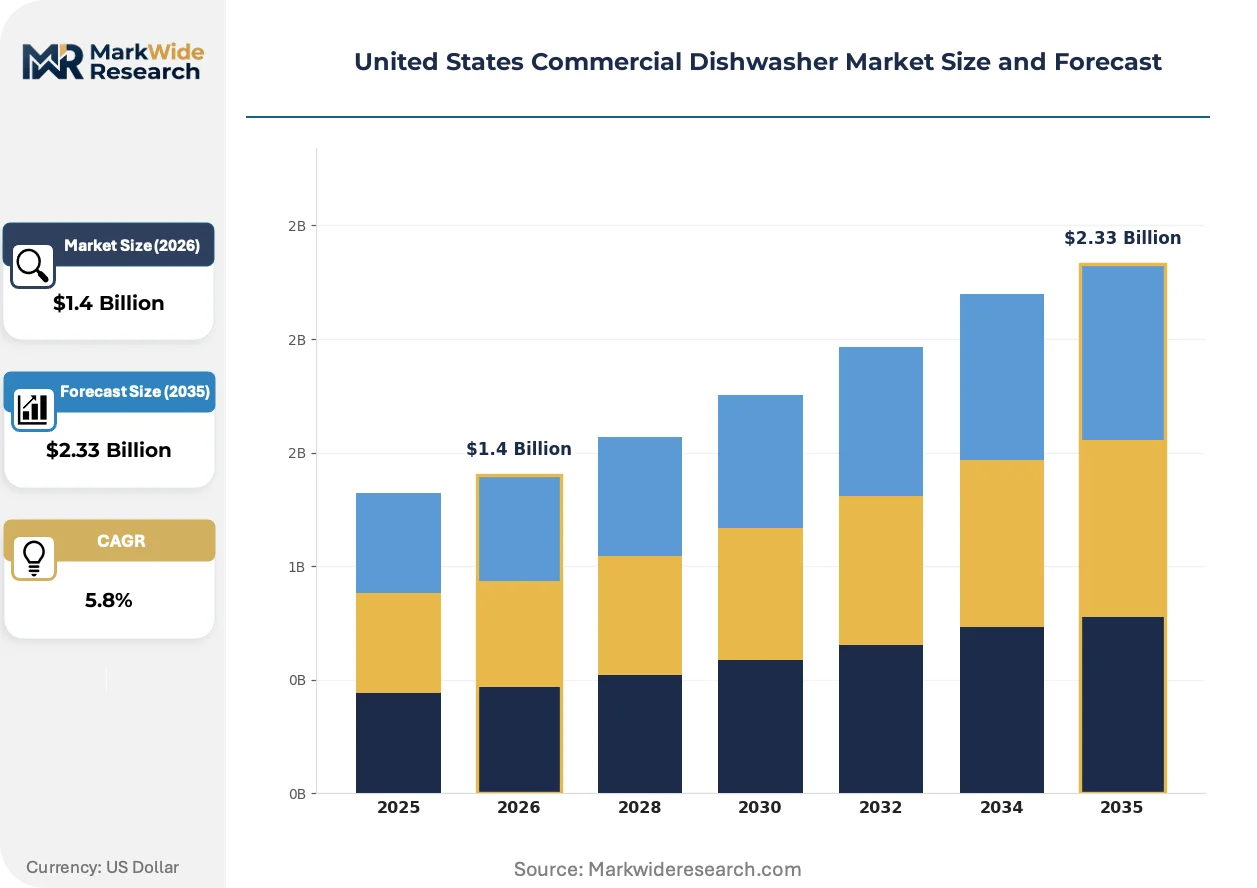
DOE efficiency mandates and EPA WaterSense protocols are compressing equipment refresh cycles across the foodservice sector, forcing operators to retire legacy units ahead of depreciation schedules. This regulatory pressure intersects with a technician shortage that limits installation capacity, creating a supply-constrained transition window.
Growth Catalysts
- California Title 24 building standards:The state's energy code mandates high-efficiency warewashing equipment in new commercial kitchen construction, pulling forward replacement demand in the nation's largest foodservice market.
- Full-service restaurant chains:National operators are standardizing equipment platforms across portfolios to reduce maintenance complexity, concentrating procurement volumes with certified high-temperature system suppliers.
- Heat pump water heating integration:Advanced dishwashers pairing with heat pump infrastructure are capturing utility rebate pools in Texas and Florida where electricity costs drive operational decisions.
Market Restraints
- 300-series stainless steel price volatility:Raw material cost swings for the dominant construction alloy compress margin predictability for domestic fabricators.
- Certified technician concentration:EPA Section 608 and OSHA confined-space credentials are concentrated in legacy manufacturing belts, constraining deployment velocity in Sun Belt growth markets.
- Steam-based alternatives:Central commissary models with off-site warewashing are displacing on-premise installation requirements in multi-unit healthcare and education contracts.
Strategic Opportunities
- Florida hospitality construction pipeline:Orlando and Miami hotel development is outpacing equipment supplier capacity, opening share capture for regional service networks.
- Texas utility incentive stacking:ERCOT territory operators can layer federal IRA commercial credits with municipal water conservation rebates for chemical sanitizing configurations.
- IoT-enabled predictive maintenance:Sensor-integrated machines converging with cloud analytics platforms are creating recurring revenue attachment opportunities beyond equipment sale.
Industry Challenges
- Cross-connection control certification:Backflow prevention assembly testing requirements vary by Texas municipality, complicating standardized installation protocols.
- Legacy electrical infrastructure retrofit:High-temperature units requiring 208V three-phase upgrades face permitting delays in older California urban cores.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Commercial Dishwasher Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Under-Counter, Glasswasher, Conveyor, Flight Type End User: Restaurants, Hotels, Cafeterias, Catering Services Capacity: Small, Medium, Large, Extra Large Technology: Standard, Energy Efficient, High Temperature, Chemical Sanitizing |
| Companies Covered | Champion, Stero, Hobart, Ecolab, Winterhalter, Jackson WWS, Meiko USA, Electrolux Professional, CMA Dishmachines, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Commercial Dishwasher Market Evolving Landscape
Water recovery and heat recapture systems are redefining equipment architecture, moving beyond compliance checkboxes toward operational cost centers. Vendors are embedding intelligence at the rack level, transforming wash data into labor and utility optimization inputs.
Heat pump integration is decomposing the traditional boiler-dependent architecture of high-temperature warewashing. Hotel operators in California are specifying these configurations to capture Title 24 compliance credits without electrical service upgrades. The technology is decomposing the capital equipment stack by eliminating separate water heating infrastructure and compressing mechanical room footprints.
EPA WaterSense specifications are tightening maximum gallons-per-rack thresholds, forcing redesigns of spray arm geometry and pump sequencing. Manufacturers must recalibrate NSF/ANSI 3 certification testing protocols to maintain listing compliance. Full-service restaurant chains procuring at national scale are prioritizing specification sheets that demonstrate margin against both current and proposed WaterSense draft standards.
Equipment-as-a-service contracting is displacing capital purchase models among multi-unit operators seeking to transfer obsolescence risk. National accounts are negotiating bundled chemistry and maintenance agreements that convert dishwasher procurement from balance-sheet capex to operational expenditure. This shift is most visible in Texas and Florida where private-equity-backed restaurant groups are standardizing fleet management approaches across portfolios.
United States Commercial Dishwasher Market Segmentation
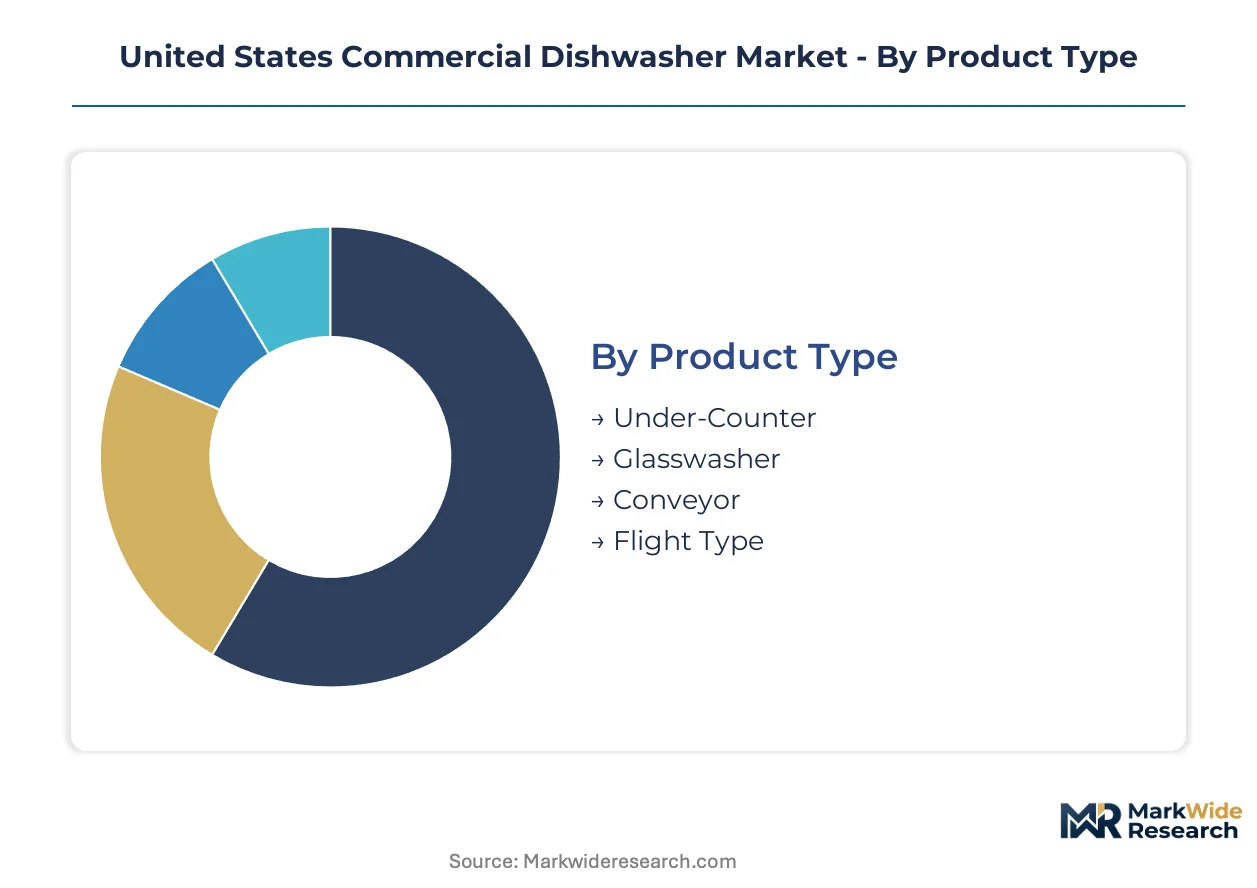
Equipment specification varies sharply across foodservice subsectors, with procurement committees weighing throughput requirements against utility infrastructure constraints. Channel partners route distinct configurations through dealer networks versus direct institutional contracts based on installation complexity and service territory density.
Product Type:
Dealer networks move under-counter and glasswasher units through broadline distributors, while conveyor and flight-type systems flow through factory-direct specification teams serving national accounts.
- Conveyor:Continuous-feed architecture processes 200-400 racks hourly through automated rack conveyance. Hotel and cafeteria operators in Florida and Texas specify these for properties exceeding 500 seats, driven by labor cost pressures and throughput guarantees.
- Under-Counter:Front-loading compact units fit beneath standard work surfaces with 30-40 rack hourly capacity. Independent restaurants in California urban cores favor these where kitchen footprints are constrained by real estate costs and electrical service limitations.
- Glasswasher:Specialized low-temperature wash zones with dedicated rinse agents prevent etching on stemware. Bars and catering operations with high wine service volumes specify these as secondary units alongside primary warewashing.
- Flight Type:Massive continuous-belt systems processing 10,000+ dishes hourly for stadiums and central commissaries. These require dedicated mechanical rooms and three-phase electrical service available only in new construction or heavy renovation projects.
Conveyor systems dominate installed base in high-volume institutional settings. Under-counter configurations are where expansion concentrates among independent operators renovating legacy kitchens.
End User:
Margin profiles diverge across customer type, with national restaurant chains extracting volume discounts while hotels accept premium pricing for integrated service packages.
- Restaurants:Full-service chains standardize equipment platforms across portfolios to compress maintenance training costs and spare parts inventories. QSR operators prioritize compact chemical sanitizing units where speed of service demands rapid dish turnover.
- Hotels:Property improvement plans mandate equipment refreshes on seven-year cycles, with procurement committees specifying heat pump-integrated models to capture Title 24 compliance credits in California properties.
- Cafeterias:Corporate and university foodservice directors process thousands of covers daily during compressed meal windows. These operators specify conveyor configurations with automated soil sorting to minimize labor at the dish return station.
- Catering Services:Mobile and off-premise operators require NSF-certified units on wheels or compact enough for event load-in. Demand concentrates in Texas and Florida where wedding and convention markets support specialized rental fleets.
Restaurants represent the deepest installed base. Hotels are climbing the fastest as property renovation cycles accelerate post-pandemic.
Capacity:
Physical dimensions and utility draw scale non-linearly, with extra-large units requiring dedicated electrical service upgrades that extend sales cycles by 90-120 days.
- Large:Single-chamber door-type machines processing 80-150 racks hourly. Independent restaurants and mid-scale hotels represent the core demand cluster, with procurement decisions driven by peak-period coverage requirements.
- Medium:Compact door-type units serving 40-80 racks hourly. These dominate replacement demand in older California properties where electrical panels cannot support high-amperage upgrades without permitting delays.
- Small:Countertop and under-counter configurations for bars, coffee shops, and food trucks. Texas convenience store chains expanding prepared food offerings are driving specification volume for these units.
- Extra Large:Flight-type and multi-chamber conveyor systems for stadiums, hospitals, and central commissaries. These require factory engineering review of mechanical room layouts and typically ship on 16-20 week lead times.
Medium-capacity units dominate replacement flows. Large configurations are gaining share fastest as independent restaurants expand seating capacity.
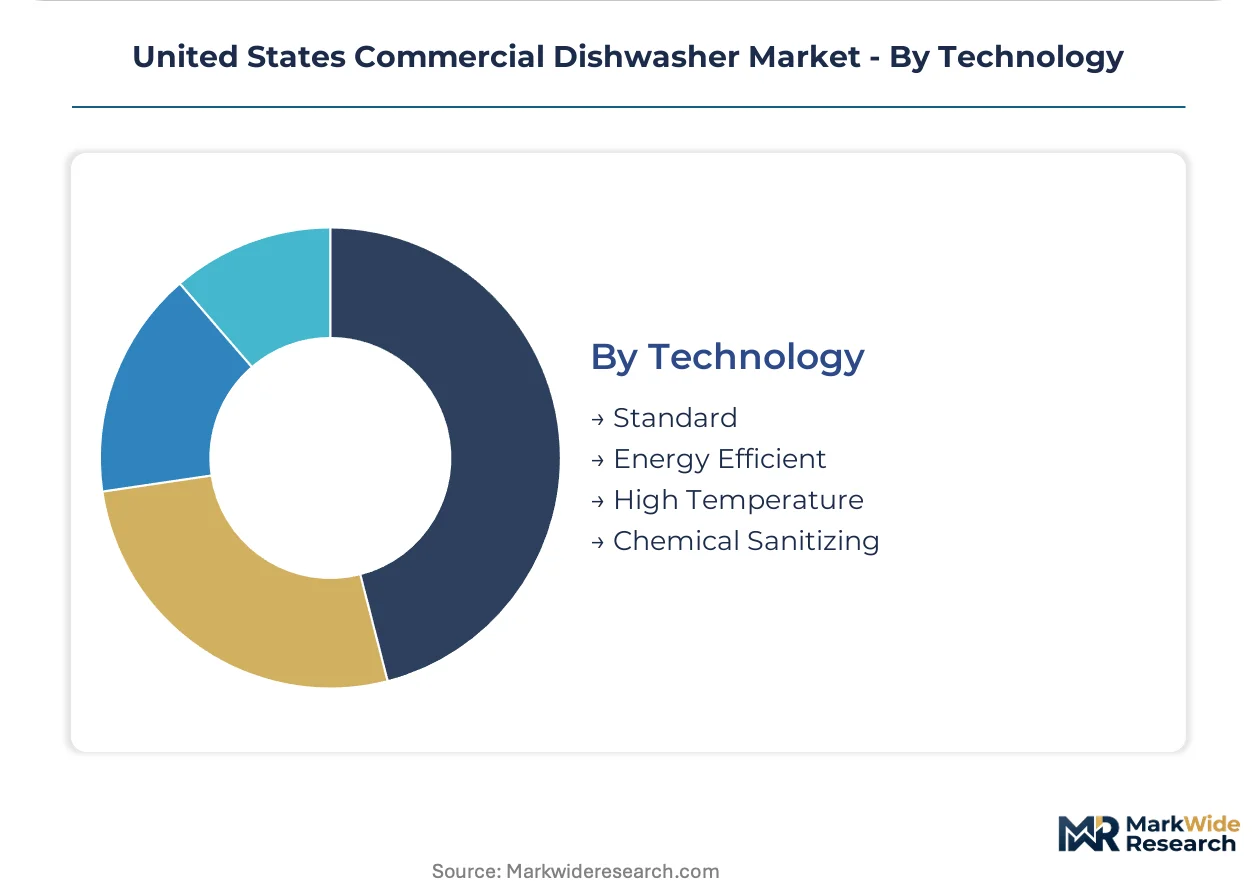
Technology:
Regulatory pressure is fragmenting procurement committees into compliance-focused and cost-focused factions, with specification authority shifting toward facilities managers from culinary directors.
- Energy Efficient:Heat recovery, variable-speed pumps, and reduced water volume per rack. California Title 24 mandates and utility rebate stacking in Texas are accelerating specification of these configurations ahead of federal compliance deadlines.
- High Temperature:Final rinse cycles exceeding 180°F eliminate chemical sanitizer costs but require 208V three-phase electrical service. Hotel operators in Florida specify these to avoid chemical storage and handling training burdens.
- Chemical Sanitizing:Low-temperature final rinse with EPA-registered sanitizing agents. Operations with limited electrical infrastructure or lower throughput requirements favor these, particularly in older urban cores where service upgrades face permitting friction.
- Standard:Baseline configurations meeting minimum NSF/ANSI 3 requirements without heat recovery or advanced controls. These retain share in price-sensitive independent restaurant segments and temporary installations.
High-temperature systems dominate legacy installed base. Energy efficient configurations are expanding most quickly as rebate programs compress payback periods below 36 months.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment deployment patterns diverge sharply across US states, with California operators prioritizing energy compliance while Texas and Florida buyers chase throughput economics in high-volume hospitality corridors.
California
Hotel renovation cycles and Title 24 building standards are accelerating specification of heat pump-integrated warewashing systems. The California Energy Commission mandates high-efficiency equipment in new commercial kitchen construction, compressing payback thresholds for premium configurations. Los Angeles and San Francisco hospitality clusters are retrofitting legacy electrical infrastructure to support 208V three-phase high-temperature installations.
Texas
ERCOT territory operators exploit layered utility incentives combining federal IRA commercial credits with municipal water conservation rebates. The Public Utility Commission of Texas oversees rebate program administration across deregulated electricity markets. Dallas-Fort Worth and Houston restaurant groups are standardizing chemical sanitizing configurations to avoid electrical service upgrade delays in suburban expansion zones.
Florida
Orlando and Miami hotel development pipelines are outpacing certified installation capacity, extending equipment lead times by 8-12 weeks. The Florida Building Code incorporates ASHRAE efficiency standards that elevate baseline specification requirements. South Florida catering operators are deploying mobile NSF-certified units for convention and wedding market density.
Midwest
Illinois and Ohio institutional foodservice directors are refreshing aging conveyor systems in K-12 and university cafeterias. The Environmental Protection Agency's WaterSense specifications influence procurement committee evaluation criteria across Great Lakes manufacturing belts. Chicago corporate dining contracts are specifying automated soil sorting to minimize labor at dish return stations.
Southeast
Georgia and North Carolina full-service restaurant chains are consolidating equipment platforms across portfolios to reduce maintenance training costs. OSHA workplace safety protocols govern operator certification requirements in states with active manufacturing employment. Atlanta hospitality construction is absorbing regional inventory of medium-capacity door-type machines for independent operator renovations.
United States Commercial Dishwasher Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with domestic manufacturing footprints conferring lead-time advantages in supply-constrained installation windows. The market structure reflects procurement committee preferences for bundled service contracts over equipment-only transactions. Two strategic archetypes dominate: chemistry-integrated platform providers and conveyor-system specialists. Competitive moves center on factory-direct specification teams for national accounts and regional service network density for hospitality construction pipelines.
Among domestic fabricators, Hobart and Jackson WWS anchor the integrated tier, with Ecolab representing the chemistry-integrated archetype through bundled warewashing programs. Hobart exemplifies the manufacturer maintaining captive production capacity to sustain institutional delivery schedules. Jackson WWS occupies a position within the high-volume conveyor specialization segment. Ecolab sits within the recurring-revenue model that converts capital expenditure into operational expenditure for multi-unit operators.
| Leading Market Players |
|---|
| Champion |
| Stero |
| Hobart |
| Ecolab |
| Winterhalter |
| Jackson WWS |
| Meiko USA |
| Electrolux Professional |
| CMA Dishmachines |
| Others |
Value Network & Pricing Analysis
Equipment-as-a-service contracting locks in multi-year revenue streams for domestic fabricators while insulating operators from 300-series stainless steel price volatility. This structure transfers obsolescence risk to vendors and compresses upfront capital requirements for private-equity-backed restaurant groups standardizing fleet management.
Pricing Analysis
Long-term lease arrangements with bundled chemistry and maintenance dominate procurement among multi-unit operators. Price differentiation rests on NSF/ANSI 3 certification tier and heat pump integration capability. Cost compression in standard configurations is intensifying because commodity-grade units face utility rebate disqualification. Independent restaurants in California urban cores exhibit highest price sensitivity, while hotel property improvement plans accept premium positioning for Title 24 compliance credits.
Supply Chain Analysis
Domestic manufacturing in Ohio and Wisconsin anchors conveyor system fabrication for institutional buyers. Production draws from 300-series stainless steel mills in Pennsylvania and Indiana, with pump and control components sourced from Illinois and Michigan. Single-source vulnerability concentrates in specialized heat exchanger assemblies. Distribution runs through factory-direct specification teams for national accounts and broadline dealer networks for independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across California Title 24, Texas ERCOT incentive structures, and Florida Building Code variants is creating specialized procurement niches. Equipment vendors must calibrate regional service density against compliance complexity.
For Market Incumbents: Compound regional service network density in Florida hospitality corridors where installation capacity lags construction pipelines. Deepen captive production of heat pump-integrated architectures to capture California Title 24 mandates before federal standards tighten. Certification investment in EPA WaterSense pre-compliance testing protocols defends margin position against commodity-grade imports. For New Entrants and Emerging Players: NSF/ANSI 3 certification fast-track through third-party testing laboratories opens entry into Texas convenience store prepared-food expansion. Target medium-capacity door-type replacement demand in older California properties where electrical upgrade permitting delays strand legacy units. Go-to-market through regional equipment rental fleets serving Florida catering operators addresses mobile NSF-certified unit shortages. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among chemistry-integrated platform providers bundling warewashing programs. Long-term viability over the coming decade favors acquisition targets with IoT-enabled predictive maintenance architectures converting equipment sales to subscription attach rates. Monitor state-level utility incentive stacking complexity as inflection indicator for vendor consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Integration Development | Captures California Title 24 compliance credits and ERCOT rebate pools simultaneously. |
| IoT Predictive Maintenance Platform Launch | Converts capital equipment transactions into recurring software revenue streams. |
| Regional Service Network Expansion | Addresses Florida installation capacity constraints extending equipment lead times. |
| NSF/ANSI 3 Pre-Compliance Certification | Anticipates EPA WaterSense threshold tightening ahead of competitor redesign cycles. |
| Chemistry-Equipment Bundle Standardization | Locks multi-unit operators into operational expenditure models reducing churn. |
Research Methodology
Operator-level perspectives from foodservice directors, facilities managers, and commercial kitchen maintenance technicians anchored the qualitative base. Primary interviews with broadline distributor procurement leads and factory-direct specification teams validated equipment flow patterns. Secondary sources incorporated DOE appliance efficiency filings, EPA WaterSense protocol drafts, California Energy Commission Title 24 documentation, and SEC 10-K disclosures from publicly traded foodservice equipment manufacturers. Bottom-up rack-hour demand estimates triangulated against top-down hospitality construction pipeline data.
Sensitivity analysis tested forecast outputs against alternative regulatory compliance timelines and stainless steel price trajectory scenarios. Segmentation modeling spanned product type, end-user vertical, capacity tier, and technology configuration across the projection horizon. CAGR derivation incorporated equipment refresh cycle compression from efficiency mandate acceleration and technician shortage constraints on installation velocity.
Underlying assumptions cover DOE standard implementation schedules and utility rebate program continuity, with deviation risk concentrated in state-level building code amendment timing and certified technician training pipeline expansion. Recalibration cycles align with material shifts in EPA WaterSense draft standard finalization and federal infrastructure credit administration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Commercial Catering Equipment Market
Food Service Equipment
Commercial Refrigerator Market
Food Service Equipment
Commercial Food Warming and Holding Equipment Market
Food Service Equipment
France Smokeless Indoor Grills Market
Food Service Equipment
North America Fountain Dispenser Equipment Market
Food Service Equipment
Global Glass Door Cooler Market
Food Service Equipment
Hospital Foodservice Equipment Market
Food Service Equipment
Draught Beer Chiller Market
Food Service Equipment
Catering Equipment Market
Food Service Equipment
Refrigerated Counter Market
Food Service Equipment
Europe Commercial Dishwashers Market
Food Service Equipment
North America Commercial Dishwashers Market
Food Service Equipment
Coffee Equipment and Supplies Market
Food Service Equipment
Cooking Hood Market
Food Service Equipment
Commercial Rotisserie Equipment Market
Food Service Equipment
Commercial Stainless Steel Cooking Equipment Market