
 North America Commercial Dishwashers Market | 2026-2036
North America Commercial Dishwashers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Commercial Dishwashers Market Analytics
Modular rack-to-conveyor upgrade paths is broadening buyer choice across mid-scale foodservice operators. Hobart leverages its integrated chemical dispensing and service network to lock in multi-site accounts. Jackson WWS anchors its position through durable stainless construction and domestic manufacturing scale. CMA Dishmachines competes on compact footprints tailored for independent restaurants with space constraints.
Commercial dishwashers are industrial warewashing machines engineered to sanitize foodservice equipment using sustained high-temperature water jets, typically operating at 150–180°F with 1–2 minute cycle times to meet health code requirements. Door-type and conveyor configurations dominate installed capacity, while smart controls and water recycling technology segments capture expanding margin pools as operators face escalating utility tariffs and labor costs. Rack-type units retain share in institutional cafeterias and hospitals where throughput predictability outweighs flexibility demands.
The U.S. Department of Energy sets minimum efficiency thresholds under commercial kitchen equipment standards, while the EPA's WaterSense program and OSHA sanitation guidelines shape product design and facility compliance burdens. Canada's Natural Resources Office and provincial health authorities impose parallel certification requirements that vendors must navigate for cross-border sales. Stakeholders should monitor state-level building electrification mandates and utility rebate programs that will tilt procurement toward heat-pump and energy-recovery models.
Market Dynamics
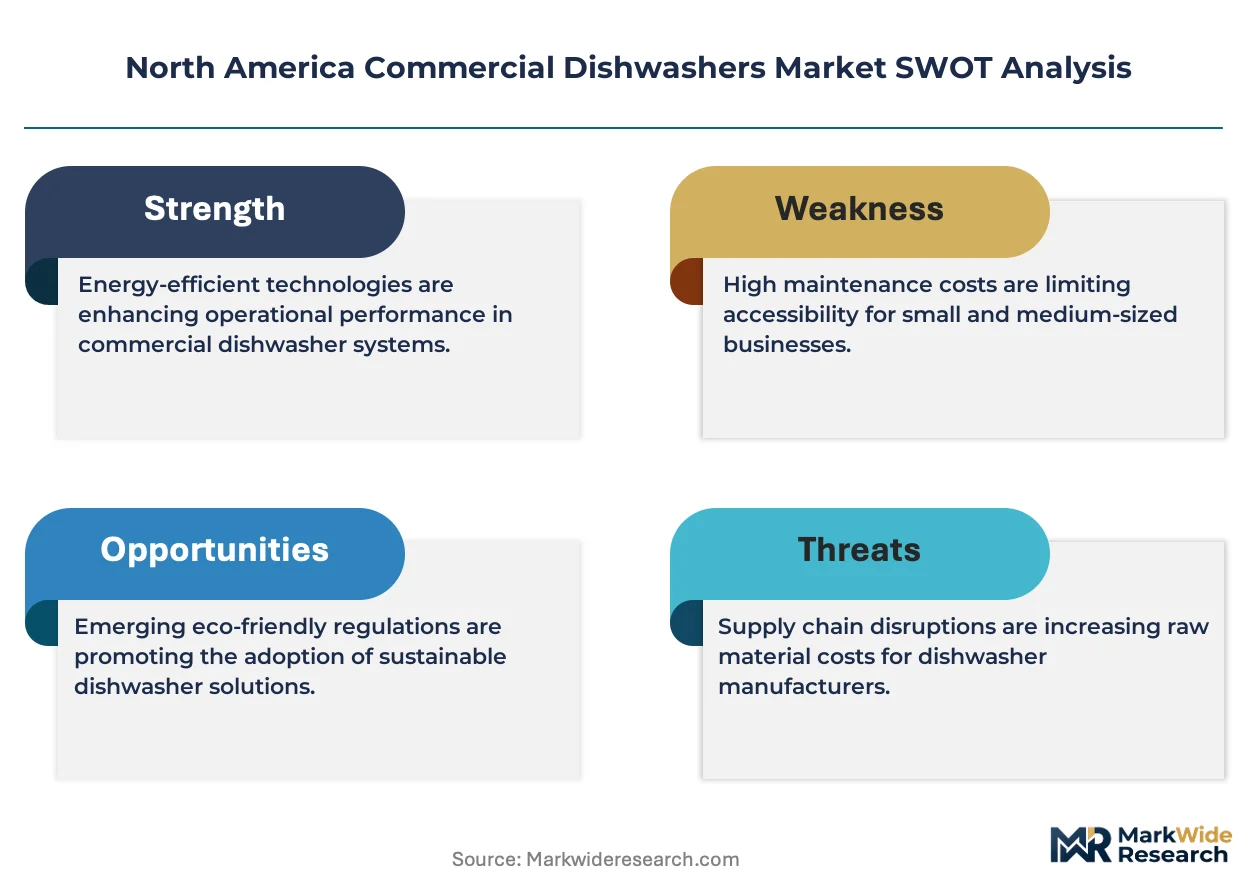
The U.S. Department of Energy's efficiency mandates are compressing product lifecycles and forcing OEMs to redesign thermal systems around heat-recovery architectures, reshaping competitive advantage toward engineering depth rather than scale economies alone.
Growth Catalysts
- Sun Belt hospitality construction:Foodservice density in Texas, Florida, and Arizona outpaces national averages, pulling conveyor-system installations into new hotel and casino developments.
- OSHA sanitation guidelines:Stricter documentation requirements for high-temperature sanitization cycles are accelerating replacement demand among institutional foodservice operators.
- Heat-recovery technology:Captured exhaust thermal energy is cutting water heating costs by double-digit percentages, shortening payback periods for premium equipment tiers.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 price swings compress margin predictability for domestic manufacturers reliant on North American mill supply.
- Cross-border certification friction:Canada's Natural Resources Office imposes parallel efficiency testing protocols that extend time-to-market for U.S.-based OEMs by 4-6 months.
- Manual warewashing substitution:Low-wage labor availability in certain secondary markets delays automation adoption among independent operators with under 50 seats.
Strategic Opportunities
- Mexican foodservice expansion:Quick-service chain growth in Monterrey and Guadalajara creates demand for compact rack-type units with voltage compatibility for 127V infrastructure.
- State electrification mandates:California's building decarbonization rules and New York's utility rebate programs are tilting procurement toward heat-pump dishwashers with energy-recovery loops.
- Smart control convergence:IoT-enabled cycle optimization and predictive maintenance alerts are opening subscription revenue streams alongside hardware sales.
Industry Challenges
- Field service technician scarcity:Specialized knowledge of high-voltage heating elements and chemical dosing calibration limits OEMs' ability to maintain response-time commitments across dispersed multi-site accounts.
- Legacy water infrastructure incompatibility:Older buildings in the U.S. Northeast often lack sufficient electrical capacity and water pressure for modern low-water, high-temperature systems, forcing costly site modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Commercial Dishwashers Market |
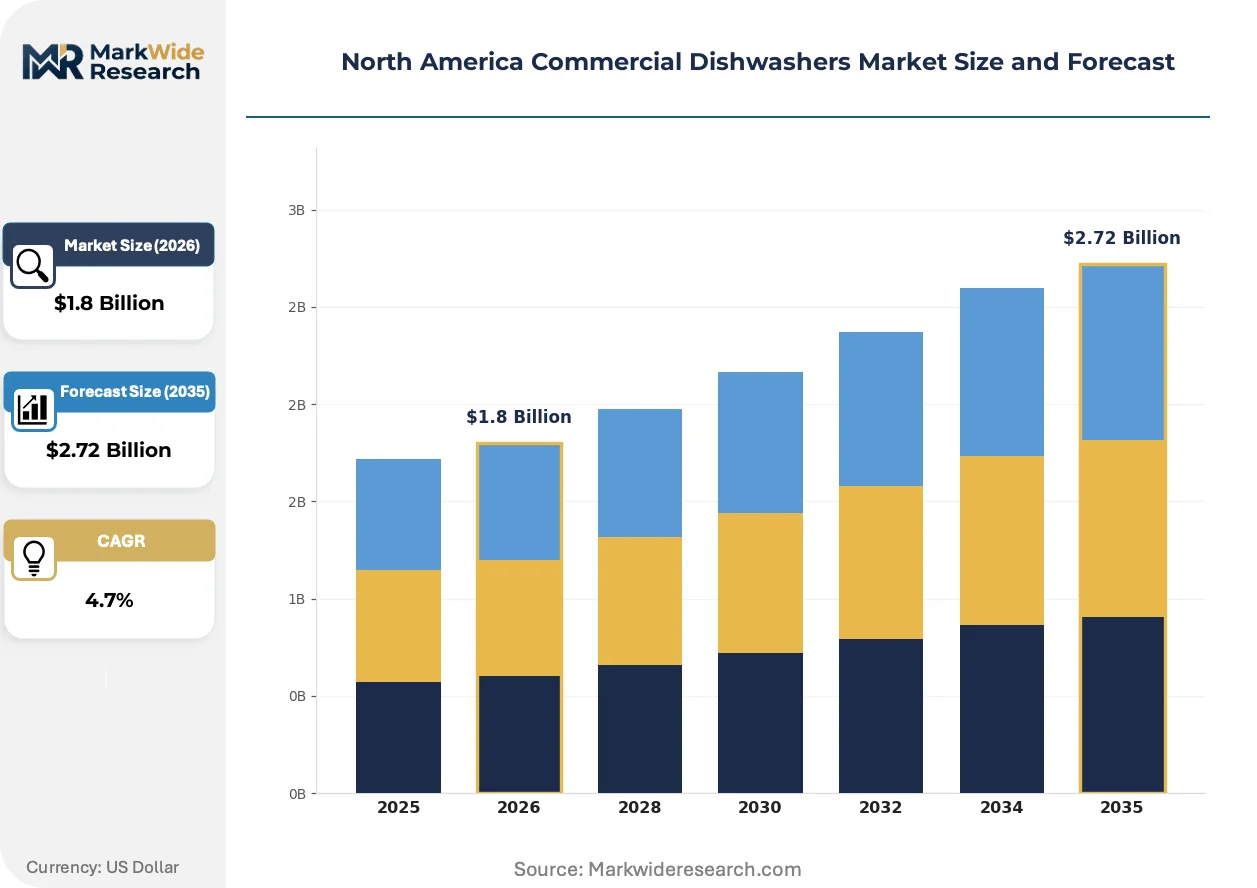
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Undercounter, Door-Type, Conveyor, Rack-Type End User: Restaurants, Hotels, Cafeterias, Hospitals Technology: Warewashing, Water Recycling, Energy Efficient, Smart Controls Installation: Stand-Alone, Built-In, Mobile, Custom Units |
| Companies Covered | Hobart, Jackson WWS, CMA Dishmachines, Champion Industries, Meiko USA, Insinger Machine Company, Sterling (Unified Brands), Electrolux Professional, Winterhalter, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Commercial Dishwashers Market Evolving Landscape
Water recycling technology is decentralizing operational control away from centralized utility dependence, while regulatory pressure on embodied carbon intensifies material selection criteria across the supply base.
Closed-loop water filtration is decentralizing wastewater management for high-volume operators. Casino and hospital foodservice directors are specifying these systems to reduce sewer discharge volumes and evade municipal surcharge penalties. This technology is decentralizing the traditional relationship between throughput capacity and municipal infrastructure constraints, enabling kitchen relocation to secondary locations previously disqualified by utility limitations.
The EPA's WaterSense program is tightening certification thresholds for commercial kitchen equipment. Manufacturers must now document gallons-per-rack performance under standardized soil-loading conditions to qualify for federal procurement preference. Full-service restaurant chains with sustainability mandates are filtering vendor lists to WaterSense-labeled products, compressing competitive sets for institutional contracts.
Equipment-as-a-service contracts are displacing capital purchase models among mid-scale regional operators. Third-party finance entities now bundle installation, chemicals, and maintenance into per-rack fees, transferring residual value risk from operator to vendor. This model is gaining traction fastest in the U.S. Southeast, where private equity-backed restaurant groups prioritize balance-sheet flexibility over ownership.
North America Commercial Dishwashers Market Segmentation
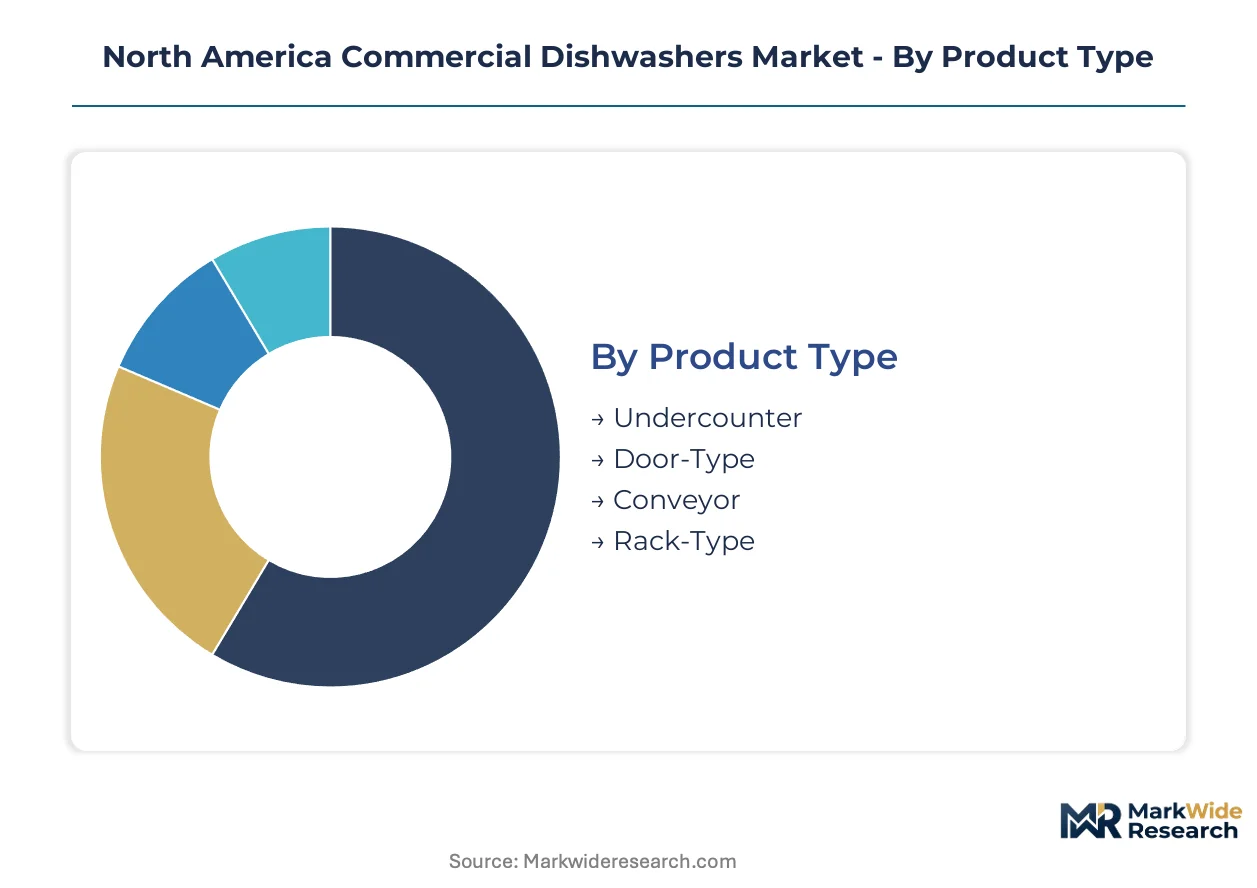
Commercial dishwasher procurement patterns diverge sharply across operator scale and facility constraints. Segmentation reveals how equipment specifications align with throughput demands, labor availability, and utility infrastructure across the United States, Canada, and Mexico.
Product Type:
Thermal system architecture and footprint geometry define competitive positioning across installation environments.
- Undercounter:Compact units integrate directly beneath stainless prep surfaces, typically processing 20-30 racks hourly through single-tank operation. Independent restaurants in dense urban cores—Manhattan, San Francisco, Chicago—specify these for kitchens under 800 square feet where floor space commands premium lease rates.
- Door-Type:Vertical-opening hood designs accommodate 60-120 racks hourly with separate wash and rinse chambers. Full-service restaurant chains across the U.S. Sun Belt deploy these as baseline automation, driven by OSHA documentation requirements for high-temperature sanitization cycles.
- Conveyor:Continuous-belt systems process 200+ racks hourly through multi-stage washing, rinsing, and drying zones. Casino and hospital foodservice directors in Las Vegas, Orlando, and Houston specify these for 24-hour operations where throughput predictability outweighs capital intensity.
- Rack-Type:Single-rack batch units with dedicated wash arms serve institutional cafeterias and K-12 school districts where meal-time surge patterns dominate operational planning.
Door-type leads on scale; conveyor leads on momentum.
End User:
Volume concentration and regulatory exposure shape equipment specification intensity across operator categories.
- Restaurants:Full-service and limited-service operators generate the dominant share of replacement demand, with quick-service chains in Texas and Florida driving conveyor-system installations. Labor cost pressure and health department inspection frequency accelerate upgrade cycles.
- Hotels:Property-level foodservice directors balance banquet capacity against breakfast service demands, often specifying modular rack-to-conveyor upgrade paths. Resort developments in Arizona and Mexican coastal markets pull premium equipment with heat-recovery architecture.
- Cafeterias:Institutional feeding operations in U.S. federal buildings and Canadian provincial facilities require WaterSense-labeled products for procurement compliance, compressing vendor qualification lists.
- Hospitals:Healthcare foodservice directors face Joint Commission sanitation documentation requirements, specifying closed-loop water filtration to evade municipal sewer surcharge penalties.
Restaurants lead on scale; hospitals lead on momentum.
Technology:
Regulatory pressure and utility tariff structures are redefining value capture away from mechanical durability toward thermal efficiency.
- Warewashing:Conventional high-temperature sanitization using 150-180°F water jets remains the installed base majority, though U.S. Department of Energy efficiency mandates compress product lifecycles.
- Water Recycling:Closed-loop filtration systems reduce sewer discharge volumes by 40-60%, enabling kitchen relocation to secondary locations previously disqualified by municipal infrastructure constraints. Casino operators in water-stressed Southwestern markets specify these most aggressively.
- Energy Efficient:Heat-recovery architectures capturing exhaust thermal energy cut water heating costs by double-digit percentages, shortening payback periods for premium equipment tiers in California and New York markets with electrification mandates.
- Smart Controls:IoT-enabled cycle optimization and predictive maintenance alerts open subscription revenue streams alongside hardware sales, gaining traction fastest among private equity-backed restaurant groups prioritizing balance-sheet flexibility.
Warewashing leads on scale; smart controls lead on momentum.
Installation:
Site modification requirements and mobility demands create distinct procurement workflows across facility types.
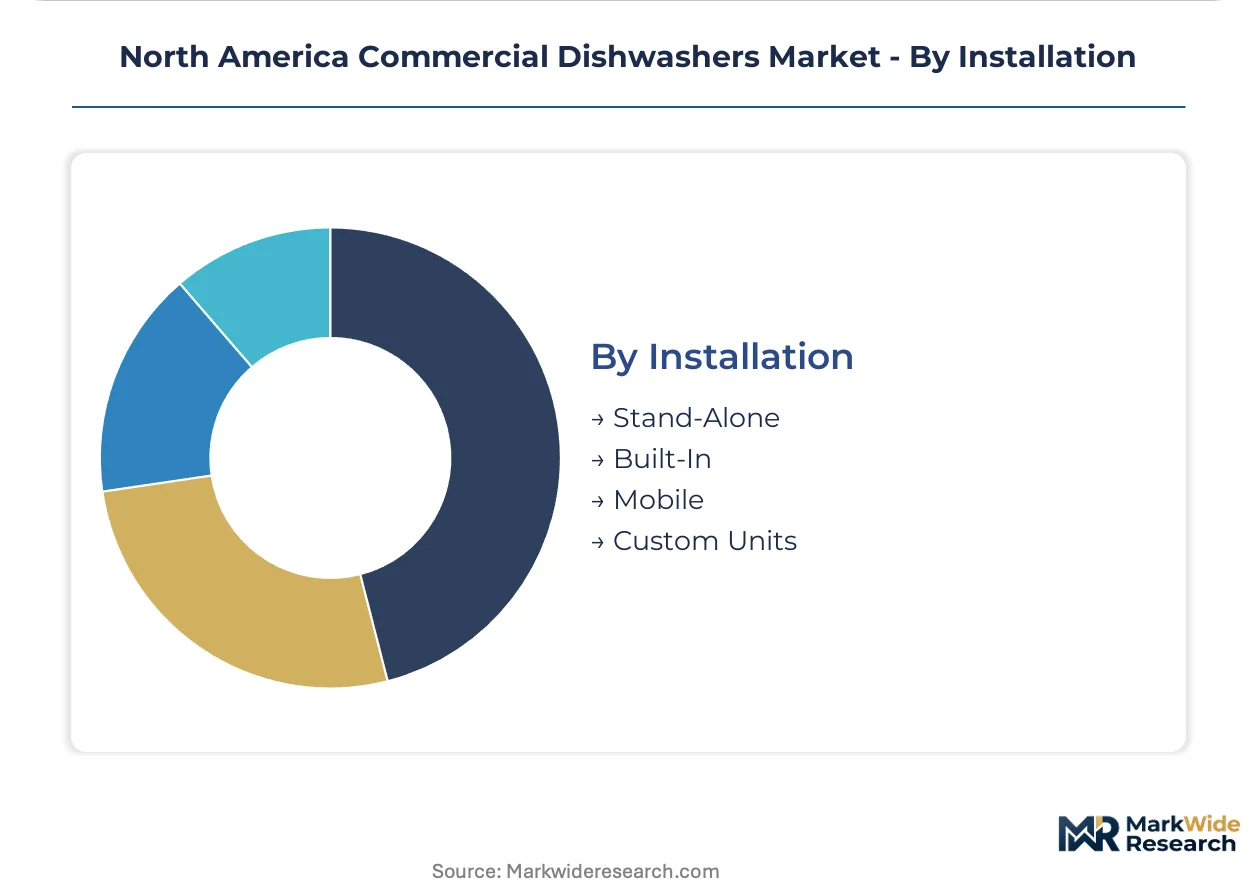
- Stand-Alone:Self-supporting units with integrated chemical dosing and drainage systems dominate new construction, particularly in Sun Belt hospitality developments where electrical and plumbing infrastructure is purpose-built.
- Built-In:Custom-fitted installations requiring architectural coordination prevail in historic urban buildings across the U.S. Northeast, where older structures often lack sufficient electrical capacity for modern low-water, high-temperature systems.
- Mobile:Castor-mounted units with quick-connect utilities serve catering operations and temporary foodservice installations, with demand clustering around event-centric markets like Los Angeles and Miami.
- Custom Units:Engineered-to-order configurations address non-standard throughput requirements or space constraints, typically specified by institutional operators with unique workflow geometries.
Stand-alone leads on scale; custom units lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial dishwasher manufacturing first scaled in the United States during the post-war foodservice boom, with domestic producers establishing the thermal system architectures that still dominate North American installations today.
United States
Sun Belt hospitality construction in Texas, Florida, and Arizona pulls conveyor-system installations into new hotel and casino developments. The Department of Energy's efficiency mandates compress product lifecycles and force OEMs toward heat-recovery designs. Las Vegas and Orlando foodservice directors specify closed-loop water filtration to evade municipal sewer surcharge penalties.
Canada
Cross-border certification friction from Natural Resources Office protocols extends time-to-market for U.S.-based OEMs by 4-6 months. Provincial health authorities impose parallel efficiency testing requirements that vendors must navigate. Toronto and Vancouver institutional operators filter procurement lists to WaterSense-labeled products for federal compliance.
Mexico
Quick-service chain growth in Monterrey and Guadalajara creates demand for compact rack-type units with voltage compatibility for 127V infrastructure. The country's national efficiency regulator shapes import certification workflows for foreign equipment vendors. Mexico City metro area foodservice density outpaces national averages, pulling automated warewashing capacity into new developments.
North America Commercial Dishwashers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across thermal efficiency and service network depth, with engineering-intensive architectures commanding pricing power over scale-driven fabricators. The vendor base clusters around three strategic archetypes: integrated chemical-service bundlers, durable-construction specialists, and compact-footprint innovators. Dominant competitive moves include vertical integration into chemical dispensing and maintenance services, plus geographic expansion through multi-site account lock-in.
Among domestic manufacturers, Hobart and Jackson WWS exemplify the integrated-service archetype, while CMA Dishmachines occupies a position within the compact-specialist tier. Meiko USA represents European-origin engineering penetration into North American institutional contracts. These anchors demonstrate how competitive positioning stratifies across chemical bundling, domestic manufacturing scale, and space-constrained installation expertise.
| Leading Market Players |
|---|
| Hobart |
| Jackson WWS |
| CMA Dishmachines |
| Champion Industries |
| Meiko USA |
| Insinger Machine Company |
| Sterling (Unified Brands) |
| Electrolux Professional |
| Winterhalter |
| Others |
Value Network & Pricing Analysis
Captive chemical dispensing networks anchor both supply position and pricing power for integrated OEMs serving multi-site foodservice accounts across the Sun Belt. This backward integration into consumables and service contracts insulates premium tiers from commodity margin compression while locking in recurring revenue streams that pure equipment vendors cannot replicate.
Pricing Analysis
Equipment-as-a-service contracts with bundled per-rack fees now dominate procurement among private equity-backed restaurant groups prioritizing balance-sheet flexibility over capital ownership. Price differentiation separates heat-recovery architectures with IoT-enabled predictive maintenance from standard high-temperature units lacking smart controls. Cost compression in mid-tier door-type equipment is intensifying because stainless steel input volatility from North American mills squeezes fabricator margins. Independent operators with under 50 seats exhibit highest price sensitivity, while hospital and casino foodservice directors demonstrate lowest sensitivity due to Joint Commission documentation requirements and 24-hour throughput demands.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from national restaurant chains and institutional operators, bypassing traditional distribution intermediaries. Manufacturing concentrates in the United States, with domestic producers leveraging proximity to Sun Belt hospitality construction clusters. Component sourcing draws from specialty stainless steel mills in the U.S. and Canada, plus control system electronics from Mexico's maquiladora corridor. Tariff exposure on cross-border steel shipments between the U.S. and Canada presents structural supply chain risk. Distribution runs through factory-authorized service networks that bundle installation, chemical supply, and predictive maintenance into long-term contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Commercial Dishwashers Market compounds steadily as regulatory pressure on water heating efficiency forces replacement cycles across the installed base. This structural tailwind ensures demand persistence regardless of macroeconomic volatility.
For Market Incumbents: Deepen captive chemical dispensing networks to lock in multi-site accounts against emerging OEMs offering unbundled hardware. Expand factory-authorized service technician training programs to address field scarcity that limits response-time commitments across dispersed geographies. Prioritize heat-pump and energy-recovery R&D investment to capture California and New York utility rebate programs before compliance mandates harden.
For New Entrants and Emerging Players: E-commerce platforms serving independent restaurants with compact undercounter units offer the most penetrable entry vector. Target Manhattan, San Francisco, and Chicago operators in kitchens under 800 square feet where lease premiums drive space-constrained procurement. Position around rapid delivery and DIY installation support to differentiate from incumbent service-bundled models.
For Investors and Strategic Acquirers: Roll-up economics work for regional service contractors with captive chemical dispensing relationships because fragmented local maintenance networks lack scale to compete against national OEM service arms. Focus acquisition screens on firms with WaterSense-labeled product portfolios and established hospital or casino account presence. Watch state-level building electrification mandate adoption velocity as the primary inflection indicator for heat-pump dishwasher demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chemical Dispensing | Captive consumables revenue insulates margin pressure from stainless steel volatility. |
| Heat-Recovery Architecture Development | DOE efficiency mandates compress product lifecycles toward premium thermal systems. |
| IoT-Enabled Predictive Maintenance Platform | Smart controls open subscription revenue streams alongside hardware sales. |
| Factory-Authorized Service Network Expansion | Technician scarcity limits OEM response times across dispersed multi-site accounts. |
| WaterSense Certification Investment | Federal procurement preference filters vendor lists for institutional contracts. |
Research Methodology
Direct dialogue with foodservice equipment procurement directors, commercial kitchen design consultants, OEM product managers, and aftermarket service technicians grounded the qualitative foundation. Secondary validation drew from U.S. Department of Energy efficiency standard filings, EPA WaterSense certification databases, SEC 10-K disclosures from publicly traded foodservice equipment parents, and Canadian Natural Resources Office protocol documentation. Bottom-up triangulation across named end-user segments and top-down reconciliation against regional construction permits and hospitality development pipelines ensured cross-verified demand estimates.
Segment-level value outputs across product type, end user, technology, and installation mode were derived through multi-variable regression incorporating utility tariff trajectories, regulatory compliance cost curves, and labor availability indices. CAGRs were computed from fitted trend lines across the projection horizon, with scenario weighting applied to electrification mandate adoption timelines and stainless steel price cycle assumptions. Industry-specific forecast inputs included Sun Belt hospitality construction permit velocity and hospital foodservice director survey data on closed-loop water filtration specification rates.
Stainless steel price volatility, cross-border certification timeline extensions, and manual warewashing substitution persistence in low-wage secondary markets are the dominant revision risks. Forecasts reflect base-case assumptions regarding DOE efficiency mandate implementation schedules and state electrification program funding continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Global Glass Door Cooler Market
Food Service Equipment
Countertop Ice Dispensers Market
Food Service Equipment
Commercial Slush Machine Market
Food Service Equipment
Electric Commercial Deep Fryers Market
Food Service Equipment
Commercial Bar Equipment Market
Food Service Equipment
Commercial Ice Equipment and Supplies Market
Food Service Equipment
Rapid Cook-High Speed Ovens Market
Food Service Equipment
Beverage Refrigeration Market
Food Service Equipment
Meal Delivery Carts and Racks Market
Food Service Equipment
Digital Menu Boards Market
Food Service Equipment
Ice Cube Tray Market
Food Service Equipment
Commercial Rotisserie Equipment Market
Food Service Equipment
Used Commercial Kitchen Equipment Market
Food Service Equipment
Gas Commercial Deep Fryers Market
Food Service Equipment
Reach-In Refrigerators Market
Food Service Equipment
Warewashing Equipment Market