
 Coffee Equipment and Supplies Market | 2026-2036
Coffee Equipment and Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Coffee Equipment and Supplies Market Outlook
Multi-source component procurement is restructuring supply economics for commercial brewer manufacturers. BUNN-O-MATIC Corporation leverages its domestic foundry network to control heating element quality. De'Longhi S.p.A. sustains competitive pressure through vertical integration into thermostat and pump assemblies. La Marzocco S.r.l. anchors the premium artisanal segment with hand-finished group heads manufactured in Florence.
Coffee equipment and supplies encompass electromechanical brewing apparatus, precision grinding mechanisms, extraction accessories, and maintenance consumables designed for controlled water temperature, pressure profiling, and particle uniformity to optimize beverage quality. Commercial espresso machines typically operate at nine bars of pressure with thermoblock or boiler systems maintaining brew temperatures between 90°C and 96°C. The product type dimension shows coffee machines capturing the dominant value share while grinders command higher margin density due to burr precision engineering. End user segmentation reveals cafes and restaurants outpacing household growth in absolute unit terms, though office breakrooms represent an underdeveloped channel with concentrated contract potential.
The US Department of Energy appliance standards and EU Ecodesign Directive constrain standby power consumption and materials usage in new equipment certification, while FDA food-contact surface regulations govern brew basket and carafe compositions for commercial applications. China's GB standards for household appliance safety create separate compliance pathways for export-oriented manufacturers. Stakeholders must monitor evolving efficiency thresholds and regional certification divergence to optimize platform architecture and avoid redundant testing cycles.
Market Dynamics
Energy efficiency mandates from the EU Ecodesign Directive are compressing standby power allowances below one watt, forcing manufacturers to redesign thermoblock architectures and abandon legacy heating coil specifications. This regulatory pressure intersects with artisanal café demand for pressure-profiling capabilities, creating a product development tension between compliance and performance.
Growth Catalysts
- Specialty coffee shop expansion:Artisanal café chains in Germany, Italy, and the United States are upgrading to dual-boiler espresso systems with independent steam and brew temperature control. Premium equipment procurement concentrates in urban clusters with established third-wave coffee culture.
- EU Ecodesign Directive:Mandatory standby power limits and materials efficiency standards are accelerating replacement cycles for commercial brewing equipment across member states. Compliance deadlines force retrofits in institutional foodservice operations.
- Pressure profiling technology:Variable extraction pressure systems enabling barista-controlled flavor modulation are penetrating high-end café segments. This capability commands substantial price premiums over fixed-nine-bar machines.
Market Restraints
- Copper and brass input volatility:Boiler and group head manufacturing depends on non-ferrous metal prices subject to mining supply disruptions and exchange rate fluctuations. Foundry energy costs amplify material price transmission.
- Precision burr supply concentration:High-carbon steel and ceramic grinding burr production clusters in specialized German and Italian machining centers. Limited alternative suppliers constrain grinder manufacturer sourcing flexibility.
- Technical limitation in compact thermoblock design:Simultaneous steam and brew output requires thermal mass that conflicts with rapid heat-up efficiency targets. Engineering trade-offs persist in sub-15-amp electrical constraints.
Strategic Opportunities
- Office breakroom channel underpenetration:Corporate foodservice contracts for bean-to-cup super-automatic systems remain fragmented across facility management providers. Concentrated procurement potential exists in multinational headquarters clusters.
- India specialty café emergence:Metro area coffee culture development in Bengaluru, Mumbai, and Delhi generates demand for semi-professional equipment previously absent from South Asian markets. Import tariff structures favor local assembly partnerships.
- China dual carbon goals:National energy efficiency targets and provincial green building standards create procurement preference for low-wattage brewing systems in hospitality developments. GB standards compliance opens distribution through domestic retail channels.
Industry Challenges
- Pressure profiling calibration expertise gap:Field service technician training for variable extraction system maintenance lags behind equipment deployment. Manufacturer service networks require capability expansion.
- Multi-jurisdiction certification complexity:Simultaneous FDA food-contact surface approval, EU CE marking, and China GB safety testing extends product launch timelines. Redundant laboratory testing cycles consume engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffee Equipment and Supplies Market |
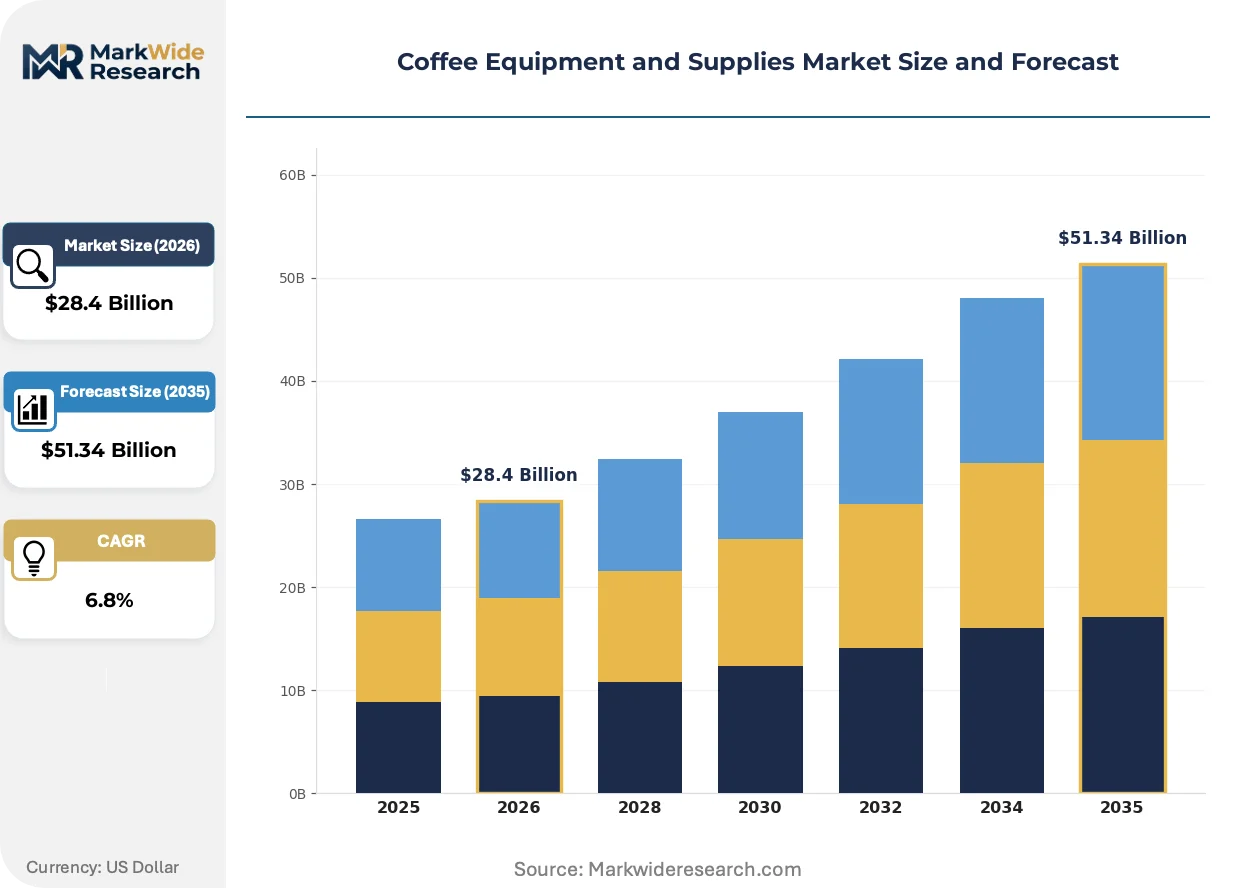
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $51.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coffee Machines, Grinders, Brew Accessories, Cleaning Supplies End User: Households, Cafes, Restaurants, Office Breakrooms Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Direct Sales Pricing Tier: Premium, Mid-range, Budget, Discounted |
| Companies Covered | BUNN-O-MATIC Corporation, Melitta Group Verwaltungsgesellschaft mbH, De'Longhi S.p.A., La Marzocco S.r.l., Rancilio Group S.p.A., JURA Elektroapparate AG, Gruppo Cimbali S.p.A., Breville Group Limited, WMF GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffee Equipment and Supplies Market Strategic Shifts
Connected brewing telemetry and predictive maintenance algorithms are redefining equipment value propositions, shifting competitive differentiation from hardware specifications toward operational data services. This convergence of electromechanical systems and software analytics is restructuring manufacturer-customer relationships across commercial segments.
Pulse extraction technology is overtaking traditional volumetric dosing in high-throughput café environments. This approach modulates water flow rate during extraction to optimize flavor clarity under varying bean conditions. Chains with centralized quality control are adopting sensor-equipped group heads at accelerated replacement cycles. The technology is compressing acceptable tolerance ranges for barista technique variation.
REACH substance restrictions on nickel and chromium compounds in food-contact applications are compelling boiler alloy reformulation across European manufacturing. Stainless steel grades with reduced nickel content are entering certification pipelines. Espresso machine producers serving EU markets are redesigning heat exchanger specifications to maintain corrosion resistance under modified metallurgical constraints.
Direct-to-roaster equipment procurement is displacing traditional distributor intermediation in mid-market café segments. Roasters with captive café networks are specifying brewing platforms and negotiating volume commitments directly with manufacturers. This pattern is most visible in United States metropolitan markets with consolidated specialty roasting operations.
Coffee Equipment and Supplies Market Segmentation
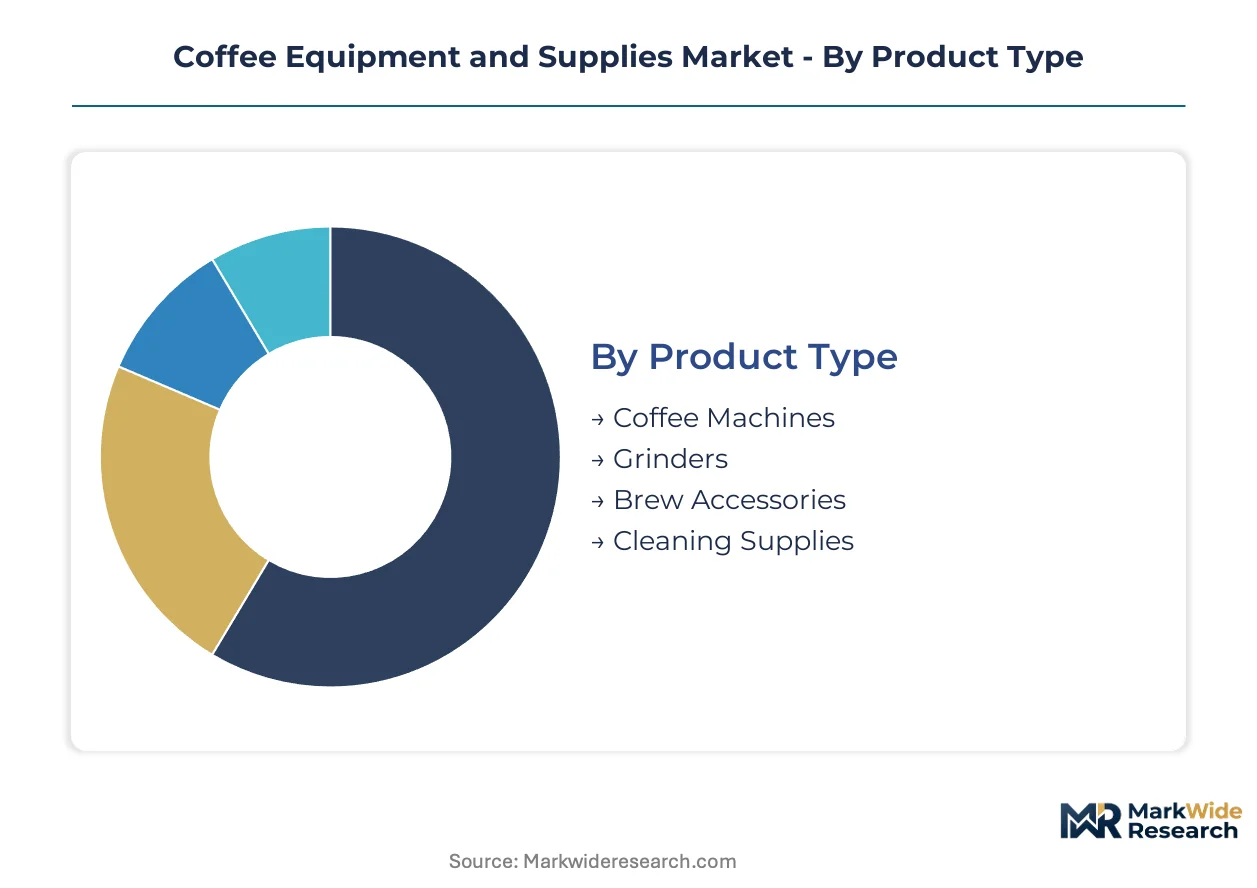
Segmentation in coffee equipment reveals how technical specifications, procurement channels, and end-use intensity create divergent margin structures. Equipment manufacturers optimize platform architectures differently when targeting artisanal cafés versus corporate breakrooms, with distribution economics and certification requirements shifting accordingly.
Product Type:
Thermal engineering specifications and precision tolerances distinguish equipment categories across extraction quality and operational durability.
- Coffee Machines:Electromechanical brewing systems operate at nine bars pressure with thermoblock or boiler architectures maintaining 90°C to 96°C brew temperatures. Demand concentrates in German and Italian urban café clusters where dual-boiler configurations with independent steam control command procurement priority. EU Ecodesign Directive standby power mandates below one watt are forcing thermoblock redesigns across commercial portfolios.
- Grinders:Precision burr mechanisms using high-carbon steel or ceramic achieve particle uniformity critical to extraction consistency. Artisanal roasting operations in the United States specify stepless adjustment systems with micron-level calibration. Burr supply concentrates in specialized German and Italian machining centers, constraining manufacturer sourcing flexibility.
- Brew Accessories:Portafilters, tampers, and precision dosing tools complete extraction workflows. Third-wave café chains standardize accessory specifications to reduce barista technique variation.
- Cleaning Supplies:Descaling agents and group head detergents maintain food-contact surface compliance under FDA regulations. Institutional foodservice contracts specify automated cleaning cycle compatibility.
Coffee machines lead on scale; grinders lead on momentum.
End User:
Volume throughput and technical sophistication requirements separate customer segments by equipment specification intensity and service network demands.
- Cafes:High-throughput operations demand dual-boiler espresso systems with pressure profiling capabilities and predictive maintenance telemetry. Specialty chains in Germany and Italy upgrade equipment at accelerated cycles to maintain competitive extraction quality. Field service technician training for variable extraction calibration lags behind deployment, creating manufacturer service network expansion requirements.
- Restaurants:Foodservice operations prioritize compact footprints and rapid heat-up times under sub-15-amp electrical constraints. Simultaneous steam and brew output requirements conflict with energy efficiency targets in thermoblock design.
- Households:Residential users drive super-automatic bean-to-cup system volume through online retail channels. China's GB standards for household appliance safety create separate compliance pathways for export-oriented manufacturers.
- Office Breakrooms:Corporate foodservice contracts remain fragmented across facility management providers. Multinational headquarters clusters in the United States represent concentrated procurement potential for automated systems with minimal operator training requirements.
Cafés dominate absolute unit demand; office breakrooms present the steepest expansion trajectory.
Distribution Channel:
Channel economics reflect customer acquisition costs, technical consultation requirements, and post-sale service obligations across segment tiers.
- Online Retail:E-commerce platforms capture household segment volume with standardized specifications and comparison-driven purchasing. Direct-to-roaster procurement is displacing traditional distributor intermediation in United States metropolitan markets with consolidated specialty roasting operations.
- Specialty Stores:Brick-and-mortar showrooms provide hands-on equipment demonstration and barista training integration. Urban clusters with established third-wave coffee culture sustain specialty store foot traffic.
- Wholesale Distributors:Regional inventory pooling reduces lead times for commercial replacement cycles. Distributor technical support capabilities vary, creating service quality fragmentation.
- Direct Sales:Manufacturer field teams handle large-format café chain and institutional contracts with customized specification negotiation. Volume commitments bypass distributor margins but require captive service network investment.
Online retail leads on household penetration; direct sales leads on contract value concentration.
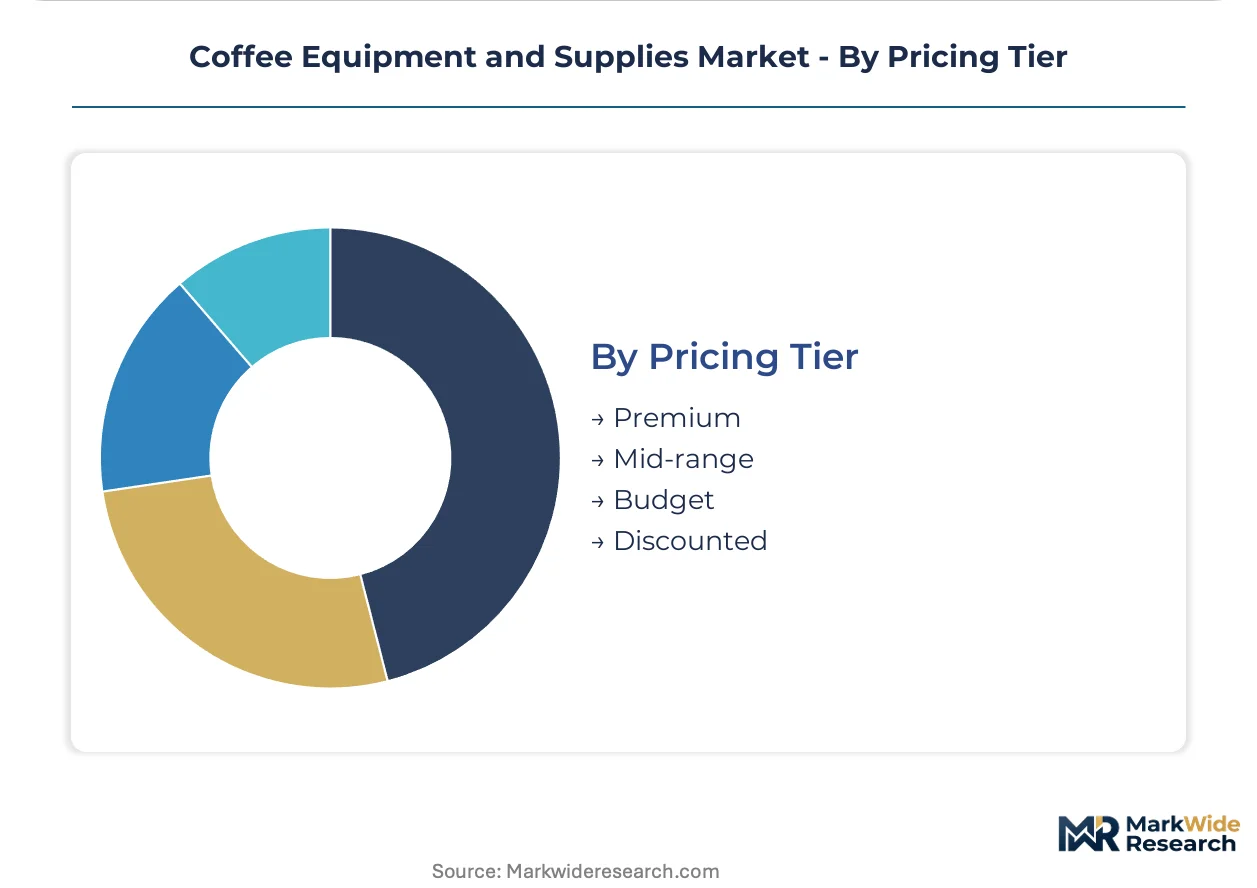
Pricing Tier:
Cost structures align with component specification grades, certification intensity, and manufacturing origin across equipment categories.
- Premium:Hand-finished group heads manufactured in Florence and pressure-profiling systems with sensor-equipped telemetry define this tier. Artisanal café demand in Germany and Italy sustains price premiums over fixed-nine-bar configurations.
- Mid-range:Standardized dual-boiler systems with volumetric dosing target independent café operators. REACH substance restrictions on nickel and chromium compounds are compelling boiler alloy reformulation across European manufacturing.
- Budget:Single-boiler thermoblock designs serve entry-level commercial and advanced residential segments. Component standardization enables competitive sourcing from multiple foundry networks.
- Discounted:Refurbished equipment and end-of-life inventory clearance channels serve price-sensitive operators. Warranty terms and service eligibility vary substantially.
Premium tier leads on margin density; mid-range leads on volume accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German artisanal café clusters concentrate equipment procurement for dual-boiler espresso systems. United States metropolitan markets drive super-automatic volume through consolidated specialty roasting networks. Italian manufacturing centers supply precision-engineered group heads to premium-tier global buyers.
Germany
Third-wave coffee culture in Berlin and Hamburg sustains demand for pressure-profiling equipment with independent steam control. The EU Ecodesign Directive mandates standby power below one watt, accelerating replacement cycles in institutional foodservice. Bavarian engineering centers refine thermoblock architectures for compliance without sacrificing extraction performance.
United States
Specialty roasting operations in Seattle and Portland specify brewing platforms directly, bypassing traditional distributor channels. FDA food-contact surface regulations govern brew basket compositions for commercial applications. Corporate headquarters clusters in Manhattan and Chicago represent concentrated procurement potential for automated breakroom systems.
Italy
Artisanal café demand in Milan and Florence anchors premium espresso machine manufacturing with hand-finished components. REACH substance restrictions on nickel compounds compel boiler alloy reformulation in domestic foundries. Tuscan machining centers supply high-carbon steel burr sets to grinder manufacturers worldwide.
China
Provincial green building standards in Shanghai and Beijing create procurement preference for low-wattage brewing systems in hospitality developments. GB standards for household appliance safety establish separate compliance pathways for export-oriented manufacturers. Yangtze River Delta assembly partnerships serve emerging specialty café demand in Bengaluru and Mumbai.
India
Metro area coffee culture development in Bengaluru generates demand for semi-professional equipment previously absent from South Asian markets. Import tariff structures favor local assembly partnerships over direct equipment imports. Mumbai café clusters adopt pressure-profiling systems as quality differentiation intensifies.
Coffee Equipment and Supplies Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue connected telemetry and predictive maintenance services. The vendor base stratifies across three maturity levels: heritage European manufacturers with captive foundry networks, Asian-scale producers optimizing component standardization, and software-integrated challengers redefining equipment value propositions. Strategic archetypes include vertical specialists controlling critical component supply, platform integrators sourcing across multi-country supplier networks, and service-layer innovators monetizing operational data. Dominant competitive moves encompass backward integration into heating element and pump assembly production, plus direct-to-roaster procurement channel development.
Within the heritage manufacturing tier, BUNN-O-MATIC Corporation and De'Longhi S.p.A. exemplify divergent approaches to supply chain control. BUNN-O-MATIC leverages domestic foundry capacity for heating element quality assurance. De'Longhi sustains competitive pressure through in-house production of thermostat and pump assemblies. La Marzocco S.r.l. anchors the premium artisanal segment, representing the hand-finished, cluster-based manufacturing archetype centered in Florence.
| Leading Market Players |
|---|
| BUNN-O-MATIC Corporation |
| Melitta Group Verwaltungsgesellschaft mbH |
| De'Longhi S.p.A. |
| La Marzocco S.r.l. |
| Rancilio Group S.p.A. |
| JURA Elektroapparate AG |
| Gruppo Cimbali S.p.A. |
| Breville Group Limited |
| WMF GmbH |
| Others |
Value Chain & Pricing Dynamics
Copper and brass foundry costs transmit directly from Tuscan and Bavarian machining centers into premium espresso machine price points, with alloy grade specifications separating hand-finished Florence group heads from standardized thermoblock assemblies serving corporate breakroom contracts.
Pricing Analysis
Input-cost pass-through from non-ferrous metal markets shapes three-tier pricing structure across premium, standard, and economy levels. Artisanal café procurement in Berlin and Milan absorbs premiums for pressure-profiling capabilities and sensor-equipped telemetry, while institutional foodservice buyers prioritize volumetric dosing systems with compressed acquisition costs. Pricing pressure stems from EU Ecodesign Directive compliance investments in sub-one-watt standby architectures. Household segment buyers exhibit highest price sensitivity; premium-tier café operators demonstrate lowest elasticity due to quality differentiation imperatives.
Supply Chain Analysis
Container freight rate volatility from Yangtze River Delta ports to Hamburg and Los Angeles destabilizes landed cost calculations for export-oriented manufacturers. Precision burr production concentrates in German and Italian machining centers; heating element foundries cluster in domestic US networks and Chinese export zones. Supply chain risk centers on single-source vulnerability for high-carbon steel grinding components. Distribution runs through direct-to-roaster procurement channels displacing traditional wholesale intermediation in United States metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment manufacturers arbitrage regulatory cost differentials between EU Ecodesign compliance investments and China's GB standards pathways, with assembly partnerships in the Yangtze River Delta offering tariff-advantaged access to South Asian emerging demand.
For Market Incumbents: Lock in captive foundry capacity for heating element and pump assembly production to defend margin position against Asian-scale producers optimizing component standardization. Secure direct-to-roaster procurement relationships in United States metropolitan clusters before distributor intermediation fully collapses. Prioritize field service network expansion to address pressure profiling calibration expertise gaps threatening equipment deployment.
For New Entrants and Emerging Players: Launch via automated breakroom system contracts targeting multinational headquarters clusters in Manhattan and Chicago where facility management provider fragmentation creates white-space opportunity. Target India specialty café emergence in Bengaluru and Mumbai through local assembly partnerships circumventing import tariff structures. Pursue software-integrated value propositions monetizing connected brewing telemetry and predictive maintenance algorithms.
For Investors and Strategic Acquirers: Consolidation pressure builds where heritage European manufacturers with captive foundry networks face valuation compression from Asian-scale competitors and service-layer challengers. Long-term viability favors vertical specialists controlling critical component supply or platform integrators with multi-country supplier network optimization. Watch for inflection signals in office breakroom channel penetration rates and direct-to-roaster procurement volume displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Elements | BUNN-O-MATIC's domestic foundry network controls quality assurance for commercial brewer thermal components. |
| Pressure Profiling Technology Launch | Variable extraction systems command substantial price premiums in German and Italian artisanal café segments. |
| Direct-to-Roaster Channel Development | Specialty roasting operations in Seattle and Portland bypass distributor margins through manufacturer-direct procurement. |
| GB Standards Compliance Investment | Export-oriented manufacturers unlock China's domestic retail channels through household appliance safety certification. |
| Connected Telemetry Platform Integration | Predictive maintenance algorithms shift competitive differentiation from hardware specifications toward operational data services. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with espresso equipment manufacturers, café chain procurement directors, foundry operations managers, and foodservice distributor technical support leads with secondary validation from EU Ecodesign Directive implementation reports, FDA food-contact surface regulations, China GB standards documentation, and customs trade data on non-ferrous metal imports. Bottom-up equipment shipment tracking and top-down market sizing triangulated volume estimates across the analysis window.
Comparable-period anchoring linked projection assumptions to historical replacement cycle patterns in commercial foodservice and residential upgrade trajectories. Segmentation modeling spanned product type, end user intensity, distribution channel economics, and pricing tier specification grades. CAGRs derived from equipment procurement pipeline analysis and regulatory deadline acceleration effects. Forecast inputs incorporated EU standby power mandate compliance timelines and specialty café expansion patterns in identified urban clusters.
Forecast precision tightens around the base case; tail outcomes carry wider variance under commodity price volatility in copper and brass markets and potential REACH substance restriction expansions beyond nickel and chromium compounds. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Instant Pot Market
Food Service Equipment
Warewashing Professional Equipment Market
Food Service Equipment
Commercial Refrigerated Display Cabinet Market
Food Service Equipment
Commercial Rotisserie Oven Market
Food Service Equipment
Food Display Cabinet Market
Food Service Equipment
Draught Beer Chiller Market
Food Service Equipment
Gas Commercial Deep Fryers Market
Food Service Equipment
Back Bar Coolers Market
Food Service Equipment
Food and Beverage Vending Machine Market
Food Service Equipment
Commercial Gas Restaurant Ranges Market
Food Service Equipment
Global QSR Food Service Equipment Market
Food Service Equipment
Commercial Ventless Cooking Equipment Market
Food Service Equipment
Slow Cooker and Sous Vide Market
Food Service Equipment
Freestanding Large Cooking Appliance Market
Food Service Equipment
Multi-Deck Refrigerated Display Cases Market
Food Service Equipment
Industrial Dishwasher Market