
 Commercial Stainless Steel Cooking Equipment Market | 2026-2036
Commercial Stainless Steel Cooking Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Stainless Steel Cooking Equipment Market Insights
NSF/ANSI Standard 51 certification for food equipment materials is collapsing the supplier base as smaller fabricators lack testing capital. Middleby Corporation leverages its captive manufacturing network across multiple continents to sustain cost advantages in high-volume ranges and ovens. Electrolux Professional anchors its position through deep specialization in energy-efficient cooking technology for European institutional kitchens. Rational AG differentiates via precision combi-steamer engineering that commands premium positioning in fine-dining and hotel chains.
Commercial stainless steel cooking equipment encompasses gas, electric, and induction-powered ranges, ovens, griddles, steamers, and fryers fabricated from austenitic grades such as 304 and 316 with minimum chromium content of 18% for oxidation resistance, designed for continuous-duty cycles in professional foodservice operations. The product type dimension shows ranges and ovens occupying the largest installed base while induction-based equipment captures the fastest growth trajectory as energy costs reshape kitchen capital planning. Cooking technology segmentation reveals gas systems still dominating existing infrastructure in North American restaurants even as electric and induction platforms gain share in European and Asian new-build environments where carbon regulations tighten.
NSF International standards govern material safety and cleanability for US foodservice equipment, while the EU Machinery Directive and CE marking framework dictate electrical safety and electromagnetic compatibility requirements across European member states. These regulatory layers shape demand by mandating specific alloy grades, surface finishes, and energy efficiency thresholds that filter which manufacturers can access commercial channels. Stakeholders must monitor evolving energy labeling requirements and electrification mandates that will determine which cooking technology portfolios warrant capital allocation in coming replacement cycles.
Market Dynamics
Electrification mandates across European and Asian jurisdictions are compressing replacement cycles for gas-fired equipment while simultaneously elevating capital requirements for manufacturers retooling their product portfolios.
Growth Catalysts
- EU F-Gas Regulation phase-down:Restrictions on hydrofluorocarbon refrigerants in commercial kitchens are accelerating demand for induction-based alternatives that eliminate cooling-dependent components entirely.
- Quick service restaurant expansion:Southeast Asian chains are scaling centralized commissary kitchens requiring heavy-duty stainless steel ranges with continuous-duty ratings exceeding 16 hours daily operation.
- NSF/ANSI Standard 51 certification tightening:Enhanced material testing protocols for food-contact surfaces are filtering out non-compliant fabricators and consolidating procurement toward certified suppliers.
Market Restraints
- Nickel price volatility:Austenitic grade 304 and 316 stainless steels contain 8-14% nickel, exposing fabricators to London Metal Exchange fluctuations that compress margin predictability on fixed-price contracts.
- Vietnam-Indonesia supply concentration:Manufacturing relocation to these lower-cost bases has created single-source dependencies for European and North American brands lacking geographic diversification.
- Induction infrastructure gap:North American restaurants in older buildings face electrical panel upgrade costs exceeding equipment purchase prices, delaying technology transitions despite operational benefits.
Strategic Opportunities
- Indonesia domestic market penetration:Local hotel and institutional kitchen construction is outpacing indigenous manufacturing capacity, creating import substitution openings for certified foreign suppliers.
- Energy-as-a-service leasing:Equipment financiers are piloting subscription models bundling induction ranges with electricity monitoring, shifting capital expenditure to operating expense for mid-sized restaurant groups.
- EU Green Deal renovation wave:Public sector kitchen refurbishment subsidies in Germany, France, and Italy are directing procurement toward A-rated energy efficiency equipment with connected monitoring capabilities.
Industry Challenges
- Welding certification scarcity:TIG welding of food-grade stainless steel to NSF surface finish requirements demands specialized technicians whose training pipelines lag equipment demand growth by 18-24 months.
- Multi-certification sequencing:Simultaneous pursuit of NSF, CE marking, and country-specific electrical approvals extends product launch timelines and fragments engineering resources across testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Stainless Steel Cooking Equipment Market |
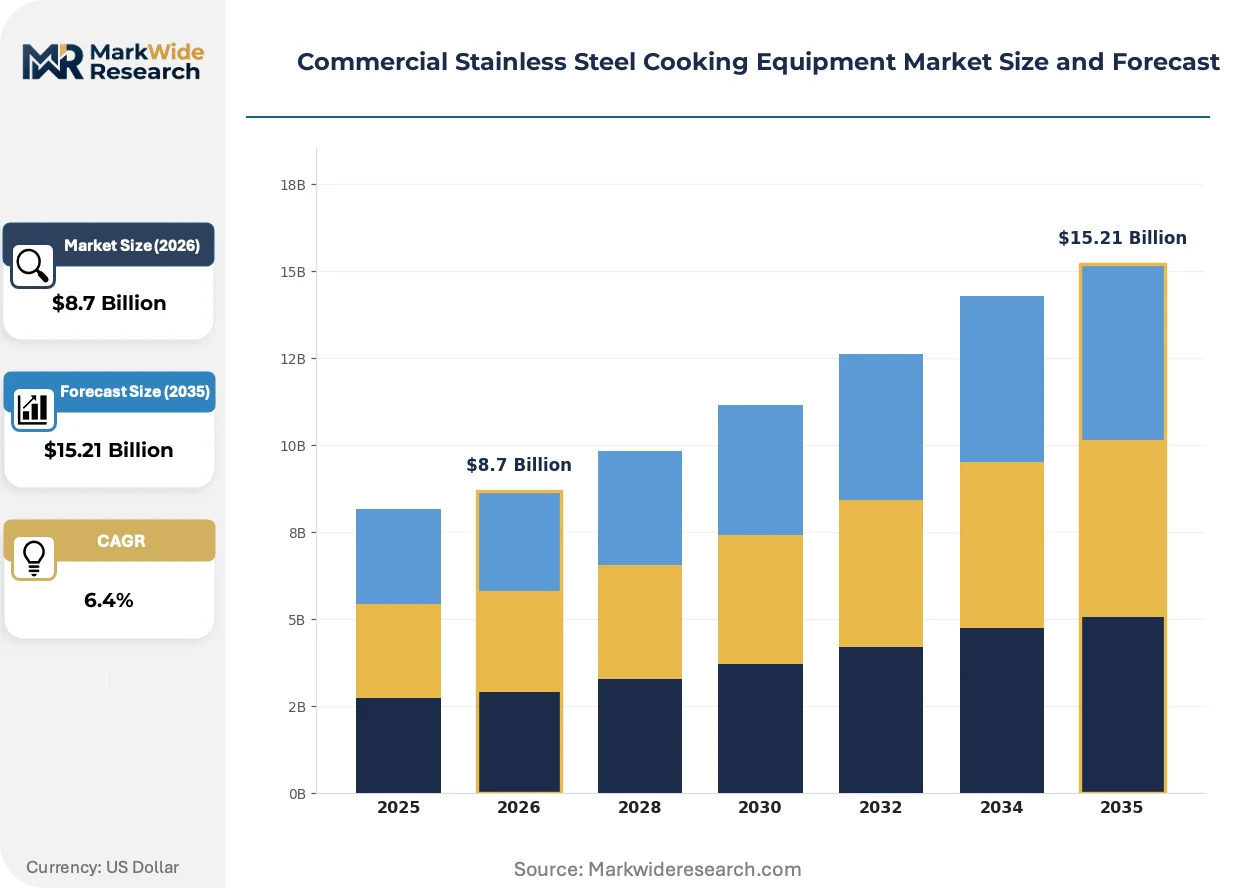
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
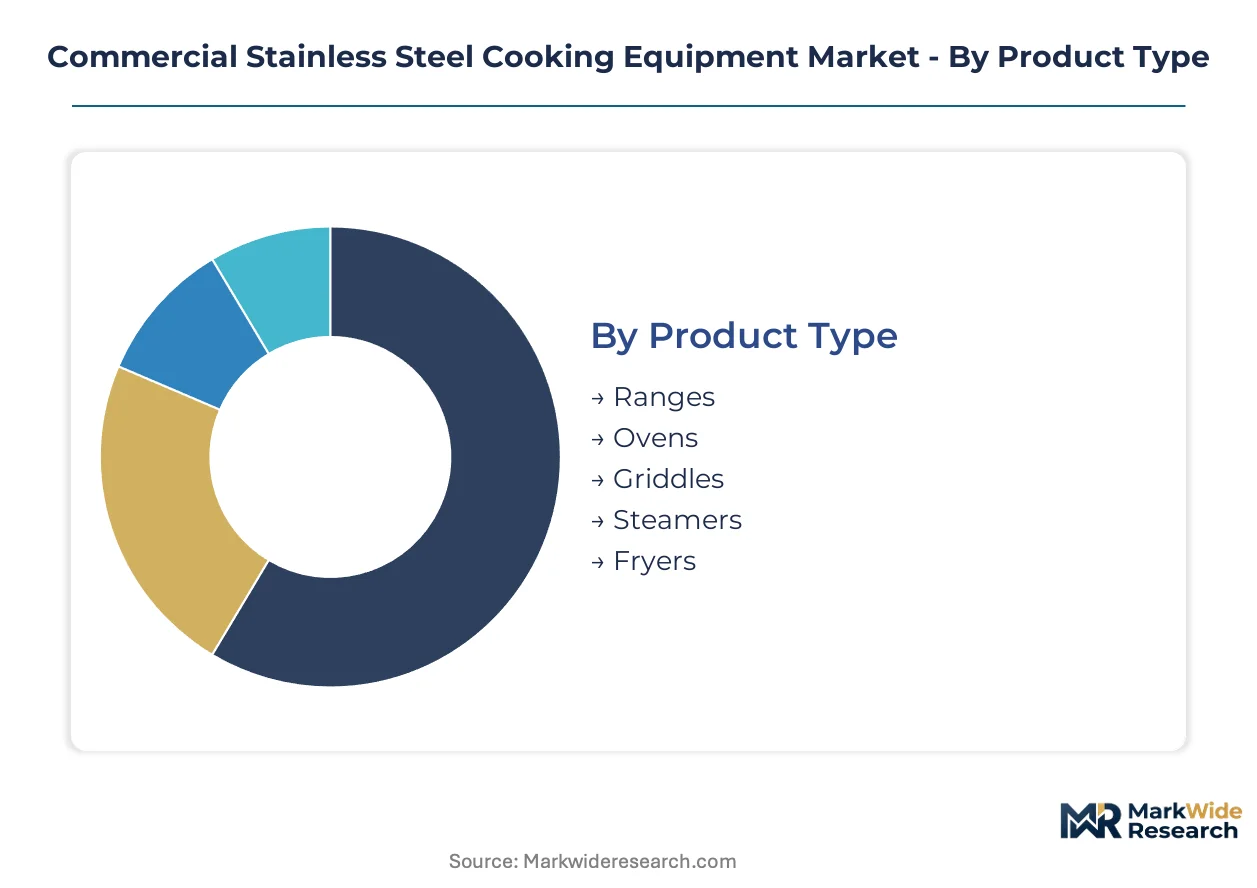
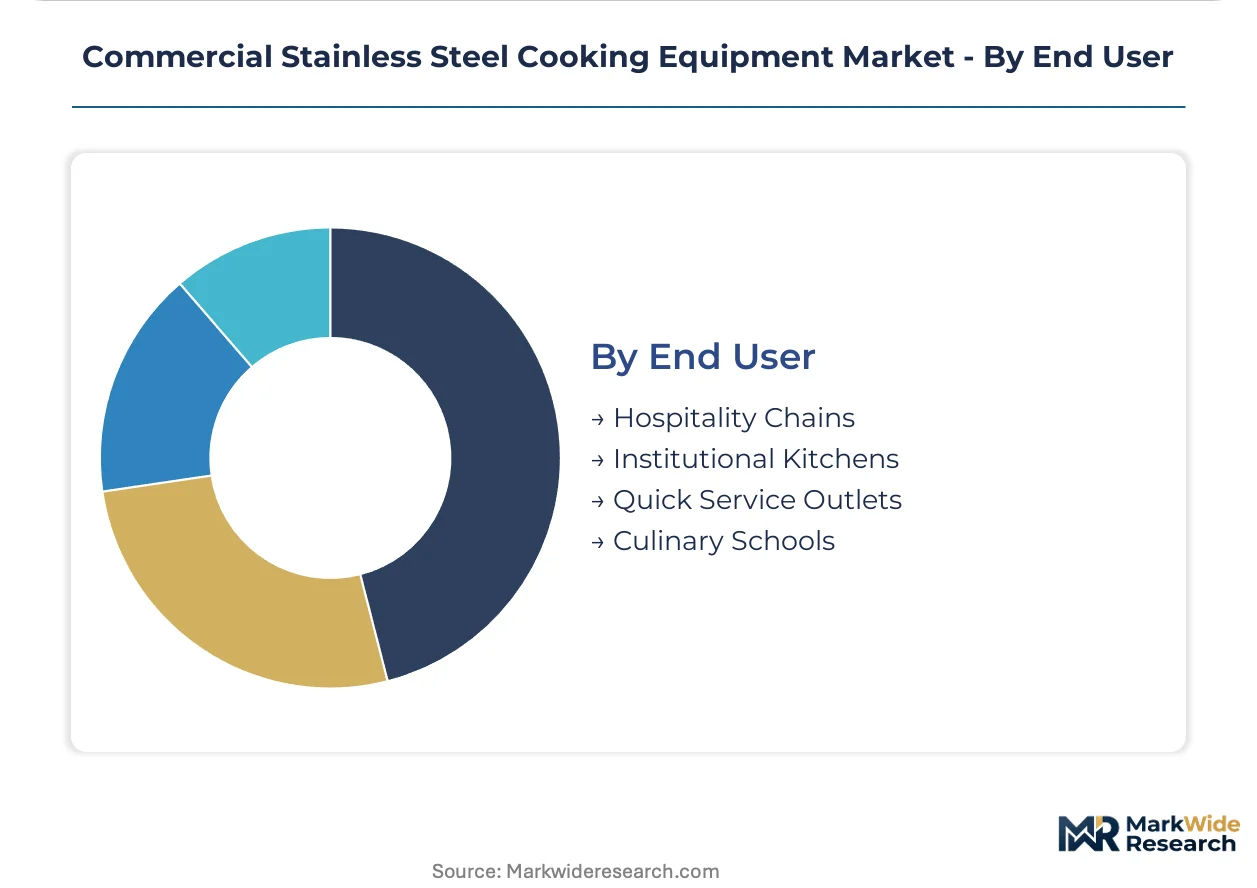
| Segmentation | Product Type: Ranges, Ovens, Griddles, Steamers, Fryers Cooking Technology: Gas, Electric, Induction, Infrared, Ceramic Application: Restaurants, Catering Services, Cafeterias, Food Trucks, Bakeries End User: Hospitality Chains, Institutional Kitchens, Quick Service Outlets, Culinary Schools |
| Companies Covered | Middleby Corporation, Ali Group, Welbilt, Inc., ITW Food Equipment Group, Rational AG, Electrolux Professional, Cleveland Range, Alto-Shaam, Inc., Duke Manufacturing Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Stainless Steel Cooking Equipment Market Trends and Innovations
Connected cooking platforms and modular equipment architectures are redefining how commercial kitchens configure their production lines and manage energy consumption across variable demand cycles.
Combi-steamer technology is decomposing traditional distinctions between steaming, convection baking, and roasting functions into programmable phases controlled through single interfaces. Fine-dining chains and hotel kitchens are adopting these systems at replacement rates exceeding conventional ovens by a factor of two to one. Equipment specification is compressing kitchen footprints and reducing capital allocations for redundant single-function appliances.
REACH chemical restrictions and the EU Machinery Directive's updated electromagnetic compatibility standards are mandating reformulation of surface coatings and control electronics. Manufacturers serving European markets must redesign interface panels and wiring harnesses to eliminate restricted substances. This regulatory pressure is most acute for mid-volume producers lacking in-house compliance teams, pushing them toward third-party certification consultants.
Kitchen operators are consolidating vendor relationships to reduce service contract fragmentation and standardize training protocols. Large contract foodservice companies are replacing multi-brand equipment mixes with single-manufacturer portfolios covering 80% or more of cooking functions. This concentration is most visible in US hospital and university dining operations where procurement departments prioritize simplified spare parts management over best-of-breed feature comparisons.
Commercial Stainless Steel Cooking Equipment Market Segmentation
Segmentation in commercial stainless steel cooking equipment reveals how capital allocation, energy infrastructure, and regulatory compliance create distinct margin architectures across product categories. Procurement patterns diverge sharply between high-volume chain operators optimizing for total cost of ownership and independent establishments prioritizing equipment flexibility.
Product Type:
Margin pools concentrate in equipment categories requiring precision thermal control and extended duty cycles, where NSF certification barriers filter competition and sustain pricing power.
- Ranges:Heavy-duty gas and induction ranges fabricated from 304-grade stainless steel with continuous-duty ratings anchor kitchen production lines. Quick service outlets across Vietnam and Indonesia are scaling centralized commissary installations requiring 16-hour daily operation capacity.
- Ovens:Convection and combi-steamer ovens command premium positioning through programmable multi-phase cooking that compresses kitchen footprints. Fine-dining chains and hotel kitchens are adopting these systems at replacement rates exceeding conventional alternatives by substantial margins.
- Griddles:Flat-top gas and electric griddles with chromium-nickel surfaces dominate breakfast-focused operations and burger chains requiring consistent thermal distribution.
- Steamers:Pressure and atmospheric steamers serve institutional kitchens with high-volume vegetable and protein preparation requirements.
- Fryers:Vat-style and pressure fryers with integrated oil filtration systems target high-throughput chicken and seafood operations.
Ranges hold installed capacity. Ovens are rotating up the share rankings.
Cooking Technology:
Technology selection now tracks electrification mandates and energy cost trajectories more than traditional fuel access considerations.
- Gas:Natural gas and propane systems retain dominance in existing North American restaurant infrastructure despite carbon regulation pressures. Legacy kitchen layouts and lower upfront capital requirements sustain demand even as operating costs escalate.
- Electric:Resistance-heating electric ranges gain share in European new-build environments where EU Green Deal subsidies direct procurement toward A-rated efficiency equipment.
- Induction:Electromagnetic induction platforms eliminate ambient heat loss and reduce ventilation loads. Electrification mandates across European and Asian jurisdictions are compressing replacement cycles for gas-fired alternatives.
- Infrared:Radiant heat systems deliver rapid temperature response for specialty searing and finishing applications in fine-dining settings.
- Ceramic:Smooth-top radiant elements occupy mid-market positioning between conventional electric and premium induction alternatives.
Gas retains legacy dominance. Induction is gaining share fastest.
Application:
Application segmentation maps directly to operational intensity and equipment durability requirements.
- Restaurants:Full-service and casual dining establishments require versatile equipment portfolios spanning multiple cooking technologies. Kitchen operators are consolidating vendor relationships to reduce service contract fragmentation.
- Catering Services:Mobile and off-premise catering demands compact, transportable equipment with rapid heat recovery cycles.
- Cafeterias:Institutional feeding operations prioritize batch cooking capacity and simplified cleaning protocols over precision control.
- Food Trucks:Space-constrained mobile kitchens drive demand for multi-function appliances and induction systems that minimize ventilation infrastructure.
- Bakeries:Specialized convection and deck ovens with humidity control target artisan bread and pastry production.
Restaurants anchor volume. Food trucks are expanding most quickly.
End User:
End-user categories separate procurement sophistication and contract scale.
- Hospitality Chains:Hotel and resort groups standardize equipment specifications across properties to simplify training and spare parts management. Rational AG and Electrolux Professional anchor positions through energy-efficient technology specialization.
- Institutional Kitchens:Hospital and university dining operations prioritize simplified procurement over best-of-breed feature comparisons, consolidating toward single-manufacturer portfolios.
- Quick Service Outlets:Burger and chicken chains drive high-volume range and fryer demand with equipment refresh cycles tied to franchise expansion schedules.
- Culinary Schools:Training institutions require durable, visible equipment that withstands novice operator error while demonstrating professional techniques.
Hospitality chains concentrate procurement volume. Quick service outlets are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government electrification subsidies across multiple jurisdictions are redirecting capital flows toward energy-efficient equipment procurement. Carbon reduction mandates in European and Asian cities are compressing replacement cycles for gas-fired infrastructure. Manufacturing relocation patterns are creating new supply concentrations in Southeast Asian industrial zones.
United States
Quick service restaurant chains are expanding commissary kitchens in Texas and Georgia requiring continuous-duty stainless steel ranges. NSF International certification requirements for food-contact surfaces are tightening equipment specifications nationwide. Chicago and Dallas-Fort Worth anchor equipment distribution networks serving franchise operators with standardized procurement protocols.
Germany
Institutional kitchen refurbishment under EU Green Deal subsidies is elevating demand for A-rated energy efficiency equipment. REACH chemical restrictions are mandating reformulation of surface coatings and control electronics. Bavaria's manufacturing clusters around Munich supply precision thermal control systems to hotel chains across Central Europe.
China
Dual carbon goals are accelerating electrification mandates in commercial kitchen construction across Yangtze River Delta cities. GB standards and SAMR regulations govern electrical safety and electromagnetic compatibility for foodservice equipment. Shanghai and Shenzhen industrial zones concentrate fabrication capacity for export-oriented induction range production.
Vietnam
Manufacturing relocation from higher-cost Asian bases is concentrating stainless steel equipment production in Ho Chi Minh City industrial parks. Centralized commissary construction for quick service chains is driving demand for heavy-duty ranges with 16-hour daily operation ratings. Da Nang and Hai Phong are emerging as secondary fabrication hubs serving regional export markets.
Indonesia
Local hotel and institutional kitchen construction in Jakarta and Surabaya is outpacing indigenous manufacturing capacity. The country's national standards body enforces electrical safety certification for imported foodservice equipment. Batam and Bintan industrial zones are attracting foreign fabricators seeking tariff advantages for ASEAN market access.
Commercial Stainless Steel Cooking Equipment Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive manufacturing networks across multiple continents. Tiered competition separates premium engineering specialists from volume-driven fabricators competing on procurement scale. Two strategic archetypes dominate: energy-efficient technology specialists and integrated multi-brand portfolio operators. M&A activity and geographic diversification through captive manufacturing networks represent the dominant competitive moves reshaping supplier positioning.
Among German-based precision engineering specialists, Rational AG exemplifies the premium-tier archetype through combi-steamer specialization. Middleby Corporation occupies a position as the diversified conglomerate with multi-continental manufacturing integration. Electrolux Professional represents the European institutional kitchen specialist with energy-efficient technology anchoring. These three companies illustrate how certification depth and manufacturing footprint determine competitive positioning in procurement consolidation environments.
| Leading Market Players |
|---|
| Middleby Corporation |
| Ali Group |
| Welbilt, Inc. |
| ITW Food Equipment Group |
| Rational AG |
| Electrolux Professional |
| Cleveland Range |
| Alto-Shaam, Inc. |
| Duke Manufacturing Co. Inc. |
| Others |
Pricing and Supply Chain Analysis
Commissary-scale production volumes in Vietnam and Indonesia are compressing unit economics for heavy-duty ranges while elevating price floors for certified fabricators lacking equivalent scale. Nickel cost pass-through mechanisms and NSF certification capital requirements interact to stratify supplier viability, concentrating procurement leverage among multi-continental manufacturers with captive alloy sourcing.
Pricing Analysis
Certification level (NSF/ANSI 51 versus basic food-grade) creates the primary spread between premium and commodity tiers, with CE-marked induction platforms commanding additional positioning in European institutional channels. Three-tier pricing structure across premium, standard, and economy levels reflects welding precision grades, energy efficiency ratings, and bundled service contract depth. Cost compression in mid-market electric ranges is intensifying because Vietnamese fabricators are absorbing nickel volatility through government-backed raw material subsidies. Quick service chains with standardized franchise specifications exhibit lowest price sensitivity, while independent restaurants prioritize upfront capital minimization over lifecycle cost.
Supply Chain Analysis
Strategic stockpiling of 304-grade stainless steel coils dominates inventory strategy among European and North American OEMs, while Asian fabricators favor just-in-time alloy delivery from Shanghai and Jakarta commodity exchanges. Manufacturing gravity centers on Vietnam, Indonesia, and China's Yangtze River Delta industrial zones, with secondary clustering emerging in Batam and Hai Phong export processing parks. Supply chains draw from nickel laterite mining in Indonesia, chromium ferroalloy production in South Africa, and cold-rolling capacity in Taiwan. Single-source vulnerability concentrates in Indonesian nickel processing following export restriction tightening. Distribution runs through hospitality equipment distributors in Dallas-Fort Worth and Frankfurt, with direct-to-chain procurement bypassing traditional channels for quick service commissary contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrification mandates across European and Asian jurisdictions are compressing replacement cycles for gas-fired infrastructure, creating a high-growth disruption window for induction-capable suppliers. This regulatory inflection rewards manufacturers with pre-positioned energy-efficient portfolios and certified multi-jurisdictional compliance.
For Market Incumbents: Fortify certification depth across NSF, CE marking, and GB standards to filter smaller competitors lacking testing capital. Middleby Corporation's captive manufacturing network across multiple continents demonstrates how geographic diversification insulates against Vietnam-Indonesia supply concentration risks. Prioritize backward integration into precision TIG welding technician training pipelines, as certification scarcity lags equipment demand growth by 18-24 months. For New Entrants and Emerging Players: Differentiate on energy-as-a-service leasing models that shift restaurant capital expenditure to operating expense, targeting mid-sized groups with electrical panel upgrade constraints. Indonesia's domestic hotel and institutional kitchen construction presents the most penetrable geography, with local manufacturing capacity trailing demand. Pursue white-label partnerships with established European brands seeking ASEAN market access without direct certification investment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision thermal control specialists with combi-steamer engineering depth over commodity range fabricators. Long-term viability hinges on electrification-ready product portfolios and multi-certification sequencing capabilities. Acquisition target archetype: mid-volume European producers with A-rated energy efficiency credentials and underutilized compliance teams. Watch for inflection when EU Green Deal renovation subsidies accelerate beyond public sector into commercial channel eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Certification Sequencing | NSF, CE, and GB standard alignment opens procurement access across North American, European, and Chinese institutional channels. |
| Backward Integration into Alloy Sourcing | Captive nickel and chromium supply agreements insulate margin predictability against London Metal Exchange volatility. |
| Energy-as-a-Service Leasing Pilot | Subscription models bundling induction ranges with electricity monitoring shift restaurant capex to opex. |
| Welding Technician Training Pipeline | In-house TIG certification programs address NSF surface finish scarcity lagging equipment demand growth. |
| Indonesia Domestic Manufacturing Footprint | Batam and Bintan industrial zone presence captures ASEAN tariff advantages and local hotel construction demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with restaurant chain procurement directors, commercial kitchen equipment distributors, NSF certification consultants, and TIG welding technician training program administrators. Secondary validation incorporated customs and trade data from Vietnam and Indonesia export processing parks, SEC 10-K filings from diversified foodservice equipment conglomerates, and EU Green Deal subsidy disbursement records. Bottom-up equipment shipment tracking across product categories triangulated against top-down market sizing from hospitality construction permits and franchise expansion announcements.
Across the analysis window, volume and value outputs reflect segmented modeling by cooking technology, product type, application intensity, and end-user procurement sophistication. CAGRs were derived from replacement cycle compression rates under electrification mandates, cross-referenced with nickel price scenario modeling and certification barrier impact assessments. Industry-specific forecast inputs incorporated quick service commissary construction timelines and EU F-Gas Regulation phase-down enforcement schedules.
The analysis sits within stated boundaries; outcomes outside sustained electrification policy commitment or nickel price stability corridors would require recalibration. Forecasts reflect documented assumptions regarding certification timeline standardization and ASEAN manufacturing relocation velocity. Revision becomes warranted when EU Green Deal subsidy allocation crosses thresholds that accelerate commercial channel eligibility beyond institutional kitchens.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Kegerator Equipment Market
Food Service Equipment
Global Commercial Cooking Equipment Market
Food Service Equipment
Global Commercial Dishwashers Market
Food Service Equipment
900 Series Cooking Equipment Market
Food Service Equipment
Commercial Rotisserie Equipment Market
Food Service Equipment
Commercial Refrigerator Market
Food Service Equipment
Coffee Equipment and Supplies Market
Food Service Equipment
Commercial Cookers Market
Food Service Equipment
Countertop Ice Dispensers Market
Food Service Equipment
Digital Menu Boards Market
Food Service Equipment
North America and Europe Vending Machine Market
Food Service Equipment
Commercial Steamer Market
Food Service Equipment
Restaurant Dish Delivery Equipment Market
Food Service Equipment
Portable Cooler Market
Food Service Equipment
Commercial Food Warming and Holding Equipment Market
Food Service Equipment
Restaurant Equipment Market