
 North America Fountain Dispenser Equipment Market | 2026-2036
North America Fountain Dispenser Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fountain Dispenser Equipment Market Analytics
Modular dispenser configurations is broadening buyer choice across the installed base. FBD Partnership, LP leverages its engineering focus to dominate high-volume custom installations for major chains. PepsiCo sustains channel control through captive equipment placement tied to syrup supply agreements. Lancer Worldwide anchors its position with manufacturing scale in automated cleaning and calibration systems.
Fountain dispenser equipment comprises electromechanical systems that mix concentrated syrup with filtered water and carbon dioxide to deliver chilled beverages at point-of-service, typically operating at 38-42°F with precision brix control for flavor consistency. Carbonated dispensers occupy the largest share of the product mix, while connected dispensers represent the fastest-expanding technology category as operators prioritize remote diagnostics and inventory telemetry. Fast food outlets generate the highest throughput volumes, though cafés present stronger margin pools due to premium beverage attachment rates.
The FDA Food Code governs equipment sanitation protocols, while NSF International standards certify materials safety and cleanability for commercial food equipment. NHTSA regulations on transport refrigeration indirectly shape syrup logistics infrastructure for outdoor and mobile installations. Operators must weigh capital deployment between retrofitting existing carbonated towers and migrating toward connected, self-service platforms that alter labor models and maintenance contracts.
Market Dynamics
The FDA's Food Code updates on equipment sanitation standards are accelerating migration from legacy carbonated towers toward connected dispenser platforms that enable remote diagnostics and automated compliance logging across quick-service restaurant chains.
Growth Catalysts
- Regulatory Compliance Mandates:The FDA Food Code pushes operators toward connected models with integrated sanitation monitoring, reducing manual inspection burden while meeting NSF International certification requirements for commercial food equipment cleanability.
- Self-Service Expansion:Quick-service restaurants across the United States and Canada are scaling self-service beverage programs to reduce labor touchpoints and improve throughput during peak traffic periods.
- Southeastern Development Concentration:Chain restaurant construction in the southeastern United States outpaces other sub-regions, creating concentrated demand pull for high-volume fountain installations.
Market Restraints
- Stainless Steel Input Volatility:Equipment chassis and dispensing towers rely heavily on stainless steel grades subject to commodity price swings, compressing margin predictability for manufacturers and operators alike.
- Syrup Supply Concentration:Captive equipment placement tied to exclusive syrup agreements limits buyer flexibility, locking smaller operators into single-source dependencies that constrain negotiating leverage.
- Legacy Infrastructure Inertia:Existing carbonated tower installations represent substantial sunk capital, slowing migration timelines even where connected platforms offer operational advantages.
Strategic Opportunities
- Café Premiumization:Independent cafés and coffee chains present underpenetrated demand for precision-brix dispensers capable of supporting premium beverage attachment rates above fast-food benchmarks.
- Mobile and Outdoor Installations:NHTSA transport refrigeration regulations are reshaping syrup logistics infrastructure, creating openings for compact, field-rugged dispenser configurations at stadiums, festivals, and food trucks.
- Modular Retrofit Kits:Technology convergence between electromechanical mixing systems and IoT-enabled telemetry modules allows staged upgrades without full equipment replacement, lowering adoption barriers for mid-size operators.
Industry Challenges
- Connected System Integration:Retrofitting legacy carbonated towers with remote diagnostics requires specialized technician expertise that remains scarce across service networks, extending deployment timelines.
- Calibration Certification Burden:Precision brix control systems demand recurring NSF International validation cycles that strain maintenance staffing and documentation protocols for multi-unit operators.
- Cross-Platform Inventory Telemetry:Synchronizing dispenser-level consumption data with enterprise resource planning systems involves API complexity and data standardization gaps that delay real-time analytics implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fountain Dispenser Equipment Market |
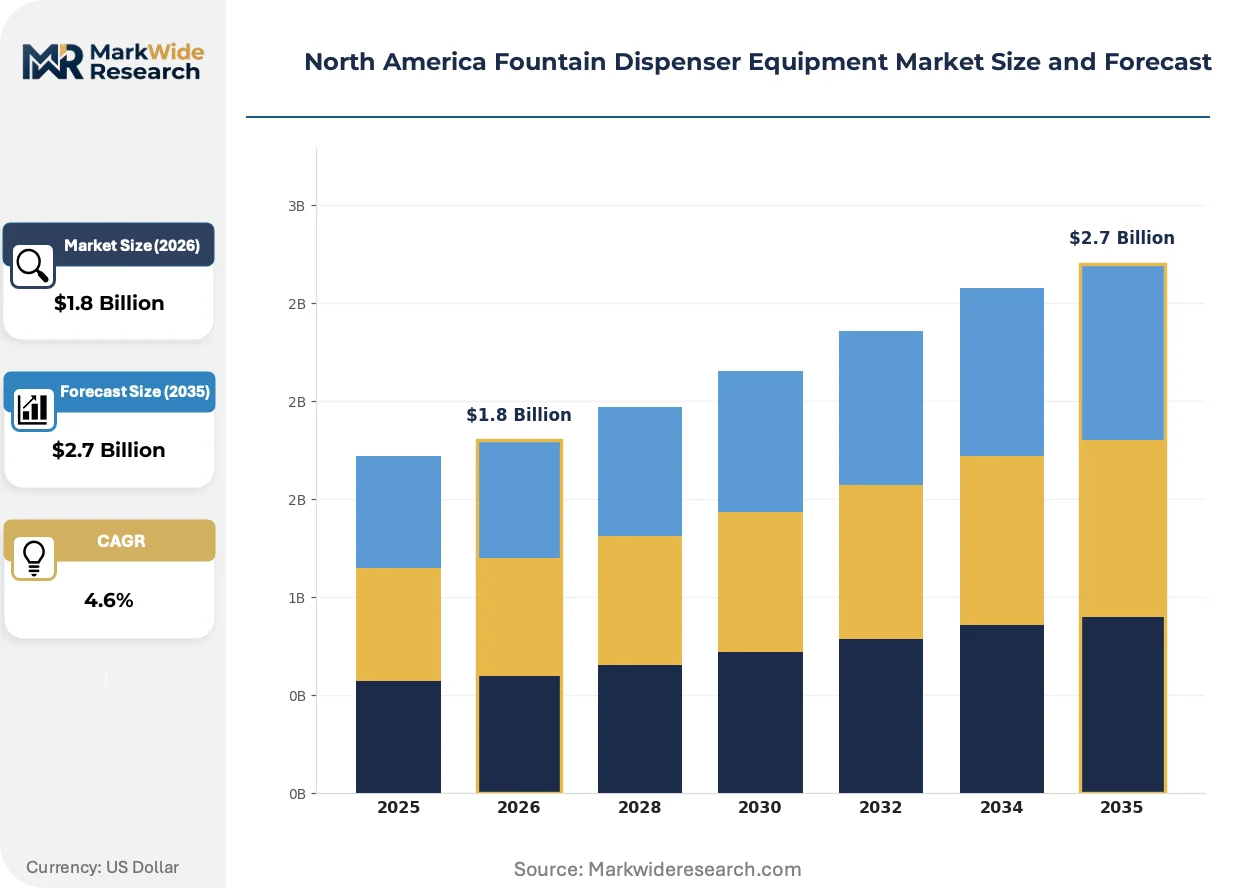
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonated Dispensers, Juice Dispensers, Beverage Dispensing Systems, Syrup Pumps End User: Restaurants, Cafés, Cinemas, Fast Food Outlets Technology: Countertop Dispensers, Wall-Mounted Dispensers, Self-Service Systems, Connected Dispensers Installation: Indoor Installation, Outdoor Installation, Modular Systems, Custom Installations |
| Companies Covered | The Coca-Cola Company, PepsiCo, FBD Partnership, LP, Lancer Worldwide, Keurig Dr Pepper Inc., Cornelius, Manitowoc Ice, Multiplex, CELLI SPA, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fountain Dispenser Equipment Market Evolving Landscape
Connected dispenser platforms are reconfiguring competitive positioning across the installed base, with remote monitoring capabilities and automated cleaning systems emerging as primary differentiators in chain procurement decisions.
Telemetry-enabled fountain dispensers is overtaking conventional electromechanical models in new chain deployments. These systems transmit real-time inventory levels, calibration drift alerts, and sanitation cycle confirmations to centralized facilities management platforms. Major quick-service restaurant operators are specifying connected platforms in new-build specifications, compressing demand for non-telemetry equipment to replacement-only scenarios.
The FDA Food Code's emphasis on automated sanitation documentation is reshaping equipment design priorities. Manufacturers are integrating self-cleaning circuits and digital logging capabilities that satisfy inspector audit requirements without manual record-keeping. Quick-service chains operating across multiple state jurisdictions view this capability as essential for compliance consistency, particularly where local health departments maintain divergent inspection protocols.
After-sales service unbundling is altering procurement economics for mid-size operators. Rather than bundled maintenance contracts, buyers are selecting dispenser hardware on capital cost metrics while sourcing calibration and cleaning services through third-party facilities management providers. This pattern is most visible in the southeastern United States, where rapid chain expansion has outpaced manufacturer service network density.
North America Fountain Dispenser Equipment Market Segmentation
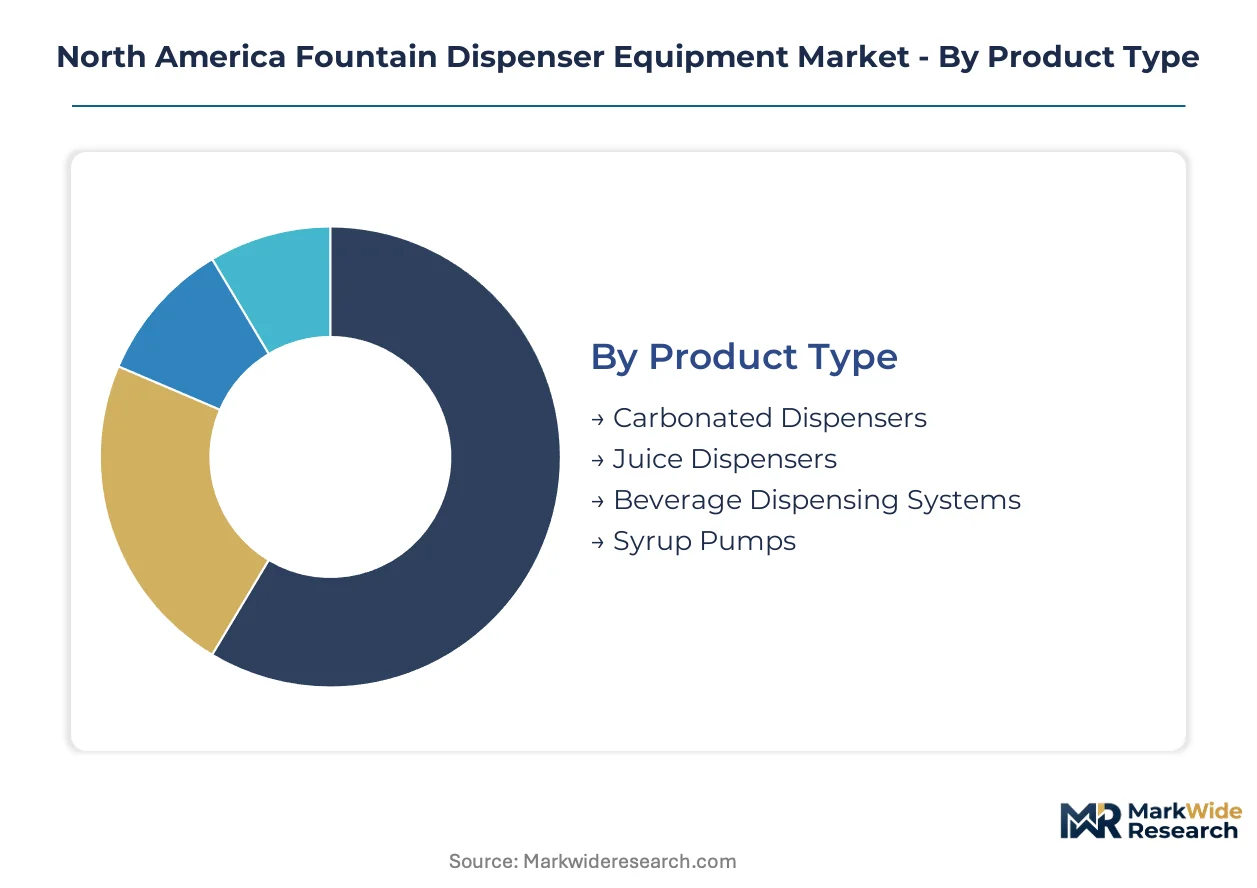
Equipment replacement cycles and upgrade trajectories vary sharply across segment boundaries in the fountain dispenser market. Procurement patterns diverge meaningfully between carbonated-heavy quick-service operators and precision-brix café installations, with technology choices increasingly governing total cost of ownership calculations.
Product Type:
Upgrade timelines stretch longest for carbonated infrastructure, while non-carbonated categories command premium replacement economics.
- Carbonated Dispensers:Electromechanical systems mixing concentrated syrup with filtered water and carbon dioxide at 38-42°F, representing the dominant installed base across quick-service restaurant chains. Demand concentrates in the southeastern United States, where chain restaurant development outpaces other sub-regions and high-throughput carbonated towers remain standard equipment.
- Juice Dispensers:Precision-brix systems designed for non-carbonated concentrate dilution with enhanced cleanability protocols for pulp and acid exposure. Independent cafés and coffee chains in Canada present underpenetrated demand, driven by premium beverage attachment rates that exceed fast-food benchmarks.
- Beverage Dispensing Systems:Integrated platforms combining multiple dispensing modalities under unified refrigeration and control architectures.
- Syrup Pumps:Peristaltic and diaphragm pump mechanisms governing concentrate-to-water ratios across dispenser configurations.
Carbonated dispensers sit at the top of the volume ranking, with juice dispensers climbing the fastest.
End User:
Margin structures and throughput requirements create distinct equipment specification patterns across buyer categories.
- Restaurants:Full-service operators deploying fountain equipment as ancillary beverage service with moderate throughput demands and labor-mediated dispensing models.
- Cafés:Precision-focused installations emphasizing brix accuracy for premium beverage consistency and customer-perceived quality differentiation.
- Cinemas:High-volume, peak-demand environments requiring rapid-fill capabilities during intermission intervals and concession rushes.
- Fast Food Outlets:Quick-service chains generating the highest throughput volumes, with self-service beverage programs expanding across the United States and Canada to reduce labor touchpoints during peak traffic periods.
Fast food outlets anchor volume demand, while cafés deliver the steepest margin expansion trajectory.
Technology:
Connected capabilities are reconfiguring competitive positioning across the installed base, with remote monitoring emerging as a primary procurement differentiator.
- Countertop Dispensers:Compact footprint units designed for space-constrained environments with reduced syrup line complexity.
- Wall-Mounted Dispensers:Floor-space-efficient configurations common in narrow-format quick-service layouts and food court installations.
- Self-Service Systems:Customer-facing dispensing platforms with integrated payment and portion control mechanisms, scaling across quick-service restaurant chains to improve throughput during peak periods.
- Connected Dispensers:Telemetry-enabled platforms transmitting real-time inventory levels, calibration drift alerts, and sanitation cycle confirmations to centralized facilities management platforms, representing the fastest-expanding technology category as operators prioritize remote diagnostics and inventory telemetry.
Connected dispensers are gaining share fastest, while countertop units retain the largest existing installed base.
Installation:
Site constraints and mobility requirements drive divergent engineering specifications and service network dependencies.
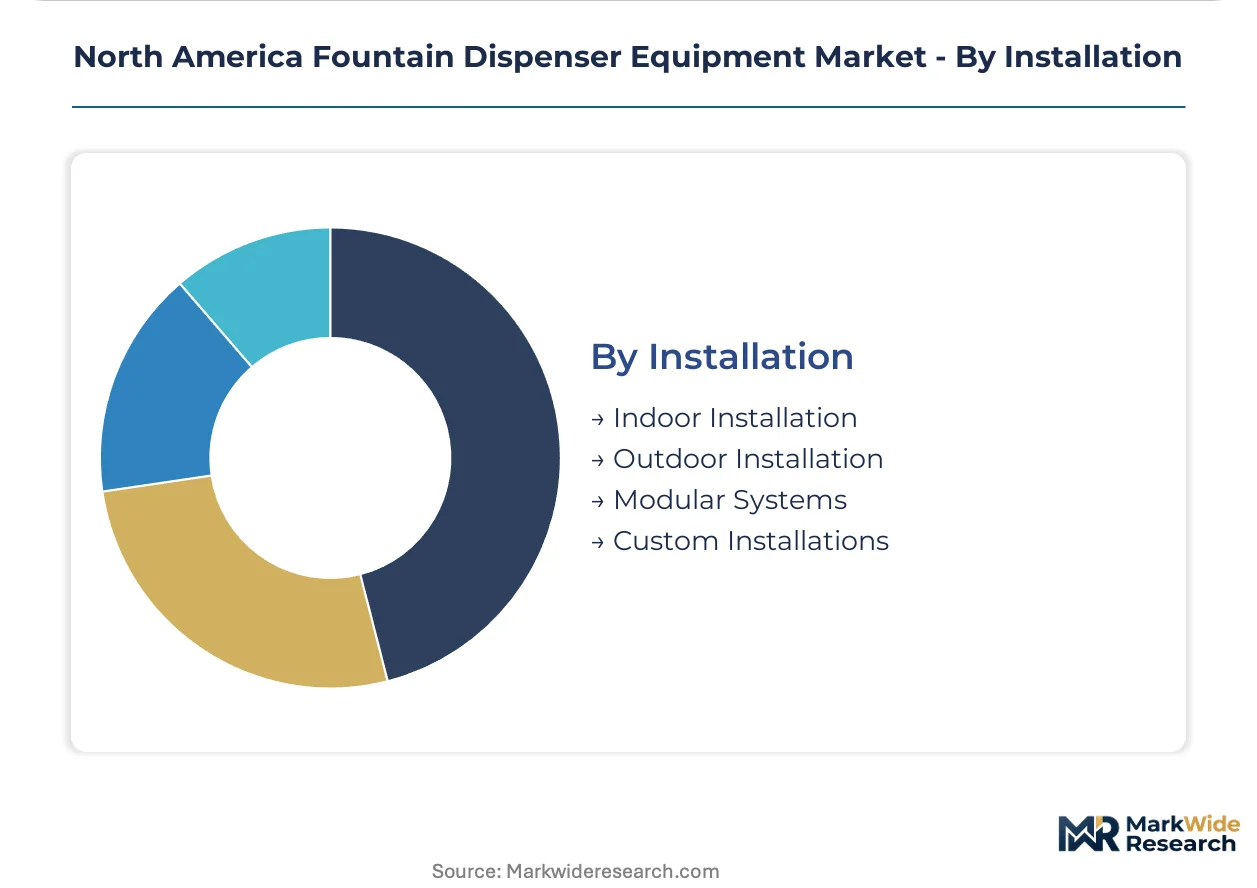
- Indoor Installation:Climate-controlled environments with standard electrical and plumbing infrastructure, dominating chain restaurant construction.
- Outdoor Installation:Weather-hardened configurations for stadiums, festivals, and food trucks, with NHTSA transport refrigeration regulations reshaping syrup logistics infrastructure for mobile deployments.
- Modular Systems:Staged upgrade pathways allowing technology convergence between electromechanical mixing systems and IoT-enabled telemetry modules without full equipment replacement.
- Custom Installations:Engineered-to-specification deployments for major chains requiring high-volume, site-specific configurations with specialized technician expertise for integration.
Indoor installation dominates the existing base, with modular systems showing the most rapid adoption acceleration among mid-size operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fountain dispenser equipment originated in the United States during the early twentieth century, when soda fountains became fixtures of American drugstores and diners. The technology scaled through postwar quick-service restaurant expansion, with Canada and Mexico developing parallel demand patterns shaped by cross-border chain operations.
United States
Self-service beverage programs at quick-service chains drive equipment refresh cycles, particularly in high-traffic southeastern markets where restaurant construction outpaces national averages. FDA Food Code updates on sanitation documentation accelerate migration toward connected dispenser platforms with automated compliance logging. Atlanta and Dallas-Fort Worth anchor concentrated demand for high-volume carbonated installations serving major chain headquarters.
Canada
Independent cafés and coffee chains present underpenetrated demand for precision-brix dispensers supporting premium beverage margins above fast-food benchmarks. Health Canada equipment certification requirements align with NSF International standards, streamlining cross-border procurement for US-based manufacturers. Toronto and Vancouver metropolitan areas concentrate café-format development, driving differentiated specification patterns from carbonated-heavy quick-service deployments.
Mexico
Quick-service chain expansion through franchise development creates pull for durable, high-throughput dispenser configurations in climate-variable operating conditions. Mexican federal sanitary regulations under COFEPRIS govern commercial food equipment standards, with enforcement patterns varying across state jurisdictions. Mexico City and Monterrey anchor concentrated demand, with Guadalajara emerging as a secondary hub for chain restaurant development.
North America Fountain Dispenser Equipment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration and service bundling dimensions, with connected platform capabilities commanding procurement preference in new-build specifications. The vendor base spans three tiers: engineering-focused custom specialists, beverage conglomerates leveraging captive syrup agreements, and manufacturing-scale automated systems producers. Consolidation pressure concentrates among mid-size fabricators lacking telemetry development resources. Dominant competitive moves include strategic partnerships between equipment manufacturers and facilities management platforms, plus portfolio diversification into modular retrofit kits.
Within the engineering-specialist tier, FBD Partnership, LP and Lancer Worldwide occupy positions defined by manufacturing depth and service network scale. PepsiCo anchors the beverage-captive tier through equipment placement tied to syrup supply agreements. These three entities exemplify divergent strategic postures: custom engineering focus, automated systems manufacturing scale, and vertical channel control through beverage supply integration.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo |
| FBD Partnership, LP |
| Lancer Worldwide |
| Keurig Dr Pepper Inc. |
| Cornelius |
| Manitowoc Ice |
| Multiplex |
| CELLI SPA |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up specialist fabricators dominate the North American fountain dispenser installed base, concentrating manufacturing assets in the southeastern United States and exercising pricing discipline through captive service bundling that locks mid-size operators into long-term maintenance contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement decisions, with premium tiers commanding spreads based on NSF International certification grade and integrated telemetry capabilities. Price differentiation centers on after-sales service bundling and customization depth for high-volume chain deployments. Cost compression in the standard tier is intensifying because stainless steel input volatility compresses margin predictability for manufacturers. Independent cafés exhibit the highest price sensitivity due to limited capital deployment flexibility, while major quick-service chains prioritize total cost of ownership over upfront equipment expenditure.
Supply Chain Analysis
Domestic-content mandates under the FDA Food Code and NSF International certification requirements are reshaping sourcing patterns toward North American fabrication facilities with validated cleanability protocols. Equipment chassis and dispensing towers draw heavily from stainless steel suppliers in the United States, Mexico, and Canada, with peristaltic pump mechanisms and refrigeration compressors anchored in specialized component manufacturing clusters. Single-source vulnerability concentrates in precision brix control sensors sourced from limited qualified suppliers. Distribution runs through manufacturer-direct channels for major chains and foodservice equipment distributors serving independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Fountain Dispenser Equipment Market functions as a regulatory compounder, with FDA Food Code sanitation documentation requirements accelerating equipment refresh cycles and expanding the addressable base for connected dispenser platforms.
For Market Incumbents: Acquire telemetry development capabilities to defend against modular retrofit specialists eroding installed base stickiness. Consolidate service network density in the southeastern United States where chain expansion has outpaced manufacturer support infrastructure. Deepen backward integration into stainless steel fabrication to buffer commodity price volatility and protect margin structures. For New Entrants and Emerging Players: Precision-brix telemetry modules for café-format installations offer the most penetrable white-space target, as independent coffee chains in Canada and metropolitan U.S. markets remain underserved by incumbent connected platforms. Target mobile and outdoor installation segments where NHTSA transport refrigeration compliance creates specification barriers for legacy suppliers. Pursue direct partnerships with third-party facilities management platforms as the primary go-to-market angle to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-size fabricators lacking IoT development resources but holding established NSF International certification portfolios and regional service footprints. The five-to-ten-year viability window favors targets with modular retrofit kit capabilities that bridge legacy carbonated towers toward connected compliance. Watch FDA enforcement variance across state health departments as the signal indicating acceleration or deceleration in connected platform migration timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry Platform Integration | Remote diagnostics capabilities satisfy FDA Food Code automated logging requirements across multi-jurisdiction operators. |
| Modular Retrofit Kit Development | Staged upgrade pathways lower adoption barriers for mid-size operators with sunk carbonated tower capital. |
| Service Network Expansion | Densified technician coverage in the southeastern United States captures demand from rapid chain restaurant construction. |
| Precision-Brix Café Specialization | Premium beverage attachment rates in independent coffee chains exceed fast-food benchmarks and support margin expansion. |
| Mobile Installation Certification | NHTSA-compliant transport refrigeration configurations open stadium, festival, and food truck deployment opportunities. |
Research Methodology
Bottom-up quick-service restaurant and café modeling reconciled against top-down equipment shipment tracking forms the analytical core of this study. Primary interviews with chain procurement directors, facilities management executives, foodservice equipment distributors, and NSF International certification auditors combined with secondary validation from FDA Food Code regulatory filings, SEC 10-K disclosures of publicly traded beverage conglomerates, and foodservice equipment customs data. Triangulation between demand-side installation patterns and supply-side manufacturing capacity ensures cross-verified market sizing.
Input-output matrices map syrup consumption volumes to installed dispenser counts across carbonated, non-carbonated, and precision-brix product categories throughout the projection horizon. Segmentation dimensions include product type, end-user format, technology tier, and installation environment, with CAGRs derived from regression analysis of replacement cycle timing and regulatory compliance-driven upgrade acceleration. Forecast inputs incorporate stainless steel price indices, chain restaurant construction permits, and state-level health department inspection protocol variance.
The model holds under stable FDA enforcement patterns and moderate commodity price fluctuation; deviation in trade policy affecting Mexican component sourcing or accelerated state-level sanitation documentation mandates would shift equipment migration timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
900 Series Cooking Equipment Market
Food Service Equipment
Warewashing Equipment Market
Food Service Equipment
Beverage Refrigeration Market
Food Service Equipment
Commercial Rotisserie Oven Market
Food Service Equipment
Back Bar Coolers Market
Food Service Equipment
France Smokeless Indoor Grills Market
Food Service Equipment
Food Trays and Bowls Market
Food Service Equipment
Used Commercial Kitchen Equipment Market
Food Service Equipment
Smart Cooker Market
Food Service Equipment
Commercial Refrigerated Display Cabinet Market
Food Service Equipment
Cooking Hood Market
Food Service Equipment
Multi Cooker Market
Food Service Equipment
Catering Equipment Market
Food Service Equipment
Food Display Cabinet Market
Food Service Equipment
Ice Maker Market
Food Service Equipment
Hot Food Display Cabinet Market