
 Cooking Hood Market | 2026-2036
Cooking Hood Market Size, Share, and Industry Trends Forecast 2026-2036
Cooking Hood Market Intelligence
The integration of smart features and designer aesthetics is repositioning the premium segment away from the function-focused commodity tier. Elica S.p.A. specializes in high-design island and wall-mounted hoods with advanced air quality sensors. BSH Home Appliances Group leverages its broad portfolio to compete across both premium connected models and mass-market under-cabinet units. Broan-NuTone sustains its position through strong distribution channels in the North American residential replacement market.
A cooking hood is an appliance containing a mechanical fan that removes airborne grease, smoke, and heat from above a stove. Performance is measured in cubic feet per minute (CFM), with residential models typically ranging from 100 to over 1200 CFM. While under-cabinet models dominate the residential volume market due to renovation cycles, island hoods command higher price points. The smart technology segment, though small, represents the fastest-growing category as homeowners seek integrated kitchen ecosystems.
Energy efficiency standards, such as the EPA's ENERGY STAR program in the United States, influence product design and component selection. In parallel, CE marking in Europe mandates safety and performance criteria, while China's GB standards set minimum airflow and noise level requirements. Navigating these divergent regional standards while managing component costs remains a central challenge for manufacturers.
Market Dynamics
The cooking hood market's evolution is driven by the convergence of smart home technology with increasingly stringent regional energy efficiency and air quality regulations. This dual pressure forces manufacturers to innovate on both connectivity and core component performance, altering product design and cost structures.
Growth Catalysts
- Urban Residential Construction:New high-density housing developments, particularly across China and other parts of Asia, incorporate modern kitchens with dedicated ventilation, creating baseline demand for new units.
- Smart Home Integration:The expansion of IoT into kitchen appliances provides a new growth vector, as homeowners seek integrated ecosystems that automate functions like ventilation based on cooking activity.
- Indoor Air Quality Standards:Stricter residential building codes and programs like the EPA's ENERGY STAR for ventilated fans incentivize the adoption of higher-performance, certified hoods in new construction and renovations.
Market Restraints
- Component Cost Volatility:Fluctuations in the prices of stainless steel, copper for motors, and electronic components create margin pressure, especially in the high-volume, price-sensitive under-cabinet segment.
- Performance Trade-offs:A persistent engineering constraint is the trade-off between high airflow capacity, measured in CFM, and low operational noise, measured in sones, which can limit design choices.
- Divergent Regional Standards:Manufacturers face complexity and higher certification costs navigating disparate requirements, such as Europe's CE marking for safety and China's GB standards for airflow and noise.
Strategic Opportunities
- Designer and Custom Segments:There is an opportunity to develop premium hoods as architectural centerpieces, integrating unique materials and collaborating with kitchen designers for high-end residential projects.
- System Integration:Developing hoods that integrate with whole-home HVAC and air purification systems offers a path to capture more value by positioning the hood as a central air quality device.
- Aftermarket Services:Subscription services for filter replacements, performance monitoring, and software updates for smart hoods can create recurring revenue streams beyond the initial hardware sale.
Industry Challenges
- Multi-Platform Interoperability:Ensuring a smart hood can seamlessly connect and function with the fragmented ecosystem of home automation platforms from Google, Amazon, and Apple remains a significant software development challenge.
- Channel Conflict:Balancing the needs of established big-box retail and wholesale distribution channels with the growth of direct-to-consumer online sales for premium models creates potential conflict.
- Certification Lead Times:The time and expense required to secure certifications like ENERGY STAR or to comply with CE marking for new product introductions can delay market entry and increase R&D costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cooking Hood Market |
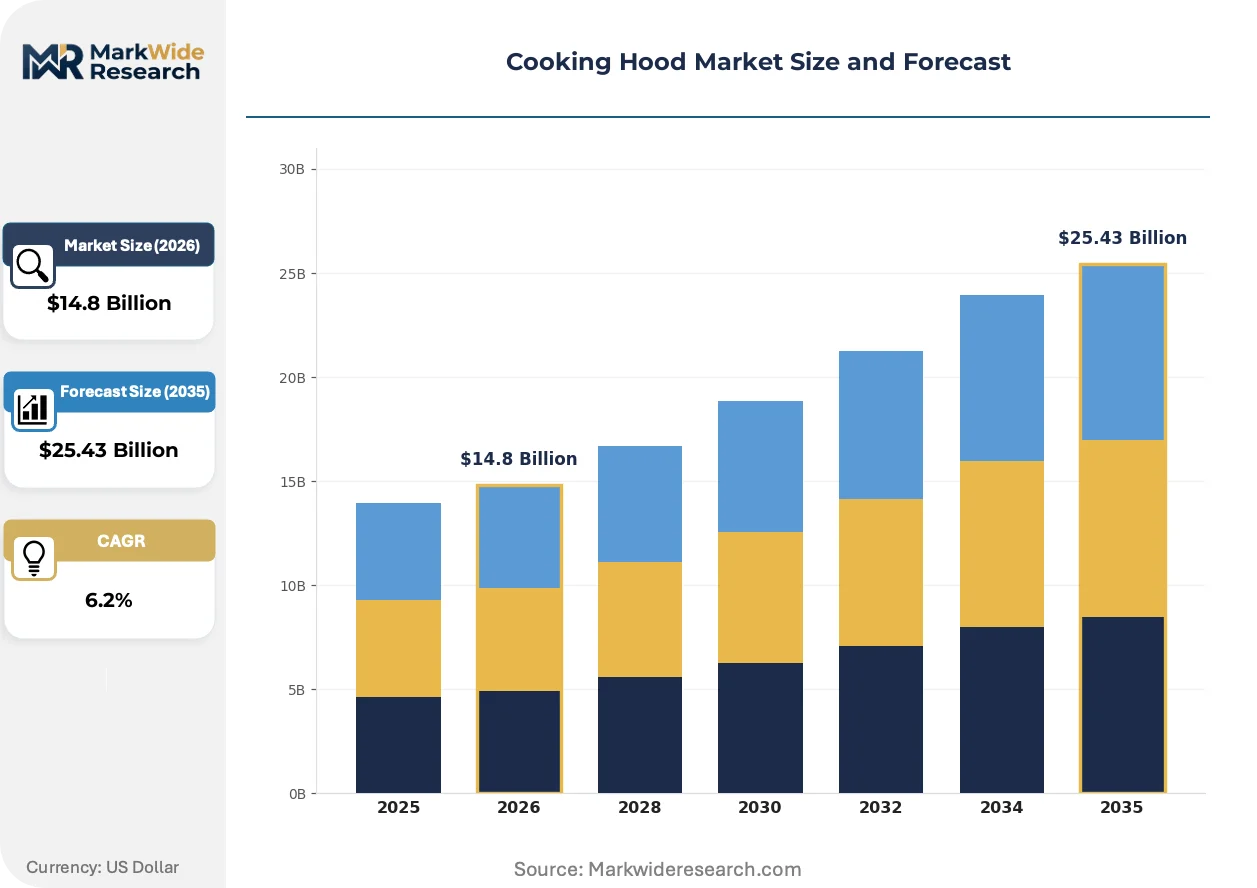
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Under-Cabinet, Island, Downdraft Technology: Ventless, Ducted, Hybrid, Smart End User: Residential, Commercial Kitchens, Restaurants, Hotels Installation Type: Fixed, Portable, Ceiling-Mounted, Under-Counter |
| Companies Covered | BSH Home Appliances Group, Elica S.p.A., Faber, Broan-NuTone, AB Electrolux, Falmec, Whirlpool Corporation, GE Appliances, Zephyr Ventilation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cooking Hood Market Strategic Shifts & Innovations
The appliance's identity is shifting from a purely functional exhaust system to a central element of kitchen design and home wellness. This transformation is reshaping product development, focusing on aesthetics, automated performance, and energy efficiency in equal measure.
Automated ventilation sensors, which use infrared or particulate detectors to monitor the cooktop, are a key product evolution. The premium residential construction and renovation segments are the earliest adopters of this technology. This hands-free, responsive functionality is rewriting the user experience, turning ventilation from a manual chore into an automated background process that optimizes air quality and energy use.
Energy efficiency mandates, including the EPA's ENERGY STAR program and Europe's Ecodesign directives, influence component selection across the industry. These regulations compel manufacturers to adopt more efficient brushless DC motors and integrated LED lighting to meet performance-per-watt targets. The mass-market under-cabinet segment is most affected, as cost pressures make it difficult to absorb the expense of these advanced components without raising prices.
A notable behavioral shift is the increasing influence of kitchen designers and architects in the selection process, especially for premium models. This trend disrupts the traditional consumer path of purchasing from a home appliance retailer late in a project. This dynamic is most pronounced in the high-end island and custom-built hood segments, where the appliance's aesthetic integration is a primary consideration from the project's inception.
Cooking Hood Market Segmentation
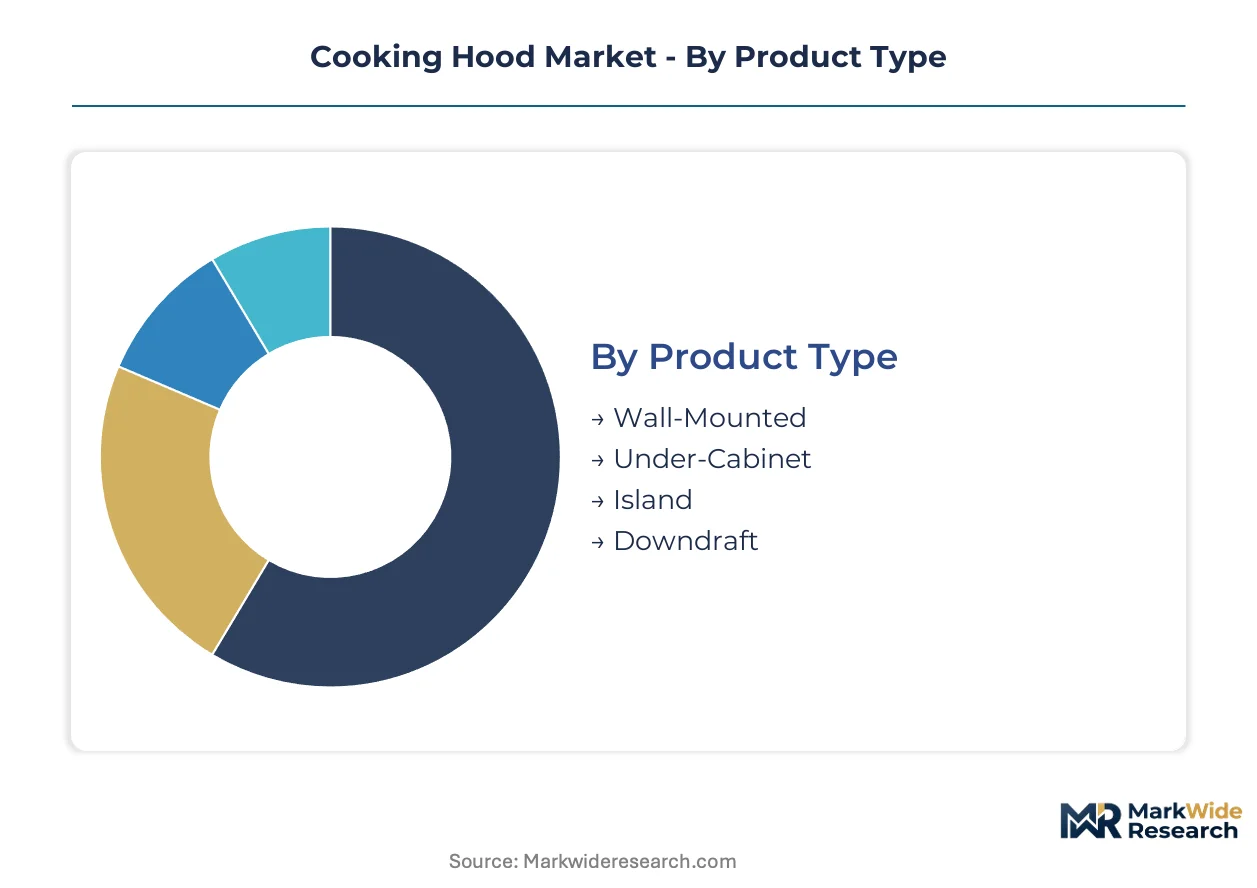
The cooking hood market segments based on distinct product characteristics, technological sophistication, end-user applications, and installation methods. This differentiation allows manufacturers to target specific consumer needs and navigate varying regulatory landscapes across residential and commercial sectors.
Product Type:
Manufacturers face varying certification burdens and design complexities across different product types, influenced by regional energy efficiency and safety standards like ENERGY STAR or CE marking.
- Under-Cabinet:These compact units fit beneath kitchen cabinetry, offering a space-efficient ventilation solution common in residential settings. Demand concentrates in the North American residential replacement market due to renovation cycles and cost-effectiveness.
- Island:Positioned above kitchen islands, these hoods often serve as architectural centerpieces, integrating high design with advanced ventilation capabilities. Demand is particularly strong in high-end residential construction and custom kitchen projects, driven by aesthetic integration and premium performance.
- Wall-Mounted:Traditional and versatile, these hoods attach directly to a kitchen wall above the range, providing direct exhaust.
- Downdraft:Integrated into the cooktop or countertop, these systems discreetly pull smoke and odors downward, offering an unobtrusive design.
Leading the category by volume: Under-Cabinet. Growing fastest: Island.
Technology:
Functional performance and installation flexibility are key differentiators within cooking hood technology, influencing efficacy and user experience.
- Smart:These hoods integrate automated ventilation sensors, IoT connectivity, and app control for responsive, hands-free operation. Homeowners seeking integrated kitchen ecosystems drive demand for convenience and optimized air quality automation.
- Ducted:These systems vent cooking fumes directly outside the home through a ductwork system, providing the most effective removal of grease, smoke, and odors. They are the performance benchmark for traditional and commercial applications requiring high CFM.
- Ventless:Also known as recirculating hoods, these units filter air and reintroduce it into the kitchen, suitable for installations where external ducting is not feasible.
- Hybrid:Combining features of both ducted and ventless systems, these hoods offer flexibility in installation and operation, adapting to various kitchen layouts.
The market's largest segment by unit sales is Ducted technology. The Smart technology segment is gaining share fastest.
End User:
Distinct operational requirements and usage scales define end-user segments, influencing product specifications, durability, and regulatory compliance.
- Residential:This segment includes single-family homes, multi-unit dwellings, and apartments, focusing on energy-efficient and aesthetically pleasing models for personal comfort. New housing developments and renovation cycles are primary demand drivers.
- Restaurants:Commercial kitchens in restaurants demand heavy-duty, high-CFM hoods with robust construction and often integrated fire suppression systems to meet stringent safety and hygiene standards. Continuous operation and high-volume cooking characterize this demand.
- Commercial Kitchens:This category encompasses institutional kitchens in schools, hospitals, and corporate cafeterias, requiring large-scale ventilation solutions.
- Hotels:Hotels utilize cooking hoods in guest room kitchenettes, banquet facilities, and on-site dining establishments, balancing design with performance.
The Residential segment generates the majority of market demand. Restaurants represent a high-value, specialized segment.
Installation Type:
Spatial integration and aesthetic impact significantly influence choices within installation types, particularly in modern kitchen design.
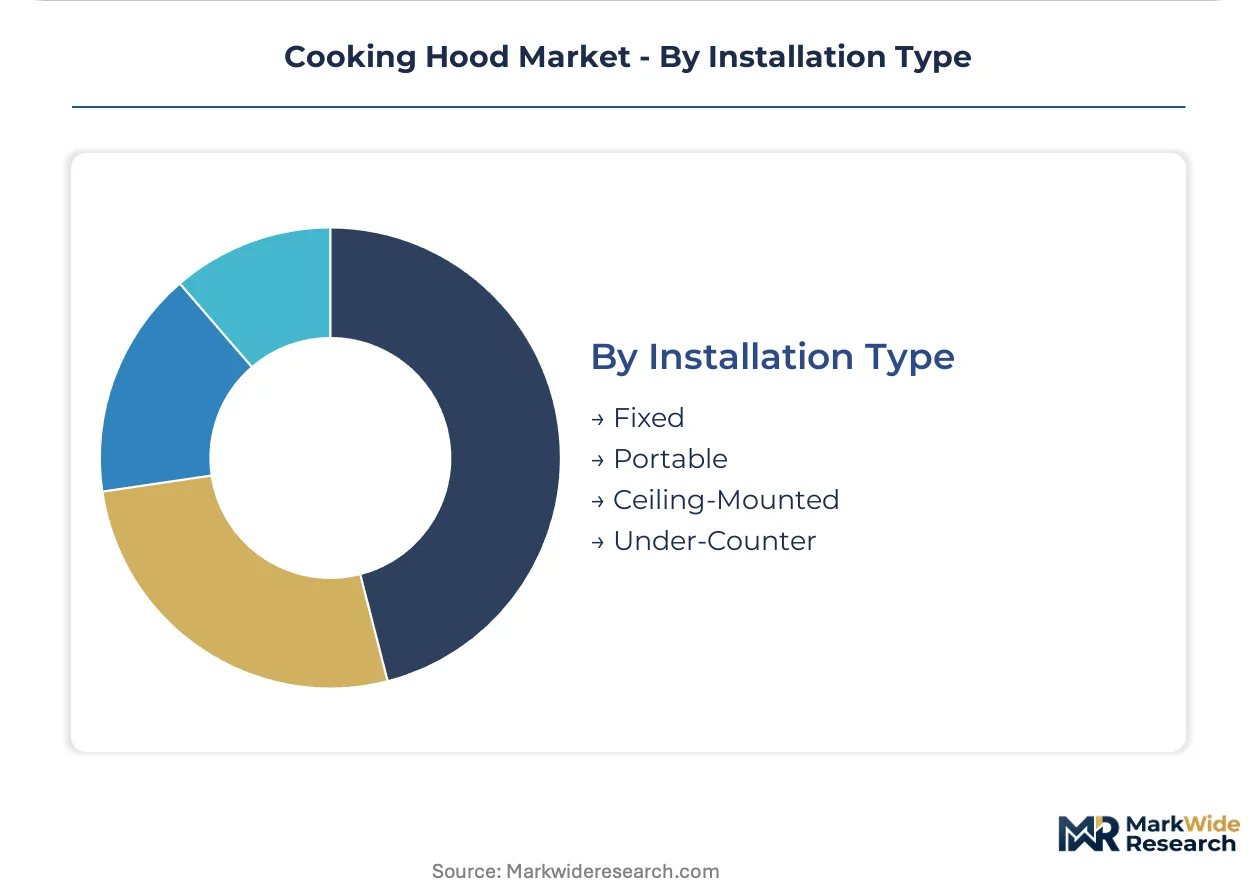
- Fixed:This broad category includes permanently installed units like wall-mounted, under-cabinet, and island hoods, representing the majority of market volume. Fixed installations are standard in most kitchen designs, prioritizing reliability and established practice.
- Ceiling-Mounted:Integrated directly into the ceiling, these hoods offer a minimalist aesthetic and are favored in modern, open-concept kitchens where an unobstructed view is desired. Demand is driven by architectural integration and premium design appeal.
- Portable:Compact and often ventless, these units are designed for temporary use or in spaces without permanent ventilation infrastructure.
- Under-Counter:These discreet units are built into the cabinetry below the countertop, typically used for specialized cooking stations or secondary ventilation.
Fixed installations dominate the market by volume. The Ceiling-Mounted category reflects evolving design preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's rapid urbanization and modern residential construction drive significant demand for cooking hoods. These developments often integrate advanced kitchen appliances. This creates a baseline for both functional and aesthetically driven ventilation solutions across the country.
China
New urban housing developments across China generate substantial demand for cooking hoods. China's GB standards mandate minimum airflow and noise level requirements for these appliances. The Yangtze River Delta region, with its dense urban centers, sees high adoption of integrated kitchen systems.
United States
Residential replacement cycles in the United States fuel consistent demand for under-cabinet and wall-mounted units. The EPA's ENERGY STAR program incentivizes the adoption of energy-efficient ventilation fans. North American residential replacement markets, especially in established suburban areas, prioritize ease of installation.
Germany
German consumers prioritize high-design aesthetics and advanced functionality in their kitchen appliances. CE marking ensures safety and performance compliance for all cooking hoods sold within the European Union. Bavaria's strong manufacturing base supports the production of premium, technologically sophisticated models.
India
The expanding middle class and new construction projects in India contribute to rising cooking hood demand. India's Bureau of Indian Standards (BIS) guides product quality and safety for consumer appliances. Delhi-NCR's burgeoning housing sector drives volume sales for both ducted and ventless systems.
Italy
Italian homeowners seek cooking hoods that blend high design with effective ventilation performance. Europe's Ecodesign directives influence component selection towards greater energy efficiency across the market. Milan's design-centric kitchen industry often integrates island hoods as central architectural features.
Cooking Hood Market Key Industry Players
Premium-margin players sit above commodity-margin players across product sophistication and design integration. The market structure is tiered, featuring specialized design-focused manufacturers, broad-portfolio appliance conglomerates, and regional specialists. Companies pursue portfolio diversification and strategic partnerships to capture value across segments.
On the premium-tier vector, Elica S.p.A. exemplifies high-design island and wall-mounted hoods with advanced air quality sensors. BSH Home Appliances Group, a German-based conglomerate, occupies a position across both premium connected models and mass-market under-cabinet units. Broan-NuTone, an American company, anchors the North American residential replacement market through robust distribution channels.
| Leading Market Players |
|---|
| BSH Home Appliances Group |
| Elica S.p.A. |
| Faber |
| Broan-NuTone |
| AB Electrolux |
| Falmec |
| Whirlpool Corporation |
| GE Appliances |
| Zephyr Ventilation |
| Others |
Cost & Logistics Intelligence
Stainless steel and electronic components, critical inputs for cooking hood manufacturing, trace their path from global suppliers through tiered pricing structures for downstream residential and commercial buyers. These material costs significantly influence final product pricing across both premium and volume segments.
Pricing Analysis
Ventilation performance and aesthetic integration anchor value-based pricing in the cooking hood market, particularly for high-end island and designer models. Price differentiation stems from advanced features like automated sensors and IoT connectivity, alongside brand premium and compliance with ENERGY STAR or CE marking certifications. Pricing pressure stems from component cost volatility, especially in the mass-market under-cabinet segment. Residential buyers of basic under-cabinet units exhibit the highest price sensitivity, while custom kitchen project clients prioritize design and performance over cost.
Supply Chain Analysis
Electronic component supply for smart cooking hoods draws heavily from manufacturers in China and Germany, alongside specialized motor and sensor producers. Key raw material dependencies include stainless steel and copper for motors. Component cost volatility represents a significant structural risk across the supply chain. Distribution runs through established big-box retail channels for mass-market units and specialized kitchen design showrooms for premium, custom-built models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is in a technology-transition phase, with IoT-enabled automated ventilation replacing traditional manual exhaust systems across residential kitchens.
For Market Incumbents: To counter component cost volatility and emerging smart technology entrants, incumbents must diversify their product portfolios to include both premium connected models and cost-effective under-cabinet units. Investing in certification for energy efficiency, such as EPA's ENERGY STAR program, can also reinforce market position. Strategic partnerships with smart home platform developers will extend ecosystem integration capabilities.
For New Entrants and Emerging Players: Launch via direct-to-consumer online channels, targeting homeowners seeking integrated kitchen ecosystems with advanced air quality features. White-space opportunities exist in developing custom-built, architecturally integrated hoods for high-end residential projects and offering subscription services for filter replacements. Collaborating with kitchen designers provides a direct go-to-market angle for premium offerings.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized design-focused manufacturers in Europe with strong intellectual property in smart ventilation technology. The cooking hood market remains a long-term viable segment due to its essential function in modern kitchens and evolving smart home integration trends. A signal to watch for inflection is the widespread adoption rates of automated ventilation sensors in new residential construction.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate advanced automated ventilation sensors | Enhances user experience and air quality optimization for premium residential consumers. |
| Expand direct-to-consumer sales channels | Captures higher margins and direct customer feedback for specialized product lines. |
| Invest in regional energy efficiency certifications | Ensures compliance and market access in regulated geographies like the United States and Europe. |
| Develop recurring aftermarket service offerings | Creates stable revenue streams beyond initial hardware sales for smart hood users. |
| Form strategic alliances with smart home platforms | Ensures seamless interoperability within broader integrated kitchen ecosystems for homeowners. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, complemented by primary interviews with kitchen designers, appliance manufacturers' R&D leads, retail buyers, and smart home platform developers. This approach combined qualitative insights with quantitative data, triangulating findings from both top-down market sizing and bottom-up demand analysis.
Market volume and value were modeled at a granular level across product type, technology, end user, installation type, and regional regulatory compliance over the projection horizon. Compound annual growth rates were derived from historical data analysis and projected market drivers such as urban housing starts and smart home adoption rates. The analytical framework integrated these specific industry inputs to forecast future market trajectories.
The model assumes a particular technology adoption path; alternative pathways for smart home integration or shifts in energy efficiency mandates would alter the outlook. Forecasts reflect assumptions regarding component cost stability and evolving consumer preferences. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Draught Beer Chiller Market
Food Service Equipment
Scroll Chiller Market
Food Service Equipment
Global Refrigerated Display Cases and Chilled Rooms Market
Food Service Equipment
Prepared Food Equipment Market
Food Service Equipment
Europe Commercial Dishwashers Market
Food Service Equipment
Global Commercial Cooking Equipment Market
Food Service Equipment
Slow Cooker and Sous Vide Market
Food Service Equipment
Ice Cube Tray Market
Food Service Equipment
Commercial Stainless Steel Cooking Equipment Market
Food Service Equipment
Meal Delivery Carts and Racks Market
Food Service Equipment
Kegerator Equipment Market
Food Service Equipment
Food Thermos Market
Food Service Equipment
Commercial Panini Grills Market
Food Service Equipment
Commercial Steamer Market
Food Service Equipment
Global Roti Maker Market
Food Service Equipment
Electric Commercial Deep Fryers Market