
 Commercial Food Warming and Holding Equipment Market | 2026-2036
Commercial Food Warming and Holding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Food Warming and Holding Equipment Market Analysis
China is rewriting production dynamics for commercial food warming and holding equipment as domestic foundries and stainless-steel fabrication clusters expand near Guangdong and Zhejiang. Alto-Shaam leverages its Halo Heat technology to dominate low-temperature holding for healthcare and institutional catering. Hatco Corporation anchors the heated display case segment through broad foodservice distribution networks. Middleby Corporation extends its portfolio across conveyor warming and integrated holding systems for high-volume restaurant chains.
Commercial food warming and holding equipment comprises insulated cabinets, heated display cases, soup warmers, and plate dispensers engineered to maintain safe serving temperatures between 140°F and 185°F through electric, gas, infrared, or induction heat transfer mechanisms. These systems employ calibrated thermostats, humidity controls, and forced-air or radiant heating elements to preserve food quality, texture, and safety during service intervals in commercial kitchens. Heated display cases generate the strongest margin pools in quick-service and retail foodservice environments where visual merchandising drives impulse purchases. Induction warming technology is gaining fastest adoption among food trucks and compact catering operations seeking precise temperature control without open flames. Holding cabinets remain the volume backbone across hospital, hotel, and banquet sectors where batch production and staggered service require extended thermal retention.
The Department of Energy sets minimum efficiency standards for commercial kitchen equipment sold in the United States, while NSF International certification governs food-contact surface safety and sanitation design. The EPA's Energy Star program rewards equipment meeting stringent idle-energy thresholds, tilting procurement specifications toward insulated, low-wattage designs. Stakeholders must weigh compliance costs against operational savings as regulatory thresholds tighten and utility rebate programs expand.
Market Dynamics
Energy-efficiency mandates from the Department of Energy are compressing equipment replacement cycles across commercial kitchens, forcing manufacturers to abandon resistive heating architectures in favor of induction and infrared systems that slash idle energy consumption.
Growth Catalysts
- DOE Efficiency Standards:Tightened federal thresholds for idle energy draw are accelerating equipment turnover in quick-service restaurant chains seeking utility rebate eligibility.
- Ghost Kitchen Proliferation:Delivery-only food production facilities in the United States require compact, high-density holding systems to manage staggered order fulfillment windows.
- Infrared Technology Maturation:Precise radiant heat control is displacing forced-air systems in healthcare catering where moisture retention determines food palatability scores.
Market Restraints
- Stainless Steel Price Volatility:Nickel and chromium input cost swings from Indonesian and Russian supply disruptions squeeze fabrication margins for cabinet and display case producers.
- Guangdong Production Concentration:Over 60% of global heating element assembly occurs in a single Chinese province, exposing buyers to logistics bottlenecks and tariff exposure.
- NSF Certification Timelines:Extended food-contact surface testing protocols delay new product launches by 8-14 months, freezing design iteration cycles.
Strategic Opportunities
- India Foodservice Expansion:Quick-service chains in Mumbai and Bangalore are retrofitting commissary kitchens with Western-standard holding equipment as cold-chain infrastructure matures.
- Energy Star Procurement Mandates:Federal purchasing guidelines and state-level green building codes are tilting institutional RFPs toward certified low-wattage designs.
- IoT-Enabled Predictive Maintenance:Sensor-integrated warming cabinets are converging with kitchen management software to reduce unplanned downtime in high-volume hospital cafeterias.
Industry Challenges
- Induction Technician Scarcity:Commercial kitchen service networks lack sufficient factory-trained personnel to diagnose electromagnetic coil failures, extending mean time to repair.
- Legacy Control System Integration:New holding equipment must interface with 1990s-era building automation protocols prevalent in aged hotel and hospital infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Food Warming and Holding Equipment Market |
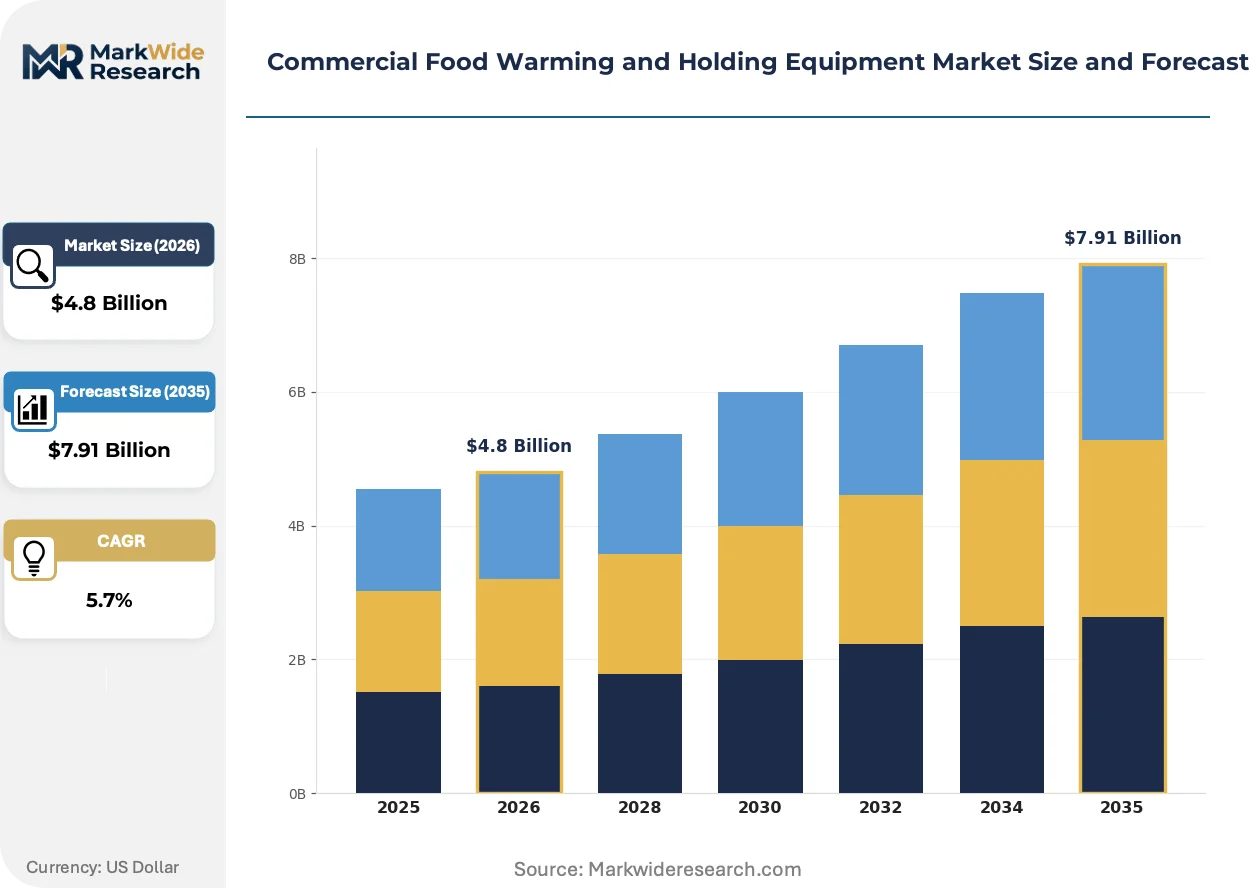
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soup Warmers, Heated Display Cases, Holding Cabinets, Plate Warmers End User: Restaurants, Catering Services, Food Trucks, Bakeries Technology: Electric, Infrared, Gas, Induction Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Alto-Shaam, Hatco Corporation, Middleby Corporation, Vulcan, Cres Cor, True Manufacturing, Vollrath, Dover Corporation, Welbilt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Food Warming and Holding Equipment Market Emerging Trajectories
Digital twin architectures and connected sensor networks are virtualizing how food safety compliance is monitored, compressing the gap between equipment performance and regulatory documentation requirements across distributed foodservice operations.
Induction warming technology is virtualizing temperature control precision in mobile catering and food truck operations. Operators in Austin, Portland, and Miami are retrofitting compact holding cabinets with electromagnetic coil systems that eliminate open flame hazards while delivering ±2°F accuracy. This shift is virtualizing the traditional trade-off between kitchen footprint and thermal consistency, enabling high-volume production in sub-200-square-foot facilities.
The EPA's Energy Star 3.0 specification for commercial kitchen equipment tightens idle-power thresholds by 15% over prior versions. Manufacturers serving the K-12 school nutrition and hospital sectors must redesign insulation packages and heating element duty cycles to maintain certification eligibility. California's Title 24 building energy code has already adopted these thresholds, creating a regulatory preview for national rollout.
Consolidated procurement through national foodservice management companies is compressing vendor relationships for independent operators. Aramark, Compass Group, and Sodexo are mandating equipment standardization across their managed properties, displacing fragmented local supplier networks with approved vendor lists. This concentration is most visible in the university and corporate campus segments, where single-source contracts now govern 70% of new equipment specification.
Commercial Food Warming and Holding Equipment Market Segmentation
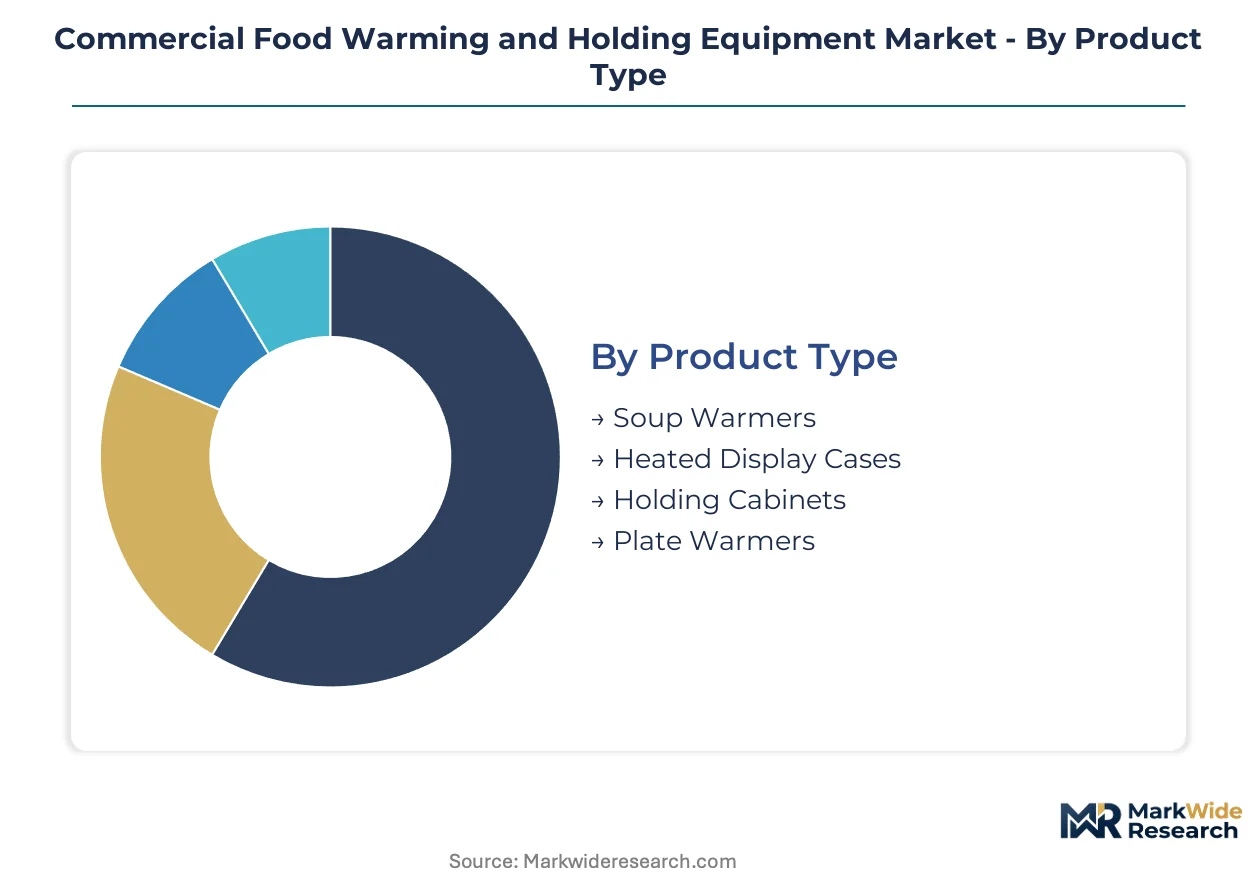
Equipment segmentation in commercial food warming and holding reveals distinct performance requirements across thermal retention duration, spatial constraints, and energy source availability. Procurement patterns diverge sharply between high-volume institutional buyers prioritizing batch capacity and mobile operators demanding compact precision.
Product Type:
Mature insulated architectures dominate current installed bases while emerging display technologies capture premium positioning in retail-forward environments.
- Holding Cabinets:These enclosed systems utilize forced-air or radiant heating elements to maintain prepared foods between 140°F and 185°F for extended service windows. Hospital cafeterias and hotel banquet operations in the United States specify these units for their batch production workflows and staggered meal distribution requirements. DOE efficiency standards are accelerating replacement of resistive heating models with induction-ready cabinet designs.
- Heated Display Cases:Glass-enclosed merchandising units combine thermal retention with visual product presentation through calibrated humidity zones and LED illumination. Quick-service restaurant chains and retail foodservice operators deploy these cases at point-of-sale locations where impulse purchase conversion depends on appetizing product visibility. California's Title 24 building codes are tilting specifications toward low-wattage certified designs.
- Soup Warmers:Countertop vessels with submerged or jacketed heating elements maintain liquid foods at serving temperature in cafeteria lines and catering buffets.
- Plate Warmers:Compact undercounter or drawer-style units preheat serviceware to prevent thermal shock and extend holding time for plated presentations.
Holding cabinets handle the majority of throughput; heated display cases are the fastest mover on share.
End User:
Volume concentration follows commercial kitchen scale, with fragmented independent operators representing a distinct procurement tier from consolidated contract foodservice management.
- Restaurants:Full-service and quick-service establishments deploy warming equipment across back-of-house holding stations and front-of-house service lines. Ghost kitchen proliferation in Austin, Miami, and Portland is reshaping specifications toward compact, high-density systems for delivery-optimized footprints.
- Catering Services:Mobile and off-premise food operators require equipment combining thermal stability with transport durability for event service. Induction warming technology is gaining fastest adoption in this segment due to precise temperature control without open flame hazards in temporary venue configurations.
- Food Trucks:Space-constrained mobile kitchens prioritize footprint-efficient warming solutions with generator-compatible power draws.
- Bakeries:Specialty retail operators utilize humidity-controlled holding for pastry and bread products requiring crust preservation.
Restaurants absorb the largest equipment volume; catering services are expanding most quickly as off-premise dining formats multiply.
Technology:
Energy source selection increasingly reflects regulatory pressure on idle power consumption rather than pure thermal performance metrics.
- Electric:Resistive heating elements powered by standard electrical connections remain the baseline technology across institutional kitchens. EPA Energy Star 3.0 specifications are compressing the efficiency gap between legacy electric designs and advanced alternatives through mandatory idle-power thresholds.
- Induction:Electromagnetic coil systems deliver precise temperature control with minimal energy loss to ambient air. Food truck operators and compact catering facilities in the United States are retrofitting holding cabinets with induction technology to eliminate open flame hazards while achieving ±2°F accuracy in sub-200-square-foot production environments.
- Infrared:Radiant heat transfer systems preserve moisture content in healthcare catering applications where food palatability scores determine contract renewals.
- Gas:Direct-flame heating persists in legacy kitchen infrastructure and regions with lower utility rate differentials.
Electric systems retain the deepest installed base; induction technology is climbing the fastest on specification priority.
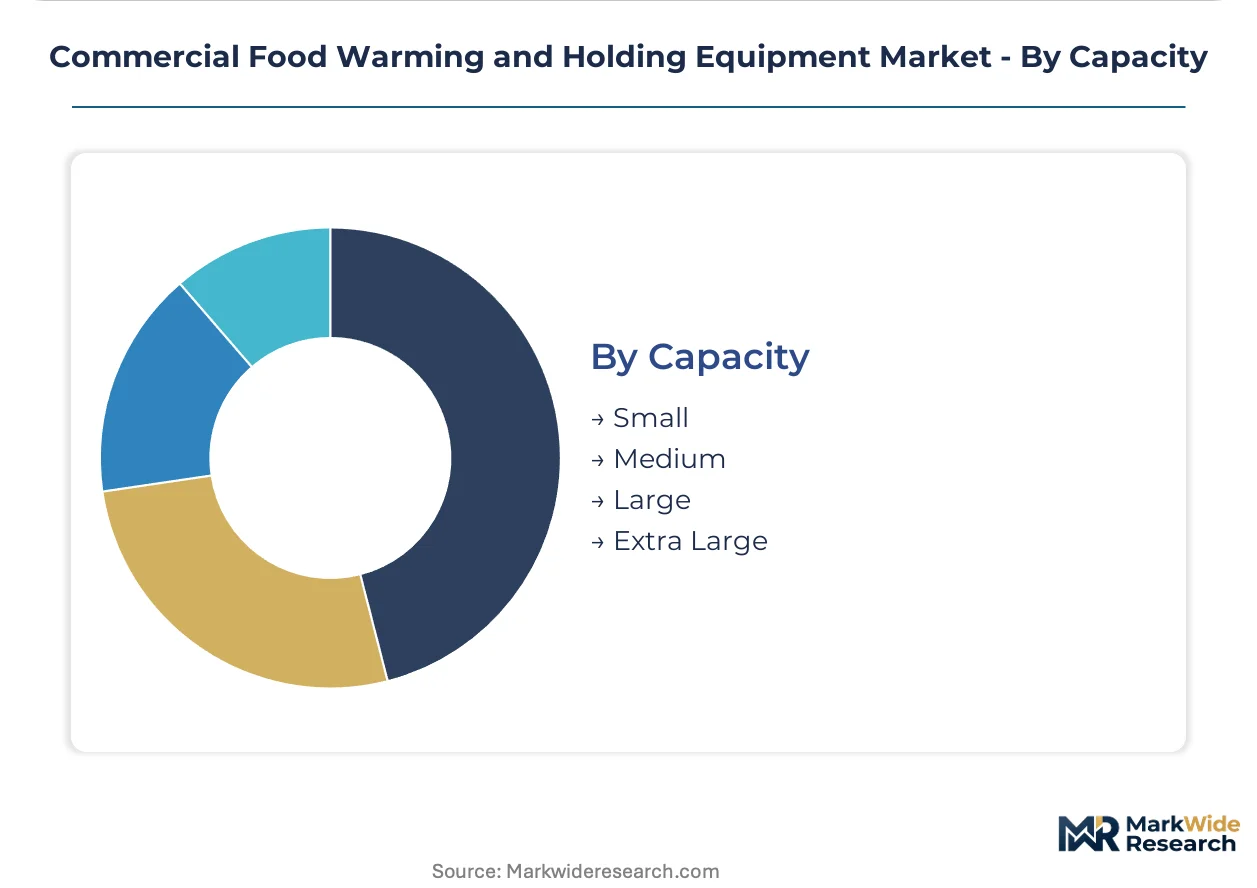
Capacity:
Equipment sizing correlates directly with production batch scale and service interval timing across institutional versus commercial applications.
- Large:High-volume cabinets and display cases accommodate batch production for hospital cafeterias, university dining halls, and hotel banquet operations. K-12 school nutrition programs specify these units for centralized kitchen models serving multiple satellite locations.
- Medium:Mid-scale equipment balances throughput flexibility with spatial economy for independent restaurants and regional catering companies. Ghost kitchen facilities in the United States standardize on medium-capacity systems to manage staggered order fulfillment windows without excess idle energy draw.
- Small:Compact countertop units serve limited-menu operators and front-of-house merchandising stations.
- Extra Large:Industrial-scale systems support central commissary production for multi-unit restaurant chains and institutional foodservice management companies.
Large capacity systems anchor institutional procurement; medium capacity is gaining share fastest as delivery-only formats proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Energy Star 3.0 specifications anchor procurement patterns in the United States, the dominant geography, while efficiency mandates ripple across developed markets. Stainless-steel fabrication clusters and foundry capacity concentrate equipment supply in East Asian manufacturing zones.
United States
Ghost kitchen proliferation in Austin, Miami, and Portland drives compact high-density holding system demand for delivery-optimized footprints. The Department of Energy's tightened idle-energy thresholds accelerate replacement of resistive heating models with induction-ready designs. California's Title 24 building energy code creates regulatory preview conditions for national efficiency rollout.
China
Domestic foundries and stainless-steel fabrication clusters near Guangdong and Zhejiang expand production capacity for global export markets. GB standards and MIIT industrial policy guide domestic equipment efficiency classifications. Zhejiang province hosts over 60% of global heating element assembly operations, exposing supply chains to logistics bottlenecks.
Germany
Industrial catering and institutional foodservice operators specify precision holding equipment for healthcare and corporate campus applications. EU Green Deal and Ecodesign Directive pressure manufacturers toward low-wattage certified designs. Bavaria's precision engineering clusters anchor fabrication of high-end induction systems for European export.
India
Quick-service chains in Mumbai and Bangalore retrofit commissary kitchens with Western-standard holding equipment as cold-chain infrastructure matures. BIS certification and FSSAI food safety protocols govern equipment import and domestic manufacture. Maharashtra's food processing zones concentrate demand for medium-capacity institutional systems.
Japan
Compact urban restaurant formats and convenience store foodservice drive demand for footprint-efficient warming solutions. METI energy efficiency standards and JIS certification requirements shape product specifications. Kanto region's Tokyo-Osaka corridor concentrates high-volume procurement from consolidated foodservice management companies.
Commercial Food Warming and Holding Equipment Market Vendor Landscape
Technology-differentiated specialists and scale-driven diversified manufacturers split the market across premium and volume tiers. The vendor base concentrates around heating-technology expertise and foodservice distribution network depth rather than pure manufacturing scale. Two archetypes dominate: precision-thermal-engineering houses with proprietary heat-transfer architectures, and diversified kitchen equipment conglomerates with broad foodservice coverage. Competitive moves center on induction technology licensing partnerships and backward integration into stainless-steel fabrication capacity.
Within the precision-thermal-engineering tier, Alto-Shaam exemplifies low-temperature holding specialization for healthcare and institutional catering, while Hatco Corporation anchors heated display case positioning through foodservice distribution network breadth. Middleby Corporation occupies a diversified conglomerate position spanning conveyor warming and integrated holding systems for high-volume restaurant chains. These three represent distinct strategic archetypes: proprietary technology licensing, distribution-led merchandising equipment, and portfolio breadth across kitchen system integration.
| Leading Market Players |
|---|
| Alto-Shaam |
| Hatco Corporation |
| Middleby Corporation |
| Vulcan |
| Cres Cor |
| True Manufacturing |
| Vollrath |
| Dover Corporation |
| Welbilt |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Long Beach freight corridor cost dynamics compress fabrication margins for stainless-steel cabinet producers while amplifying price spreads between Guangdong-sourced economy tiers and Bavarian-engineered induction systems. Nickel and chromium input volatility from Indonesian and Russian supply disruptions feeds directly into downstream price differentiation across buyer archetypes.
Pricing Analysis
Geographic price spreads separate Guangdong-manufactured economy units from German-engineered premium induction systems by a factor reflecting certification tier and after-sales bundling intensity. Pricing stratifies across NSF-certified premium, UL-listed standard, and uncertified economy tiers, with Energy Star 3.0 compliance emerging as the primary price differentiation driver. Cost compression in the economy tier is intensifying because stainless-steel feedstock volatility squeezes fixed-margin contracts. Independent restaurant operators exhibit the highest price sensitivity, while consolidated foodservice management companies absorb premium pricing for standardization benefits.
Supply Chain Analysis
Stainless-steel feedstock draws from Indonesian nickel smelters, Chinese chromium processors, and German cold-rolling mills before reaching fabrication clusters. Heating element assembly concentrates in Guangdong province, Zhejiang stainless-steel forming, and Bavarian precision coil winding operations. Single-source vulnerability in Guangdong's heating element corridor exposes buyers to logistics bottlenecks and tariff exposure. Distribution runs through national foodservice equipment distributors, regional kitchen supply houses, and direct OEM relationships with institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial food warming and holding equipment sits in early-cycle expansion as ghost kitchen proliferation and DOE efficiency mandates accelerate replacement demand beyond traditional refresh timelines.
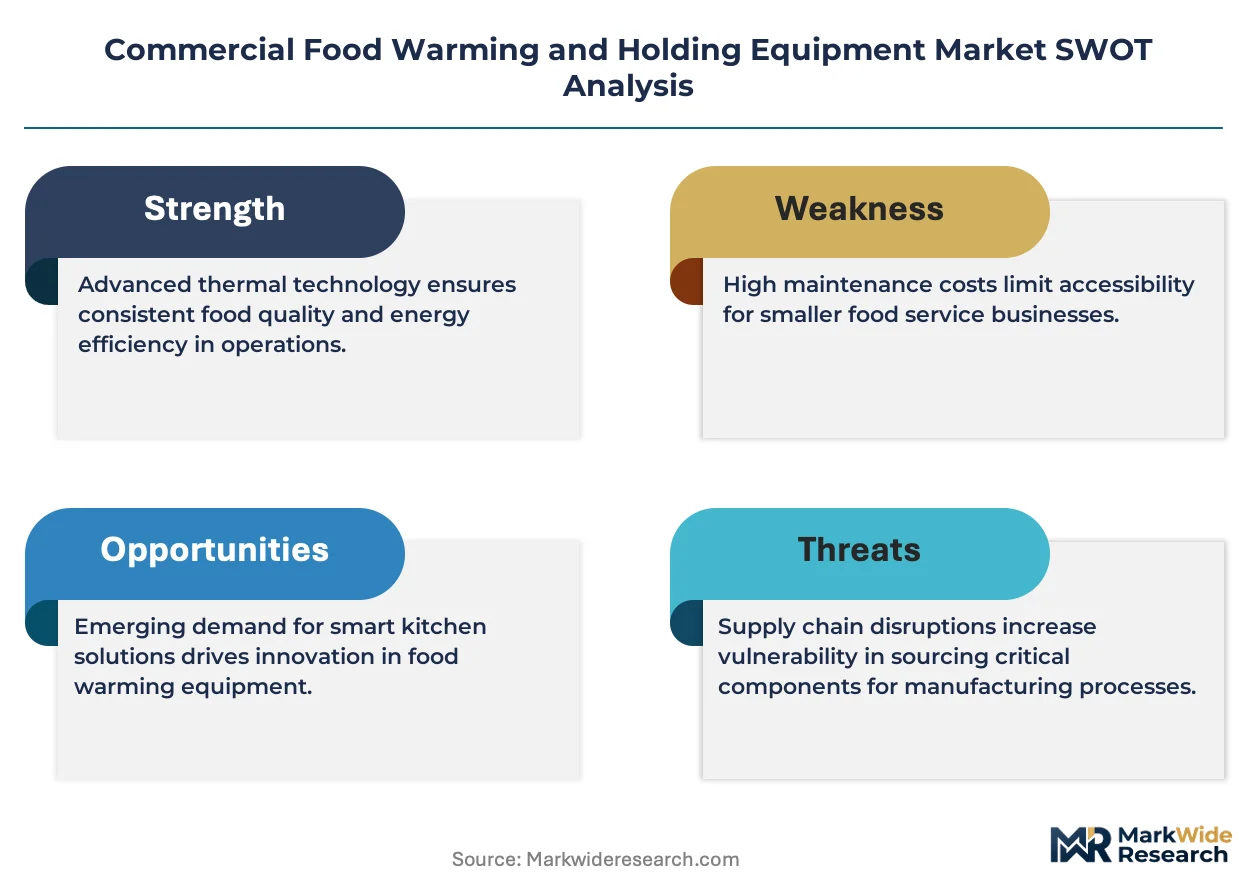
For Market Incumbents: Build certification moats around EPA Energy Star 3.0 and NSF sanitation credentials to defend against low-cost Guangdong imports. Deepen backward integration into stainless-steel fabrication capacity to offset nickel price volatility. Secure exclusive distribution lockups with Aramark, Compass Group, and Sodexo procurement committees to freeze out challenger brands from institutional RFPs. For New Entrants and Emerging Players: Build out IoT-enabled predictive maintenance capabilities for hospital and university cafeteria segments where unplanned downtime costs exceed equipment price premiums. Target India's quick-service retrofit wave in Mumbai and Bangalore commissaries as cold-chain infrastructure matures. Lead with induction technology licensing partnerships to bypass factory-trained technician scarcity barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified kitchen equipment conglomerates seeking to divest non-core warming portfolios. Long-term viability hinges on regulatory tailwinds tightening idle-energy thresholds and institutional procurement consolidation favoring certified vendors. Watch for inflection signals in California Title 24 adoption velocity as preview for national DOE efficiency rollout.| Strategic Initiative | Industry Significance |
|---|---|
| Induction Technology Licensing | Alto-Shaam and Middleby extend proprietary coil architectures to second-tier manufacturers seeking EPA compliance. |
| Backward Integration into Stainless Fabrication | Hatco Corporation secures captive supply of 304-grade steel from Zhejiang clusters to insulate margins from nickel volatility. |
| IoT Predictive Maintenance Platform | Sensor-integrated warming cabinets from Vollrath converge with Sodexo kitchen management software to reduce hospital cafeteria downtime. |
| Energy Star 3.0 Certification Fast-Track | True Manufacturing accelerates NSF testing protocols to maintain eligibility for California Title 24 procurement mandates. |
| Ghost Kitchen Compact System Launch | Cres Cor deploys sub-200-square-foot induction cabinets for Austin and Miami delivery-only facilities. |
Methodological Framework
Desk research of DOE efficiency standard filings, NSF certification databases, and EPA Energy Star product directories preceded structured interviews with commercial kitchen equipment procurement directors, foodservice management company operations executives, hospital cafeteria facilities managers, and ghost kitchen development leads. Secondary validation drew from customs trade data for stainless-steel imports, SEC 10-K disclosures from diversified kitchen equipment conglomerates, and state-level utility rebate program specifications. Bottom-up unit economics and top-down sector spend estimates were triangulated to anchor market sizing.
Assumptions held fixed include DOE efficiency standard enforcement timelines and stainless-steel price volatility within historical bands; variables tested include ghost kitchen proliferation velocity and induction technician training pipeline expansion. The analytical framework modeled equipment type, capacity tier, heating technology, and end-user segment dimensions across the projection horizon. CAGRs were derived from replacement cycle compression analysis and regulatory mandate adoption curves, with hospital catering volume and quick-service off-premise share as primary demand inputs.
Sensitivities concentrate around nickel supply disruption severity, Guangdong logistics chokepoint duration, and DOE standard implementation delays. Cross-checking against NAFEM industry shipment data and FE&S magazine equipment spend surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Commercial Cookers Market
Food Service Equipment
France Smokeless Indoor Grills Market
Food Service Equipment
Commercial Slush Machine Market
Food Service Equipment
Kegerator Equipment Market
Food Service Equipment
Slow Cooker and Sous Vide Market
Food Service Equipment
Meal Delivery Carts and Racks Market
Food Service Equipment
Commercial Ice Equipment and Supplies Market
Food Service Equipment
Germany Countertop Ice Makers Market
Food Service Equipment
Commercial Stainless Steel Cooking Equipment Market
Food Service Equipment
Combi Cooler Market
Food Service Equipment
Draught Beer Chiller Market
Food Service Equipment
Commercial Hot Dog Cooker Market
Food Service Equipment
Global Roti Maker Market
Food Service Equipment
Dispensing Tap Market
Food Service Equipment
Saudi Arabia Foodservice Disposable Packaging Market
Food Service Equipment
Commercial Refrigerated Display Cabinet Market