
 Clean Technology Market | 2026-2036
Clean Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Clean Technology Market Analysis
Corporate offtake agreements are unwinding traditional utility-centric procurement patterns as data center operators and heavy manufacturers seek direct renewable supply. Tesla leverages its integrated battery-manufacturing footprint to anchor utility-scale storage deployments across multiple continents. LONGi Green Energy Technology dominates crystalline silicon supply chains through backward integration into polysilicon production. Vestas Wind Systems competes on offshore turbine platform scale, sustaining R&D intensity in blade aerodynamics and drivetrain reliability.
Clean technology encompasses hardware, software, and process innovations that reduce environmental impact across energy generation, storage, distribution, and end-use consumption. Photovoltaic modules typically achieve conversion efficiencies between 20-22% for commercial monocrystalline cells, with utility-scale installations requiring DC-to-AC ratios optimized for local irradiance and grid interconnection standards. Energy storage systems command expanding margin pools as lithium-ion cell costs decline and four-hour duration configurations displace peaker plants in wholesale markets. Electric vehicles represent the fastest-growing product category, though wind turbines retain higher per-unit capital intensity and longer asset lifecycles.
The EU Green Deal and its accompanying CSRD disclosure requirements are reshaping corporate capital allocation toward verifiable emissions reductions. EPA power plant standards in the United States and China's dual carbon goals administered by MEE are converging on phased coal retirement timelines, though implementation speed varies by national grid structure. India's PLI scheme for solar manufacturing is attracting cell and module assembly capacity away from incumbent Southeast Asian hubs. Stakeholders must monitor how local content rules interact with technology transfer requirements when selecting manufacturing locations.
Market Dynamics
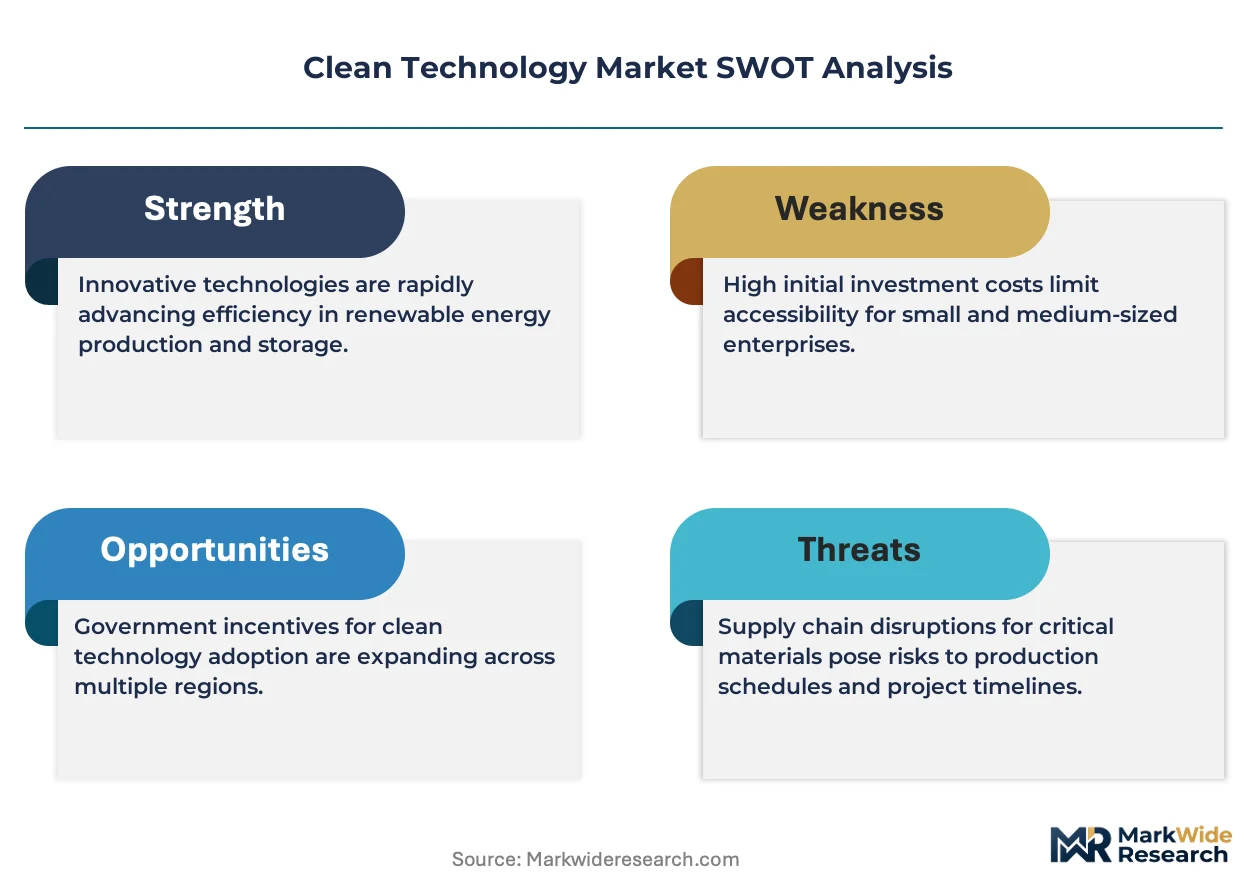
Corporate offtake agreements are unwinding traditional utility-centric procurement patterns as data center operators and heavy manufacturers seek direct renewable supply contracts outside incumbent utility structures.
Growth Catalysts
- EU Green Deal compliance thresholds:The CSRD disclosure requirements are reshaping corporate capital allocation toward verifiable emissions reductions across member states.
- Data center operators:Hyperscale cloud providers are contracting directly with solar and wind developers to secure 24/7 carbon-free energy for facility expansion.
- Lithium-ion cell cost curves:Four-hour duration battery configurations are capturing wholesale market share from natural gas peaker plants in multiple jurisdictions.
Market Restraints
- Polysilicon supply concentration:Xinjiang-sourced material faces trade restrictions in the United States and Europe, constraining crystalline silicon module availability.
- Grid interconnection queues:Transmission access timelines in the United States stretch 3-5 years, delaying utility-scale project completion regardless of permitting status.
- Critical mineral dependencies:Cobalt and lithium refining capacity concentrates in China and the Democratic Republic of Congo, exposing battery supply chains to geopolitical friction.
Strategic Opportunities
- India's PLI scheme for solar manufacturing:Production-linked incentives are attracting cell and module assembly capacity away from incumbent Southeast Asian hubs.
- Green hydrogen integration:Electrolyzer deployments at offshore wind sites in Germany and Denmark are creating new offtake channels for curtailed renewable generation.
- Building-integrated photovoltaics:Façade and rooftop-integrated systems are penetrating commercial real estate retrofits where conventional rooftop space is constrained.
Industry Challenges
- Power electronics engineering talent:Inverter and grid-forming battery control system design expertise remains scarce relative to deployment targets.
- CE marking and UL certification timelines:Safety testing backlogs for novel storage chemistries delay product launches by 12-18 months.
- Legacy SCADA integration:Distributed energy resource management systems must interface with decades-old utility control infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clean Technology Market |
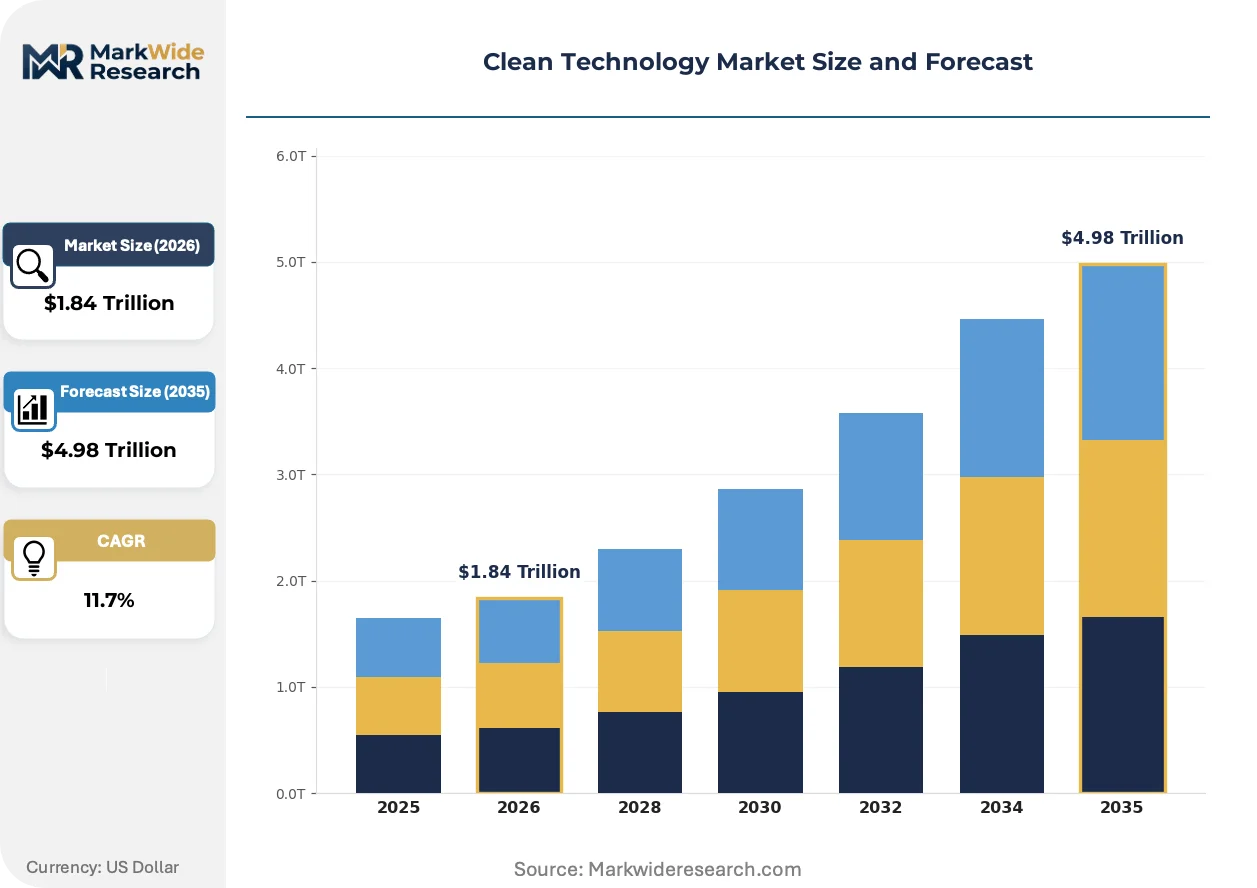
| Market Size in 2026 | $1.84 Trillion |
| Market Size in 2035 | $4.98 Trillion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Panels, Wind Turbines, Energy Storage Systems, Electric Vehicles Technology: Photovoltaic, Biomass, Fuel Cell, Geothermal Application: Residential, Commercial, Industrial, Transportation End User: Utilities, Corporations, Government, Households |
| Companies Covered | Tesla, Sungrow Power Supply, Vestas Wind Systems, NextEra Energy, GE Vernova, Adani Green Energy, LONGi Green Energy Technology, ACWA Power, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clean Technology Market Emerging Trajectories
Solid-state battery chemistries, advanced grid-forming inverters, and automated manufacturing processes are compressing cost structures while expanding operational envelopes across generation and storage assets.
Topcon and heterojunction cell architectures are supplanting passivated emitter and rear contact designs in utility-scale module procurement. Independent power producers in Spain and Australia are specifying higher-efficiency bifacial configurations for new-build solar farms. This technology transition is compressing levelized cost of electricity benchmarks and forcing incumbent manufacturers to retool crystalline silicon production lines.
The EPA power plant standards in the United States are mandating carbon capture or co-firing requirements for existing coal facilities. Baseload generators are accelerating retirement timelines or converting to natural gas combined-cycle configurations. Coal-dependent utilities in the Midwest and Southeast are responding by procuring utility-scale solar-plus-storage portfolios to replace retiring capacity.
Direct power purchase agreements are displacing traditional green tariff structures for corporate renewable procurement. Heavy manufacturers and data center operators in Germany and the Netherlands are contracting directly with project developers rather than purchasing through regulated utilities. This channel shift is most visible in the Netherlands, where cross-border cable capacity and certificate tracking systems enable physical delivery matching.
Clean Technology Market Segmentation
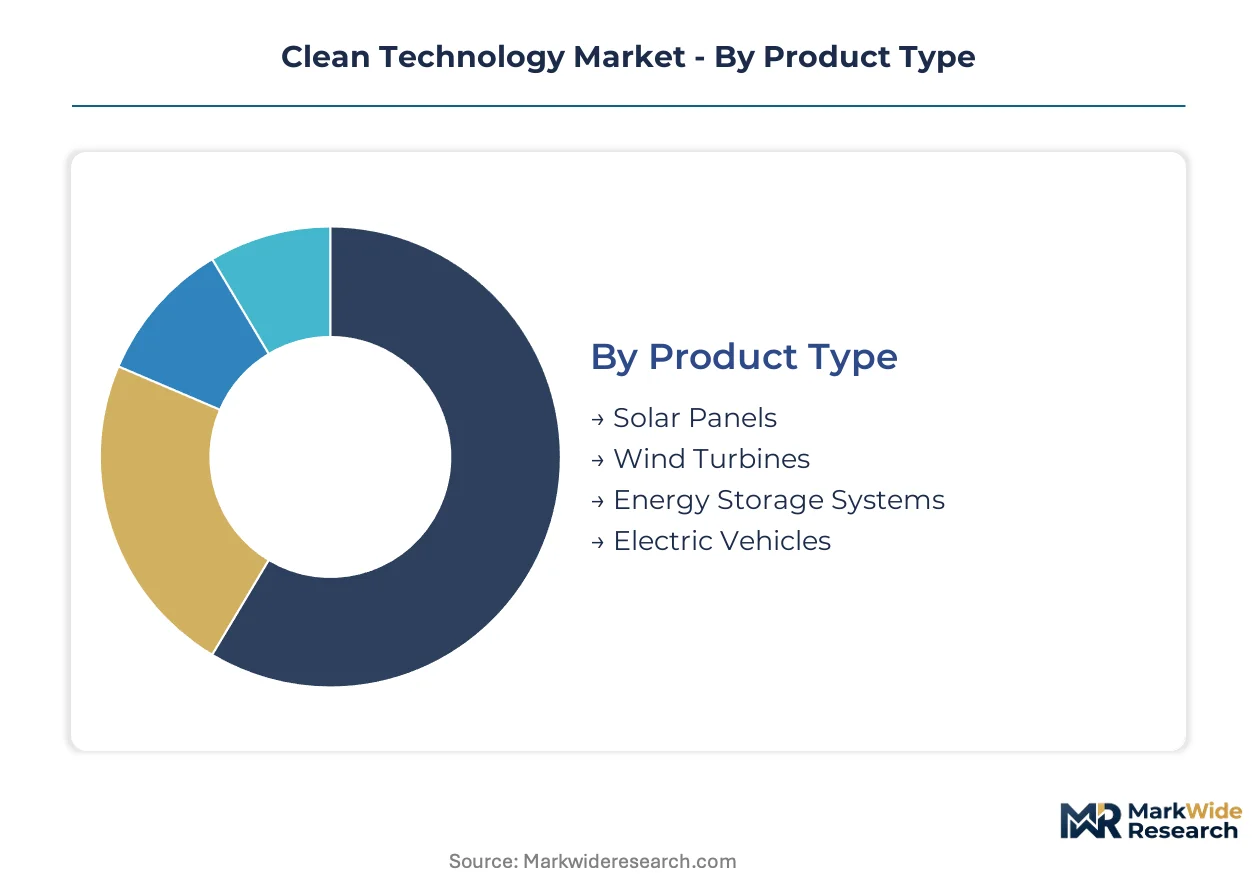
Clean technology market segmentation reveals divergent compliance pathways across regulatory jurisdictions. Product categories face distinct certification requirements under EU Green Deal thresholds, EPA power plant standards, and China's MEE dual carbon goals.
Product Type:
Regulatory differentiation separates segments by grid interconnection standards and carbon accounting methodologies. EU CSRD disclosure rules favor assets with verifiable lifecycle emissions data, while IRA tax credits in the United States prioritize domestic content thresholds.
- Solar Panels:Crystalline silicon modules achieving 20-22% conversion efficiency dominate utility-scale procurement. Demand concentrates in Germany, India, and the United States as national manufacturing incentives reshape supply geography.
- Energy Storage Systems:Four-hour duration lithium-ion configurations displace natural gas peaker plants in wholesale markets. Procurement accelerates among Texas and California independent system operators facing renewable curtailment challenges.
- Wind Turbines:Offshore platforms command higher capital intensity and longer asset lifecycles than solar equivalents.
- Electric Vehicles:Fastest-expanding product category across passenger and commercial fleet segments.
Solar panels handle the majority of throughput; energy storage systems are gaining share fastest as grid operators mandate firm capacity.
Technology:
Cost tier stratification separates mature commercialized platforms from emerging configurations awaiting certification. Photovoltaic and biomass technologies operate at scale with established financing structures, while fuel cell and geothermal segments require differentiated incentive mechanisms.
- Photovoltaic:TOPCon and heterojunction cell architectures supplant legacy PERC designs in utility procurement. Spain and Australia independent power producers specify bifacial configurations for new-build solar farms.
- Biomass:Co-firing retrofits at existing coal facilities satisfy EPA power plant standards in the United States. Midwest utilities deploy biomass to extend asset lifecycles while meeting interim emissions targets.
- Fuel Cell:Electrolyzer deployments at German and Danish offshore wind sites create hydrogen offtake channels.
- Geothermal:Baseload generation profile attracts capacity payments in markets with high renewable penetration.
Photovoltaic captures the dominant share of installed capacity; fuel cell technology is expanding most quickly on policy support for hydrogen economies.
Application:
Customer type determines procurement channel and contract structure. Residential and commercial segments rely on net metering and behind-the-meter financing, while industrial and transportation applications command direct power purchase agreements and fleet electrification mandates.
- Industrial:Heavy manufacturers in Germany and the Netherlands contract directly with renewable developers outside regulated utility structures. Physical delivery requirements drive cross-border cable investments and certificate tracking system upgrades.
- Transportation:Fleet electrification mandates in California and the European Union accelerate charging infrastructure deployment. Logistics operators specify 24/7 carbon-free energy for depot and corridor charging networks.
- Residential:Rooftop installations face interconnection queue delays in jurisdictions with outdated distribution infrastructure.
- Commercial:Building-integrated photovoltaics penetrate real estate retrofits where conventional rooftop space is constrained.
Industrial applications command the largest absolute demand; transportation is climbing the fastest as fleet decarbonization deadlines approach.
End User:
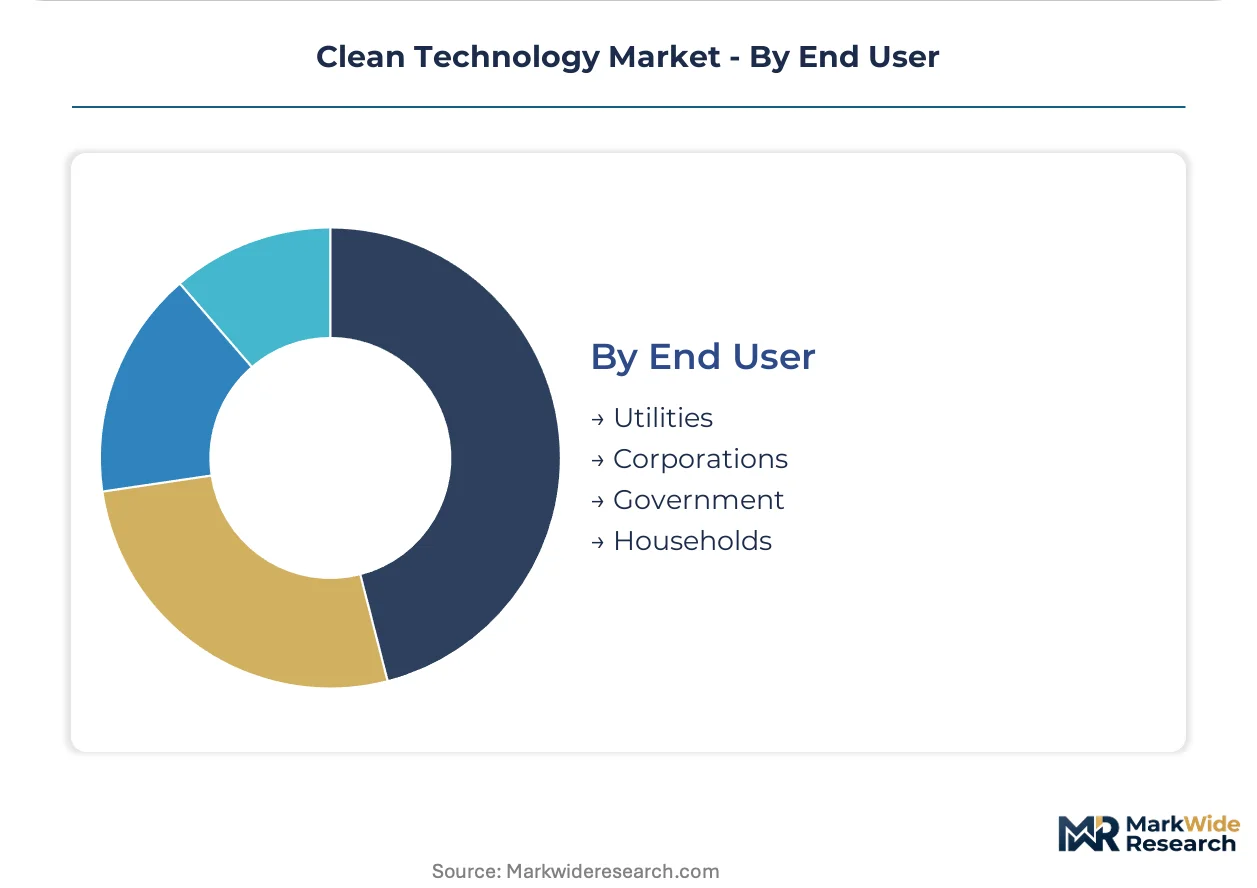
Margin structure varies by counterparty credit quality and contract duration. Utilities and corporations negotiate long-term offtake agreements with investment-grade terms, while government and household segments depend on subsidy mechanisms and retail financing products.
- Corporations:Hyperscale data center operators in Virginia and Iowa secure direct renewable supply for facility expansion. Procurement teams specify 24/7 carbon-free matching rather than annual renewable energy certificate aggregation.
- Utilities:Coal-dependent Midwest and Southeast operators procure solar-plus-storage portfolios to replace retiring baseload capacity. FERC interconnection timelines stretch 3-5 years regardless of permitting status.
- Government:Military and municipal procurement mandates drive domestic content requirements.
- Households:Net metering policy revisions in California and Nevada reshape payback calculations for rooftop solar.
Utilities manage the largest project pipelines; corporate offtake is expanding most quickly as sustainability commitments harden into procurement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese solar module exports supply utility-scale developers in Germany, India, and the United States as domestic manufacturing incentives reshape procurement geography. Trade restrictions on Xinjiang-sourced polysilicon fragment supply chains across Atlantic corridors.
United States
Data center operators in Virginia and Iowa contract directly with renewable developers for 24/7 carbon-free energy matching. EPA power plant standards mandate carbon capture or co-firing for existing coal facilities, accelerating Midwest utility procurement of solar-plus-storage portfolios. Texas and California independent system operators face interconnection queues stretching 3-5 years regardless of permitting status.
Germany
Heavy manufacturers and data center operators contract outside regulated utility structures for physical renewable delivery. The EU Green Deal and CSRD disclosure requirements reshape corporate capital allocation toward verifiable emissions reductions. Electrolyzer deployments at offshore wind sites in the North Sea create hydrogen offtake channels for curtailed generation.
China
Dual carbon goals administered by MEE converge on phased coal retirement timelines with implementation varying by provincial grid structure. Domestic module manufacturers leverage backward integration into polysilicon production to anchor crystalline silicon supply chains. Investment in energy storage systems concentrates in eastern manufacturing clusters serving both domestic and export markets.
India
The PLI scheme for solar manufacturing attracts cell and module assembly capacity away from incumbent Southeast Asian hubs. State-run utilities procure utility-scale installations as national grid structure determines renewable integration speed. Gujarat and Rajasthan host the largest concentrations of new manufacturing capacity responding to production-linked incentives.
Denmark
Offshore wind developers integrate electrolyzer capacity to monetize curtailed generation through green hydrogen production. Cross-border cable investments and certificate tracking systems enable physical delivery matching for corporate offtake agreements. Copenhagen anchors Nordic clusters competing on turbine platform scale and blade aerodynamics engineering.
Clean Technology Market Vendor Landscape
Player mix skews toward integrated technology conglomerates with captive battery manufacturing and project development arms. Market structure concentrates around vertically positioned specialists controlling upstream material flows and downstream deployment channels. Two strategic archetypes dominate: integrated energy-storage-platform vendors and pure-play renewable generation developers. Competitive moves center on manufacturing capacity expansion in tariff-advantaged jurisdictions and strategic partnerships securing offtake commitments from hyperscale data center operators.
Among integrated technology conglomerates, Tesla exemplifies the platform-architecture approach spanning vehicle, stationary storage, and energy generation verticals. LONGi Green Energy Technology occupies a position within crystalline silicon specialists leveraging polysilicon integration. Vestas Wind Systems anchors the European offshore turbine segment where blade aerodynamics and drivetrain reliability determine competitive positioning.
| Leading Market Players |
|---|
| Tesla |
| Sungrow Power Supply |
| Vestas Wind Systems |
| NextEra Energy |
| GE Vernova |
| Adani Green Energy |
| LONGi Green Energy Technology |
| ACWA Power |
| Schneider Electric |
| Others |
Supply Flow & Price Mechanics
Three-to-five-year grid interconnection timelines in the United States compress developer margins and amplify pricing power for equipment suppliers with certified, immediately available inventory. This lead-time environment rewards crystalline silicon module manufacturers with captive polysilicon production and punishes project developers facing FERC queue uncertainty.
Pricing Analysis
PERC-to-TOPCon-to-heterojunction pricing gaps stratify procurement tiers as next-generation cell architectures command 15-20% premiums over legacy configurations. Project-based long-term offtake contracts dominate utility-scale transactions, with price differentiation driven by module efficiency tier and domestic content qualification under IRA provisions. Cost compression in standard-efficiency modules intensifies as Chinese manufacturers expand wafer capacity, while premium bifacial configurations face softer pricing pressure from European and Indian procurement mandates. Heavy manufacturers exhibit highest price sensitivity due to 24/7 carbon-free matching requirements, whereas data center operators absorb premiums for firm capacity guarantees.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for crystalline silicon modules and lithium-ion battery cells. Manufacturing gravity centers on China for polysilicon refining and cell assembly, South Korea for cathode active materials, and Germany for inverter production. Raw material dependencies span lithium carbonate from Chile and Australia, cobalt hydroxide from the Democratic Republic of Congo, and high-purity quartz for crucibles. Tariff exposure on Xinjiang-sourced polysilicon fragments Atlantic supply chains. Distribution runs through regional EPC contractors and independent power producers with direct developer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean technology markets are crossing into platform economics as grid-forming inverters and distributed energy resource management systems demand interoperability standards. Tesla's integrated ecosystem spanning vehicle, stationary storage, and solar generation exemplifies this shift toward unified control architectures.
For Market Incumbents: Compound manufacturing scale advantages in tariff-advantaged jurisdictions to defend against Southeast Asian and Indian challengers. Secure captive polysilicon supply through backward integration or long-term offtake agreements to mitigate Xinjiang trade restriction exposure. Prioritize UL and CE certification investment for next-generation storage chemistries ahead of 12-18 month testing backlogs.
For New Entrants and Emerging Players: IEC 61400 and IEEE 1547 certification fast-tracks unlock utility interconnection eligibility without incumbent field-proven track records. Target building-integrated photovoltaics in commercial real estate retrofits where rooftop constraints limit conventional module deployment. Pursue strategic partnerships with hyperscale data center operators seeking 24/7 carbon-free energy matching outside regulated utility structures.
For Investors and Strategic Acquirers: Long-term, this sits as a grid-flexibility play because four-hour battery duration configurations are displacing natural gas peaker plants across multiple independent system operators. Acquisition candidates include power electronics engineering specialists with scarce inverter and grid-forming battery control system expertise. Watch FERC interconnection queue reform as the signal for project completion velocity inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Gigafactory-scale battery manufacturing in Nevada and Germany anchors Tesla's utility-scale storage deployments. |
| Power Purchase Agreement | Direct corporate offtake contracts with Virginia data center operators displace traditional green tariff structures. |
| Technology Licensing | TOPCon cell architecture licensing accelerates retooling timelines for incumbent PERC manufacturers. |
| Backward Integration into Polysilicon | LONGi's captive polysilicon production insulates crystalline silicon margins from Xinjiang trade restrictions. |
| Green Certification Program | EU Green Deal CSRD disclosure requirements reshape corporate capital allocation toward verifiable emissions reductions. |
Methodological Framework
Cross-validation between EIA project development databases and IEA renewable deployment statistics anchors the qualitative findings. Primary interviews with utility planning officers, independent power producer project developers, EPC contractors, and grid operators combine with FERC interconnection filings, EPA power plant standard dockets, and customs trade data for bottom-up and top-down triangulation.
Sensitivity analysis around lithium-ion cell cost curves and coal retirement timelines shapes the forecast framework. Segmentation dimensions span product type, technology generation, application, and end-user across the projection horizon. CAGRs derive from capacity addition trajectories, policy incentive evolution, and substitution elasticity between renewable and fossil generation. Forecast inputs include FERC queue depth, IRA domestic content bonus qualification rates, and EU Green Deal compliance threshold stringency.
Underlying assumptions cover sustained IRA tax credit extension and EU carbon border adjustment implementation, with deviation risk concentrated in trade policy fragmentation and critical mineral supply disruption. Forecasts reflect these conditions; outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging Energy Technologies
Global Power-To-X Market
Emerging Energy Technologies
Methanation Technology Market
Emerging Energy Technologies
Europe Clean Coal Technologies Market
Emerging Energy Technologies
Cryogenic Technology Market
Emerging Energy Technologies
United States Clean Coal Technologies Market
Emerging Energy Technologies
Clean Coal Technologies Sales Market
Emerging Energy Technologies
Global Microreactor Technology Market
Emerging Energy Technologies
Advanced Energy Market
Emerging Energy Technologies
Nanotechnology in Energy Market
Emerging Energy Technologies
Multi Energy Systems Market
Emerging Energy Technologies
Energy Transition Market
Emerging Energy Technologies
Decarbonization Market