
 Methanation Technology Market | 2026-2036
Methanation Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Methanation Technology Market Insights
The EU F-Gas Regulation is hardening the cost-of-entry calculus for conventional refrigerant-based hydrogen liquefaction, redirecting capital toward ambient-temperature methanation pathways. Johnson Matthey leverages its catalytic IP portfolio to dominate high-pressure reactor supply for power-to-gas facilities. Haldor Topsoe sustains technology leadership through its proprietary sulfur-resistant catalyst formulations that extend reactor run lengths. Electrochaea anchors the biological methanation segment with archaea-based biocatalyst systems that operate at lower temperature thresholds than thermal alternatives.
Methanation technology converts carbon oxides and hydrogen into synthetic methane through exothermic catalytic or biological reaction pathways, typically requiring nickel-based catalysts at 250-450°C and 20-80 bar pressure to achieve CO2 conversion efficiencies exceeding 99%. The primary industrial purpose centers on renewable energy storage and synthetic natural gas production for grid injection or transport fuel applications. Catalytic methanation occupies the dominant commercial position due to mature reactor engineering and established catalyst supply chains, while biological methanation represents the fastest-expanding technology category as archaea-based systems reduce energy intensity and tolerate variable renewable power input. Feedstock segmentation shows CO2 capture from industrial point sources concentrating margin pools, as biogas upgrading competes on narrower yield spreads.
Germany's Federal Network Agency, Denmark's Energinet, and the EU's Renewable Energy Directive III collectively shape demand by mandating renewable gas quotas and establishing grid interconnection standards for synthetic methane injection. The EU Emissions Trading System carbon price trajectory directly determines project economics for CO2-sourced methanation, while national hydrogen strategies in the Netherlands and Spain allocate dedicated funding envelopes for power-to-gas demonstrations. Stakeholders must monitor whether upcoming revisions to the Gas Directive extend tariff exemptions for synthetic methane to match biomethane treatment, as this regulatory equivalence decision will determine pipeline access economics for methanation project developers.
Market Dynamics
The EU F-Gas Regulation is hardening cost structures for conventional hydrogen liquefaction, redirecting capital toward ambient-temperature methanation pathways and compressing technology selection timelines for power-to-gas developers.
Growth Catalysts
- RED III renewable gas quotas:The EU Renewable Energy Directive III mandates escalating synthetic methane targets, forcing grid operators to secure injection-ready biomethane alternatives.
- Industrial cluster decarbonization:Germany's Ruhr and Netherlands' Port of Rotterdam hydrogen hubs are anchoring methanation offtake agreements tied to steel and chemical sector emissions targets.
- Biological methanation maturation:Archaea-based biocatalyst systems now achieve commercial-scale throughput at 40-60°C below thermal thresholds, slashing reactor energy intensity.
Market Restraints
- Nickel catalyst supply concentration:High-purity nickel for Sabatier reactors concentrates in Indonesian and Russian mining jurisdictions, exposing project developers to sanctions-linked input volatility.
- Grid injection tariff asymmetry:Synthetic methane lacks guaranteed tariff parity with biomethane under current Gas Directive frameworks, eroding pipeline access economics.
- Carbon capture feedstock quality variance:Industrial point-source CO2 streams carry sulfur and oxygen contaminants that poison nickel catalyst beds, forcing costly pre-treatment capex.
Strategic Opportunities
- Spain's hydrogen valley deployments:The Spanish national hydrogen strategy allocates dedicated funding envelopes for power-to-gas demonstrations in Aragon and Catalonia industrial corridors.
- Biogas upgrading convergence:Co-location of anaerobic digesters with electrolyzers enables integrated biogas-to-biomethane upgrading, capturing margin pools from agricultural waste valorization.
- EU ETS carbon price trajectory:Escalating emissions trading system prices above €80/tonne CO2-equivalent are compressing breakeven thresholds for CO2-sourced methanation projects.
Industry Challenges
- Specialized reactor engineering talent scarcity:High-pressure catalytic vessel design expertise concentrates in legacy ammonia and methanol plant engineering pools, creating recruitment bottlenecks for power-to-gas EPC contractors.
- Certification timeline compression:TÜV and DVGW certification for synthetic methane grid injection requires 18-24 month validation cycles, delaying project revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methanation Technology Market |
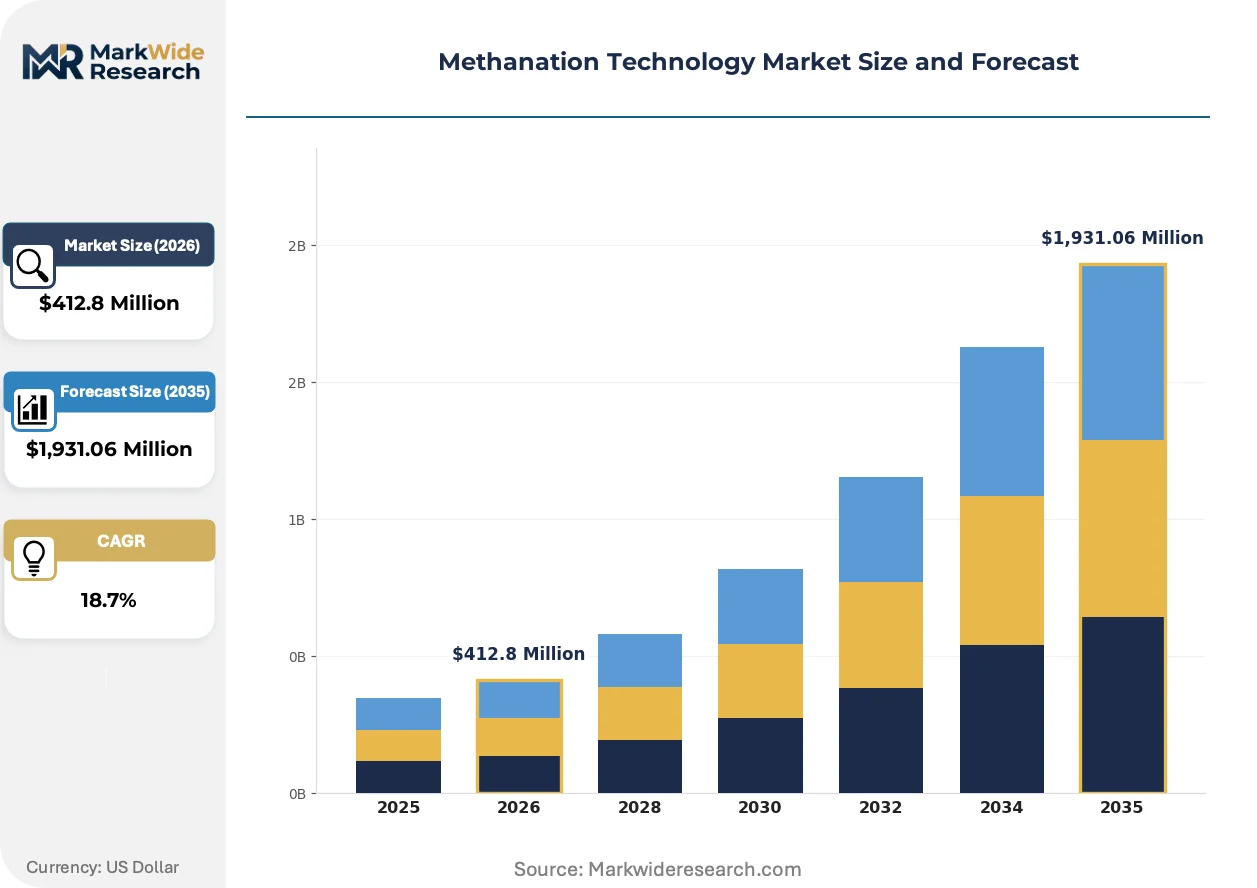
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $1,931.06 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Catalytic Methanation, Biological Methanation, Electrochemical Methanation, Thermal Methanation Feedstock: CO2, Biogas, Natural Gas, Synthetic Gas End User: Power Plants, Industrial Facilities, Residential Users, Transportation Sector Application: Renewable Energy Storage, Synthetic Fuels, Chemical Production, Grid Stabilization |
| Companies Covered | Johnson Matthey, Haldor Topsoe, BASF, ThyssenKrupp AG, Clariant AG, Electrochaea, Wood, Air Liquide, MAN Energy Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methanation Technology Market Trends and Innovations
Technology trajectories in methanation are pivoting around energy efficiency gains and regulatory compliance automation, with biological pathways capturing disproportionate R&D allocation.
Biological methanation is expanding into power-to-gas facilities seeking variable renewable energy integration. Archaea-based biocatalyst systems tolerate intermittent hydrogen supply from wind and solar electrolysis without thermal cycling damage. This operational flexibility is compressing project LCOE calculations for developers in Denmark and Germany.
REACH and F-Gas Regulation amendments are tightening catalyst material disclosure requirements and refrigerant phase-out timelines for liquefaction competitors. Industrial gas suppliers must now document full substance life-cycle impacts for nickel catalyst registration. German project developers are responding by accelerating biological methanation pilot transitions to bypass thermal pathway compliance burdens.
Buyers are consolidating procurement around integrated engineering-procurement-construction contracts that bundle electrolyzer, methanation reactor, and grid injection infrastructure. This pattern compresses vendor fragmentation and shifts risk allocation toward turnkey contractors. The trend is most visible in Netherlands hydrogen corridor tenders, where port authorities demand single-point accountability for synthetic methane delivery guarantees.
Methanation Technology Market Segmentation
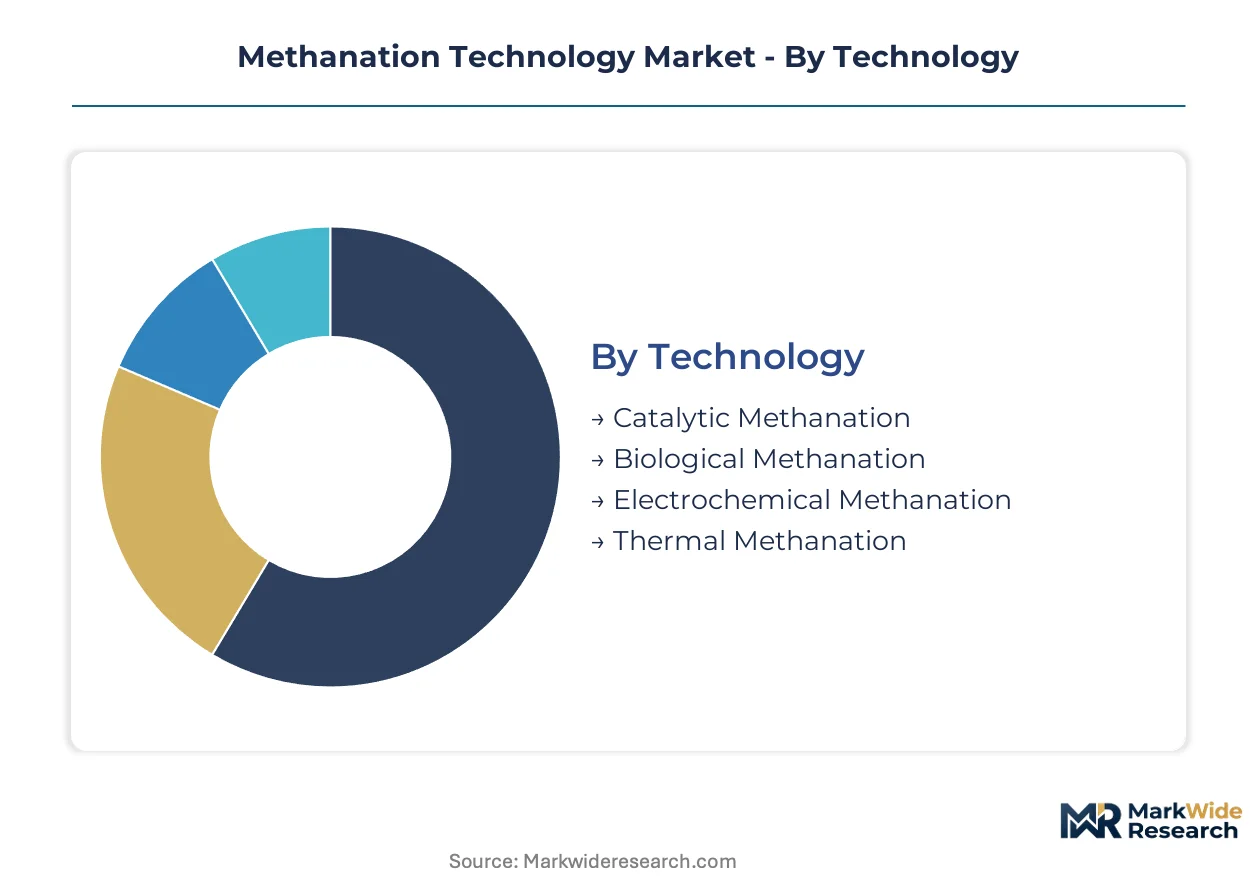
Methanation technology segments diverge sharply on certification intensity, with biological pathways facing lighter TÜV validation burdens than high-pressure catalytic systems. Feedstock provenance determines carbon intensity scoring under EU Renewable Energy Directive III, directly shaping project finance access and offtake pricing.
Technology:
DVGW certification mandates and REACH catalyst registration requirements split this category by compliance burden and reactor engineering complexity.
- Catalytic Methanation:Nickel-based Sabatier reactors operating at 250-450°C and 20-80 bar pressure dominate commercial deployments. Germany's Ruhr industrial cluster anchors demand as ThyssenKrupp and MAN Energy Solutions execute pilot-to-commercial transitions under RED III quotas.
- Biological Methanation:Archaea-based biocatalyst systems achieve synthetic methane production at 40-60°C below thermal thresholds, slashing energy intensity. Denmark's Energinet-funded power-to-gas facilities favor this pathway for variable renewable integration without thermal cycling damage.
- Electrochemical Methanation:Solid oxide electrolysis cell integration remains pre-commercial, with Spain's Aragon hydrogen valley hosting demonstration units.
- Thermal Methanation:Legacy high-temperature pathways concentrate in ammonia plant retrofit applications with established catalyst supply chains.
Catalytic Methanation sits at the top of the volume ranking, with Biological Methanation climbing the fastest.
Feedstock:
Carbon intensity certification tiers under EU Emissions Trading System protocols segment this category by feedstock origin and pre-treatment capex requirements.
- CO2:Industrial point-source capture from steel and cement facilities dominates project pipelines. Netherlands Port of Rotterdam developers prioritize this feedstock for synthetic methane export to German chemical buyers seeking scope 3 emissions reductions.
- Biogas:Agricultural waste and wastewater digester output enables integrated upgrading with electrolytic hydrogen. German biogas plant operators leverage existing grid injection infrastructure for biomethane-to-synthetic methane conversion.
- Natural Gas:Steam methane reforming feedstock serves pilot-scale methanation testing with established pipeline logistics.
- Synthetic Gas:Gasification-derived syngas from biomass or waste streams targets circular carbon applications in aviation fuel synthesis.
CO2 commands the largest project pipeline, while Biogas gains share fastest on agricultural waste valorization economics.
End User:
Grid injection tariff treatment and offtake contract duration differentiate demand profiles across customer categories.
- Power Plants:Utility-scale electrolyzer-methanation hybrids serve renewable curtailment management and seasonal storage.
- Industrial Facilities:Steel, cement, and chemical sector buyers anchor synthetic methane procurement for process heat and feedstock substitution under EU ETS compliance deadlines.
- Residential Users:District heating network injection remains marginal pending gas distribution tariff parity rulings.
- Transportation Sector:LNG and compressed natural gas vehicle fleets represent emerging demand as renewable methane certificates gain fleet decarbonization traction.
Industrial Facilities anchor current offtake volumes, with Transportation Sector expanding most quickly on maritime and heavy-duty fuel switching.
Application:
Revenue recognition timelines and certification pathway complexity segment this category by project development risk profiles.
- Renewable Energy Storage:Power-to-gas facilities convert surplus wind and solar into storable methane for seasonal grid balancing.
- Synthetic Fuels:E-methane production for aviation and maritime sectors targets EU ReFuelEU and FuelEU Maritime regulatory compliance.
- Chemical Production:Methanol and ammonia synthesis feedstock substitution drives methanation integration with existing petrochemical complexes.
- Grid Stabilization:Synthetic methane injection provides frequency regulation services and peak shaving capacity for transmission system operators.
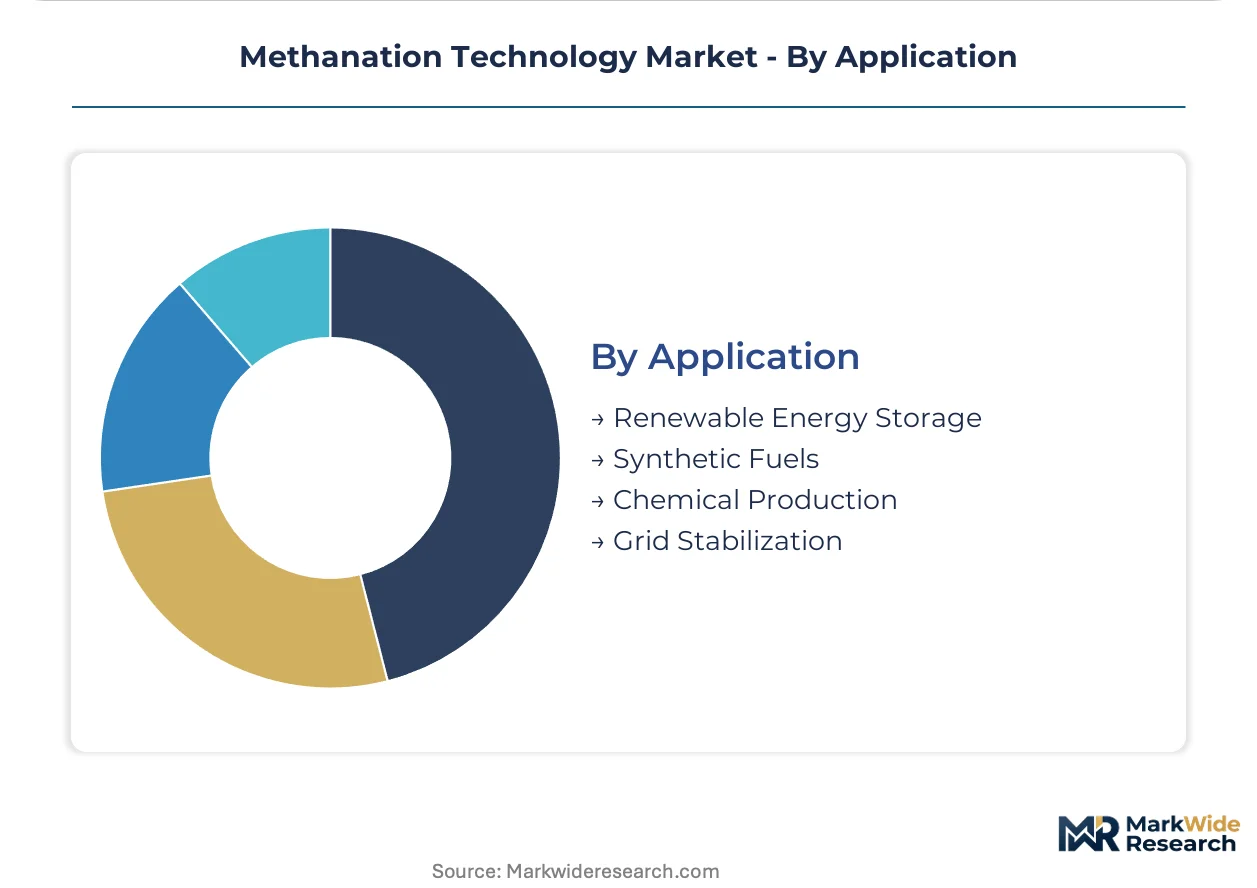
Renewable Energy Storage leads deployment scale, with Synthetic Fuels showing the steepest expansion trajectory on transport decarbonization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial-scale methanation during its 2010s power-to-gas demonstration wave, establishing the regulatory and engineering templates now diffusing across Northern Europe. The technology's commercial geography now clusters where hydrogen hub funding intersects with carbon capture infrastructure and renewable curtailment.
Germany
The Ruhr industrial cluster anchors continental demand as steel and chemical buyers execute synthetic methane offtake agreements under EU ETS compliance deadlines. The Federal Network Agency's renewable gas quotas force grid operators to secure injection-ready biomethane alternatives. ThyssenKrupp and MAN Energy Solutions dominate reactor deployment in North Rhine-Westphalia's hydrogen corridor.
Denmark
Energinet-funded power-to-gas facilities favor biological methanation for variable renewable integration without thermal cycling damage. The Danish national hydrogen strategy allocates dedicated capital envelopes for archaea-based pilot transitions. Copenhagen's industrial periphery hosts the densest concentration of operational biological methanation capacity outside Germany.
Netherlands
Port of Rotterdam developers prioritize CO2 point-source capture from refineries for synthetic methane export to German chemical buyers seeking scope 3 reductions. The national hydrogen strategy mandates power-to-gas integration with North Sea electrolyzer buildout. Shell and Air Liquide anchor reactor deployment in the Maasvlakte hydrogen hub.
Spain
The Aragon and Catalonia industrial corridors host demonstration units for electrochemical methanation integration with solar-driven electrolysis. Spain's hydrogen valley deployments allocate dedicated funding envelopes for pre-commercial technology validation. Barcelona's chemical complex buyers are negotiating synthetic methane procurement for process heat substitution.
France
The national hydrogen strategy targets methanation for seasonal storage in the country's nuclear-heavy grid balancing architecture. ANSM and CNIL oversight of catalyst substance registration creates compliance complexity for thermal pathway developers. The Fos-sur-Mer industrial cluster near Marseille anchors pilot deployment for cement sector CO2 valorization.
Methanation Technology Market Competitive Landscape
The competitive structure tilts toward integrated technology licensors with captive catalyst supply chains. Johnson Matthey and Haldor Topsoe dominate high-pressure reactor engineering through proprietary catalytic IP, while Electrochaea anchors the biological segment with archaea-based biocatalyst systems. Three archetypes define positioning: legacy chemical catalyst suppliers extending into power-to-gas, specialized biological methanation developers, and engineering-procurement-construction contractors bundling electrolyzer-reactor-infrastructure packages. Dominant competitive moves center on strategic partnerships with electrolyzer OEMs and geographic expansion into hydrogen valley tenders.
Among UK-based diversified chemical groups, Johnson Matthey occupies a position exemplifying the catalyst-supplier archetype with deep Sabatier reactor expertise. Haldor Topsoe represents the sulfur-resistant catalyst specialization vector through its proprietary formulations. Electrochaea anchors the biological methanation tier with lower-temperature operational thresholds that reduce energy intensity for Danish and German power-to-gas developers.
| Leading Market Players |
|---|
| Johnson Matthey |
| Haldor Topsoe |
| BASF |
| ThyssenKrupp AG |
| Clariant AG |
| Electrochaea |
| Wood |
| Air Liquide |
| MAN Energy Solutions |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation refrigerant phase-out mandates gate qualified supply for thermal methanation pathways and premium-tier pricing access for biological alternatives that bypass compliance burdens. Project developers face bifurcated procurement economics where catalyst registration costs under REACH and DVGW certification timelines compress margin structures for high-pressure reactor suppliers while archaea-based systems capture pricing premiums through faster grid injection approval.
Pricing Analysis
Project-based long-term offtake contracting dominates methanation technology procurement, with price differentiation hinging on TÜV certification grade and electrolyzer-reactor integration depth. Premium-mid-economy pricing differentiation separates turnkey EPC bundles from component-only supply, with after-sales service bundling widening spreads. Cost compression in catalytic reactor tiers is intensifying because nickel catalyst pre-treatment capex is escalating on sulfur-contaminated CO2 feedstock streams. Industrial cluster buyers in Germany's Ruhr demonstrate lowest price sensitivity due to EU ETS compliance deadlines, while agricultural biogas operators in Denmark exhibit highest sensitivity to upfront capital outlays.
Supply Chain Analysis
DVGW and TÜV certification gating concentrates qualified reactor engineering talent in Germany, Denmark, and the Netherlands, creating supply-side bottlenecks for power-to-gas EPC contractors. High-purity nickel catalyst feedstock draws from Indonesian and Russian mining jurisdictions, while archaea biocatalyst cultures source from specialized biotechnology suppliers in Germany and Denmark. Single-source vulnerability runs through Indonesian nickel supply exposed to sanctions-linked disruption. Distribution runs through integrated engineering-procurement-construction contractors bundling electrolyzer, methanation reactor, and grid injection infrastructure for port authority and industrial cluster buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Methanation technology constitutes a late-cycle quality story as power-to-gas developers shift procurement toward integrated EPC bundles with guaranteed synthetic methane delivery specifications. Premium-tier demand is concentrating around biological methanation pathways that tolerate variable renewable input without thermal cycling degradation.
For Market Incumbents: To counter biological methanation entrants capturing margin pools through lower certification burdens, Johnson Matthey and Haldor Topsoe should deepen backward integration into captive nickel catalyst recycling infrastructure and accelerate sulfur-resistant formulation R&D to extend reactor run lengths against archaea-based competition. Capacity addition in Spain's Aragon hydrogen corridor offers geographic defense against Danish and German biological pathway concentration. For New Entrants and Emerging Players: Launch via biogas upgrading convergence models targeting agricultural waste valorization economics in Denmark and Germany, where anaerobic digester co-location with electrolyzers remains underpenetrated relative to industrial CO2 point-source capture. Spain's Catalonia industrial corridor represents the most penetrable geography for electrochemical methanation demonstration units given dedicated hydrogen valley funding envelopes and solar-driven electrolysis integration potential. For Investors and Strategic Acquirers: Roll-up economics work for specialized biological methanation developers because certification timeline compression under DVGW and TÜV protocols creates stranded asset risk for standalone technology licensors lacking EPC integration capabilities. Five-to-ten-year viability hinges on EU Gas Directive tariff parity rulings extending biomethane-equivalent treatment to synthetic methane. The signal to watch is Federal Network Agency pipeline access tariff announcements for methanation project revenue recognition timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Supply | Captive nickel sourcing insulates Johnson Matthey and Haldor Topsoe from Indonesian supply volatility under EU sanctions frameworks. |
| Biological Methanation Pilot Scale-Up | Electrochaea's archaea-based systems reduce DVGW certification burdens for Danish Energinet-funded power-to-gas developers. |
| Integrated EPC Contracting | Turnkey bundling of electrolyzer, reactor, and grid infrastructure shifts risk allocation toward contractors in Netherlands port tenders. |
| Hydrogen Valley Geographic Expansion | Spain's Aragon and Catalonia corridors offer pre-commercial validation sites for electrochemical methanation integration. |
| EU Gas Directive Tariff Advocacy | Pipeline access parity lobbying determines synthetic methane economics for German industrial cluster offtake agreements. |
Research Methodology
Multiple input streams — executive interviews with power-to-gas project developers, catalyst procurement leads at industrial gas suppliers, and EPC contractor engineering directors — were reconciled against secondary validation from EU Hydrogen Strategy filings, RED III implementation documents, Energinet and Bundesnetzagentur regulatory releases, and TÜV certification database records. Bottom-up project pipeline aggregation across Germany, Denmark, Netherlands, and Spain was triangulated against top-down hydrogen corridor funding allocation analysis.
Data-stream reconciliation across technology segmentation by catalytic versus biological pathway, feedstock provenance from industrial CO2 capture versus biogas upgrading, and end-use concentration in industrial facilities versus power plants shaped the analytical framework across the projection horizon. CAGRs were derived from capacity buildout trajectories, electrolyzer cost curves, and carbon price elasticity modeling for methanation breakeven thresholds.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU ETS carbon price volatility and nickel supply disruption scenarios. Forecasts reflect assumptions on RED III renewable gas quota enforcement and Gas Directive tariff parity rulings. A model refresh is warranted upon material change in EU F-Gas Regulation amendment timelines or Federal Network Agency synthetic methane grid injection standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging Energy Technologies
Nanotechnology in Energy Market
Emerging Energy Technologies
Decarbonization Market
Emerging Energy Technologies
Advanced Energy Market
Emerging Energy Technologies
United States Clean Coal Technologies Market
Emerging Energy Technologies
Clean Technology Market
Emerging Energy Technologies
Clean Coal Technologies Sales Market
Emerging Energy Technologies
Global Power-To-X Market
Emerging Energy Technologies
Cryogenic Technology Market
Emerging Energy Technologies
Energy Transition Market
Emerging Energy Technologies
Global Microreactor Technology Market
Emerging Energy Technologies
Europe Clean Coal Technologies Market
Emerging Energy Technologies
Multi Energy Systems Market