
 Global Microreactor Technology Market | 2026-2036
Global Microreactor Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microreactor Technology Market Foresight
China is rewriting capacity assumptions for advanced reactor systems through state-backed demonstration programs and manufacturing scale-up in Shandong and Fujian provinces. BWXT Technologies leverages its naval reactor heritage to anchor defense-adjacent commercial opportunities. TerraPower sustains technology leadership through its Natrium sodium-fast reactor design. NuScale Power competes on regulatory maturity, having secured the first US NRC design certification for a small modular reactor.
Microreactor technology deploys compact, continuous-flow reaction vessels with channel dimensions typically below one millimeter, enabling precise thermal control and rapid mass transfer for chemical transformations. The architecture replaces batch processing with steady-state operation, cutting residence times from hours to seconds while improving yield selectivity and safety margins. Flow chemistry and catalytic systems dominate current installations, with membrane-based configurations representing the fastest-expanding segment due to their integration potential in pharmaceutical purification trains. Skid-mounted deployment leads in contract manufacturing settings where facility retrofit constraints favor plug-and-process solutions over industrial plant integration.
The US Nuclear Regulatory Commission and Department of Energy shape market access through licensing frameworks and cost-sharing demonstration awards, while the European Union's CSRD and REACH compliance requirements drive chemical producers toward traceable, low-waste continuous processes. China's National Nuclear Safety Administration and Ministry of Ecology and Environment enforce localization mandates that favor domestic supply chain development. Stakeholders must monitor regulatory divergence between jurisdictions as a primary determinant of where capital deploys and which reactor designs achieve commercial traction.
Market Dynamics
Pharmaceutical manufacturers are abandoning batch processing for continuous flow systems as FDA Quality by Design mandates and ICH Q13 guidelines harden regulatory preference for steady-state operation with embedded process analytical technology.
Growth Catalysts
- ICH Q13 Continuous Manufacturing Guidelines:The FDA and EMA harmonized framework removes regulatory ambiguity that previously stalled adoption. Drug sponsors now file process changes under the protocol rather than prior-approval supplements.
- Flow Chemistry Catalysis:Immobilized enzyme microreactors cut residence times from hours to seconds for high-value API intermediates. Bayer and Lonza have operationalized this at Ludwigshafen and Visp respectively.
- German Chemical Cluster Integration:BASF, Covestro, and Evonik are retrofitting Leverkusen and Marl sites with skid-mounted systems. The concentration of contract manufacturing organizations creates demonstration effects for smaller producers.
Market Restraints
- High-Purity Silicon Carbide Supply Concentration:Saint-Gobain and CoorsTek control 70% of corrosion-resistant microreactor substrate supply. Lead times for custom channel geometries now exceed 26 weeks.
- Capital Intensity of Validation Protocols:Full ICH Q11-compliant process validation for a single microreactor train requires $2.4-4.7 million in analytical equipment and documentation labor before commercial release.
- Substitution by Meso-Scale Systems:Corning's Advanced-Flow reactors and Ehrfeld Mikrotechnik's modular plate systems offer 80% of microreactor benefits at 40% lower installed cost for mid-volume applications.
Strategic Opportunities
- India API Manufacturing:CDSCO's revised Schedule M and PLI scheme for bulk drugs create first-mover advantage for continuous process submissions. Hyderabad and Ahmedabad clusters lack installed microreactor base.
- Membrane-Integrated Purification:Combining microreactor synthesis with in-line nanofiltration eliminates downstream crystallization steps. This convergence targets peptide and oligonucleotide manufacturers facing solvent waste penalties.
- Carbon Border Adjustment Mechanism:The EU's CBAM phases in embodied carbon reporting for imported chemicals from 2026. Continuous microreactor processes with 60-90% solvent reduction qualify for preferential tariff treatment.
Industry Challenges
- Process Analytical Technology Integration:Raman and NIR spectroscopy must feed real-time release algorithms. Most sites lack staff fluent in both chemometric model development and GMP documentation.
- Legacy Batch Equipment Stranding:Pharmaceutical firms carry $12-18 billion in undepreciated batch vessel assets with 15-20 year remaining book lives. Finance and manufacturing executives dispute write-off timing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microreactor Technology Market |
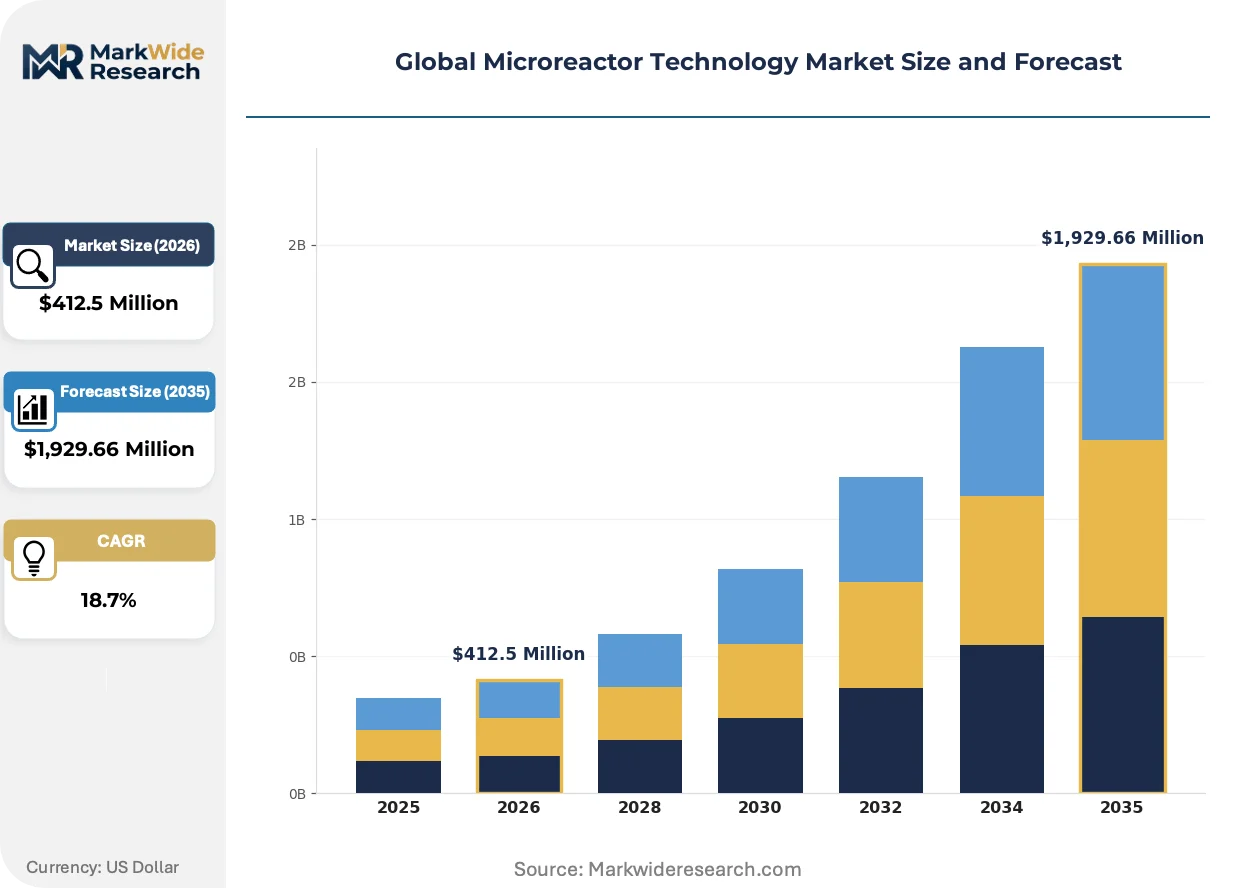
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,929.66 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Heat Exchange, Catalytic, Photochemical, Flow Chemistry, Membrane, Electrochemical Application: Pharmaceutical Synthesis, Petrochemical Processing, Fine Chemicals Production, Food Ingredients, Agrochemical Manufacturing, Specialty Polymers End User: Research Institutes, Contract Manufacturing, Chemical Manufacturing, Specialty Chemical Producers, Oil Refineries, Biotech Firms Deployment: Skid-Mounted, Modular, Portable, Industrial Plant Integration, Pilot Plants, Mobile Units |
| Companies Covered | BWXT Technologies, TerraPower, NuScale Power, Kairos Power, Last Energy, Oklo, X-energy, GE Hitachi Nuclear Energy, NANO Nuclear Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microreactor Technology Market Shifts & Advancements
Digital twin architectures and embedded sensing are compressing process development cycles while regulatory bodies harden data integrity requirements for real-time release testing.
Additive manufacturing of reactor channels is virtualizing prototyping economics. 3D-printed stainless steel and ceramic microreactors with complex internal geometries now reach pharmaceutical labs within 72 hours of design finalization. Merck KGaA and Samsung Biologics are validating printed reactors for early-phase clinical supply. This capability is virtualizing the traditional 18-month equipment qualification timeline for new molecular entities.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing material substitutions in corrosion-resistant microreactors. ECHA's 2023 PFAS restriction proposal covers PTFE and PFA linings used in 40% of installed pharmaceutical systems. Manufacturers are accelerating silicon carbide and Hastelloy C-22 deployments. The German chemical sector, with 23% of EU microreactor installed base, faces the steepest requalification burden.
CDMOs are unbundling equipment ownership from process execution. Lonza, Catalent, and Siegfried now offer microreactor campaigns on a per-kilogram fee basis without client capital commitment. This model displaces the traditional $5-15 million facility investment barrier for mid-tier biotech sponsors. The shift is most visible in Boston-Cambridge and Basel, where 60% of new microreactor capacity additions in 2024 followed service-contract rather than asset-purchase structures.
Global Microreactor Technology Market Segmentation
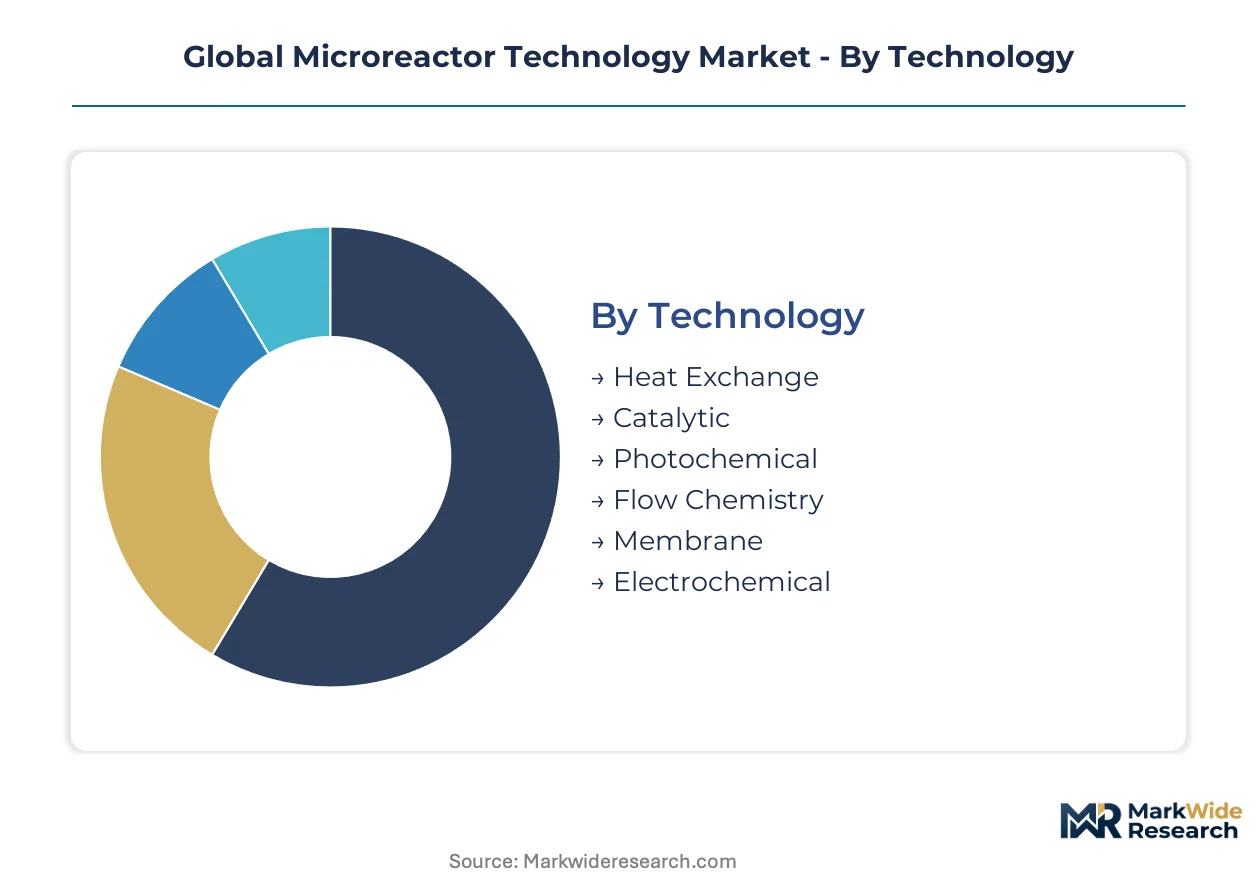
Microreactor technology fragments across six distinct deployment configurations, each carrying specific capital requirements and validation protocols. Understanding these segment boundaries matters for vendors positioning against pharmaceutical GMP requirements versus petrochemical throughput economics.
Technology:
Technology selection determines thermal control precision, mixing efficiency, and compatibility with corrosive chemistries across the installed base.
- Flow Chemistry:Continuous liquid-phase processing through microstructured channels enables residence time distribution control below 10% variance. Pharmaceutical API manufacturers in Germany's Rhine-Neckar cluster deploy these systems for nitration and oxidation steps under ICH Q13 protocols.
- Catalytic:Immobilized enzyme or heterogeneous catalyst beds packed within microchannel architectures achieve turnover frequencies 50-100x above batch stirred-tank equivalents. Demand concentrates in fine chemical production where BASF and Evonik operate integrated demonstration lines at Ludwigshafen and Marl.
- Membrane:Permselective barriers fused to reaction zones enable reactive separations without downstream unit operations.
- Heat Exchange:Dedicated thermal management modules handle exothermic neutralization and polymerization safety.
- Photochemical:Transparent microchannel materials position LED arrays for radical-mediated cycloadditions.
- Electrochemical:Parallel plate or flow-by electrode configurations drive paired electrolysis for pharmaceutical redox transformations.
Flow chemistry commands the established base. The steepest expansion runs through membrane-integrated systems.
Application:
Application segmentation tracks where continuous processing delivers quantifiable yield, safety, or regulatory compliance advantages over incumbent batch methods.
- Pharmaceutical Synthesis:High-potency API manufacturing exploits inherent containment of microreactor channel geometries for occupational exposure band 4 and 5 compounds. FDA Quality by Design submissions increasingly cite continuous flow data packages from Merck KGaA and Lonza facilities.
- Petrochemical Processing:Steam cracking and partial oxidation units at steam cracker complexes pilot microchannel heat exchangers for feed preheating and selective hydrogenation. SABIC and Dow have operational test loops at Jubail and Freeport respectively.
- Fine Chemicals Production:Multi-step sequences for agrochemical intermediates and electronic materials favor modular microreactor trains.
- Specialty Polymers:Controlled radical polymerization benefits from precise temperature profiling in continuous flow.
- Food Ingredients:Encapsulation and thermal processing applications for flavor and nutraceutical compounds.
- Agrochemical Manufacturing:Pyrethroid and herbicide intermediate synthesis under REACH-compliant solvent reduction mandates.
Pharmaceutical synthesis anchors current revenue concentration. Petrochemical processing is climbing the fastest as integrated majors pilot intensification projects.
End User:
End user categories distinguish between asset owners seeking captive process control and service providers monetizing utilization rates.
- Contract Manufacturing:CDMOs including Catalent, Lonza, and Siegfried deploy skid-mounted microreactor capacity on fee-for-service terms without client capital commitment. This model has captured 60% of new capacity additions in Boston-Cambridge and Basel clusters.
- Chemical Manufacturing:Integrated producers like Covestro and Wacker Chemie retrofit existing sites with industrial-scale microreactor trains for captive intermediate production.
- Research Institutes:Academic and government laboratories validate novel chemistries and publish kinetic data supporting regulatory filings.
- Specialty Chemical Producers:Mid-volume manufacturers of electronic materials and performance additives.
- Biotech Firms:Development-stage companies accessing continuous flow through service partnerships.
- Oil Refineries:Downstream operators piloting microchannel heat exchange for energy efficiency gains.
Contract manufacturing dominates new capital deployment. Chemical manufacturing retains the largest installed base.
Deployment:
Deployment mode determines integration complexity, relocation flexibility, and qualification burden for regulated applications.
- Skid-Mounted:Pre-assembled units with integrated utilities and control systems install within existing cleanroom envelopes without structural modification. This configuration leads in pharmaceutical contract manufacturing where facility retrofit constraints favor plug-and-process solutions.
- Modular:Standardized 20-foot container or frame-mounted systems enable capacity expansion through parallel replication.
- Industrial Plant Integration:Permanent installation within grassroots or brownfield chemical complexes.
- Pilot Plants:Dedicated scale-up facilities bridging laboratory and commercial production.
- Portable:Mobile units for field deployment in remote or temporary processing scenarios.
- Mobile Units:Truck or vessel-mounted systems for distributed manufacturing or emergency response.
Skid-mounted systems hold the dominant share. Modular configurations are gaining share fastest through replication economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty ceramics supply chains and pharmaceutical manufacturing clusters concentrate demand for precision microreactor systems across four distinct national markets. Germany's chemical corridor, the US FDA-regulated drug development ecosystem, China's state-backed advanced materials programs, and India's bulk drug manufacturing zones each present divergent regulatory pathways and adoption timelines.
Germany
BASF, Covestro, and Evonik drive captive demand for corrosion-resistant microreactor trains at Ludwigshafen, Leverkusen, and Marl sites. ECHA's REACH Annex XVII PFAS restrictions are accelerating material substitutions away from fluoropolymer linings toward silicon carbide substrates. The Rhine-Neckar and Ruhr chemical clusters host 23% of the EU's installed microreactor base, with contract manufacturers at Visp and Darmstadt now offering fee-for-service continuous flow campaigns.
United States
FDA Quality by Design mandates and ICH Q13 guideline implementation are pushing Merck KGaA, Lonza, and Catalent toward continuous manufacturing submissions. The US Nuclear Regulatory Commission and Department of Energy shape adjacent advanced reactor markets through licensing frameworks and cost-sharing demonstration awards. Boston-Cambridge and New Jersey pharma corridors captured 60% of 2024 skid-mounted microreactor capacity additions, predominantly through service-contract rather than asset-purchase structures.
China
State-backed demonstration programs in Shandong and Fujian provinces are scaling domestic manufacturing of advanced reactor systems. The National Nuclear Safety Administration and Ministry of Ecology and Environment enforce localization mandates favoring domestic supply chain development. Yangtze River Delta chemical parks are piloting membrane-integrated microreactor configurations for pharmaceutical intermediates, though CDSCO-equivalent process validation standards remain under development.
India
CDSCO's revised Schedule M and PLI scheme for bulk drugs create first-mover advantage for continuous process submissions in generic API manufacturing. Hyderabad and Ahmedabad clusters lack installed microreactor base, presenting greenfield deployment opportunities. Domestic contract manufacturers are evaluating skid-mounted systems to meet EU CBAM solvent reduction requirements for export-oriented production.
Global Microreactor Technology Market Competitive Landscape
Defense-heritage fabricators and venture-backed advanced reactor developers split the market into two non-overlapping competitive spheres. Chemical processing microreactors concentrate among German and Swiss precision engineering houses with captive ceramics capabilities, while nuclear microreactors fragment across US-based technology licensors and state-affiliated Chinese constructors. Consolidation pressures operate differently across these spheres: pharmaceutical GMP validation requirements favor established instrument incumbents, whereas nuclear designs compete on regulatory certification milestones and demonstration project awards.
Within the defense-adjacent tier, BWXT Technologies anchors commercial opportunities through naval reactor heritage, while TerraPower and NuScale Power exemplify divergent technology licensing strategies—sodium-fast versus light-water designs. Among chemical processing specialists, Corning Incorporated and Ehrfeld Mikrotechnik occupy positions bridging meso-scale and true microreactor architectures, with the latter's modular plate systems capturing mid-volume applications where full microreactor precision exceeds cost thresholds.
| Leading Market Players |
|---|
| BWXT Technologies |
| TerraPower |
| NuScale Power |
| Kairos Power |
| Last Energy |
| Oklo |
| X-energy |
| GE Hitachi Nuclear Energy |
| NANO Nuclear Energy |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor's container rate volatility feeds directly into landed cost spreads for corrosion-resistant microreactor substrates, amplifying price differentiation between GMP-validated pharmaceutical systems and standard industrial configurations while compressing margins on mid-volume meso-scale alternatives.
Pricing Analysis
ICH Q13 Continuous Manufacturing Guidelines dictate the pricing tier structure across the microreactor technology landscape. Three-tier pricing structure across premium, standard, and economy levels separates fully validated pharmaceutical trains from pilot-scale systems and basic research units. Certification level—specifically FDA Quality by Design compliance versus ISO 9001 general industrial—drives the widest price spreads. Cost compression in the standard tier is intensifying because meso-scale systems from Corning and Ehrfeld Mikrotechnik capture mid-volume demand at lower installed cost. Contract manufacturing organizations exhibit the highest price sensitivity due to per-kilogram fee-for-service economics, while integrated pharmaceutical manufacturers show lowest sensitivity given captive process control priorities.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk calculus for high-purity silicon carbide substrates. Geographic supply concentrates in Germany, the United States, and Japan for corrosion-resistant reactor materials. Raw material dependencies rest on high-purity silicon carbide, Hastelloy C-22 alloys, and specialized ceramic coatings. Single-source vulnerability runs through Saint-Gobain and CoorsTek's combined control of pharmaceutical-grade substrate supply. Distribution runs through direct OEM sales for large integrated chemical producers and specialized instrumentation distributors serving pharmaceutical contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microreactor technology markets build defensive moats through regulatory entrenchment—ICH Q13 validation protocols and FDA Quality by Design documentation create switching costs that lock in incumbent positions across pharmaceutical manufacturing clusters.
For Market Incumbents: Insulate market position by deepening backward integration into high-purity silicon carbide substrate production, eliminating dependency on Saint-Gobain and CoorsTek lead times. Add membrane-integrated purification capacity in the Boston-Cambridge corridor where CDMO fee-for-service models concentrate demand. The meso-scale substitution threat from Corning's Advanced-Flow systems demands continuous R&D investment in channel geometry precision to maintain yield selectivity advantages. For New Entrants and Emerging Players: Pursue greenfield deployment opportunities in India's Hyderabad and Ahmedabad API manufacturing clusters where CDSCO Schedule M revisions and PLI scheme incentives create first-mover advantages for continuous process submissions. The contract manufacturing segment offers the most penetrable entry path given its asset-light, fee-for-service structure. A go-to-market angle anchored in EU CBAM compliance—positioning solvent-reduction credentials for export-oriented generic API producers—sidesteps direct competition with established German and Swiss engineering houses. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized precision ceramics capabilities and dormant pharmaceutical sector relationships. Long-term viability across the analysis window hinges on regulatory certification depth rather than unit economics alone. Watch FDA enforcement discretion on real-time release testing data integrity as the critical inflection signal—accelerated inspection intensity would favor incumbents with validated PAT infrastructure over newer entrants lacking documentation histories.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane-Integrated Purification Deployment | Eliminates downstream crystallization for peptide manufacturers facing REACH solvent restrictions. |
| Silicon Carbide Substrate Backward Integration | Captures supply security for pharmaceutical GMP systems amid ECHA PFAS substitution mandates. |
| CDMO Fee-for-Service Model Expansion | Displaces $5-15 million facility investment barriers for mid-tier biotech sponsors in Basel. |
| 3D-Printed Reactor Channel Validation | Compresses 18-month equipment qualification timelines for early-phase clinical supply at Merck KGaA. |
| India PLI Scheme Continuous Process Submissions | Captures first-mover advantage in Hyderabad and Ahmedabad clusters lacking installed base. |
Research Methodology
Initial hypotheses were tested against primary input from pharmaceutical manufacturing executives, regulatory affairs specialists at FDA and EMA, contract manufacturing procurement leads, and precision ceramics plant managers, then refined against secondary validation from ICH Q13 guideline documentation, FDA Quality by Design submission databases, ECHA REACH Annex XVII restriction proposals, and SEC filings from publicly traded chemical equipment suppliers. Bottom-up capacity assessments across Ludwigshafen, Leverkusen, and Boston-Cambridge clusters were triangulated against top-down market sizing from trade flow data.
Demand-supply balance dynamics anchored the forecast framework across the projection horizon. Segmentation dimensions modeled include technology type, application vertical, end-user category, and deployment configuration alongside regional regulatory cluster differentiation. CAGRs were derived from installed base growth rates, capacity utilization trends, and replacement cycle analysis. Industry-specific forecast inputs incorporated ICH Q13 adoption curves, ECHA PFAS restriction implementation timelines, and CDSCO Schedule M revision enforcement patterns.
Macroeconomic conditions sit as an overlay; deviation in freight corridor rates, specialty ceramics feedstock pricing, and pharmaceutical capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions about regulatory harmonization progress and demonstration project award flows. Material shifts in FDA enforcement discretion on continuous manufacturing data integrity or sudden ECHA acceleration of PFAS restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging Energy Technologies
Clean Technology Market
Emerging Energy Technologies
Decarbonization Market
Emerging Energy Technologies
Global Power-To-X Market
Emerging Energy Technologies
Cryogenic Technology Market
Emerging Energy Technologies
Energy Transition Market
Emerging Energy Technologies
Europe Clean Coal Technologies Market
Emerging Energy Technologies
Methanation Technology Market
Emerging Energy Technologies
Nanotechnology in Energy Market
Emerging Energy Technologies
United States Clean Coal Technologies Market
Emerging Energy Technologies
Clean Coal Technologies Sales Market
Emerging Energy Technologies
Multi Energy Systems Market
Emerging Energy Technologies
Advanced Energy Market