
 Nanotechnology in Energy Market | 2026-2036
Nanotechnology in Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Nanotechnology in Energy Market Foresight
PhD-level electrochemist shortages across North American battery corridors is redrawing competitive boundaries for advanced anode developers. Sila Nanotechnologies leverages silicon nanocomposite expertise to anchor its position in next-generation lithium-ion architectures. Amprius Technologies dominates high-energy-density silicon nanowire anodes for aviation and defense applications. QuantumScape sustains solid-state battery development through proprietary ceramic nanolayer separators.
Nanotechnology in energy encompasses the manipulation of matter at 1-100 nanometer scales to engineer materials with quantum-confined electronic, thermal, and catalytic properties for power generation, conversion, and storage systems. Solid-state electrolytes employing lithium lanthanum zirconium oxide nanograins achieve ionic conductivities exceeding 10⁻³ S/cm at room temperature, enabling safer, higher-voltage cell architectures. Nanomaterials command the largest product-type position due to established manufacturing infrastructure for carbon black and metal oxide additives. Energy storage applications are expanding fastest as silicon nanowire and lithium metal anodes approach commercial scale. Carbon nanotube conductive additives in cathode slurries concentrate margin pools through premium pricing tied to batch consistency and defect control.
The EPA regulates nanomaterial disposal under TSCA Section 5 premanufacture notification rules, while the EU REACH framework mandates registration and safety dossiers for nanoscale substances imported above one ton annually. China's SAMR enforces GB standards for nano-enabled battery materials, creating divergent compliance pathways that fragment supplier qualification timelines. Stakeholders must monitor evolving nanomaterial classification thresholds across jurisdictions to preempt supply chain exclusions.
Market Dynamics
Battery-grade nanomaterial supply chains are compressing qualification timelines as electric vehicle OEMs enforce stricter cathode purity specifications, forcing raw material processors to retrofit atomization and calcination lines.
Growth Catalysts
- EU Green Deal clean energy mandates:Binding carbon neutrality targets for 2050 are tightening material traceability requirements across cell manufacturing, accelerating substitution of conventional graphite with engineered silicon nanocomposites in anode formulations.
- Aviation electrification:Defense contractors and commercial airframers are qualifying silicon nanowire anodes for unmanned aerial systems and regional electric aircraft, creating pull-through demand for high-energy-density cell architectures.
- Jiangsu and Guangdong production clusters:Concentrated cathode-active nanomaterial capacity in these Chinese provinces is achieving economies of scale that lower unit costs for nickel-rich layered oxide precursors.
Market Restraints
- High-purity precursor cost volatility:Battery-grade nickel sulfate and cobalt hydroxide prices swing with LME trading patterns, compressing margins for nanostructured cathode material producers locked into annual supply contracts.
- PhD-level electrochemist scarcity:North American battery corridors face acute talent shortages in solid-state electrolyte formulation and silicon anode cycling stability, elongating R&D timelines for next-generation architectures.
- Divergent nanomaterial classification thresholds:EPA TSCA Section 5 premanufacture notification rules, EU REACH registration mandates for nanoscale substances above one ton annually, and China's SAMR GB standards create fragmented supplier qualification pathways.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cell manufacturing:Production-linked incentives are attracting nanomaterial suppliers to establish localized precursor synthesis and surface modification capabilities.
- Solid-state electrolyte-ceramic nanolayer convergence:Lithium lanthanum zirconium oxide nanograins paired with dry electrode coating processes are enabling safer, higher-voltage cell designs with simplified thermal management.
- Direct OEM procurement of carbon nanotube conductive additives:Cathode slurry manufacturers are bypassing traditional distributor networks to secure batch-consistent, low-defect nanotube supply through long-term offtake agreements.
Industry Challenges
- Multi-jurisdictional safety dossier compilation:Nanomaterial registration under EPA, ECHA, and SAMR frameworks demands toxicology data packages that extend commercialization timelines by 18-24 months.
- Legacy wet electrode coating line retrofit costs:Transitioning to nanostructured active material slurries requires capital-intensive slot-die equipment upgrades and solvent recovery system overhauls.
- IP fragmentation across ceramic separator patents:Licensing complexity for oxide nanolayer architectures is forcing cell manufacturers into defensive patent pools or costly cross-licensing arrangements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanotechnology in Energy Market |
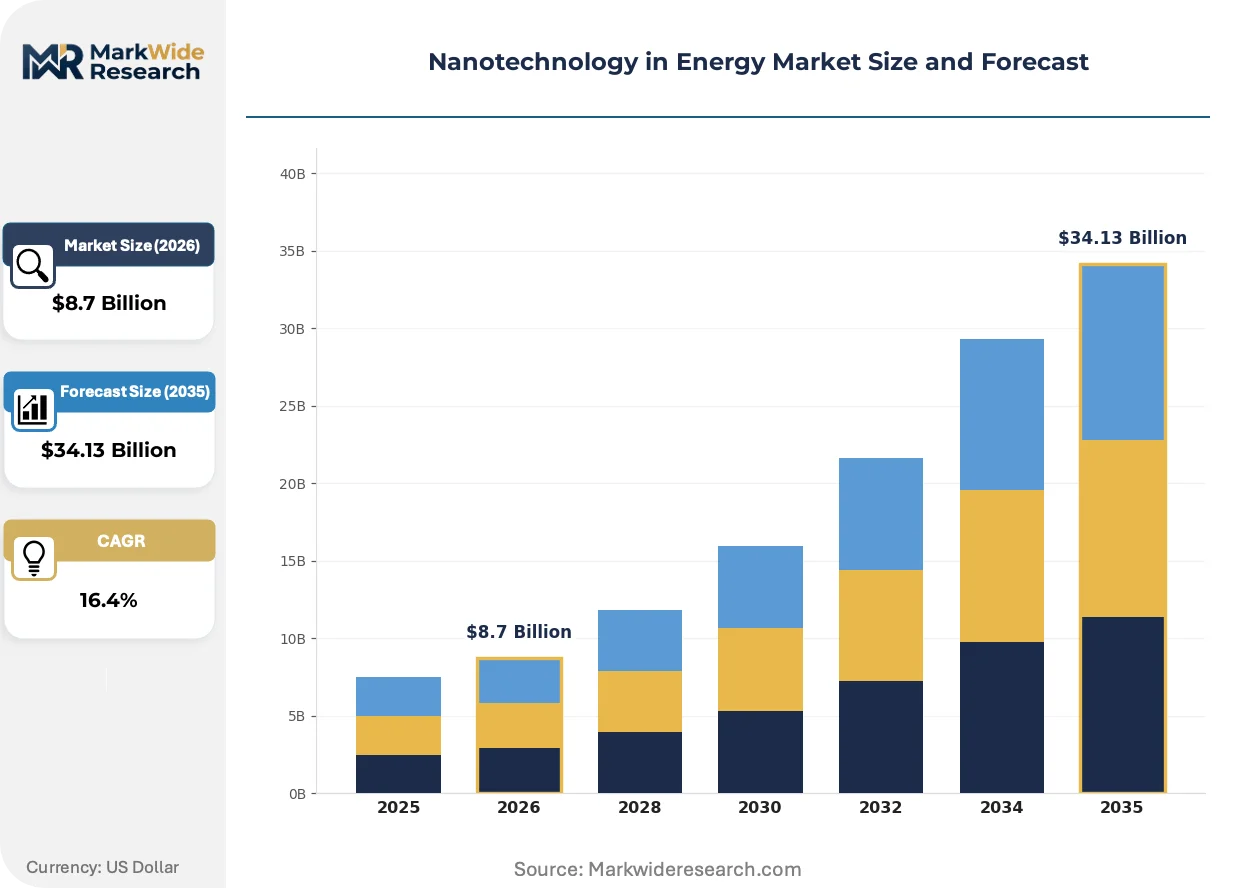
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nanomaterials, Nanocapsules, Nanocomposites, Nanostructured Coatings Application: Energy Storage, Solar Cells, Fuel Cells, Photovoltaics End User: Utilities, Industrial, Commercial, Residential Technology: Advanced Materials, Quantum Dots, Carbon Nanotubes, Nanowires |
| Companies Covered | Electrovaya, Sila Nanotechnologies, QuantumScape, Zentek Ltd., Forge Nano, Amprius Technologies, Altair Nanotechnologies, NVE Corporation, Enovix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanotechnology in Energy Market Shifts & Advancements
Silicon nanocomposite anode technologies are rewriting energy density benchmarks across transportation electrification, while regulatory frameworks race to keep pace with nanomaterial scale-up. Three developments are commanding strategic attention.
Silicon nanowire architectures are supplanting conventional graphite in premium cell designs by accommodating volume expansion during lithiation. Aviation and defense contractors are accelerating qualification programs for these anodes, compressing the timeline for high-energy-density batteries to reach commercial scale in weight-critical applications.
REACH mandates for nanoscale substance registration and safety dossiers are tightening import controls into European manufacturing zones. Battery material processors must now maintain separate formulation records and toxicology profiles for nanostructured versus conventional precursors, elevating compliance costs most acutely for mid-tier cathode suppliers without dedicated regulatory affairs functions.
Electric vehicle OEMs are consolidating nanomaterial procurement through direct technical partnerships rather than commodity spot markets. Tier-1 cell manufacturers are responding by embedding application engineers at customer sites, with this relationship-intensive model most visible in Germany's automotive supply chain where BMW and Volkswagen have established dedicated nanomaterial qualification labs.
Nanotechnology in Energy Market Segmentation
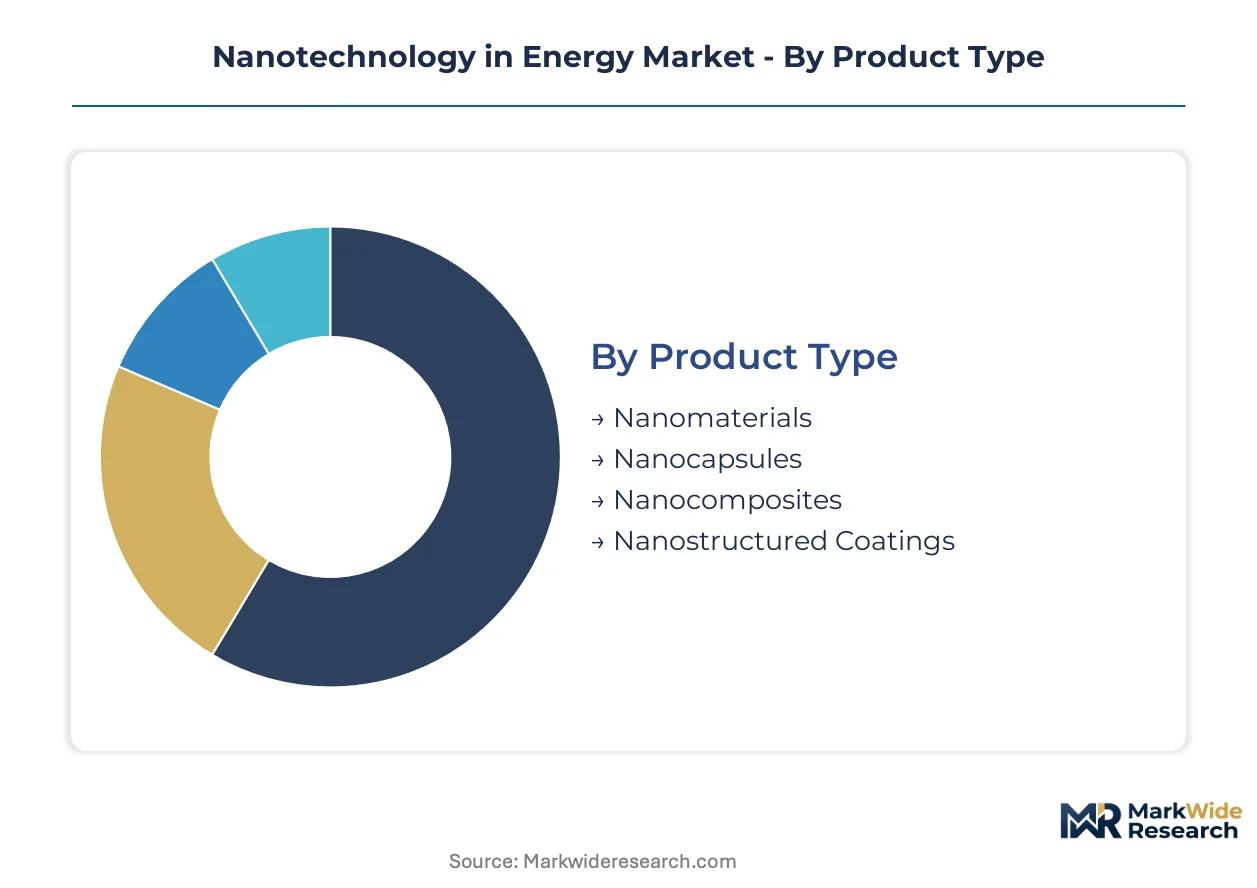
Nanotechnology in energy demands precise segmentation because material specifications diverge sharply across storage versus generation applications. Product purity thresholds and regulatory classifications reshape supplier economics differently within each category.
Product Type:
Substitution pressure from conventional bulk materials weighs heaviest on nanocomposites and nanostructured coatings, where cost-performance trade-offs against standard additives remain unresolved.
- Nanomaterials:Carbon black and metal oxide powders constitute the established manufacturing base, with batch consistency tied to defect control commanding premium pricing. Demand concentrates in China's Jiangsu and Guangdong cathode production clusters where nickel-rich layered oxide precursors achieve scale economies.
- Nanocomposites:Silicon-carbon matrices accommodate volume expansion during lithiation, enabling higher energy densities than graphite anodes. Aviation electrification programs in defense and commercial unmanned systems are accelerating qualification timelines for these architectures.
- Nanocapsules:Encapsulated phase-change materials target thermal management in grid-scale storage installations.
- Nanostructured Coatings:Atomic-layer-deposited barrier films protect current collectors from electrolyte corrosion.
Nanomaterials anchors the volume base while nanocomposites gains share at the steepest rate.
Application:
Margin pools concentrate where certification requirements create technical moats against commodity substitution.
- Energy Storage:Solid-state electrolytes employing lithium lanthanum zirconium oxide nanograins exceed ionic conductivities of 10⁻³ S/cm at room temperature. Electric vehicle OEMs enforce stricter cathode purity specifications, compressing qualification timelines for silicon nanowire and lithium metal anode suppliers.
- Solar Cells:Quantum-confined absorber layers boost conversion efficiency in perovskite tandem architectures. India's PLI scheme for advanced chemistry cell manufacturing is attracting precursor synthesis capabilities alongside photovoltaic material investments.
- Fuel Cells:Platinum-group-metal nanocatalysts reduce loading requirements in proton-exchange membrane electrodes.
- Photovoltaics:Transparent conductive oxide nanolayers enable flexible thin-film module form factors.
Energy Storage commands the largest revenue position while Solar Cells expands most quickly through tandem cell commercialization.
End User:
Procurement scale separates capital-intensive utility deployments from distributed commercial and residential installations.
- Utilities:Grid-scale battery installations demand nanomaterial supply contracts spanning decade-long operational lifespans. Direct OEM procurement of carbon nanotube conductive additives is bypassing traditional distributor networks through long-term offtake agreements.
- Industrial:Manufacturing facilities integrate behind-the-meter storage with nanostructured electrode fast-charging capabilities.
- Commercial:Retail and office building solar-plus-storage systems prioritize payback period over technical performance thresholds.
- Residential:Rooftop photovoltaic installations with home battery backup represent price-sensitive demand with limited nanomaterial content.
Utilities anchors the volume base while Industrial climbs the fastest through manufacturing reshoring and captive power investments.
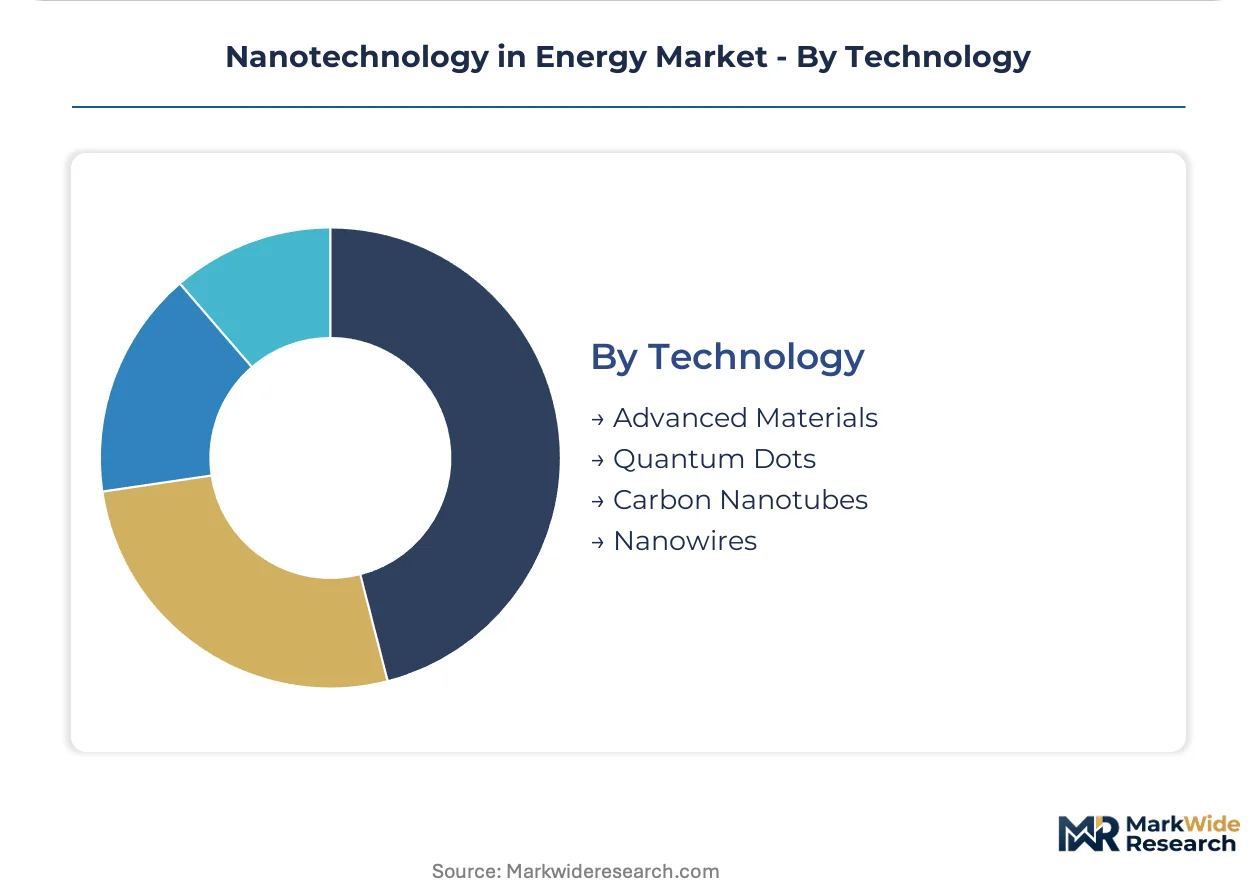
Technology:
Intellectual property fragmentation across patent estates shapes competitive access to each technology family.
- Advanced Materials:Solid-state electrolyte-ceramic nanolayer convergence pairs lithium lanthanum zirconium oxide nanograins with dry electrode coating processes. EU Green Deal clean energy mandates are tightening material traceability requirements that favor these safer, higher-voltage cell designs.
- Carbon Nanotubes:Conductive additives in cathode slurries concentrate margin pools through premium pricing tied to batch consistency. Multi-jurisdictional safety dossier compilation under EPA TSCA Section 5, EU REACH, and China's SAMR GB standards extends commercialization timelines.
- Quantum Dots:Colloidal semiconductor nanocrystals tune absorption spectra for next-generation photovoltaic stacks.
- Nanowires:Silicon nanowire architectures supplant graphite in premium cell designs by accommodating lithiation volume expansion.
Advanced Materials anchors the volume base while Carbon Nanotubes gains share at the steepest rate through direct OEM procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes nanotechnology in energy primarily for battery-grade cathode production, while the United States and Germany concentrate demand in aviation-qualified silicon anodes and solid-state electrolyte development respectively.
China
Jiangsu and Guangdong provinces host concentrated cathode-active nanomaterial production clusters achieving economies of scale for nickel-rich layered oxide precursors. SAMR enforces GB standards for nano-enabled battery materials, creating distinct compliance pathways from Western frameworks. Suzhou and Shenzhen manufacturing zones are retrofitting atomization and calcination lines to meet tightening purity specifications from electric vehicle OEMs.
United States
Defense contractors and commercial airframers are qualifying silicon nanowire anodes for unmanned aerial systems and regional electric aircraft. EPA regulates nanomaterial disposal under TSCA Section 5 premanufacture notification rules, extending supplier qualification timelines. Michigan and California battery corridors face acute PhD-level electrochemist shortages in solid-state electrolyte formulation, elongating R&D programs for next-generation architectures.
Germany
BMW and Volkswagen have established dedicated nanomaterial qualification labs, consolidating procurement through direct technical partnerships rather than commodity markets. EU Green Deal clean energy mandates and ECHA REACH registration requirements for nanoscale substances above one ton annually are tightening material traceability across cell manufacturing. Bavaria's automotive supply chain is embedding application engineers at customer sites to support relationship-intensive qualification models.
Japan
Carbon nanotube conductive additive producers are securing long-term offtake agreements with cathode slurry manufacturers bypassing traditional distributor networks. METI oversees national energy storage technology roadmaps that prioritize safer, higher-voltage cell designs. Kansai region industrial corridors are pairing lithium lanthanum zirconium oxide nanograin development with dry electrode coating process commercialization.
India
Production-linked incentive schemes for advanced chemistry cell manufacturing are attracting nanomaterial suppliers to establish localized precursor synthesis capabilities. Central Electricity Authority guidelines intersect with BIS standards for grid-scale battery installations demanding decade-long nanomaterial supply contracts. Gujarat and Maharashtra are emerging as concentrated zones for surface modification capability investments alongside photovoltaic material expansions.
Nanotechnology in Energy Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the market structure tiered by technical qualification depth and regulatory dossier completeness. The upper tier commands premium positioning through captive relationships with aviation and defense contractors, while mid-tier players compete on batch consistency for electric vehicle cathode additives. Two dominant archetypes emerge: silicon nanocomposite anode specialists and solid-state electrolyte ceramic developers. Competitive moves concentrate on capacity expansion in China's Jiangsu production cluster and strategic partnerships for direct OEM procurement bypassing distributor networks.
Among North American technology developers, Sila Nanotechnologies, QuantumScape, and Amprius Technologies occupy positions representing the silicon nanocomposite and solid-state electrolyte archetypes. These entities exemplify the integrated leader tier through their focus on next-generation lithium-ion architectures and aviation-qualified high-energy-density designs. Their geographic concentration in California battery corridors reflects the talent and capital access requirements for advanced anode and separator development.
| Leading Market Players |
|---|
| Electrovaya |
| Sila Nanotechnologies |
| QuantumScape |
| Zentek Ltd. |
| Forge Nano |
| Amprius Technologies |
| Altair Nanotechnologies |
| NVE Corporation |
| Enovix |
| Others |
Supply & Pricing Matrix
Jiangsu and Guangdong cathode cluster scale economies compress unit costs for nickel-rich layered oxide precursors while simultaneously elevating price floors for battery-grade nanomaterials outside these zones. Electric vehicle OEM procurement consolidation through direct technical partnerships rather than spot markets concentrates pricing power among qualified suppliers with complete EPA TSCA Section 5 and EU REACH dossiers.
Pricing Analysis
Long-term offtake agreements dominate procurement for carbon nanotube conductive additives and silicon nanowire anodes, displacing spot-market transactions as aviation and defense contractors secure decade-qualified supply. Three-tier pricing structure across aviation-certified, automotive-grade, and industrial-tier nanomaterials reflects batch consistency and defect control premiums. Cost compression in mid-tier cathode additives intensifies because LME-linked nickel sulfate and cobalt hydroxide volatility squeezes processors locked into annual contracts. Residential solar-plus-storage buyers exhibit highest price sensitivity while defense contractors show least elasticity due to performance-critical weight specifications.
Supply Chain Analysis
Inventory cycles for battery-grade nanomaterials stretch 18-24 months as multi-jurisdictional safety dossier compilation under EPA, ECHA, and SAMR frameworks elongates qualification timelines. Supply concentrates in China, Japan, and South Korea for cathode-active precursors, silicon nanocomposite anodes, and solid-state electrolyte ceramics respectively. Raw material flows draw from Chilean lithium brine, Indonesian nickel laterite, and DRC cobalt hydroxide, tethering cost structures to extractive geopolitics. Single-source vulnerability in ceramic nanolayer separator patents forces cell manufacturers into defensive licensing pools. Distribution runs through Tier-1 cell manufacturers embedding application engineers at OEM customer sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon nanocomposite anode commercialization and solid-state electrolyte ceramic convergence represent simultaneous technological inflections accelerating market disruption. EU Green Deal binding carbon neutrality mandates and EPA TSCA Section 5 enforcement tighten qualification barriers, compressing viable supplier sets.
For Market Incumbents: Secure captive relationships with aviation and defense contractors through dedicated qualification lab investments, insulating against silicon nanowire anode commoditization. Lock in backward integration into battery-grade nickel sulfate and cobalt hydroxide precursor supply to blunt LME price volatility margin compression. Prioritize in-house production of carbon nanotube conductive additives to defend against direct OEM procurement bypassing traditional distributor networks.
For New Entrants and Emerging Players: EU REACH registration fast-tracks for nanoscale substances above one ton annually offer white-space entry through mid-tier cathode supplier acquisition targets lacking dedicated regulatory affairs functions. India's PLI scheme for advanced chemistry cell manufacturing presents the most penetrable geography for localized precursor synthesis and surface modification capability establishment. Target solid-state electrolyte-ceramic nanolayer convergence through dry electrode coating process partnerships with Kansai region industrial corridors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated silicon nanocomposite anode developers with aviation-qualified product lines and decade-long defense supply contracts. Long-term viability across the projection horizon favors specialists with complete multi-jurisdictional safety dossiers and embedded application engineering relationships. Watch for inflection in direct OEM procurement consolidation rates as Tier-1 cell manufacturers bypass distributor networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Nanomaterial Offtake Agreement | Aviation contractors secure decade-qualified silicon nanowire anode supply from Amprius Technologies. |
| Backward Integration into Precursor Synthesis | Cathode processors acquire captive nickel sulfate capacity to blunt LME trading pattern volatility. |
| Multi-jurisdictional Dossier Completion | Suppliers preempt supply chain exclusions under EPA TSCA Section 5 and EU REACH frameworks. |
| Dry Electrode Coating Process Partnership | Kansai region developers pair lithium lanthanum zirconium oxide nanograins with simplified thermal management. |
| Direct OEM Technical Partnership | BMW and Volkswagen qualification labs embed application engineers to bypass distributor networks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA TSCA filings, ECHA REACH registrations, SAMR GB standards, and IEA energy storage technology roadmaps. Primary interviews engaged solid-state electrolyte formulation scientists, cathode slurry procurement directors, aviation battery qualification engineers, and nanomaterial regulatory affairs specialists. Secondary validation drew from customs trade data, SEC battery developer filings, and METI national technology roadmaps. Bottom-up nanomaterial demand modeling triangulates against top-down electric vehicle production forecasts.
Segmentation dimensions modeled span product type, application, end user, and technology across the projection horizon. Value outputs incorporate nanomaterial batch consistency premiums, aviation certification tier differentials, and regional regulatory compliance cost structures. CAGRs derive from electric vehicle adoption curves, aviation electrification program timelines, and solid-state battery commercialization milestones. Forecast inputs include silicon nanowire anode cycling stability improvements and ceramic nanolayer ionic conductivity thresholds.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and EPA TSCA Section 5 premanufacture notification adherence; material deviation in regulatory stringency or solid-state electrolyte technical performance would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging Energy Technologies
United States Clean Coal Technologies Market
Emerging Energy Technologies
Cryogenic Technology Market
Emerging Energy Technologies
Multi Energy Systems Market
Emerging Energy Technologies
Clean Coal Technologies Sales Market
Emerging Energy Technologies
Advanced Energy Market
Emerging Energy Technologies
Decarbonization Market
Emerging Energy Technologies
Methanation Technology Market
Emerging Energy Technologies
Global Microreactor Technology Market
Emerging Energy Technologies
Global Power-To-X Market
Emerging Energy Technologies
Clean Technology Market
Emerging Energy Technologies
Europe Clean Coal Technologies Market
Emerging Energy Technologies
Energy Transition Market