
 Partial Oxidation Blue Hydrogen Market | 2026-2036
Partial Oxidation Blue Hydrogen Market Size, Share, and Industry Trends Forecast 2026-2036
Partial Oxidation Blue Hydrogen Market Insights
The EU Green Deal is rebalancing the cost-of-entry calculus for new hydrogen production capacity across European industrial corridors. Air Products and Chemicals leverages its Gulf Coast carbon capture infrastructure to compete on delivered cost. Linde plc anchors its position through large-scale ASU and gasification technology integration. Shell differentiates via offshore pipeline networks linking production to North Sea storage sites.
Partial oxidation blue hydrogen refers to hydrogen produced through the exothermic reaction of hydrocarbon feedstocks with a sub-stoichiometric oxygen supply, typically operating at temperatures between 1200°C and 1500°C with carbon capture rates exceeding 90% when paired with amine-based absorption systems. The process yields a syngas mixture subsequently processed to high-purity hydrogen for ammonia synthesis and refinery hydrocracking applications. Catalytic partial oxidation dominates current deployment due to mature reactor designs and established catalyst supply chains, while autothermal reforming captures expanding interest from operators seeking thermal efficiency gains through integrated steam injection. Natural gas feedstock configurations sustain the largest margin pools given existing pipeline infrastructure, though biomethane pathways are gaining project finance traction in jurisdictions with renewable gas certificates.
EPA greenhouse gas reporting protocols and the EU F-Gas Regulation shape equipment specifications and emission verification requirements for cross-border hydrogen trade. Germany's KBA and national carbon accounting frameworks enforce transport-sector offtake standards that filter back to production certification. Stakeholders must monitor evolving carbon intensity thresholds in offtake contracts and storage site licensing timelines to preserve project bankability.
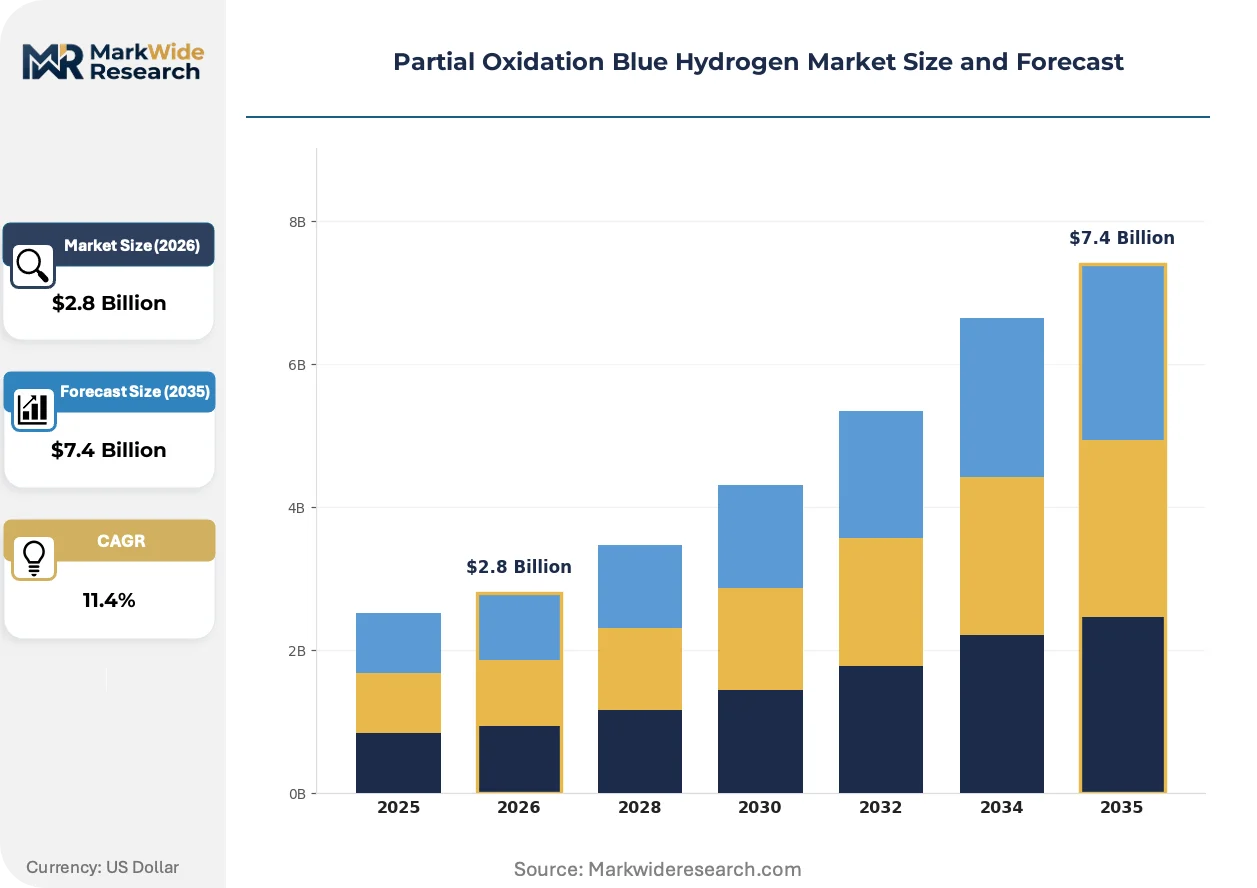
Market Dynamics
The EU Green Deal's carbon border adjustment mechanism is restructuring cost competitiveness across European hydrogen supply chains, forcing conventional gray hydrogen producers to absorb compliance premiums or exit refinery feedstock contracts.
Growth Catalysts
- Refinery Hydrocracking Demand:German industrial clusters in the Ruhr and North Sea ports are anchoring long-term offtake agreements for low-carbon hydrogen feedstock, creating predictable demand basins for new production capacity.
- EU F-Gas Regulation:Equipment specifications for carbon capture systems are tightening emission verification standards, accelerating replacement cycles for legacy amine absorption infrastructure.
- Biomethane Pathways:Renewable gas certificate frameworks in jurisdictions with established biomethane supply chains are opening margin pools for feedstock-flexible partial oxidation configurations.
Market Restraints
- Natural Gas Price Volatility:Feedstock cost swings compress project IRRs and deter long-term offtake commitments from risk-averse industrial buyers.
- Carbon Capture Equipment Supply Concentration:Amine-based absorption system manufacturing concentrates in a narrow supplier base, creating bottleneck risks for project timelines.
- Autothermal Reforming Substitution:Thermal efficiency advantages of integrated steam injection processes threaten catalytic partial oxidation market share in new-build capacity.
Strategic Opportunities
- Ammonia Synthesis Integration:Coastal production sites with direct pipeline access to fertilizer manufacturing clusters can capture vertical margin through captive hydrogen consumption.
- Offshore Pipeline Networks:North Sea storage site connectivity enables producers to monetize carbon sequestration as a separate revenue stream from hydrogen sales.
- German Transport-Sector Mandates:KBA enforcement of carbon intensity thresholds for fuel-cell vehicle hydrogen is creating certified-premium product tiers.
Industry Challenges
- High-Temperature Reactor Engineering Talent:Shortages of specialists capable of designing 1200°C to 1500°C process vessels are extending commissioning timelines.
- Cross-Border Certification Complexity:Divergent EPA greenhouse gas reporting protocols and EU emission verification standards create documentation burdens for export-oriented producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Partial Oxidation Blue Hydrogen Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Production Technology: Catalytic Partial Oxidation, Autothermal Reforming, Steam Methane Reforming, Dry Reforming, Plasma Reforming Feedstock Type: Natural Gas, Coal Bed Methane, Biomethane, LPG, Naphtha End User Industry: Refining, Ammonia Production, Methanol Synthesis, Power Generation, Synthetic Fuels Deployment Scale: Small-Scale, Mid-Scale, Large-Scale, Modular Units |
| Companies Covered | Air Products and Chemicals, Air Liquide, Linde plc, Shell, BP, ExxonMobil, Equinor, Eni, Technip Energies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Partial Oxidation Blue Hydrogen Market Trends and Innovations
Process intensification and digital control systems are compressing reactor footprints while tightening carbon capture rates, reshaping capital efficiency benchmarks for new production facilities.
Autothermal reforming configurations are automating thermal management through integrated oxygen-steam injection control systems. Refinery operators with existing syngas processing infrastructure are adopting these units at pilot scale. The technology is automating heat recovery optimization, reducing auxiliary fuel consumption below catalytic partial oxidation baselines.
The EU Green Deal's carbon border adjustment mechanism is tightening compliance costs for imported gray hydrogen. Industrial buyers in German chemical corridors are rewriting offtake contracts to include certified carbon intensity clauses. Ammonia synthesis facilities with existing pipeline connections are responding fastest, locking in blue hydrogen supply before border adjustments take full effect.
Long-term offtake contracting is displacing spot-market purchases among refinery hydrogen buyers. Procurement teams are signing 10-15 year agreements with fixed carbon intensity floors, transferring operational risk to producers. This pattern concentrates most visibly in the Ruhr industrial cluster, where hydrocracking capacity expansions require guaranteed low-carbon feedstock supply.
Partial Oxidation Blue Hydrogen Market Segmentation
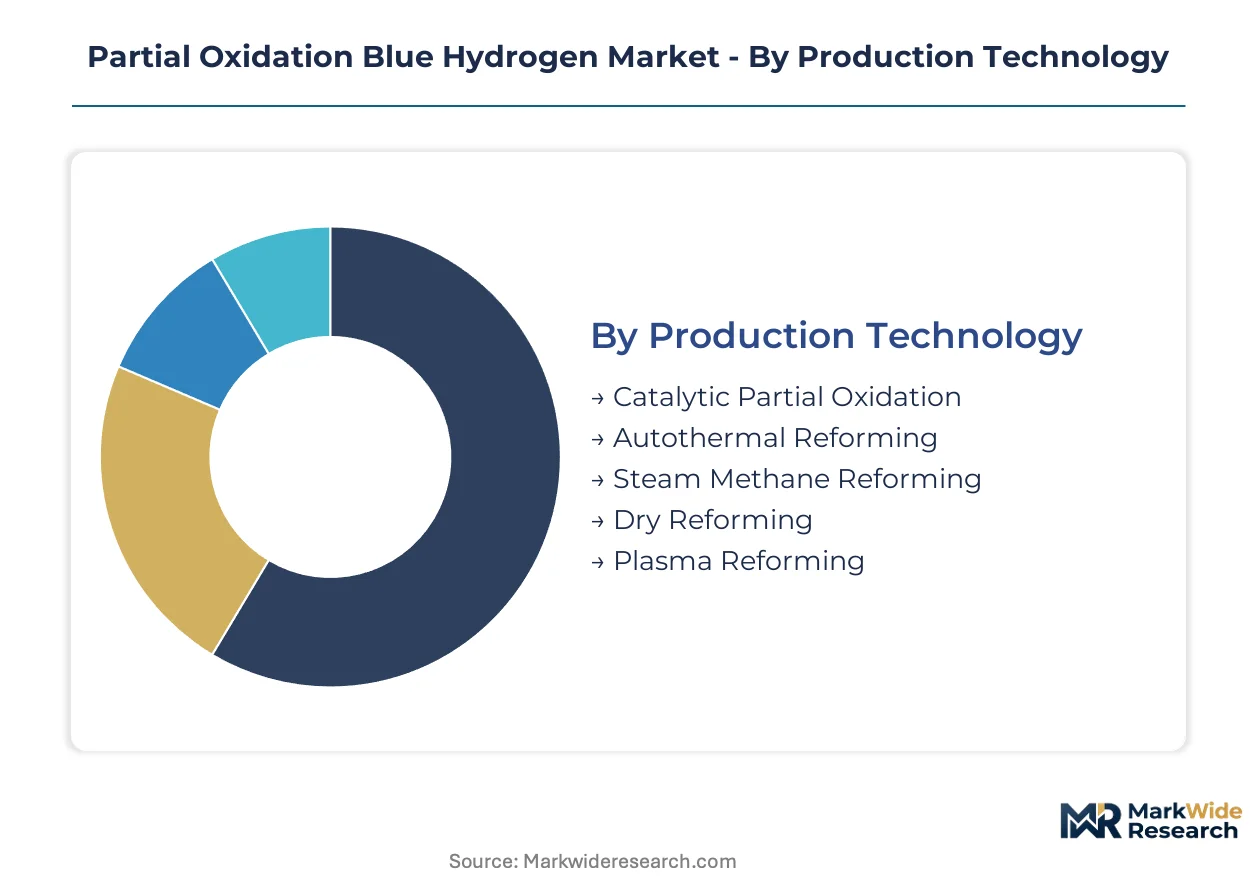
Technology selection and feedstock flexibility determine project bankability across the partial oxidation blue hydrogen value chain. Deployment scale and end-use specifications shape equipment procurement patterns and offtake contract structures.
Production Technology:
Customization intensity spans from mature reactor designs with standardized catalyst supply chains to emerging plasma configurations requiring bespoke engineering.
- Catalytic Partial Oxidation:Established reactor designs operate at 1200°C to 1500°C with proven nickel-based catalyst systems. German refinery clusters in the Ruhr favor this technology for hydrocracking hydrogen supply due to predictable maintenance cycles and established spare parts logistics.
- Autothermal Reforming:Integrated oxygen-steam injection automates thermal management and reduces auxiliary fuel consumption below catalytic baselines. Coastal ammonia synthesis facilities in the Netherlands and Belgium are adopting these units to capture efficiency premiums in long-term offtake contracts.
- Steam Methane Reforming:Competing technology with higher carbon capture complexity and larger physical footprint. Operators with existing SMR infrastructure face retrofit decisions rather than greenfield partial oxidation investments.
- Dry Reforming:Experimental configurations utilizing CO2 as oxidant rather than oxygen. Pilot projects in Norway leverage offshore carbon dioxide streams for integrated carbon utilization pathways.
- Plasma Reforming:Electrified non-catalytic process enabling smaller reactor footprints. Technology remains pre-commercial with limited supplier base and extended commissioning timelines.
Most installed capacity flows through Catalytic Partial Oxidation. Expansion is steepest in Autothermal Reforming.
Feedstock Type:
Margin profiles diverge sharply between pipeline-connected natural gas and certificate-backed biomethane alternatives.
- Natural Gas:Pipeline infrastructure in the US Gulf Coast and North Sea corridors delivers lowest delivered cost for large-scale facilities. Henry Hub price volatility compresses project IRRs and complicates long-term offtake pricing.
- Biomethane:Renewable gas certificates in Germany and Denmark create premium product tiers for transport-sector hydrogen. KBA certification requirements filter back to production facility design specifications.
- Coal Bed Methane:Regional feedstock concentrated in Australia and parts of North America. Limited pipeline interconnectivity restricts deployment to captive industrial sites.
- LPG:Liquid feedstock enables modular production units without pipeline dependency. Higher per-unit energy costs constrain application to remote or stranded gas locations.
- Naphtha:Refinery-integrated configurations consume internal streams for hydrocracker hydrogen loops. Tight integration limits standalone market opportunity.
Natural Gas dominates current throughput. Biomethane is climbing the fastest on certificate value capture.
End User Industry:
Application requirements range from ultra-high purity ammonia synthesis to flexible refinery hydrocracking operations.
- Refining:Hydrocracking and hydrotreating units consume hydrogen at scale with variable daily demand profiles. German and Dutch refineries are rewriting feedstock contracts to include certified carbon intensity floors ahead of EU Green Deal border adjustments.
- Ammonia Production:Synthesis loops demand 99.9% purity with minimal CO slip to protect iron-based catalysts. Coastal production sites with direct pipeline access capture vertical margin through captive consumption.
- Methanol Synthesis:Syngas ratio requirements differ from pure hydrogen applications. Partial oxidation configurations can optimize CO/H2 output for methanol-specific offtake.
- Power Generation:Gas turbine blending specifications tolerate lower purity than chemical applications. Emerging demand concentrated in hydrogen-ready combined cycle projects.
- Synthetic Fuels:Fischer-Tropsch and e-fuel pathways require specific H2/CO ratios. Offtake agreements remain sparse as synthetic fuel production scales from demonstration to commercial.
Refining absorbs the largest volume share. Ammonia Production is gaining share fastest on coastal cluster development.
Deployment Scale:
Capital efficiency and offtake risk allocation vary across unit size categories from containerized systems to integrated mega-complexes.
- Large-Scale:Integrated facilities exceeding 100,000 Nm3/hr anchor industrial cluster hydrogen supply. North Sea port locations exploit pipeline networks and offshore carbon storage connectivity.
- Modular Units:Factory-fabricated skids reduce field construction timelines and enable phased capacity expansion. Project developers in distributed industrial zones favor this approach to match offtake ramp schedules.
- Mid-Scale:Intermediate configurations serving single large industrial sites without cluster integration. Financing structures blend project finance with corporate balance sheet support.
- Small-Scale:Containerized systems for remote fueling stations or pilot demonstrations. Limited carbon capture integration restricts blue hydrogen classification in most jurisdictions.
Large-Scale captures the majority of committed capital. Modular Units are expanding most quickly on risk-managed deployment models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized reactor engineering talent concentrates in German industrial corridors and US Gulf Coast petrochemical hubs, anchoring project execution capacity for high-temperature process vessels.
United States
Refinery hydrocracking demand along the Texas and Louisiana coastlines drives blue hydrogen offtake for low-carbon feedstock substitution. EPA greenhouse gas reporting protocols enforce emission verification standards for cross-border hydrogen trade. Houston-area industrial clusters leverage existing carbon capture infrastructure to compress delivered costs for coastal ammonia synthesis facilities.
Germany
KBA transport-sector mandates create certified-premium hydrogen tiers for fuel-cell vehicle applications, filtering back to production facility specifications. EU F-Gas Regulation tightens equipment standards for amine-based absorption systems, accelerating replacement cycles. Ruhr industrial clusters anchor long-term offtake agreements, while North Sea ports develop pipeline networks linking production to offshore carbon storage sites.
Netherlands
Coastal ammonia synthesis facilities seek direct pipeline access to capture vertical margin through captive hydrogen consumption. EU Green Deal carbon border adjustments tighten compliance costs for conventional gray hydrogen imports. Rotterdam port infrastructure enables integrated mega-complexes exceeding 100,000 Nm3/hr with offshore carbon sequestration connectivity.
Norway
Offshore carbon dioxide streams feed experimental dry reforming pilot projects utilizing CO2 as oxidant rather than oxygen. Equinor anchors North Sea storage site development, enabling producers to monetize carbon sequestration as separate revenue streams. Industrial corridors concentrate on integrated carbon utilization pathways linking production to subsea injection infrastructure.
United Kingdom
Refinery operators with existing syngas processing infrastructure pilot autothermal reforming units for thermal efficiency gains. Health Canada and PMRA emission frameworks shape equipment specifications for export-oriented production. Humber and Teesside industrial clusters develop hydrogen-ready combined cycle projects with lower purity tolerance than chemical applications.
Partial Oxidation Blue Hydrogen Market Competitive Landscape
The competitive structure tilts toward integrated industrial gas suppliers with established carbon capture infrastructure and project execution capabilities. Market concentration reflects high barriers to entry for high-temperature reactor engineering and amine absorption system manufacturing. Two strategic archetypes dominate: Gulf Coast-based operators leveraging pipeline networks and storage connectivity, and European industrial gas majors with large-scale ASU and gasification technology integration. Dominant competitive moves include capacity expansion at coastal production sites and strategic partnerships linking hydrogen supply to ammonia synthesis clusters.
Among integrated industrial gas suppliers, Air Products and Chemicals, Linde plc, and Shell exemplify the scale-driven archetype. Air Products and Chemicals occupies a position anchored by Gulf Coast carbon capture infrastructure. Linde plc sits within the technology-integrated tier through large-scale ASU and gasification capabilities. Shell represents the offshore network specialist, with pipeline connectivity to North Sea storage sites enabling separate carbon sequestration revenue streams.
| Leading Market Players |
|---|
| Air Products and Chemicals |
| Air Liquide |
| Linde plc |
| Shell |
| BP |
| ExxonMobil |
| Equinor |
| Eni |
| Technip Energies |
| Others |
Pricing and Supply Chain Analysis
Autothermal reforming adoption simultaneously compresses production cost curves and concentrates procurement leverage among operators with integrated oxygen-steam injection capabilities. German industrial clusters in the Ruhr and North Sea ports now negotiate from position, using long-term offtake scale to extract favorable terms from equipment suppliers and feedstock providers alike. This technology-driven cost restructuring feeds directly into contract structures that reward thermal efficiency with pricing premiums.
Pricing Analysis
Bundled carbon sequestration services separate from hydrogen molecule sales define the dominant contract architecture. Premium-mid-economy pricing differentiation rests on KBA certification tiers for transport-sector hydrogen and EU-verified carbon intensity thresholds. Cost compression in standard-grade supply intensifies as autothermal reforming operators capture efficiency gains. Refinery procurement teams show highest price sensitivity due to feedstock cost volatility exposure, while ammonia synthesis facilities with captive consumption tolerate premium tiers for purity guarantees.
Supply Chain Analysis
Regional distribution centers for nickel-based catalyst systems concentrate in Germany and the US Gulf Coast, creating hub-and-spoke patterns for spare parts logistics. Amine-based absorption equipment manufacturing draws from specialized fabricators in the Netherlands and Japan, with reactor vessel engineering anchored in Houston and Dusseldorf industrial corridors. Single-source vulnerability for high-temperature process vessels creates bottleneck risk for project timelines. Distribution runs through integrated industrial gas suppliers with captive ASU and carbon capture infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Transport-sector demand for KBA-certified hydrogen is filtering procurement specifications toward premium carbon intensity tiers that reward production discipline.
For Market Incumbents: Deploy backward integration into amine absorption system manufacturing to secure equipment availability and compress delivered cost. Anchor capacity additions at North Sea port locations with offshore carbon storage connectivity to monetize sequestration as separate revenue streams. Autothermal reforming substitution threatens catalytic partial oxidation market share; operators must invest in integrated steam injection capabilities to defend position. For New Entrants and Emerging Players: The gap between premium KBA-certified hydrogen and economy-grade refinery supply creates entry space for mid-tier producers with biomethane feedstock flexibility. Target German transport-sector mandates where certification premiums justify greenfield investment. Coastal ammonia synthesis facilities with pipeline access offer the most penetrable offtake anchor. Go-to-market positioning should emphasize renewable gas certificate value capture in jurisdictions with established biomethane supply chains. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale operators with stranded gas access but limited carbon capture integration. Long-term viability hinges on securing offshore storage site licensing timelines and preserving project bankability through offtake contract duration. Acquisition targets should show feedstock-flexible partial oxidation configurations with established catalyst supply relationships. The signal to watch is tightening carbon intensity thresholds in EU offtake contracts as border adjustments take effect.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Capture Equipment | Secures amine absorption system supply and compresses project timelines for German industrial clusters. |
| Long-term Offtake Agreement with Ammonia Synthesis Facilities | Locks in coastal demand basins with direct pipeline access and captive hydrogen consumption. |
| KBA Certification Investment for Transport-Sector Hydrogen | Captures premium pricing tiers as German fuel-cell vehicle mandates tighten carbon intensity floors. |
| North Sea Port Capacity Expansion | Exploits offshore carbon storage connectivity and Rotterdam infrastructure for integrated mega-complexes. |
| Biomethane Feedstock Flexibility Program | Opens renewable gas certificate margin pools in Denmark and Germany with transport-sector offtake. |
Research Methodology
Multiple input streams — executive interviews with industrial gas project developers, technical consultations with high-temperature reactor engineering specialists, and regulatory tracking across EPA and EU F-Gas frameworks — were reconciled against customs data for catalyst and absorption equipment trade flows. Primary discussions with refinery procurement directors, ammonia synthesis facility operators, and carbon capture system fabricators informed demand-side validation. Secondary sources included EIA hydrogen production databases, EU ETS carbon price series, and SEC filings from integrated industrial gas suppliers. Bottom-up capacity buildout schedules triangulated against top-down hydrogen demand projections across the analysis window.
Data-stream reconciliation employed a segmentation framework spanning production technology, feedstock type, end-use industry, and deployment scale. CAGRs were derived from installed capacity trajectories and offtake contract velocity across German, Dutch, and US Gulf Coast industrial corridors. Forecast inputs incorporated EU Green Deal carbon border adjustment implementation schedules, KBA certification pathway timelines, and autothermal reforming technology adoption curves. Volume and value outputs reflect reconciliation between supply-side engineering constraints and demand-side procurement patterns throughout the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for plasma reforming electrification would alter the outlook if pre-commercial units achieve scaled deployment. Forecasts reflect stated assumptions regarding carbon capture rate verification protocols and offshore storage site licensing timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Hydrogen Energy Storage Market
Hydrogen Energy
Merchant Hydrogen Market
Hydrogen Energy
Hydrogen Station Market
Hydrogen Energy
Liquid Organic Hydrogen Carrier (LOHC) Market
Hydrogen Energy
Hydrogen Storage Technology Market
Hydrogen Energy
Hydrogen Refueling Protocol and Dispenser Performance Test Systems Market
Hydrogen Energy
Hydrogen Generator Market
Hydrogen Energy
Hydrogen Purifiers Market
Hydrogen Energy
Hydrogen-Cooled Turbine Generator Market
Hydrogen Energy
On-Site Hydrogen Generator Market
Hydrogen Energy
Europe Hydrogen Generation Market
Hydrogen Energy
Hydrogen Composite Tanks Market
Hydrogen Energy
Europe Clean Hydrogen Market
Hydrogen Energy
Water Electrolysis Green Hydrogen Production Market
Hydrogen Energy
Hydrogen Liquefaction Unit Market
Hydrogen Energy
Hydrogen Powered Engine Market