
 Cryogenic Technology Market | 2026-2036
Cryogenic Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Cryogenic Technology Market Outlook
ISO 9001 and ASME Section VIII certification cycles is reorganizing vendor qualification for cryogenic pressure equipment, extending project timelines for new entrants. Chart Industries sustains manufacturing scale across North American and European fabrication facilities. Linde plc anchors industrial gas supply chains through captive production of cryogenic distillation systems. Air Liquide competes on geographic reach with dense service networks in Western Europe and East Asia.
Cryogenic technology encompasses systems operating below minus 150 degrees Celsius, utilizing liquefied gases such as nitrogen, oxygen, argon, and helium stored in vacuum-insulated vessels with multi-layer insulation achieving thermal conductivity below 0.0001 watts per meter-kelvin. These systems enable separation, storage, and transport of gases in industrial processes, medical preservation, and energy applications where ambient-temperature handling proves impossible. Cryogenic tanks command the largest product-type revenue pool due to capital intensity and replacement cycles in LNG infrastructure. Medical applications within the application dimension generate premium margins from regulatory compliance burdens and precision requirements. Pulse tube technology displaces Stirling variants in satellite cooling and quantum computing applications where vibration sensitivity dictates selection.
FDA 21 CFR Part 820 quality system regulation governs cryogenic medical devices in the United States, while the EU MDR imposes clinical evaluation and post-market surveillance obligations on European manufacturers. China's NMPA implements GB standards for cryogenic vessel safety, creating divergent testing protocols for multinational suppliers. Stakeholders must monitor evolving hydrogen economy infrastructure codes, as liquid hydrogen storage specifications will redefine certification requirements and equipment design parameters.
Market Dynamics
The EU F-Gas Regulation is forcing a wholesale equipment retrofit cycle across European industrial gas infrastructure, compressing replacement timelines and redrawing vendor qualification hierarchies for cryogenic systems manufacturers.
Growth Catalysts
- LNG Export Infrastructure:Qatar and Australia are expanding liquefaction terminal capacity, driving procurement of large-scale cryogenic storage spheres and transport trailers for marine bunkering operations.
- EU F-Gas Phase-Down:The regulation mandates refrigerant containment and recovery systems, accelerating demand for retrofitted cryogenic cooling equipment in pharmaceutical cold chains.
- Pulse Tube Cryocoolers:NASA and ESA satellite programs are standardizing on pulse tube variants over Stirling engines for vibration-sensitive infrared instrumentation.
Market Restraints
- Nickel Superalloy Supply Concentration:Inconel and Hastelloy feedstock for cryogenic pressure vessels concentrates among a handful of specialty steel mills in Germany and Japan, exposing fabricators to input cost volatility.
- ASME Section VIII Certification Friction:The qualification cycle for new pressure equipment vendors extends 18-24 months, creating structural barriers to capacity expansion.
- Helium Reserve Depletion:The US Bureau of Land Management's reserve auction system is winding down, forcing medical MRI operators toward closed-loop helium recovery or substitute cooling technologies.
Strategic Opportunities
- Liquid Hydrogen Storage:Germany's hydrogen backbone initiative and Japan's Kobe Hydrogen Port are creating first-mover openings for cryogenic tank fabricators meeting SAE J2601 fueling protocols.
- Quantum Computing Cryogenics:Dilution refrigeration systems for superconducting qubits represent an emerging application with premium pricing power and limited qualified suppliers.
- Remote Monitoring Integration:IoT-enabled vacuum integrity sensing is opening service contract revenue streams independent of equipment sales in biobank and fertility clinic networks.
Industry Challenges
- Welding Certification Scarcity:Qualified GTAW and orbital welders for vacuum-jacketed piping command wage premiums exceeding 40% above standard pressure vessel trades, constraining fabrication throughput.
- Multi-Jurisdictional Compliance:Vendors supplying both FDA-regulated medical devices and ASME-stamped industrial equipment must maintain parallel quality systems, duplicating audit overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryogenic Technology Market |
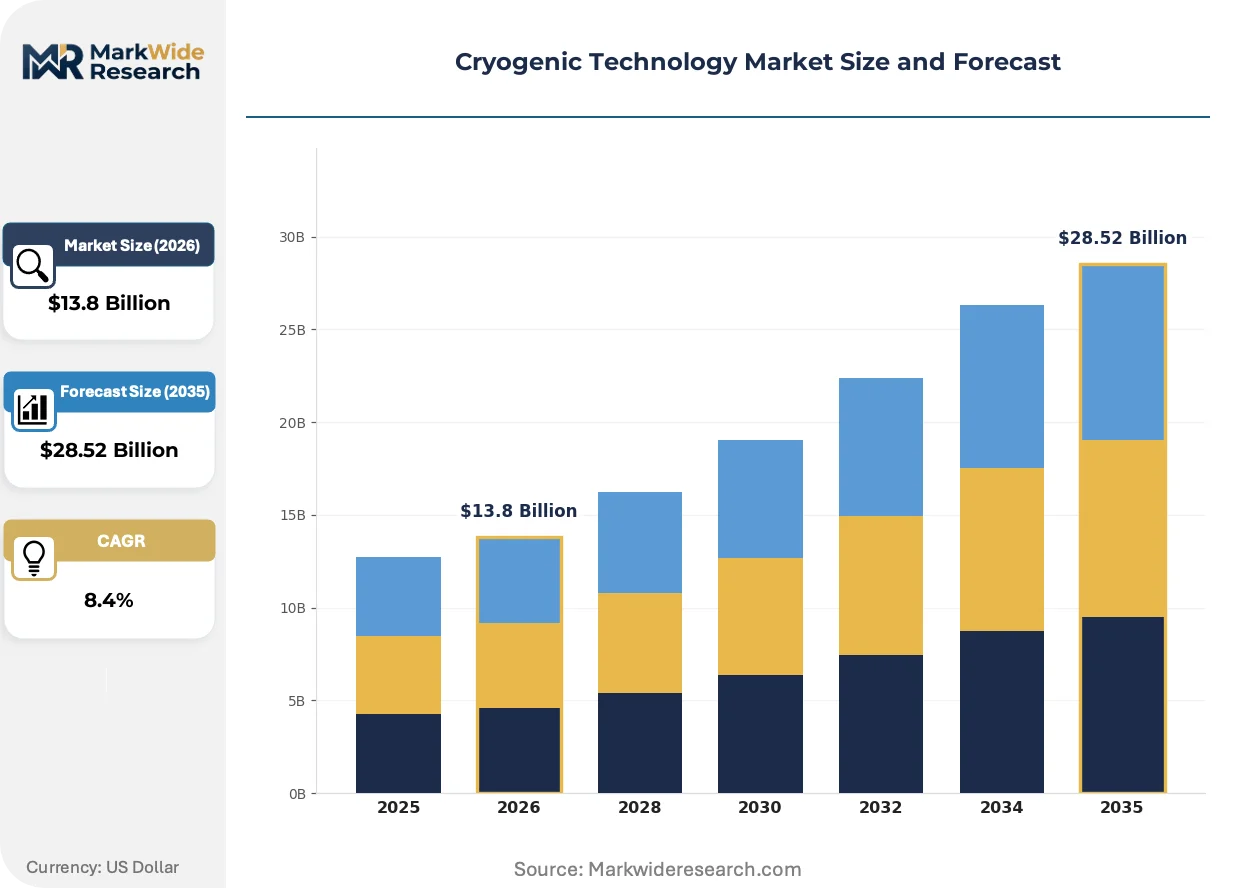
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cryogenic Freezers, Cryostats, Insulation Materials, Cryogenic Tanks Application: Medical Applications, Industrial Gas, LNG Production, Aerospace End User: Healthcare Institutions, Research Laboratories, Energy Sector, Manufacturing Technology: Closed Cycle, Pulse Tube, Joule-Thomson, Hybrid |
| Companies Covered | Nikkiso Co. Ltd, SHI Cryogenics Group, Chart Industries, Inc., Air Products and Chemicals, Air Liquide, Cryofab, Inc., Nikkisso Cryoquip, Emerson Electric Co., Linde plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryogenic Technology Market Strategic Shifts
Active magnetic bearing technology and additive-manufactured heat exchangers are compressing equipment footprints while expanding operational envelopes for cryogenic systems in space-constrained urban installations.
Additive manufacturing of aluminum heat exchanger cores is fragmenting procurement patterns for plate-fin and coil-wound heat exchangers. Aerospace prime contractors and satellite integrators are qualifying laser-powder-bed-fusion components for thermal management subsystems. This technology is fragmenting the traditional supplier base by enabling in-house production of complex geometries previously sourced from specialized fabricators.
REACH authorization requirements for nickel compounds are tightening material traceability obligations across European cryogenic equipment supply chains. Manufacturers must now document full substance histories for alloys used in medical and food-grade applications. German and French pressure vessel fabricators are responding by consolidating supplier panels and investing in in-house metallurgical testing capabilities.
Biobank operators are unbundling equipment procurement from long-term service contracts, compressing vendor switching cycles from decade-long lock-ins to 3-5 year renewable agreements. This pattern is most visible in US academic medical centers and UK National Health Service tissue storage networks. Equipment vendors are responding with modular upgrade paths and subscription-based predictive maintenance offerings to retain account control.
Cryogenic Technology Market Segmentation
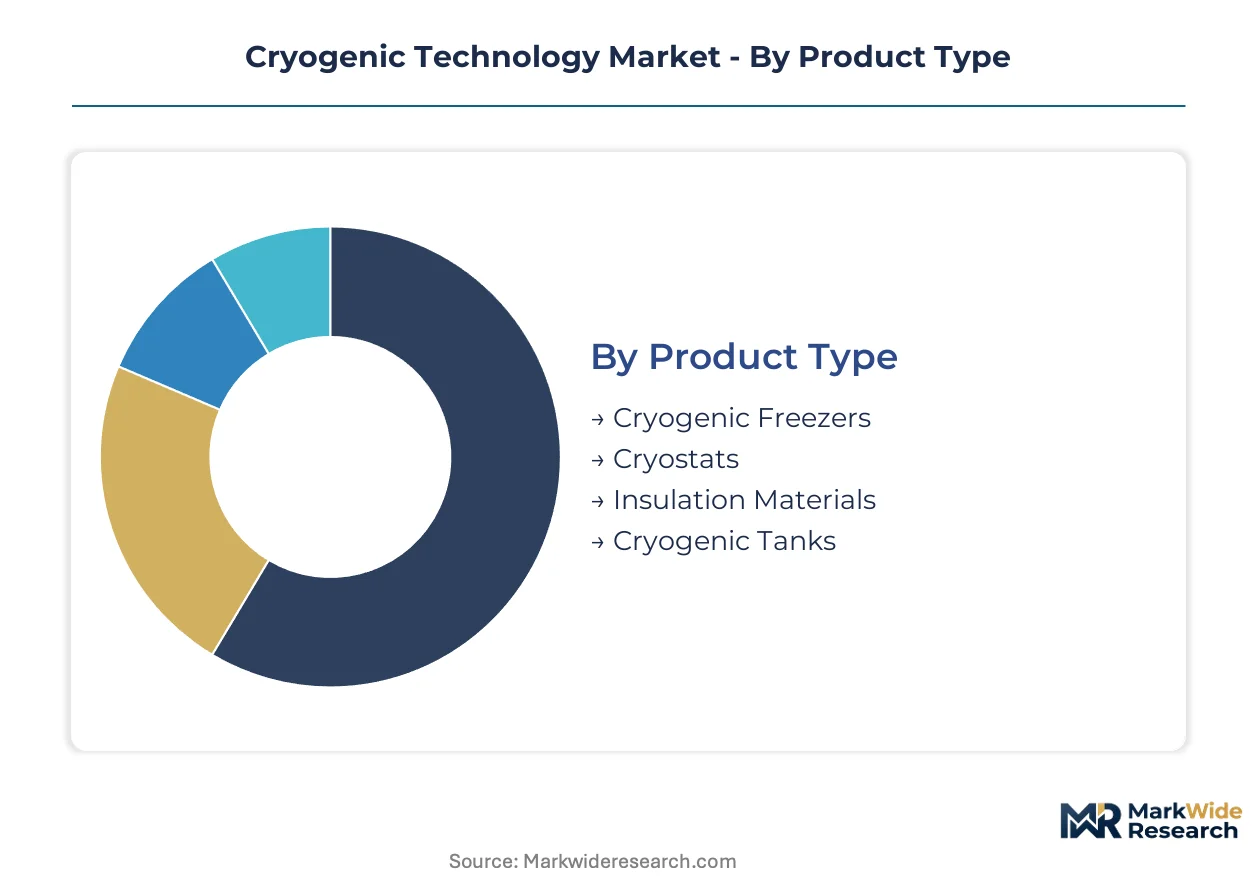
Cryogenic technology spans equipment categories with vastly different certification burdens and margin profiles. Segmentation reveals where regulatory complexity concentrates value and which technology pathways are displacing legacy approaches.
Product Type:
ASME Section VIII and FDA 21 CFR Part 820 create divergent compliance pathways across equipment categories, with pressure-rated vessels facing 18-24 month qualification cycles while non-pressurized systems move faster to market.
- Cryogenic Tanks:Vacuum-insulated pressure vessels with multi-layer insulation achieving thermal conductivity below 0.0001 W/m-K dominate capital expenditure in LNG export terminals across Qatar and Australia. Replacement cycles in marine bunkering infrastructure sustain aftermarket demand.
- Cryogenic Freezers:Ultra-low temperature storage systems operating below minus 150 degrees Celsius serve biobank networks and fertility clinics under FDA and EU MDR quality system mandates. Procurement is unbundling from decade-long service contracts toward 3-5 year renewable agreements.
- Cryostats:Temperature-controlled chambers for scientific instrumentation require precision thermal stability for superconducting applications.
- Insulation Materials:Multi-layer vacuum superinsulation and aerogel composites reduce boil-off losses in transport applications.
Cryogenic tanks handle the majority of throughput; cryogenic freezers are expanding most quickly on share as biobank infrastructure proliferates.
Application:
End-use concentration varies sharply by margin structure, with medical and aerospace applications commanding premium pricing against commoditized industrial gas handling.
- Medical Applications:Tissue preservation, biobanking, and MRI cooling operate under FDA 21 CFR Part 820 and EU MDR clinical evaluation obligations. Regulatory compliance burdens and precision requirements generate the highest margins across the application spectrum.
- LNG Production:Liquefaction terminals and marine bunkering systems in Qatar and Australia drive procurement of large-scale storage spheres and transport trailers. QatarEnergy and Australia Pacific LNG anchor demand concentration.
- Industrial Gas:Cryogenic distillation for nitrogen, oxygen, and argon separation serves petrochemical corridors along the US Gulf Coast.
- Aerospace:Satellite infrared instrumentation and propellant storage impose vibration sensitivity requirements favoring pulse tube over Stirling cryocoolers.
LNG production commands the largest revenue pool; medical applications deliver the steepest expansion trajectory as precision cold chain requirements intensify.
End User:
Customer sophistication and procurement authority reshape vendor engagement models, with centralized healthcare purchasing diverging from fragmented research laboratory decision-making.
- Healthcare Institutions:Academic medical centers and NHS tissue storage networks in the US and UK are consolidating biobank procurement under shared service organizations. Modular upgrade paths and subscription-based predictive maintenance are displacing traditional equipment lock-ins.
- Energy Sector:LNG terminal operators and hydrogen backbone developers in Germany and Japan specify SAE J2601 fueling protocols for liquid hydrogen storage systems.
- Research Laboratories:Quantum computing facilities require dilution refrigeration for superconducting qubits with limited qualified supplier bases.
- Manufacturing:Petrochemical and semiconductor fabrication plants consume industrial gases in continuous-process environments.
Healthcare institutions concentrate procurement volume; the energy sector is climbing the fastest as hydrogen economy infrastructure codes mature.
Technology:
Cooling cycle selection hinges on vibration sensitivity, efficiency trade-offs, and maintenance access constraints across deployment environments.
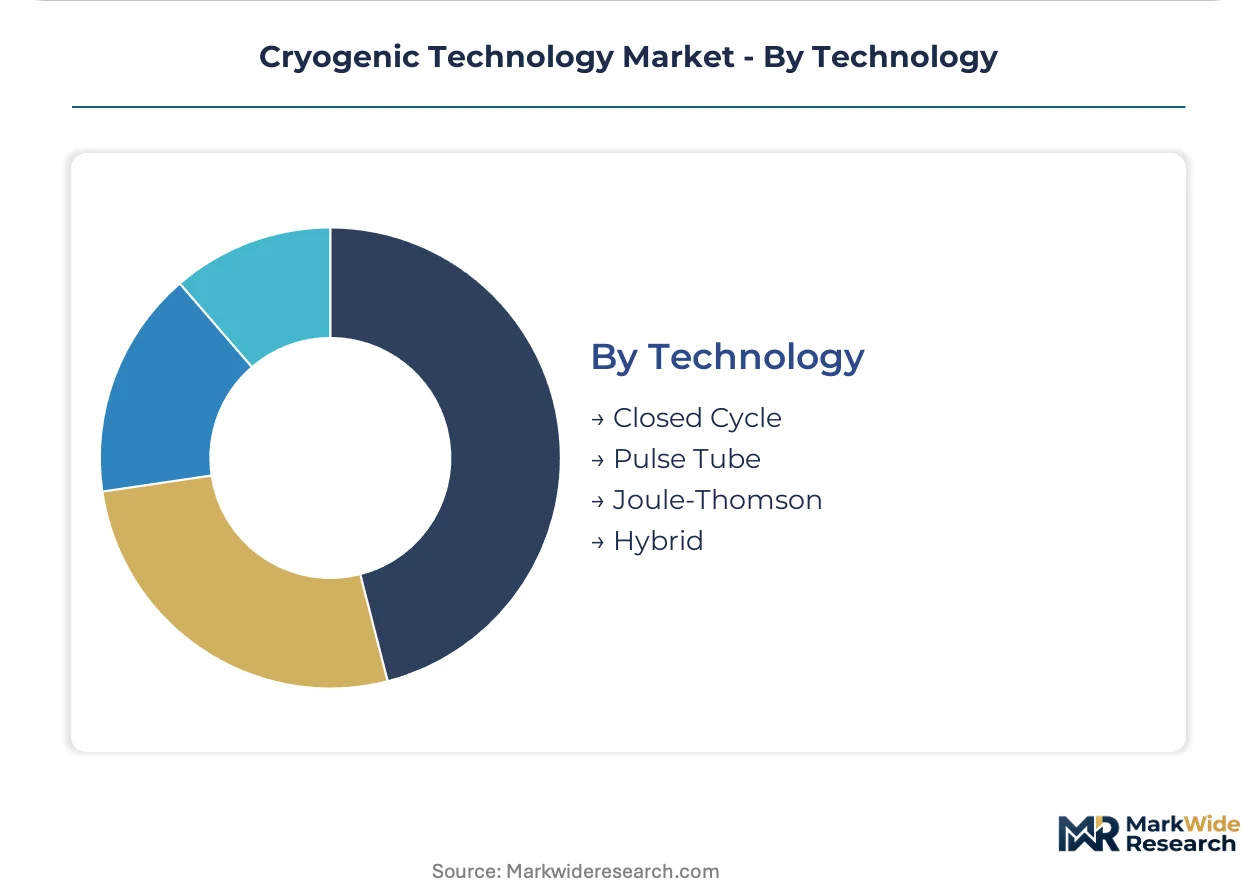
- Pulse Tube:NASA and ESA satellite programs have standardized on pulse tube cryocoolers for vibration-sensitive infrared instrumentation. The absence of moving parts at the cold end extends operational life in space-constrained installations.
- Closed Cycle:Gifford-McMahon and Stirling variants dominate ground-based applications where vibration tolerance permits higher cooling capacity per unit mass.
- Joule-Thomson:Expansion cooling through throttling valves serves rapid cooldown requirements in missile seeker and tactical cryocooler applications.
- Hybrid:Combined cycle architectures optimize efficiency across broad temperature ranges in scientific instrumentation.
Closed cycle systems retain the installed base; pulse tube technology is gaining share fastest as aerospace and quantum computing specifications harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation phase-down timelines and hydrogen economy infrastructure codes are redrawing procurement patterns across major industrial economies. Each geography concentrates demand in distinct end-use clusters while imposing divergent certification burdens on equipment suppliers.
United States
LNG export terminals along the Gulf Coast anchor demand for large-scale cryogenic storage spheres and marine bunkering trailers. FDA 21 CFR Part 820 governs medical device quality systems for biobank and MRI cooling applications. Houston and Corpus Christi petrochemical corridors sustain concentrated procurement from industrial gas operators.
Germany
The hydrogen backbone initiative creates first-mover openings for liquid hydrogen storage fabricators meeting SAE J2601 fueling protocols. REACH authorization requirements for nickel compounds tighten material traceability obligations across pressure vessel supply chains. Bavarian and North Rhine-Westphalian industrial clusters host dense networks of specialty steel mills supplying Inconel feedstock.
China
NMPA implements GB standards for cryogenic vessel safety, creating divergent testing protocols for multinational suppliers. State-backed LNG import terminal expansions drive procurement of transport trailers and vacuum-insulated storage systems. Yangtze River Delta manufacturing bases concentrate domestic fabrication capacity for industrial gas separation equipment.
Japan
METI coordinates hydrogen port infrastructure development at Kobe and Yokohama, specifying cryogenic storage protocols for liquid hydrogen fueling. JIS standards govern pressure equipment certification alongside ASME Section VIII for export-oriented fabricators. Satellite programs under JAXA standardize pulse tube cryocoolers for vibration-sensitive infrared instrumentation.
Australia
QatarEnergy and Australia Pacific LNG anchor liquefaction terminal capacity expansions driving cryogenic procurement. TGA medical device regulations impose parallel quality system requirements for biobank equipment imports. Perth and Queensland energy corridors concentrate LNG infrastructure investment with linked demand for boil-off gas recovery systems.
Cryogenic Technology Market Competitive Environment
Listed leaders compete with private specialists across certification-intensive segments, creating tiered competitive dynamics where ASME and FDA qualification cycles erect structural barriers. The vendor landscape concentrates around industrial gas majors with captive equipment production, diversified fabricators spanning multiple end-use verticals, and regional specialists serving geographic niches. Three archetypes dominate: integrated gas suppliers with in-house cryogenic system production, diversified pressure equipment fabricators with multi-jurisdictional certification portfolios, and technology-focused specialists in satellite cooling or medical preservation. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with hydrogen economy infrastructure codes accelerating alliance formation between storage fabricators and energy developers.
Within the integrated gas supplier tier, Linde plc and Air Liquide exemplify archetypes combining captive cryogenic distillation production with dense service networks. Chart Industries, Inc. occupies a position among diversified fabricators sustaining manufacturing scale across North American and European facilities. Nikkiso Co. Ltd represents the specialist vector with concentrated expertise in cryogenic pump and heat exchanger systems. These anchors illustrate how competitive positioning depends on certification breadth, geographic service density, and end-use diversification rather than scale alone.
| Leading Market Players |
|---|
| Nikkiso Co. Ltd |
| SHI Cryogenics Group |
| Chart Industries, Inc. |
| Air Products and Chemicals |
| Air Liquide |
| Cryofab, Inc. |
| Nikkisso Cryoquip |
| Emerson Electric Co. |
| Linde plc |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at German and Japanese specialty steel mills directly determines price floors for Inconel and Hastelloy feedstock, compressing margins for cryogenic pressure vessel fabricators while amplifying procurement power for industrial gas majors with captive metallurgical testing capabilities.
Pricing Analysis
Certification level (ASME Section VIII/FDA 21 CFR Part 820/CE marking) creates the primary spread between equipment tiers, with medical-grade cryogenic freezers commanding substantial premiums over industrial gas handling systems. Project-based pricing dominates large-scale LNG storage spheres, while subscription models penetrate biobank service contracts. Cost compression in standard industrial tanks is intensifying due to welding certification scarcity. Academic medical centers exhibit highest price sensitivity; quantum computing facilities show lowest.
Supply Chain Analysis
Strait of Hormuz transit underwrites nickel alloy feedstock flows from European mills to Asian fabrication hubs, exposing cryogenic equipment supply chains to geopolitical friction. Germany, Japan, and China concentrate vacuum-insulated vessel production. Inconel, multi-layer insulation, and helium reserves constitute critical input dependencies. Single-source vulnerability concentrates in specialty steel mills. Distribution runs through industrial gas majors with dense service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability between liquid hydrogen storage protocols and existing LNG infrastructure is redefining competitive boundaries, positioning early SAE J2601 adopters as platform orchestrators for hydrogen economy buildouts.
For Market Incumbents: Secure ASME Section VIII certification breadth across multiple jurisdictions to defend against emerging fabricators from China's Yangtze River Delta. Deepen captive production of cryogenic distillation systems to offset margin pressure from nickel superalloy cost volatility. Prioritize modular upgrade paths for biobank equipment to retain account control against subscription-based challengers. For New Entrants and Emerging Players: Anchor in dilution refrigeration for quantum computing applications, where limited qualified suppliers create white-space opportunity. Target remote monitoring integration for fertility clinic networks as the most penetrable service contract segment. Lead with IoT-enabled vacuum integrity sensing to bypass capital-intensive equipment fabrication barriers. For Investors and Strategic Acquirers: Pulse tube cryocooler specialists with NASA and ESA program heritage represent the most defensible acquisition archetype, given aerospace standardization trends and limited vendor pools. Long-term viability hinges on hydrogen backbone infrastructure maturation. Watch Germany's hydrogen port commissioning timelines as the critical demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| SAE J2601 Protocol Certification | Unlocks liquid hydrogen storage contracts with Germany's hydrogen backbone developers. |
| Pulse Tube Cryocooler Qualification | Secures aerospace positioning as NASA and ESA displace Stirling variants. |
| Remote Monitoring Platform Launch | Captures recurring revenue from biobank operators unbundling equipment procurement. |
| Nickel Alloy Backward Integration | Insulates margins from German and Japanese specialty steel mill concentration. |
| EU MDR Quality System Investment | Preserves medical device access as post-market surveillance obligations intensify. |
Study Parameters
The analysis maps cryogenic tanks, freezers, cryostats, and insulation materials, each validated through equipment procurement managers at LNG terminal operators, biomedical engineers at academic medical centers, and aftermarket service heads at industrial gas distributors. Primary interviews combined with secondary validation from ASME certification databases, FDA 510(k) filings, EU MDR technical documentation, and customs trade records. Bottom-up and top-down triangulation cross-checked vendor capacity announcements against end-user procurement timelines.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and cooling cycle technology. CAGRs derived from equipment replacement cycle analysis and infrastructure investment pipelines. Hydrogen economy infrastructure codes and F-Gas Regulation phase-down timelines served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under sustained LNG export terminal investment and helium reserve depletion assumptions; material deviation in nickel alloy pricing or hydrogen protocol standardization would warrant model refresh. Practitioners should keep alternative scenarios live as EU F-Gas Regulation enforcement intensity and quantum computing commercialization timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging Energy Technologies
Multi Energy Systems Market
Emerging Energy Technologies
Nanotechnology in Energy Market
Emerging Energy Technologies
Advanced Energy Market
Emerging Energy Technologies
Global Power-To-X Market
Emerging Energy Technologies
Clean Technology Market
Emerging Energy Technologies
Global Microreactor Technology Market
Emerging Energy Technologies
Energy Transition Market
Emerging Energy Technologies
Europe Clean Coal Technologies Market
Emerging Energy Technologies
Clean Coal Technologies Sales Market
Emerging Energy Technologies
United States Clean Coal Technologies Market
Emerging Energy Technologies
Methanation Technology Market
Emerging Energy Technologies
Decarbonization Market