
 Multi Energy Systems Market | 2026-2036
Multi Energy Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Multi Energy Systems Market Foresight
Industrial buyers are gaining share as residential adoption plateaus, and demand is bifurcating between large-scale utility procurement and behind-the-meter commercial installations. Siemens Energy AG leverages its turbine-to-grid integration capabilities to anchor European offshore wind-hydrogen projects. General Electric Company competes in North American hybrid power plant configurations, while ABB Ltd. controls automation and power electronics layers that knit disparate generation assets into dispatchable blocks.
Multi energy systems integrate two or more generation, storage, or grid management technologies into a single optimized asset capable of dispatching firm power against variable renewable output. These configurations typically couple photovoltaic arrays with lithium-ion battery storage and synchronous condensers to maintain frequency stability within 0.5 Hz deviation limits. Solar-biomass hybrid segments carry the deepest margin pools where baseload reliability commands capacity payments, while smart grid technology layers are expanding fastest as distribution operators retrofit legacy infrastructure with bidirectional communication and automated switching protocols.
The EU Green Deal and F-Gas Regulation constrain fluorinated insulating gases in switchgear, forcing suppliers toward vacuum interrupter and clean air alternatives that reshape equipment procurement specifications. China's MIIT issues GB standards for grid-forming inverters that dictate harmonic distortion thresholds and ride-through requirements for hybrid plants connecting at 35 kV and above. Stakeholders must monitor how divergent certification regimes across Brussels, Beijing, and Washington fragment component interoperability and determine where to localize supply chain qualification investments.
Market Dynamics
Dispatch requirements under Germany's net-zero mandates are compressing project timelines for hybrid renewable assets, forcing developers to front-load grid-forming inverter certification and synchronous condenser integration before financial close.
Growth Catalysts
- EU Green Deal dispatch mandates:Germany's tightening frequency stability requirements for hybrid plants are accelerating procurement of lithium-ion battery storage co-located with offshore wind arrays.
- Data center load growth:Hyperscale operators in Northern Virginia and Frankfurt are contracting behind-the-meter microgrids to isolate mission-critical compute from grid volatility.
- Grid-forming inverter standards:China's MIIT GB certification for harmonic distortion thresholds above 35 kV is creating qualified supplier lists that favor integrated technology providers.
Market Restraints
- Fluorinated gas supply constraints:The EU F-Gas Regulation is restricting availability of SF6 insulating medium for high-voltage switchgear, forcing retrofits toward vacuum interrupter designs with longer lead times.
- Lithium supply concentration:Cathode precursor processing clusters in Jiangsu and Hunan provinces create single-point vulnerability for battery storage cost structures.
- Synchronous condenser technical limits:Rotating mass inertia provision struggles to match response times of grid-forming inverters during sub-cycle frequency events.
Strategic Opportunities
- India CEA grid codes:Central Electricity Authority mandates for renewable hybrid projects are opening procurement windows for wind-solar-storage complexes in Gujarat and Rajasthan.
- Green hydrogen offtake:Electrolyzer integration with offshore wind in the North Sea creates new revenue stacking for capacity payments and hydrogen offtake contracts.
- Biomass-solar hybrid baseload:Agricultural waste-to-energy coupling with photovoltaic arrays commands premium capacity payments where grid operators value dispatchable renewable output.
Industry Challenges
- Power electronics talent scarcity:Grid-forming inverter firmware engineering and harmonic filter design capabilities concentrate among a narrow pool of specialists in Munich and Shenzhen.
- Multi-technology integration timelines:Coordinating turbine, battery, and hydrogen electrolyzer commissioning schedules extends project construction windows and complicates revenue recognition.
- Legacy SCADA interoperability:Distribution operators in older European markets face protocol translation costs when retrofitting bidirectional communication layers onto electromechanical switching infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi Energy Systems Market |
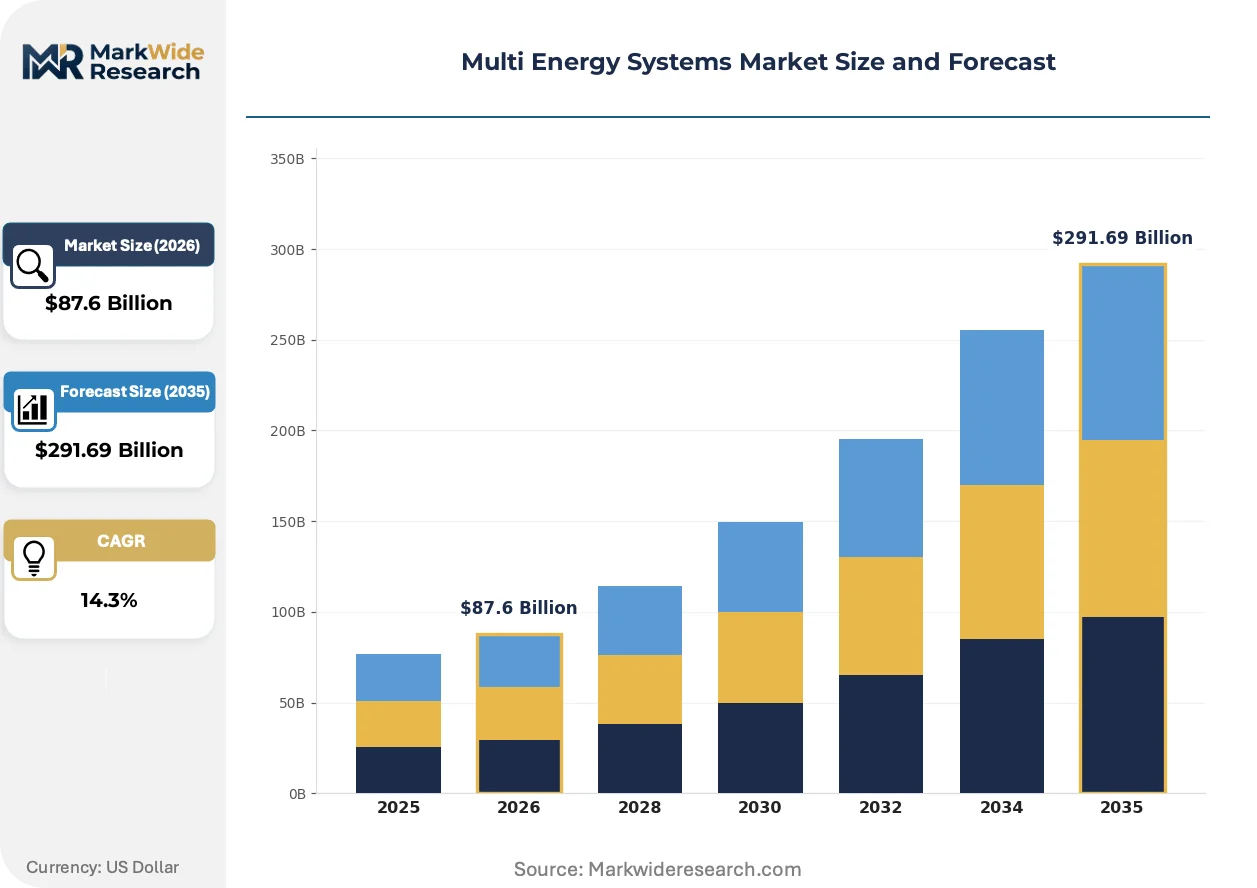
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $291.69 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Type: Solar, Wind, Biomass, Hydropower Technology: Energy Storage, Smart Grids, Microgrids, Demand Response End User: Residential, Commercial, Industrial, Utilities Application: Power Generation, Heating, Transportation, Backup Power |
| Companies Covered | Vestas Wind Systems A/S, First Solar, Inc., General Electric Company, TotalEnergies SE, Hitachi Ltd., Siemens Energy AG, Enel Green Power S.p.A., Schneider Electric SE, ABB Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi Energy Systems Market Shifts & Advancements
Technology convergence between power electronics and electrochemical storage is compressing the functional boundary between generation assets and grid stabilization equipment. This reconfiguration is redrawing supplier hierarchies and procurement specifications across utility-scale and behind-the-meter segments.
Solid-state transformer architectures are supplanting conventional magnetic core designs in medium-voltage hybrid substations. Offshore wind developers in the North Sea are specifying silicon carbide-based power conversion for 66 kV collector platforms. This semiconductor transition is enabling direct current interconnection between turbine strings and battery racks without intermediate alternating current conversion stages.
The EU F-Gas Regulation is accelerating vacuum interrupter adoption in high-voltage switchgear procurement specifications. Siemens Energy and ABB are requalifying product lines for clean air insulation mediums ahead of 2030 phase-down deadlines. German transmission system operators are rewriting technical connection rules to exclude fluorinated gases from new substation projects above 110 kV.
Industrial offtakers are unbundling engineering-procurement-construction contracts into separate technology supply and integration service agreements. Chemical operators in the Rhine-Ruhr corridor are direct-procuring battery racks and inverters while contracting system integrators for balance-of-plant optimization. This disintermediation is compressing margins for turnkey providers while expanding addressable market for specialized power electronics vendors.
Multi Energy Systems Market Segmentation
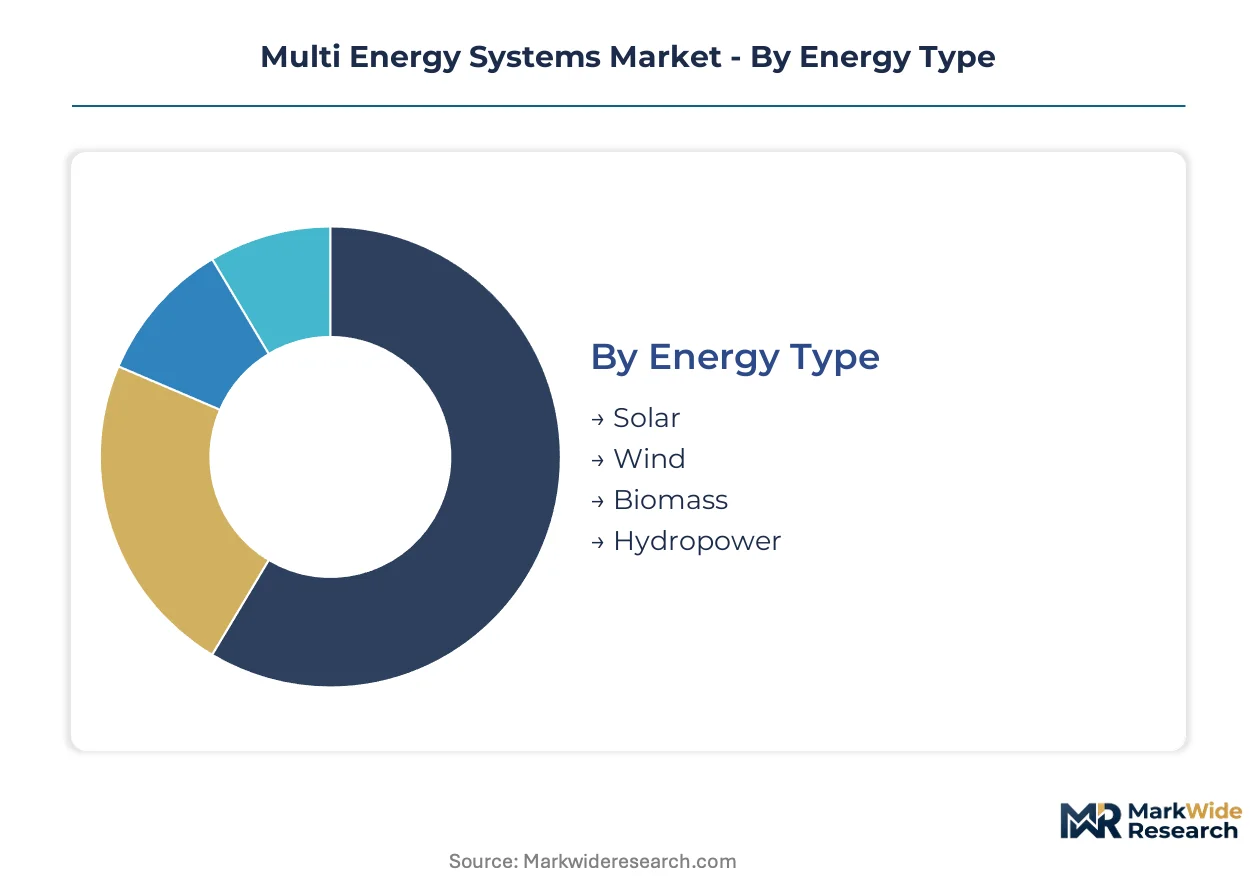
Segmentation in multi energy systems reveals how technology combinations map to distinct procurement channels and revenue models. Channel strategy diverges sharply between utility-scale hybrid plants and behind-the-meter commercial installations.
Energy Type:
Solar and wind assets flow through utility procurement channels governed by grid-forming inverter standards, while biomass and hydropower concentrate in baseload contracting with capacity payment structures.
- Solar:Photovoltaic arrays paired with lithium-ion battery storage dominate utility-scale procurement in China and Germany. Provincial grid operators in Jiangsu and Shandong are tendering integrated solar-storage complexes above 100 MW capacity.
- Wind:Offshore wind in the North Sea couples with electrolyzer integration for hydrogen offtake contracts. Siemens Energy anchors turbine-to-grid projects where frequency stability requirements exceed 0.5 Hz deviation limits.
- Biomass:Agricultural waste-to-energy systems command premium capacity payments where dispatchable renewable output is valued.
- Hydropower:Existing reservoir infrastructure provides synchronous condenser inertia for hybrid plant frequency response.
By volume, solar leads. By growth pace, wind is expanding most quickly through offshore-electrolyzer configurations.
Technology:
Cost tier separation distinguishes premium grid-forming inverter stacks from standard-compliant storage racks, with microgrids occupying a mid-tier position behind utility-scale deployments.
- Energy Storage:Lithium-ion battery racks with silicon carbide power conversion enable direct current interconnection without intermediate AC stages. Cathode precursor processing in Jiangsu and Hunan creates supply vulnerability for cost structures.
- Smart Grids:Bidirectional communication and automated switching protocols retrofit legacy distribution infrastructure. Distribution operators in older European markets face protocol translation costs when layering digital controls onto electromechanical switching systems.
- Microgrids:Behind-the-meter configurations isolate mission-critical loads from grid volatility. Hyperscale data center operators in Northern Virginia and Frankfurt are contracting these systems directly.
- Demand Response:Load curtailment aggregation provides ancillary services revenue stacking for commercial and industrial offtakers.
By installed base, energy storage dominates. By margin expansion, smart grids are gaining share fastest through retrofit cycles.
End User:
Application maturity separates established utility procurement from emerging industrial direct contracting, with residential adoption plateauing relative to commercial growth.
- Industrial:Chemical operators in Germany's Rhine-Ruhr corridor are unbundling EPC contracts to direct-procure battery racks and inverters. This disintermediation compresses turnkey provider margins while expanding addressable market for specialized power electronics vendors.
- Utilities:Transmission system operators in Germany are rewriting technical connection rules to exclude fluorinated gases from new substation projects above 110 kV.
- Commercial:Behind-the-meter installations concentrate in data center load clusters where uptime requirements exceed 99.99%.
- Residential:Distributed solar-battery systems face interconnection queue delays in markets with legacy net metering frameworks.
By revenue concentration, utilities lead. By contract velocity, industrial is climbing the fastest through direct procurement restructuring.
Application:
Customer type alignment maps power generation to utility buyers, heating to district energy operators, and backup power to mission-critical commercial facilities.
- Power Generation:Hybrid renewable plants dispatch firm output against variable solar and wind profiles. Grid-forming inverter certification under China's MIIT GB standards creates qualified supplier lists favoring integrated technology providers.
- Backup Power:Microgrid configurations isolate critical loads from grid volatility. Data center operators contract these systems to maintain compute availability during transmission disturbances.
- Heating:Biomass-solar hybrid systems provide dispatchable thermal output for district energy networks.
- Transportation:Electrolyzer integration with offshore wind creates hydrogen offtake contracts for maritime and heavy-duty mobility applications.
By deployment scale, power generation leads. By revenue stacking potential, backup power shows the steepest expansion trajectory through critical infrastructure contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea offshore grid interconnect underwrites Europe's role in multi energy systems deployment, while China's ultra-high voltage transmission corridors enable provincial-scale wind-solar-storage procurement.
China
Jiangsu and Shandong provincial grid operators tender integrated solar-storage complexes above 100 MW capacity. MIIT GB standards for grid-forming inverters dictate harmonic distortion thresholds and ride-through requirements for hybrid plants connecting at 35 kV and above. Yangtze River Delta manufacturing clusters supply silicon carbide power conversion modules for direct current interconnection architectures.
Germany
Rhine-Ruhr chemical operators unbundle EPC contracts to direct-procure battery racks and inverters. The EU F-Gas Regulation and national net-zero mandates tighten dispatch requirements for hybrid renewable assets, forcing front-loaded grid-forming inverter certification. Transmission system operators rewrite technical connection rules to exclude fluorinated gases from new substation projects above 110 kV.
United States
Hyperscale data center operators in Northern Virginia contract behind-the-meter microgrids to isolate mission-critical compute from grid volatility. FERC Order 2222 enables distributed energy resource aggregation for wholesale market participation. ERCOT's Texas grid faces interconnection queue pressures as solar-wind-storage hybrid developers compete for transmission access.
India
Central Electricity Authority mandates for renewable hybrid projects open procurement windows for wind-solar-storage complexes in Gujarat and Rajasthan. State distribution companies in Maharashtra and Karnataka issue tenders for integrated renewable assets with guaranteed dispatch capability. National grid code harmonization efforts accelerate under Ministry of Power directives.
United Kingdom
North Sea offshore wind developers specify electrolyzer integration for hydrogen offtake contracts serving maritime mobility applications. Ofgem's RIIO-ED2 price control framework incentivizes distribution network operators to deploy bidirectional communication and automated switching protocols. Scottish Power and SSE anchor turbine-to-grid integration projects where frequency stability requirements exceed 0.5 Hz deviation limits.
Multi Energy Systems Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and technology integration depth. The vendor base clusters around three strategic archetypes: turbine-to-grid integrators anchoring offshore wind-hydrogen projects, power electronics specialists controlling automation layers, and hybrid power plant configurators serving North American utility procurement. Dominant competitive moves include vertical integration into battery rack manufacturing and geographic expansion through qualified supplier list certification under divergent national standards regimes.
Among European-listed energy technology groups, Siemens Energy AG, ABB Ltd., and Vestas Wind Systems A/S occupy positions across the integration spectrum. Siemens Energy exemplifies the turbine-to-grid archetype through its offshore wind-electrolyzer project anchoring. ABB represents the power electronics and automation layer specialization that knits disparate generation assets into dispatchable blocks. Vestas occupies a position within wind turbine supply that increasingly couples with storage and grid-forming inverter integration requirements.
| Leading Market Players |
|---|
| Vestas Wind Systems A/S |
| First Solar, Inc. |
| General Electric Company |
| TotalEnergies SE |
| Hitachi Ltd. |
| Siemens Energy AG |
| Enel Green Power S.p.A. |
| Schneider Electric SE |
| ABB Ltd. |
| Others |
Supply & Pricing Matrix
Gigawatt-scale procurement volumes in Jiangsu and Shandong provinces compress unit economics for grid-forming inverter stacks while simultaneously concentrating supplier qualification power among integrated technology providers. This scale dynamic establishes price floors for certified equipment tiers and rewards backward integration into silicon carbide power conversion modules.
Pricing Analysis
Volume-discount tiering structures separate utility-scale hybrid plant procurement above 100 MW from behind-the-meter commercial installations and residential distributed systems. Certification under China's MIIT GB standards and Germany's F-Gas Regulation compliance tiers create price differentiation across grid-forming inverter and switchgear categories. Pricing pressure stems from cathode precursor processing concentration in Jiangsu and Hunan provinces, which tightens lithium-ion battery rack margins. Industrial offtakers in Germany's Rhine-Ruhr corridor exhibit lowest price sensitivity due to uptime requirements exceeding 99.99%, while residential segments face interconnection queue delays that amplify cost consciousness.
Supply Chain Analysis
China anchors cathode precursor processing and silicon carbide power conversion module fabrication, while South Korea and Japan control premium electrolyte and separator membrane supply. Raw material dependencies center on lithium carbonate, cobalt sulfate, and high-purity silicon metal feedstocks. Single-source vulnerability concentrates in Jiangsu province battery component clusters, exposing cost structures to regional logistics disruption. Distribution runs through qualified supplier lists maintained by provincial grid operators and transmission system operators, with direct procurement restructuring bypassing traditional EPC intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grid-forming inverter substitution by solid-state transformer architectures threatens incumbent power electronics specialists who fail to anchor turbine-to-grid integration projects. Incumbents must defend against this technology displacement through defensive capability building.
For Market Incumbents: Shield market position by securing backward integration into silicon carbide wafer supply and accelerating clean air insulation qualification ahead of EU F-Gas Regulation phase-down deadlines. Grid-forming inverter firmware engineering scarcity in Munich and Shenzhen threatens margin capture for firms without captive talent pipelines. For New Entrants and Emerging Players: Lead with specialized harmonic filter design services targeting India's CEA-mandated renewable hybrid projects in Gujarat and Rajasthan, where qualified supplier list gaps create procurement windows. Agricultural waste-to-energy coupling with photovoltaic arrays in biomass-solar hybrid configurations offers the most penetrable white-space for premium capacity payment capture. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among power electronics specialists with grid-forming inverter certification under multiple national standards regimes. Long-term viability favors acquisition targets controlling automation layers that knit disparate generation assets into dispatchable blocks. Watch for divergence between GB standard harmonization in China and F-Gas Regulation enforcement in Germany as inflection indicator for supply chain localization requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Grid-Forming Inverter Certification | MIIT GB standard compliance creates qualified supplier lists favoring integrated technology providers in China. |
| Clean Air Insulation Transition | EU F-Gas Regulation phase-down forces vacuum interrupter requalification for substation projects above 110 kV. |
| Silicon Carbide Integration | Direct current interconnection architectures eliminate AC conversion stages in North Sea offshore wind platforms. |
| Biomass-Solar Hybrid Development | Agricultural waste-to-energy coupling commands premium capacity payments where dispatchable renewable output is valued. |
| Behind-the-Meter Microgrid Expansion | Hyperscale data center operators in Northern Virginia contract systems isolating mission-critical compute from grid volatility. |
Research Methodology
A spread of perspectives from utility planning officers, IPP project developers, EPC contractors, and grid operators converged on the working assumptions underlying this analysis. Primary interviews with power electronics specialists and transmission system operators combined with secondary validation from EIA data, IEA reports, FERC filings, and project development databases. Bottom-up capacity installation tracking and top-down regulatory framework assessment provided triangulation across modeling approaches.
Segmentation dimensions modeled include fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type across the projection horizon. CAGRs derive from installed base progression analysis and revenue recognition timing for multi-technology integration projects. Forecast inputs incorporate grid-forming inverter certification timelines and synchronous condenser commissioning schedules as technology deployment constraints.
Forecasts assume regulatory continuity in EU Green Deal implementation, China's MIIT GB standards enforcement, and Germany's net-zero mandate dispatch requirements; material policy shifts would require re-modeling. Specific risks include fluorinated gas supply restriction acceleration, lithium supply concentration disruption, and divergent certification regime fragmentation. Recalibration cycles align with material shifts in national grid code harmonization efforts and qualified supplier list publication schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging Energy Technologies
Clean Coal Technologies Sales Market
Emerging Energy Technologies
Clean Technology Market
Emerging Energy Technologies
Global Power-To-X Market
Emerging Energy Technologies
Europe Clean Coal Technologies Market
Emerging Energy Technologies
Energy Transition Market
Emerging Energy Technologies
Decarbonization Market
Emerging Energy Technologies
Advanced Energy Market
Emerging Energy Technologies
United States Clean Coal Technologies Market
Emerging Energy Technologies
Global Microreactor Technology Market
Emerging Energy Technologies
Methanation Technology Market
Emerging Energy Technologies
Cryogenic Technology Market
Emerging Energy Technologies
Nanotechnology in Energy Market