
 Decarbonization Market | 2026-2036
Decarbonization Market Size, Share, and Industry Trends Forecast 2026-2036
Decarbonization Market Analytics
Software-defined carbon accounting and verification platforms is consolidating the value proposition that solution providers deliver to enterprise buyers. Siemens Energy leverages its digital grid infrastructure to embed emissions tracking into power distribution workflows. IBM anchors its position through AI-driven sustainability analytics that integrate with existing enterprise resource planning systems. Deloitte competes by bundling net-zero strategy consulting with regulatory compliance frameworks across multiple jurisdictions.
Decarbonization encompasses the systematic reduction of greenhouse gas emissions through energy transition, process reengineering, and carbon removal technologies, typically measured in CO2-equivalent tons abated and requiring continuous monitoring against science-based targets. Its primary commercial purpose centers on enabling organizations to meet contractual, regulatory, and investor-mandated emissions thresholds while maintaining operational output. Renewable Energy technology commands the largest installed base but Carbon Capture represents the fastest-expanding investment category as hard-to-abate sectors seek residual emissions solutions. Consulting Services within the Solution dimension captures concentrated margin pools because clients prioritize bespoke pathway design over commoditized hardware procurement.
The EU Green Deal and its accompanying Carbon Border Adjustment Mechanism reshape import competitiveness by embedding emissions costs into cross-border trade, while the EPA in the United States enforces methane reduction mandates across oil and gas infrastructure that accelerate monitoring technology deployment. China's MEE implements dual carbon goals through provincial emissions caps that redirect industrial investment toward low-carbon process equipment. Stakeholders must track how divergent national accounting standards create compliance fragmentation that favors multi-jurisdiction advisory specialists over single-market technology vendors.
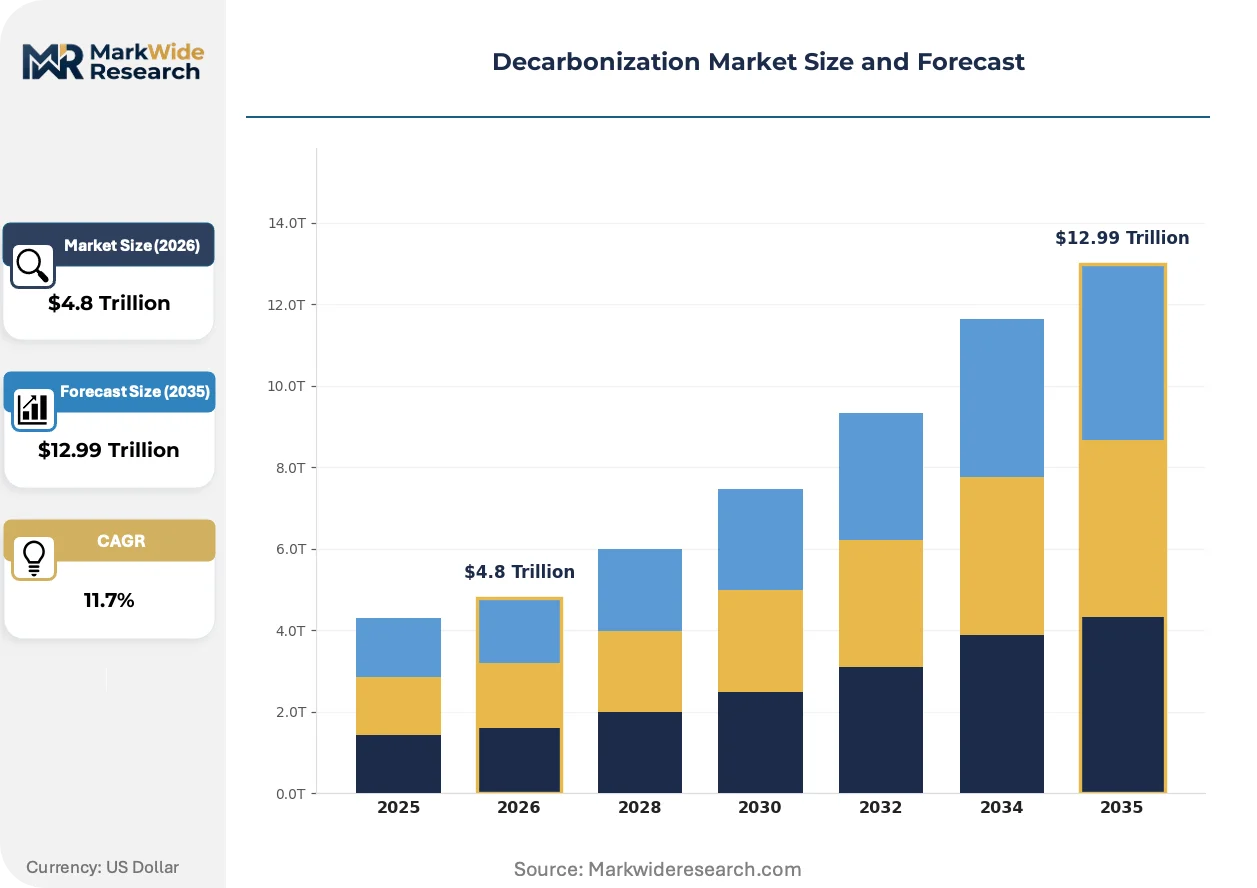
Market Dynamics
The EU Green Deal's Carbon Border Adjustment Mechanism is restructuring trade competitiveness by embedding emissions costs into cross-border transactions, forcing exporters to adopt verifiable carbon accounting systems or face margin compression at European ports.
Growth Catalysts
- EU Carbon Border Adjustment Mechanism:Industrial exporters to Europe must install emissions tracking infrastructure, creating demand for verification software and low-carbon process equipment across steel, cement, and aluminum supply chains.
- China's dual carbon goals:The MEE's provincial emissions caps redirect capital toward carbon capture retrofits and hydrogen process integration in Jiangsu and Shandong industrial clusters.
- Hard-to-abate sectors:Cement, steel, and chemicals producers face residual emissions constraints that accelerate investment in point-source carbon capture and electrolytic hydrogen feedstocks.
Market Restraints
- Electrolyzer supply concentration:Proton exchange membrane stack production concentrates among European and Japanese suppliers, constraining green hydrogen project timelines and inflating capex commitments.
- Geologic storage permitting:Carbon dioxide injection well approvals in the US and North Sea face multi-year regulatory review cycles that delay capture project returns.
- Biomass feedstock competition:Sustainable aviation fuel and bio-based chemicals producers compete for limited agricultural residue and forestry waste streams, elevating input costs.
Strategic Opportunities
- India's PLI scheme for electrolyzers:Domestic manufacturing incentives create white space for local assembly of alkaline and solid oxide systems serving industrial hydrogen demand.
- Direct air capture integration:Offtake agreements from corporate buyers seeking residual emissions offsets are consolidating project finance for modular capture units co-located with geothermal or nuclear power.
- Blockchain-verified carbon accounting:Distributed ledger platforms are penetrating voluntary carbon markets by eliminating double-counting risks and accelerating credit retirement verification.
Industry Challenges
- Process engineer scarcity:Industrial decarbonization projects require specialized expertise in heat pump integration, electrochemical reactor design, and carbon capture solvent chemistry that outpaces university pipeline output.
- Legacy asset stranding risk:Steel and petrochemicals producers face compressed payback periods on carbon-intensive equipment as science-based target deadlines approach, complicating capital allocation decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decarbonization Market |
| Market Size in 2026 | $4.8 Trillion |
| Market Size in 2035 | $12.99 Trillion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Renewable Energy, Carbon Capture, Energy Storage, Electric Vehicles Application: Industrial Processes, Transportation, Power Generation, Agriculture End User: Corporations, Governments, NGOs, Consumers Solution: Consulting Services, Software Solutions, Infrastructure Development, Investment Funds |
| Companies Covered | Siemens Energy, ABB, Climeworks, Carbon Clean, Deloitte, IBM, TotalEnergies, Air Liquide, General Electric Vernova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decarbonization Market Evolving Landscape
Software-defined measurement and verification platforms are displacing manual emissions audits, compressing reporting cycles from annual to continuous while embedding carbon data directly into operational technology stacks.
Digital twin technology for industrial process optimization is consolidating the value proposition that engineering firms deliver to heavy manufacturers. Steel and cement producers in Germany and South Korea deploy physics-based simulations to model heat recovery and fuel substitution scenarios before committing to physical retrofits. This capability compresses project development timelines and reduces performance risk for first-of-a-kind low-carbon installations.
The EPA's methane reduction mandates across US oil and gas infrastructure are accelerating optical gas imaging and satellite monitoring deployment. Pipeline operators and storage facility managers must install continuous emissions detection systems or face escalating penalties under the Inflation Reduction Act's fee structure. This regulatory pressure is concentrating procurement decisions on integrated sensor networks that feed directly into federal reporting databases.
Corporate buyers are consolidating decarbonization procurement through sustainability-linked service contracts that tie vendor payments to verified emissions outcomes. Industrial facilities in the Netherlands and California now structure equipment leases with performance guarantees measured in tons abated rather than uptime or throughput metrics. This shift transfers technical risk to solution providers while compressing sales cycles for proven technologies.
Decarbonization Market Segmentation
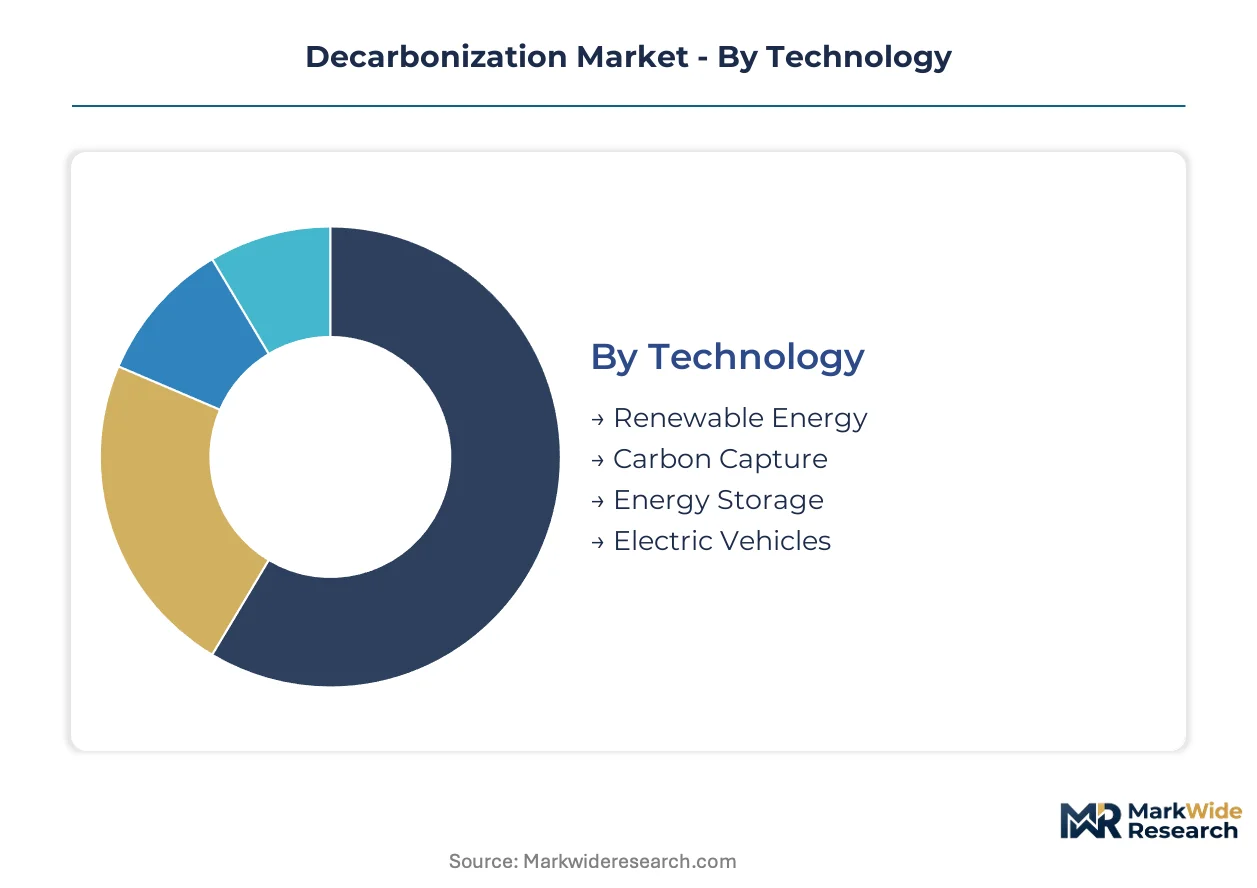
Decarbonization procurement splits between capital-intensive infrastructure and recurring service models, with technology selection and buyer type determining contract structures and margin profiles. Understanding these fault lines reveals where solution providers can anchor recurring revenue versus one-time equipment sales.
Technology:
Volume deployment concentrates in mature hardware categories while premium pricing attaches to emerging systems with residual emissions applications.
- Renewable Energy:Solar PV and wind turbine installations dominate installed capacity across utility and commercial portfolios. Procurement concentrates in China's Jiangsu province and Texas wind corridors as grid interconnection queues clear, though land-use constraints and curtailment risk compress returns in saturated markets.
- Carbon Capture:Point-source amine scrubbing and solid sorbent systems target cement, steel, and petrochemicals facilities with residual emissions profiles. Investment flows fastest to Gulf Coast and North Sea clusters where geologic storage permits advance, constrained by multi-year regulatory review cycles that delay project finance close.
- Energy Storage:Lithium-ion battery systems and emerging iron-air technologies buffer renewable intermittency.
- Electric Vehicles:Fleet electrification and charging infrastructure span passenger, commercial, and heavy-duty transport segments.
Mature deployment sits with Renewable Energy. Newer deployment is concentrated in Carbon Capture.
Application:
End-use concentration determines technology bundling, with process heat applications commanding integrated solutions and mobility segments favoring modular procurement.
- Industrial Processes:Cement kilns, blast furnaces, and steam crackers require heat pump integration, electrochemical reactors, and fuel substitution retrofits. Demand clusters in Germany's Ruhr Valley and South Korea's Ulsan complex as science-based target deadlines approach, constrained by process engineer scarcity that stretches project timelines.
- Transportation:Fleet electrification, sustainable aviation fuel, and maritime ammonia fuel span road, air, and sea corridors. Procurement accelerates in California and the Netherlands where low-carbon fuel standards mandate blending quotas, though electrolyzer supply concentration inflates green hydrogen project capex.
- Power Generation:Utility-scale renewable procurement and grid balancing services.
- Agriculture:Methane capture from livestock operations and precision fermentation for protein alternatives.
Capital intensity peaks in Industrial Processes. Fastest policy tailwinds attach to Transportation.
End User:
Contract sophistication varies by procurement scale, with large buyers demanding performance guarantees and smaller participants accepting standardized offerings.
- Corporations:Science-based target commitments drive Scope 1-3 emissions accounting and supply chain decarbonization mandates. Procurement concentrates in Fortune 500 industrials with 2030 interim deadlines, favoring sustainability-linked service contracts that tie vendor payments to verified tons abated.
- Governments:National dual carbon goals and municipal fleet electrification programs anchor public sector demand. China's MEE provincial caps redirect investment toward low-carbon equipment in state-owned steel and chemicals enterprises.
- NGOs:Voluntary carbon market development and conservation finance mechanisms.
- Consumers:Residential solar, heat pump, and electric vehicle adoption through subsidy programs.
Contract value concentrates with Corporations. Policy leverage resides with Governments.
Solution:
Margin pools shift from hardware commoditization toward advisory and software layers that embed into operational workflows.
- Consulting Services:Net-zero pathway design, regulatory compliance across multiple jurisdictions, and M&A due diligence for stranded asset risk. Demand concentrates among industrial exporters facing EU Carbon Border Adjustment Mechanism compliance thresholds, favoring multi-jurisdiction specialists over single-market vendors.
- Software Solutions:Continuous emissions monitoring, digital twin process optimization, and blockchain-verified carbon accounting. Procurement accelerates as EPA methane mandates and EU CSRD disclosure rules compress reporting cycles from annual to real-time.
- Infrastructure Development:Turnkey EPC for renewable generation, carbon capture retrofits, and hydrogen production facilities.
- Investment Funds:Green bonds, sustainability-linked loans, and project finance for first-of-a-kind technologies.
Recurring revenue concentrates in Consulting Services. Fastest technology refresh cycles attach to Software Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates production capacity for electrolyzers and carbon capture equipment, while the United States and Europe absorb the majority of deployed systems. Demand fragmentation across jurisdictions creates compliance complexity for multinational industrial exporters.
United States
The EPA enforces methane reduction mandates across oil and gas infrastructure under the Inflation Reduction Act. Pipeline operators in Texas and Louisiana install continuous emissions detection systems to avoid escalating federal penalties. Houston anchors carbon capture project finance as Gulf Coast geologic storage permits advance through regulatory review.
Germany
Industrial exporters face EU Carbon Border Adjustment Mechanism compliance thresholds that embed emissions costs into cross-border steel and cement shipments. The EU Green Deal tightens disclosure rules through CSRD requirements that compress corporate reporting cycles. The Ruhr Valley clusters blast furnace retrofits and hydrogen process integration as science-based target deadlines approach.
China
Provincial emissions caps from the MEE redirect capital toward low-carbon equipment in state-owned steel and chemicals enterprises. Dual carbon goals accelerate carbon capture retrofits and electrolytic hydrogen feedstock adoption. Jiangsu and Shandong industrial clusters concentrate demand for point-source capture systems and solid oxide electrolyzer manufacturing.
India
Domestic manufacturing incentives through the PLI scheme for electrolyzers create white space for local alkaline and solid oxide system assembly. State-owned refiners and fertilizer producers anchor industrial hydrogen demand in Gujarat and Maharashtra. Mumbai-Pune industrial corridor attracts project finance for first-of-a-kind green hydrogen installations.
United Kingdom
The North Sea geologic storage licensing framework shapes carbon capture investment timelines for industrial clusters. Offshore wind procurement contracts anchor power-to-X project economics in Scotland and northeast England. Teesside and Humber industrial zones consolidate point-source capture deployments serving cement and petrochemicals facilities.
Decarbonization Market Competitive Landscape
Top-tier vendors anchor premium advisory and integrated infrastructure contracts, while mid-tier specialists compete on regional compliance expertise and technology licensing. The vendor base stratifies across three tiers: multinational engineering conglomerates with digital grid capabilities, pure-play carbon capture technology developers, and professional services firms bundling net-zero strategy with regulatory frameworks. Siemens Energy and IBM exemplify the first archetype through embedded emissions tracking, while Climeworks and Carbon Clean occupy the technology developer niche. Deloitte represents the advisory tier. Competitive moves concentrate on M&A for process engineering talent and strategic partnerships to secure electrolyzer stack supply.
Among European-based solution providers, Siemens Energy and ABB occupy positions within the integrated infrastructure archetype, anchoring digital grid and power distribution workflows that embed emissions monitoring. Climeworks, a Swiss developer, exemplifies the direct air capture specialization vector that attracts corporate offtake agreements for residual emissions offsets. Deloitte, a UK-originated professional services partnership, sits within the multi-jurisdiction advisory tier where EU Carbon Border Adjustment Mechanism compliance creates concentrated margin pools. IBM, a US-based technology corporation, represents the AI-driven sustainability analytics archetype that integrates with enterprise resource planning systems.
| Leading Market Players |
|---|
| Siemens Energy |
| ABB |
| Climeworks |
| Carbon Clean |
| Deloitte |
| IBM |
| TotalEnergies |
| Air Liquide |
| General Electric Vernova |
| Others |
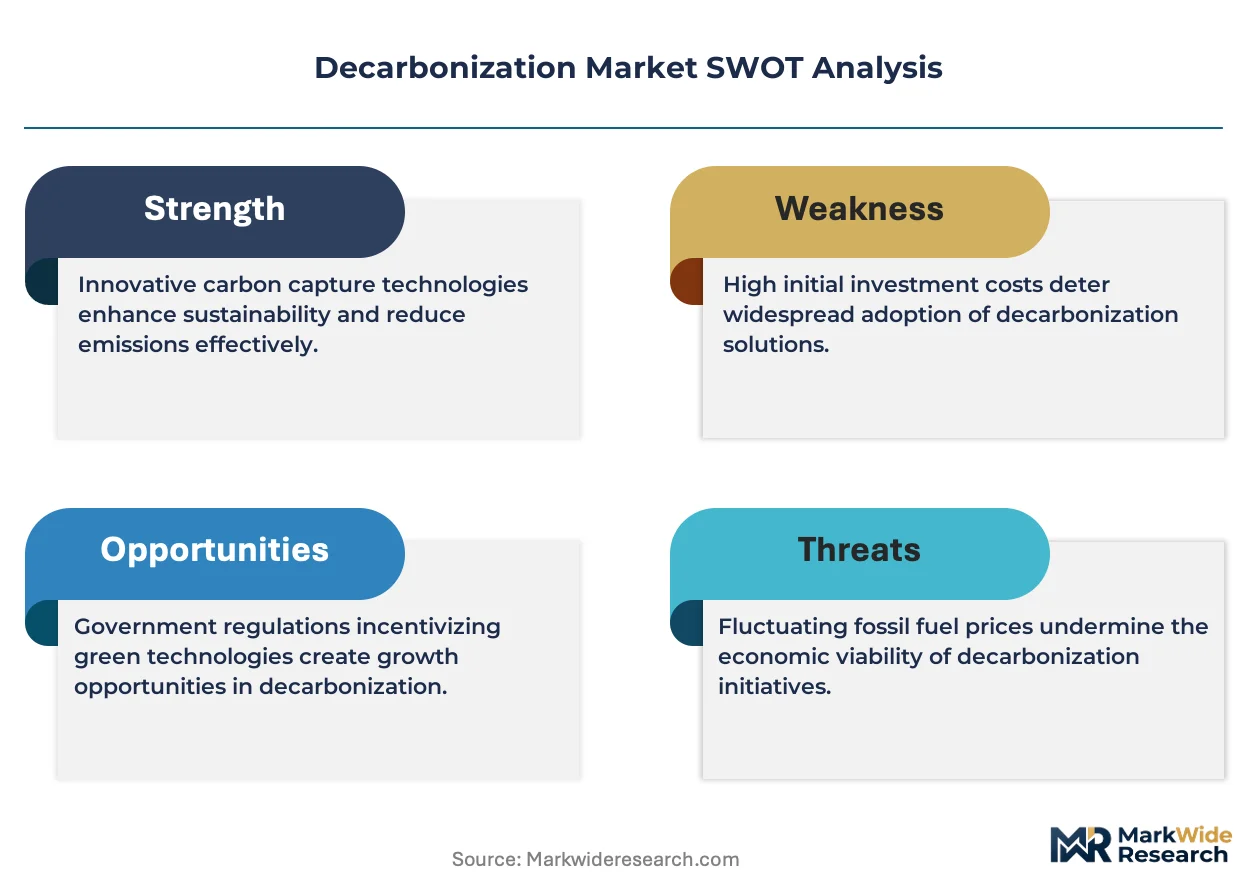
Value Network & Pricing Analysis
Corporate procurement teams demanding sustainability-linked performance guarantees are forcing solution providers to absorb technical risk and restructure contracts around verified tons abated rather than equipment uptime, compressing margins for unproven technologies while concentrating pricing power with vendors holding operational track records.
Pricing Analysis
Margin tightening in emerging technology tiers reflects electrolyzer stack supply concentration among European and Japanese suppliers, constraining project timelines and inflating capex commitments for green hydrogen deployments. Three-tier pricing structure across premium, standard, and economy levels separates vendors with geologic storage permits and operational capture facilities from equipment-only suppliers. Price differentiation hinges on certification grade under EU Carbon Border Adjustment Mechanism compliance frameworks and vertical integration into solvent chemistry manufacturing. Industrial exporters facing science-based target deadlines exhibit lowest price sensitivity, while municipal fleet electrification programs show highest elasticity.
Supply Chain Analysis
ISO 14064 and EU CSRD certification requirements gate access to premium procurement channels, favoring vendors with established verification protocols and multi-jurisdiction compliance documentation. Manufacturing concentration centers on China for electrolyzer assembly and carbon capture module fabrication, with Germany and South Korea anchoring precision component production for heat pump and electrochemical reactor systems. Critical inputs include proton exchange membrane stacks, solid sorbent materials, and specialized carbon capture solvents. Single-source vulnerability in geologic storage permitting creates bottlenecks that delay project finance close. Distribution runs through engineering-procurement-construction contractors and direct utility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrolyzer manufacturing capacity constraints and multi-year geologic storage permitting timelines prop pricing for vendors with secured supply chains and approved injection well access, creating durable margin pools for incumbents with operational assets.
For Market Incumbents: Extend digital twin capabilities into predictive maintenance offerings that guarantee uptime for first-of-a-kind carbon capture installations, defending against pure-play technology developers lacking operational service networks. Secure backward integration into solid sorbent manufacturing to reduce exposure to Chinese supply concentration and capture margin from specialty chemical inputs.
For New Entrants and Emerging Players: Mid-sized industrial facilities in India's Gujarat and Maharashtra corridors remain underserved by integrated advisory-technology bundles, presenting white space for local assembly partnerships under PLI scheme incentives. Target state-owned refiners with alkaline electrolyzer systems that bypass European supply constraints, using performance contracting to overcome buyer skepticism toward unproven vendors.
For Investors and Strategic Acquirers: The window for entry favors engineering firms with process chemistry expertise and established relationships with hard-to-abate sector facility managers. Long-term viability rests on acquiring capabilities in heat pump integration and electrochemical reactor design that outpace university pipeline output. Watch EPA methane enforcement intensity and EU CBAM expansion scope as signals for monitoring technology demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer Manufacturing Scale-Up | Domestic assembly under India's PLI scheme reduces capex inflation from European supply concentration. |
| Carbon Capture Retrofit Partnership | Co-development with cement and steel producers in China's Jiangsu province accelerates operational track record accumulation. |
| Digital Twin Platform Integration | Siemens Energy and ABB embed emissions monitoring into power distribution workflows for continuous verification. |
| Geologic Storage Joint Venture | Gulf Coast and North Sea permit holders consolidate access to injection well infrastructure for project finance. |
| Blockchain-Verified Carbon Accounting | Distributed ledger platforms eliminate double-counting risks in voluntary carbon markets for corporate offtake agreements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with carbon capture project developers, electrolyzer manufacturing executives, EPC contractors, and utility procurement officers. Primary fieldwork combined with validation against EPA enforcement databases, EU ETS transaction registries, and China's MEE provincial emissions disclosure filings. Bottom-up capacity installation tracking and top-down policy impact modeling were triangulated to reconcile segment-level outputs.
Reconciliation of project finance databases, equipment shipment records, and corporate sustainability disclosure filings informed the analytical framework across the projection horizon. Segmentation dimensions modeled include technology maturity tier, end-use application intensity, buyer contract sophistication, and regional regulatory framework stringency. CAGRs were derived from capacity deployment curves and policy implementation timelines, incorporating electrolyzer manufacturing lead times and geologic storage permitting duration as industry-specific inputs.
Revisions become necessary when EPA methane enforcement intensity shifts, EU CBAM scope expands beyond pilot sectors, or China's MEE provincial cap adjustments redirect state-owned enterprise capital allocation. Forecasts reflect assumptions around technology cost reduction trajectories and regulatory compliance deadline adherence. A model refresh is warranted upon material change in electrolyzer supply chain configuration or geologic storage permitting velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging Energy Technologies
Multi Energy Systems Market
Emerging Energy Technologies
Global Microreactor Technology Market
Emerging Energy Technologies
Clean Technology Market
Emerging Energy Technologies
Cryogenic Technology Market
Emerging Energy Technologies
United States Clean Coal Technologies Market
Emerging Energy Technologies
Global Power-To-X Market
Emerging Energy Technologies
Europe Clean Coal Technologies Market
Emerging Energy Technologies
Methanation Technology Market
Emerging Energy Technologies
Advanced Energy Market
Emerging Energy Technologies
Clean Coal Technologies Sales Market
Emerging Energy Technologies
Energy Transition Market
Emerging Energy Technologies
Nanotechnology in Energy Market