
 Europe Clean Coal Technologies Market | 2026-2036
Europe Clean Coal Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Clean Coal Technologies Market Intelligence
The Europe Clean Coal Technologies Market is restructuring around a sharp split between premium integrated gasification combined cycle installations and commodity fluidized bed combustion retrofits. Siemens Energy AG leverages its turbine technology leadership to dominate the premium tier across German utilities. Babcock & Wilcox Enterprises anchors the retrofit segment with boiler upgrade systems for aging Polish coal fleets. Shell PLC competes through carbon capture integration partnerships with industrial off-takers.
Clean coal technologies encompass combustion, gasification, and emissions control systems designed to reduce sulfur dioxide, nitrogen oxides, and carbon dioxide output from coal-fired plants, typically achieving capture rates above 90 percent for sulfur compounds through flue-gas desulfurization. These systems serve power generators and industrial facilities seeking to extend asset life while meeting tightening environmental standards. Carbon capture technology commands the deepest margin pools as utilities face mounting pressure to demonstrate decarbonization pathways. Power generation applications lead installed capacity, though industrial processes represent the fastest-growing segment as cement and steel producers explore co-firing alternatives. Retrofit solutions occupy the largest addressable base given Europe's extensive legacy coal infrastructure.
The EU Green Deal, REACH, and F-Gas Regulation collectively shape market access by mandating progressive emission reductions and chemical handling standards for coal plant operators. ECHA oversight of industrial chemicals used in scrubbing and capture media directly influences equipment specification requirements. Stakeholders must monitor how the EU AI Act extends to automated plant optimization systems and whether national regulators in Poland and Germany accelerate phase-out timelines that could strand retrofit investments.
Market Dynamics
The Europe Clean Coal Technologies Market is bifurcating around the EU Green Deal's emission benchmarks, which force utilities to choose between premium gasification systems and accelerated asset retirement. This regulatory pressure compresses decision timelines for Polish and German operators holding aging coal fleets.
Growth Catalysts
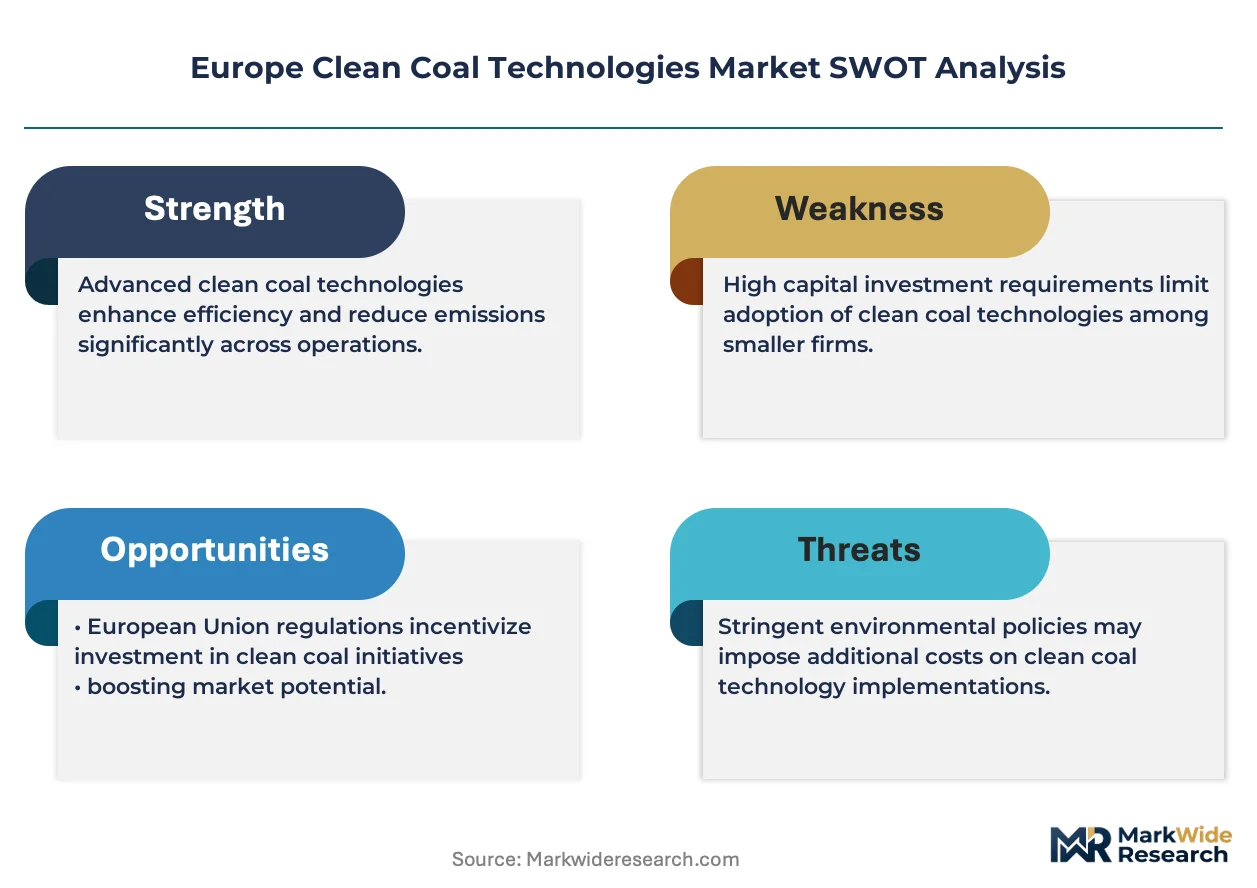
- Integrated Gasification Combined Cycle:Polish utilities in the Silesian basin are retrofitting plants with IGCC systems to extend asset life while meeting EU F-Gas Regulation targets for fluorinated gas emissions.
- EU Green Deal trajectory:The framework's progressive decarbonization mandates create compliance-driven demand for carbon capture retrofits among Central European power generators facing 2030 interim targets.
- Industrial co-firing:Cement and steel producers in Germany's Ruhr region are piloting clean coal technologies to substitute natural gas in high-heat processes.
Market Restraints
- Amine solvent cost volatility:Fluctuations in monoethanolamine prices directly impact carbon capture unit economics, squeezing margins on retrofit projects.
- Single-source turbine dependency:Premium IGCC installations rely on concentrated supply of advanced gas turbines from limited European manufacturing bases.
- EU ETS carbon price exposure:Emissions trading scheme volatility creates investment uncertainty for utilities weighing retrofit against fuel switching.
Strategic Opportunities
- Czech brown coal basins:Underpenetrated lignite regions present retrofit potential as operators seek alternatives to politically sensitive mine closures.
- Hydrogen co-firing convergence:Integration of gasification systems with emerging hydrogen infrastructure creates dual-fuel flexibility for German utilities.
- CSRD disclosure mandates:Corporate Sustainability Reporting Directive requirements are pushing industrial off-takers toward verified carbon capture partnerships.
Industry Challenges
- Scrubber chemistry expertise gap:Utilities struggle to recruit specialists in flue-gas desulfurization system optimization amid workforce transitions to renewables.
- Legacy boiler integration complexity:Retrofitting 1970s-era Polish coal units with modern emissions controls requires custom engineering that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Clean Coal Technologies Market |
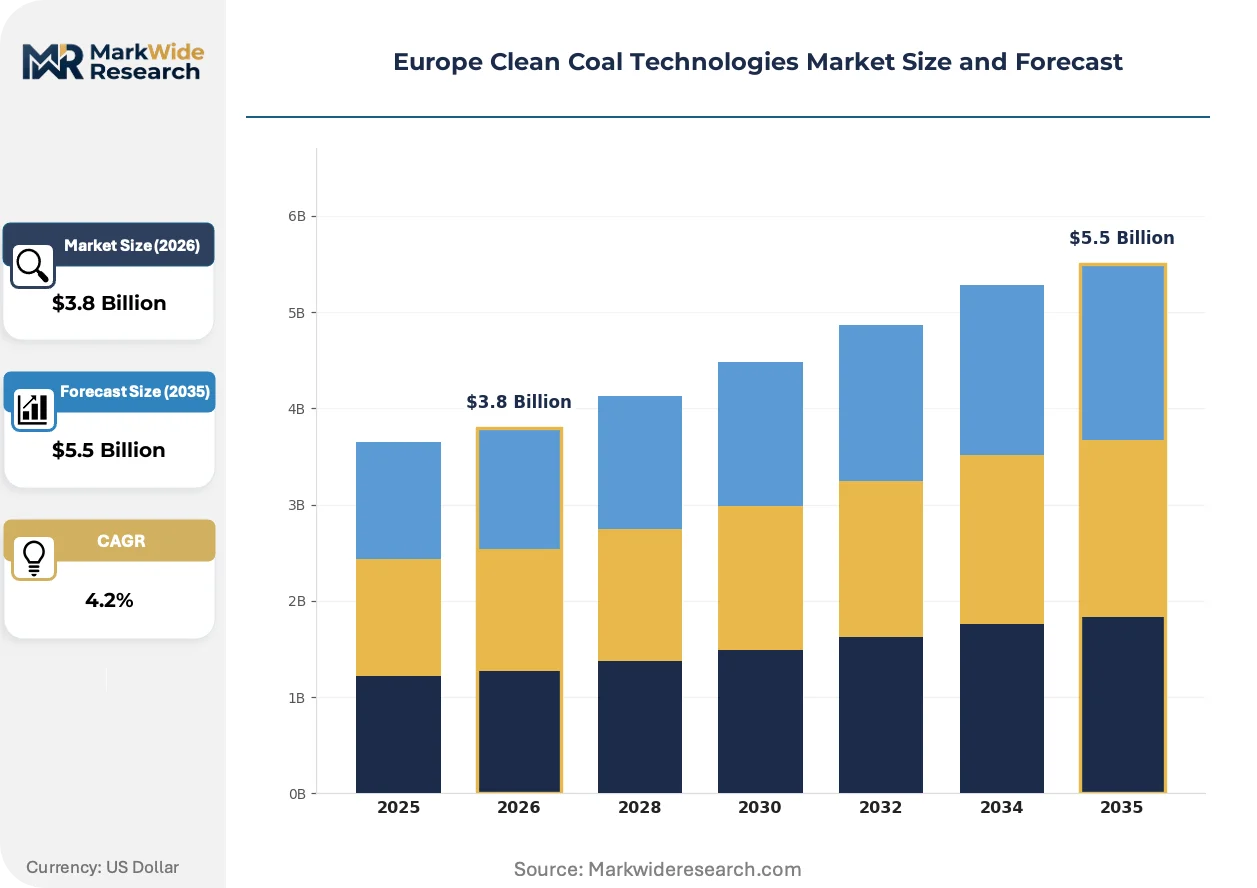
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Carbon Capture, Gasification, Fluidized Bed Combustion, Integrated Gasification Combined Cycle Application: Power Generation, Industrial Processes, Co-Firing, Carbon Sequestration End User: Utilities, Manufacturing, Mining, Energy Producers Installation Type: Onshore, Offshore, Integrated Systems, Retrofit Solutions |
| Companies Covered | Siemens Energy AG, Babcock & Wilcox Enterprises, KBR Inc., General Electric Company, Alstom SA, Shell PLC, RAFAKO S.A., Polimex Mostostal S.A., Doosan Škoda Power, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Clean Coal Technologies Market Strategic Shifts & Innovations
Technology convergence and regulatory disclosure mandates are compressing equipment procurement cycles across European utilities. Operators now prioritize modular retrofit architectures that accommodate future carbon capture add-ons.
Advanced amine-based post-combustion capture is unifying previously separate sulfur and carbon dioxide removal trains into single-process configurations. German utilities in North Rhine-Westphalia are piloting these integrated systems at three pilot-scale facilities. This unification is compressing the physical footprint and capital intensity of retrofit projects, enabling installation at space-constrained urban plants.
The EU AI Act's risk classification framework is extending to automated plant optimization systems used in coal fleet management. Equipment vendors must now certify algorithmic decision-making tools for emissions monitoring and load balancing. German operators are most affected, requiring documentation upgrades for existing supervisory control systems before 2026 enforcement deadlines.
Industrial buyers are consolidating procurement authority for emissions control equipment under centralized sustainability functions. Previously fragmented purchasing across plant engineering departments is giving way to group-level framework agreements with technology providers. This concentration is most visible in Poland, where state-controlled utilities are standardizing on preferred scrubber and capture system suppliers.
Europe Clean Coal Technologies Market Segmentation
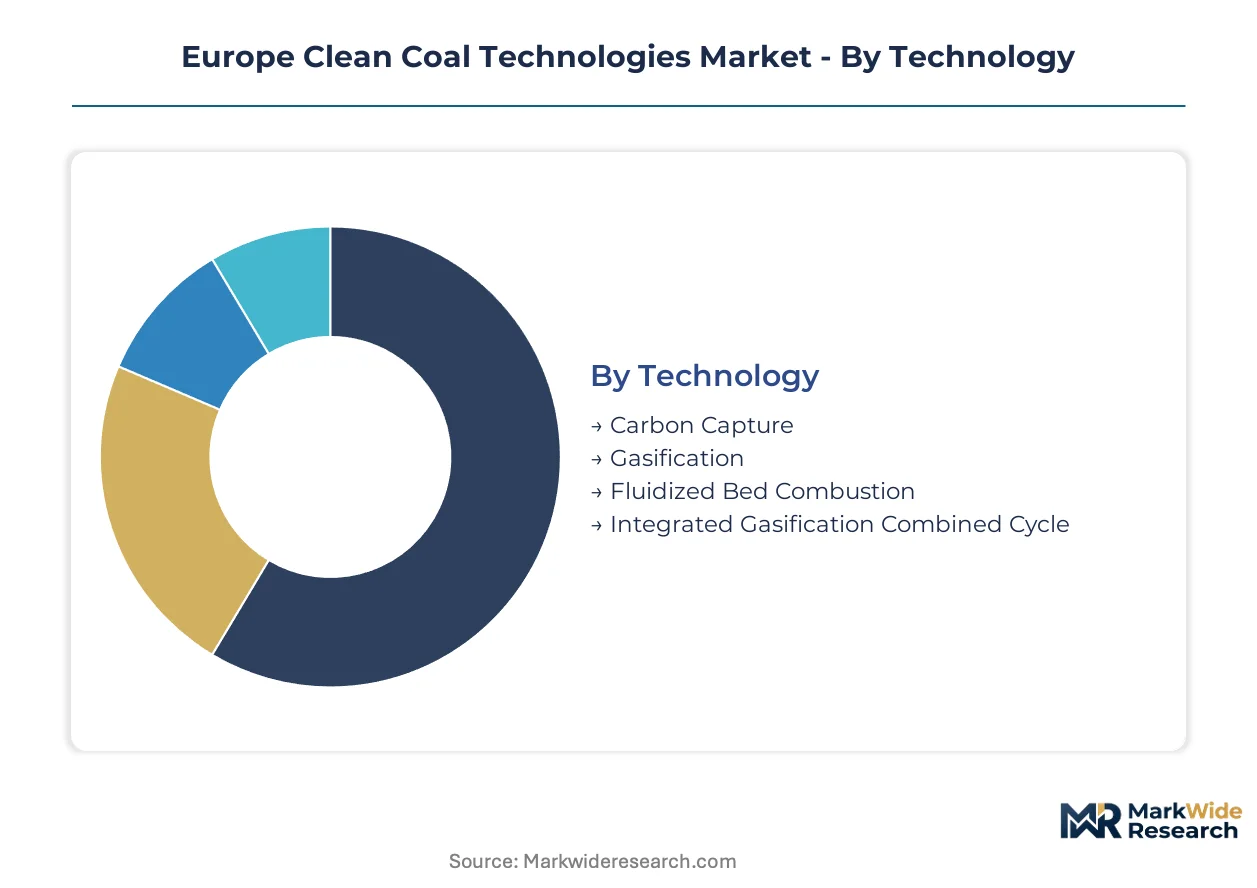
Segmentation in the Europe Clean Coal Technologies Market reveals how regulatory pressure and asset age determine technology choices across the region. Polish utilities favor retrofit-compatible systems, while German operators invest in premium integrated configurations to meet EU Green Deal benchmarks.
Technology:
REACH and EU Green Deal compliance obligations vary sharply across these four technology classes, with carbon capture systems facing the heaviest ECHA chemical registration burdens for amine solvents and sorbent materials.
- Carbon Capture:Post-combustion amine scrubbing and pre-combustion capture systems strip carbon dioxide from flue gas or syngas streams. German utilities in North Rhine-Westphalia deploy these systems to satisfy CSRD disclosure mandates for Scope 1 emissions. Amine solvent cost volatility squeezes project economics.
- Gasification:Partial oxidation converts coal into synthetic gas for cleaner combustion or chemical feedstock production. Polish operators in the Silesian basin adopt gasification to extend mine life while meeting F-Gas Regulation fluorinated emission limits. Capital intensity limits deployment to large baseload plants.
- Fluidized Bed Combustion:Crushed coal burns suspended in upward air flows, enabling lower-temperature sulfur retention within the bed.
- Integrated Gasification Combined Cycle:Combined gasification and combined-cycle turbine configuration maximizes efficiency and capture potential.
Leading the category by volume: Fluidized Bed Combustion. Growing fastest: Carbon Capture.
Application:
Cost tier separation distinguishes utility-scale deployments from industrial pilot projects, with power generation commanding premium engineering resources and co-firing experiments operating on constrained capital budgets.
- Power Generation:Centralized electricity production from dedicated coal-fired plants equipped with emissions control trains. Polish state-controlled utilities dominate procurement, retrofitting aging units to avoid politically sensitive capacity closures. Baseload reliability requirements sustain investment despite renewable competition.
- Industrial Processes:Cement kilns and steel blast furnaces substitute coal for natural gas in high-heat applications. German Ruhr region manufacturers pilot clean coal integration to hedge against gas price volatility and meet EU ETS compliance obligations. Process heat demands exceed what electrification currently delivers.
- Co-Firing:Biomass or waste materials burn alongside coal in modified boilers.
- Carbon Sequestration:Long-term geological storage of captured carbon dioxide in depleted oil fields or saline aquifers.
Power Generation holds the largest installed base. Industrial Processes are climbing the fastest as manufacturing decarbonization pressures intensify.
End User:
Customer type fragmentation separates regulated utilities with rate-base recovery mechanisms from industrial offtakers exposed to commodity margin pressure.
- Utilities:Regulated power generators with franchise territories and cost-pass-through structures. German municipal utilities and Polish state energy groups anchor demand for integrated gasification systems. Regulatory asset base treatment enables long-payback technology investments.
- Manufacturing:Cement, steel, and chemicals producers seeking process emissions reductions. German industrial clusters in North Rhine-Westphalia and Poland's Upper Silesia drive pilot deployments. Corporate sustainability commitments override pure project economics.
- Mining:Coal extraction operations with captive power needs and methane management requirements.
- Energy Producers:Independent power merchants and district heating operators without regulated cost recovery.
Utilities dominate procurement volume. Manufacturing is gaining share fastest as CSRD disclosure mandates expand the buyer pool.
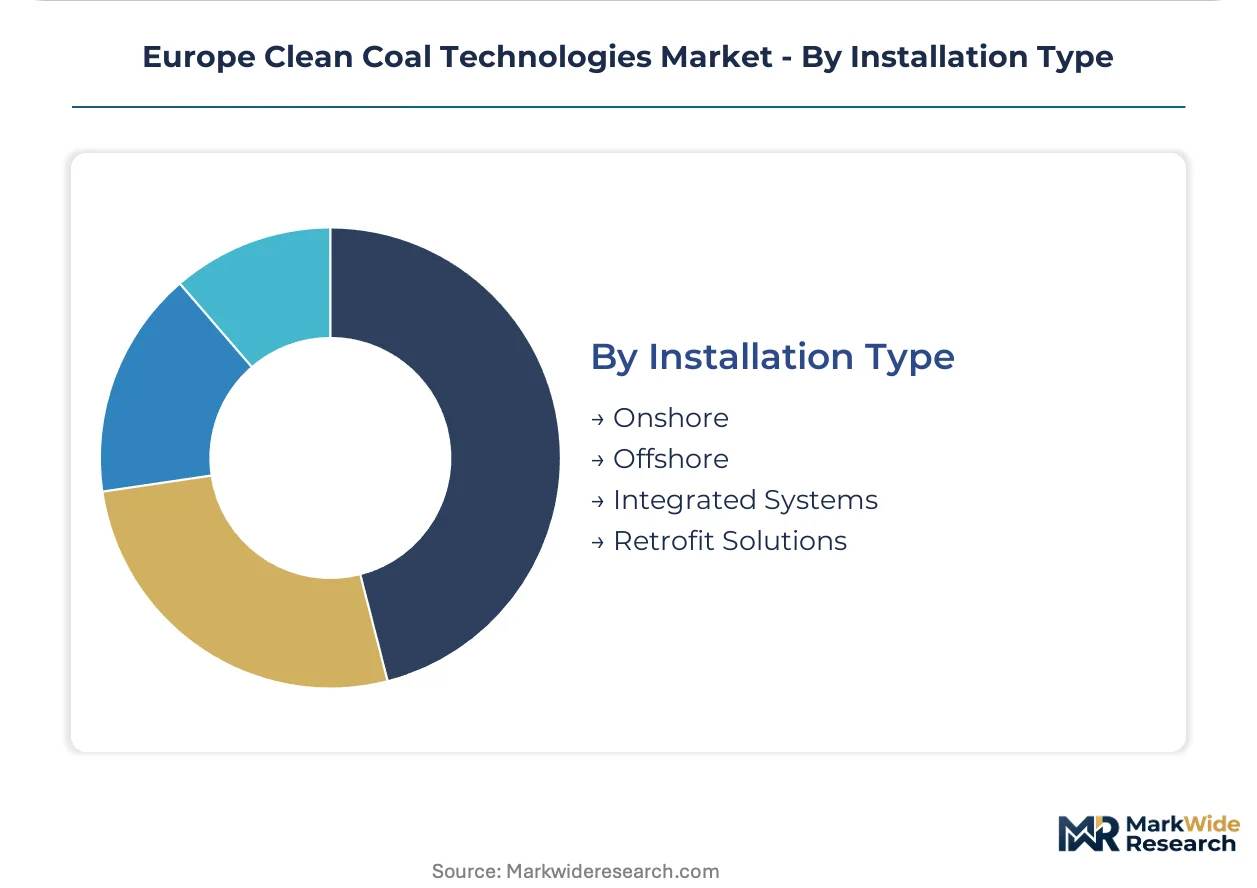
Installation Type:
Geography of deployment constrains physical configuration, with landlocked Central European plants limited to onshore retrofits while coastal locations access offshore carbon transport infrastructure.
- Retrofit Solutions:Emissions control and gasification equipment added to existing coal-fired units. Polish utilities favor this approach to preserve sunk capital in 1970s-era boiler infrastructure. Custom engineering requirements extend project timelines and inflate costs.
- Integrated Systems:Greenfield installations combining gasification, power generation, and carbon capture in unified configurations. German utilities deploy these at replacement sites where old plants face forced retirement. Higher efficiency justifies premium capital outlays.
- Onshore:Land-based installations at existing plant sites.
- Offshore:Coastal or marine-based carbon transport and storage infrastructure.
Retrofit Solutions carry the largest addressable base. Integrated Systems show the steepest expansion trajectory where greenfield permits are obtainable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Silesian coal basin spanning southern Poland anchors European clean coal deployment, with utilities retrofitting legacy infrastructure under tightening EU Green Deal emission benchmarks.
Poland
Polish state-controlled utilities in the Silesian basin drive retrofit demand for integrated gasification systems to extend mine life. The EU F-Gas Regulation mandates fluorinated gas emission reductions from coal plant operations. Katowice-based energy groups are consolidating procurement under centralized sustainability functions to standardize scrubber supplier relationships.
Germany
German municipal utilities in North Rhine-Westphalia pilot advanced amine-based carbon capture to satisfy CSRD disclosure mandates for Scope 1 emissions. The EU AI Act requires certification upgrades for automated plant optimization systems before 2026 enforcement deadlines. Ruhr region industrial clusters are testing clean coal integration in cement and steel processes to hedge against gas price volatility.
Czech Republic
Czech brown coal operators in the North Bohemian lignite fields seek retrofit alternatives to politically sensitive mine closure schedules. REACH compliance obligations for amine solvents and sorbent materials shape equipment specification requirements. The Ústí nad Labem industrial corridor hosts pilot projects for fluidized bed combustion upgrades.
United Kingdom
UK power generators face accelerated coal phase-out timelines that compress decision windows for final retrofit investments. The UK Emissions Trading Scheme parallels EU ETS carbon price exposure, creating investment uncertainty. Former coal-dependent regions in Yorkshire and the Midlands explore carbon capture readiness for remaining industrial facilities.
Netherlands
Dutch utilities concentrate procurement authority for emissions control equipment under group-level framework agreements with technology providers. The EU Green Deal trajectory forces choices between premium gasification systems and accelerated asset retirement. Rotterdam port infrastructure supports pilot carbon transport and storage integration for coastal plant locations.
Europe Clean Coal Technologies Market Key Industry Players
Premium-margin players sit above commodity-margin players across technology complexity tiers, with integrated gasification combined cycle specialists commanding deeper returns than fluidized bed combustion retrofitters. The vendor base stratifies between turbine-technology leaders, boiler upgrade specialists, and carbon capture integrators. Three archetypes dominate: engineering conglomerates with power generation portfolios, industrial equipment fabricators with scrubber expertise, and energy majors pivoting toward decarbonization services. Competitive moves concentrate on strategic partnerships for carbon capture integration and modular retrofit architectures that accommodate future technology add-ons.
Within the engineering conglomerate tier, Siemens Energy AG and General Electric Company exemplify premium-positioned players leveraging turbine technology leadership across German utility installations. Babcock & Wilcox Enterprises anchors the commodity-margin retrofit segment with boiler upgrade systems for aging Polish coal fleets. Shell PLC occupies a distinct position as an energy major competing through carbon capture integration partnerships with industrial off-takers seeking verified emissions reductions.
| Leading Market Players |
|---|
| Siemens Energy AG |
| Babcock & Wilcox Enterprises |
| KBR Inc. |
| General Electric Company |
| Alstom SA |
| Shell PLC |
| RAFAKO S.A. |
| Polimex Mostostal S.A. |
| Doosan Škoda Power |
| Others |
Cost & Logistics Intelligence
Backward integration into turbine manufacturing anchors Siemens Energy AG's supply position and pricing power across German IGCC installations. This captive production of gas turbine components insulates premium-tier vendors from amine solvent cost volatility while compressing margins for commodity retrofitters dependent on spot-market boiler materials.
Pricing Analysis
Outcome-based pricing tied to guaranteed carbon capture rates anchors contract structures for post-combustion amine systems. Three-tier pricing structure across premium, standard, and economy levels separates integrated gasification combined cycle installations from fluidized bed combustion retrofits and basic scrubber upgrades. Cost compression in the retrofit tier is intensifying because Polish utilities consolidate procurement under centralized sustainability functions. State-controlled energy groups exhibit highest price sensitivity due to rate-base scrutiny, while German municipal utilities prioritize performance guarantees over unit economics.
Supply Chain Analysis
Refurbishment flows for 1970s-era Polish boiler components create secondary supply channels that extend asset life and dampen new equipment demand. Component fabrication concentrates in Germany, Czech Republic, and Poland for combustion systems and emissions control trains. Raw material dependencies center on specialty steel alloys for high-temperature gasification vessels, ceramic membranes for filtration systems, and monoethanolamine for carbon capture chemistry. Single-source vulnerability in advanced gas turbine supply from limited European manufacturing bases threatens project timelines. Distribution runs through engineering-procurement-construction contractors with utility relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon capture technology is displacing legacy flue-gas desulfurization as the primary compliance pathway under EU Green Deal benchmarks. This transition compresses decision timelines for utilities holding aging coal fleets.
For Market Incumbents: Extend service contract coverage for scrubber chemistry optimization to capture recurring revenue as hardware margins tighten. Deepen backward integration into amine solvent production to offset feedstock cost volatility threatening carbon capture unit economics. Siemens Energy AG and Babcock & Wilcox Enterprises must consolidate procurement relationships with Polish state utilities before centralized sustainability functions lock in preferred supplier frameworks. For New Entrants and Emerging Players: Begin with modular carbon capture architectures designed for retrofits at space-constrained urban plants in North Rhine-Westphalia. Czech brown coal basins present the most penetrable geography given political resistance to mine closures and underinvestment in alternatives. Target industrial off-takers in cement and steel through verified emissions reduction partnerships that satisfy CSRD disclosure mandates without requiring utility-scale project capabilities. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by engineering conglomerates seeking carbon capture integration capabilities. Five-to-ten year viability hinges on whether EU ETS carbon price trajectories sustain retrofit economics against fuel switching alternatives. Target acquisition archetypes are scrubber chemistry specialists with ECHA registration expertise and pilot-scale carbon capture technology developers. Monitor EU AI Act enforcement deadlines for automated plant optimization certification as inflection indicator for compliance service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration Partnership | Shell PLC leverages industrial off-taker relationships to secure verified emissions reduction contracts under CSRD mandates. |
| Modular Retrofit Architecture Development | Equipment vendors accommodate future technology add-ons at Polish utilities preserving sunk capital in aging boiler infrastructure. |
| Amine Solvent Supply Security | Backward integration into monoethanolamine production hedges feedstock cost volatility squeezing carbon capture project margins. |
| Centralized Procurement Consolidation | Katowice-based energy groups standardize scrubber supplier relationships under sustainability functions to compress vendor margins. |
| Hydrogen Co-firing Convergence | Ruhr region utilities pilot dual-fuel flexibility integrating gasification systems with emerging hydrogen infrastructure. |
Research Approach
Multi-period observation of EU ETS carbon price trajectories, F-Gas Regulation compliance timelines, and IGCC deployment permits anchored the trend analysis, supplemented by interviews with utility planning officers, EPC contractors, plant engineers, and aftermarket service heads. Secondary validation drew from ECHA chemical registration databases, EU Green Deal policy documents, FERC-equivalent grid operator filings, and customs data on emissions control equipment imports. Bottom-up project pipeline assessment triangulated against top-down regulatory mandate modeling.
Segment-weighting across technology classes, application types, end-user categories, and installation configurations shaped the analytical framework over the projection horizon. Technology splits encompassed carbon capture, gasification, fluidized bed combustion, and integrated gasification combined cycle systems. Application modeling separated power generation baseload from industrial process heat and co-firing pilots. CAGRs were derived from regression analysis of historical deployment rates against regulatory milestone acceleration.
Regulatory phase-out acceleration, amine solvent price spikes, and EU AI Act certification delays are the dominant revision risks that could compress or extend the analysis window. Forecasts reflect documented assumptions on carbon price trajectories and technology cost curves. Practitioners should monitor EU ETS price volatility and national coal closure announcements for early signals of retrofit investment abandonment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging Energy Technologies
Clean Coal Technologies Sales Market
Emerging Energy Technologies
Clean Technology Market
Emerging Energy Technologies
Cryogenic Technology Market
Emerging Energy Technologies
Global Microreactor Technology Market
Emerging Energy Technologies
Energy Transition Market
Emerging Energy Technologies
Decarbonization Market
Emerging Energy Technologies
Global Power-To-X Market
Emerging Energy Technologies
Multi Energy Systems Market
Emerging Energy Technologies
United States Clean Coal Technologies Market
Emerging Energy Technologies
Methanation Technology Market
Emerging Energy Technologies
Advanced Energy Market
Emerging Energy Technologies
Nanotechnology in Energy Market