
 Ceramic Transducers Market | 2026-2036
Ceramic Transducers Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Transducers Market Analysis
Japanese piezoelectric material production is shifting toward higher-purity formulations for medical-grade applications. Murata Manufacturing Co., Ltd. leverages its integrated ceramic powder-to-device pipeline to dominate consumer electronics frequency control segments. CeramTec GmbH anchors European supply for surgical ultrasound handpieces through specialized alumina and PZT formulations. PI Ceramic GmbH differentiates via custom actuator geometries for semiconductor lithography positioning systems.
Ceramic transducers convert electrical energy into mechanical vibration or acoustic signals through piezoelectric crystalline structures, typically lead zirconate titanate or barium titanate compositions fired at temperatures exceeding 1,200°C, enabling precision motion control and non-invasive diagnostic imaging. Piezoelectric devices generate the deepest margin pools due to specialized dopant recipes and tight tolerance requirements in medical and aerospace qualification paths. Ultrasonic sensors lead volume demand through automotive parking assistance and industrial proximity detection, while actuators capture premium positioning in adaptive optics and precision manufacturing where nanometer-scale repeatability commands price premiums.
FDA medical device regulations and the EU MDR framework impose biocompatibility and traceability requirements that filter out uncertified suppliers from diagnostic imaging supply chains. ISO 13485 quality management standards and REACH substance restrictions further shape material selection and cross-border market access for ceramic transducer manufacturers. Stakeholders must monitor evolving rare earth element sourcing policies and qualification timelines for next-generation lead-free piezoelectric compositions.
Market Dynamics
Medical imaging OEMs are consolidating supplier bases around vertically integrated ceramic powder-to-device manufacturers capable of delivering REACH-compliant and FDA-cleared piezoelectric arrays under single-source accountability.
Growth Catalysts
- EU MDR traceability mandates:Biocompatibility documentation requirements are filtering out uncertified suppliers and concentrating procurement among ISO 13485-qualified manufacturers serving diagnostic imaging supply chains.
- Semiconductor lithography positioning:Nanometer-scale repeatability demands in EUV scanner stages are pulling custom actuator geometries from specialized piezoelectric suppliers.
- German precision manufacturing clusters:Concentrated healthcare infrastructure investments and surgical device production anchor regional demand for alumina and PZT formulations.
Market Restraints
- Lead zirconate titanate feedstock volatility:Rare earth element sourcing policies and geopolitical friction concentrate critical dopant supply among limited national stockpiles.
- High-temperature firing energy intensity:Sintering temperatures exceeding 1,200°C impose carbon cost exposure under EU Green Deal emissions frameworks.
- Lead-free piezoelectric performance gap:Barium titanate and potassium sodium niobate alternatives exhibit inferior electromechanical coupling coefficients for high-frequency medical arrays.
Strategic Opportunities
- Japan PMDA fast-track pathways:Accelerated device approval timelines for breakthrough diagnostic technologies reward early movers in high-purity formulation development.
- Automotive ultrasonic sensor densification:Parking assistance and cabin monitoring systems are proliferating transducer nodes per vehicle platform.
- Adaptive optics convergence:Piezoelectric deformable mirrors integrating with AI-driven wavefront correction are opening precision manufacturing applications beyond traditional microscopy.
Industry Challenges
- Specialized ceramic engineering talent scarcity:Deep expertise in piezoelectric dopant recipe optimization and high-temperature process control concentrates among aging workforce cohorts in Japan and Germany.
- FDA 510(k) clearance timeline compression:Predicate device substantiation requirements for next-generation ultrasound handpieces extend qualification cycles and strain R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Transducers Market |
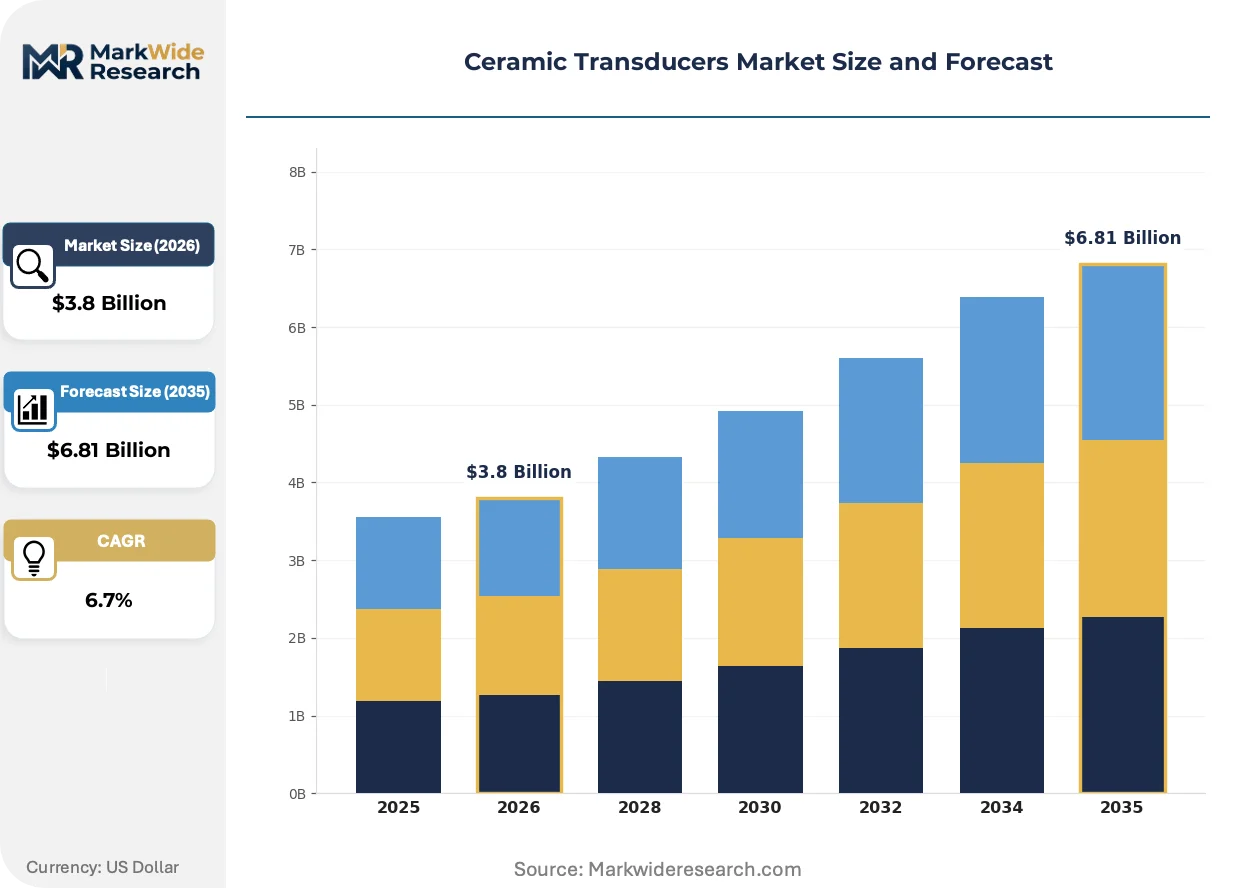
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Sensors, Actuators, Generators, Piezoelectric Devices Application: Medical Imaging, Industrial Automation, Automotive Sensors, Consumer Electronics End User: Manufacturers, Healthcare Providers, Research Institutions, Aerospace Firms Technology: Piezoelectric Effect, Electromechanical Transduction, Microfabrication, Acoustic Wave Technology |
| Companies Covered | PI Ceramic GmbH, CeramTec GmbH, Murata Manufacturing Co., Ltd., TDK Corporation, CTS Corporation, APC International, Ltd., Morgan Advanced Materials, Sparkler Ceramics Pvt. Ltd., Kistler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Transducers Market Emerging Trajectories
Piezoelectric device architectures are fragmenting into application-specific configurations as end-users reject generic component platforms in favor of purpose-built form factors.
Multi-layer ceramic capacitor-derived manufacturing techniques are transferring into piezoelectric stack production, enabling thinner active layers and higher displacement density. Medical ultrasound probe manufacturers in Japan and Germany are adopting these processes for 2D matrix array fabrication. The technology is modularizing transducer assembly from monolithic ceramic blocks into laminate sub-assemblies that permit field-replaceable active elements.
REACH substance restrictions are tightening permissible lead content thresholds in consumer and industrial piezoelectric devices ahead of full medical equipment exemptions. ECHA authorization requirements are forcing reformulation investments across European manufacturing footprints. Surgical ultrasound handpiece suppliers are responding by accelerating biocompatible coating qualification to maintain MDR compliance without sacrificing acoustic performance.
Diagnostic imaging OEMs are unbundling after-sales service contracts from hardware procurement, shifting toward performance-based maintenance agreements indexed to uptime guarantees. Independent service organizations are capturing calibration and probe replacement revenue previously retained by original equipment manufacturers. This reconfiguration is most advanced in United States hospital procurement, where GPO-negotiated multi-vendor service panels are displacing single-source captive service models.
Ceramic Transducers Market Segmentation
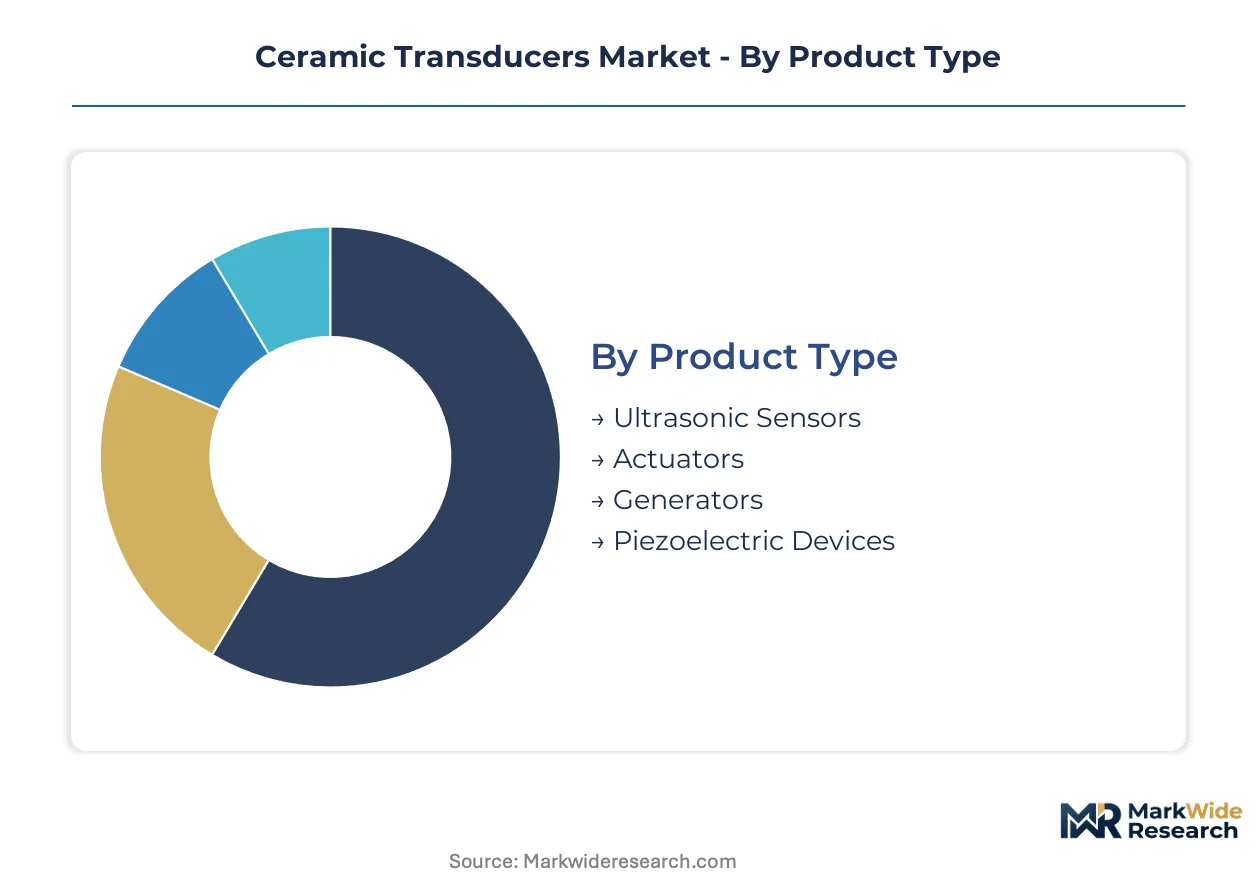
Ceramic transducers fragment into sharply differentiated product architectures where volume-scale automotive sensors coexist with precision medical arrays commanding tenfold price premiums. Application-specific qualification requirements and regional regulatory divergence prevent component standardization across end-use verticals.
Product Type:
Volume concentration sits with automotive proximity detection, while premium capture concentrates in medical-grade piezoelectric arrays requiring specialized dopant formulations.
- Piezoelectric Devices:Lead zirconate titanate and barium titanate crystalline structures fired above 1,200°C enable electromechanical energy conversion with nanometer-scale precision. Medical imaging OEMs in Germany and Japan are consolidating procurement around REACH-compliant and FDA-cleared single-source suppliers for diagnostic arrays. REACH substance restrictions and EU MDR biocompatibility mandates filter out uncertified manufacturers from this segment.
- Ultrasonic Sensors:Automotive parking assistance and industrial proximity detection systems drive unit volume through standardized transmitter-receiver configurations. German precision manufacturing clusters and Japanese automotive supply chains anchor regional demand concentration. Semiconductor lithography positioning requirements are pulling custom actuator geometries from specialized suppliers.
- Actuators:Adaptive optics and precision manufacturing applications command premium positioning where nanometer-scale repeatability justifies specialized engineering.
- Generators:High-power ultrasonic welding and cleaning equipment deploy ceramic resonators in industrial process environments.
Mature deployment sits with ultrasonic sensors. Newer deployment is concentrated in piezoelectric devices for medical-grade applications.
Application:
Medical imaging generates the deepest margin pools through specialized qualification paths, while automotive sensors lead absolute unit shipments.
- Medical Imaging:Ultrasound diagnostic equipment requires 2D matrix arrays fabricated through multi-layer ceramic techniques derived from capacitor manufacturing. Japanese probe manufacturers and German surgical device producers dominate procurement concentration. FDA 510(k) clearance timelines and EU MDR traceability mandates extend qualification cycles beyond eighteen months.
- Automotive Sensors:Parking assistance and cabin monitoring systems proliferate transducer nodes per vehicle platform. United States and German automotive OEMs specify IP-rated ultrasonic modules for bumper-integrated deployment. Densification trends are expanding sensor counts from four to twelve units per vehicle.
- Industrial Automation:Proximity detection and level sensing applications standardize around robust ceramic housings for harsh environment operation.
- Consumer Electronics:Haptic feedback and fingerprint sensing modules utilize thinner active layers for miniaturized form factors.
Revenue concentration favors medical imaging. Volume expansion is climbing fastest in automotive sensor deployment.
End User:
Healthcare providers impose the most stringent qualification requirements, while manufacturers capture scale economies through standardized procurement.
- Healthcare Providers:Hospital procurement through United States GPO-negotiated panels and German hospital networks demands ISO 13485 quality management certification. Performance-based maintenance agreements indexed to uptime guarantees are displacing single-source captive service models. Biocompatibility documentation requirements filter supplier bases aggressively.
- Manufacturers:Industrial automation and automotive OEMs consolidate supplier relationships around vertically integrated ceramic powder-to-device producers. German precision manufacturing clusters and Japanese electronics supply chains anchor regional procurement concentration. REACH compliance and material traceability shape vendor selection.
- Research Institutions:Adaptive optics and microscopy applications drive demand for custom actuator geometries with specialized displacement characteristics.
- Aerospace Firms:Vibration control and precision positioning systems require extended temperature range qualification beyond commercial specifications.
Procurement maturity sits with manufacturers. Emerging qualification complexity is concentrating in healthcare provider channels.
Technology:
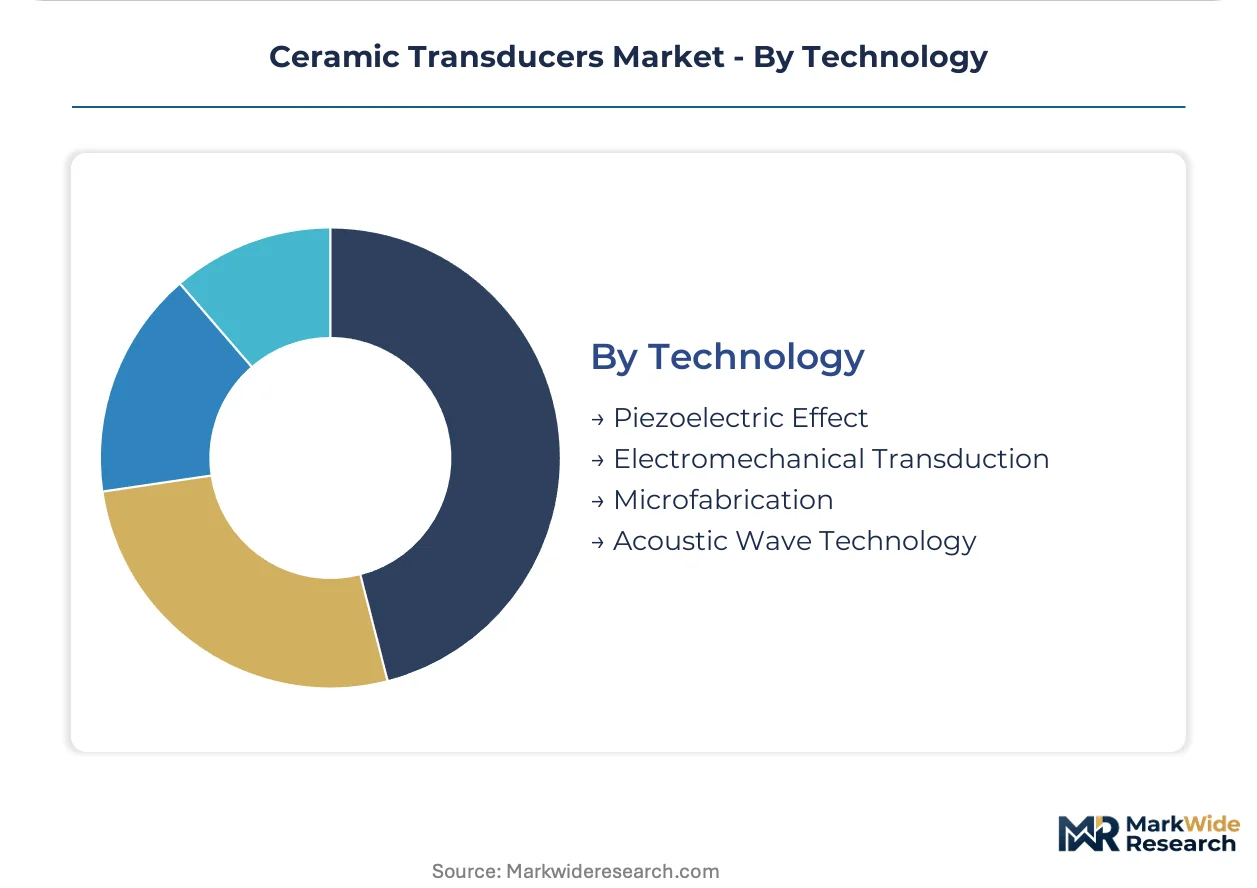
Established piezoelectric effect architectures dominate commercial deployment, while microfabrication techniques enable next-generation form factors.
- Piezoelectric Effect:Direct and converse electromechanical coupling in perovskite crystal structures enables the core energy conversion mechanism across all product categories. Lead zirconate titanate formulations retain performance advantages over lead-free alternatives for high-frequency medical arrays. Rare earth element sourcing policies concentrate critical dopant supply among limited national stockpiles.
- Microfabrication:Thin-film deposition and lithographic patterning enable miniaturized transducer arrays for consumer electronics and medical catheters. Japanese manufacturers transfer multi-layer ceramic capacitor manufacturing techniques into piezoelectric stack production. Thinner active layers and higher displacement density characterize advancing process generations.
- Electromechanical Transduction:Resonant frequency optimization and impedance matching engineering support ultrasonic generator applications.
- Acoustic Wave Technology:Surface and bulk acoustic wave devices address frequency control and filtering applications in telecommunications infrastructure.
Production scale sits with piezoelectric effect platforms. Technology transition is accelerating most quickly in microfabrication for medical miniaturization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth element deposits in China and Japan anchor feedstock supply chains for piezoelectric dopant formulations. German precision manufacturing clusters and United States healthcare infrastructure investments concentrate downstream demand for medical-grade ceramic arrays.
United States
FDA 510(k) clearance pathways for ultrasound diagnostic equipment drive procurement consolidation among ISO 13485-qualified manufacturers. Hospital procurement through GPO-negotiated multi-vendor service panels is displacing single-source captive maintenance models. Greater Boston and Minneapolis-St. Paul medical device corridors anchor surgical ultrasound handpiece production for domestic healthcare networks.
Germany
EU MDR biocompatibility traceability mandates filter uncertified suppliers from diagnostic imaging supply chains. REACH substance restrictions tighten permissible lead content thresholds ahead of full medical equipment exemptions. Baden-Württemberg and Bavaria precision manufacturing clusters anchor regional demand for alumina and PZT formulations in surgical device production.
Japan
PMDA fast-track pathways for breakthrough diagnostic technologies reward early movers in high-purity piezoelectric formulation development. METI rare earth element sourcing policies concentrate critical dopant supply among national stockpiles. Kanto and Kansai industrial corridors host integrated ceramic powder-to-device pipelines serving consumer electronics frequency control segments.
China
Domestic production of barium titanate and lead-free piezoelectric alternatives accelerates under dual carbon emissions reduction goals. MIIT industrial standards for electronic ceramic materials shape qualification requirements for domestic medical device integration. Yangtze River Delta manufacturing hubs concentrate multi-layer ceramic capacitor-derived techniques transferring into piezoelectric stack production.
South Korea
MFDS medical device approval timelines align with semiconductor lithography positioning demands for custom actuator geometries. Seoul Capital Area and Busan-Ulsan industrial corridors anchor automotive ultrasonic sensor module production for export-oriented vehicle platforms. Domestic manufacturers consolidate backward integration into ceramic powder synthesis to reduce rare earth element import dependency.
Ceramic Transducers Market Vendor Landscape
Global majors compete with regional champions across material purity and regulatory qualification dimensions. The vendor base stratifies into vertically integrated powder-to-device manufacturers, specialized actuator geometry designers, and volume-scale automotive sensor suppliers. Three archetypes dominate: integrated ceramic engineers owning high-temperature process control, precision motion specialists capturing semiconductor lithography positioning contracts, and automotive module assemblers standardizing around IP-rated transmitter-receiver configurations. Competitive moves center on M&A for REACH-compliant formulation capabilities and capacity expansion for medical-grade array production.
Among German fabricators, CeramTec GmbH and PI Ceramic GmbH exemplify the precision-engineering archetype through specialized alumina and custom actuator positioning systems. Murata Manufacturing Co., Ltd. anchors the integrated production model with captive ceramic powder synthesis through finished device assembly. These three entities represent the dominant competitive positioning vectors in medical imaging and semiconductor manufacturing applications.
| Leading Market Players |
|---|
| PI Ceramic GmbH |
| CeramTec GmbH |
| Murata Manufacturing Co., Ltd. |
| TDK Corporation |
| CTS Corporation |
| APC International, Ltd. |
| Morgan Advanced Materials |
| Sparkler Ceramics Pvt. Ltd. |
| Kistler Group |
| Others |
Supply Flow & Price Mechanics
Multi-layer ceramic capacitor manufacturing techniques migrating into piezoelectric stack production are compressing unit economics while concentrating procurement power among Japanese and German fabricators with captive powder synthesis capabilities. This process transition simultaneously reduces per-layer firing costs and raises barriers for second-tier suppliers lacking high-temperature process control expertise.
Pricing Analysis
After-sales service unbundling from hardware procurement is reshaping contract structures across medical imaging channels. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared diagnostic arrays from industrial proximity sensors and automotive parking modules. ISO 13485 certification tier and REACH compliance status drive price differentiation between qualified and uncertified suppliers. Cost compression in automotive ultrasonic modules is intensifying because German and Japanese OEMs are standardizing around IP-rated transmitter-receiver configurations. Healthcare providers show least price sensitivity due to eighteen-month qualification timelines and biocompatibility documentation requirements.
Supply Chain Analysis
Rare earth element feedstock for PZT dopant formulations rests on Chinese mining operations and Japanese national stockpiles, with German precision manufacturing clusters dependent on both sources. Critical inputs include lead zirconate titanate powders, alumina substrates, and specialized sintering furnaces capable of exceeding 1,200°C operation. Single-source vulnerability concentrates in high-purity piezoelectric ceramic formulations where METI sourcing policies and REACH authorization requirements restrict qualified supplier pools. Distribution runs through vertically integrated powder-to-device manufacturers serving medical imaging OEMs directly, with automotive sensor modules flowing through Tier 1 subsystem assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over high-temperature firing infrastructure and REACH-compliant formulation capabilities determines pricing power and qualification access.
For Market Incumbents: To counter independent service organizations capturing calibration and probe replacement revenue, medical imaging OEMs should deepen backward integration into ceramic powder synthesis and secure captive capacity for 2D matrix array production. Incumbents must also accelerate biocompatible coating qualification to maintain EU MDR compliance without sacrificing acoustic performance. For New Entrants and Emerging Players: Direct-to-device-manufacturer digital channels offer the lowest friction entry path for specialized actuator geometries targeting semiconductor lithography positioning. White-space targets include adaptive optics deformable mirrors for AI-driven wavefront correction and field-replaceable active elements for modular transducer assemblies. South Korean automotive sensor module production presents the most penetrable geography given MFDS alignment with semiconductor manufacturing demands. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated mid-cap specialists possessing captive high-temperature process control and ISO 13485 certification given EU MDR traceability mandates filtering uncertified competitors. Long-term viability over the projection horizon favors manufacturers with rare earth element sourcing agreements and lead-free formulation R&D pipelines. The signal to monitor is PMDA fast-track pathway approvals for breakthrough diagnostic technologies, which would accelerate procurement consolidation among early movers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Powder Synthesis | Captive supply of PZT formulations insulates against rare earth element sourcing volatility and REACH authorization delays. |
| Multi-Layer Ceramic Capacitor Process Transfer | Thinner active layers and higher displacement density enable 2D matrix array fabrication for next-generation ultrasound probes. |
| Biocompatible Coating Qualification Acceleration | Maintains EU MDR compliance for surgical ultrasound handpieces ahead of full lead content threshold restrictions. |
| Adaptive Optics Deformable Mirror Development | Piezoelectric positioning systems for AI-driven wavefront correction open precision manufacturing beyond traditional microscopy. |
| ISO 13485 Quality Management Certification Investment | Filters uncertified suppliers from hospital procurement through GPO-negotiated panels and German network contracts. |
Methodological Framework
Document review covered FDA 510(k) clearance databases, EU MDR biocompatibility guidance documents, METI rare earth element policy filings, and ceramic materials trade data, complemented by interviews with medical imaging OEM procurement directors, surgical device biomedical engineers, piezoelectric materials R&D leads, and hospital GPO contracts managers. Secondary validation drew from SEC filings of listed component manufacturers, Japanese industrial standards documentation, and REACH authorization registers. Bottom-up unit economics modeling and top-down market sizing triangulated across these sources.
Segment-level projections across product type, application, end user, and technology dimensions were generated through driver-linked elasticity modeling over the projection horizon. CAGRs were derived from regression against historical qualification timeline data and semiconductor lithography equipment shipment patterns. Industry-specific inputs included EUV scanner stage positioning requirements, automotive sensor node densification curves, and PMDA fast-track approval velocity.
The model holds under stable rare earth element sourcing policies and sustained REACH authorization timelines; deviation in geopolitical trade restrictions or accelerated lead-free mandate implementation would shift supplier competitive positioning. Forecasts reflect documented assumptions around high-temperature firing energy costs and medical device qualification cycle durations. A small set of triggers—PMDA breakthrough designations, ECHA substance restriction accelerations, and automotive platform sensor count specifications—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Torque Sensor Market
Sensors and Controls
Asia-Pacific Sensors Market
Sensors and Controls
Piezoelectric MEMS Resonators Market
Sensors and Controls
Global Color Detection Sensors Market
Sensors and Controls
Global Level Sensors Market
Sensors and Controls
Digital Barometer Market
Sensors and Controls
Active Sensor Market
Sensors and Controls
North America Bulk Acoustic Wave Sensors Market
Sensors and Controls
Thermometer Market
Sensors and Controls
Smart Flow Meter Market
Sensors and Controls
APAC Occupancy Sensors Market
Sensors and Controls
Battery Monitor Market
Sensors and Controls
MEMS Microphones Market
Sensors and Controls
Middle East and Africa Touch Sensor Market
Sensors and Controls
US Vibration Sensors Market
Sensors and Controls
Instrumented Load Shackle Market