
 Micro-Electro Mechanical Systems Market | 2026-2036
Micro-Electro Mechanical Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Micro-Electro Mechanical Systems Market Outlook
The divergence between automotive-grade MEMS and consumer-grade commodity sensors is repositioning procurement priorities across the supply chain. Robert Bosch GmbH leverages its captive foundry network to dominate automotive pressure sensors and inertial modules. STMicroelectronics anchors its position through deep integration with smartphone OEMs for motion sensing arrays.
Micro-Electro Mechanical Systems are micron-scale electromechanical devices fabricated through photolithography, thin-film deposition, and deep reactive-ion etching on silicon wafers, enabling mechanical sensing or actuation with integrated circuitry. Their primary purpose spans motion detection, pressure measurement, acoustic capture, and environmental monitoring across electronics, transportation, and healthcare equipment. Accelerometers and gyroscopes lead product-type revenue owing to smartphone stabilization and vehicle rollover detection, while pressure sensors in medical devices represent the fastest-expanding margin pool. Automotive systems and consumer electronics split application demand, with industrial automation emerging as the structural growth vector due to predictive maintenance instrumentation.
FDA scrutiny of implantable MEMS in the United States, REACH material restrictions in Europe, and Japan's METI subsidies for domestic semiconductor fabrication collectively shape compliance costs and market access pathways. China's GB standards and NMPA medical device rules add further certification layers for entrants targeting its electronics manufacturing base. Stakeholders must weigh regional regulatory divergence against concentrated customer clusters when siting packaging and calibration operations.
Market Dynamics
The divergence between automotive-grade reliability requirements and consumer electronics cost pressures is fragmenting foundry capacity allocation, with EU Green Deal emissions mandates accelerating sensor miniaturization timelines faster than process node migration can accommodate.
Growth Catalysts
- EU Green Deal acceleration:Tightened vehicle emissions standards in Europe are mandating expanded sensor deployment for real-time monitoring, pulling MEMS pressure and gas sensors into powertrain architectures.
- Smartphone motion sensing densification:Optical image stabilization and spatial computing headsets require six-axis inertial measurement units, expanding die area allocation for gyroscope-accelerometer combos.
- Japan METI semiconductor subsidies:Domestic fabrication incentives are reshoring 200mm MEMS foundry capacity for automotive and industrial customers seeking supply security.
Market Restraints
- 200mm silicon wafer supply concentration:Legacy MEMS processes depend on constrained 200mm substrate supply where foundry expansion lags behind 300mm logic migration.
- Platinum and palladium input volatility:Piezoelectric MEMS and certain gas sensors require noble metal electrodes exposed to commodity price swings.
- Technical limitation in hermetic sealing:Long-term drift in absolute pressure sensors limits calibration intervals for implantable medical applications.
Strategic Opportunities
- Industrial predictive maintenance instrumentation:Vibration and acoustic MEMS arrays for rotating machinery monitoring represent underpenetrated demand outside automotive and consumer verticals.
- China NMPA medical device pathway:Streamlined certification for Class II implantable sensors creates regulatory tailwind for cardiovascular pressure monitoring entrants.
- Silicon photonics convergence:Integration of MEMS tunable lenses with optical transceivers is opening data center and telecom packaging contracts.
Industry Challenges
- Specialized process engineer scarcity:Deep reactive-ion etching and sacrificial layer release expertise concentrates in Germany, Japan, and the United States, constraining foundry expansion elsewhere.
- Multi-regional certification burden:FDA 510(k) timelines, REACH material declarations, and China GB standard testing create sequential validation bottlenecks for single-SKU global products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro-Electro Mechanical Systems Market |
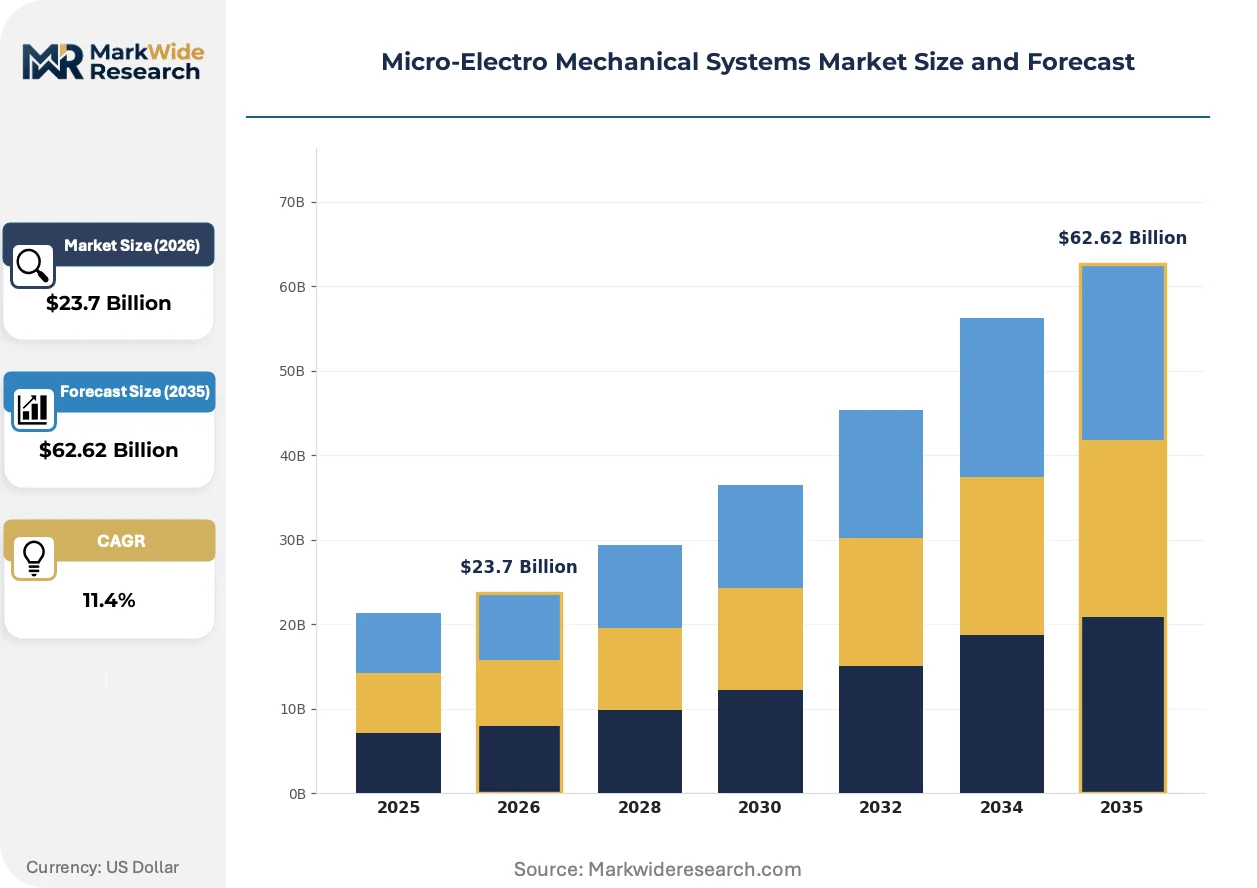
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Accelerometers, Gyroscopes, Pressure Sensors, Microphones Application: Consumer Electronics, Automotive Systems, Medical Devices, Industrial Automation Technology: Fabrication Techniques, Integration Methods, Packaging Solutions, Calibration Processes End User: Electronics Manufacturers, Automotive Companies, Healthcare Providers, Aerospace Firms |
| Companies Covered | Robert Bosch GmbH, STMicroelectronics, Broadcom, Texas Instruments Incorporated, Qorvo, TDK Corporation, Analog Devices, NXP Semiconductors, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro-Electro Mechanical Systems Market Strategic Shifts
Process integration and packaging architectures are compressing the traditional separation between MEMS wafer fabrication and application-specific signal conditioning, collapsing historical vendor boundaries.
Monolithic integration of MEMS resonators with CMOS readout circuits is consolidating timing and frequency control functions onto single-die solutions. Smartphone and wearable OEMs are adopting these integrated oscillators for space-constrained designs. This consolidation is displacing discrete quartz crystal packages and compressing the addressable market for standalone timing component suppliers.
REACH substance restrictions on lead and certain piezoelectric ceramics are forcing material substitutions in pressure sensor diaphragms and ultrasonic transducers. Industrial and automotive suppliers are qualifying aluminum nitride and scandium-doped aluminum nitride alternatives. Medical device manufacturers face the steepest requalification burden as FDA biocompatibility reviews extend timelines for implantable acoustic sensors.
Automotive Tier-1 suppliers are consolidating sensor procurement through platform-level contracts rather than discrete component sourcing. Bosch, Continental, and Denso are negotiating multi-year supply agreements covering inertial, pressure, and acoustic modules. Germany and Japan anchor this concentration, with calibration and final test operations following OEM assembly plant locations to minimize logistics liability.
Micro-Electro Mechanical Systems Market Segmentation
MEMS procurement patterns diverge sharply across product architectures and end-use reliability tiers. Automotive qualification cycles and smartphone refresh rates create fundamentally different upgrade rhythms that reshape foundry allocation and pricing structures.
Product Type:
Replacement cycles vary from annual smartphone component swaps to decade-long industrial sensor deployments, fragmenting inventory strategies and margin expectations across the supply base.
- Accelerometers:Silicon-mass spring structures detect linear acceleration across three axes with micro-g resolution. Smartphone OEMs in the United States and South Korea dominate procurement for optical image stabilization and screen orientation, with automotive rollover detection adding secondary volume through German Tier-1 suppliers.
- Gyroscopes:Vibrating structure or ring-based designs measure rotational velocity for navigation and stabilization. Six-axis inertial measurement units combining gyroscope-accelerometer pairs are displacing discrete components in spatial computing headsets from California-based developers.
- Pressure Sensors:Piezoresistive or capacitive diaphragm structures for absolute and differential measurement.
- Microphones:Capacitive MEMS acoustic transducers with integrated ASICs for signal conditioning.
Accelerometers sit at the top of the volume ranking, with pressure sensors climbing the fastest on medical implant and emissions monitoring demand.
Application:
Cost tiers separate commodity consumer-grade sensors from automotive-grade modules carrying decade-long reliability guarantees and traceability documentation.
- Consumer Electronics:High-volume, price-sensitive procurement for smartphones, wearables, and hearables. Motion sensing arrays and microphone clusters from STMicroelectronics and Knowles dominate bill-of-materials, with annual design wins hinging on millimeter-scale package dimensions.
- Automotive Systems:Safety-critical inertial modules, tire pressure monitors, and powertrain sensors requiring AEC-Q100 qualification. Robert Bosch GmbH's captive foundries supply German OEMs directly, while Japanese suppliers serve Toyota and Honda through keiretsu relationships.
- Medical Devices:Implantable pressure sensors and diagnostic acoustic probes facing FDA 510(k) and EU MDR validation timelines.
- Industrial Automation:Vibration monitoring and predictive maintenance instrumentation with extended calibration intervals.
Consumer electronics commands the highest unit volumes, while industrial automation is gaining share fastest on predictive maintenance instrumentation adoption.
Technology:
Process maturity determines which fabrication approaches can support automotive reliability without sacrificing the cost structures viable for consumer markets.
- Fabrication Techniques:Deep reactive-ion etching, wafer bonding, and sacrificial layer release define structural geometry. Bosch's AlN process and STMicroelectronics' Thelma technology anchor competing foundry platforms with divergent piezoelectric coefficient profiles.
- Integration Methods:Monolithic CMOS-MEMS integration versus heterogeneous die stacking. TSMC's specialized MEMS nodes enable single-die oscillators displacing quartz crystals in Apple and Samsung timing circuits.
- Packaging Solutions:Wafer-level chip-scale and system-in-package configurations for hermetic sealing.
- Calibration Processes:Temperature compensation and offset trimming for precision applications.
Fabrication techniques anchor the installed equipment base, with integration methods expanding most quickly on monolithic timing device demand.
End User:
Customer concentration in Germany, Japan, and the United States shapes regional foundry placement and calibration facility siting decisions.
- Electronics Manufacturers:Foxconn, Pegatron, and Luxshare assemble MEMS-rich modules for Apple and Samsung in China and Vietnam. Procurement leverage concentrates in Shenzhen and Taipei design centers where six-month product cycles demand flexible foundry relationships.
- Automotive Companies:Volkswagen, Toyota, and General Motors specify sensor performance through platform-level contracts. German KBA type approval and Japan's MLIT safety standards create divergent validation requirements that fragment global SKU strategies.
- Healthcare Providers:Hospital systems and device OEMs sourcing implantable and diagnostic sensors.
- Aerospace Firms:Satellite and avionics applications with extended qualification horizons.
Electronics manufacturers generate the highest shipment volumes, with automotive companies driving the steepest expansion trajectory on electrification and ADAS sensor densification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized process engineers for deep reactive-ion etching and sacrificial layer release concentrate in Germany, Japan, and the United States, anchoring foundry expansion decisions and calibration facility siting across the Micro-Electro Mechanical Systems supply chain.
United States
FDA scrutiny of implantable MEMS and NHTSA mandates for advanced driver-assistance systems pull pressure and inertial sensors into medical and automotive applications. The IRA semiconductor manufacturing incentives are reshoring 200mm foundry capacity for automotive and defense customers. Greater Boston and Silicon Valley host precision MEMS design clusters serving Medtronic and Apple procurement teams.
Germany
Volkswagen and BMW platform-level contracts for tire pressure monitors and powertrain sensors expand Bosch's captive foundry output. The EU Green Deal tightened emissions standards mandate real-time sensor deployment across vehicle architectures. Stuttgart and Munich anchor automotive OEM headquarters and KBA type approval laboratories that fragment global SKU strategies.
Japan
Toyota and Honda keiretsu relationships channel MEMS procurement through Denso and consolidated Tier-1 supply agreements. METI semiconductor subsidies are reshoring 200mm MEMS foundry capacity for industrial and automotive supply security. Nagoya and Tokyo host MLIT safety standard validation and deep reactive-ion etching expertise that constrains foundry expansion elsewhere.
China
Foxconn and Luxshare assembly operations in Shenzhen consume high-volume motion sensing arrays and microphone clusters for smartphone export markets. NMPA medical device rules and GB standards add certification layers for implantable sensor entrants targeting domestic healthcare demand. Yangtze River Delta fabrication parks are absorbing packaging and calibration operations to minimize logistics liability.
South Korea
Samsung and LG smartphone refresh cycles demand six-axis inertial measurement units with millimeter-scale package dimensions. MFDS medical device regulations and national semiconductor subsidies support domestic MEMS oscillator production for timing circuits. Seoul Capital Area design centers negotiate flexible foundry relationships on six-month product cycles.
Micro-Electro Mechanical Systems Market Competitive Environment
Capital-heavy producers compete with asset-light designers across a bifurcated structure where captive foundries serve automotive safety-critical demand and merchant foundries supply consumer electronics volume. The market consolidates around three strategic archetypes: vertically integrated automotive suppliers with in-house fabrication, smartphone-focused merchant foundries with CMOS integration expertise, and diversified semiconductor conglomerates with MEMS as a product line extension. Dominant competitive moves include platform-level supply agreements covering multi-sensor modules and geographic expansion of calibration facilities following OEM assembly plant locations.
Within the vertically integrated tier, Robert Bosch GmbH exemplifies the automotive-grade reliability archetype through its Stuttgart-based captive foundry network. STMicroelectronics occupies a merchant-foundry position exemplifying deep CMOS-MEMS integration for consumer electronics timing and motion sensing. Texas Instruments Incorporated sits within the diversified semiconductor conglomerate archetype, leveraging analog and mixed-signal expertise across industrial and automotive sensor portfolios.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| STMicroelectronics |
| Broadcom |
| Texas Instruments Incorporated |
| Qorvo |
| TDK Corporation |
| Analog Devices |
| NXP Semiconductors |
| Infineon Technologies |
| Others |
Value Chain & Pricing Dynamics
Deep reactive-ion etching specialists concentrated in Germany, Japan, and the United States command wage premiums that widen pricing spreads between automotive-grade modules and consumer-grade commodities. Labor-cost differentials between these precision engineering clusters and emerging packaging hubs in China and Vietnam directly feed into three-tier pricing stratification across AEC-Q100 certified, industrial-grade, and smartphone-integrated sensor tiers.
Pricing Analysis
Calibration and testing services are increasingly unbundled from die supply, with Bosch and STMicroelectronics offering tiered service levels. Price differentiation hinges on AEC-Q100 automotive certification tier and wafer-level packaging complexity, with smartphone OEMs driving the sharpest cost compression through annual design-win cycles. Pricing pressure intensifies in microphone and accelerometer commodities as Chinese packaging houses absorb calibration operations. Tier-1 automotive suppliers exhibit the lowest price sensitivity due to decade-long reliability guarantees and traceability documentation requirements.
Supply Chain Analysis
Freight costs for hermetic packaging materials and calibrated sensor modules shape regional foundry siting decisions, with calibration facilities following OEM assembly plants to minimize logistics liability. Fabrication concentrates in Germany, Japan, and the United States where process engineering expertise anchors 200mm MEMS foundry output. Raw material dependencies include platinum and palladium electrodes for piezoelectric devices, 200mm silicon wafers, and aluminum nitride thin-film substrates. Single-source vulnerability in noble metal electrode supply creates exposure to commodity price swings. Distribution runs through platform-level supply agreements negotiated by Bosch, Continental, and Denso with direct OEM integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Micro-Electro Mechanical Systems Market functions as a stable compounder anchored by automotive electrification and sensor densification mandates that ensure sustained procurement growth across economic cycles.
For Market Incumbents: Hedge against captive foundry overcapacity by qualifying merchant alternatives for consumer-grade volume, while accelerating AEC-Q200 certification investments to defend automotive margin pools from emerging Asian packaging houses. Deepen backward integration into aluminum nitride sputtering targets to offset platinum price volatility and REACH material substitution costs. For New Entrants and Emerging Players: NMPA streamlined Class II implantable pathways in China open a window for cardiovascular pressure monitoring specialists to establish clinical evidence before EU MDR and FDA 510(k) competitors consolidate. Target industrial predictive maintenance instrumentation where vibration and acoustic MEMS arrays remain underpenetrated relative to automotive and consumer verticals. Pursue co-development partnerships with rotating machinery OEMs rather than discrete component distribution. For Investors and Strategic Acquirers: Automotive Tier-1 suppliers are the most active acquirer in this space, seeking multi-sensor module capabilities and calibration facility networks. Five-to-ten-year viability rests on monolithic CMOS-MEMS integration expertise displacing discrete quartz timing devices. Monitor TSMC specialized MEMS node utilization rates as the inflection signal for merchant foundry capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Platform-Level Supply Agreement | Bosch and Denso negotiate multi-year contracts covering inertial, pressure, and acoustic modules with Volkswagen and Toyota. |
| Monolithic CMOS-MEMS Integration | TSMC's specialized nodes enable single-die oscillators displacing quartz crystals in Apple and Samsung timing circuits. |
| Calibration Facility Geographic Expansion | STMicroelectronics and TDK follow OEM assembly plants to Mexico and Eastern Europe to minimize logistics liability. |
| REACH Material Substitution Program | Aluminum nitride and scandium-doped alternatives replace lead-based piezoelectric ceramics in pressure sensor diaphragms. |
| Industrial Predictive Maintenance Partnership | Knowles and Analog Devices co-develop vibration arrays with Siemens and ABB for rotating machinery monitoring. |
Study Parameters
Bottom-up automotive and consumer electronics modeling reconciled against top-down 200mm foundry capacity tracking forms the analytical core of this study. Primary interviews with MEMS process engineers, Tier-1 supplier procurement directors, FDA regulatory affairs leads, and smartphone OEM hardware architects were validated against secondary sources including SEC 10-K filings, EU Green Deal implementation documents, METI subsidy disclosures, and NMPA medical device registration databases. Triangulation between demand-side design-win tracking and supply-side equipment utilization data ensures cross-verification of volume and value estimates.
Historical trendline analysis of automotive sensor content per vehicle and smartphone motion-sensing die area allocation informed the projection framework. Segmentation dimensions modeled include product architecture, AEC-Q100 certification tier, integration method, and regional OEM production cluster. CAGRs were derived from weighted average of foundry capacity expansion schedules and platform-level contract visibility across the analysis window. Forecast inputs incorporate EU emissions mandate timelines, Japan METI semiconductor reshoring incentives, and China NMPA Class II pathway throughput.
Revisions become necessary when 200mm silicon wafer supply constraints intensify, noble metal electrode prices spike beyond historical bands, or FDA biocompatibility review timelines extend for implantable acoustic sensors. Forecasts reflect assumptions about foundry yield improvements and automotive electrification sensor densification rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
RTD Temperature Sensors Market
Sensors and Controls
Europe Human Machine Interface Market
Sensors and Controls
MEMS Inertial Sensors Market
Sensors and Controls
APAC Acoustic Sensors Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
Piezoelectric Accelerometer Market
Sensors and Controls
HVAC Sensor Market
Sensors and Controls
Global Solid State Lidar Sensor Market
Sensors and Controls
Global Digital Temperature and Humidity Sensor Market
Sensors and Controls
Multi Touch Sensing Market
Sensors and Controls
Europe Bulk Acoustic Wave Sensors Market
Sensors and Controls
Water and Wastewater Sensors Market
Sensors and Controls
MEMS-Based Oscillator Market
Sensors and Controls
ADAS Sensors Market
Sensors and Controls
High-Precision Confocal Sensor Market
Sensors and Controls
Advanced Carbon Dioxide (CO2) Sensors Market