
 Magnetic Sensor Market | 2026-2036
Magnetic Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Sensor Market Analysis
The gap between premium magnetic sensing modules and commodity-grade components is broadening as automotive OEMs impose stricter accuracy and temperature resilience specifications on tier-one suppliers. Allegro MicroSystems dominates the automotive Hall Effect segment through captive gallium arsenide foundry partnerships that shield margin pools from silicon cycle volatility. NXP Semiconductors leverages its secure sensor portfolio to anchor design wins in electric vehicle motor control systems across European and North American platforms.
Magnetic sensors detect and measure magnetic field strength, direction, or flux density, typically operating across temperature ranges from minus forty to one hundred fifty degrees Celsius with microtesla resolution in precision applications. Hall Effect Sensors occupy the largest revenue share due to mature cost curves and automotive qualification pathways, while Magnetoresistive Sensors lead growth in industrial automation where sub-millimeter position accuracy commands premium pricing. Integrated Sensors combining signal conditioning and digital output stages are capturing margin from discrete analog architectures as system designers prioritize board-space reduction and electromagnetic compatibility compliance.
FDA oversight of magnetic sensor integration into diagnostic imaging equipment shapes product validation cycles in the United States, while REACH substance restrictions and RoHS compliance obligations in Europe constrain magnet and plating material selections across the supply base. NHTSA functional safety mandates for advanced driver assistance systems are pushing automotive suppliers toward ISO 26262-certified magnetic sensing architectures. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's embedded carbon reporting requirements recast supplier qualification criteria for rare-earth magnet sourcing.
Market Dynamics
Automotive electrification programs in Germany, Japan, and the United States are forcing tier-one suppliers to abandon analog-output architectures in favor of integrated digital sensing modules with ISO 26262 functional safety certification.
Growth Catalysts
- NHTSA ADAS mandates:Functional safety requirements for advanced driver assistance systems are accelerating OEM procurement of Hall Effect position sensors with redundant signal paths.
- Industrial automation precision demands:Sub-millimeter positioning requirements in robotic assembly lines are pulling magnetoresistive architectures into high-value factory automation deployments.
- Rare-earth magnet supply concentration:China's dominance in neodymium processing is incentivizing Western automotive OEMs to qualify alternative magnetic materials for sensor cores.
Market Restraints
- Gallium arsenide wafer cost volatility:Captive foundry capacity for high-temperature Hall Effect substrates faces pricing pressure from compound semiconductor cycle swings.
- REACH substance restrictions:European magnet plating material bans are forcing redesigns of sensor packaging to eliminate hexavalent chromium surface treatments.
- Optical encoder substitution:Photoelectric position sensing is capturing applications below fifty degrees Celsius where magnetic drift tolerance is non-critical.
Strategic Opportunities
- India automotive production:PLI scheme incentives for electric vehicle manufacturing are opening design-win opportunities for current sensing modules in motor controllers.
- EU Green Deal embedded carbon reporting:Supplier qualification criteria now favor magnetic sensor vendors with documented rare-earth recycling streams and low-carbon smelter partnerships.
- TMR-XMR convergence:Tunneling magnetoresistance and extraordinary magnetoresistance signal conditioning integration is enabling single-chip solutions for multi-axis field detection.
Industry Challenges
- ISO 26262 certification timelines:Automotive ASIL-D qualification cycles for magnetic position modules now exceed eighteen months, compressing product launch windows.
- Legacy powertrain controller integration:Analog-output sensor footprints persist in service-part pipelines, forcing dual-interface product strategies that inflate BOM complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Sensor Market |
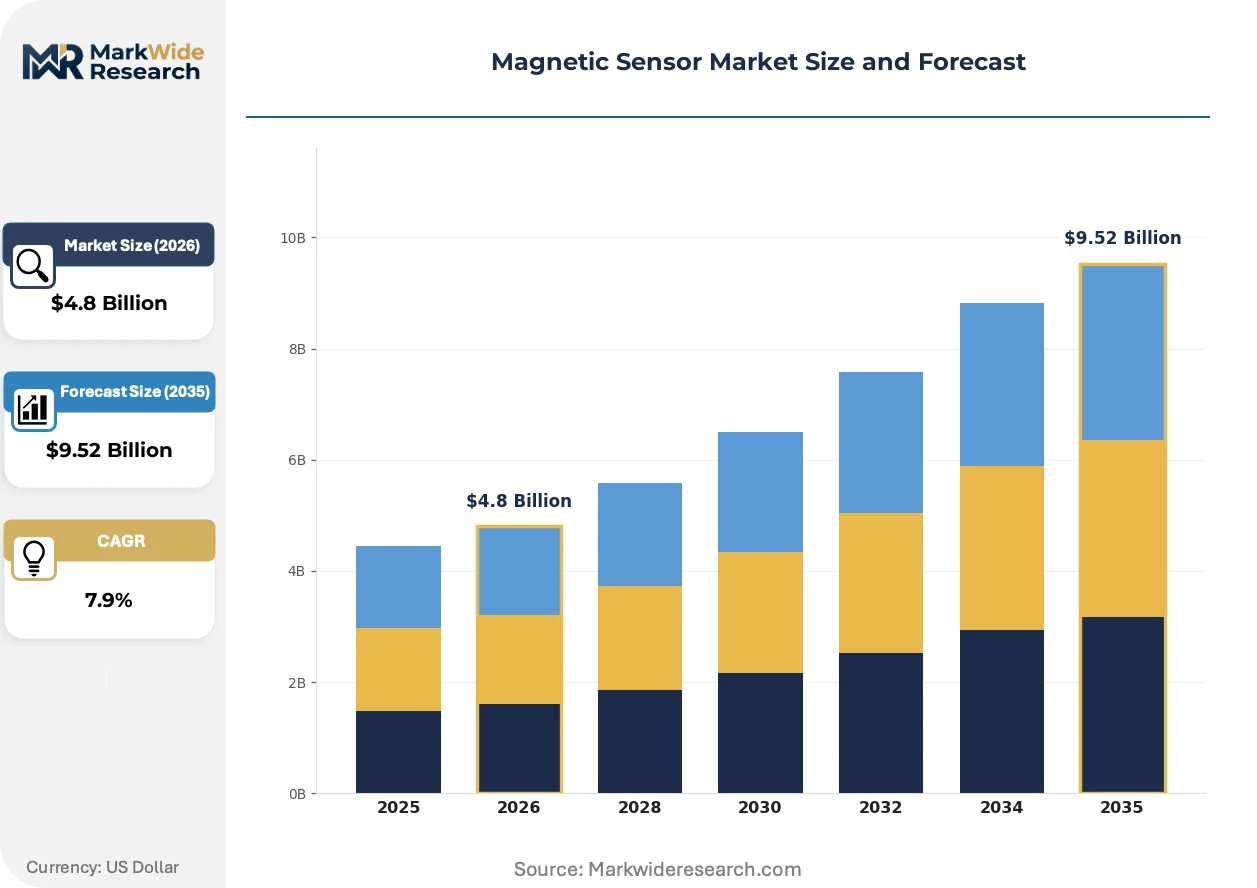
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.52 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hall Effect Sensors, Magnetoresistive Sensors, Fluxgate Sensors, Inductive Sensors Technology: Analog Sensors, Digital Sensors, Integrated Sensors, Wireless Sensors End User: Automotive Sector, Consumer Electronics, Industrial Automation, Aerospace & Defense Application: Position Sensing, Speed Detection, Current Measurement, Navigation Systems |
| Companies Covered | Asahi Kasei Microdevices Corporation, NXP Semiconductors, Allegro MicroSystems, Melexis, STMicroelectronics, Infineon Technologies AG, Honeywell International Inc., LEM International SA, TDK Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Sensor Market Emerging Trajectories
Digital integration of signal conditioning and output stages is collapsing the traditional separation between discrete magnetic sensing elements and system-level controller chips.
TMR (tunneling magnetoresistance) sensing elements are consolidating the high-precision position detection segment previously split between AMR and GMR architectures. Automotive steering-angle and motor-commutation applications in European and North American EV platforms are adopting TMR modules for their microtesla resolution and thermal stability. This consolidation is compressing the addressable market for second-tier magnetoresitive suppliers without proprietary TMR foundry access.
REACH substance restrictions and RoHS compliance obligations in Europe are constraining magnet plating chemistry and core material selections across the magnetic sensor supply base. Manufacturers must now validate alternative surface treatments and document substance declarations through the full production chain. Sensor vendors serving medical imaging and automotive safety applications face the steepest requalification burdens.
Automotive OEM procurement teams are consolidating supplier relationships around vendors offering ASIL-certified magnetic modules with integrated diagnostics. Tier-one suppliers in Germany and Japan are signing multi-year sourcing agreements that bundle position sensing, current sensing, and angle detection into single vendor portfolios. This consolidation favors integrated device manufacturers with captive foundry capacity over fabless sensor design houses.
Magnetic Sensor Market Segmentation
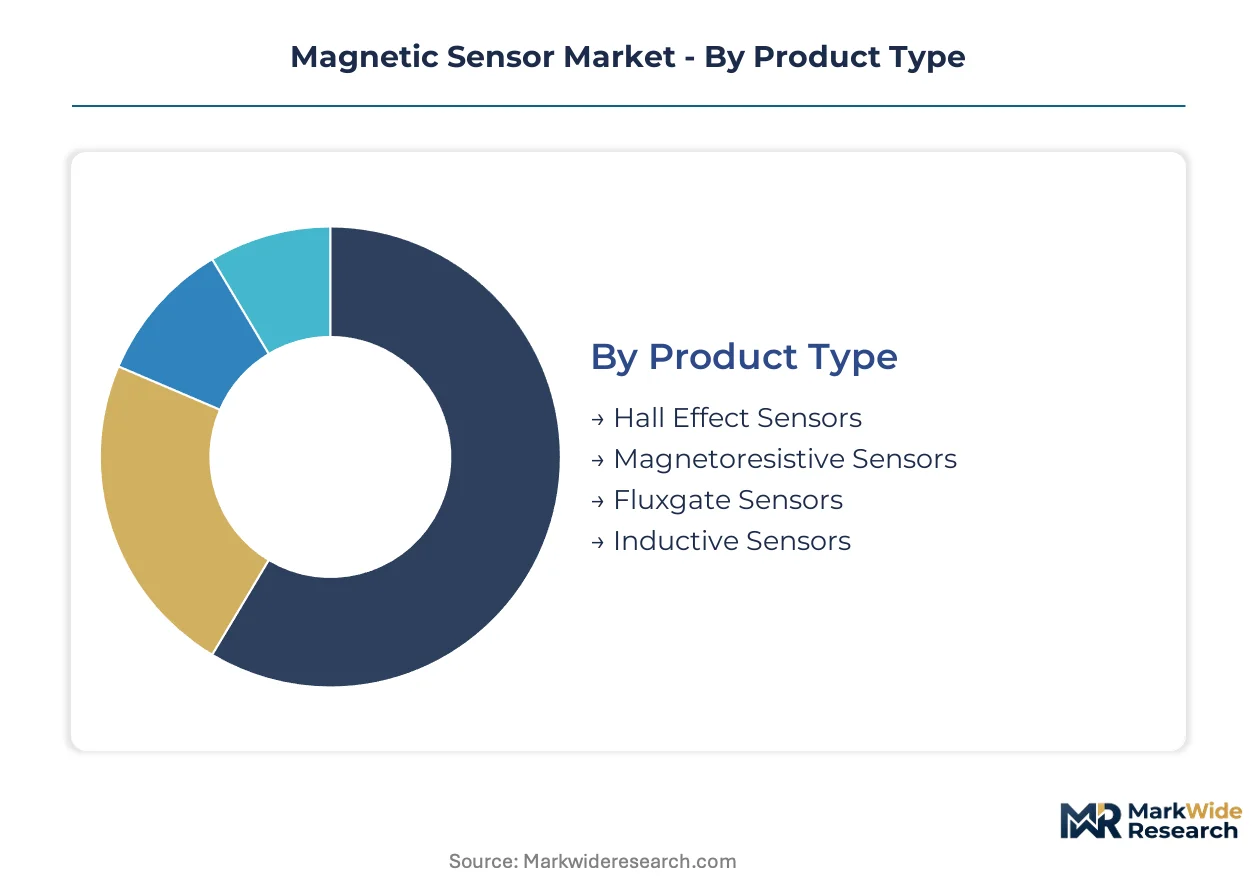
Magnetic sensor procurement splits across four orthogonal dimensions that rarely overlap cleanly in practice. Product type determines the underlying physics, technology governs the output interface, end user shapes certification requirements, and application dictates resolution and bandwidth specifications.
Product Type:
Hall Effect Sensors carry ISO 26262 ASIL-D burdens for automotive position detection, while Magnetoresistive variants face REACH substance scrutiny on nickel-iron alloy compositions. Fluxgate and Inductive architectures operate under less stringent electromagnetic compatibility frameworks but must satisfy IEC 61000-4 industrial immunity standards.
- Hall Effect Sensors:These devices exploit the Lorentz force on charge carriers in semiconductor substrates, typically gallium arsenide or silicon, generating voltage proportional to magnetic flux density. Automotive steering-angle and pedal-position modules in German and Japanese EV platforms drive procurement volumes, with NHTSA functional safety mandates forcing redundant dual-die packaging.
- Magnetoresistive Sensors:AMR, GMR, and TMR thin-film stacks detect field direction through resistance anisotropy, achieving microtesla resolution in sub-millimeter position loops. Industrial robotic assembly lines in the United States and South Korea pull these architectures where precision exceeds Hall Effect capability.
- Fluxgate Sensors:Saturable core magnetometers offer vector field measurement with drift stability suited to geological survey and military navigation applications.
- Inductive Sensors:Eddy-current and variable-reluctance designs dominate high-temperature environments above 150°C where semiconductor junctions degrade.
Leading the category by volume: Hall Effect Sensors. Growing fastest: Magnetoresistive Sensors.
Technology:
Cost tiers separate these segments sharply. Analog sensors occupy the economy tier with minimal signal conditioning, while Integrated and Wireless variants command premium positioning through embedded microcontrollers and RF front-ends.
- Analog Sensors:Raw voltage outputs require external ADC conversion and temperature compensation, preserving lowest BOM cost for legacy powertrain controllers in service-part pipelines.
- Digital Sensors:SPI and SENT protocol interfaces collapse board-space requirements and improve electromagnetic immunity in next-generation automotive domain controllers.
- Integrated Sensors:Single-package solutions combining sensing element, signal conditioning, and diagnostic logic are displacing discrete architectures as OEMs consolidate supplier relationships around ASIL-certified modules.
- Wireless Sensors:Battery-free RFID and NFC magnetic field detectors enable predictive maintenance in rotating machinery where wired connections fail.
Volume concentrates in Analog Sensors. Steepest expansion trajectory: Integrated Sensors.
End User:
Customer type determines margin structure and sales cycle length. Automotive and Aerospace & Defense segments demand 18-24 month qualification timelines, while Consumer Electronics and Industrial Automation move on 6-9 month development cycles.
- Automotive Sector:Electric vehicle motor commutation, battery current sensing, and chassis position modules consume the majority of high-precision Hall Effect and TMR production. OEM procurement teams in Germany, Japan, and the United States bundle multi-year sourcing agreements around vendors with captive foundry capacity.
- Consumer Electronics:Smartphone compass modules, laptop lid detectors, and wearable fitness trackers prioritize lowest cost and smallest footprint over absolute accuracy.
- Industrial Automation:Sub-millimeter robotic positioning, CNC machine tool feedback, and conveyor speed monitoring pull magnetoresistive architectures where repeatability commands premium pricing.
- Aerospace & Defense:Inertial navigation, weapons platform stabilization, and satellite attitude control demand radiation-hardened fluxgate and Hall Effect designs with military-qualified supply chains.
Automotive Sector leads by revenue. Industrial Automation gains share fastest.
Application:
Application maturity varies across the precision-bandwidth matrix. Position Sensing and Speed Detection are commoditized with established supply bases, while Current Measurement and Navigation Systems retain specialized vendor ecosystems.
- Position Sensing:Linear and angular position modules dominate unit shipments, spanning throttle control, valve timing, and suspension height adjustment in automotive platforms.
- Speed Detection:Crankshaft and wheel-speed sensors represent high-volume, low-margin production with intense price pressure from tier-one suppliers.
- Current Measurement:Non-contact current sensing in EV battery management systems and photovoltaic inverters requires isolated galvanic separation and wide dynamic range, favoring integrated Hall Effect modules with built-in temperature drift compensation.
- Navigation Systems:Geomagnetic heading reference and indoor positioning applications in smartphones and drones exploit three-axis magnetometer arrays fused with inertial sensors.
Position Sensing leads by unit volume. Current Measurement expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart's automotive corridor anchors European procurement of Hall Effect position modules for electric powertrains. German OEMs in this cluster are bundling multi-year sourcing agreements that span current sensing, angle detection, and chassis position applications.
Germany
Electric vehicle motor commutation and battery management systems pull high-precision TMR modules from domestic tier-one suppliers. KBA vehicle safety mandates enforce ISO 26262 ASIL-D certification on all magnetic position sensors deployed in ADAS architectures. The Baden-Württemberg cluster around Stuttgart houses captive foundry partnerships that shield margin pools from compound semiconductor cycle volatility.
United States
NHTSA functional safety requirements for advanced driver assistance systems accelerate OEM procurement of redundant Hall Effect architectures. EPA emissions regulations indirectly shape sensor specifications through powertrain electrification timelines. Michigan's automotive engineering corridor concentrates design validation facilities where ASIL-D qualification cycles now exceed eighteen months.
Japan
METI industrial policy incentives support domestic production of magnetoresistive thin-film stacks for robotic automation. JIS standards govern electromagnetic compatibility testing for factory automation deployments. The Nagoya-Toyota industrial zone anchors supply relationships between sensor vendors and precision equipment manufacturers serving sub-millimeter positioning markets.
China
Dual carbon goals recast supplier qualification criteria for rare-earth magnet sourcing in sensor cores. MIIT standards on electric vehicle safety systems mandate current sensing module redundancy in battery management architectures. The Yangtze River Delta manufacturing belt concentrates winding and assembly operations for export-oriented automotive sensor modules.
India
PLI scheme incentives for electric vehicle manufacturing open design-win opportunities for current sensing modules in motor controllers. BIS certification requirements shape electromagnetic immunity specifications for domestic automotive platforms. The Tamil Nadu industrial corridor around Chennai attracts tier-one sensor packaging operations serving Southeast Asian export markets.
Magnetic Sensor Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification grade and foundry ownership dimensions. The vendor base stratifies into three tiers: integrated device manufacturers with captive gallium arsenide capacity, fabless design houses licensing TMR intellectual property, and discrete component assemblers serving replacement part pipelines. Strategic consolidation centers on multi-year sourcing agreements that bundle position, current, and angle sensing into single vendor portfolios, alongside backward integration into rare-earth magnet recycling streams.
Within the integrated device manufacturer tier, Allegro MicroSystems and NXP Semiconductors exemplify archetypes that anchor automotive design wins through ASIL-certified module portfolios. Asahi Kasei Microdevices Corporation occupies a position among Asia-Pacific specialists leveraging thin-film magnetoresistive expertise for industrial automation precision demands. These named entities represent competitive positioning patterns rather than exhaustive market coverage, with each exemplifying distinct geographic and technological anchoring strategies visible in their corporate nomenclature and regional clustering.
| Leading Market Players |
|---|
| Asahi Kasei Microdevices Corporation |
| NXP Semiconductors |
| Allegro MicroSystems |
| Melexis |
| STMicroelectronics |
| Infineon Technologies AG |
| Honeywell International Inc. |
| LEM International SA |
| TDK Corporation |
| Others |
Supply Flow & Price Mechanics
Thin-film deposition specialists concentrated in Japan's Nagoya-Toyota industrial zone command wage premiums that widen spreads between precision magnetoresistive modules and commodity Hall Effect alternatives. Labor-cost differentials between captive gallium arsenide foundries and outsourced silicon packaging operations translate directly into three-tier pricing structures across automotive, industrial, and consumer segments.
Pricing Analysis
ASIL-D certification outcomes anchor value-based pricing for automotive position modules, with redundant signal-path architectures commanding substantial premiums over single-die alternatives. Price differentiation separates ISO 26262-certified suppliers from uncertified competitors, while volume scale and captive foundry ownership determine margin capture. Cost compression in analog-output tiers is intensifying as tier-one suppliers consolidate procurement around integrated digital modules. Consumer electronics buyers exhibit highest price sensitivity, whereas aerospace and defense procurement teams prioritize radiation-hardening and traceability over unit cost.
Supply Chain Analysis
Dual-sourcing requirements mandated by German and US automotive OEMs are forcing tier-one suppliers to qualify secondary gallium arsenide foundries beyond their primary captive capacity. Geographic supply concentration centers on Japan for magnetoresistive thin-film stacks, China for rare-earth magnet processing, and Germany for automotive module integration. Raw material dependencies include neodymium-iron-boron alloys, nickel-iron thin-film substrates, and high-purity gallium arsenide wafers. Single-source vulnerability in neodymium processing creates structural exposure to export restriction shocks. Distribution runs through tier-one automotive supplier networks and direct OEM contracts rather than open-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Magnetic Sensor Market operates as a cost-of-compliance story where ISO 26262 ASIL-D certification creates an eighteen-month barrier-to-entry moat that protects qualified incumbents from commodity competition.
For Market Incumbents: Acquire captive TMR foundry capacity to consolidate the high-precision position detection segment before AMR and GMR architectures face further displacement. Defend margin pools by backward integration into rare-earth magnet recycling streams that satisfy EU Green Deal embedded carbon reporting requirements. Optical encoder substitution in sub-fifty-degree applications represents the primary substitute threat requiring dual-interface product strategies.
For New Entrants and Emerging Players: India's PLI scheme incentives for electric vehicle manufacturing open a window for current sensing module design wins in motor controllers before domestic tier-one relationships solidify. Target the industrial automation segment in South Korea where sub-millimeter positioning demands exceed incumbent capacity. A partnership-based go-to-market angle with established winding and assembly operations in the Yangtze River Delta accelerates qualification timelines.
For Investors and Strategic Acquirers: Re-rating potential sits with fabless TMR intellectual property licensors given tunneling magnetoresistance and extraordinary magnetoresistance convergence enabling single-chip multi-axis solutions. Long-term viability over a five-to-ten year window favors vendors with documented rare-earth recycling streams and low-carbon smelter partnerships. The signal to monitor is NHTSA rulemaking on redundant sensor mandates for advanced driver assistance systems.
| Strategic Initiative | Industry Significance |
|---|---|
| TMR Foundry Capacity Acquisition | Consolidates high-precision position detection as AMR and GMR architectures face displacement. |
| Rare-Earth Recycling Stream Integration | Documents low-carbon smelter partnerships that satisfy EU Green Deal supplier qualification criteria. |
| Dual-Interface Product Architecture | Preserves legacy analog-output service-part revenue while capturing integrated digital module growth. |
| ASIL-D Certification Investment | Creates eighteen-month competitive moats against uncertified entrants in automotive safety applications. |
| India PLI Scheme Localization | Positions current sensing modules for electric vehicle motor controller design wins ahead of relationship lock-in. |
Methodological Framework
SEC 10-K filings, customs and trade data, and vehicle production databases formed the secondary backbone, supplemented by primary interviews with tier-one automotive supplier procurement teams, OEM platform engineers, Hall Effect foundry operations managers, and industrial automation system integrators. Bottom-up unit shipment estimates across Hall Effect, magnetoresistive, fluxgate, and inductive product types were cross-validated against top-down revenue triangulation from disclosed semiconductor segment reporting.
Historical trendline analysis tracked technology transitions from analog to integrated digital output stages and from AMR/GMR to TMR sensing element architectures across the projection horizon. The forecast framework modeled segmentation dimensions spanning product type, technology interface, end-user vertical, and application precision-bandwidth requirements, with CAGRs derived from regression analysis of electrification program timelines and regulatory mandate implementation schedules. Rare-earth magnet supply concentration indices and ISO 26262 certification pipeline data served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for optical encoder substitution in temperature-tolerant applications would alter the outlook. Forecasts reflect assumptions regarding NHTSA ADAS mandate implementation pacing and EU REACH substance restriction enforcement. Deviation in neodymium export policy from China would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Advanced Carbon Dioxide (CO2) Sensors Market
Sensors and Controls
MEMS Combo Sensors Market
Sensors and Controls
Europe Temperature Sensors Market
Sensors and Controls
Proximity Sensors Market
Sensors and Controls
MEMS Inertial Sensors Market
Sensors and Controls
Smart Pressure Sensors Market
Sensors and Controls
Mexico Smart Ventilation Fans Market
Sensors and Controls
Differential Pressure Sensor Market
Sensors and Controls
Gyroscope Market
Sensors and Controls
High Purity Flow Meter Market
Sensors and Controls
LAMEA Active Sensor Market
Sensors and Controls
SQUID Sensor Market
Sensors and Controls
Germany Digital Thermometer Market
Sensors and Controls
Bio-FET Market
Sensors and Controls
Industrial Sensors Market
Sensors and Controls
Photonic Sensors and Detectors Market