
 Motor Bearings Market | 2026-2036
Motor Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Motor Bearings Market Foresight
Modular bearing-assembly kits that integrate seals, lubrication reservoirs, and condition-monitoring sensors are rebalancing buyer choice away from standalone component procurement. SKF AB leverages its integrated sensor-bearing platforms to capture aftermarket service contracts across industrial machinery fleets. Schaeffler AG anchors its position through captive ceramic-material supply and in-house grinding capabilities for aerospace-grade tolerances. The Timken Company specializes in tapered-roller configurations for heavy-duty electric motors in mining and energy applications.
Motor bearings are precision-engineered mechanical components that constrain relative motion between rotating shafts and stationary housings, typically manufactured from through-hardened alloy steel or silicon-nitride ceramic with raceway surface finishes below 0.2 micrometers Ra to minimize friction and fatigue. Their primary industrial purpose is to maintain radial and axial load support while controlling vibration, thermal expansion, and energy loss in rotating equipment ranging from fractional-horsepower appliances to multi-megawatt drivetrains. Ball bearings occupy the largest volume share across electric motor applications due to standardized geometries and cost-efficient mass production, while ceramic-hybrid variants in the material category command premium positioning as thermal and electrical insulation requirements intensify in high-frequency inverter-driven motors. Roller bearings in the product type category dominate heavy-load industrial machinery and wind turbine main shafts where contact-line geometry distributes higher radial forces across extended bearing life cycles.
The US Department of Energy enforces minimum efficiency standards for integral horsepower motors under 10 CFR 431, directly tightening tolerances on bearing friction coefficients and seal drag losses that manufacturers must certify. The EU Ecodesign Directive and REACH chemical restrictions from ECHA jointly constrain lubricant formulations and surface treatment chemistries available to bearing producers serving European industrial and automotive OEMs. China's GB standards for motor efficiency and the MIIT catalog of energy-saving equipment create compliance thresholds that filter market access for imported bearing assemblies. Stakeholders must monitor how regional efficiency mandates diverge in stringency and test methodology, as compliance fragmentation will determine which product architectures warrant platform investment versus localized adaptation.
Market Dynamics
The motor bearings market is undergoing structural recalibration as electric drivetrain architectures impose thermal and rotational speed demands that exceed conventional steel-bearing capabilities. This force is compressing product lifecycles and forcing material transitions across industrial and automotive supply chains.
Growth Catalysts
- Ceramic-hybrid material adoption:Silicon-nitride rolling elements tolerate inverter-induced electrical discharge and thermal spikes in high-frequency motor applications.
- EU F-Gas Regulation:Industrial decarbonization mandates in Germany and France are accelerating replacement of standard motors with energy-efficient designs requiring precision bearing systems.
- China's wind turbine buildout:Domestic turbine installations are driving volume requirements for main-shaft roller bearings and generator ball bearings alike.
Market Restraints
- Raw material concentration:High-purity silicon-nitride powder supply concentrates among Japanese and German specialty ceramic producers.
- REACH chemical restrictions:ECHA constraints on chromium surface treatments and certain lubricant additives limit formulation flexibility for European-market bearings.
- Technical substitution ceiling:Magnetic levitation bearings threaten ultra-high-speed applications above 30,000 RPM where ceramic hybrids currently dominate.
Strategic Opportunities
- India's motor efficiency upgrade cycle:BIS implementation of IE3 and IE4 efficiency standards creates replacement demand for low-friction bearing configurations.
- Condition-monitoring convergence:Integration of vibration and temperature sensors into bearing housings is automating predictive maintenance contracts.
- US Inflation Reduction Act:Domestic content incentives for clean energy manufacturing are reshoring bearing procurement for wind and EV supply chains.
Industry Challenges
- Precision grinding workforce scarcity:Aerospace-grade tolerance finishing requires skilled technicians that bearing producers struggle to recruit.
- Multi-certification burden:Divergent efficiency test methodologies between DOE 10 CFR 431, EU Ecodesign, and China's GB standards force redundant validation cycles.
- Legacy system integration friction:Smart bearing retrofits into installed industrial motor bases face mechanical incompatibility and data protocol mismatches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motor Bearings Market |
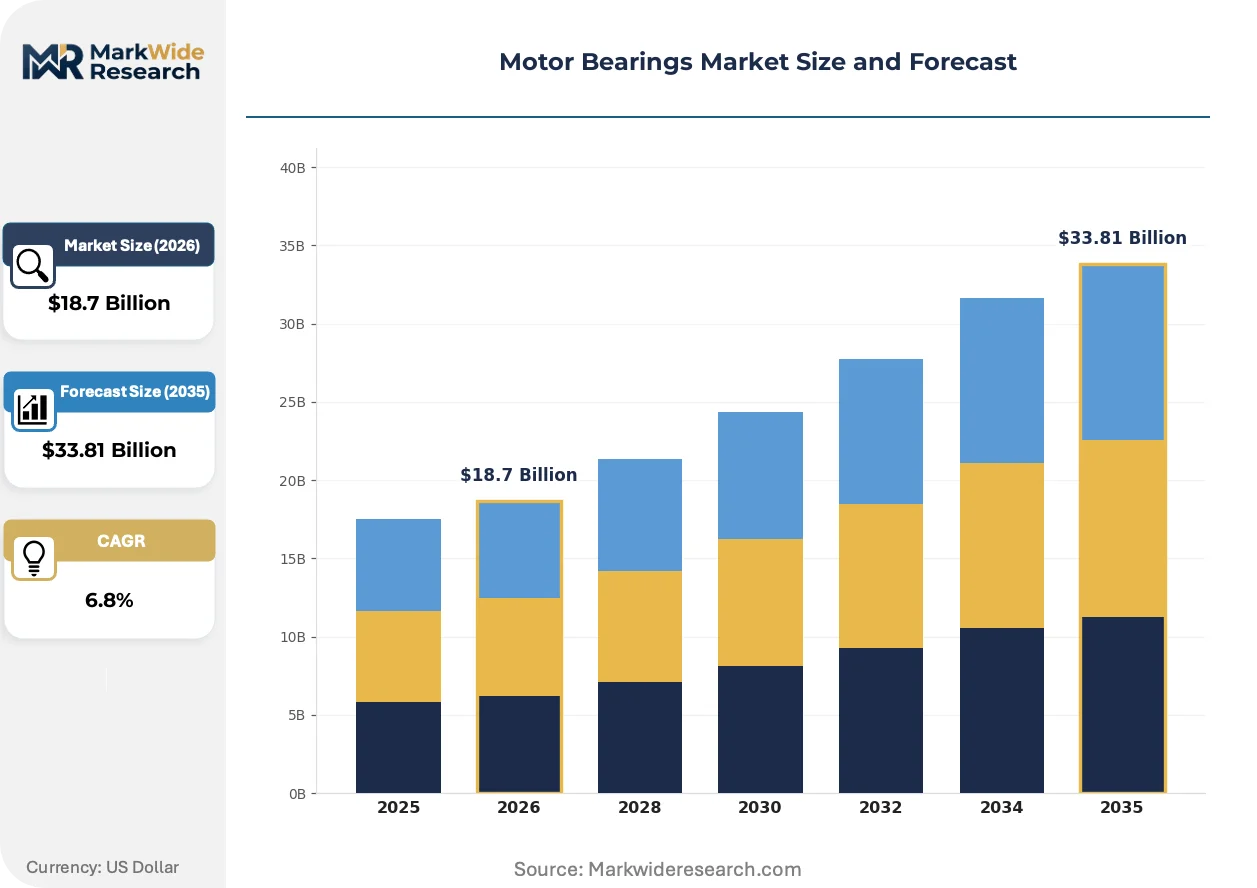
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Bearings, Roller Bearings, Thrust Bearings, Needle Bearings Material: Steel, Stainless Steel, Ceramic, Bronze End User: Automotive, Aerospace, Industrial Machinery, HVAC Application: Electric Motors, Pumps, Compressors, Fans |
| Companies Covered | SKF AB, Schaeffler AG, The Timken Company, NSK Ltd., NTN Corporation, JTEKT Corporation, Nachi-Fujikoshi Corporation, MinebeaMitsumi Inc., NRB Bearings Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motor Bearings Market Shifts & Advancements
Digitalization of rotating equipment is compressing maintenance cycles and redefining how bearing value is captured across industrial asset fleets. Three convergent developments are restructuring competitive positioning.
Integrated sensor-bearing platforms are embedding accelerometers and thermocouples directly into bearing outer rings. Mining and energy operators are adopting these configurations fastest, replacing periodic manual inspection with continuous telemetry streams. This hardware convergence is automating condition-based maintenance scheduling and shifting revenue from component sales to subscription diagnostics.
The EU F-Gas Regulation and REACH chemical restrictions are jointly constraining lubricant formulation space. Bearing producers serving European OEMs must now qualify synthetic base stocks and additive packages that satisfy both environmental compliance and operating life requirements. Industrial motor manufacturers in Germany are responding by pre-specifying approved lubricant chemistries in procurement contracts.
Buyer consolidation among wind turbine OEMs and EV powertrain integrators is compressing supplier qualification timelines. Tier-one manufacturers are unbundling after-sales service from original equipment procurement, creating separate contract streams for bearing replacement and refurbishment. This procurement bifurcation is most visible in China, where domestic turbine producers now separate main-shaft bearing supply agreements from 20-year service and remanufacturing pacts.
Motor Bearings Market Segmentation
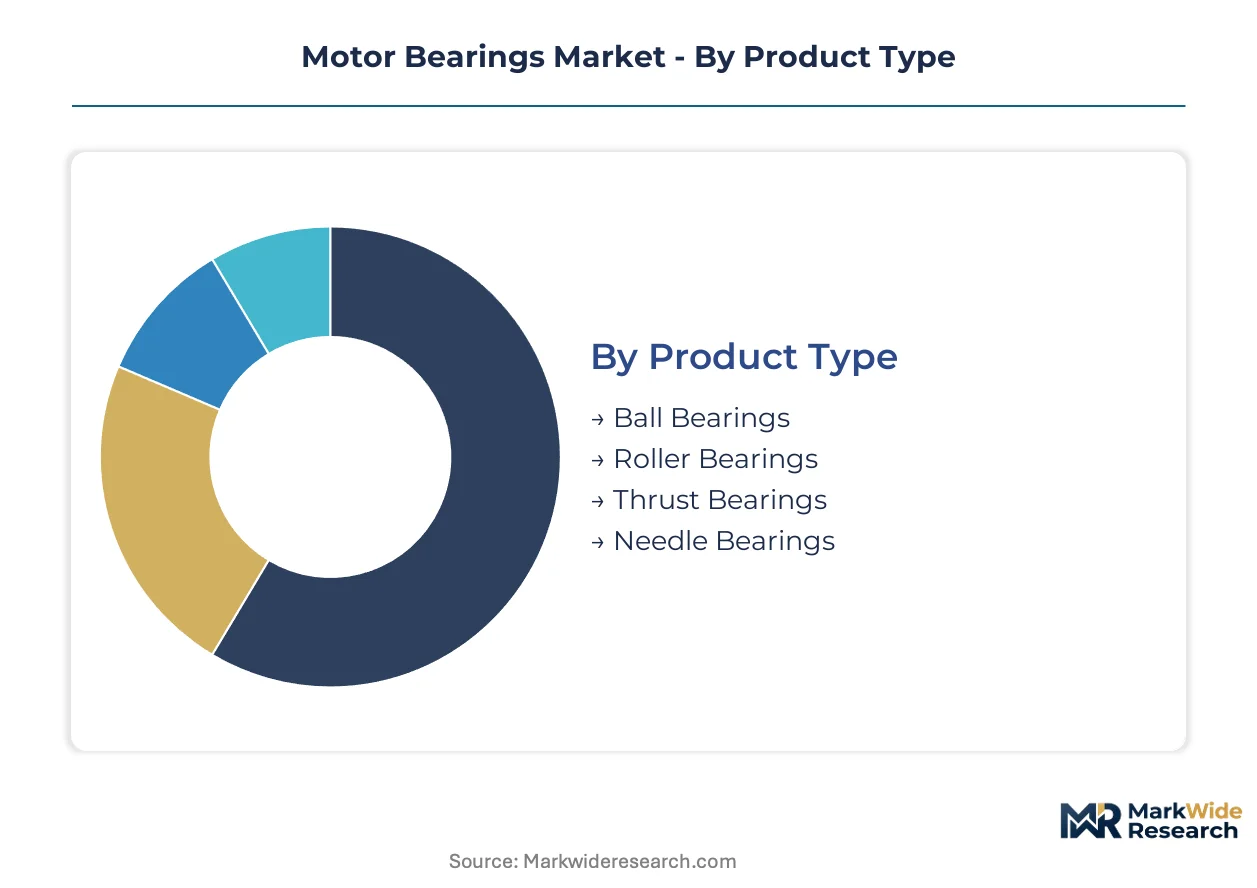
Motor bearing segmentation reveals how material science, load geometry, and end-use thermal requirements fragment procurement patterns. Buyers optimize across friction coefficients, electrical insulation properties, and maintenance cycle economics.
Product Type:
Supply concentration in precision grinding capacity favors producers with in-house finishing operations for high-volume geometries.
- Ball Bearings:Deep-groove and angular-contact configurations dominate fractional-horsepower to 500kW electric motors. Demand clusters in China's domestic motor production and German industrial automation where standardized geometries enable cost-efficient mass procurement.
- Roller Bearings:Cylindrical and tapered designs distribute radial loads across extended contact lines for heavy machinery. Wind turbine main shafts in China and mining equipment in Australia specify these for 100,000-hour life cycles under variable thrust loading.
- Thrust Bearings:Axial-load specialization serves vertical pump configurations and gearbox pinion supports.
- Needle Bearings:Compact radial designs fit constrained envelope spaces in automotive auxiliary motors and aerospace actuators.
Today's leader: Ball Bearings. Tomorrow's challenger: Roller Bearings.
Material:
Cost tier stratification separates commodity steel from performance ceramics with 3-5x unit economics.
- Steel:Through-hardened chrome and alloy grades remain the volume baseline for standard-efficiency motors. REACH restrictions on surface treatment chemistries constrain European producers qualifying hexavalent-chromium-free alternatives.
- Ceramic:Silicon-nitride rolling elements insulate against electrical discharge damage in inverter-driven motors. EV powertrain manufacturers in Germany and Japan specify hybrids for rotational speeds exceeding 15,000 RPM where thermal management fails steel.
- Stainless Steel:Corrosion resistance serves food-processing and marine applications with washdown requirements.
- Bronze:Self-lubricating properties suit boundary-condition operation where oil film breakdown risks seizure.
Steel commands present volume. Ceramic climbs the fastest on electrification torque.
End User:
Customer type fragmentation splits procurement between OEM specification power and aftermarket replacement velocity.
- Automotive:Tier-one powertrain integrators consolidate bearing qualification to 3-4 approved suppliers per platform. China's NEV production and Germany's premium drivetrain exports drive ceramic-hybrid specification for 800V architectures.
- Industrial Machinery:Discrete manufacturing and process industries balance first-cost against energy loss calculations. Mining operators in Australia and cement producers in India prioritize sealed-for-life configurations that eliminate relubrication labor.
- Aerospace:AS9100 certification and lot-traceability requirements filter supplier participation to specialty producers.
- HVAC:Compressor and fan motor replacement cycles generate steady aftermarket demand for standardized sizes.
Industrial Machinery anchors replacement revenue. Automotive captures specification premiums.
Application:
Maturity differentiation separates established motor categories from emerging thermal management challenges.
- Electric Motors:Efficiency mandates under DOE 10 CFR 431 and EU Ecodesign tighten allowable friction losses. IE4 and IE5 motor designs in Germany and China specify hybrid ceramic or special lubricant formulations to hit loss reduction targets.
- Pumps:Submersible and process pump configurations demand corrosion-resistant sealing systems.
- Compressors:Refrigeration duty cycles stress lubricant film stability under F-Gas phasedown refrigerant transitions.
- Fans:HVAC and industrial ventilation applications prioritize low-noise cage designs for occupational exposure compliance.
Electric Motors absorb R&D investment. Compressors face refrigerant chemistry recalibration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The motor bearings industry traces its modern scale to German industrial machinery clusters and Japanese automotive supply chains that standardized precision grinding techniques in the mid-20th century. Today, manufacturing concentrates in economies with integrated steel-ceramic supply bases and captive end-use demand from electrification transitions.
China
Domestic electric motor production and wind turbine installations drive volume requirements for both standard ball bearings and specialized main-shaft roller configurations. MIIT catalog listings for energy-saving equipment filter market access for imported bearing assemblies. The Yangtze River Delta hosts precision grinding operations serving NEV powertrain integrators.
Germany
Industrial decarbonization mandates accelerate replacement of standard motors with energy-efficient designs requiring precision bearing systems. The EU F-Gas Regulation tightens tolerances on friction coefficients that manufacturers must certify. Bavaria anchors captive ceramic-material supply chains for aerospace-grade tolerance finishing.
United States
The Inflation Reduction Act's domestic content incentives reshore bearing procurement for wind and EV supply chains. DOE 10 CFR 431 enforces minimum efficiency standards that tighten allowable seal drag losses. Texas and the Midwest industrial corridor concentrate heavy-duty electric motor manufacturing for mining applications.
Japan
Silicon-nitride powder supply concentrates among specialty ceramic producers serving high-frequency inverter-driven motor specifications. METI efficiency guidelines and JIS standards constrain lubricant formulation space for industrial OEMs. The Nagoya-Tokyo corridor hosts integrated sensor-bearing platform development.
India
BIS implementation of IE3 and IE4 efficiency standards creates replacement demand for low-friction bearing configurations in industrial machinery. Cement producers and mining operators prioritize sealed-for-life configurations that eliminate relubrication labor. Gujarat and Maharashtra clusters absorb capacity expansion for automotive auxiliary motor supply.
Motor Bearings Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material-grade and certification-tier segmentation. The vendor base concentrates among integrated producers with in-house grinding capabilities and captive ceramic supply, while specialized regional fabricators fill standardized geometries. Three archetypes dominate: sensor-integrated platform specialists, ceramic-hybrid material leaders, and heavy-load roller configuration experts. Competitive moves center on backward integration into silicon-nitride supply and predictive maintenance service contract capture.
Within the integrated platform tier, SKF AB and Schaeffler AG exemplify European producers leveraging sensor-bearing convergence for aftermarket service retention. The Timken Company anchors North American positioning through tapered-roller specialization. Japanese fabricators including NSK Ltd. and NTN Corporation occupy positions spanning automotive qualification and industrial machinery supply. NRB Bearings Ltd. represents Indian regional scale serving cost-optimized motor replacement cycles.
| Leading Market Players |
|---|
| SKF AB |
| Schaeffler AG |
| The Timken Company |
| NSK Ltd. |
| NTN Corporation |
| JTEKT Corporation |
| Nachi-Fujikoshi Corporation |
| MinebeaMitsumi Inc. |
| NRB Bearings Ltd. |
| Others |
Supply & Pricing Matrix
The EU F-Gas Regulation gates qualified supply and premium-tier pricing access by mandating energy-efficient motor designs that only certified bearing configurations can satisfy. Buyers in Germany and France now face bifurcated procurement: standard steel bearings compete on unit cost while ceramic-hybrid assemblies command 3-5x multiples through guaranteed efficiency compliance.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the motor bearings market by certification grade and material composition. Price differentiation stems from ISO/AS9100 certification tier and captive ceramic supply, with premium hybrids capturing efficiency-mandate premiums in German automotive supply chains. Cost compression in standard steel tiers is intensifying because Chinese domestic producers are expanding grinding capacity. Industrial machinery OEMs exhibit highest price sensitivity, while aerospace integrators prioritize lot-traceability over unit economics.
Supply Chain Analysis
Silicon-nitride powder supply rests on Japanese and German specialty ceramic producers, creating upstream concentration for high-performance bearing tiers. High-purity ceramic feedstock, through-hardened alloy steel billets, and precision grinding equipment anchor the input base. Single-source vulnerability in aerospace-grade tolerance finishing exposes lead times to skilled technician scarcity. Distribution runs through authorized industrial distributors and direct OEM qualification programs, with aftermarket service contracts increasingly unbundled from original equipment procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The motor bearings market functions as a geographic-arbitrage play where India's IE3/IE4 efficiency upgrade cycle offers cost-advantaged manufacturing access against European regulatory compliance premiums. This divergence creates positioning opportunities across three stakeholder archetypes.
For Market Incumbents: To counter magnetic levitation substitution above 30,000 RPM, SKF and Schaeffler should deepen sensor-bearing platform integration and secure 20-year service contracts with Chinese wind turbine OEMs. Backward integration into silicon-nitride supply insulates margin pressure from Japanese ceramic producers.
For New Entrants and Emerging Players: Capture India's sealed-for-life bearing replacement cycle in cement and mining applications where relubrication labor costs dominate total ownership economics. Target BIS-certified configurations for IE3 motor retrofits, leveraging Gujarat manufacturing clusters for cost positioning against European imports.
For Investors and Strategic Acquirers: Roll-up economics work for regional precision grinding specialists because aerospace-grade tolerance certification creates defensible moats against commodity competition. Watch ceramic-hybrid penetration rates in 800V EV architectures as the inflection signal for material-transition velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon-Nitride Supply | Captive ceramic feedstock insulates margin pressure from Japanese and German specialty producers. |
| Sensor-Bearing Platform Integration | SKF's embedded accelerometer configurations automate predictive maintenance subscription revenue streams. |
| India IE3/IE4 Certification Investment | BIS compliance unlocks replacement demand from cement and mining operators eliminating relubrication labor. |
| Wind Turbine Service Contract Unbundling | Chinese OEMs now separate main-shaft supply from 20-year remanufacturing pacts, creating dual revenue streams. |
| Aerospace AS9100 Qualification Expansion | Lot-traceability requirements filter supplier participation to specialty producers with captive grinding capacity. |
Research Methodology
Bottom-up electric motor and wind turbine modeling reconciled against top-down bearing production tracking forms the analytical core of this study. Primary interviews with maintenance directors at mining operations, OEM procurement teams at German automotive Tier 1s, aftermarket service heads, and plant engineers at Indian cement producers combined with secondary validation from customs/trade data, MIIT energy-saving equipment catalogs, SEC 10-K filings, and ECHA REACH restriction updates. This dual approach triangulates volume estimates against disclosed capacity expansions and qualification timelines.
Historical trendline analysis of ceramic-hybrid adoption rates and efficiency-mandate compliance costs informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, material grade, end-user industry, application thermal requirements, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to disclosed OEM procurement volumes and MIIT catalog installation targets. Forecast inputs incorporated silicon-nitride supply constraints and precision grinding workforce availability by geography.
Raw material price volatility, regulatory timeline acceleration, and magnetic levitation technology maturation are the dominant revision risks to the outlook. Forecasts reflect documented assumptions about efficiency standard implementation schedules and EV platform architecture decisions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Hinges Market
Automotive Parts
Canada Automotive Parts Zinc Die Casting Market
Automotive Parts
Global Automotive Gasket and Seal Market
Automotive Parts
South Korea Passenger Vehicles Lubricants Market
Automotive Parts
Sintered Silencer Market
Automotive Parts
Automotive Oil Pans Market
Automotive Parts
North America Automotive Parts Magnesium Die Casting Market
Automotive Parts
Global EV Speed Reducer Market
Automotive Parts
Automotive Parts Aluminum Die Casting Market
Automotive Parts
India Electric Hydraulic Power Steering Market
Automotive Parts
Automotive Rear Spoiler Market
Automotive Parts
India Brake Pads Market
Automotive Parts
Europe Industrial Roller Chain Drive Market
Automotive Parts
Oil Filter Market
Automotive Parts
Automotive Brake Caliper Market
Automotive Parts
Indonesia Automotive Lubricants Market