
 Automotive Winches System (AWS) Market | 2026-2036
Automotive Winches System (AWS) Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Winches System (AWS) Market Outlook
A capital-intensity divergence between integrated manufacturers and assembly-dependent competitors is bifurcating the Automotive Winches System landscape. Warn Industries leverages captive motor production and in-house metallurgy to command premium positioning in electric winch categories. Superwinch sustains cost competitiveness through modular platform architectures that span multiple vehicle fitments. Ingersoll Rand anchors industrial-grade hydraulic portfolios with distribution networks penetrating mining and construction procurement channels.
Automotive Winches Systems encompass motorized or manually operated drum mechanisms engineered to generate pulling forces typically ranging from 2,000 to 18,000 pounds, utilizing steel cable or synthetic rope wound around a rotating cylinder driven by electric, hydraulic, pneumatic, or hand-crank power sources. These systems serve primary functions in vehicle self-recovery, cargo handling, and terrain traversal assistance across commercial, recreational, and military contexts. Electric winches dominate consumer-facing revenue pools due to simpler installation protocols and compatibility with standard 12-volt automotive electrical architectures. Hydraulic winches retain structural importance in heavy-duty industrial and military applications where sustained load duty cycles exceed electric motor thermal tolerances. Off-road vehicle application demand exhibits the steepest trajectory as OEMs integrate winch-ready bumpers and elevated electrical capacity into factory platforms.
FCC electromagnetic emission standards govern electric winch motor controllers marketed in the United States, while EPA regulations constrain hydraulic fluid formulations and leak containment protocols across domestic supply chains. NHTSA vehicle modification guidelines influence aftermarket installation compliance, particularly for bumper-integrated systems affecting crashworthiness. Military procurement through Defense Federal Acquisition Regulation Supplement frameworks imposes additional testing regimes on suppliers targeting tactical vehicle programs. Stakeholders must monitor evolving interoperability standards between winch controllers and vehicle CAN bus architectures as electrified powertrains proliferate.
Market Dynamics
Vehicle electrification is reshaping powertrain architectures and forcing winch manufacturers to redesign motor controllers for compatibility with high-voltage electrical systems and regenerative braking protocols.
Growth Catalysts
- Adventure tourism expansion:Off-road recreation participation is climbing across the United States, Australia, and South Africa, driving aftermarket winch installations on modified SUVs and pickup trucks.
- NHTSA bumper modification guidelines:Updated federal vehicle modification standards are mandating crash-tested winch mounting systems, creating certified product demand from compliant suppliers.
- Synthetic rope substitution:Ultra-high-molecular-weight polyethylene fiber is replacing steel cable in consumer segments due to weight reduction and handling safety improvements.
Market Restraints
- Copper and rare-earth magnet cost volatility:Electric winch motor production faces input price instability from concentrated Chinese rare-earth processing and Chilean copper supply fluctuations.
- Hydraulic fluid EPA constraints:Biodegradable hydraulic fluid formulations required under EPA spill prevention rules increase material costs for industrial winch operators.
- Thermal limitation of compact motors:Sustained duty-cycle applications in mining and military contexts exceed electric motor heat dissipation capacity, preserving hydraulic system lock-in.
Strategic Opportunities
- India commercial vehicle retrofit:Underpenetrated tractor and heavy truck segments present white-space demand for locally manufactured electric winch systems.
- EU Green Deal procurement incentives:Public sector vehicle fleet electrification programs in Germany and France are creating specification windows for low-emission recovery equipment.
- CAN bus integration protocols:Convergence between winch motor controllers and vehicle diagnostic networks enables predictive maintenance service offerings.
Industry Challenges
- Electromagnetic compatibility certification:FCC Part 15 testing timelines for electric winch motor controllers extend product launch cycles by four to six months.
- High-voltage technician shortage:Installation and service of electrified winch systems on hybrid and battery-electric vehicles requires scarce skilled labor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Winches System (AWS) Market |
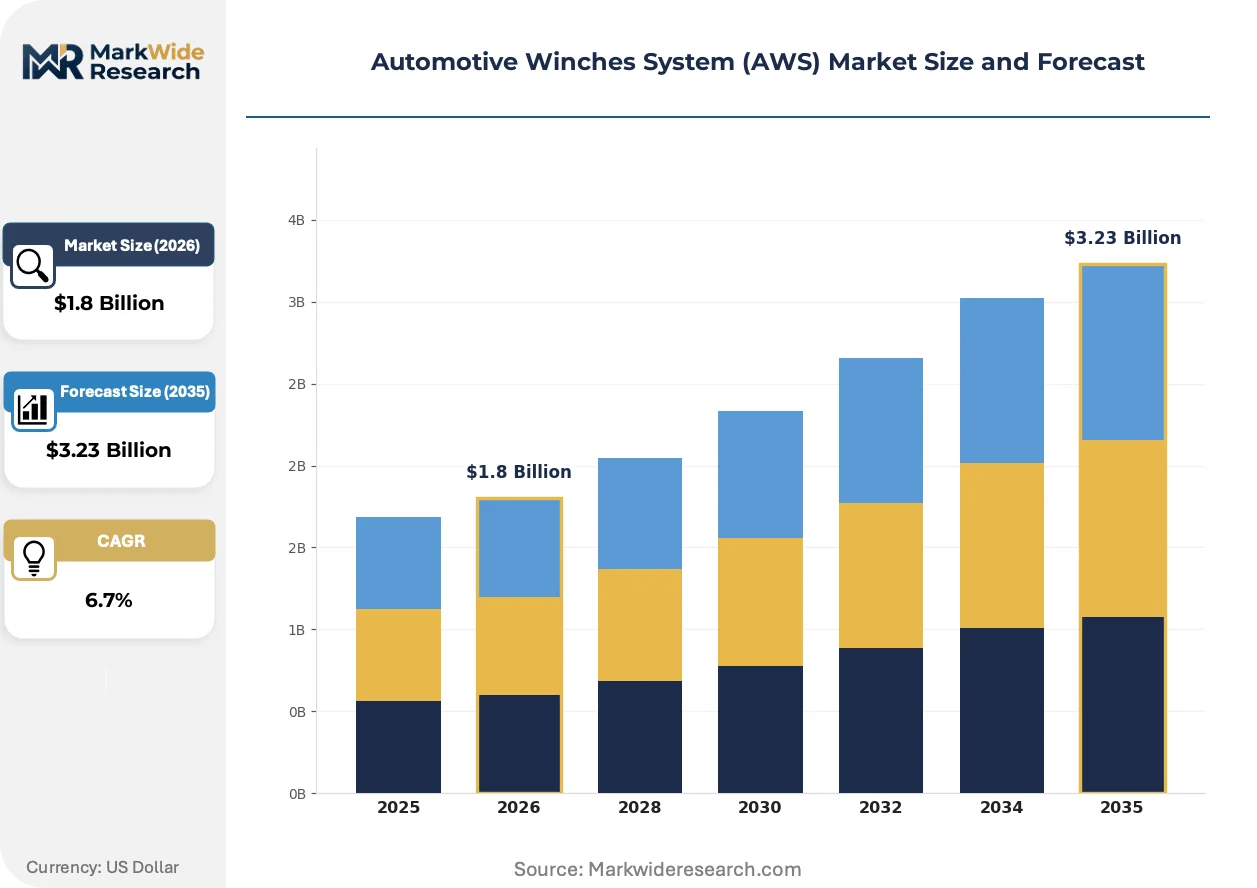
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Winches, Hydraulic Winches, Pneumatic Winches, Manual Winches Application: Off-Road Vehicles, Recovery Operations, Marine Applications, Industrial Use Installation Type: Static Mounting, Portable Setup, Integrated System, Aftermarket Installation End User: Fleet Operators, Recreational Users, Construction Companies, Military |
| Companies Covered | Superwinch, Ingersoll Rand, Warn Industries, Westin Automotive Products, ARB Corporation, Ramsey Winch, TJM Products, Mile Marker Industries, Smittybilt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Winches System (AWS) Market Strategic Shifts
Winch system architecture is pivoting toward intelligent motor control and connected diagnostics, with manufacturers embedding sensors and wireless monitoring to differentiate beyond raw pulling capacity.
Synthetic rope constructed from Dyneema fiber is displacing traditional steel cable in recreational and light-commercial applications. Weekend off-road enthusiasts and overland tour operators are adopting synthetic lines at accelerating rates due to reduced weight and elimination of whiplash hazards. This material transition is compressing steel cable demand in consumer-facing revenue pools while elevating drum surface engineering requirements.
REACH substance restrictions on chromium(VI) plating are forcing European winch manufacturers to convert to trivalent chrome or ceramic coating alternatives for corrosion protection. The industrial consequence extends to supply chain requalification and surface treatment vendor consolidation. German and Italian winch assemblers are responding fastest, with several achieving full conversion ahead of regulatory deadlines.
Direct-to-consumer online channels are capturing growing share from traditional off-road specialty retailers. Amazon and manufacturer-direct storefronts are disrupting brick-and-motor distribution, particularly for replacement parts and accessory bundles. This pattern is most pronounced in the United States and Australia, where established e-commerce infrastructure supports technical product purchases without physical inspection.
Automotive Winches System (AWS) Market Segmentation
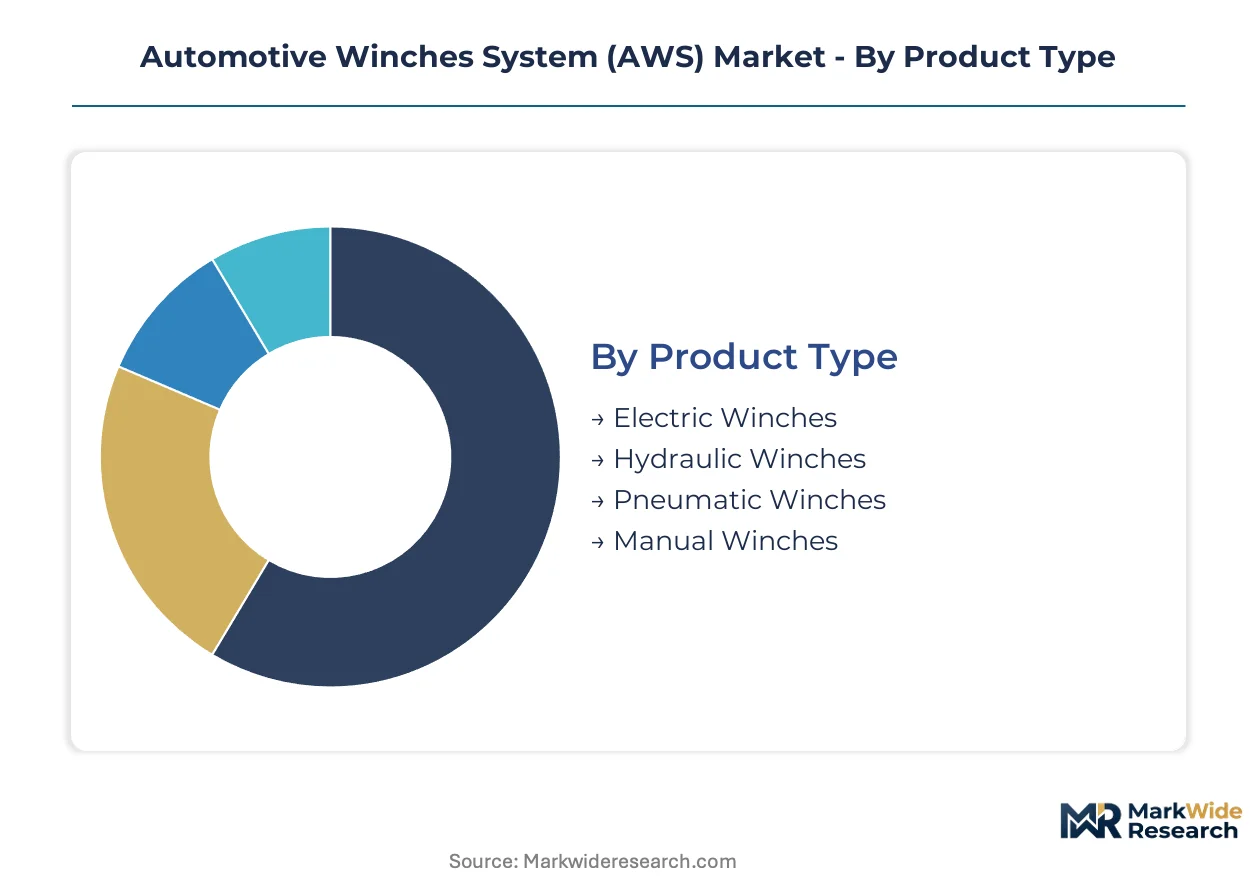
Automotive Winches System segmentation reveals distinct procurement channels and technical specifications that shape manufacturer go-to-market strategies. Channel concentration varies sharply across product categories, with fleet and military buyers favoring direct vendor relationships while recreational demand flows through aftermarket distributors and e-commerce platforms.
Product Type:
Electric winches dominate direct-to-consumer channels through Amazon and specialty retailers, while hydraulic systems concentrate in industrial distributor networks serving mining and construction verticals.
- Electric Winches:These systems utilize 12-volt DC motors with permanent magnet or series-wound architectures, delivering pulling forces from 2,000 to 18,000 pounds through steel cable or synthetic rope configurations. United States aftermarket channels capture the majority of consumer-facing volume as off-road enthusiasts upgrade factory-equipped vehicles with higher-capacity units. FCC Part 15 electromagnetic compatibility certification creates a four-to-six-month launch barrier that favors established suppliers with testing infrastructure.
- Hydraulic Winches:Closed-loop hydraulic circuits powered by vehicle power take-off systems enable sustained duty cycles exceeding electric motor thermal tolerances, with pulling capacities reaching 30,000 pounds for heavy-duty applications. Mining operations in Australia and construction fleets in Germany anchor procurement demand where continuous-load recovery operations are standard. EPA biodegradable fluid requirements under spill prevention rules elevate operating costs versus electric alternatives.
- Pneumatic Winches:Compressed-air drive systems serve explosion-sensitive environments in chemical processing and oilfield operations where electrical ignition risks are prohibitive.
- Manual Winches:Hand-crank mechanisms retain niche demand for emergency backup systems and lightweight recreational trailers where power source independence outweighs convenience trade-offs.
Electric winches dominate installed base. Hydraulic systems are where expansion concentrates in heavy-duty industrial procurement.
Application:
Cost tier differentiation separates premium integrated OEM specifications from price-sensitive aftermarket retrofit demand across use cases.
- Off-Road Vehicles:Factory-integrated winch-ready bumpers with elevated electrical capacity are proliferating across SUV and pickup truck platforms from Detroit and Stuttgart manufacturers. Adventure tourism growth in South Africa and Australia is accelerating aftermarket installations on modified 4x4 vehicles for overland expedition operators.
- Recovery Operations:Towing and roadside assistance fleets require rapid-deployment portable systems with wireless remote controls and synthetic rope for operator safety. Fleet standardization programs in the United States are consolidating procurement around certified mounting systems that satisfy NHTSA crashworthiness guidelines.
- Marine Applications:Saltwater corrosion resistance specifications drive stainless steel and aluminum alloy material selections for anchor handling and trailer loading functions.
- Industrial Use:Warehouse cargo handling and forestry skidding operations specify heavy-duty drum configurations with mechanical load-holding brakes.
Off-Road Vehicles command premium pricing tiers. Recovery Operations are climbing the fastest as fleet electrification creates specification windows for compatible winch systems.
Installation Type:
Customer type segmentation separates institutional buyers with engineering staff from individual consumers dependent on installer networks.
- Static Mounting:Permanent bumper or frame-integrated installations require structural reinforcement and electrical system upgrades, typically performed by certified shops. Military tactical vehicle programs through DFARS procurement frameworks specify static mounting with ballistic protection compatibility.
- Portable Setup:Hitch-mounted or receiver-based systems enable rapid vehicle-to-vehicle transfer for recreational users with multiple vehicles or rental fleet operators. Australian mining camps and South African safari operators favor portable configurations for fleet flexibility.
- Integrated System:OEM factory installations with CAN bus controller compatibility and warranty coverage are expanding across premium truck and SUV segments from manufacturers in Michigan and Bavaria.
- Aftermarket Installation:Post-purchase retrofit demand concentrates in the United States and Australia where consumer modification culture supports specialty retailer and mobile installer channels.
Aftermarket Installation dominates current volume. Integrated System is where margin expansion concentrates through OEM specification capture.
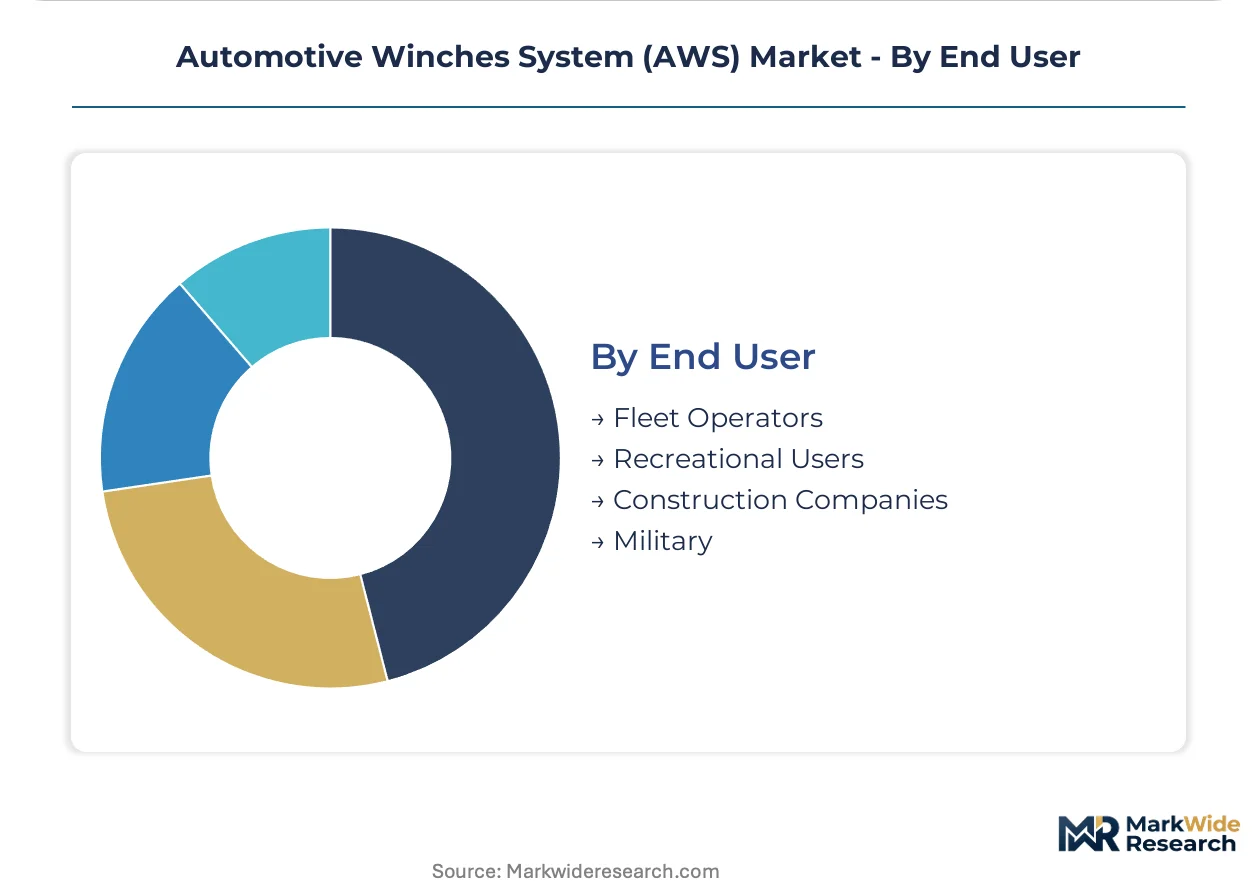
End User:
Supply concentration varies by procurement sophistication, with military and fleet operators consolidating around qualified vendor lists while recreational demand fragments across channels.
- Fleet Operators:Commercial trucking and utility vehicle fleets negotiate multi-year supply agreements with performance-based maintenance clauses and telematics integration requirements. German postal and French utility fleets are incorporating EU Green Deal procurement criteria into winch specifications.
- Recreational Users:Individual off-road enthusiasts and overland tour operators purchase through e-commerce platforms and specialty retailers, with synthetic rope configurations displacing steel cable for weight and safety advantages. Weekend warrior segments in Colorado and Utah drive seasonal demand spikes.
- Construction Companies:Heavy equipment recovery and material handling applications specify hydraulic systems through industrial distribution relationships with rental yard networks.
- Military:Tactical vehicle programs impose environmental testing, electromagnetic hardening, and supply chain security requirements that restrict qualified supplier pools.
Fleet Operators anchor long-term contract value. Recreational Users are where channel disruption through direct-to-consumer platforms concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between recreational aftermarket cultures and industrial procurement regimes. The United States and Australia concentrate demand in off-road enthusiast segments with synthetic rope preferences. Germany and China anchor heavy-duty hydraulic procurement for mining and construction fleets.
United States
Aftermarket customization culture and military fleet modernization sustain premium winch procurement across Colorado and Utah recreational clusters. NHTSA bumper modification guidelines mandate crash-tested mounting systems, creating certified product demand from compliant suppliers. Detroit manufacturers integrate winch-ready bumpers into factory SUV and pickup truck platforms.
Germany
Industrial distributor networks serve mining and construction verticals with sustained-duty hydraulic systems through Baden-Württemberg engineering clusters. REACH substance restrictions on chromium(VI) plating force conversion to trivalent chrome or ceramic coating alternatives for corrosion protection. Bavarian winch assemblers achieve full supply chain requalification ahead of regulatory deadlines.
Australia
Adventure tourism expansion drives aftermarket installations on modified 4x4 vehicles for overland expedition operators in Queensland and Western Australia. Mining camps favor portable configurations for fleet flexibility across remote extraction sites. Perth-based industrial distributors anchor hydraulic procurement for continuous-load recovery operations.
China
Commercial vehicle retrofit demand concentrates in underpenetrated tractor and heavy truck segments for locally manufactured electric winch systems. GB standards govern electromagnetic compatibility testing for motor controllers marketed domestically. Yangtze River Delta manufacturing clusters scale production for export-oriented recreational winch assemblies.
South Africa
Safari operators and adventure tourism fleets drive synthetic rope adoption for weight and safety advantages in overland expedition vehicles. Mining recovery operations specify heavy-duty hydraulic configurations through Johannesburg industrial distribution channels. Cape Town specialty retailers serve recreational aftermarket demand through direct-to-consumer platforms.
Automotive Winches System (AWS) Market Competitive Environment
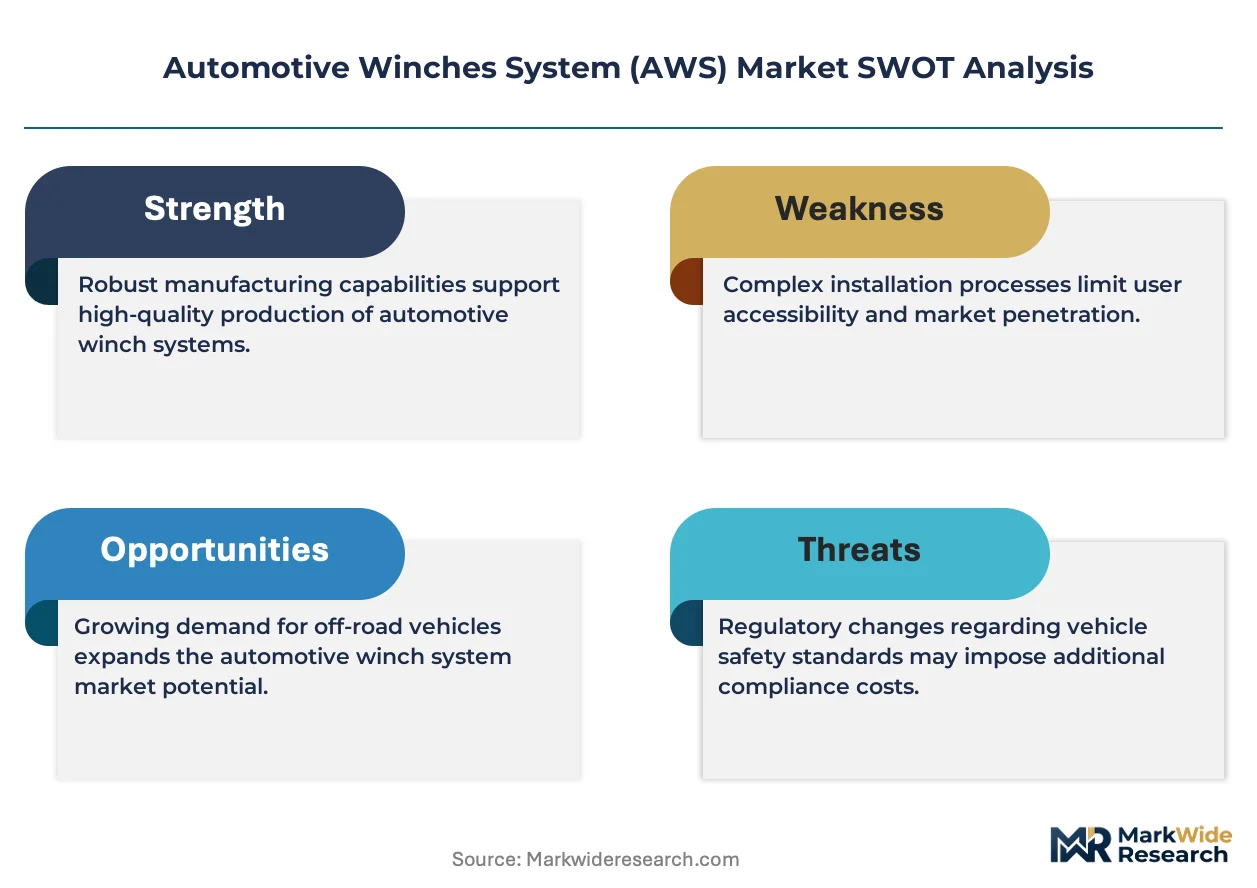
A small set of integrated leaders sits above a broader specialist tier, with Warn Industries leveraging captive motor production and in-house metallurgy to command premium positioning. Assembly-dependent competitors sustain cost competitiveness through modular platform architectures spanning multiple vehicle fitments. Three archetypes dominate: vertically integrated manufacturers with metallurgical capabilities, modular platform specialists, and industrial-grade hydraulic distributors penetrating mining procurement channels. Competitive moves concentrate on FCC Part 15 certification infrastructure investment and CAN bus integration protocol development.
Within the integrated manufacturing tier, Warn Industries and Superwinch occupy distinct positioning vectors. Warn Industries exemplifies captive supply chain control through its electric winch category concentration. Superwinch represents modular platform architecture approaches that span fitment flexibility. Ingersoll Rand anchors industrial-grade hydraulic portfolio distribution through mining and construction procurement channels. These three entities collectively illustrate the capital-intensity divergence bifurcating competitive positioning.
| Leading Market Players |
|---|
| Superwinch |
| Ingersoll Rand |
| Warn Industries |
| Westin Automotive Products |
| ARB Corporation |
| Ramsey Winch |
| TJM Products |
| Mile Marker Industries |
| Smittybilt |
| Others |
Value Chain & Pricing Dynamics
Synthetic rope substitution for steel cable simultaneously redraws procurement geography toward Dyneema fiber producers in the Netherlands and Japan while compressing margin structures for traditional cable drum manufacturers. This material transition forces supply chain reconfiguration around specialized polymer handling equipment and elevates pricing power for fiber suppliers at the expense of metalworking tiers.
Pricing Analysis
After-sales service revenue from replacement rope, motor controller diagnostics, and mounting hardware retrofit sustains lifetime value beyond initial unit sales. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and thermal duty cycle rating. Cost compression in economy electric winch tiers intensifies because modular platform specialists from China scale production for Amazon-direct distribution. Fleet operators exhibit lowest price sensitivity due to telematics integration requirements and multi-year service bundling, while weekend recreational buyers drive transactional volume through promotional seasonal pricing.
Supply Chain Analysis
Inventory cycles for rare-earth magnet motor assemblies stretch lead times when Chinese processing capacity faces environmental compliance inspections. Manufacturing concentrates in China, the United States, and Germany, with Yangtze River Delta clusters feeding export-oriented recreational assemblies and Baden-Württemberg engineering centers serving hydraulic industrial demand. Copper windings and neodymium magnets anchor cost structures, with supply chain risk centered on single-source vulnerability for concentrated rare-earth processing. Distribution runs through Amazon and manufacturer-direct storefronts for consumer segments, while mining and military procurement flows through qualified vendor lists and DFARS-compliant distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified electromagnetic compatibility testing capacity represents the binding constraint separating compliant suppliers from launch-delayed competitors, with FCC Part 15 infrastructure investment determining market access velocity.
For Market Incumbents: Fortify captive motor production and in-house metallurgy capabilities against modular platform specialists eroding premium positioning through cost-engineered alternatives. Expand FCC Part 15 certification infrastructure to compress four-to-six-month launch barriers that protect established supplier market share. Deepen backward integration into synthetic rope handling equipment to capture margin migrating from steel cable drum manufacturing. For New Entrants and Emerging Players: Anchor in India's underpenetrated tractor and heavy truck retrofit segment where localized electric winch manufacturing escapes established brand loyalty. Target commercial fleet telematics integration as the most penetrable specification window, with CAN bus protocol compatibility as the essential go-to-market credential. Pursue EU Green Deal procurement incentives through low-emission recovery equipment certification for German and French public sector fleet electrification programs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed modular platform specialists possessing Amazon-direct distribution infrastructure but lacking electromagnetic compatibility certification depth. Long-term viability favors suppliers with integrated motor controller design capabilities and military DFARS qualification pathways. Watch FCC enforcement intensity on electromagnetic emission standards as the signal indicating certification infrastructure valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CAN Bus Integration Protocol Development | Enables predictive maintenance service offerings through vehicle diagnostic network convergence. |
| Synthetic Rope Handling Equipment Investment | Captures margin migration from steel cable toward Dyneema fiber configurations in recreational segments. |
| FCC Part 15 Certification Infrastructure Expansion | Compresses launch timelines and defends market access against testing-backlogged competitors. |
| India Localized Manufacturing Footprint | Addresses underpenetrated commercial vehicle retrofit demand with cost-competitive electric assemblies. |
| Military DFARS Qualification Pathway | Opens tactical vehicle procurement channels with supply chain security and environmental hardening requirements. |
Study Parameters
A spread of perspectives from OEM platform engineers, aftermarket distributor operations heads, fleet maintenance directors, and military procurement officers converged on the working assumptions around electrification compatibility requirements and duty cycle specifications. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, NHTSA regulatory dockets, EPA spill prevention guidance documents, and vehicle production databases. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled include product type architecture, application use case, installation configuration, and end-user procurement sophistication alongside regional regulatory cluster differentiation. CAGRs were derived from installed base growth rates, replacement cycle compression, and content-per-vehicle trajectories. Forecast inputs incorporated electric vehicle powertrain penetration curves and military fleet modernization program specifications throughout the projection horizon.
Material uncertainties — copper and rare-earth magnet price volatility, FCC enforcement intensity variations, and REACH substance restriction phase-in timing — sit outside the modeled envelope. Forecasts reflect documented assumptions around electrification adoption pathways and aftermarket channel evolution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Bumper Beam Market
Automotive Parts
Automotive Hydroformed Parts Market
Automotive Parts
Global Automotive Hydraulic Brake Market
Automotive Parts
Automotive Electric Drive Axle Market
Automotive Parts
Global Windshield Wiper Blades Market
Automotive Parts
Automatic Gearbox Valves Market
Automotive Parts
Automotive Fluids Market
Automotive Parts
Power Steering Oil Market
Automotive Parts
Fuel Injection Cleaning Machine Market
Automotive Parts
Australia Automotive Parts Magnesium Die Casting Market
Automotive Parts
China Passenger Vehicles Lubricants Market
Automotive Parts
UK Automotive Parts Magnesium Die Casting Market
Automotive Parts
Undercarriage Systems Market
Automotive Parts
US Automotive Airfilters Market
Automotive Parts
Automotive Electric Water Pump Market
Automotive Parts
Europe Automotive Lubricants Market