
 Japan Automotive Hydraulic Actuators Market | 2026-2036
Japan Automotive Hydraulic Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Automotive Hydraulic Actuators Market Foresight
Buyer concentration among Japanese OEMs is expanding as top-tier automakers consolidate supplier rosters toward vertically integrated partners. Denso Corporation leverages its captive supply relationships with Toyota to dominate integrated hydraulic modules for brake and steering applications. Aisin Corporation anchors the light-truck segment through specialized cylinder actuator production for domestic commercial vehicle platforms. Hitachi Astemo competes across multiple installation types, sustaining R&D intensity in rotary actuator designs for next-generation suspension architectures.
Automotive hydraulic actuators are electromechanical devices that convert fluid pressure into linear or rotary mechanical force, typically operating at system pressures between 10 and 35 MPa to enable precise motion control in vehicle subsystems. Their primary industrial purpose is to transmit controlled force in brake, steering, and suspension systems where electrical actuation cannot match torque density requirements. Cylinder actuators occupy the largest product category due to entrenched deployment in brake and steering control across passenger car and heavy truck platforms. Modular installation types are gaining share as OEMs seek standardized sub-assemblies that reduce assembly-line complexity, while integrated configurations retain margin pools in premium passenger car programs where space and weight optimization dominate engineering priorities.
METI enforces fuel-efficiency and emissions frameworks that directly shape hydraulic actuator specifications, compelling suppliers to reduce system weight and parasitic energy losses. JIS standards govern material grades and fatigue testing protocols, creating compliance barriers for non-domestic component sources. PMDA oversight intersects indirectly where hydraulic systems support autonomous braking and steering safety functions. Stakeholders must monitor how Japan's vehicle electrification timeline alters hydraulic content per platform, particularly as hybrid architectures retain hydraulic braking while full battery-electric designs migrate toward electro-mechanical alternatives.
Market Dynamics
Electrification pressure from METI decarbonization roadmaps is fragmenting hydraulic actuator demand, as hybrid platforms retain fluid-based braking while battery-electric architectures accelerate migration toward electro-mechanical alternatives.
Growth Catalysts
- Commercial Fleet Renewal:Domestic logistics operators are upgrading brake and suspension systems in heavy-duty trucks, expanding procurement volumes for cylinder actuators rated above 25 MPa operating pressure.
- METI Fuel-Efficiency Mandates:Tightening corporate average fuel economy standards compel OEMs to specify lighter hydraulic modules with reduced parasitic energy losses across passenger car platforms.
- Kanto Supplier Clustering:Tier-one actuator manufacturers concentrate production capacity within 150 kilometers of Toyota City and Nissan Yokohama headquarters, compressing logistics costs and joint development cycles.
Market Restraints
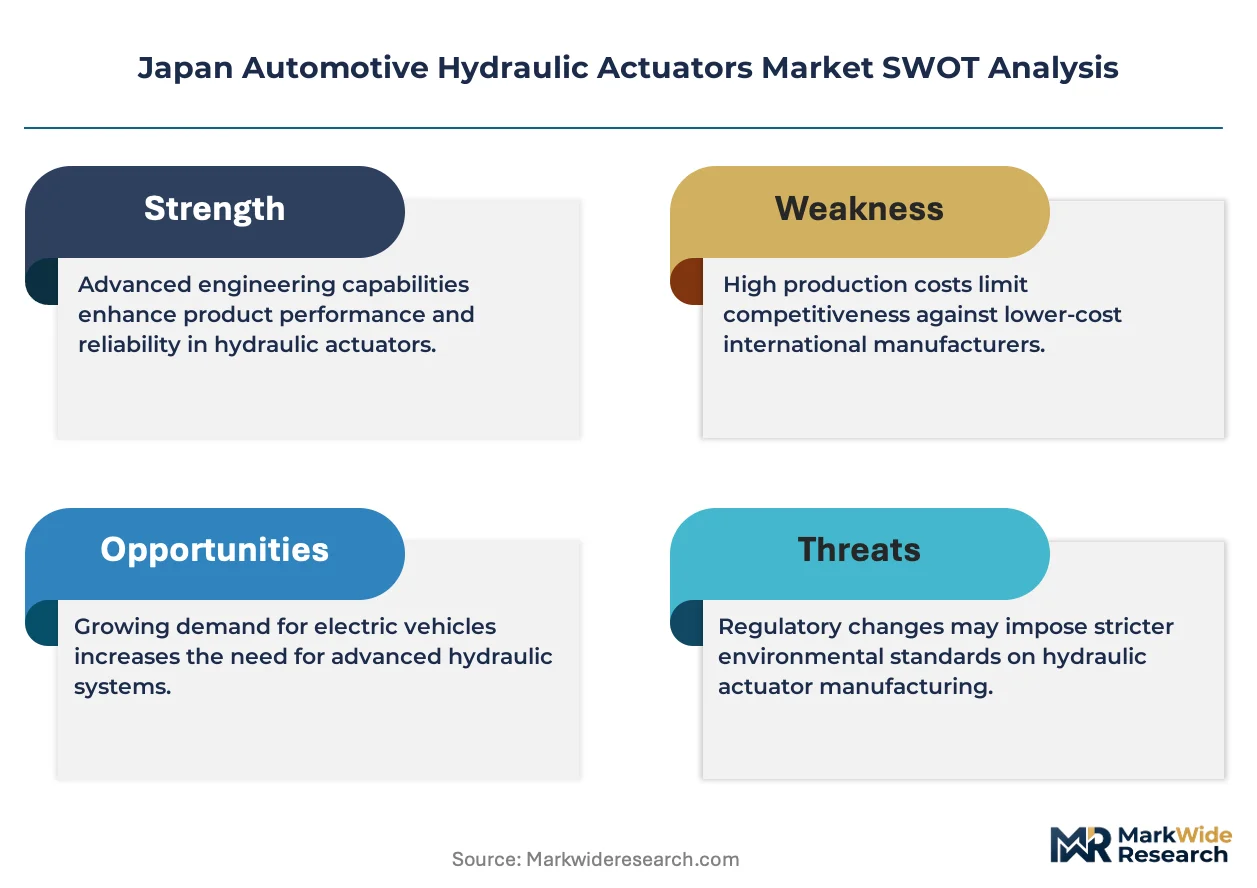
- Steel and Aluminum Input Volatility:JIS-certified alloy grades for high-pressure cylinder bodies face price swings tied to commodity exchange fluctuations, compressing margin predictability for mid-volume suppliers.
- Single-Source Concentration Risk:Domestic OEMs maintain captive supply relationships with Denso and Aisin, creating barrier-to-entry effects for independent actuator specialists seeking platform qualification.
- Electro-Mechanical Substitution:Brake-by-wire and steer-by-wire architectures in premium battery-electric vehicles eliminate hydraulic circuits entirely, eroding addressable market in the highest-value passenger segments.
Strategic Opportunities
- Aftermarket Retrofit Channel:Independent service networks in Osaka and Nagoya industrial zones present underdeveloped routes for replacement actuator sales outside OEM-captive distribution.
- Light-Truck Export Platforms:ASEAN-bound commercial vehicle programs manufactured in Japan retain hydraulic braking architectures, extending production runs for cylinder actuators displaced from domestic passenger applications.
- Smart Factory Integration:Convergence of hydraulic pressure sensors with IoT-enabled predictive maintenance systems creates value-added module configurations for fleet telematics providers.
Industry Challenges
- Mechatronics Talent Scarcity:Cross-functional engineers capable of integrating hydraulic, electronic, and software subsystems command premium compensation, constraining R&D throughput at second-tier suppliers.
- JIS Fatigue Certification Timelines:Extended validation protocols for high-cycle cylinder testing delay new product introductions by 18-24 months, compressing window for platform design-in.
- Legacy System Integration Complexity:Retrofitting smart actuator modules into existing brake and steering architectures requires custom calibration interfaces, inflating engineering service costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Automotive Hydraulic Actuators Market |
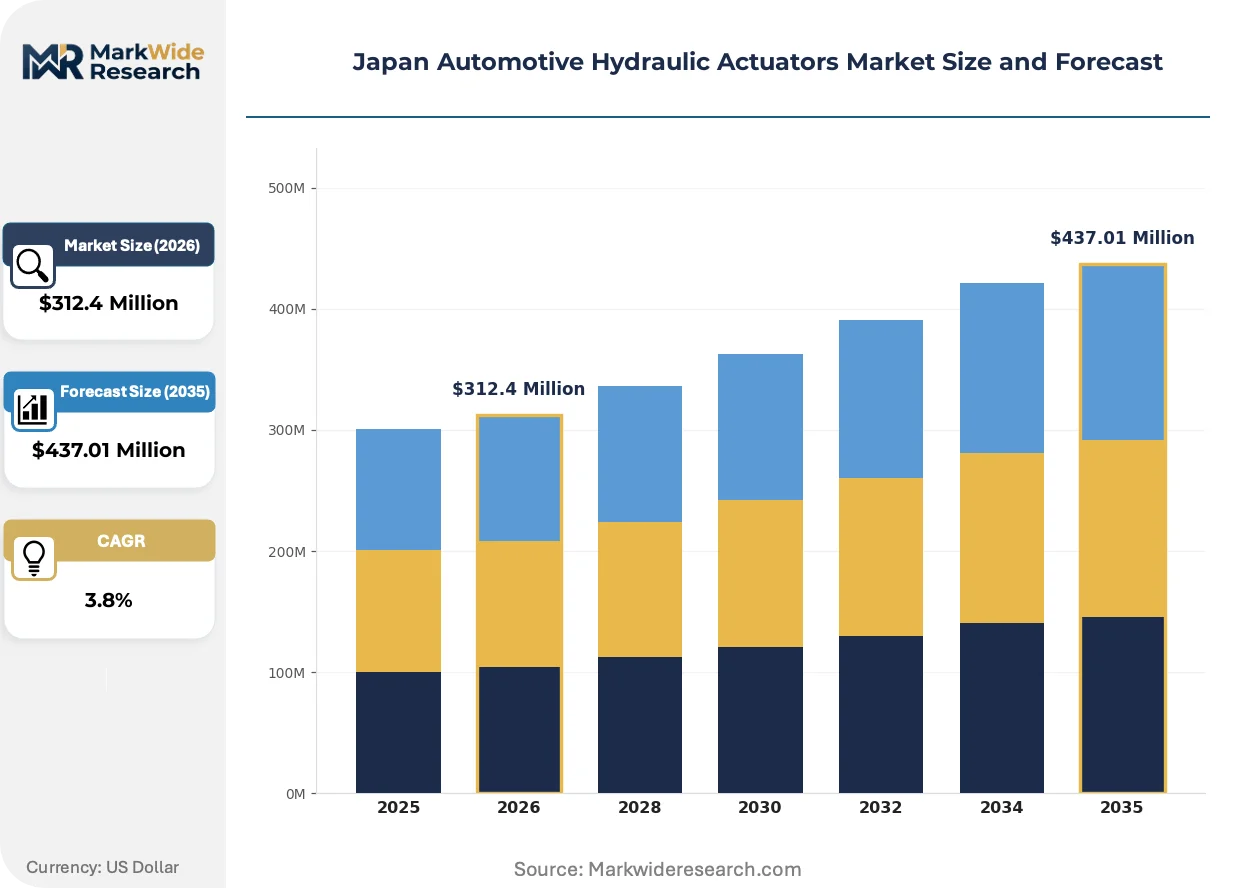
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $437.01 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Push Rod, Cylinder Actuators, Rotary Actuators, Linear Actuators End User: Passenger Cars, Light Trucks, Heavy Trucks, OEMs Installation Type: Integrated, Modular, Custom, Aftermarket Application: Steering Control, Brake Systems, Suspension Systems, Engine Control |
| Companies Covered | Denso Corporation, Aisin Corporation, Hitachi Astemo Ltd., Nissin Kogyo Co., Ltd., KYB Corporation, Mitsubishi Electric Corporation, Nidec Corporation, Robert Bosch GmbH, Continental AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Automotive Hydraulic Actuators Market Shifts & Advancements
Fluid power architectures are bifurcating as electrification pressures force suppliers to defend hydraulic relevance in hybrid applications while ceding ground to electro-mechanical systems in full-electric platforms.
Modular sub-assembly designs are overtaking discrete component supply in brake and steering systems. These standardized hydraulic modules integrate valves, cylinders, and sensors into single replaceable units. Toyota and Nissan procurement divisions are specifying modular configurations for 2027 platform cycles. This standardization is overtaking traditional component-level sourcing, compressing supplier margins while reducing assembly-line complexity at OEM plants.
METI's 2030 fuel-efficiency roadmap mandates 30% reduction in vehicle energy consumption versus 2020 baselines. The regulation forces hydraulic actuator suppliers to redesign seals and port geometries to minimize fluid friction losses. Cylinder actuators for passenger car steering applications face the most stringent redesign timelines, with suppliers accelerating computational fluid dynamics investment to meet certification deadlines.
Fleet operators now bundle actuator replacement schedules with telematics-driven predictive maintenance contracts. This service unbundling disrupts traditional parts-distribution channels through independent maintenance providers. The pattern concentrates in Tokyo and Osaka metropolitan logistics corridors, where commercial vehicle uptime guarantees override brand-loyal procurement preferences.
Japan Automotive Hydraulic Actuators Market Segmentation
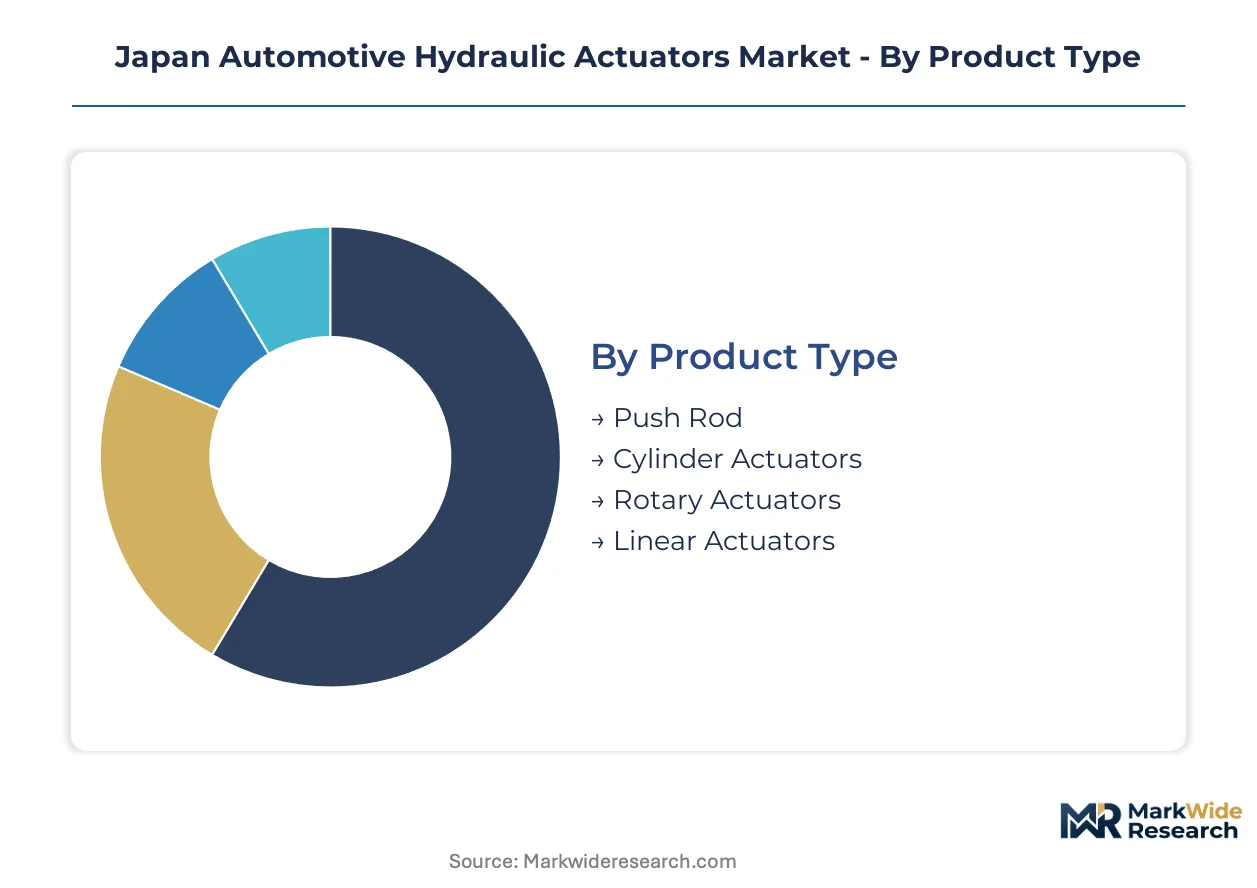
Segmentation reveals how METI regulations and OEM procurement strategies allocate demand across actuator configurations. Each dimension exposes distinct margin structures and qualification barriers.
Product Type:
OEM specification committees prioritize torque density and packaging constraints when selecting hydraulic actuator architectures for platform design-in.
- Cylinder Actuators:These devices convert fluid pressure into linear mechanical force through piston displacement within precision-machined barrels. Demand concentrates in Kanto-region brake and steering applications for Toyota and Nissan passenger car platforms, driven by JIS fatigue certification requirements that favor established domestic suppliers. Cylinder actuators lead on scale; rotary actuators lead on momentum.
- Rotary Actuators:Vane or gear mechanisms transform hydraulic energy into rotational motion for steering rack assistance and suspension articulation. Procurement is accelerating for next-generation active suspension architectures in premium hybrid vehicles, where electro-mechanical alternatives cannot match torque density requirements. Lightweight aluminum housing designs face METI pressure for 30% energy loss reduction.
- Linear Actuators:Screw-driven mechanisms extend hydraulic force along defined axes for clutch and transmission control.
- Push Rod:Simple force-transmission elements connect master cylinders to slave mechanisms in legacy braking systems.
Cylinder actuators dominate procurement volumes; rotary actuators command the steepest expansion trajectory as suspension electrification intensifies.
End User:
Vehicle platform architecture determines hydraulic content per unit, with commercial applications retaining fluid-based systems longer than passenger segments.
- Passenger Cars:Brake and steering systems in hybrid architectures sustain demand for compact hydraulic modules. Specification pressure from METI fuel-efficiency mandates drives lightweight seal redesigns and parasitic loss minimization across Kanto production corridors.
- Heavy Trucks:Air-over-hydraulic braking and suspension leveling systems require actuators rated above 25 MPa operating pressure. Fleet renewal programs in Osaka and Nagoya logistics zones sustain procurement volumes as operators upgrade to meet safety compliance.
- Light Trucks:Domestic commercial platforms manufactured for ASEAN export retain hydraulic braking architectures.
- OEMs:Captive supply relationships with Denso and Aisin concentrate procurement among vertically integrated tier-one suppliers.
Heavy trucks anchor current revenue; passenger cars face the most severe electro-mechanical substitution pressure.
Installation Type:
Assembly-line efficiency targets and service network economics shape whether actuators ship as discrete components or pre-integrated modules.
- Modular:Standardized sub-assemblies integrate valves, cylinders, and sensors into single replaceable units. Toyota and Nissan procurement divisions specified modular configurations for upcoming platform cycles, compressing supplier margins while reducing OEM plant complexity.
- Integrated:Custom-engineered actuator systems embed directly into vehicle architectures for space and weight optimization. Premium passenger car programs in Toyota City engineering centers retain this configuration for performance differentiation despite higher engineering service costs.
- Custom:Bespoke actuator designs address specialized commercial vehicle or motorsport applications.
- Aftermarket:Independent service networks in Osaka and Nagoya industrial zones present underdeveloped replacement channels outside OEM-captive distribution.
Modular configurations gain share fastest; integrated systems defend margin pools in premium segments.
Application:
Functional safety requirements and autonomous driving roadmaps fragment hydraulic actuator relevance across vehicle subsystems.
- Brake Systems:Master cylinders, caliper actuation, and ABS modulation depend on hydraulic force multiplication. Hybrid platforms retain fluid-based architectures while battery-electric designs migrate toward electro-mechanical alternatives, fragmenting addressable market scope.
- Suspension Systems:Active damping and ride-height adjustment require rotary and linear actuators with millisecond response times. Hitachi Astemo sustains R&D intensity in this segment for next-generation architectures that integrate with autonomous chassis control.
- Steering Control:Rack-and-pinion assistance and steer-by-wire backup systems face the most aggressive electro-mechanical substitution timelines.
- Engine Control:Variable valve timing and turbocharger wastegate actuation sustain niche hydraulic demand in internal combustion powertrains.
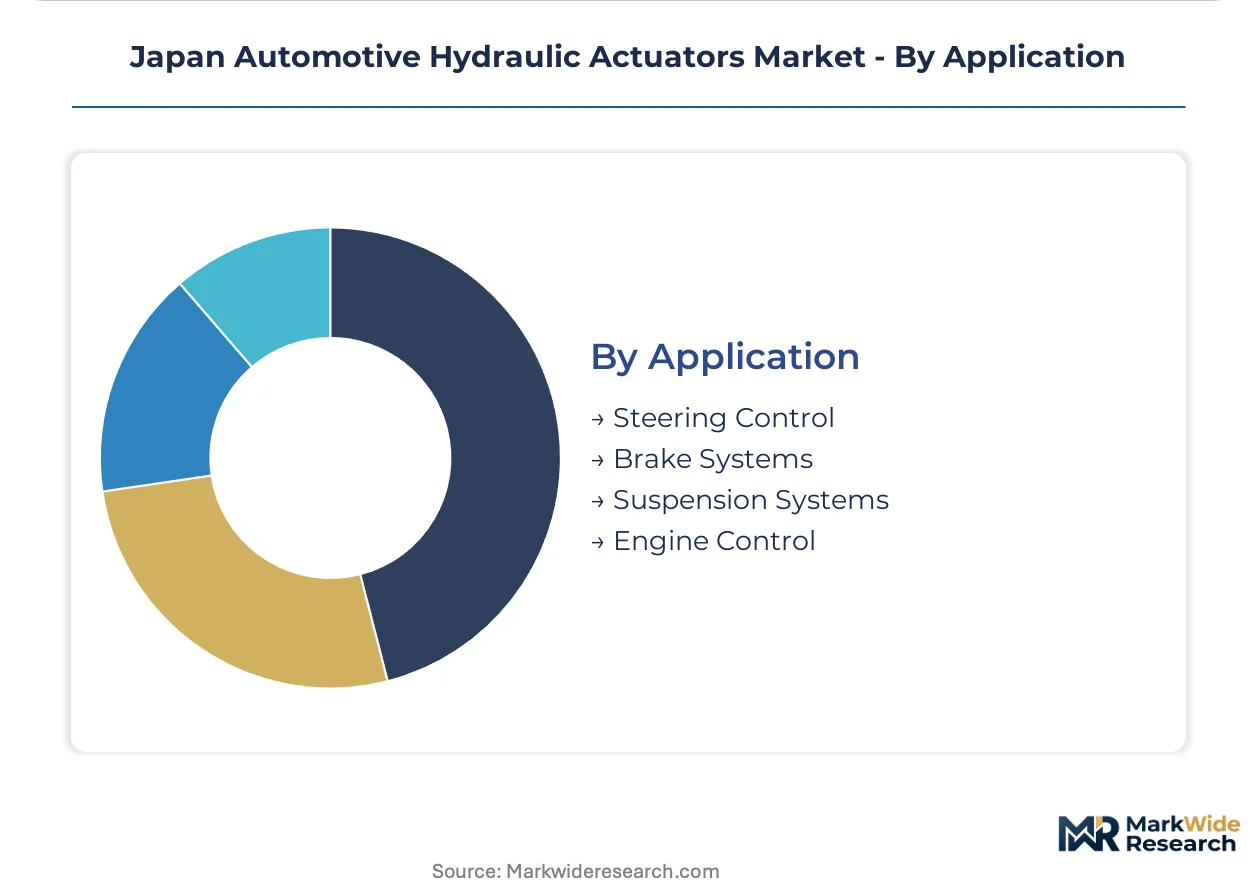
Brake systems retain the largest installed base; suspension systems offer the most defensible growth pathway against electrification pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's precision manufacturing workforce concentrates in the Kanto industrial corridor, where tier-one suppliers cluster around Toyota City and Nissan Yokohama headquarters. This talent density underpins actuator production capabilities unmatched elsewhere in the archipelago.
Kanto/Tokyo
Domestic OEM procurement from Toyota and Nissan anchors demand for brake and steering actuators in this corridor. METI fuel-efficiency standards compel suppliers to reduce system weight and parasitic energy losses. Denso Corporation and Hitachi Astemo maintain engineering centers in Toyota City and Yokohama respectively, compressing joint development cycles with captive automaker partners.
Kansai/Osaka
Independent service networks in Osaka and Nagoya industrial zones present underdeveloped aftermarket channels for replacement actuator sales. Fleet operators bundle actuator replacement schedules with telematics-driven predictive maintenance contracts. Aisin Corporation anchors light-truck production from facilities serving domestic commercial vehicle platforms manufactured for regional logistics operators.
Chubu/Nagoya
Commercial fleet renewal programs sustain procurement volumes for cylinder actuators rated above 25 MPa operating pressure. JIS fatigue certification requirements favor established domestic suppliers with extended validation protocols. Heavy-truck brake and suspension system upgrades concentrate manufacturing activity for high-pressure hydraulic modules in this central industrial zone.
Kyushu
ASEAN-bound commercial vehicle export platforms manufactured in Japan retain hydraulic braking architectures, extending production runs displaced from domestic passenger applications. Regional suppliers serve as secondary sourcing nodes for tier-one actuator manufacturers facing capacity constraints in Kanto. Logistics corridors connecting Fukuoka port facilities to Southeast Asian markets reinforce this export-oriented production profile.
Hokkaido
Specialized cold-climate testing infrastructure supports validation protocols for seal materials and fluid formulations in sub-zero operating conditions. Limited domestic demand concentrates activity on R&D satellite operations rather than volume manufacturing. Suppliers leverage Hokkaido facilities to accelerate certification timelines for products destined for northern European and North American export markets.
Japan Automotive Hydraulic Actuators Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Japan's automotive hydraulic actuators market. The supplier base exhibits tiered concentration, with vertically integrated tier-one manufacturers commanding platform qualification relationships while independent specialists serve aftermarket and niche export segments. Three strategic archetypes dominate: captive suppliers with automaker equity ties, independent component specialists, and multinational system integrators. Competitive dynamics center on backward integration into precision machining capabilities and geographic expansion into ASEAN export corridors.
Among domestic captive suppliers, Denso Corporation and Aisin Corporation exemplify the vertically integrated archetype, leveraging equity relationships with Toyota to dominate integrated hydraulic module supply. Hitachi Astemo occupies a position spanning multiple installation types, representing the diversified industrial conglomerate model with sustained engineering intensity in rotary actuator architectures. These three Japanese entities anchor the competitive structure, with multinational system integrators such as Robert Bosch GmbH and Continental AG competing on technology licensing and modular platform supply.
| Leading Market Players |
|---|
| Denso Corporation |
| Aisin Corporation |
| Hitachi Astemo Ltd. |
| Nissin Kogyo Co., Ltd. |
| KYB Corporation |
| Mitsubishi Electric Corporation |
| Nidec Corporation |
| Robert Bosch GmbH |
| Continental AG |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between JIS-fatigue-certified premium actuators and non-certified commodity alternatives manifests in pricing spreads exceeding material cost differentials, while supply chain configurations concentrate precision-machining capacity within METI-incentivized domestic content zones to maintain qualification access.
Pricing Analysis
Capacity additions in ASEAN export corridors are reshaping price floors for standard-grade cylinder actuators as Japanese suppliers extend production runs for regional commercial vehicle platforms. Contract-based long-term offtake agreements dominate OEM procurement, with price differentiation driven by JIS certification tier and volume scale commitments. Cost compression in standard-grade modules intensifies because steel and aluminum input volatility erodes margin buffers. Fleet operators in Osaka logistics corridors exhibit highest price sensitivity, while premium passenger car programs at Toyota City engineering centers prioritize performance specifications over unit economics.
Supply Chain Analysis
METI domestic-content mandates and JIS material-grade requirements are reshaping sourcing patterns toward Japan-based precision-machining clusters and captive alloy suppliers. Production draws from domestic steel mills for JIS-certified cylinder bodies, South Korean specialty aluminum foundries for lightweight rotary actuator housings, and Taiwanese sensor component manufacturers for smart module integration. Single-source vulnerability concentrates in high-pressure seal compounds where qualified domestic suppliers maintain process exclusivity. Distribution runs through tier-one supplier consolidation centers in Kanto before final assembly at Toyota City and Yokohama OEM plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's automotive hydraulic actuators market functions as a geographic-arbitrage play where ASEAN-bound export production retains hydraulic architectures abandoned in domestic electrification timelines, exploiting regulatory divergence between Japan's battery-electric mandates and Southeast Asia's hybrid-transition pathways.
For Market Incumbents: Extend captive supply relationships through modular platform standardization to defend against electro-mechanical substitution in brake and steering applications. Deepen backward integration into precision-machining capabilities for JIS-certified cylinder production, prioritizing capacity retention in Kanto supplier clusters where joint development cycles compress qualification timelines for next-generation hybrid architectures. For New Entrants and Emerging Players: Launch via independent aftermarket distribution networks in Osaka and Nagoya industrial zones where fleet telematics contracts disrupt OEM-captive parts channels. Target underdeveloped replacement actuator sales for commercial vehicles rated above 25 MPa operating pressure, penetrating through predictive maintenance service bundling rather than component-only supply. For Investors and Strategic Acquirers: Consolidation pressure builds where second-tier suppliers face JIS fatigue certification timelines extending 18-24 months and mechatronics talent scarcity constraining R&D throughput. Five-to-ten-year viability hinges on hybrid-platform content retention; acquisition candidates include independent specialists with ASEAN export qualifications. Signal to monitor: METI vehicle electrification timeline acceleration that would compress hydraulic content per platform.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Standardization | Toyota and Nissan procurement divisions specified standardized sub-assemblies for 2027 platform cycles, compressing supplier margins while reducing assembly-line complexity. |
| Backward Integration into Precision Machining | Domestic suppliers secure JIS-certified alloy supply chains and control critical cylinder body production processes against commodity input volatility. |
| ASEAN Export Corridor Expansion | Commercial vehicle programs manufactured in Kyushu retain hydraulic braking architectures displaced from domestic passenger applications. |
| Smart Factory Sensor Integration | Convergence of hydraulic pressure sensors with IoT-enabled predictive maintenance creates value-added configurations for fleet telematics providers. |
| Aftermarket Channel Development | Independent service networks in Osaka and Nagoya industrial zones present underdeveloped routes outside OEM-captive distribution systems. |
Research Methodology
Multiple input streams — structured interviews with tier-one supplier procurement officers, OEM platform engineers, and aftermarket distributors; secondary validation through vehicle production databases, METI regulatory filings, and IHS Markit registration data; plus customs records for ASEAN export flows — were reconciled through bottom-up and top-down triangulation to construct segment-level estimates.
Historical shipment patterns were cross-referenced against expert panel assessments of electrification penetration rates across the analysis window. Segmentation dimensions modeled include product type, vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs were derived from slope-consistency checks against input cost trajectories and platform lifecycle schedules.
Several conditions sit outside the modeled scope, including unannounced regulatory accelerations, breakthrough electro-mechanical torque density improvements, and commodity price shocks exceeding historical volatility bands. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Italy Automotive Parts Zinc Die Casting Market
Automotive Parts
Europe Ball Bearings Market
Automotive Parts
Saudi Arabia Automotive Lubricants Market
Automotive Parts
Automotive Mechanical Control Cable Market
Automotive Parts
UK Automotive Actuators Market
Automotive Parts
Engine Oil Market
Automotive Parts
Poland Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Bellows Market
Automotive Parts
Full Synthetic Motor Oil Market
Automotive Parts
Engine Bearings Market
Automotive Parts
Global Automotive Gasoline Particulate Filter (GPF) Market
Automotive Parts
Automotive Engine Oil Coolers Market
Automotive Parts
Global Truck Refrigeration Unit Market
Automotive Parts
Small Engine Market
Automotive Parts
Brazil Automotive Airfilters Market
Automotive Parts
Power Steering Oil Market