
 United States Aluminum Beverage Cans Market | 2026-2036
United States Aluminum Beverage Cans Market Size, Share, and Industry Trends Forecast 2026-2036
United States Aluminum Beverage Cans Market Analytics
Aftermarket service revenue from can line engineering and refurbishment is narrowing as original equipment manufacturers consolidate technical support under long-term service contracts. Ball Corporation leverages its integrated metal supply agreements to sustain domestic smelter partnerships across the Gulf Coast. Crown Holdings anchors its position through beverage can specialty lines optimized for craft beer and sparkling water formats. Ardagh Group competes by operating multiple two-piece can plants with quick-change tooling systems for short-run custom jobs.
United States aluminum beverage cans are cylindrical containers fabricated from aluminum alloy sheet, typically 3104-H19 or 3004-H19 temper, formed through deep drawing and ironing processes to achieve wall thickness below 0.004 inches with internal epoxy or polyester coatings for beverage compatibility. These containers serve as the dominant primary packaging format for carbonated and non-carbonated ready-to-drink beverages, offering oxygen and light barrier properties alongside infinite recyclability within existing municipal stream infrastructure. Slim cans and tall cans represent the fastest-growing product type categories as beverage marketers pursue shelf differentiation and portion control positioning, while standard cans retain volume dominance in mainstream beer and soft drink applications. Recycled aluminum material grade commands expanding share as smelters and rolling mills invest in closed-loop scrap processing, though primary aluminum still feeds capacity-constrained regions where beverage demand outpaces regional scrap recovery rates.
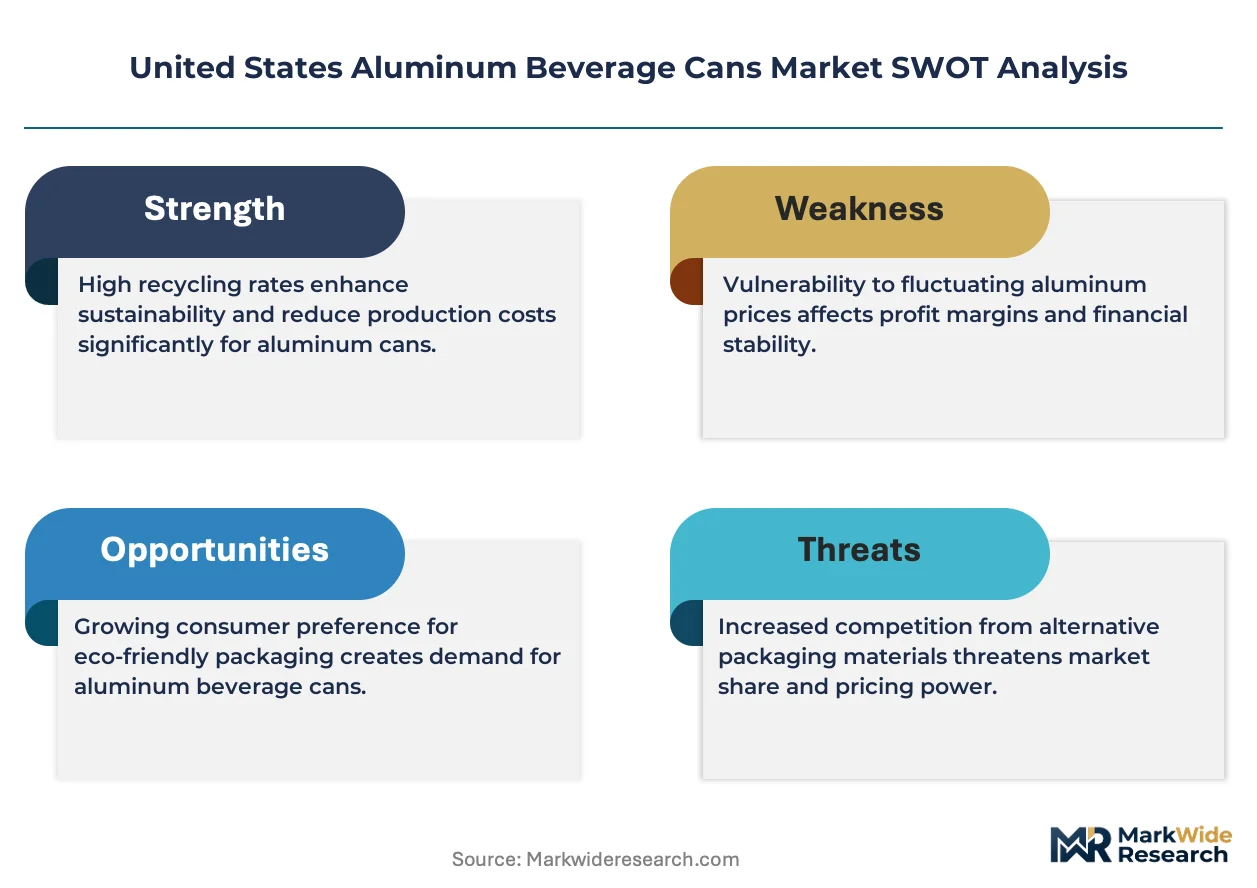
The EPA oversees hazardous waste determinations for can manufacturing coatings and solvents, while OSHA mandates exposure limits for aluminum oxide particulate in forming and decorating operations, and the FDA regulates interior coating migration thresholds under 21 CFR indirect food additive provisions. These overlapping frameworks elevate compliance costs for smaller converters and favor capital-intensive players with dedicated environmental health and safety infrastructure. Stakeholders must monitor how state-level extended producer responsibility legislation in California, Oregon, and Maine reshapes post-consumer collection economics and brand owner fee structures.
Market Dynamics
Recycled content mandates from the EPA are forcing converters to reengineer supply chains around post-consumer aluminum certification, compressing margins for smaller players while advantaging integrated manufacturers with captive scrap processing infrastructure.
Growth Catalysts
- EPA Recycled Content Standards:Evolving sustainable materials management frameworks require certified post-consumer aluminum inputs, creating compliance-driven demand for closed-loop processing capabilities.
- Energy Drinks Segment Migration:Red Bull, Monster, and Celsius have shifted decisive volume from PET to aluminum formats, establishing aluminum as the dominant primary packaging for functional beverages.
- Craft Brewery Expansion:Pacific Northwest and Mountain West craft breweries are scaling aluminum packaging lines as production volumes grow beyond regional draft distribution.
Market Restraints
- Primary Aluminum Supply Concentration:Capacity-constrained regions where beverage demand outpaces regional scrap recovery rates remain dependent on Gulf Coast smelter partnerships.
- Coating Compliance Costs:FDA interior coating migration thresholds under 21 CFR indirect food additive provisions elevate formulation and testing expenses for epoxy and polyester interior linings.
- Input Cost Volatility:Aluminum alloy sheet pricing fluctuates with LME aluminum and regional energy costs, compressing converter margins on fixed-price annual contracts.
Strategic Opportunities
- Short-Run Custom Tooling:Quick-change tooling systems enable two-piece can plants to capture craft beer and sparkling water format diversity without line changeover penalties.
- State Extended Producer Responsibility:California, Oregon, and Maine EPR legislation reshapes post-consumer collection economics, creating fee structure advantages for brands with verified recycled content.
- Slim and Tall Can Formats:Shelf differentiation and portion control positioning in premium beverages drives equipment upgrade cycles for specialty line configurations.
Industry Challenges
- Aluminum Oxide Particulate Exposure:OSHA mandated exposure limits in forming and decorating operations require capital-intensive ventilation and monitoring infrastructure that disadvantages smaller converters.
- Coating Solvent Hazardous Waste Determinations:EPA oversight of can manufacturing coatings creates compliance timeline uncertainty and documentation burdens for environmental health and safety departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Aluminum Beverage Cans Market |
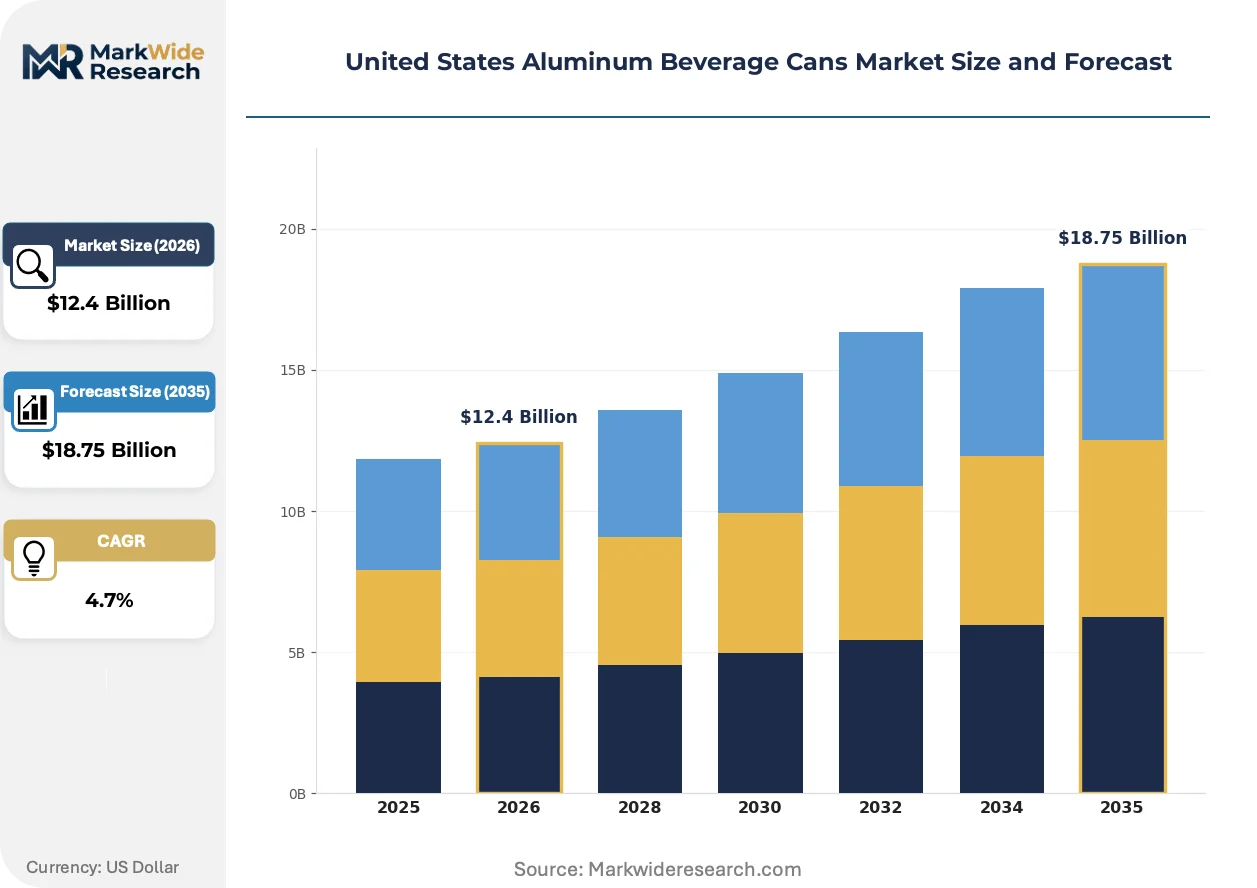
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $18.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cans, Slim Cans, Tall Cans, Custom Cans End User: Soft Drinks, Beer, Energy Drinks, Juices Material Grade: Recycled Aluminum, Primary Aluminum, Alloyed Aluminum, Coated Aluminum Distribution Channel: Retail Stores, Online Platforms, Wholesalers, Distributors |
| Companies Covered | Silgan Holdings, Envases Group, Ball Corporation, Allstate Can Corporation, Independent Can Company, Crown Holdings, Metal Container Corporation, CAN-PACK, Ardagh Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Aluminum Beverage Cans Market Evolving Landscape
Digital process control and automated quality assurance systems are penetrating can forming operations, enabling real-time wall thickness monitoring and coating uniformity verification that reduces material waste and rejection rates.
Machine vision inspection technology is digitizing defect detection in deep drawing and ironing operations. Major converters are deploying inline laser measurement systems for wall thickness below 0.004 inches. This capability is compressing quality assurance labor costs and enabling statistical process control integration with rolling mill suppliers.
OSHA exposure limits for aluminum oxide particulate are tightening enforcement protocols across forming and decorating operations. Rolling mills and converters are jointly investing in closed-loop dust collection and employee monitoring systems. Craft beer and energy drink segments face the steepest compliance cost escalations due to higher line speeds and coating application rates.
Direct procurement relationships between beverage brand owners and aluminum rolling mills are displacing traditional converter-mediated supply chains. Red Bull and Monster have established volume commitments with domestic smelters for primary alloy allocation. This pattern concentrates most visibly in the energy drinks vertical where annual volume scale justifies bypassing intermediate metal service centers.
United States Aluminum Beverage Cans Market Segmentation
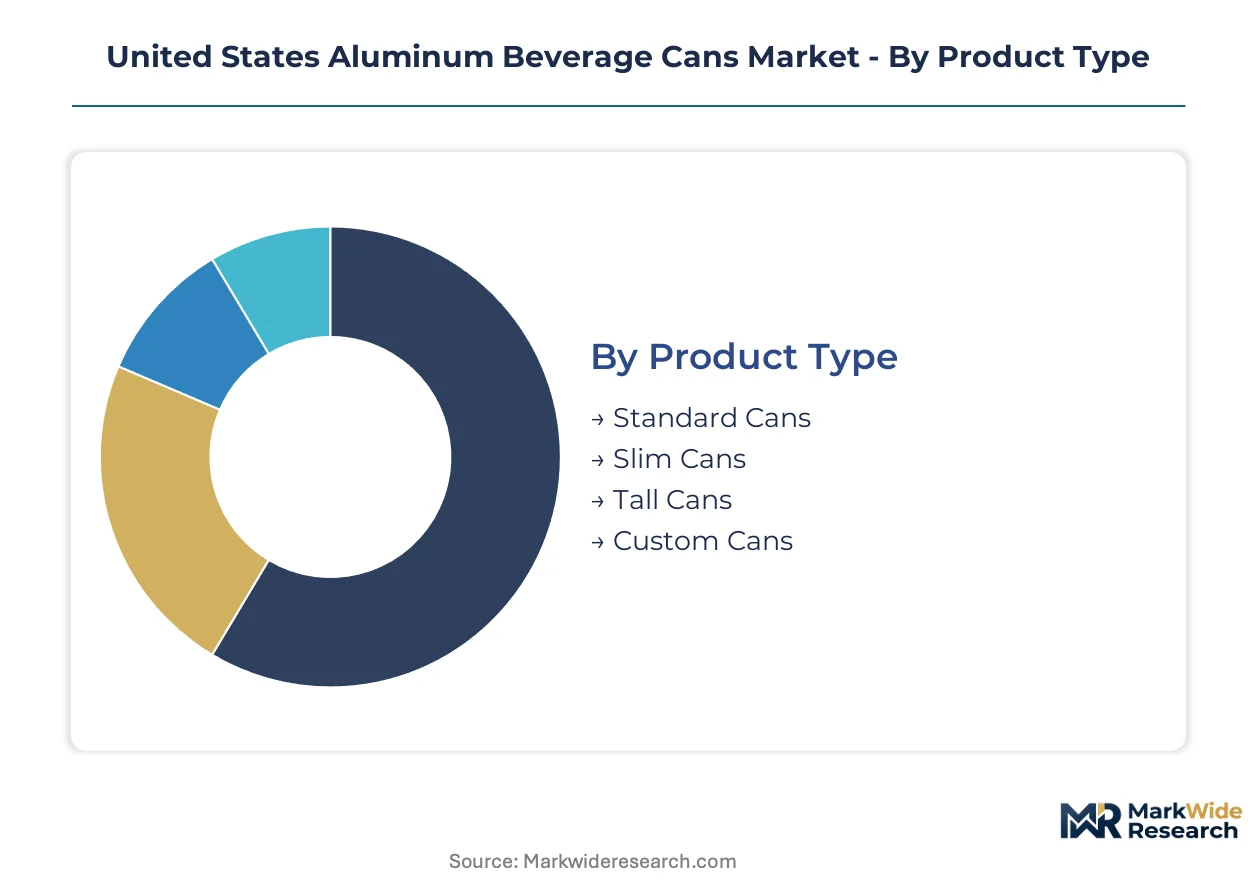
Aluminum beverage can segmentation in the United States reflects divergent tooling investments, alloy sourcing strategies, and channel economics that shape converter capacity allocation. Each dimension captures distinct margin profiles and regulatory exposure that determine competitive positioning across the value chain.
Product Type:
Cost tier differentiation in can formats drives capital deployment intensity and line changeover flexibility across converter plants.
- Standard Cans:These 12-ounce cylindrical containers with 211 diameter specifications serve mainstream beer and carbonated soft drink volume. Demand concentrates in Midwest and Southeast production corridors where legacy lines achieve maximum throughput efficiency on annual supply contracts with major beverage brands.
- Slim Cans:Narrower 204 diameter bodies with elongated profiles require specialized deep-drawing tooling and modified ironing sequences. Pacific Northwest craft breweries and energy drink marketers in California are rotating volume decisively toward this format for shelf differentiation and portion-control positioning.
- Tall Cans:Extended-height 16-ounce and 19.2-ounce configurations target craft beer and sparkling water segments seeking single-serve premium positioning.
- Custom Cans:Non-standard geometries with embossed branding or shaped walls demand quick-change tooling systems and carry higher per-unit conversion costs.
Standard cans hold installed capacity. Slim cans are rotating up the share rankings.
End User:
Application-specific requirements for barrier performance, carbonation retention, and filling line compatibility segment converter technical capabilities.
- Soft Drinks:High-carbonation formulations with phosphoric acid chemistry demand robust internal epoxy coatings and precise flange specifications for double-seam integrity. Concentrated demand from Coca-Cola and Pepsi bottling networks in Texas and Georgia drives volume allocation toward high-speed lines with automated inspection.
- Energy Drinks:Functional beverages with taurine and caffeine formulations shifted decisively from PET to aluminum across Red Bull, Monster, and Celsius portfolios. California and Florida distribution hubs concentrate demand for slim and tall formats with metallic finishes requiring advanced decorating lines.
- Beer:Pasteurization-compatible coatings and oxygen-scavenging interior linings serve Anheuser-Busch and Molson Coors production networks.
- Juices:Non-carbonated aseptic filling compatibility with reduced sulfur migration thresholds shapes coating selection.
Soft drinks anchor volume throughput. Energy drinks are climbing the fastest in margin contribution per unit.
Material Grade:
Supply concentration and scrap recovery economics determine alloy sourcing strategies across smelter and rolling mill relationships.
- Recycled Aluminum:Post-consumer 3104-H19 and 3004-H19 scrap processed through closed-loop remelt operations delivers lower carbon intensity. EPA recycled content certification requirements are compressing margins for converters without captive scrap processing infrastructure.
- Primary Aluminum:Virgin metal from Gulf Coast smelters feeds capacity-constrained regions where beverage demand outpaces regional scrap recovery rates. Energy drink brand owners increasingly bypass converters to secure direct volume commitments with domestic smelters.
- Alloyed Aluminum:Modified manganese and magnesium compositions optimize deep-draw formability for complex geometries.
- Coated Aluminum:Pre-laminated polymer or lacquer-coated sheet reduces inline coating steps for specialty decorative applications.
Primary aluminum dominates current supply agreements. Recycled aluminum is gaining share fastest under compliance pressure.
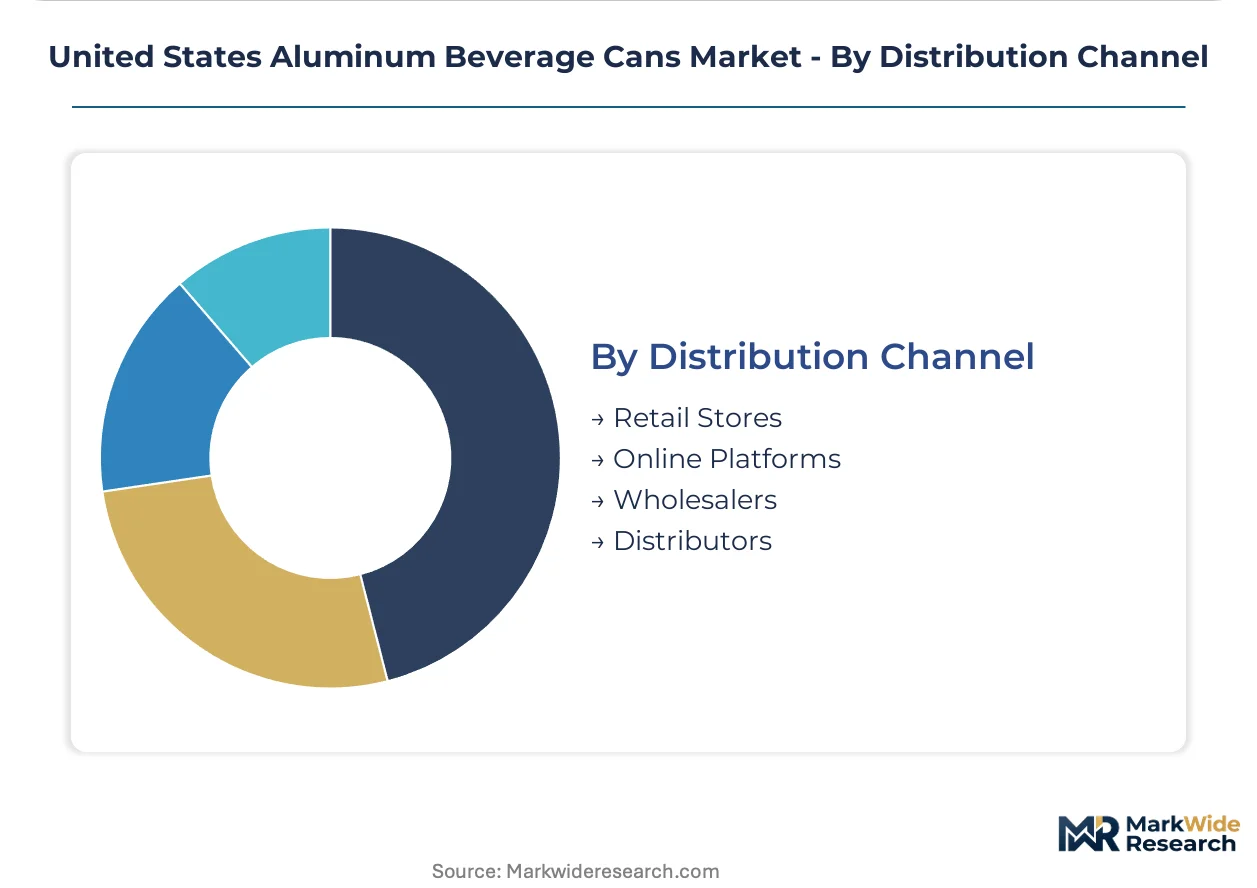
Distribution Channel:
Customer type and order pattern variability shape logistics configuration and working capital requirements across the value chain.
- Retail Stores:Direct-to-grocery and convenience store distribution demands palletized unit loads with retail-ready packaging and seasonal promotional changeovers. Walmart and Kroger procurement networks in Ohio and Illinois concentrate volume through dedicated converter warehousing arrangements.
- Online Platforms:E-commerce direct-to-consumer fulfillment requires smaller pack configurations and damage-resistant secondary packaging. Amazon and beverage subscription services in California and New York are expanding this channel for premium craft and functional beverage segments.
- Wholesalers:Beverage distribution intermediaries aggregate fragmented craft brewery demand across multi-state territories.
- Distributors:Anheuser-Busch and Reyes Beverage Company networks manage just-in-time delivery to filling plants.
Retail stores maintain infrastructure dominance. Online platforms are expanding most quickly in format diversity requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic smelter partnerships cluster along the Gulf Coast, where integrated metal supply agreements feed rolling mill capacity serving beverage can converters. This concentration shapes regional competitive dynamics and scrap recovery economics.
California
Energy drink marketers and craft breweries drive slim can demand across Los Angeles and San Francisco distribution hubs. State extended producer responsibility legislation reshapes post-consumer collection economics and brand owner fee structures. The Central Valley hosts beverage filling operations that source tall formats for premium positioning.
Texas
Gulf Coast smelter partnerships anchor primary aluminum supply for high-throughput soft drink lines serving Coca-Cola and Pepsi bottling networks. EPA recycled content standards pressure converters to certify post-consumer inputs. Houston-area warehousing arrangements concentrate retail-bound palletized unit loads.
Pacific Northwest
Craft breweries across Oregon and Washington expand aluminum packaging lines as production scales beyond regional draft distribution. OSHA exposure limits for aluminum oxide particulate tighten enforcement protocols across forming operations. Seattle and Portland clusters specialize in quick-change tooling for short-run custom jobs.
Florida
Energy drink distribution hubs concentrate demand for metallic finishes requiring advanced decorating lines. The state's beverage distribution intermediaries aggregate fragmented craft brewery demand across multi-state territories. Miami and Tampa operations face coating compliance cost escalations from higher line speeds.
Illinois
Midwest retail procurement networks from Walmart and Kroger drive volume allocation toward high-speed lines with automated inspection. Chicago-area converter plants optimize standard can throughput efficiency on annual supply contracts. The region remains capacity-constrained for scrap recovery relative to beverage demand.
United States Aluminum Beverage Cans Market Competitive Landscape
Integrated manufacturers and specialized converters split the market along capital intensity lines. Ball Corporation, Crown Holdings, and Ardagh Group anchor the top tier through captive metal supply and multi-plant geographic coverage. Mid-scale operators compete on quick-change flexibility for craft and premium segments. Dominant competitive moves include long-term service contract consolidation and direct procurement relationships bypassing traditional metal service centers.
Among integrated metal packaging specialists, Ball Corporation exemplifies the smelter-partnership archetype through Gulf Coast supply agreements. Crown Holdings occupies a position within the beverage can specialty tier, with operations optimized for format diversity. Ardagh Group represents the quick-change tooling specialist model, serving short-run custom demand across multiple two-piece can plants.
| Leading Market Players |
|---|
| Silgan Holdings |
| Envases Group |
| Ball Corporation |
| Allstate Can Corporation |
| Independent Can Company |
| Crown Holdings |
| Metal Container Corporation |
| CAN-PACK |
| Ardagh Group |
| Others |
Value Network & Pricing Analysis
Commodity volatility in London Metal Exchange aluminum pricing determines both tier spreads between recycled and primary alloy grades and the geographic configuration of Gulf Coast smelter partnerships. EPA recycled content certification requirements compress margins for converters without captive scrap processing, forcing pricing stratification across integrated and non-integrated supply chain archetypes.
Pricing Analysis
EPA recycled content standards dictate the pricing tier structure across three levels: premium certified post-consumer grades, standard primary alloy contracts, and economy spot-market purchases. Price differentiation hinges on carbon intensity certification and volume scale commitments, with energy drink brand owners showing lowest price sensitivity due to direct smelter relationships. Cost compression in standard can segments is intensifying because fixed-price annual contracts expose converters to LME aluminum swings. Craft breweries exhibit highest price sensitivity, driving demand for quick-change tooling that minimizes per-unit conversion penalties on short runs.
Supply Chain Analysis
Tariff exposure between Canada and the United States dominates aluminum sheet sourcing decisions for domestic converters. Primary supply draws from Gulf Coast smelters in Texas and Louisiana, with secondary feedstock anchored in Midwest scrap recovery clusters. Raw material dependencies center on 3104-H19 and 3004-H19 alloy sheet, epoxy and polyester coating chemistries, and lithographic printing inks. Single-source vulnerability concentrates in rolling mill capacity serving high-throughput soft drink lines. Distribution runs through dedicated converter warehousing arrangements feeding Walmart and Kroger procurement networks in Ohio and Illinois.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States aluminum beverage cans market represents early-cycle expansion as craft brewery aluminum packaging adoption accelerates beyond regional draft distribution constraints. Energy drink segment migration from PET formats sustains volume tailwinds for specialty can configurations.
For Market Incumbents: Entrench smelter partnership exclusivity through long-term service contract consolidation that locks in technical support and refurbishment revenue. Ball Corporation and Crown Holdings should expand quick-change tooling capacity in Pacific Northwest clusters before mid-scale operators capture craft brewery format diversity. Backward integration into closed-loop scrap processing defends margin position against EPA compliance cost escalations.
For New Entrants and Emerging Players: Mountain West craft brewery territories outside Seattle and Portland Portland offer underpenetrated demand for short-run custom can jobs with premium per-unit economics. Target sparkling water marketers in California Central Valley seeking tall format premium positioning without incumbent converter minimum order constraints. A specialty decorating line investment with metallic finish capability unlocks energy drink segment access.
For Investors and Strategic Acquirers: Regional two-piece can plants with quick-change tooling systems present acquisition targets positioned for craft segment consolidation. Long-term viability hinges on recycled content certification infrastructure and state extended producer responsibility fee structure advantages. Monitor California, Oregon, and Maine EPR implementation timelines as inflection indicators for collection economics reshaping.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Scrap Processing Investment | EPA certification requirements reward converters with captive post-consumer aluminum remelt capacity. |
| Quick-Change Tooling System Deployment | Craft breweries in Oregon and Washington demand format flexibility without line changeover penalties. |
| Direct Smelter Partnership Establishment | Red Bull and Monster bypassing metal service centers concentrates supply chain control with brand owners. |
| State EPR Compliance Infrastructure Buildout | California fee structure advantages require verified recycled content tracking systems. |
| Digital Process Control Integration | Inline laser measurement for wall thickness below 0.004 inches reduces material waste and rejection rates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, EPA sustainable materials management documentation, and aluminum industry trade data. Primary interviews engaged can line engineering directors, beverage brand procurement leads, rolling mill technical sales managers, and scrap processor operations heads. Secondary validation drew from LME aluminum pricing archives, state extended producer responsibility legislative records, and OSHA enforcement protocol updates. Bottom-up capacity modeling triangulated against top-down beverage volume demand projections.
Forecast inputs include product type segmentation across standard, slim, tall, and custom can configurations; end-use segmentation spanning soft drinks, energy drinks, beer, and juices; material grade segmentation between recycled and primary aluminum; and distribution channel segmentation across retail, online, wholesale, and direct distributor networks. CAGRs were derived through demand elasticity modeling against aluminum price scenarios and regulatory compliance cost trajectories. Industry-specific inputs incorporate craft brewery packaging line expansion rates and energy drink PET-to-aluminum migration velocity.
Practitioners should monitor LME aluminum volatility, EPA recycled content standard enforcement intensity, and state EPR fee structure implementation for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Dispensing Carboy Market
Beverage Packaging
Cup Sleeves Market
Beverage Packaging
Media Bottles Market
Beverage Packaging
PET Syrup Bottle Market
Beverage Packaging
Disposable Water Bottle Market
Beverage Packaging
Baritainer Jerry Can Market
Beverage Packaging
Self-Cleaning Bottle Market
Beverage Packaging
Biotainer Market
Beverage Packaging
Slip Cover Cans Market
Beverage Packaging
Indonesia Plastic Bottles Market
Beverage Packaging
French Square Bottle Market
Beverage Packaging
Cardboard Flask Market
Beverage Packaging
Bamboo Cups Market
Beverage Packaging
Twin Neck Bottles Market
Beverage Packaging
Zippered Bottle Suit Market
Beverage Packaging
Multicomponent Bottle Market