
 Slip Cover Cans Market | 2026-2036
Slip Cover Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Slip Cover Cans Market Analytics
North American steel-tinplate producers is realigning capacity toward food-grade slip cover formats as beverage brand owners diversify packaging portfolios. Ball Corporation leverages vertical integration from aluminum smelting to decorated can ends, sustaining cost advantages across multiple container categories. Crown Holdings anchors its position through R&D intensity in lightweight steel alloys, while Silgan Holdings competes on manufacturing scale in the personal care segment.
Slip cover cans are cylindrical metal or composite containers with a friction-fit lid that slides over the body wall, typically manufactured from tinplate, aluminum, or polymer-lined steel with body diameters ranging from 202 to 404 standard sizes, designed for repeated opening and reclosing without tools. Their primary purpose is to preserve product freshness while enabling consumer convenience in food, beverage, and household applications. Aluminum material commands premium positioning due to infinite recyclability and lower transport weight, whereas steel tinplate dominates volume in shelf-stable food channels where oxygen barrier performance is critical. Twist-off closure formats lead in personal care applications, while snap-on designs are gaining traction in household products where child-resistant functionality matters.
FDA food contact substance regulations and EPA sustainable materials management frameworks govern material composition and end-of-life handling for slip cover cans distributed in the United States. The EU Green Deal and REACH chemical restrictions are accelerating substitution of epoxy-based interior coatings with polyester and oleoresin alternatives across European supply chains. Stakeholders must monitor evolving state-level extended producer responsibility mandates and coating chemistry transitions that will determine qualification for premium retail shelf placement.
Market Dynamics
Steel decarbonization protocols in the European Union are forcing tinplate suppliers to requalify their metallurgical processes, compressing qualified supplier pools and elevating sourcing costs for food-grade slip cover formats.
Growth Catalysts
- EU Green Deal material mandates:REACH chemical restrictions are accelerating substitution of epoxy-based interior coatings with polyester alternatives, creating upgrade cycles across European supply chains.
- Food industry resealable packaging demand:Processors of shelf-stable goods in Germany are expanding procurement of premium tinplate slip cover formats to replace rigid closures.
- Aluminum infinite recyclability:Beverage brand owners are diversifying packaging portfolios toward aluminum slip cover cans to meet EPA sustainable materials management frameworks.
Market Restraints
- Steel input cost volatility:Tinplate pricing fluctuates with iron ore and tin ingot indices, squeezing converter margins on long-dated food contracts.
- Supply concentration risk:European tinplate production clusters in German and Benelux steelworks, creating geographic vulnerability to energy price shocks.
- Polymer substitution threat:Flexible retort pouches and multilayer barrier films are capturing ambient food segments where oxygen sensitivity is moderate.
Strategic Opportunities
- Household product channel expansion:Snap-on slip cover designs with child-resistant functionality are gaining traction in North American home care applications.
- Coating chemistry regulatory tailwind:FDA food contact substance regulations favoring BPA-free alternatives are opening qualification pathways for oleoresin-lined steel formats.
- Personal care twist-off convergence:Cosmetic brand owners in South Korea are adopting metal slip cover cans to differentiate premium skincare lines from plastic competitors.
Industry Challenges
- Coating requalification timelines:FDA and EFSA parallel review processes for new interior lining chemistries extend product launch cycles by 18-24 months.
- Legacy press tooling incompatibility:Lightweight steel alloys require recalibrated forming equipment, stranding mid-tier converters with depreciated mechanical assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slip Cover Cans Market |
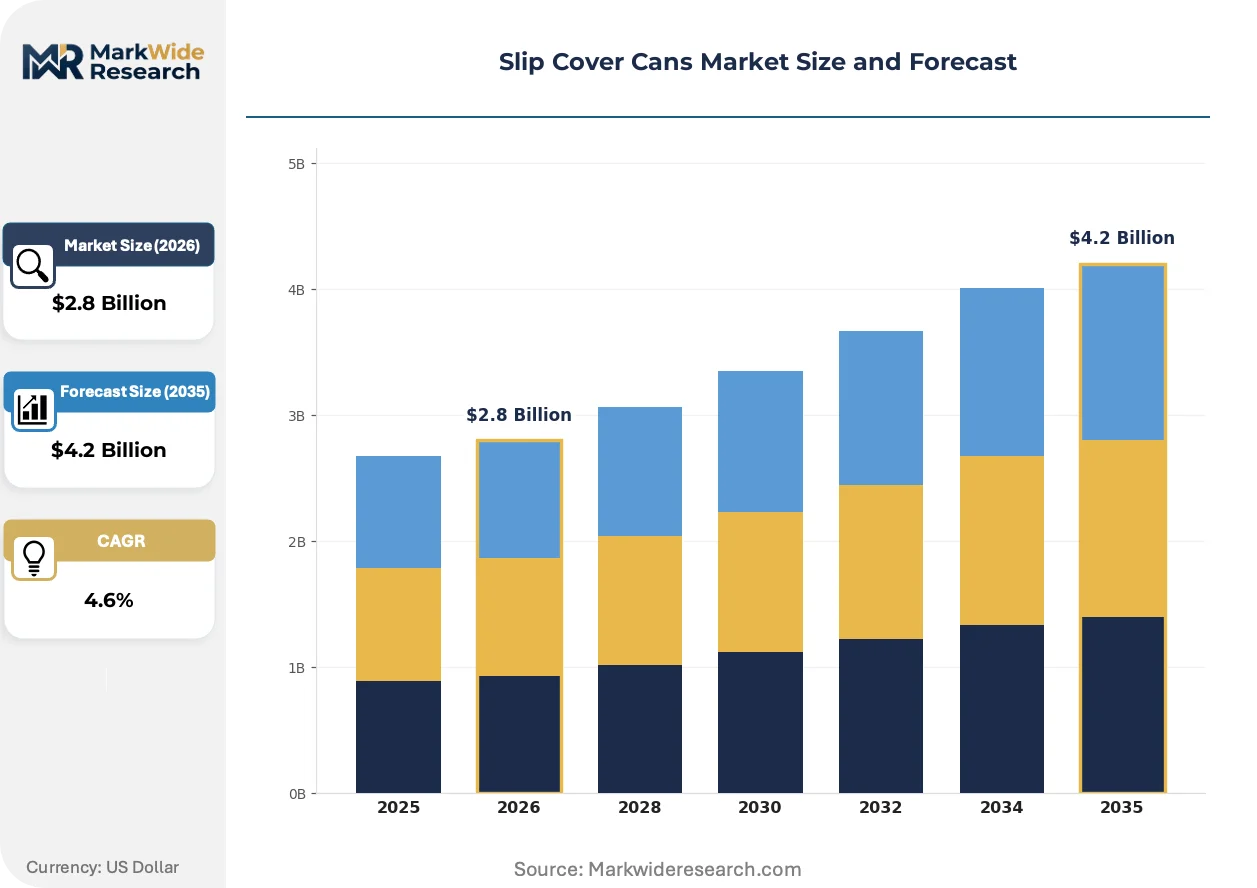
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pop-Top, Pull-Tab, Twist-Off, Snap-On Material: Aluminum, Steel, Plastic, Composite End User: Beverage Industry, Food Industry, Personal Care, Household Products Distribution Channel: Online Store, Retail Store, Wholesale, Direct Sales |
| Companies Covered | Ball Corporation, Crown Holdings, Silgan Holdings, Ardagh Group, CANPACK, Berlin Packaging, The Cary Company, Basco USA, Best Containers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slip Cover Cans Market Evolving Landscape
Digital printing on metal substrates is collapsing minimum order quantities and enabling mass customization, while coating chemistry transitions and lightweight alloy development are reshaping material specifications across food and beverage applications.
Polyester-oleoresin hybrid interior coatings are converging with high-speed canning line automation to eliminate retort discoloration while maintaining sulfur resistance. Food processors in Italy and Spain are adopting these systems at pilot scale ahead of EU coating restrictions. This convergence is compressing the qualification window for legacy epoxy formulations and elevating R&D intensity among European coating suppliers.
EPA sustainable materials management frameworks are tightening end-of-life handling requirements for metal packaging distributed in the United States. The industrial consequence is mandatory recycled content verification and chain-of-custody documentation. Food brands targeting premium retail placement are responding by sourcing exclusively from mills with certified scrap recovery programs.
Brand owner direct sourcing from integrated metal packaging producers is displacing traditional converter-distributor relationships in North American beverage markets. Regional craft breweries and specialty coffee roasters are negotiating volume commitments directly with decorated can manufacturers. This pattern is most visible in Pacific Northwest and Northeast urban clusters where brand density supports dedicated production lines.
Slip Cover Cans Market Segmentation
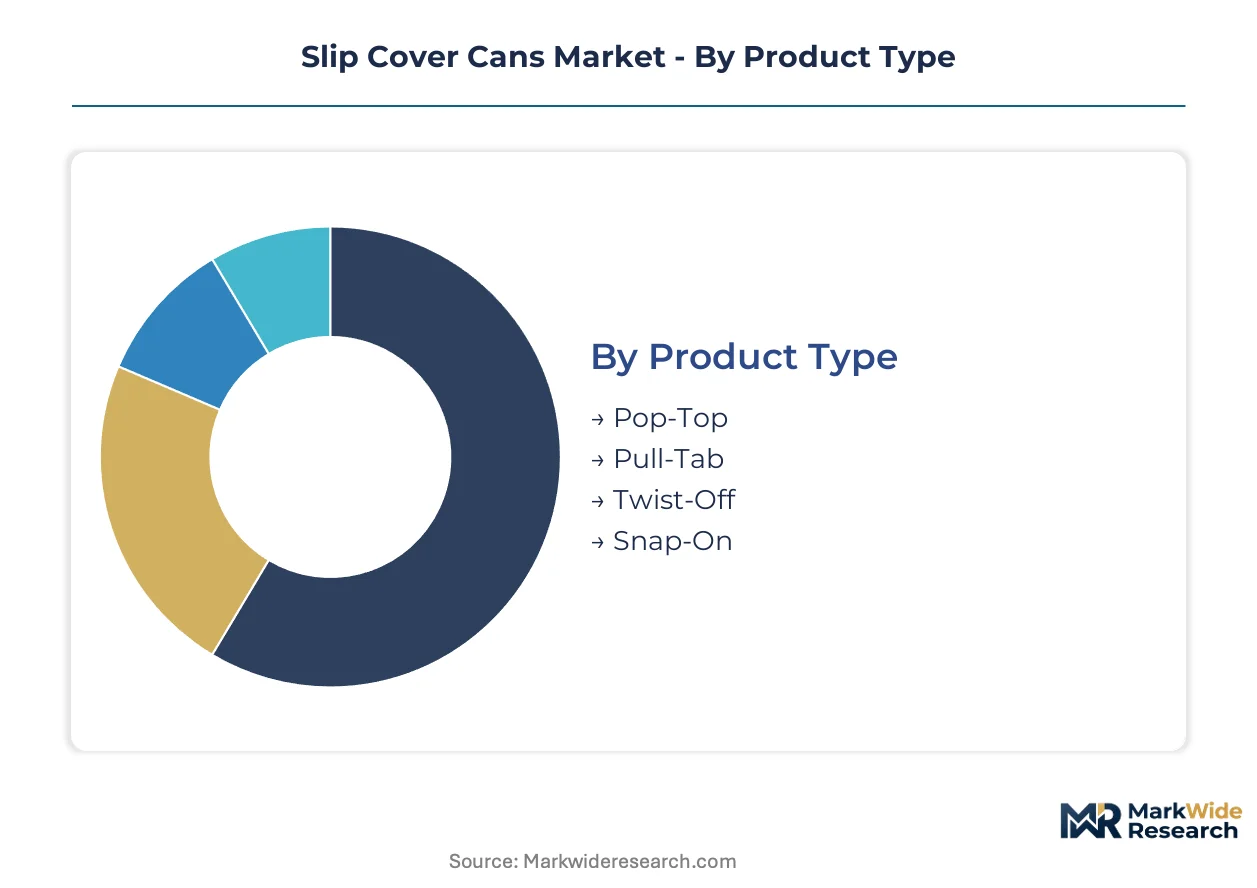
Slip cover can segmentation reveals divergent compliance burdens across closure mechanisms and material substrates. FDA food contact substance regulations and EU REACH chemical restrictions create asymmetric qualification costs that reshape competitive positioning in each category.
Product Type:
Closure format selection determines which regulatory frameworks apply—FDA 21 CFR for food-contact surfaces, EPA sustainable materials mandates for recyclability claims, and EU EFSA migration limits for interior coatings.
- Twist-Off:Threaded metal closures with gasket-sealed engagement provide repeatable hermetic seals. Personal care brand owners in South Korea favor this format for premium skincare differentiation from plastic alternatives, though EFSA coating requalification extends launch timelines.
- Snap-On:Friction-fit lids with child-resistant functionality integrate dual-action release mechanisms. North American household product manufacturers are expanding procurement of this format for home care applications where safety compliance intersects with convenience demands.
- Pop-Top:Pre-scored aluminum lids with ring-pull activation require BPA-free interior coating verification under FDA food contact substance regulations.
- Pull-Tab:Detachable metal tabs with full-aperture opening suit beverage applications where aluminum infinite recyclability supports EPA sustainable materials frameworks.
Twist-Off sits at the top of the volume ranking, with Snap-On climbing the fastest.
Material:
Raw material selection stratifies cost structures and end-use eligibility, with steel tinplate requiring REACH-compliant coating substitutions while aluminum commands transport efficiency premiums.
- Steel:Tinplate and chromium-coated substrates deliver oxygen barrier performance critical for shelf-stable food preservation. German food processors are expanding procurement of premium tinplate formats as EU Green Deal decarbonization protocols compress qualified supplier pools and elevate sourcing costs.
- Aluminum:Lightweight substrates with infinite recyclability support beverage brand owner diversification toward sustainable packaging portfolios. Pacific Northwest craft breweries negotiate direct volume commitments with decorated can manufacturers, bypassing traditional converter-distributor relationships.
- Plastic:Polymer-lined steel and all-polymer constructions face substitution pressure from flexible retort pouches in ambient food segments.
- Composite:Multilayer barrier constructions combine metal structural integrity with polymer sealing layers for moderate oxygen sensitivity applications.
Steel dominates current volume, with aluminum gaining share fastest in beverage channel expansion.
End User:
End-use verticals impose distinct performance specifications—oxygen barrier thresholds, reclosure durability cycles, and surface decoration requirements—that filter supplier qualification.
- Food Industry:Shelf-stable goods processors demand epoxy-free interior coatings as EU REACH restrictions accelerate polyester and oleoresin substitution. Italian and Spanish food processors are piloting hybrid coating systems ahead of regulatory deadlines.
- Beverage Industry:Brand owners source directly from integrated producers, collapsing traditional distribution tiers. Specialty coffee roasters in Northeast urban clusters support dedicated production lines through volume commitments.
- Personal Care:Cosmetic brand owners adopt metal slip cover formats to differentiate premium positioning from plastic competitors.
- Household Products:Home care applications favor child-resistant snap-on designs where safety functionality commands formulation compatibility.
Food Industry anchors procurement volume, with Beverage Industry expanding most quickly through direct sourcing restructuring.
Distribution Channel:
Channel configuration reflects customer scale and technical service requirements, with large-volume food processors favoring direct mill relationships while fragmented personal care brands rely on distributor intermediation.
- Direct Sales:Integrated metal packaging producers negotiate volume commitments with brand owners, displacing converter-distributor relationships. This channel concentrates in North American beverage markets where production line dedication supports urban cluster density.
- Wholesale:Regional distributors aggregate fragmented demand from mid-tier converters and private-label food processors, managing inventory risk across multiple SKU configurations.
- Retail Store:Big-box and specialty retailers stock standard-size slip cover formats for household and personal care applications with immediate fulfillment requirements.
- Online Store:E-commerce platforms serve small-batch craft producers and startup cosmetic brands with collapsed minimum order quantities enabled by digital printing on metal substrates.
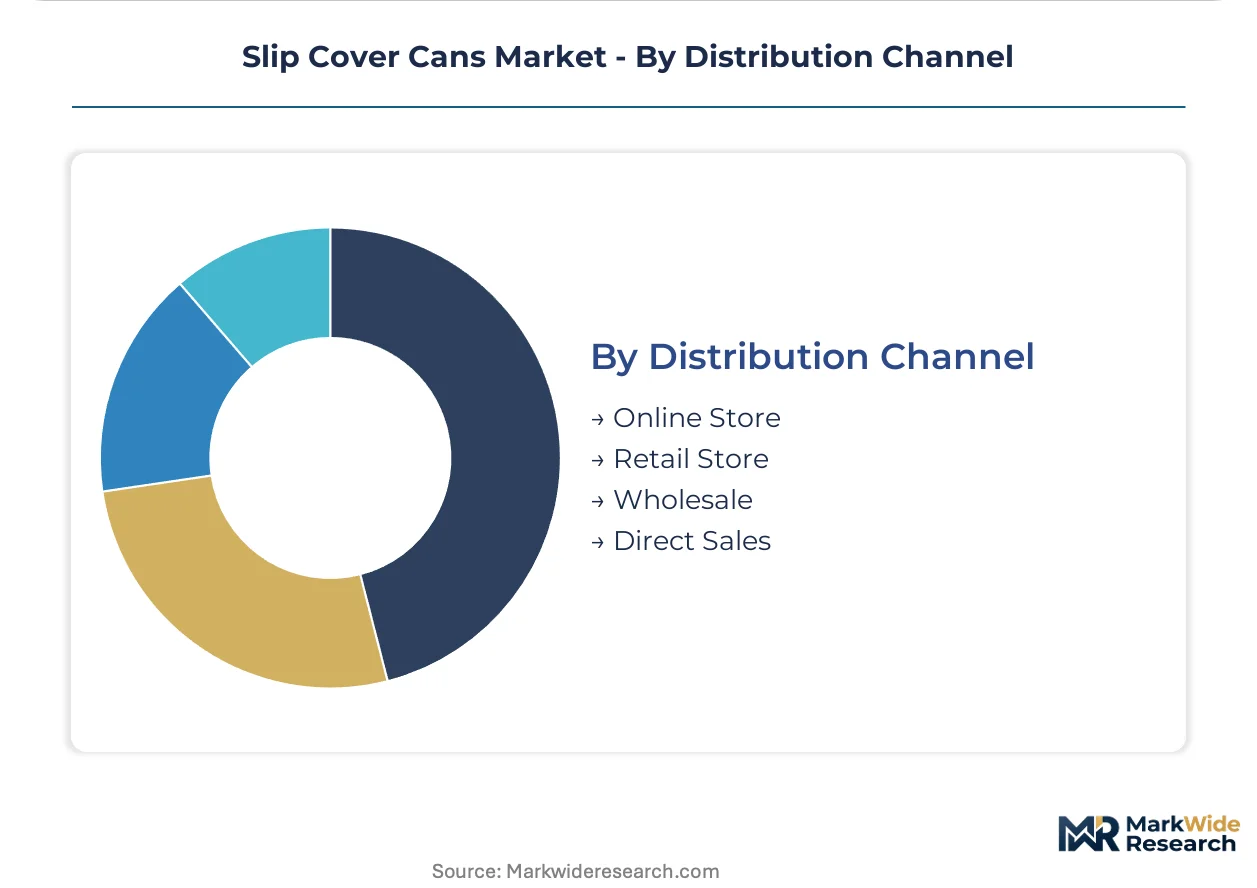
Direct Sales leads channel volume, with Online Store climbing fastest as digital printing collapses order minimums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as EU decarbonization protocols elevate compliance costs, prompting capacity migration toward jurisdictions with lower carbon-border exposure while premium food-grade demand concentrates in high-regulation markets.
United States
EPA sustainable materials management frameworks and FDA food contact substance regulations are tightening recycled content verification requirements. Beverage brand owners in the Pacific Northwest negotiate direct volume commitments with decorated can manufacturers. Specialty coffee roasters across Northeast urban clusters support dedicated production lines through consolidated procurement.
Germany
Food processors favor premium tinplate slip cover formats for shelf-stable goods as EU Green Deal steel decarbonization protocols compress qualified supplier pools. REACH chemical restrictions accelerate epoxy-to-polyester coating substitutions across Benelux-connected supply chains. Industrial concentration in the Ruhr-Rhine corridor elevates sourcing costs while maintaining quality premiums.
China
Dual carbon goals and MIIT industrial standards are forcing metallurgical requalification among tinplate suppliers serving export markets. Yangtze River Delta fabricators pivot toward lightweight alloy development for beverage applications. Domestic food brands absorb coating chemistry upgrade costs ahead of anticipated alignment with EU migration limits.
Italy
Food processors pilot polyester-oleoresin hybrid interior coatings ahead of EFSA deadline compression. Emilia-Romagna canning equipment manufacturers integrate high-speed automation to eliminate retort discoloration. Regional coating suppliers intensify R&D investment as legacy epoxy formulations face qualification window closure.
South Korea
Cosmetic brand owners adopt metal slip cover formats to differentiate premium skincare positioning from plastic competitors. MFDS cosmetic safety regulations intersect with REACH-aligned chemical restrictions on interior linings. Seoul Capital Area personal care manufacturers source twist-off closures through direct mill relationships.
Slip Cover Cans Market Competitive Landscape
North American integrated producers anchor one tier; European metallurgical specialists hold process-qualification advantages. The market structures around three to five dominant players with captive steel supply, mid-tier converters dependent on spot tinplate purchasing, and regional specialists in closure mechanism engineering. Competitive moves concentrate on backward integration into aluminum smelting and coating chemistry licensing partnerships.
Within the integrated producer tier, Ball Corporation and Crown Holdings exemplify scale-driven positioning through captive supply chain control. Silgan Holdings occupies a distinct archetype as a manufacturing-scale competitor concentrated in personal care applications. These three entities represent the dominant competitive anchors against which mid-tier converters and regional specialists calibrate differentiation strategies.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings |
| Silgan Holdings |
| Ardagh Group |
| CANPACK |
| Berlin Packaging |
| The Cary Company |
| Basco USA |
| Best Containers |
| Others |
Value Network & Pricing Analysis
Family-owned German tinplate specialists anchor the upper tier of supply, their multi-generational balance sheets enabling patient capital allocation that shields premium pricing from spot-market volatility while compressing converter margins elsewhere.
Pricing Analysis
Distributor margin compression in the wholesale tier separates commodity-grade converters from integrated producers commanding direct-to-brand pricing power. Three-tier pricing structure across premium, standard, and economy levels reflects coating chemistry certification, with FDA food-contact qualification and EU REACH epoxy-free verification commanding substantial premiums. Pricing pressure stems from tin ingot index volatility squeezing long-dated food contract profitability. Small-batch craft beverage producers exhibit highest price sensitivity, while German shelf-stable food processors absorb premiums for decarbonization-compliant tinplate.
Supply Chain Analysis
Regional distribution centers in the Ruhr-Rhine corridor, Yangtze River Delta, and Great Lakes industrial belt orchestrate hub-and-spoke patterns for tinplate coil and finished can inventory. Geographic supply concentrates in Germany, China, and the United States, with Benelux steelworks feeding European demand. Raw material dependencies center on iron ore, tin ingot, and epoxy-alternative coating resins. Single-source vulnerability runs through German tinplate requalification bottlenecks under EU decarbonization protocols. Distribution runs through direct mill relationships for large-volume food processors, with distributor intermediation serving fragmented personal care brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with German food processors shifting procurement toward premium tinplate formats that satisfy EU Green Deal steel decarbonization mandates.
For Market Incumbents: Acquire coating chemistry licensing portfolios to preempt regulatory requalification windows closing on legacy epoxy formulations. Secure captive aluminum smelting capacity or long-dated offtake agreements to buffer against tinplate input volatility. Flexible retort pouches and multilayer barrier films threaten ambient food segments, demanding defensive R&D investment in hybrid polyester-oleoresin interior coatings. For New Entrants and Emerging Players: Capture household product channel expansion in North American home care applications where child-resistant snap-on designs face limited incumbent specialization. Personal care twist-off formats in South Korean cosmetic markets offer penetrable white space against plastic-dominated competition. Digital printing-enabled mass customization supports startup cosmetic brands through collapsed minimum order quantities. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier converters stranded with depreciated mechanical assets incompatible with lightweight steel alloy forming requirements. Long-term viability hinges on coating chemistry transition completion and direct sourcing relationship displacement of traditional distribution tiers. Watch for EU EFSA parallel review process acceleration as inflection signal for qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Chemistry Licensing Partnership | Secures FDA and EFSA qualification pathways ahead of epoxy restriction deadlines. |
| Direct-to-Brand Sourcing Relationship | Pacific Northwest craft breweries negotiate volume commitments bypassing converter-distributor tiers. |
| Lightweight Steel Alloy Development | Crown Holdings anchors positioning through R&D intensity in food-grade metallurgical specifications. |
| Digital Printing Platform Investment | Collapses minimum order quantities for Italian and Spanish food processor pilot programs. |
| Backward Integration into Aluminum Supply | Ball Corporation sustains cost advantages through captive smelting to decorated can end production. |
Research Methodology
Multiple input streams — primary interviews with coating R&D directors, food processor procurement leads, and beverage brand packaging managers; secondary validation through FDA food contact substance filings, EU EFSA migration limit documentation, and SEC disclosures from integrated metal packaging producers; customs and trade flow data from German and Benelux steelworks — were reconciled through bottom-up volume modeling and top-down market sizing triangulation.
Historical volume trajectories were cross-referenced against panel input from tinplate suppliers and canning equipment manufacturers across the analysis window. Segmentation dimensions modeled include closure mechanism, material substrate, end-use vertical, and distribution channel configuration. CAGRs were derived from regression analysis of input cost indices and demand elasticity parameters, incorporating EU Green Deal compliance cost pass-through assumptions and aluminum recycling rate improvements.
Steel decarbonization protocol acceleration, coating chemistry requalification timeline compression, and polymer substitution threat intensification are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Skep Bottle Market
Beverage Packaging
Sugarcane Bottles Market
Beverage Packaging
Aluminium Cup Market
Beverage Packaging
Heavy Wall Bottles Market
Beverage Packaging
Beverage Crates Market
Beverage Packaging
Asia Pacific Beverage Packaging Market
Beverage Packaging
US Beverage Packaging Market
Beverage Packaging
Square Media Bottle Market
Beverage Packaging
Europe Beverage Container Market
Beverage Packaging
Bomber Bottles Market
Beverage Packaging
Biotainer Market
Beverage Packaging
Pouring Spout Market
Beverage Packaging
Juice Packaging Market
Beverage Packaging
Multicomponent Bottle Market
Beverage Packaging
Beverage Aluminum Cans Market
Beverage Packaging
Ice Transport Buckets Market