
 Bamboo Cups Market | 2026-2036
Bamboo Cups Market Size, Share, and Industry Trends Forecast 2026-2036
Bamboo Cups Market Outlook
Vietnam is tilting toward large-scale bamboo processing capacity as raw material costs and labor availability attract molders and finishers from higher-cost Asian bases. Oceans Republic leverages its coastal Vietnamese facilities to supply European private-label buyers with FSC-certified bamboo cup stock. MVI ECOPACK anchors its competitive stance through in-house production of both virgin and composite bamboo fiber blends. Yi Bamboo specializes in heat-resistant coatings that extend product lifespans beyond standard untreated alternatives.
Bamboo cups are molded vessels fabricated from pulverized bamboo fiber combined with food-safe binding agents, typically formed under heat and pressure into wall thicknesses ranging from 3 mm to 8 mm depending on insulation requirements; they serve as reusable alternatives to disposable beverage containers across foodservice and consumer retail channels. Double-wall construction commands the dominant share of commercial procurement because thermal performance justifies unit price premiums in cafe and restaurant settings. Printed design variants represent the fastest-growing segment as brand owners seek differentiation through direct-to-cup graphics that replace sleeve-based labeling. The insulated category remains comparatively narrow but carries concentrated margin pools in specialty beverage retail.
The EU Green Deal and REACH chemical compliance frameworks govern material safety and environmental marketing claims for bamboo cups entering European distribution channels, while the FDA maintains migration limits on binding resins for U.S.-bound food-contact applications. BIS certification requirements in India create a secondary compliance layer for exporters targeting that emerging demand base. Stakeholders must monitor how evolving compostability standards in major consuming countries reshape product formulation roadmaps and supplier qualification criteria.
Market Dynamics
EU Green Deal enforcement is compressing the viable supply base for foodservice disposables, redirecting procurement budgets toward compostable alternatives that satisfy end-of-life traceability requirements.
Growth Catalysts
- REACH chemical compliance:Binding agent restrictions favor bamboo fiber suppliers with pre-certified resin systems, accelerating qualification timelines for European distributors.
- Specialty coffee chains:Brand differentiation through visible sustainability credentials drives cup replacement programs across Germany, France, and Netherlands outlets.
- Municipal composting infrastructure:German industrial composting facilities validate product claims, closing the loop for foodservice buyers seeking verified end-of-life pathways.
Market Restraints
- Raw material concentration:Vietnam dominates bamboo fiber processing, exposing buyers to single-source supply risk during monsoon harvest disruptions.
- Melamine-formaldehyde resin costs:Food-safe binding agents face petrochemical price volatility that erodes margin stability for molded cup producers.
- Performance ceiling:Heat resistance limitations below 120°C restrict bamboo cup penetration into high-temperature beverage segments like specialty tea service.
Strategic Opportunities
- Indian institutional catering:BIS certification creates a compliance moat for early entrants targeting railway and airline procurement channels.
- Direct-to-cup printing:Digital decoration technology eliminates secondary labeling, enabling brand owners to command premium positioning in retail gift sets.
- EU CSRD reporting mandates:Scope 3 emissions disclosure requirements push foodservice chains toward supplier networks with verified carbon accounting.
Industry Challenges
- Compostability certification timelines:Industrial and home composting standards diverge across member states, forcing redundant testing protocols.
- Coating chemistry expertise:Heat-resistant surface treatments require polymer science capabilities scarce among traditional bamboo processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bamboo Cups Market |
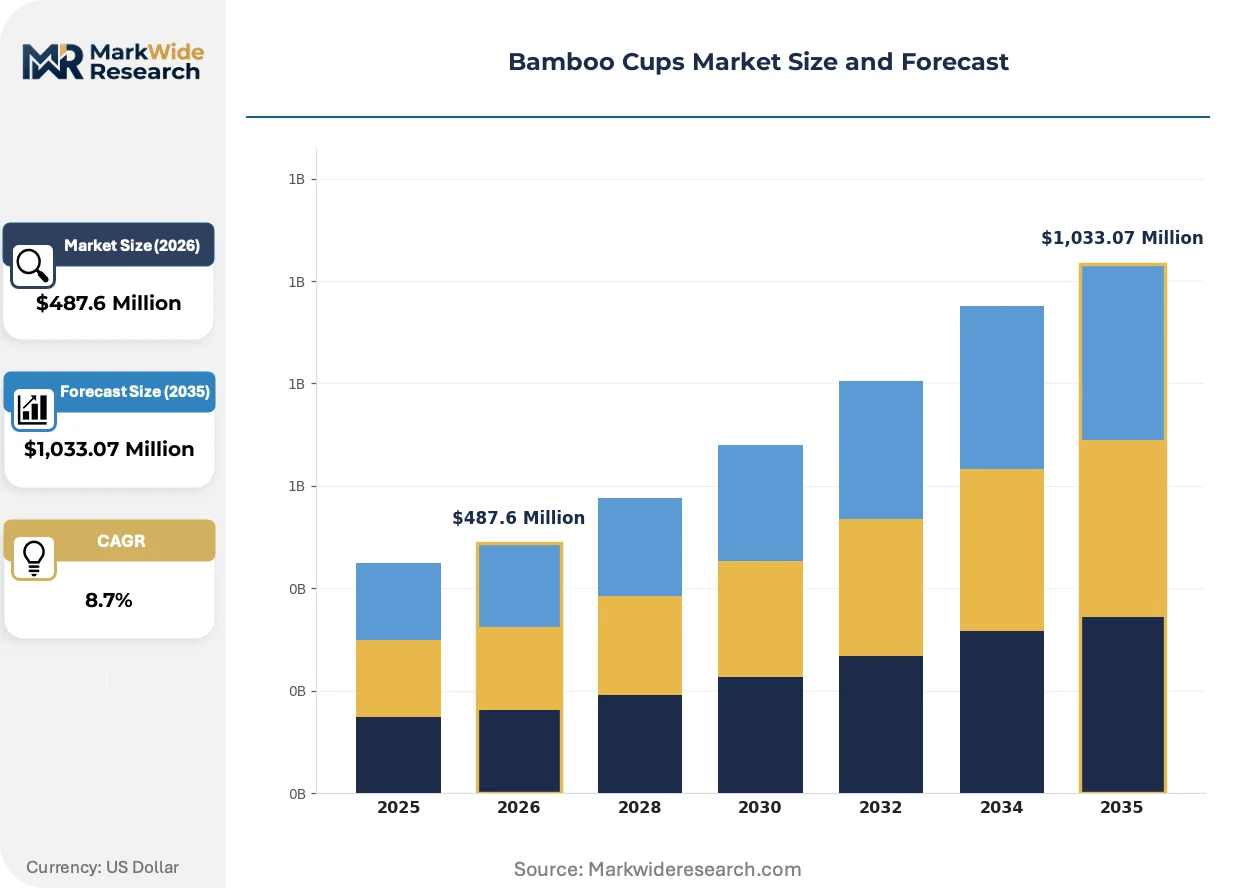
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wall, Double Wall, Insulated, Printed End User: Cafes, Restaurants, Retail Stores, Home Users Design Type: Classic, Modern, Eco-Friendly, Customized Distribution Channel: Online, Offline, Wholesale, Specialty Stores |
| Companies Covered | Oceans Republic, MVI ECOPACK, You Cheng, AnzhuCraft, Panabam, Yi Bamboo, Bamboomake, Eco-Pack, Bamboo Vision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bamboo Cups Market Strategic Shifts
Material science advances and regulatory disclosure mandates are compressing product development cycles while expanding the addressable use cases for plant-based foodservice ware.
PLA-bamboo fiber composites are collapsing the performance gap between biodegradable and petroleum-based alternatives. Specialty roasters in Copenhagen and Amsterdam are piloting these hybrid formulations for espresso service. The technology is collapsing resistance from baristas who previously rejected bamboo cups for thermal instability.
EU Green Deal packaging waste directives now mandate extended producer responsibility fees calibrated to recyclability scores. Foodservice distributors face cost penalties for non-compostable inventory, accelerating warehouse clearance of conventional plastic alternatives. German buying cooperatives are consolidating purchase volumes to secure dedicated production lines from certified molders.
Café procurement teams now require batch-level carbon footprint documentation before contract renewal. Large-format specialty chains in France and Belgium have displaced traditional RFP processes with sustainability scorecards that weight end-of-life verification above unit pricing. This pattern concentrates most visibly in Nordic markets where municipal waste authorities publish real-time composting facility performance data.
Bamboo Cups Market Segmentation
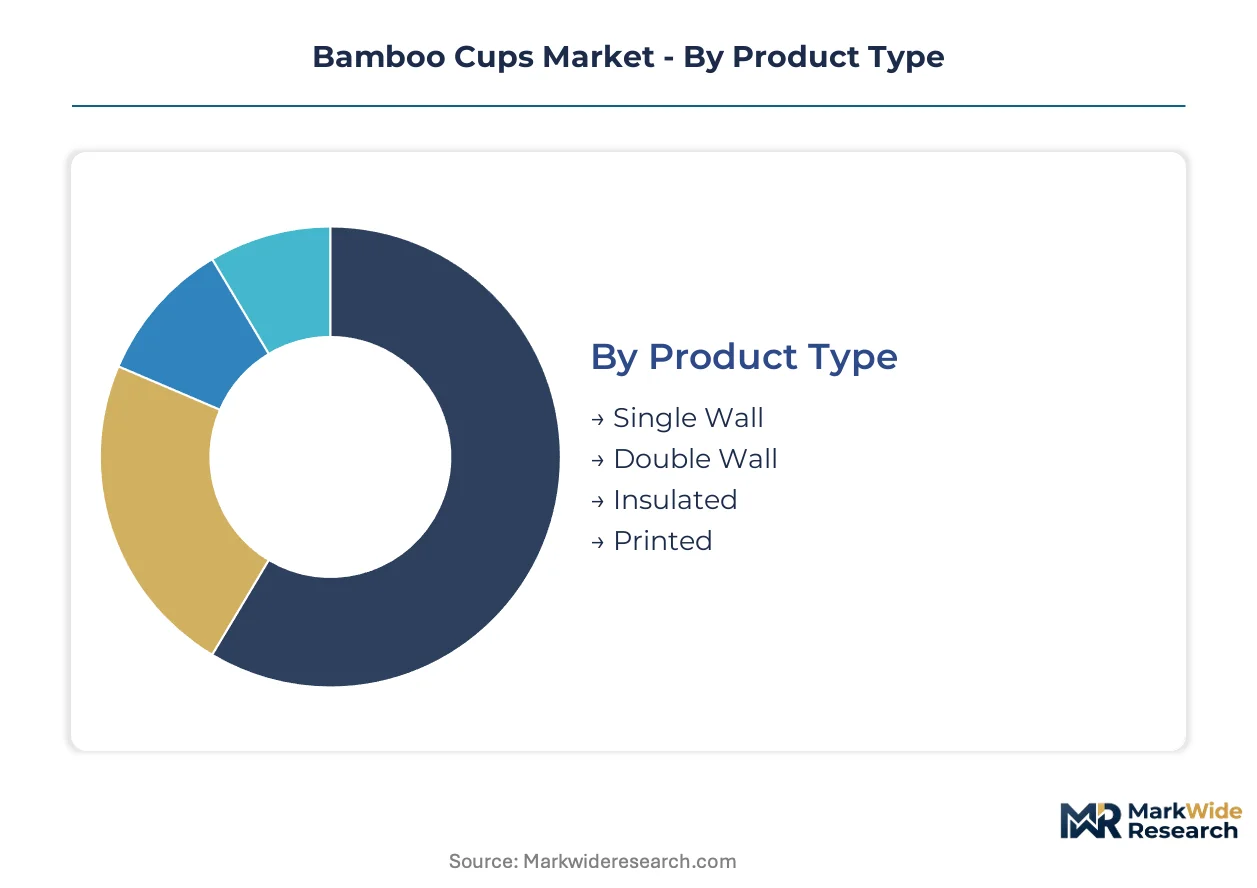
Product architecture and procurement channel choices determine margin capture and compliance burden for bamboo cup suppliers. Segmentation reveals where thermal performance justifies premium positioning versus where decoration drives retail velocity.
Product Type:
Wall construction defines thermal performance thresholds and procurement economics across foodservice and retail channels.
- Double Wall:Two-layer construction with trapped air insulation maintains beverage temperature for extended service periods. Specialty coffee chains in Germany and the Netherlands specify this format for in-house consumption, accepting unit cost premiums that eliminate sleeve accessories.
- Printed:Direct-to-surface digital decoration enables brand-specific graphics without secondary labeling. Copenhagen and Amsterdam roasters are rotating procurement toward printed variants for merchandise and gift set channels.
- Single Wall:Monolithic construction for cost-sensitive high-volume foodservice applications where thermal retention is secondary to disposability compliance.
- Insulated:Vacuum or foam-core variants for extended temperature maintenance in specialty tea and slow-consumption beverage formats.
Double wall holds installed capacity. Printed is rotating up the share rankings.
End User:
Customer procurement sophistication varies sharply across institutional, commercial, and household demand pools.
- Cafes:Front-of-house service operations require batch consistency and brand customization at volume scale. French and Belgian buying cooperatives now mandate carbon documentation before contract renewal.
- Restaurants:Full-service operators prioritize durability through dishwashing cycles and stackability for storage efficiency.
- Retail Stores:Merchandising-driven procurement emphasizing shelf appeal and gift packaging configurations.
- Home Users:Individual purchase behavior driven by sustainability signaling and aesthetic preference rather than thermal specification.
Cafes hold installed capacity. Restaurants are rotating up the share rankings.
Design Type:
Aesthetic positioning signals target demographic and price tier without altering core material composition.
- Eco-Friendly:Raw fiber visibility and minimal surface treatment appeal to sustainability-verified procurement channels. Nordic municipal buyers specify this format for public sector catering contracts.
- Customized:Bespoke geometry and private-label graphics for corporate gifting and loyalty program redemption.
- Modern:Contemporary silhouette and matte finish targeting urban retail demographics.
- Classic:Traditional cylindrical form factor for replacement of conventional ceramic and paper alternatives.
Eco-Friendly holds installed capacity. Customized is rotating up the share rankings.
Distribution Channel:
Channel selection determines margin structure, working capital requirements, and regulatory documentation burden.
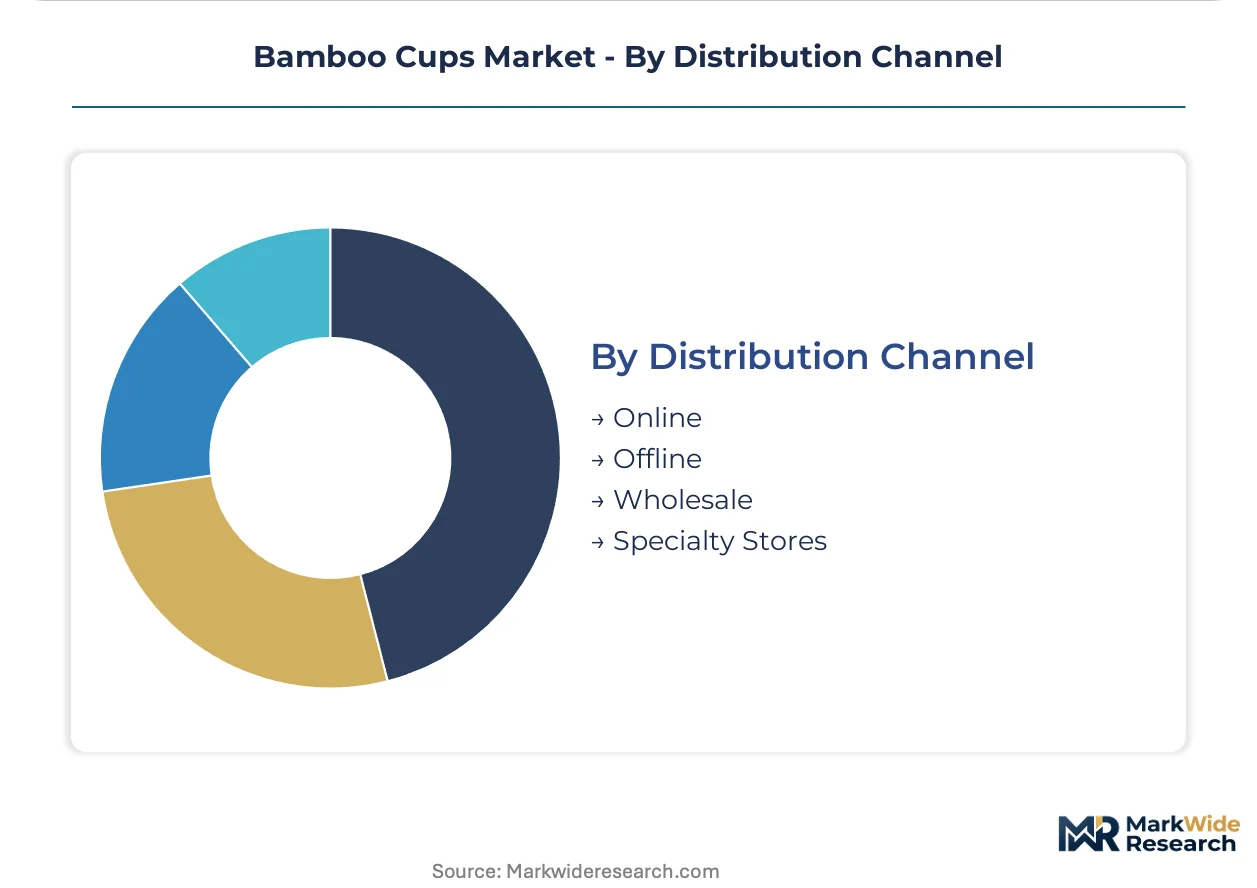
- Wholesale:Pallet-scale procurement through foodservice distributors with REACH pre-certification and batch traceability. German buying cooperatives are consolidating volumes to secure dedicated production lines.
- Online:Direct-to-consumer and B2B platform sales with compressed lead times and customization workflows.
- Offline:Physical retail presence through housewares and specialty kitchen channels.
- Specialty Stores:Curated assortment in sustainability-focused retail environments with staff-assisted selling.
Wholesale holds installed capacity. Online is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnamese coastal provinces concentrate bamboo fiber processing capacity, drawing molders and finishers from higher-cost Asian manufacturing bases. Raw material availability and labor economics anchor this supply-side clustering.
Germany
Municipal composting infrastructure validates end-of-life claims for foodservice buyers. The EU Green Deal packaging waste directives mandate extended producer responsibility fees calibrated to recyclability scores. Berlin and Hamburg buying cooperatives consolidate purchase volumes to secure dedicated production lines from certified molders.
France
Specialty coffee chains displace traditional RFP processes with sustainability scorecards weighting carbon documentation above unit pricing. REACH chemical compliance frameworks govern binding agent safety for bamboo cups entering French distribution. Paris and Lyon roasters pilot PLA-bamboo fiber composites for espresso service.
Netherlands
Café procurement teams require batch-level carbon footprint documentation before contract renewal. Amsterdam specialty roasters rotate procurement toward printed variants for merchandise channels. Dutch municipal waste authorities publish real-time composting facility performance data that shapes buyer qualification.
India
BIS certification requirements create a compliance moat for early entrants targeting railway and airline institutional catering channels. Central government procurement guidelines increasingly favor compostable foodservice ware in public sector contracts. Maharashtra and Karnataka processing clusters expand molded fiber capacity for export qualification.
United States
FDA migration limits on binding resins govern food-contact applications for bamboo cups entering U.S. distribution. California and Pacific Northwest specialty coffee markets drive retail demand for reusable alternatives. West Coast distributors face working capital pressure from petrochemical volatility in melamine-formaldehyde resin inputs.
Bamboo Cups Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with raw fiber processing and coating chemistry capabilities. The vendor base distributes across three tiers: coastal Vietnamese molders serving European private-label buyers, composite material specialists controlling resin formulation, and decoration-technology providers enabling direct-to-cup printing. Two strategic archetypes dominate: FSC-certified sustainable sourcing platforms and heat-resistant coating specialists. Capacity expansion and strategic partnerships represent the primary competitive moves, with German buying cooperatives consolidating volumes to lock dedicated production lines.
Among Vietnamese-based fabricators, Oceans Republic exemplifies the coastal processing archetype leveraging proximity to European shipping lanes. MVI ECOPACK occupies a position within the composite material tier through in-house production of virgin and blended bamboo fiber stocks. Yi Bamboo represents the coating chemistry specialization segment with heat-resistant surface treatment capabilities. These three anchors illustrate how geographic concentration, material control, and technical differentiation stratify competitive positioning.
| Leading Market Players |
|---|
| Oceans Republic |
| MVI ECOPACK |
| You Cheng |
| AnzhuCraft |
| Panabam |
| Yi Bamboo |
| Bamboomake |
| Eco-Pack |
| Bamboo Vision |
| Others |
Value Chain & Pricing Dynamics
Vietnamese coastal provinces anchor bamboo fiber processing capacity, and their expansion dynamics translate directly into downstream pricing power for European distributors negotiating long-term supply contracts.
Pricing Analysis
EU Green Deal packaging waste directives dictate the pricing tier structure across the bamboo cups market. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified double-wall variants from basic single-wall formats and uncoated commodity grades. Pricing pressure stems from melamine-formaldehyde resin cost volatility, which compresses margins for mid-tier molders. Foodservice chains demonstrate lowest price sensitivity, while retail gift-set channels exhibit highest elasticity to unit cost increases.
Supply Chain Analysis
Raw bamboo feedstock draws from plantation networks concentrated in Vietnam, China, and India. Pulverized fiber processing rests on mechanical grinding equipment and food-safe binding resin systems, with melamine-formaldehyde and PLA-bamboo composites representing alternative formulation paths. Single-source vulnerability runs through Vietnamese coastal processing clusters exposed to monsoon harvest disruptions. Distribution runs through foodservice wholesalers with REACH pre-certification and dedicated production line commitments from certified molders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bamboo cups market represents a high-growth disruption as EU Green Deal enforcement compresses viable supply bases for foodservice disposables and redirects procurement toward compostable alternatives.
For Market Incumbents: Insulate margin stability through backward integration into resin formulation capabilities and captive bamboo fiber processing in Vietnamese coastal provinces. Binding agent cost volatility threatens mid-tier producers lacking polymer science expertise. Capacity addition in Maharashtra and Karnataka processing clusters secures BIS certification moats for Indian institutional catering channels. For New Entrants and Emerging Players: Railway and airline procurement channels in India represent the most penetrable entry point given BIS certification barriers for established European suppliers. Direct-to-cup digital decoration technology for Copenhagen and Amsterdam specialty roasters offers a second white-space target. Go-to-market positioning should emphasize batch-level carbon footprint documentation to satisfy French and Belgian sustainability scorecard requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified foodservice packaging conglomerates with underutilized bamboo fiber processing assets and dormant FSC certification pathways. Long-term viability hinges on coating chemistry capabilities for heat-resistant surface treatments. The signal to watch is municipal composting facility performance data publication rates across Nordic markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Melamine-formaldehyde cost volatility threatens margin stability for molders without captive polymer production. |
| FSC Certification Investment | German buying cooperatives now mandate forest stewardship documentation before contract renewal. |
| Direct-to-Cup Printing Capability | Digital decoration eliminates secondary labeling for Copenhagen and Amsterdam roaster merchandise channels. |
| BIS Certification Pathway Development | Indian railway and airline procurement channels remain inaccessible without Bureau of Indian Standards compliance. |
| Coating Chemistry R&D Partnership | Heat-resistant surface treatments above 120°C unlock specialty tea service segments currently blocked by performance ceilings. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with bamboo fiber processors, foodservice procurement managers, coating chemistry specialists, and sustainability certification auditors; and secondary validation through customs trade records, FSC certification databases, EU Green Deal implementation tracking, and REACH compliance registries. Bottom-up volume modeling triangulated against top-down market sizing from identified supplier capacity.
Forecast inputs span wall construction type, end-user procurement channel, design aesthetic positioning, and distribution format across the analysis window. CAGRs derive from segment-level growth rate reconciliation with macro demand drivers. Binding agent cost trajectories and municipal composting infrastructure deployment schedules represent industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in petrochemical price indices and EU packaging waste directive enforcement intensity would shift the trajectory. Cross-checking against industrial composting facility capacity expansion announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Cup Filler Market
Beverage Packaging
Tumblers Market
Beverage Packaging
Slip Cover Cans Market
Beverage Packaging
Beveled Bottles Market
Beverage Packaging
Heavy Wall Bottles Market
Beverage Packaging
Bottle Dividers Market
Beverage Packaging
Self-Cleaning Bottle Market
Beverage Packaging
Europe Soft Drinks Packaging Market
Beverage Packaging
US Soft Drinks Packaging Market
Beverage Packaging
PET Bottle Market
Beverage Packaging
Media Bottles Market
Beverage Packaging
Biotainer Market
Beverage Packaging
Cup Carriers Market
Beverage Packaging
Light Water Tap Market
Beverage Packaging
United States Aluminum Beverage Cans Market
Beverage Packaging
Stackable Beaker Market