
 North America Cross Border Road Freight Transport Market | 2026-2036
North America Cross Border Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cross Border Road Freight Transport Market Analytics
Truck driver availability is bifurcating the competitive landscape between asset-heavy carriers and digital freight brokers. Knight-Swift Transportation leverages its consolidated fleet scale to sustain dedicated lane contracts across the US-Mexico border. C.H. Robinson Worldwide competes through technology-driven brokerage platforms that match fragmented shipper demand with available carrier capacity. J.B. Hunt Transport Services anchors intermodal operations through proprietary container fleets and rail partnerships.
Cross border road freight transport encompasses the movement of goods via commercial trucking across international boundaries, typically involving customs clearance, bonded carrier authority, and compliance with origin-destination weight limits up to 80,000 pounds gross vehicle weight on US federal highways. Its primary commercial purpose is to enable integrated supply chains spanning multiple sovereign jurisdictions with door-to-door delivery reliability. Full truck load services dominate volume throughput on high-frequency lanes like Detroit-Windsor and Laredo-Nuevo Laredo, while less than truck load segments capture margin concentration through consolidated customs brokerage and deconsolidation services. Refrigerated transportation mode is expanding fastest, driven by perishable agricultural exports from Mexico and temperature-sensitive pharmaceutical shipments.
The Federal Motor Carrier Safety Administration and Mexico's Secretaría de Infraestructura, Comunicaciones y Transportes jointly govern cross-border operating authority, hours-of-service reciprocity, and safety inspection standards that determine which carriers gain market access. USMCA rules of origin documentation requirements enforced by US Customs and Border Protection directly shape freight routing decisions and carrier qualification thresholds. Stakeholders must monitor evolving emissions standards from the US EPA and California Air Resources Board, as zero-emission truck mandates threaten to disrupt diesel-dependent long-haul economics on border corridors.
Market Dynamics
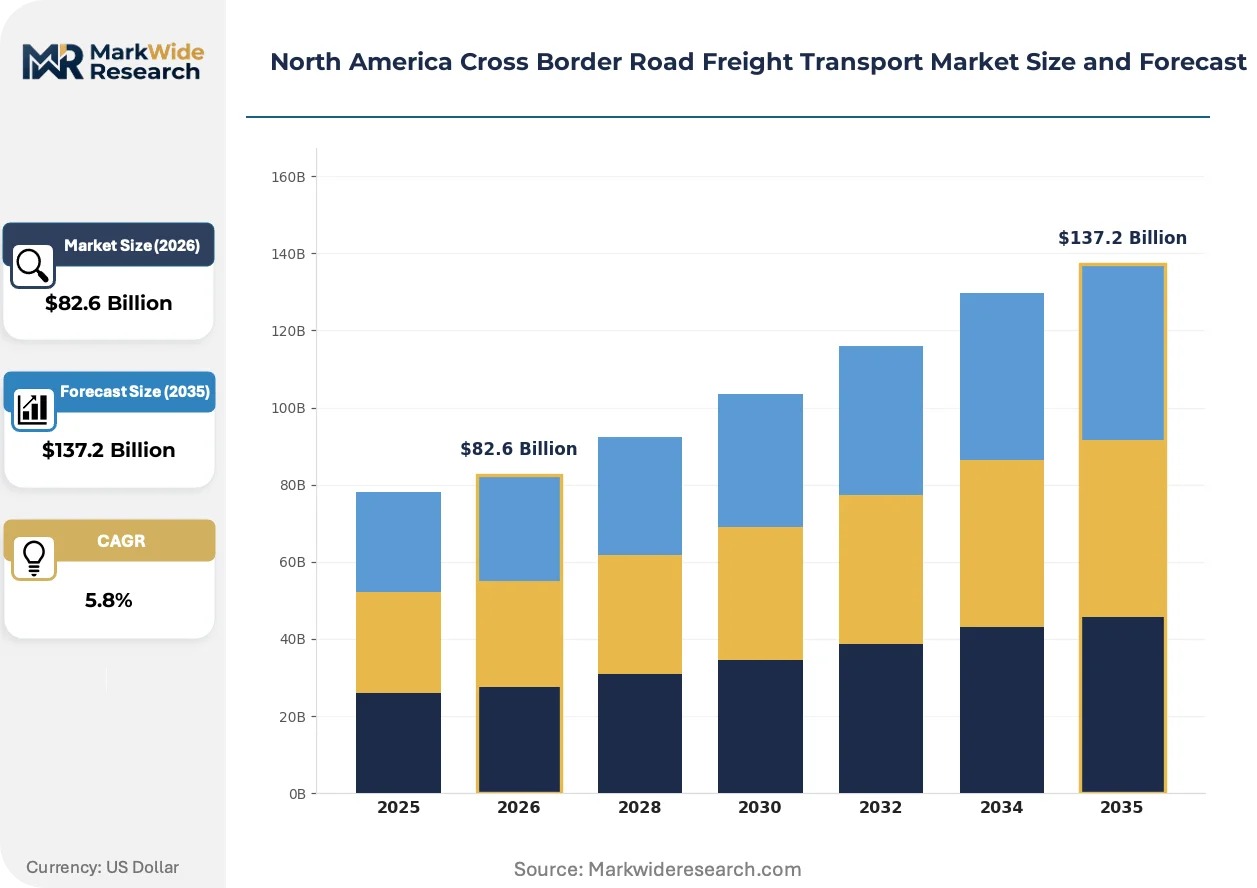
USMCA compliance mandates and zero-emission truck regulations are compressing carrier margins while forcing asset reconfiguration across the US-Mexico-Canada corridor. The tension between diesel-dependent long-haul economics and California Air Resources Board mandates is accelerating fleet turnover timelines.
Growth Catalysts
- Nearshoring Reshoring:Automotive and electronics manufacturers are consolidating supplier networks within USMCA territory to minimize tariff exposure and reduce trans-Pacific lead times.
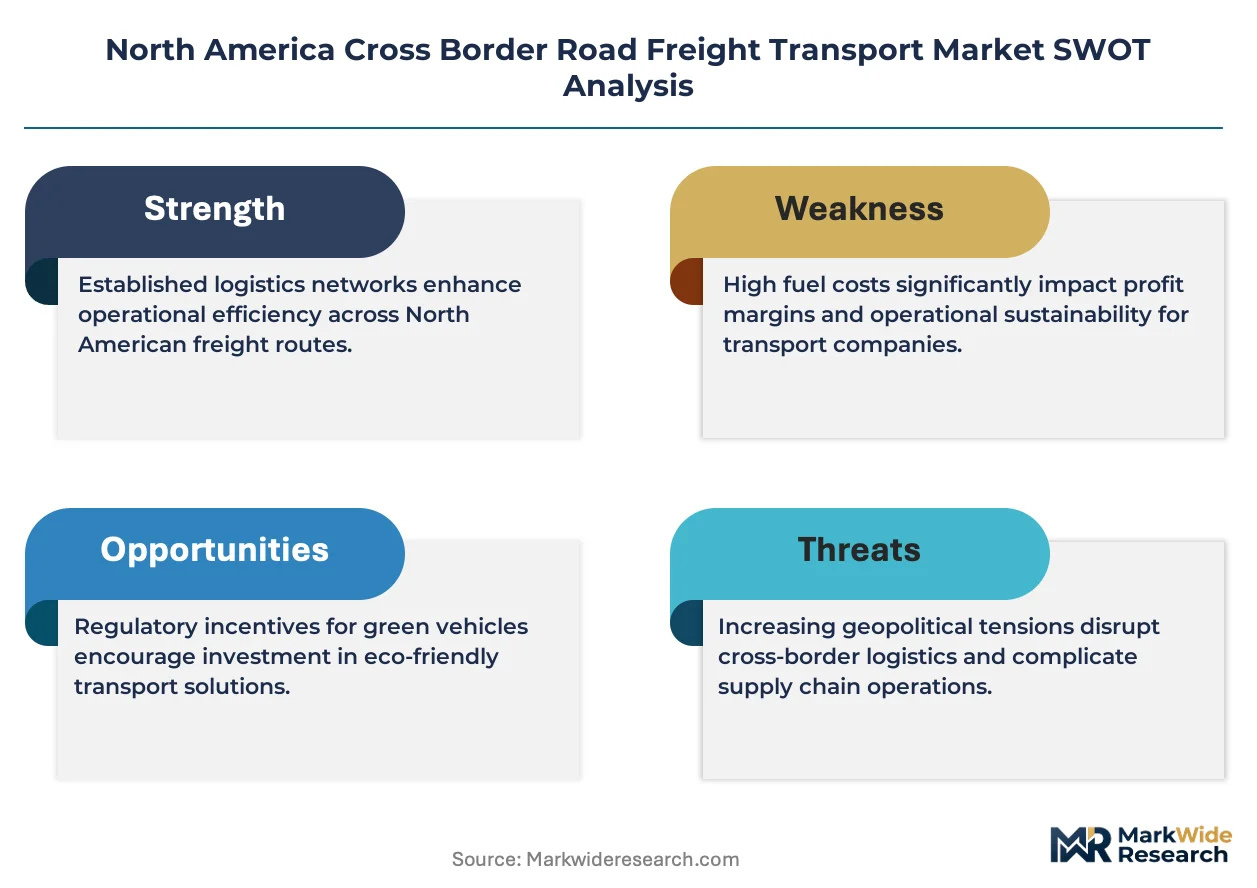
- EPA Phase 3 Standards:Stricter emissions thresholds for heavy-duty vehicles are incentivizing carriers to modernize fleets with fuel-efficient powertrains ahead of enforcement deadlines.
- Refrigerated Cross-Border Lanes:Perishable agricultural exports from Mexico's Sinaloa and Jalisco growing regions are generating dedicated temperature-controlled capacity demand through Texas border crossings.
Market Restraints
- Diesel Price Volatility:Fuel represents 25-30% of operating costs for long-haul carriers, with price spikes immediately eroding thin margin structures on competitive lanes.
- Driver Pool Contraction:The combined effect of demographic retirement and commercial driver's license issuance bottlenecks is constraining capacity expansion regardless of equipment availability.
- Customs Inspection Friction:US Customs and Border Protection secondary screening protocols at Laredo and Otay Mesa create unpredictable dwell times that disrupt just-in-time delivery commitments.
Strategic Opportunities
- Electric Truck Corridors:The Texas Triangle freight network offers 300-mile range compatibility with emerging battery-electric Class 8 tractors for regional drayage and border zone distribution.
- Bonded Warehouse Integration:USMCA rules of origin documentation requirements are creating demand for in-bond storage facilities that defer duty payment until final destination determination.
- Biometric Driver Credentialing:The Federal Motor Carrier Safety Administration's trusted traveler programs are streamlining cross-border identity verification for frequent commercial operators.
Industry Challenges
- Hours-of-Service Reciprocity Gaps:Divergent rest break requirements between US FMCSA and Mexico's SICT regulations complicate driver scheduling for continuous operations.
- Legacy Dispatch System Integration:Smaller carriers operating across the border struggle to reconcile Mexican freight forwarder platforms with US electronic logging device mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cross Border Road Freight Transport Market |
| Market Size in 2026 | $82.6 Billion |
| Market Size in 2035 | $137.2 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truck Load, Less Than Truck Load, Intermodal, Expedited End User: Retail, Automotive, Chemicals, Food & Beverage Transportation Mode: Standard, Refrigerated, Flatbed, Tanker Load Type: Dry Cargo, Hazardous Materials, Perishable Goods, Oversized Loads |
| Companies Covered | Knight-Swift Transportation, TFI International, Schneider National, Estes Express Lines, FedEx Corporation, C.H. Robinson Worldwide, United Parcel Service of America (UPS), Old Dominion Freight Line, J.B. Hunt Transport Services, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cross Border Road Freight Transport Market Evolving Landscape
Digital freight matching and autonomous vehicle pilot programs are restructuring how capacity gets priced and deployed across North American border corridors. These shifts are compressing traditional brokerage margins while opening new service categories.
Telematics-enabled predictive maintenance is bifurcating fleet economics between asset-heavy operators and technology-leveraged competitors. Large carriers with integrated sensor networks are reducing unplanned downtime by 15-20% through component-failure forecasting. This capability gap is concentrating contract awards with carriers who can guarantee uptime SLAs on automotive and pharmaceutical lanes.
The Federal Motor Carrier Safety Administration's entry-level driver training rule and Mexico's updated licencia federal requirements are harmonizing safety certification standards across the border. Carriers must now document 160 hours of combined classroom and behind-the-wheel instruction for new commercial operators. Cross-border fleets with dual-country training programs are securing preferential insurance rates and shipper qualification status.
Shippers are consolidating freight spend with fewer core carriers rather than fragmenting across spot markets. Large manufacturers in automotive and consumer electronics are awarding multi-year dedicated contracts to carriers with proven USMCA documentation expertise. This concentration is visible in the Texas-Mexico border zone, where shippers prioritize carriers with in-house customs brokerage capabilities over transactional freight matching.
North America Cross Border Road Freight Transport Market Segmentation
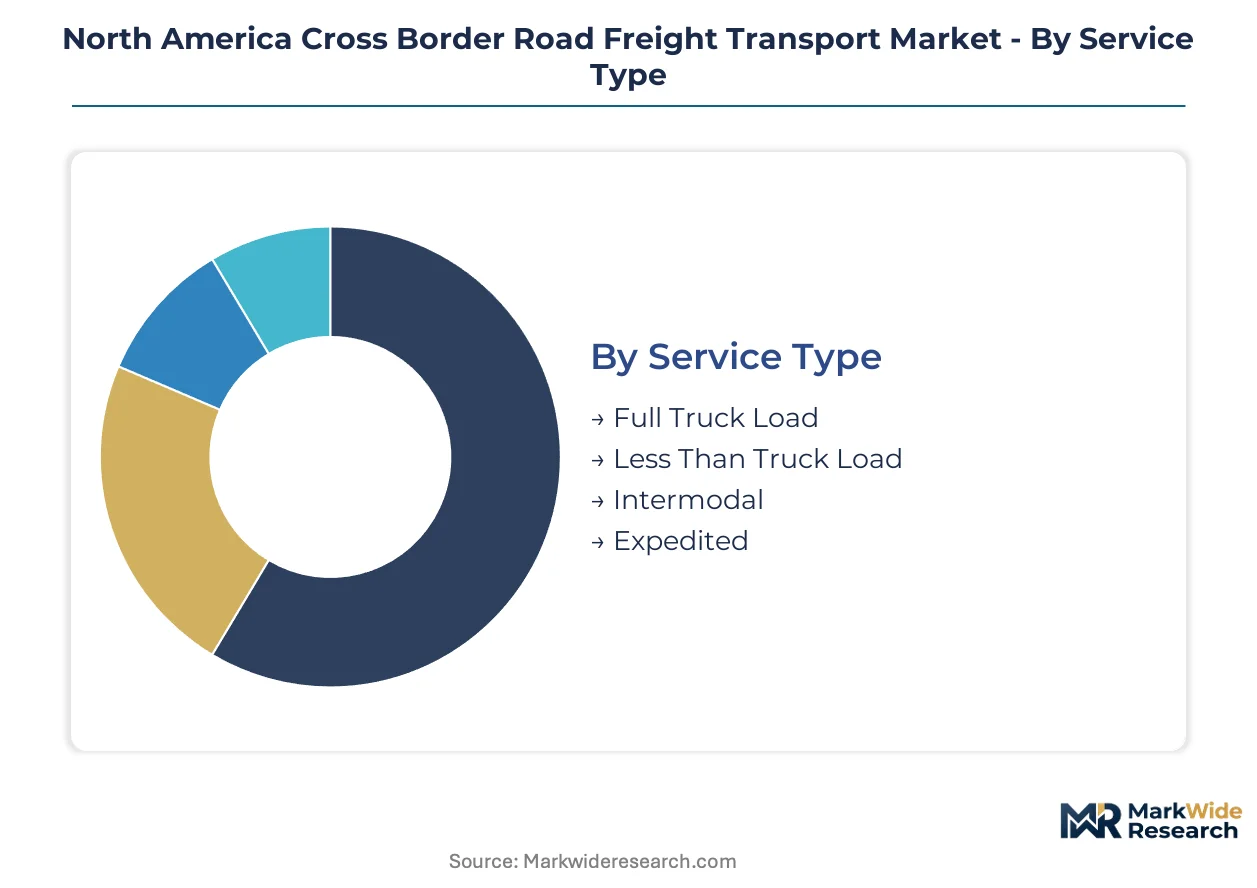
Cross-border freight segmentation reveals where carriers capture premium pricing versus commodity volume. Service configuration, cargo characteristics, and end-user requirements determine margin structure across the US-Mexico-Canada corridor.
Service Type:
Margin pools concentrate in services that bundle customs brokerage with physical transport, reducing shipper administrative burden.
- Full Truck Load:Dedicated trailer capacity moves single-shipper freight across Detroit-Windsor and Laredo-Nuevo Laredo corridors with minimal handling. Automotive manufacturers anchor demand through just-in-time production schedules that penalize delivery variance.
- Less Than Truck Load:Consolidated shipments from multiple shippers share trailer space and customs entry documentation. Retailers and small manufacturers prize the fixed-cost absorption that shared capacity provides on lower-volume lanes.
- Intermodal:Rail-truck combinations extend reach beyond direct highway corridors. J.B. Hunt's proprietary container fleet exemplifies the integrated asset control that secures long-haul contracts.
- Expedited:Time-definite delivery with dedicated driver teams commands surcharge pricing. Pharmaceutical and aerospace shippers absorb premium rates to prevent supply chain stockouts.
Full Truck Load holds installed capacity. Expedited is rotating up the share rankings.
End User:
Customer concentration patterns vary sharply by cross-border corridor density and customs complexity tolerance.
- Automotive:Tier-1 suppliers and OEMs operate synchronized assembly lines spanning Detroit, Windsor, and Mexican Bajío industrial parks. USMCA rules of origin documentation requirements disqualify carriers lacking in-house customs expertise.
- Retail:Big-box and e-commerce fulfillment networks push inventory positioning closer to US consumer markets. Seasonal volume surges through Laredo strain available capacity each fourth quarter.
- Chemicals:Hazmat certification requirements and cross-border environmental regulations constrain eligible carrier pools. Tanker and specialized equipment needs limit price competition.
- Food & Beverage:Temperature-controlled capacity from Mexico's agricultural zones requires continuous cold chain integrity. FDA and Mexico's COFEPRIS dual inspection protocols add dwell time risk.
Automotive anchors contract stability. Food & Beverage is climbing the fastest as perishable exports expand.
Transportation Mode:
Equipment specialization creates defensible niches against commoditized dry van competition.
- Refrigerated:Insulated trailers with integrated refrigeration units maintain cargo temperatures from Sinaloa growing regions through Texas distribution centers. Pharmaceutical cold chain requirements are tightening equipment specification standards.
- Standard:Dry van trailers handle non-temperature-sensitive manufactured goods and packaged consumer products. Knight-Swift's fleet scale generates operating cost advantages on high-frequency lanes.
- Flatbed:Open-deck configurations accommodate oversized machinery, construction materials, and steel coils. Securement regulations differ between US FMCSA and Mexican SICT jurisdictions.
- Tanker:Liquid and gas bulk transport requires specialized pumping equipment and hazmat endorsements. Chemical corridor density between Houston and Mexican petrochemical hubs sustains dedicated fleet investment.
Standard equipment holds installed capacity. Refrigerated is rotating up the share rankings.
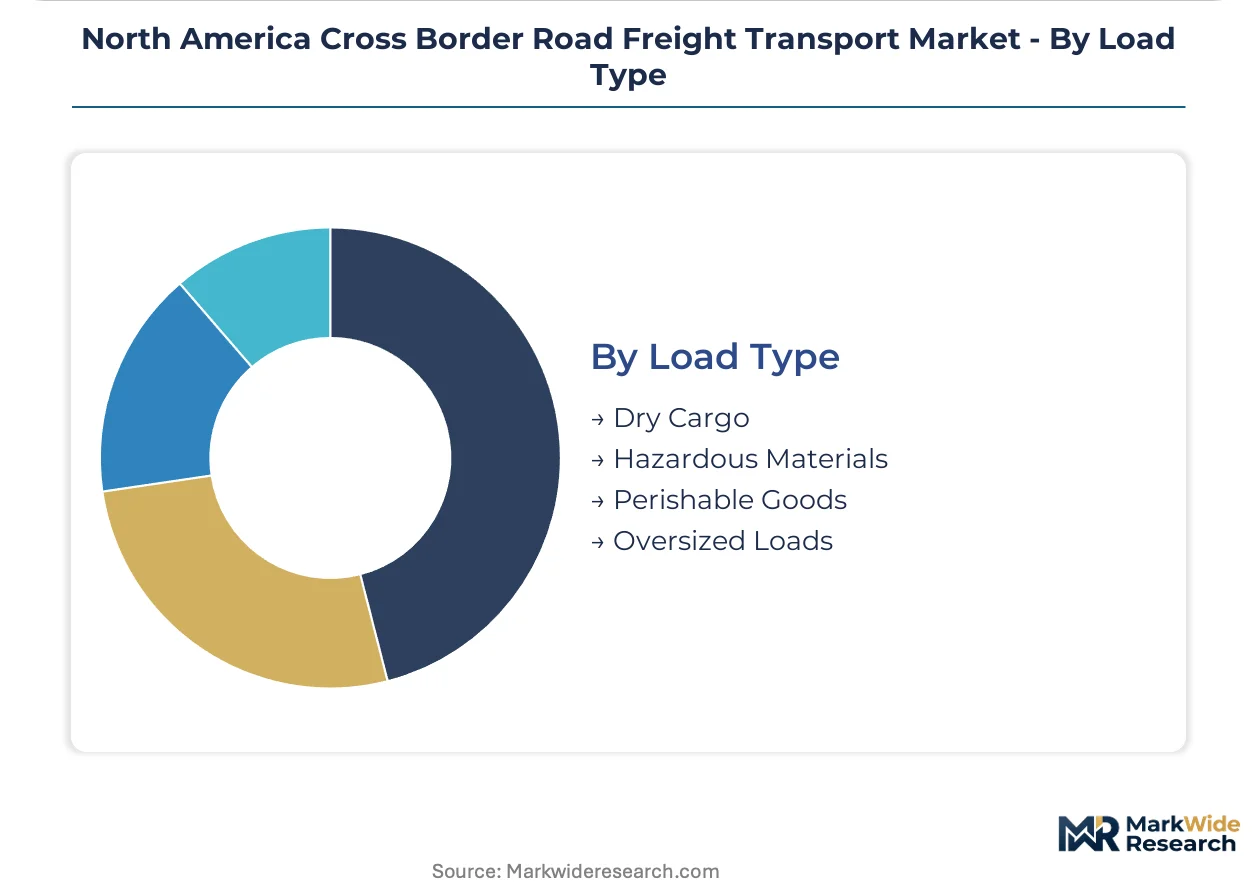
Load Type:
Cargo characteristics determine insurance, handling, and regulatory compliance cost structures.
- Perishable Goods:Time-sensitive agricultural and pharmaceutical products degrade with inspection delays. C.H. Robinson's digital brokerage matches available refrigerated capacity to shipper urgency.
- Dry Cargo:Packaged manufactured goods and consumer products tolerate longer transit windows. Consolidation potential attracts price-sensitive shippers to LTL service configurations.
- Hazardous Materials:Chemical, flammable, and toxic substances trigger dual-country permit requirements and specialized routing. Carrier liability exposure concentrates market share with established safety records.
- Oversized Loads:Dimensional and weight exceptions require escort vehicles, permit coordination, and infrastructure clearance verification. Project cargo for energy and industrial construction moves on dedicated heavy-haul equipment.
Dry Cargo holds installed capacity. Perishable Goods is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Federal Motor Carrier Safety Administration governs operating authority for carriers moving freight across the US-Mexico-Canada corridor, with compliance thresholds determining market access for cross-border operators.
United States
Automotive manufacturers anchor freight volumes through just-in-time delivery networks spanning Detroit-Windsor and Laredo-Nuevo Laredo corridors. The EPA Phase 3 emissions standards for heavy-duty vehicles are compressing fleet turnover timelines for carriers operating interstate commerce. Texas border infrastructure concentrates capacity investment, with the Laredo-Nuevo Laredo freight corridor processing the highest commercial vehicle volume between the two nations.
Mexico
Perishable agricultural exports from Sinaloa and Jalisco growing regions are generating dedicated refrigerated capacity demand through Texas border crossings. Mexico's Secretaría de Infraestructura, Comunicaciones y Transportes coordinates hours-of-service reciprocity with US regulators for continuous operations. The Bajío industrial parks host tier-1 automotive suppliers synchronizing assembly lines with US and Canadian OEMs.
Canada
Automotive parts shipments through the Detroit-Windsor corridor sustain dedicated lane contracts for carriers with cross-border bonded authority. Transport Canada harmonizes commercial vehicle safety standards with US FMCSA regulations to facilitate seamless freight movement. Ontario's manufacturing clusters in Windsor and London anchor volume throughput on the busiest Canada-US freight corridor.
California
The California Air Resources Board's zero-emission truck mandates are disrupting diesel-dependent long-haul economics for carriers serving cross-border lanes. CARB regulations phase out internal combustion engine sales ahead of federal timelines, forcing accelerated fleet reconfiguration. The Otay Mesa commercial port of entry experiences unpredictable dwell times from secondary screening protocols that disrupt just-in-time delivery commitments.
North America Cross Border Road Freight Transport Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America cross-border freight market. Asset-heavy carriers with consolidated fleet scale compete against digital freight brokers matching fragmented shipper demand with available capacity. Three strategic archetypes dominate: integrated intermodal operators with proprietary container fleets, technology-driven brokerage platforms, and specialized refrigerated carriers with temperature-controlled equipment. Competitive moves concentrate on fleet electrification partnerships and in-house customs brokerage capability expansion.
Within the integrated carrier tier, Knight-Swift Transportation, J.B. Hunt Transport Services, and C.H. Robinson Worldwide represent distinct strategic positions. Knight-Swift exemplifies scale-driven fleet consolidation enabling dedicated lane contract retention across high-frequency border corridors. J.B. Hunt anchors intermodal operations through proprietary container assets and rail partnerships extending reach beyond direct highway corridors. C.H. Robinson occupies the technology-leveraged brokerage position, matching shipper demand with available carrier capacity through digital platforms.
| Leading Market Players |
|---|
| Knight-Swift Transportation |
| TFI International |
| Schneider National |
| Estes Express Lines |
| FedEx Corporation |
| C.H. Robinson Worldwide |
| United Parcel Service of America (UPS) |
| Old Dominion Freight Line |
| J.B. Hunt Transport Services |
| Others |
Value Network & Pricing Analysis
Fleet scale economies in the Texas-Mexico border zone compress per-mile operating costs below break-even thresholds for sub-regional operators, concentrating pricing power with asset-heavy carriers while forcing smaller players toward digital brokerage margins. This scale dynamic anchors price floors on high-frequency lanes like Laredo-Nuevo Laredo, where dedicated contract rates sustain carrier viability against spot market volatility.
Pricing Analysis
Geographic price spreads widen sharply between Detroit-Windsor automotive lanes and California border corridors, reflecting divergent regulatory cost burdens and capacity utilization patterns. Contract-based long-term offtake dominates automotive and pharmaceutical verticals, where USMCA documentation expertise commands premium positioning over transactional freight matching. Price differentiation separates carriers with in-house customs brokerage from those relying on third-party intermediaries. Diesel price volatility and driver scarcity are intensifying cost compression in the standard dry van tier. Small manufacturers and seasonal retail shippers exhibit highest price sensitivity, while automotive OEMs absorb rate premiums to secure just-in-time reliability.
Supply Chain Analysis
Bridge and port infrastructure at Laredo-Nuevo Laredo and Otay Mesa creates chokepoints that concentrate carrier scheduling leverage and amplify dwell time costs across the US-Mexico corridor. Manufacturing supply clusters in Mexico's Bajío industrial parks, Texas distribution hubs, and Ontario automotive corridors anchor cross-border volume flows. Raw material dependencies include diesel fuel, refrigerated trailer units, and Class 8 tractor chassis from US and Mexican assembly plants. Tariff exposure under USMCA rules of origin enforcement threatens supply chain reconfiguration for carriers lacking bonded warehouse integration. Distribution runs through hub-and-spoke networks with rail intermodal extensions, prioritizing drayage efficiency at border crossings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-border freight services increasingly attach recurring revenue through customs brokerage retainers and compliance-as-a-service offerings, expanding faster than pure transportation margins as shippers outsource USMCA documentation complexity.
For Market Incumbents: Consolidate market position through captive customs brokerage capability and dedicated lane contract renewal. Digital freight brokers threaten margin compression on spot market lanes, requiring incumbents to deepen backward integration into bonded warehousing and in-house documentation services. Capacity concentration in the Texas Triangle freight network secures preferred shipper status against regional competitors.
For New Entrants and Emerging Players: Differentiate on refrigerated cross-border specialization and biometric driver credentialing integration. White-space opportunity concentrates in temperature-controlled lanes serving Sinaloa and Jalisco agricultural exports, where carrier qualification gaps persist. Target pharmaceutical cold chain shippers through expedited service guarantees and FDA-COFEPRIS dual inspection pre-clearance capabilities.
For Investors and Strategic Acquirers: Specialized refrigerated carriers with USMCA-compliant documentation infrastructure represent priority acquisition targets for platform rollup strategies. Long-term viability hinges on electric truck corridor readiness and hours-of-service reciprocity harmonization across the analysis window. Monitor CARB zero-emission enforcement timelines as fleet turnover inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Customs Brokerage Integration | In-house USMCA documentation capability captures shipper contract concentration and reduces third-party margin leakage. |
| Electric Fleet Transition | CARB and EPA Phase 3 compliance positions carriers for zero-emission corridor access before regulatory deadlines. |
| Biometric Credentialing Program | FMCSA trusted traveler status accelerates cross-border identity verification and reduces secondary screening dwell times. |
| Bonded Warehouse Network | In-bond storage facilities defer duty payment and attract shippers with complex rules of origin determination needs. |
| Refrigerated Capacity Expansion | Temperature-controlled equipment captures perishable agricultural export growth from Mexico's central growing regions. |
Research Methodology
Desk research of customs trade databases, carrier operating authority filings, and EPA regulatory dockets preceded structured interviews with cross-border fleet operations managers, customs brokerage directors, automotive procurement leads, and refrigerated transport specialists. Primary fieldwork captured lane-level pricing dynamics and dwell time variability at Laredo, Otay Mesa, and Detroit-Windsor corridors. Secondary validation drew from FMCSA safety measurement system data, US CBP commercial port statistics, and Transport Canada freight flow reports. Bottom-up carrier capacity modeling and top-down trade volume projections were triangulated against shipper spend consolidation patterns.
Variance decomposition across service type, transportation mode, and end-user segmentation informed volume and value outputs over the projection horizon. The analytical framework modeled full truck load, less than truck load, intermodal, and expedited service configurations against automotive, retail, chemical, and food and beverage demand verticals. CAGRs were derived from trade flow elasticity assumptions and fleet turnover timelines under evolving emissions standards. Forecast inputs incorporated diesel price trajectory scenarios and driver pool demographic projections.
Decision-makers should treat outputs as directional under stable USMCA enforcement and moderate fuel price volatility assumptions; material deviation in tariff policy or accelerated zero-emission mandates would warrant model refresh. Practitioners should keep alternative scenarios live as CARB regulatory timelines and FMCSA hours-of-service reciprocity negotiations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
China Cold Chain Logistics Market
Logistics and Shipping
Qatar Freight and Logistics Market
Logistics and Shipping
Asia Pacific International Express Service Market
Logistics and Shipping
Digital Freight Forwarding Market
Logistics and Shipping
Sweden Cold Chain Logistics Market
Logistics and Shipping
Peru Cold Chain Logistics Market
Logistics and Shipping
Courier, Express and Parcel Services Market
Logistics and Shipping
Global Container Terminal Operations Market
Logistics and Shipping
Illinois Freight and Logistics Market
Logistics and Shipping
APAC Contract Logistics Market
Logistics and Shipping
Egypt Third Party Logistics (3PL) Market
Logistics and Shipping
US Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
GCC Warehousing and Distribution Logistics Market
Logistics and Shipping
Europe Chemical Logistics Market
Logistics and Shipping
Maritime Logistics and Services Market
Logistics and Shipping
United States FTL Freight Brokerage Market