
 Fleet of Containers Market | 2026-2036
Fleet of Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Fleet of Containers Market Insights
Telematics integration is rewriting fleet economics across container shipping. Mediterranean Shipping Company leverages satellite-enabled cargo monitoring to sustain premium service tiers on Asia-Europe lanes. Maersk Line anchors its competitive position through in-house production of refrigerated units, while CMA CGM Group differentiates via LNG-ready vessel-to-container compatibility programs.
A fleet of containers comprises standardized intermodal freight boxes engineered from corrosion-resistant steel or aluminum alloys with structural corner castings for crane handling, designed to move seamlessly between ship, rail, and truck without cargo transfer. The 40 ft dry van segment dominates volume throughput on east-west trade lanes due to its optimal vessel slot utilization. Refrigerated containers command the strongest margin pools as pharmaceutical and fresh produce shippers prioritize temperature integrity over freight rates. Composite material adoption remains nascent but attracts R&D investment from operators seeking tare weight reduction on high-frequency routes.
The International Maritime Organization enforces container weight verification under the SOLAS convention, reshaping terminal gate procedures and equipment procurement standards. The EU F-Gas Regulation and California Air Resources Board rules jointly compress refrigerant choices for reefer fleets, pushing manufacturers toward CO2 or ammonia-based cooling systems. Stakeholders must monitor the divergence between regional environmental compliance timelines when positioning container procurement programs across trade networks.
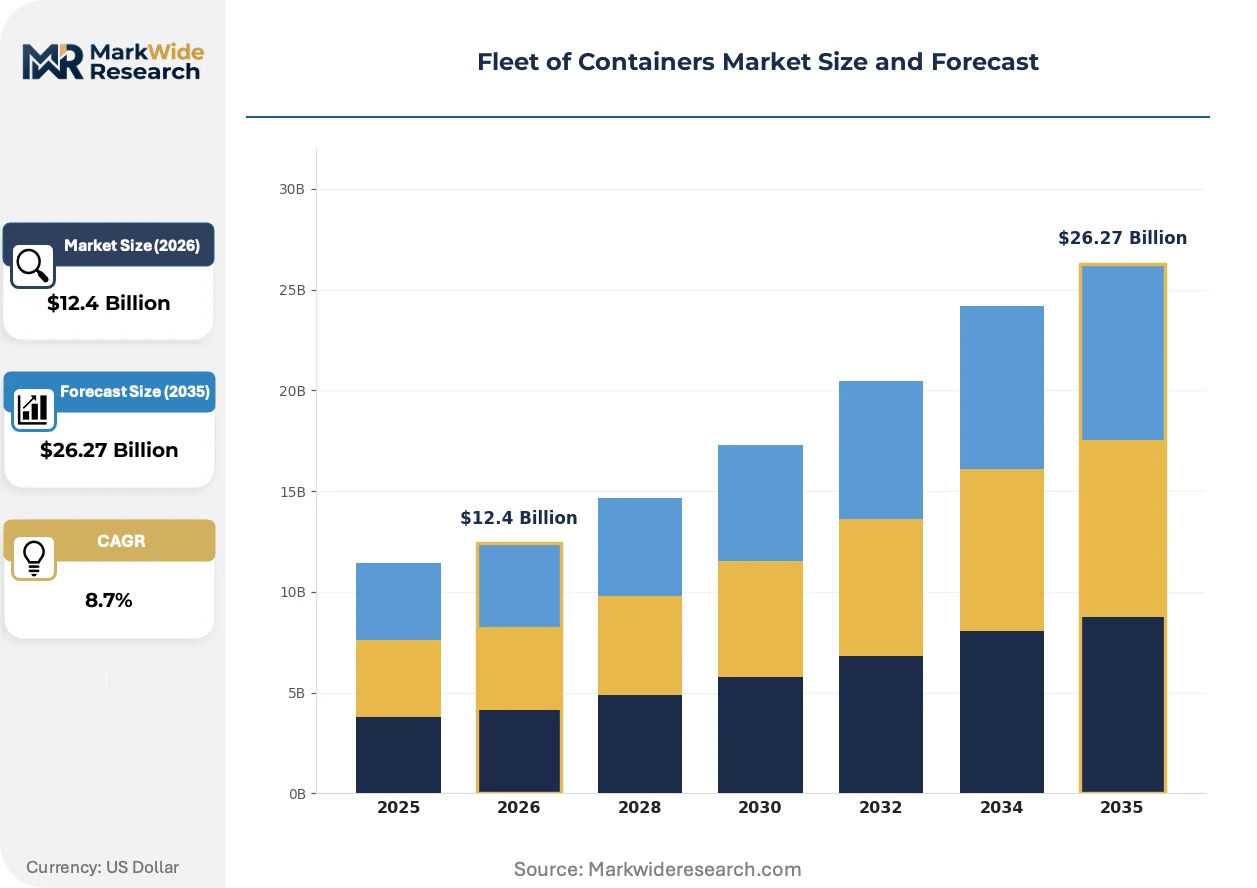
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant choices across reefer fleets, forcing operators to reconfigure procurement programs while maritime freight carriers simultaneously expand cold-chain capacity for pharmaceutical cargo. This dual pressure—environmental compliance tightening against specialized demand expansion—is restructuring fleet investment priorities.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of high-GWP refrigerants under this framework is accelerating fleet turnover toward CO2-based cooling systems, creating replacement demand across European transshipment hubs.
- Pharmaceutical cold chains:Temperature-sensitive biologics and vaccine distribution requirements are pulling refrigerated container deployment into dedicated pharmaceutical lanes with premium service tiers.
- Southeast Asian transshipment concentration:Singapore and Port Klang are absorbing disproportionate reefer investment as regional manufacturing clusters deepen integration with global shipping networks.
Market Restraints
- Aluminum alloy price volatility:Input cost swings for corrosion-resistant container shells compress manufacturing margins and destabilize long-term fleet procurement contracts.
- Refrigerant supply concentration:Limited qualified suppliers of low-GWP alternatives create bottleneck risk for reefer fleet expansion timelines.
- SOLAS weight verification compliance:The International Maritime Organization mandate adds terminal gate friction and equipment certification overhead that slows container throughput velocity.
Strategic Opportunities
- Composite material adoption:Tare weight reduction through fiber-reinforced polymer panels offers fuel savings on high-frequency intra-Asia routes where vessel slot optimization drives carrier economics.
- Telematics-enabled cargo monitoring:Satellite connectivity integration creates service differentiation opportunities for premium freight segments requiring real-time temperature and location visibility.
- LNG-ready vessel compatibility:Dual-fuel ship deployment is pulling demand for container fleets engineered to harmonize with alternative propulsion infrastructure investments.
Industry Challenges
- Refrigeration technician scarcity:Specialized skills for CO2 and ammonia-based system maintenance lag fleet deployment schedules, creating service coverage gaps in secondary ports.
- Certification timeline compression:Divergent regional environmental compliance schedules force manufacturers to maintain multiple equipment variants, fragmenting production scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fleet of Containers Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Container Type: Dry Van, Refrigerated, Tank, Open Top Material: Steel, Aluminum, Fiberglass, Composite Size: 20 ft, 40 ft, 45 ft, 53 ft End User: Retailers, Wholesalers, Logistics Providers, Manufacturers |
| Companies Covered | Mediterranean Shipping Company (MSC), Maersk Line, CMA CGM Group, COSCO Shipping Lines, Hapag-Lloyd, Evergreen Marine Corporation, Ocean Network Express (ONE), Yang Ming Marine Transport Corporation, Hyundai Merchant Marine (HMM), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fleet of Containers Market Trends and Innovations
Reefer container engineering is pivoting from mechanical compression toward alternative cooling architectures as regulatory pressure intersects with energy efficiency imperatives. Equipment manufacturers and maritime operators are racing to field compliant systems before phase-out deadlines harden.
Transcritical CO2 refrigeration is hybridizing conventional reefer architectures by integrating gas cooler technology with electronic expansion valve control. Pharmaceutical shippers and fresh produce exporters are specifying these units for newbuild orders despite 15-20% capital premiums. The technology is hybridizing fleet procurement standards, compressing the viable lifecycle of HFC-dependent equipment already in service.
California Air Resources Board rules are layering additional refrigerant constraints onto the EU F-Gas framework, creating a trans-Atlantic regulatory floor that equipment manufacturers must engineer against. Reefer fleets serving trans-Pacific lanes face dual compliance burdens that favor unified low-GWP platform designs. The California rules are accelerating adoption of natural refrigerant systems most aggressively among carriers with heavy US West Coast exposure.
Shippers are unbundling temperature integrity guarantees from base freight contracts, creating standalone cold-chain service tiers with separate pricing and liability structures. Large pharmaceutical distributors and perishable commodity traders are driving this bifurcation, seeking audited chain-of-custody documentation that standard freight terms do not provide. This unbundling is most advanced on Asia-Europe lanes where cargo value density justifies premium service segmentation.
Fleet of Containers Market Segmentation
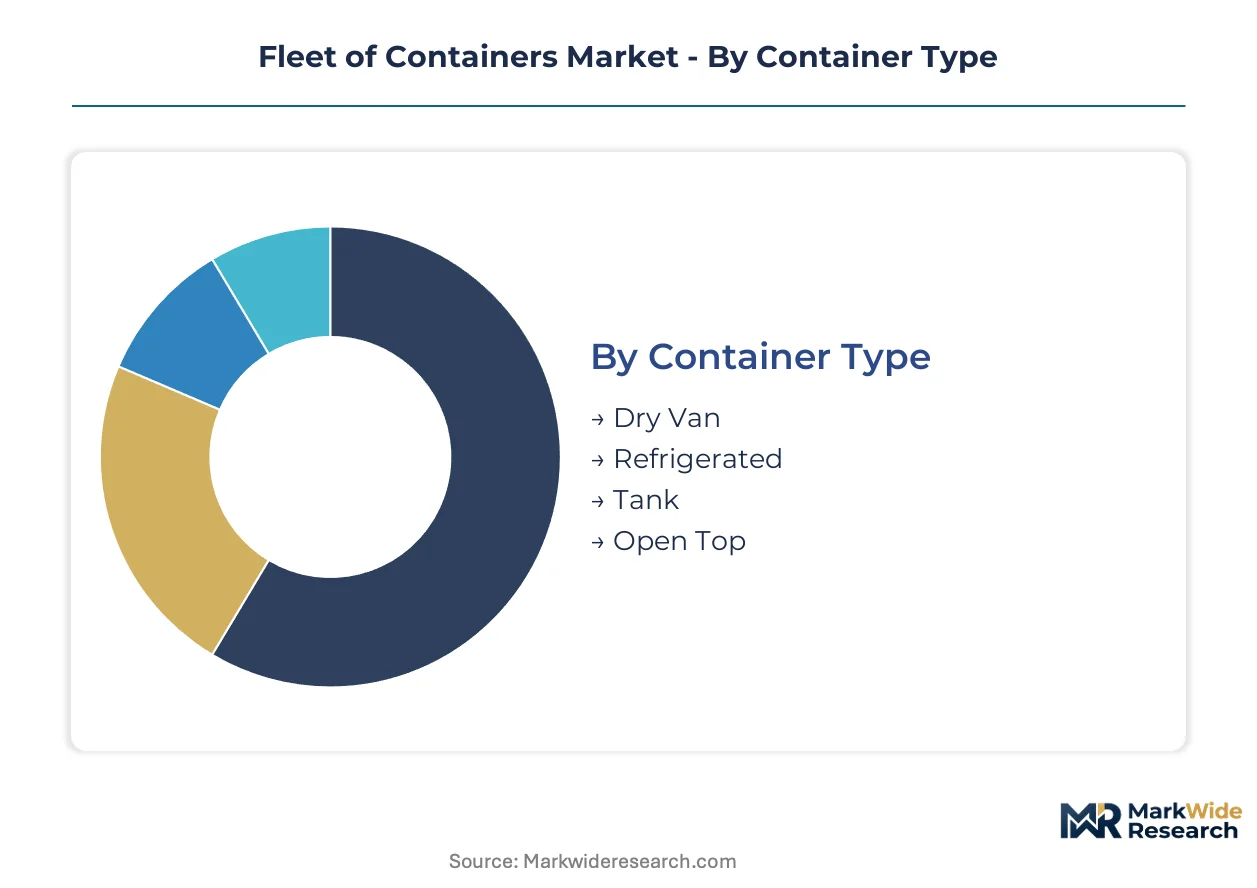
Container fleet segmentation reveals how cargo characteristics, infrastructure constraints, and regulatory pressures fragment procurement strategies across maritime and intermodal networks. Equipment specifications diverge sharply between commodity bulk flows and temperature-sensitive pharmaceutical lanes, forcing carriers to maintain heterogeneous fleet portfolios.
Container Type:
Dry van units handle standardized palletized cargo across the full trade lane spectrum, while specialized formats address liquid bulk, temperature control, and oversized dimensional requirements.
- Dry Van:Corrosion-resistant steel enclosures with structural corner castings dominate trans-Pacific and Asia-Europe volume throughput. Retail replenishment cycles and e-commerce fulfillment networks in Singapore and Port Klang absorb the highest deployment density on east-west strings.
- Refrigerated:Active cooling systems with transcritical CO2 architectures preserve pharmaceutical cold chains and fresh produce integrity. The EU F-Gas Regulation accelerates fleet turnover toward natural refrigerant platforms, compressing residual value of HFC-dependent units already in service.
- Tank:Cylindrical stainless steel or aluminum vessels transport liquid chemicals, food-grade oils, and compressed gases. Chemical manufacturers in Rotterdam and Houston anchor procurement demand for IMO-certified hazardous cargo configurations.
- Open Top:Removable tarpaulin roofs accommodate heavy machinery and project cargo exceeding standard door dimensions. Construction equipment exporters in Shanghai and Hamburg drive spot charter premiums for this low-volume, high-margin segment.
Established volume favors dry van; emerging adoption favors refrigerated.
Material:
Shell composition trades acquisition cost against tare weight, corrosion resistance, and repair cycle frequency across different route intensities.
- Steel:Corten-grade weathering alloys deliver lowest unit cost for dry van construction. High-frequency intra-Asia feeders favor steel for its damage tolerance and spot-weld repairability in secondary ports.
- Aluminum:Lightweight alloys reduce tare weight for refrigerated units where fuel burn on cooling compressors compounds vessel fuel consumption. Price volatility in aluminum ingot markets destabilizes long-term manufacturing contracts.
- Fiberglass:Reinforced polymer panels offer intermediate weight reduction with superior thermal insulation properties. Reefer manufacturers in South Korea deploy fiberglass for premium pharmaceutical service tiers.
- Composite:Carbon-fiber hybrid laminates achieve maximum tare reduction for high-frequency shuttle routes. R&D investment concentrates on Japan-flagged carriers seeking slot optimization on intra-Asia strings.
Steel dominates procurement volume; composite attracts development capital.
Size:
Dimensional standards align with vessel slot configurations, rail loading gauges, and chassis compatibility across modal interchange points.
- 20 ft:Twenty-foot equivalent units optimize weight-constrained cargo and dense commodity flows. Australian mineral exporters and West African project cargo operators specify this format for heavy lift applications.
- 40 ft:Forty-foot high-cube dimensions maximize vessel slot utilization on mainline east-west services. Pharmaceutical distributors in Basel and Singapore specify 40 ft reefers for temperature-controlled biologics distribution.
- 45 ft:Extended length accommodates European road trailer interchange without cargo transfer. EU inland logistics providers favor 45 ft units for continental rail-road intermodal shuttles.
- 53 ft:North American domestic standard aligns with US Class I railroad loading profiles and highway weight limits. Domestic US intermodal operators deploy 53 ft containers for retail distribution from Los Angeles to Chicago corridors.
Forty-foot units anchor ocean carrier economics; fifty-three-foot formats capture domestic US volume.
End User:
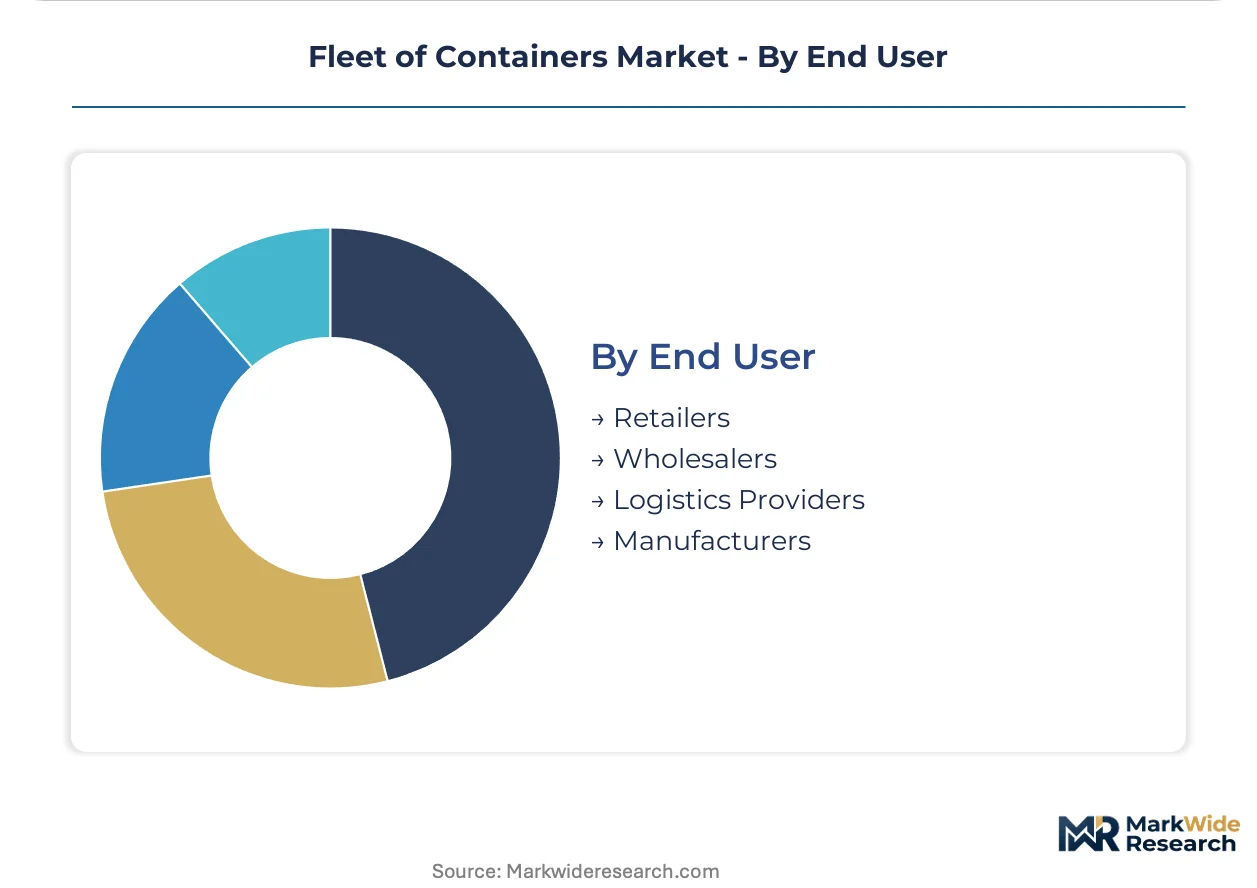
Stakeholder procurement patterns diverge between asset ownership models and outsourced fleet management arrangements.
- Retailers:Large-format merchandisers maintain dedicated container pools for inventory replenishment cycles. Walmart and Carrefour specifications drive standardization in dry van door width and flooring systems.
- Wholesalers:Agricultural commodity traders require flexible reefer access for seasonal harvest windows. Brazilian soybean exporters and Chilean fruit cooperatives charter refrigerated capacity on spot markets.
- Logistics Providers:Third-party operators aggregate shipper demand across multiple trade lanes. DHL Supply Chain and Kuehne+Nagel negotiate fleet scale discounts with equipment lessors.
- Manufacturers:Industrial producers secure captive container pools for just-in-time component supply. German automotive tier-one suppliers deploy dedicated 40 ft units for Mexico assembly plant feeds.
Logistics providers intermediate the largest equipment volumes; manufacturers pursue captive fleet control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports containerized manufacturing output to European and North American consumer markets through Singapore and Port Klang transshipment hubs. This trade corridor anchors reefer fleet deployment for pharmaceutical and electronics cargo. Regulatory divergence across destination markets forces carriers to maintain multi-compliant equipment configurations.
United States
Pharmaceutical distributors in New Jersey and California drive demand for temperature-controlled container services. The EPA and California Air Resources Board enforce refrigerant phase-down schedules that compress HFC equipment lifecycles. Los Angeles-Long Beach port complex absorbs premium reefer investment for Asia-Pacific import flows.
Germany
Automotive component manufacturers in Bavaria and Baden-Württemberg secure dedicated dry van pools for just-in-time supply chains. The EU F-Gas Regulation mandates CO2-based cooling systems for reefer fleets operating European lanes. Hamburg port infrastructure supports transcritical refrigeration maintenance capabilities for North Sea services.
Singapore
Regional headquarters of multinational logistics providers concentrate reefer procurement decisions for Southeast Asian manufacturing networks. The Maritime and Port Authority coordinates environmental standards with IMO conventions. Tuas mega-port development is absorbing disproportionate investment in automated container handling and cold-chain infrastructure.
China
Electronics exporters in the Pearl River Delta and Yangtze River Delta generate high-frequency container demand for trans-Pacific routes. MIIT and SAMR administer equipment certification standards that align with international maritime conventions. Shanghai port maintains the world's largest container throughput volume, driving slot optimization investments across carrier fleets.
Netherlands
Flower and perishable commodity traders in the Randstad region specify reefer units with precise temperature control for auction distribution networks. The EU F-Gas Regulation accelerates fleet turnover toward natural refrigerant platforms. Rotterdam port infrastructure integrates barge-rail-truck intermodal connections for continental distribution.
Fleet of Containers Market Competitive Landscape
On the supply side, the industry is consolidating around scale-driven maritime carriers with captive equipment production capabilities and specialized lessors serving niche temperature-controlled segments. Strategic archetypes include integrated ocean carriers owning manufacturing subsidiaries, independent container lessors with global depot networks, and regional specialists focusing on pharmaceutical cold-chain certification. Competitive moves center on vertical integration into equipment manufacturing and telematics-enabled service tier differentiation.
Among integrated ocean carriers, Mediterranean Shipping Company, Maersk Line, and CMA CGM Group represent the dominant equipment ownership archetype. These Geneva-based, Copenhagen-based, and Marseille-based entities exemplify carriers that internalize container production decisions rather than relying on third-party lessors. Their positioning reflects a strategic preference for captive supply of refrigerated and dry van units to secure slot utilization economics on core trade lanes.
| Leading Market Players |
|---|
| Mediterranean Shipping Company (MSC) |
| Maersk Line |
| CMA CGM Group |
| COSCO Shipping Lines |
| Hapag-Lloyd |
| Evergreen Marine Corporation |
| Ocean Network Express (ONE) |
| Yang Ming Marine Transport Corporation |
| Hyundai Merchant Marine (HMM) |
| Others |
Pricing and Supply Chain Analysis
Shanghai's concentrated reefer manufacturing base wields asymmetric pricing power over European and North American carriers, translating capacity tightness into premium surcharges for transcritical CO2 units. The Pearl River Delta's vertical integration into compressor assembly compresses procurement timelines but amplifies cost pass-through when aluminum alloy markets spike.
Pricing Analysis
HFC-dependent reefer units trade at 15-20% discounts to transcritical CO2 platforms, with next-generation ammonia architectures commanding additional premiums for pharmaceutical certification tiers. Pricing stratifies across premium pharmaceutical-grade, standard fresh-produce, and economy dry-van tiers, with certification level and after-sales service bundling as primary differentiation levers. Cost compression in standard reefers is intensifying because refrigerant supply concentration limits qualified vendor pools. Pharmaceutical distributors exhibit lowest price sensitivity; spot-market agricultural traders drive aggressive rate negotiation.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for container manufacturers serving trans-Pacific lanes. Production gravity centers on China, South Korea, and Japan for finished units, with Germany anchoring European final assembly. The supply chain draws from aluminum alloy ingots, corrosion-resistant steel coils, and electronic expansion valve components. Single-source vulnerability concentrates in transcritical CO2 compressor manufacturing. Distribution runs through maritime carrier direct procurement programs and specialized lessor depot networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized refrigeration technician pipelines are failing to match fleet deployment velocity, creating a widening capability gap that rewards operators with in-house training infrastructure. This scarcity dynamic favors stakeholders who secure maintenance certification networks before competitor lock-in.
For Market Incumbents: Insulate refrigerated fleet margins by accelerating backward integration into CO2 compressor servicing capabilities, countering the technician scarcity threat. Lock in long-term aluminum supply contracts with South Korean smelters before spot volatility returns. Prioritize certification investment for EU F-Gas and California Air Resources Board dual compliance to maintain trans-Pacific lane access. For New Entrants and Emerging Players: Build out composite material reefer manufacturing for intra-Asia high-frequency routes where tare weight reduction commands fuel-saving premiums. Target Southeast Asian transshipment hub expansion as the most penetrable geography, with Singapore and Port Klang absorbing disproportionate cold-chain investment. Lead with telematics-enabled cargo monitoring as a differentiated service tier for pharmaceutical distributors. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because environmental phase-down timelines guarantee replacement demand regardless of trade volume cyclicality. Acquisition targets should concentrate on regional lessors with established depot maintenance networks for natural refrigerant systems. Watch refrigerant supplier consolidation as the inflection signal for pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Transcritical CO2 Fleet Conversion | EU F-Gas Regulation mandates accelerate capital deployment toward natural refrigerant platforms. |
| Telematics Platform Integration | Satellite-enabled cargo monitoring creates premium service tiers for pharmaceutical cold chains. |
| Composite Material Manufacturing Scale-Up | Fiber-reinforced polymer panels reduce tare weight for intra-Asia route optimization. |
| Refrigeration Technician Training Network | CO2 and ammonia system skills scarcity creates competitive moat for certified service coverage. |
| Southeast Asian Depot Expansion | Singapore and Port Klang transshipment concentration demands localized maintenance infrastructure. |
Research Methodology
A standing panel of fleet procurement directors, reefer maintenance engineers, terminal operations managers, and pharmaceutical logistics coordinators provided ongoing calibration across the research phase. Primary interview findings were cross-validated against customs trade data, International Maritime Organization regulatory filings, EU F-Gas implementation reports, and carrier capital expenditure disclosures. Bottom-up equipment deployment estimates were triangulated with top-down trade volume projections.
Scenario-bracketing framed low, base, and high cases across the projection horizon, with container type, material composition, size configuration, and end-user segment serving as core segmentation dimensions. CAGRs were derived from fitted growth curves anchored to observed fleet replacement cycles and regulatory deadline impacts. Forecast inputs incorporated refrigerant phase-down schedules, aluminum price volatility bands, and pharmaceutical cold-chain expansion trajectories.
Stress conditions across commodity price spikes, regulatory enforcement delays, and technician training bottlenecks were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about compliance timeline adherence and trade lane stability. Macroeconomic contraction, regulatory divergence acceleration, or breakthrough cooling technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Colombia Cold Chain Logistics Market
Logistics and Shipping
Global 3PL Market
Logistics and Shipping
United States Chartered Air Freight Transport Market
Logistics and Shipping
France Last Mile Delivery Market
Logistics and Shipping
Illinois Freight and Logistics Market
Logistics and Shipping
North America Shipping Agency Market
Logistics and Shipping
Global Air Cargo and Freight Logistics Market
Logistics and Shipping
Poland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Cloud Logistics Market
Logistics and Shipping
Spain 3PL Market
Logistics and Shipping
Freight Brokerage Market
Logistics and Shipping
Nigeria Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Germany Dangerous Goods Logistics Market
Logistics and Shipping
Qatar Third-Party Logistics (3PL) Market
Logistics and Shipping
South Africa Third-Party Logistics (3PL) Market
Logistics and Shipping
Sea Freight Forwarding Market