
 Asia-Pacific Container Drayage Market | 2026-2036
Asia-Pacific Container Drayage Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Container Drayage Market Insights
Market Context
Premium drayage contracts bundled with real-time visibility and carbon reporting is shifting away from spot-rate commodity haulage across Asia-Pacific port corridors. Maersk Asia Pacific leverages integrated ocean-to-inland service contracts to anchor long-term volume commitments at major transshipment hubs. Kerry Logistics Network competes through cross-border trucking licenses that span ASEAN manufacturing belts. CJ Logistics dominates South Korea's automated port gate systems, sustaining throughput advantages at Busan and Gwangyang terminals.
Technical Definition and Segment Structure
Asia-Pacific container drayage encompasses short-haul movement of marine shipping containers between seaports and inland logistics nodes, typically involving chassis-mounted twenty-foot equivalent unit (TEU) or forty-foot equivalent unit (FEU) boxes moved via diesel, electric, or alternative-fuel tractors within a fifty-kilometer radius. Intermodal service combining rail terminal connections with first-mile road haulage captures expanding margin pools as shippers prioritize modal flexibility over pure road speed. GPS Tracking and Telematics installations are accelerating fastest among technology segments, driven by terminal operators mandating dwell-time transparency to reduce demurrage exposure. Full Truck Load retains volume leadership while Less Than Truck Load drayage grows among mid-sized manufacturers consolidating partial container loads from shared port facilities.
Regulatory Framework and Outlook
China's MEE enforces port emission control area standards that restrict conventional diesel tractor access at Shanghai, Ningbo-Zhoushan, and Shenzhen terminals, while Japan's METI subsidizes hydrogen fuel cell terminal vehicle pilots at Yokohama and Kobe. Australia's TGA-equivalent transport regulators and South Korea's MFDS-aligned environmental standards collectively tighten fleet compliance thresholds across the region. Stakeholders must monitor which port authorities will mandate zero-emission drayage zones first, as this determines capital deployment timing for electrified chassis and charging infrastructure.
Market Dynamics
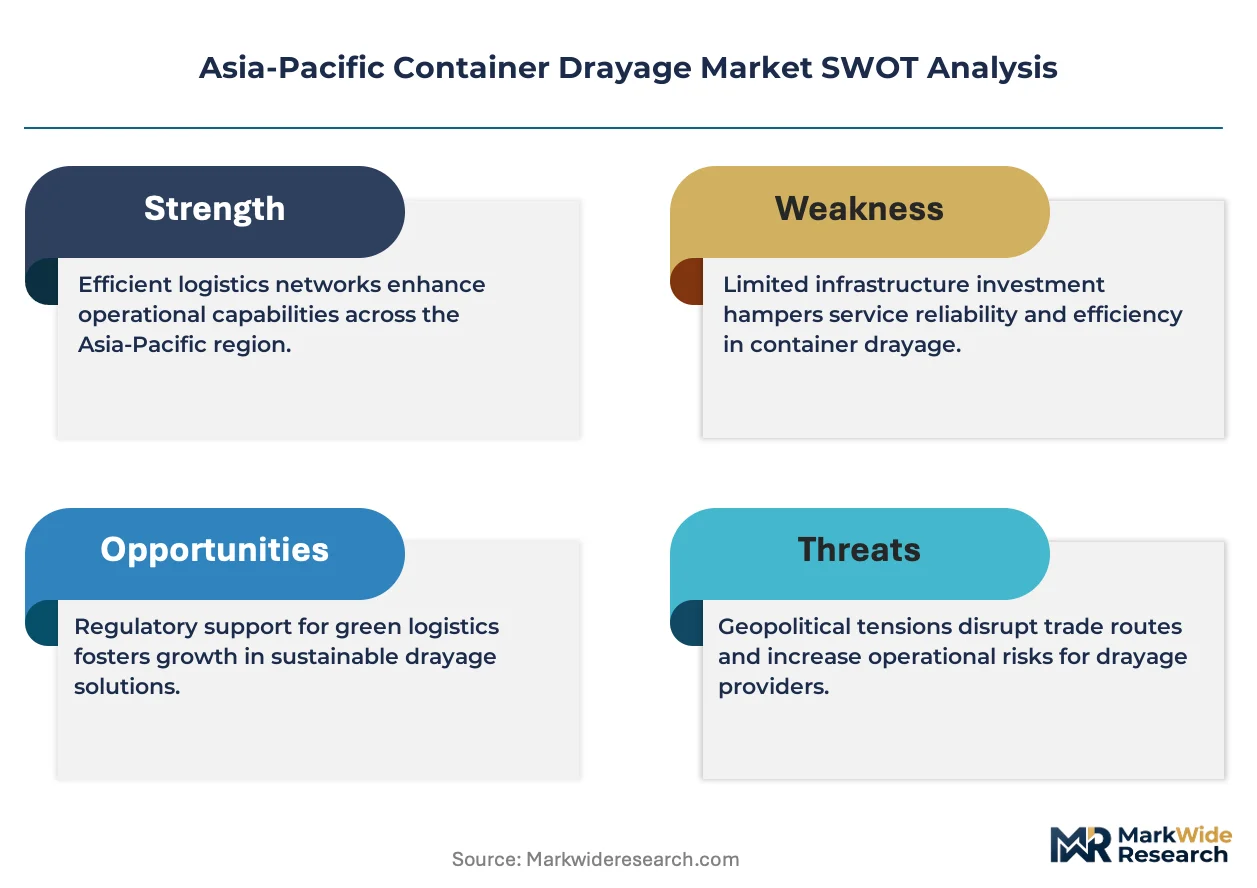
China's MEE port emission control areas are forcing fleet turnover at Shanghai, Ningbo-Zhoushan, and Shenzhen terminals, compressing diesel tractor residual values while accelerating capital deployment into battery-electric and hydrogen-powered alternatives across the Asia-Pacific container drayage market.
Growth Catalysts
- E-commerce fulfillment scaling:Southeast Asian distribution hubs are multiplying container movements from port to inland nodes, with Vietnam's manufacturing corridors generating concentrated demand between Ho Chi Minh City ports and industrial zones in Binh Duong and Dong Nai provinces.
- MEE emission control mandates:China's port emission control area standards restrict conventional diesel tractor access at major terminals, creating regulatory pull for zero-emission fleet replacement and charging infrastructure buildout.
- GPS telematics penetration:Terminal operators now mandate dwell-time transparency systems to reduce demurrage exposure, accelerating hardware installation across chassis fleets serving first-mile port connections.
Market Restraints
- Battery-electric chassis capital intensity:Battery pack costs and charging infrastructure requirements strain operator balance sheets, particularly for smaller fleet owners serving secondary Chinese and Vietnamese port complexes.
- Hydrogen supply concentration:Hydrogen fuel cell terminal vehicle pilots at Yokohama and Kobe depend on limited regional hydrogen production and distribution networks, constraining fleet scaling beyond demonstration projects.
- Cross-border licensing fragmentation:ASEAN manufacturing belts require separate trucking permits across multiple jurisdictions, adding administrative overhead and compliance complexity for integrated drayage operators.
Strategic Opportunities
- Intermodal rail-road integration:First-mile road haulage combined with rail terminal connections captures expanding margin pools as shippers prioritize modal flexibility over pure road speed across Australian and South Korean corridors.
- Less Than Truck Load consolidation:Mid-sized manufacturers in Vietnam and Thailand are consolidating partial container loads from shared port facilities, creating service opportunities between full truckload incumbents and parcel networks.
- METI hydrogen subsidies:Japan's Ministry of Economy, Trade and Industry funding for fuel cell terminal vehicle pilots reduces technology risk for early adopters at Yokohama and Kobe, establishing operational templates for regional replication.
Industry Challenges
- Electrification technician scarcity:Battery-electric and hydrogen-powered terminal tractors require specialized maintenance capabilities that outpace vocational training program output across Chinese and Vietnamese port cities.
- Legacy dispatch system integration:Real-time visibility platforms must interface with decades-old terminal operating systems at Busan and Gwangyang, creating data latency and synchronization failures.
- Zero-emission zone timing uncertainty:Port authorities have not synchronized mandates for zero-emission drayage zones, complicating fleet planning and charging infrastructure investment decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Container Drayage Market |
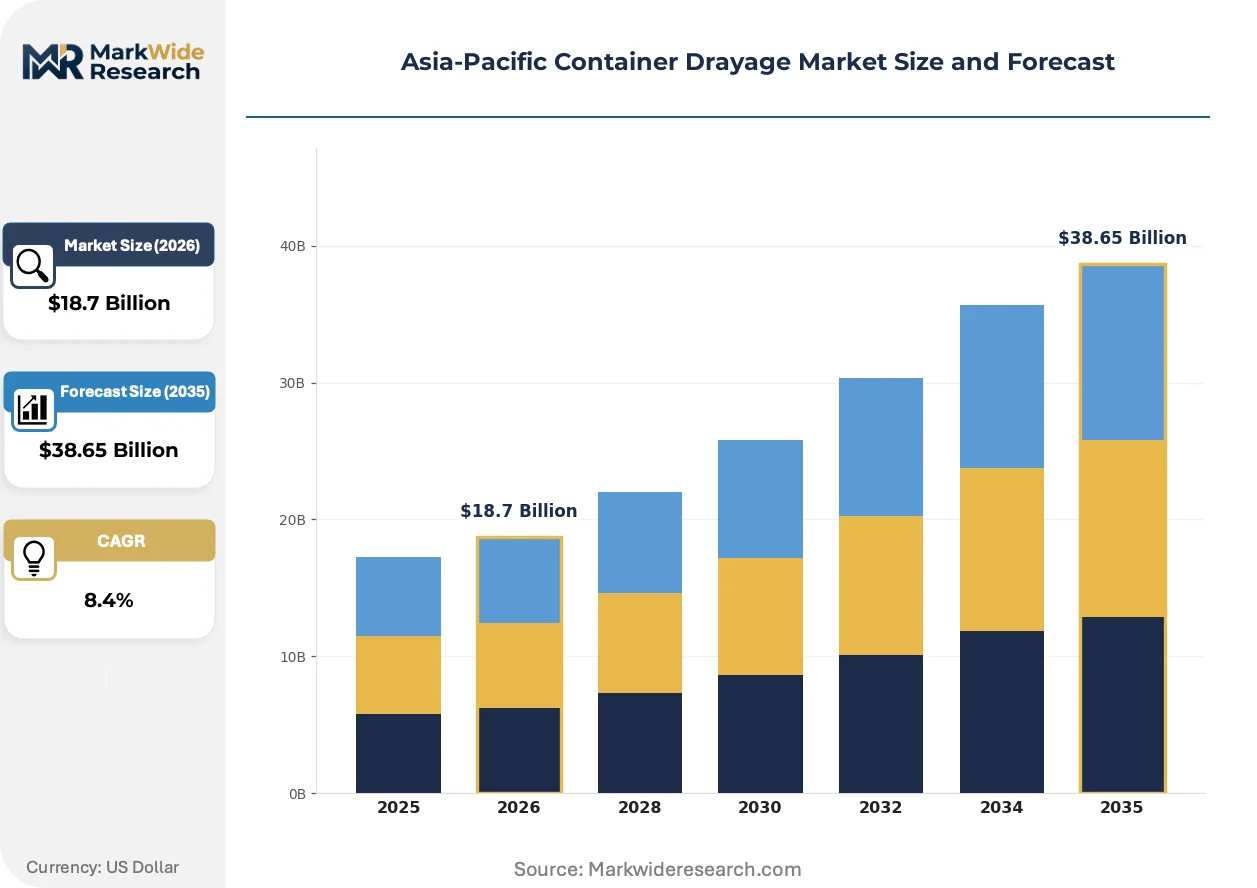
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truck Load, Less Than Truck Load, Intermodal, Drop Shipping Technology: GPS Tracking, TMS, RFID, Telematics End User: Manufacturers, Retailers, Distributors, Freight Forwarders Delivery Mode: Road, Rail, Sea, Last Mile |
| Companies Covered | Maersk Asia Pacific, Agility, C H Robinson Worldwide, FedEx, Deutsche Post DHL Group, Yusen Logistics, Kerry Logistics Network, CJ Logistics, NIPPON EXPRESS HOLDINGS, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Container Drayage Market Trends and Innovations
Digital freight matching and automated gate systems are compressing transaction friction at Asia-Pacific port terminals, while alternative powertrain adoption reconfigures fleet economics and infrastructure requirements across the region.
Autonomous terminal tractors are consolidating yard operations at select Chinese and South Korean ports, reducing labor dependency for repetitive container repositioning tasks. Terminal operators at Shanghai and Busan are piloting limited autonomous zones for overnight operations, compressing turnaround times during off-peak hours. The technology is consolidating operational control within integrated port management platforms that unify gate, yard, and vessel-side coordination.
Australia's TGA-equivalent transport regulators and South Korea's MFDS-aligned environmental standards are tightening fleet compliance thresholds in parallel with China's MEE port emission controls. These overlapping mandates create compound compliance burdens for multi-country operators while accelerating homologation of battery-electric chassis designs across jurisdictions. Vietnamese and Thai fleet operators face the steepest adaptation curves given smaller technical compliance departments and limited regulatory affairs resources.
Shippers are unbundling ocean and inland drayage contracts, demanding standalone pricing and service-level agreements for port-to-hinterland movements. Premium drayage contracts bundled with real-time visibility and carbon reporting are displacing spot-rate commodity haulage across major transshipment corridors. This behavioral shift is most visible among electronics and automotive manufacturers with concentrated production in Vietnam's manufacturing belts and stringent supply chain disclosure requirements.
Asia-Pacific Container Drayage Market Segmentation
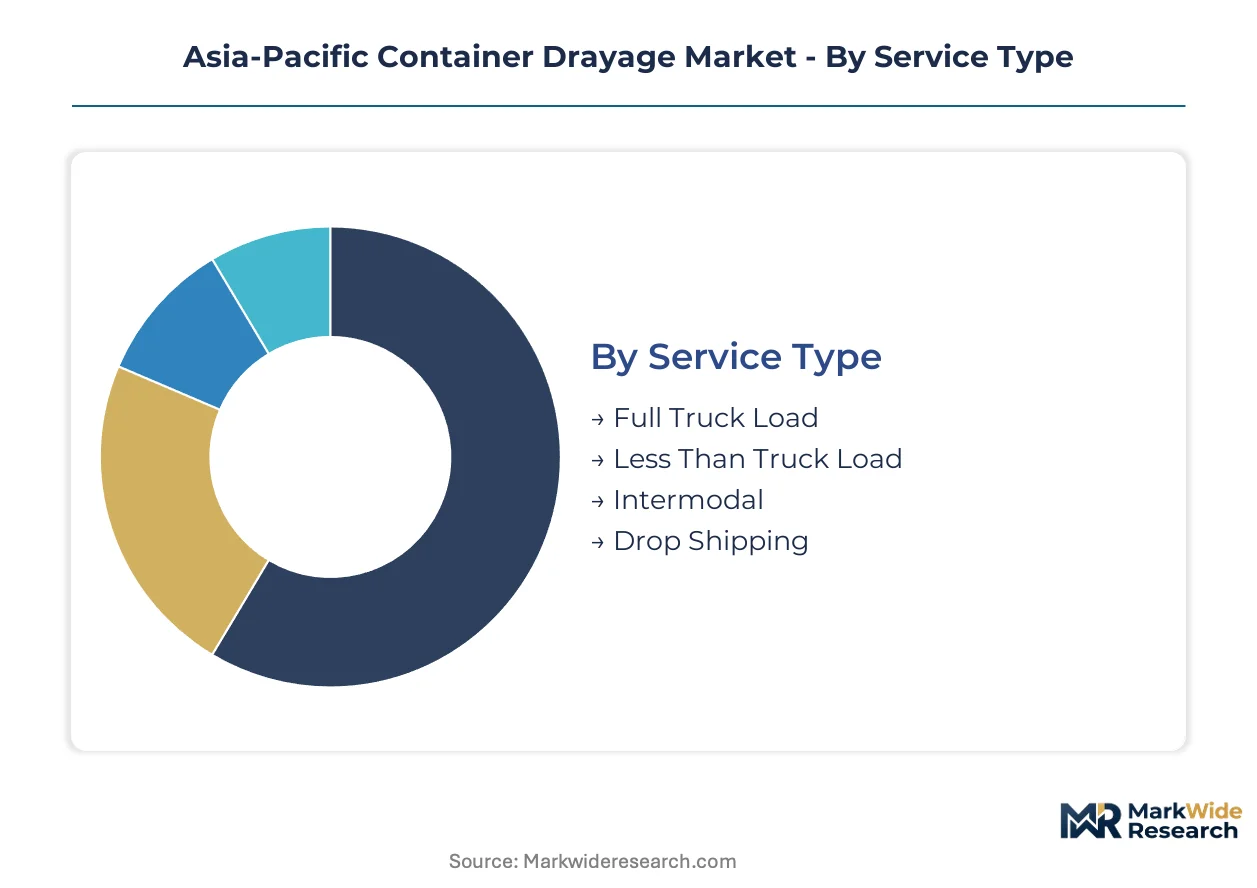
Segmentation in Asia-Pacific container drayage reveals how service configuration, technology adoption, and modal choice determine operator profitability across port-to-inland corridors. Fleet operators configure assets differently when serving Vietnam's manufacturing belts versus Australia's intermodal rail networks.
Service Type:
Service differentiation tracks cargo consolidation economics and customer scale, with contract structures varying sharply between high-volume manufacturing corridors and fragmented retail distribution.
- Full Truck Load:Dedicated chassis movements of single-container loads dominate revenue pools at Shanghai, Ningbo-Zhoushan, and Busan terminals. Electronics manufacturers in Vietnam's Binh Duong province anchor long-term contracts with guaranteed equipment availability.
- Less Than Truck Load:Consolidated partial container loads from shared port facilities serve mid-sized Thai and Vietnamese manufacturers lacking volume for dedicated haulage. This segment gains traction as regional distribution centers multiply across Southeast Asia.
- Intermodal:Rail terminal connections combined with first-mile road haulage capture margin premiums in Australian and South Korean corridors where shippers prioritize modal flexibility.
- Drop Shipping:Direct port-to-consignee movements bypass intermediate warehousing, appealing to time-sensitive automotive and electronics supply chains with synchronized production schedules.
Full Truck Load leads on scale; Less Than Truck Load leads on momentum.
Technology:
Technology deployment intensity correlates with terminal operator mandates and demurrage exposure, creating divergent investment patterns across fleet sizes.
- GPS Tracking:Real-time location systems are now baseline equipment at Shanghai, Shenzhen, and Yokohama terminals. Terminal operators mandate dwell-time transparency to reduce detention fee disputes with ocean carriers.
- Telematics:Integrated vehicle diagnostics and driver behavior monitoring support predictive maintenance for battery-electric tractor fleets. Korean and Japanese operators leverage these systems to optimize charging schedules and route efficiency.
- TMS:Transport management systems automate dispatch and load matching for multi-terminal operators spanning ASEAN cross-border corridors.
- RFID:Automated container identification at port gates accelerates gate processing times, particularly at Busan and Gwangyang automated terminal facilities.
GPS Tracking commands installed base; Telematics claims steepest expansion trajectory.
End User:
End-user concentration maps directly to manufacturing geography, with electronics and automotive production belts generating disproportionate drayage demand.
- Manufacturers:Electronics and automotive producers in Vietnam's Dong Nai province and Thailand's Eastern Economic Corridor drive contracted volume commitments with integrated visibility requirements.
- Freight Forwarders:NVOCCs and logistics intermediaries bundle drayage with ocean freight, capturing margin through integrated service contracts at major transshipment hubs.
- Retailers:E-commerce fulfillment networks across Indonesia and Philippines require rapid port-to-warehouse turnaround with flexible scheduling.
- Distributors:Regional wholesalers serving fragmented retail bases consolidate partial loads from shared port facilities in secondary Vietnamese and Thai ports.
Manufacturers anchor contract value; Freight Forwarders capture integration premiums.
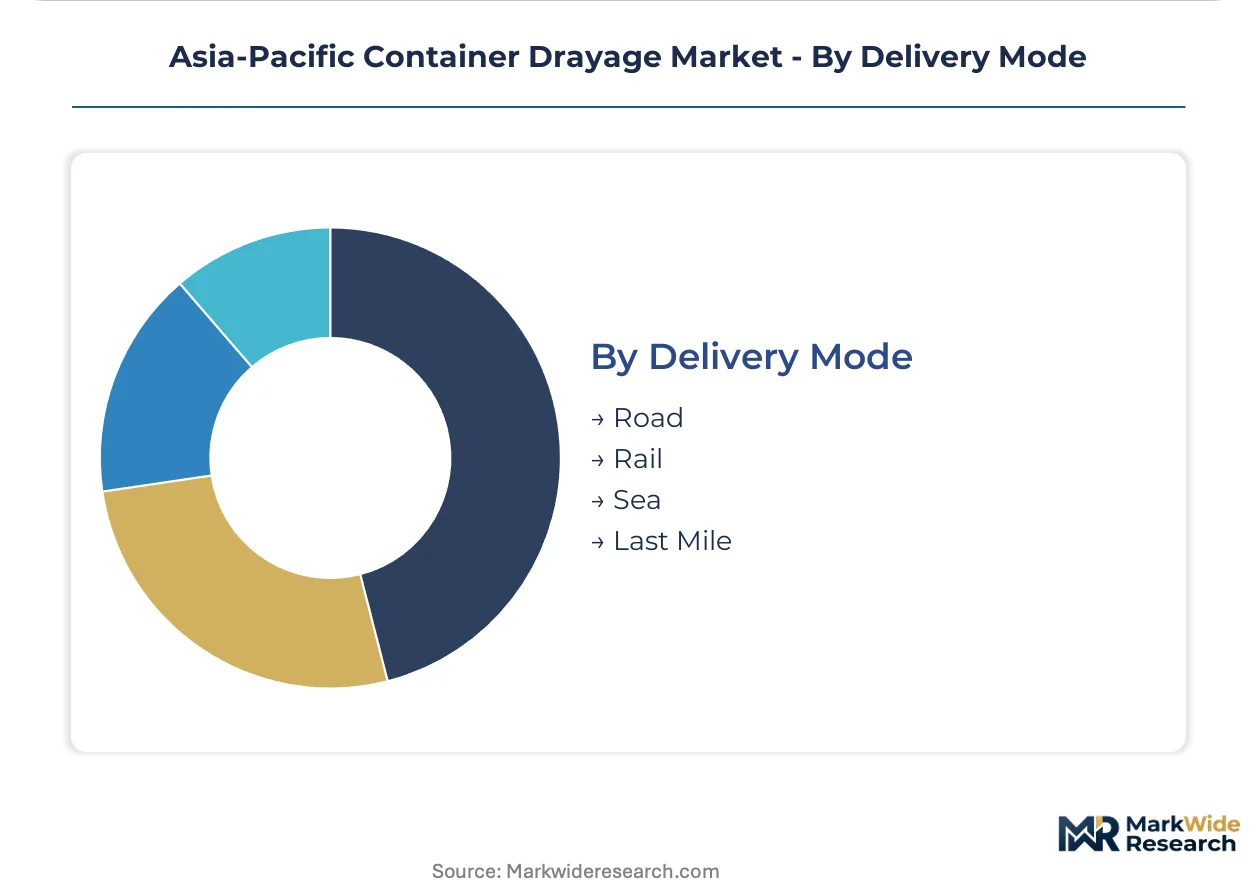
Delivery Mode:
Modal selection reflects infrastructure maturity and corridor distance, with electrification mandates reshaping feasible options near major terminals.
- Road:Diesel and battery-electric tractors handle the majority of movements within fifty-kilometer port radii, though China's MEE emission controls restrict conventional diesel access at Shanghai and Shenzhen.
- Rail:Intermodal terminal connections gain share in Australian bulk corridors and South Korean manufacturing belts where rail infrastructure parallels port access.
- Sea:Short-sea feeder movements between proximate ports supplement road haulage in archipelagic markets like Indonesia and Philippines.
- Last Mile:Final delivery to consignee facilities completes the container journey, with urban congestion charges affecting economics in Ho Chi Minh City and Bangkok metropolitan areas.
Road retains volume dominance; Rail gains share on corridor extension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's manufacturing corridors generate denser drayage demand per kilometer than Australia's intermodal networks, reflecting divergent industrial geographies across the Asia-Pacific region.
China
Shanghai, Ningbo-Zhoushan, and Shenzhen terminals anchor the region's largest drayage volume pools. MEE port emission control area standards restrict conventional diesel tractor access, forcing fleet turnover toward battery-electric and hydrogen alternatives. Yangtze River Delta manufacturing clusters sustain contracted haulage commitments with integrated visibility requirements.
Vietnam
Electronics and automotive production in Binh Duong and Dong Nai provinces concentrate container movements between Ho Chi Minh City ports and inland industrial zones. Cross-border trucking licenses into Cambodia and Laos add administrative complexity for integrated operators. The Eastern Economic Corridor extension drives demand for dedicated chassis availability with guaranteed turnaround times.
Japan
METI subsidies for hydrogen fuel cell terminal vehicle pilots at Yokohama and Kobe establish operational templates for regional replication. Automotive manufacturers with just-in-time production schedules demand precise port-to-facility coordination. Kansai manufacturing belts require synchronized drayage with vessel arrival windows to minimize inventory holding costs.
South Korea
Busan and Gwangyang automated port gate systems sustain throughput advantages for operators with integrated terminal access. MFDS-aligned environmental standards tighten fleet compliance thresholds alongside electrification mandates. Seoul Capital Area electronics manufacturers anchor long-term contracts with penalty clauses for dwell-time overruns.
Australia
TGA-equivalent transport regulators enforce parallel compliance burdens with Chinese and Korean environmental standards. Intermodal rail-road combinations capture margin premiums in bulk corridors where shippers prioritize modal flexibility. New South Wales and Queensland mining exports drive heavy-haul container movements from Port Botany and Brisbane terminals to inland processing facilities.
Asia-Pacific Container Drayage Market Competitive Landscape
Top-tier vendors anchor integrated ocean-to-inland service contracts, while mid-tier operators compete through cross-border licensing and specialized terminal access. The vendor base clusters around three strategic archetypes: global ocean carriers with captive drayage units, regional logistics networks with ASEAN trucking permits, and automated port specialists with yard management integration. Capacity expansion into electrified chassis fleets and strategic partnerships for hydrogen infrastructure represent the dominant competitive moves across tiers.
Among Asia-Pacific-based integrated operators, Kerry Logistics Network and CJ Logistics exemplify the regional network archetype, while Maersk Asia Pacific occupies a position reflecting ocean carrier backward integration into inland haulage. These three entities represent contrasting approaches to port-to-hinterland service configuration across the region's major transshipment hubs.
| Leading Market Players |
|---|
| Maersk Asia Pacific |
| Agility |
| C H Robinson Worldwide |
| FedEx |
| Deutsche Post DHL Group |
| Yusen Logistics |
| Kerry Logistics Network |
| CJ Logistics |
| NIPPON EXPRESS HOLDINGS |
| Others |
Pricing and Supply Chain Analysis
Certified electrification technicians concentrated in Shanghai and Busan command wage premiums that compress margins for Vietnamese and Thai operators lacking comparable vocational training infrastructure, widening the spread between premium zero-emission service tiers and diesel-based commodity haulage across Asia-Pacific port corridors.
Pricing Analysis
The bundled-vs-unbundled service split is reshaping contract economics as shippers unbundle ocean and inland drayage to demand standalone pricing with carbon reporting. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and real-time visibility integration. Pricing pressure stems from battery-electric chassis capital intensity squeezing smaller fleet operators. Mid-sized manufacturers consolidating partial loads show highest price sensitivity; electronics producers with just-in-time requirements show lowest.
Supply Chain Analysis
Reverse-logistics flows for retired diesel tractors and battery pack refurbishment are concentrating specialized dismantling capacity in China's Jiangsu province and South Korea's Gyeonggi region. Chassis manufacturing draws from steel mills in China, battery cell production in South Korea, and hydrogen fuel cell stacks in Japan. Single-source vulnerability runs through lithium-ion battery supply chains. Distribution runs through integrated port management platforms unifying gate, yard, and vessel-side coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific container drayage offers margin-expansion pathways through electrification-driven cost compression in fuel and maintenance, alongside premium-tier pricing for carbon-transparent service bundles.
For Market Incumbents: Lock in long-term volume commitments with electronics manufacturers in Vietnam's Dong Nai province through guaranteed equipment availability clauses. Anchor integrated ocean-to-inland service contracts at Shanghai and Busan terminals to deter spot-rate competitors. Defend against emerging regional logistics networks with ASEAN cross-border trucking permits by accelerating charging infrastructure deployment ahead of MEE zero-emission zone mandates. For New Entrants and Emerging Players: METI hydrogen subsidies in Japan open a window for fuel cell terminal vehicle pilots at Yokohama and Kobe with reduced technology risk. Target Less Than Truck Load consolidation among mid-sized Thai manufacturers lacking volume for dedicated haulage. Enter through cross-border licensing partnerships spanning Cambodia and Laos to bypass fragmented permit overhead. For Investors and Strategic Acquirers: Valuations sit cheapest among Vietnamese fleet operators facing the steepest electrification adaptation curves. Long-term viability favors automated port specialists with yard management integration capabilities. Monitor which port authorities synchronize zero-emission drayage zone mandates first as the inflection signal for charging infrastructure investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Electrified Fleet Conversion | MEE port emission controls at Shanghai and Shenzhen terminals force capital redeployment into battery-electric chassis. |
| Hydrogen Infrastructure Partnership | METI-funded pilots at Yokohama and Kobe establish operational templates for regional fuel cell scaling. |
| Cross-Border Licensing Consolidation | ASEAN trucking permit unification reduces administrative overhead for integrated operators spanning Vietnam and Thailand. |
| Intermodal Rail-Road Integration | First-mile road haulage combined with Australian and South Korean rail terminals captures modal flexibility premiums. |
| Real-Time Visibility Platform Deployment | GPS telematics installations mandated by terminal operators reduce demurrage exposure and anchor premium contract tiers. |
Research Methodology
Direct dialogue with fleet operations managers, terminal authority procurement leads, chassis OEM technical directors, and logistics contract negotiators across Shanghai, Ho Chi Minh City, and Busan informed primary data collection. Secondary validation drew from MEE emission control filings, METI hydrogen subsidy disclosures, ASEAN customs transit records, and Busan Port Authority throughput statistics. Bottom-up fleet deployment estimates and top-down port volume projections were triangulated to anchor market sizing.
Bottom-up modeling of chassis fleet composition by powertrain type, service tier penetration, and technology adoption rates was cross-checked against top-down port throughput and container movement data across the projection horizon. Segmentation dimensions included service type, technology deployment, end-user industry concentration, and delivery mode. CAGRs were derived from regression analysis of historical fleet turnover patterns and regulatory mandate timelines, with hydrogen supply chain maturity and battery cost curves as key forecast inputs.
Revisions become necessary when MEE emission control area expansion accelerates beyond modeled trajectories, or when hydrogen production capacity fails to scale beyond Japanese demonstration projects. Practitioners should monitor port authority zero-emission zone mandate synchronization and cross-border trucking permit harmonization progress for early signals of competitive repositioning requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Global Air Cargo and Freight Logistics Market
Logistics and Shipping
Europe Refrigerated Container Shipping Market
Logistics and Shipping
Estonia Freight and Logistics Market
Logistics and Shipping
Mexico Last Mile Delivery Market
Logistics and Shipping
Japan Logistics Market
Logistics and Shipping
Inland Container Depot and Dry Port Market
Logistics and Shipping
Middle Mile Delivery Market
Logistics and Shipping
Global 5PL Solutions Market
Logistics and Shipping
Czech Republic Third-Party Logistics Market
Logistics and Shipping
Dry Van Container Market
Logistics and Shipping
North America Cross Border Road Freight Transport Market
Logistics and Shipping
Myanmar Freight and Logistics Market
Logistics and Shipping
Multi-Enterprise Logistics Contract and SLA Performance Management Platforms Market
Logistics and Shipping
GCC Event Logistics Market
Logistics and Shipping
Manufacturing Logistics Market
Logistics and Shipping
Japan Freight and Logistics Market