
 Netherlands Courier, Express, and Parcel (CEP) Market | 2026-2036
Netherlands Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Courier, Express, and Parcel (CEP) Market Insights
Buyer concentration in Dutch e-commerce is decoupling from traditional retail channels as marketplace platforms fragment order volumes across thousands of sellers. PostNL leverages its universal service obligation and dense pickup point network to sustain last-mile dominance. DHL Group anchors European cross-border parcel flows through its Maastricht and Rotterdam hubs. DPD competes on speed through automated sorting investments in Eindhoven.
Courier, Express, and Parcel (CEP) services constitute time-definite logistics solutions encompassing document and goods movement through integrated collection, sortation, line-haul, and delivery operations with service-level guarantees ranging from same-day to standard multi-day transit. The sector employs barcode-based track-and-trace systems, automated hub sortation, and dynamic route optimization to achieve delivery precision within contracted windows. Next-day delivery leads service type revenue as Dutch consumers normalize premium speed expectations, while same-day delivery represents the fastest-expanding segment constrained by urban density and micro-fulfillment proximity. Ground shipping dominates delivery method volumes given the Netherlands' compact geography and superior road infrastructure, though drone delivery pilots concentrate in medical corridor applications between Leiden and Rotterdam.
The Dutch Authority for Consumers and Markets (ACM) enforces postal sector liberalization and tariff transparency, while EU REACH and F-Gas Regulation frameworks govern refrigerant use in temperature-controlled pharmaceutical transport. The EU Green Deal's transport decarbonization mandates accelerate zero-emission vehicle procurement across Dutch CEP fleets, reshaping capital allocation toward electric vans and cargo bikes. Stakeholders must monitor how Amsterdam's municipal zero-emission zones expand to additional Randstad cities and whether EU CSRD disclosure requirements alter carrier sustainability reporting burdens.
Market Dynamics
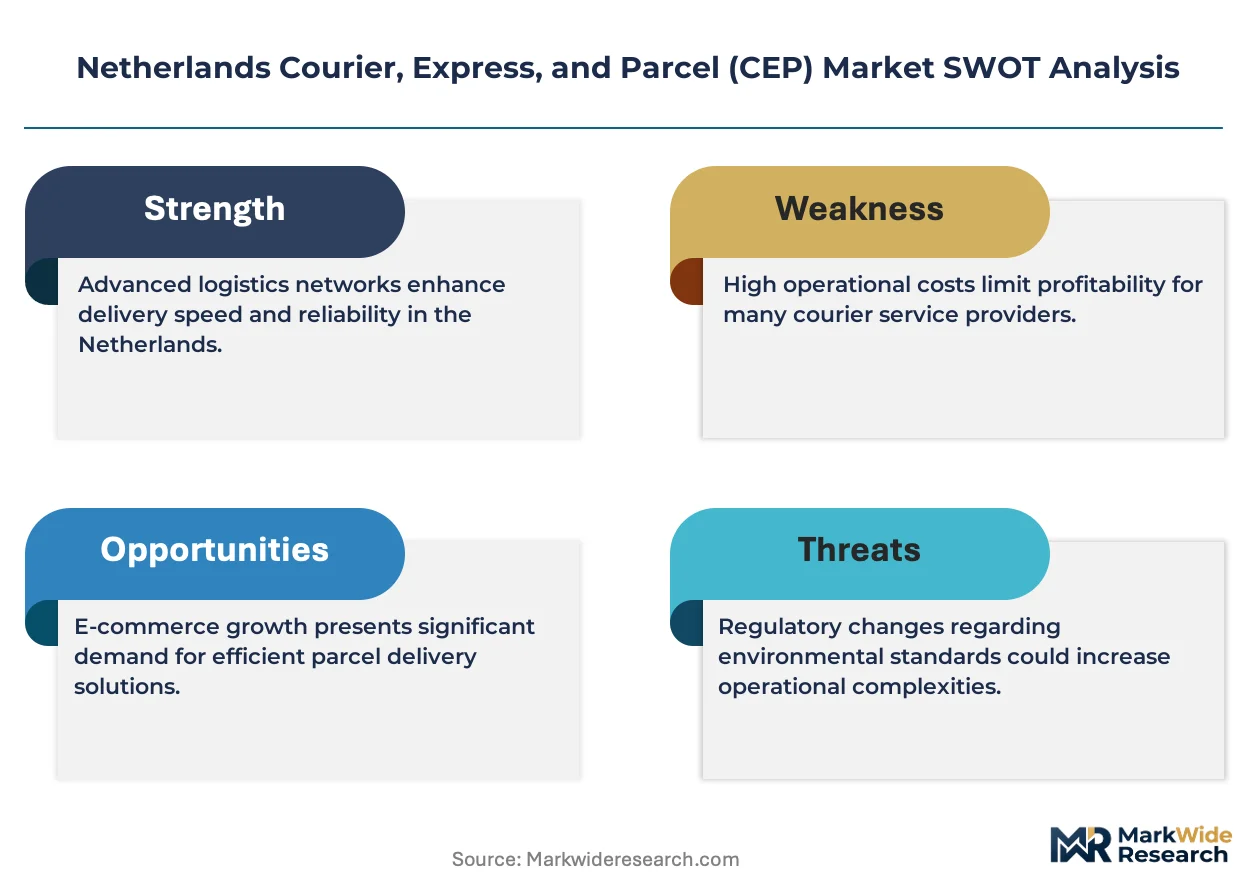
The EU Green Deal's transport decarbonization mandates are forcing fleet electrification across Dutch CEP operations, reshaping capital allocation toward electric vans and cargo bikes while municipal zero-emission zones expand beyond Amsterdam into Rotterdam and Utrecht.
Growth Catalysts
- E-commerce platform proliferation:Marketplace fragmentation disperses order volumes across thousands of sellers, generating parcel density that sustains route economics for next-day and same-day service tiers.
- EU Green Deal mandates:Transport decarbonization requirements accelerate zero-emission vehicle procurement, unlocking subsidies and priority access to urban delivery zones for compliant carriers.
- Randstad urban corridor concentration:Amsterdam, Rotterdam, The Hague, and Utrecht generate sufficient delivery density to support micro-fulfillment networks and automated sorting investments.
Market Restraints
- Electric vehicle supply constraints:Battery production bottlenecks and semiconductor shortages limit fleet conversion timelines, forcing carriers to retain diesel assets longer than planned.
- Last-mile labor cost inflation:Driver shortages in dense urban corridors push wage premiums higher, compressing margins on standard delivery services where price competition is fiercest.
- ACM tariff transparency requirements:The Dutch Authority for Consumers and Markets mandates published pricing for universal service obligations, constraining dynamic pricing flexibility during peak demand windows.
Strategic Opportunities
- Temperature-controlled pharmaceutical corridors:Leiden-to-Rotterdam medical logistics lanes offer premium pricing for validated cold chain services with EU REACH and F-Gas Regulation compliance.
- Drone delivery medical applications:Regulatory sandbox approvals for urban air mobility between hospital clusters enable pilot programs that bypass ground congestion entirely.
- Reverse logistics integration:E-commerce return volumes create secondary revenue streams through consolidated pickup point networks and automated sortation for refurbishment channels.
Industry Challenges
- Dynamic route optimization talent scarcity:Data science and operations research specialists capable of integrating real-time traffic, weather, and customer availability into dispatch algorithms command premium compensation.
- Multi-modal fleet integration complexity:Synchronizing electric vans, cargo bikes, and potential drone assets requires unified telematics platforms that legacy warehouse management systems struggle to accommodate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Courier, Express, and Parcel (CEP) Market |
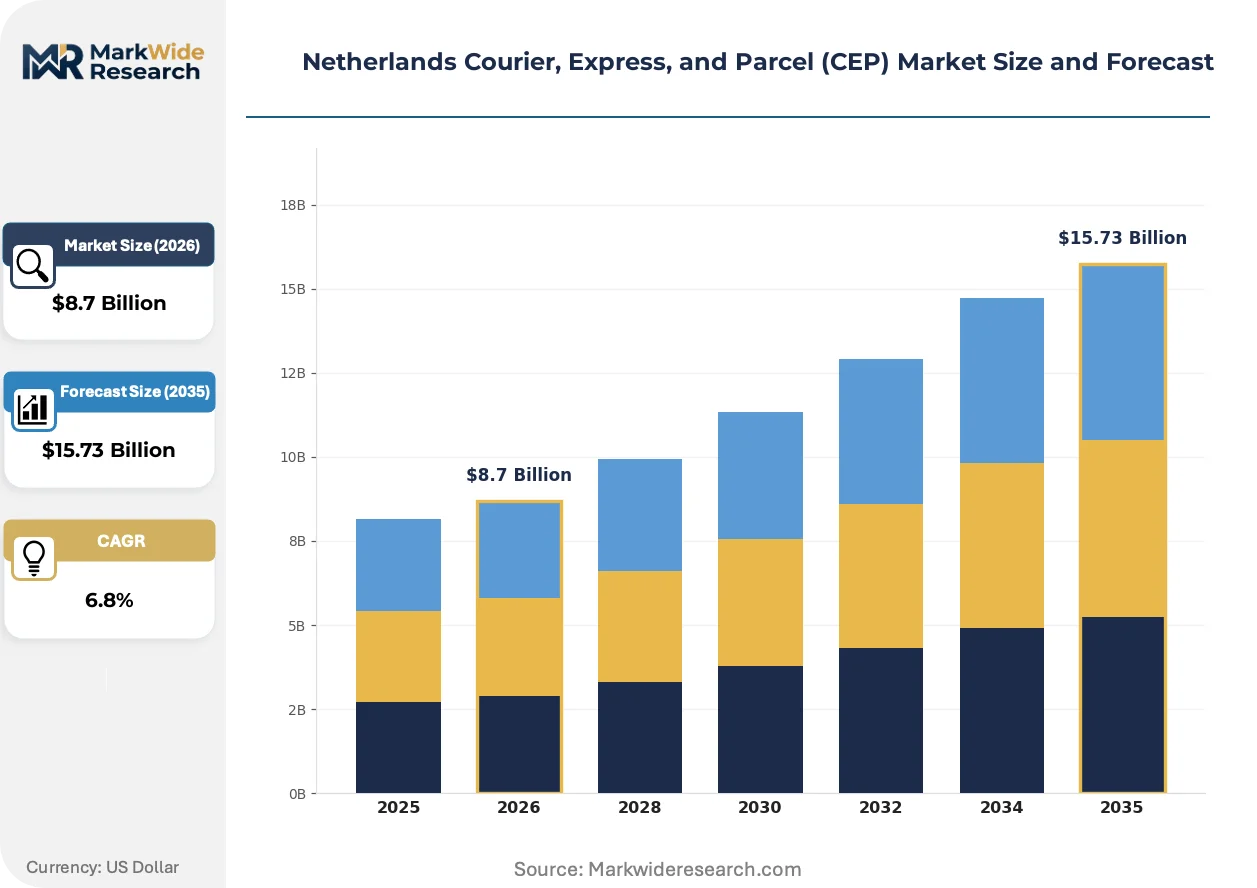
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same-Day Delivery, Next-Day Delivery, Standard Delivery, Scheduled Delivery Delivery Method: Ground Shipping, Air Freight, Ocean Freight, Drone Delivery End User: E-commerce, Retail, Healthcare, Manufacturing Package Size: Small Parcel, Medium Parcel, Large Parcel, Bulk Shipment |
| Companies Covered | PostNL, DHL Group, UPS, FedEx, DPD, GLS, Bpost Group, GEODIS, TNT, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Courier, Express, and Parcel (CEP) Market Trends and Innovations
Automated sortation and dynamic routing technologies are compressing delivery windows while regulatory pressure on emissions forces operational redesign across Dutch CEP networks.
Automated hub sortation systems are absorbing labor costs and throughput constraints in Rotterdam and Eindhoven facilities. PostNL and DPD Group are deploying these systems at pace to handle e-commerce volume surges without proportional headcount expansion. The technology is absorbing sorting bottlenecks that previously constrained same-day service expansion.
EU CSRD disclosure requirements are mandating granular sustainability reporting across Scope 1, 2, and 3 emissions. Dutch carriers must now audit subcontractor fleets and upstream packaging materials, adding compliance overhead but creating differentiation for early adopters. Temperature-controlled pharmaceutical transport faces additional F-Gas Regulation scrutiny on refrigerant leakage rates.
Buyer expectations for delivery precision have compressed switching tolerance to single-hour windows. Dutch consumers now penalize carriers missing narrow slots, forcing investment in predictive ETAs and customer communication platforms. This behavioral shift is most visible in Amsterdam's dense canal districts where access restrictions amplify failure costs.
Netherlands Courier, Express, and Parcel (CEP) Market Segmentation
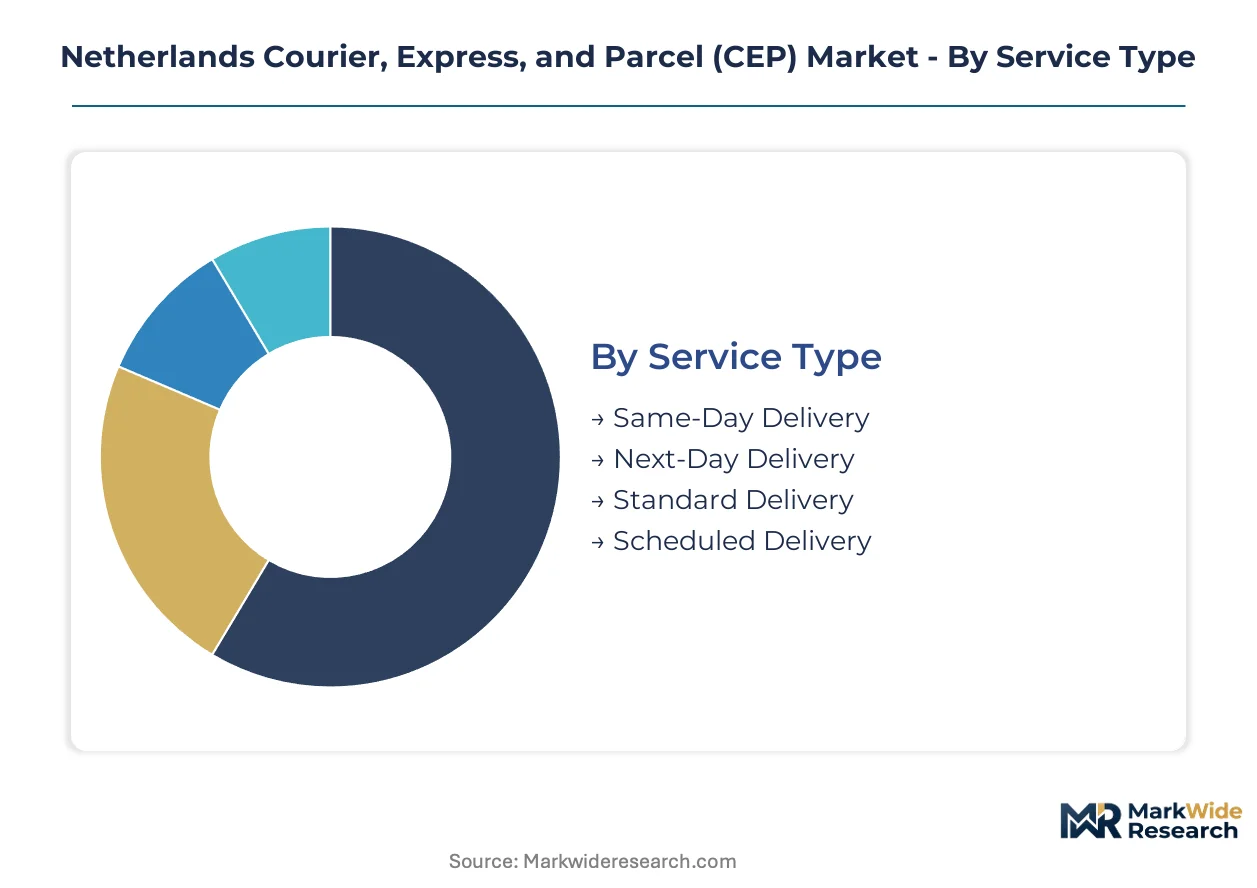
Segmentation in Dutch CEP markets reveals how capital deployment and service guarantees stratify across distinct operational models. Each dimension exposes different pressure points from e-commerce velocity mandates, EU Green Deal compliance costs, and Randstad urban density constraints.
Service Type:
Capital intensity peaks in time-definite tiers where guaranteed delivery windows demand redundant network capacity and real-time dispatch systems.
- Same-Day Delivery:Requires micro-fulfillment nodes within 15km of delivery clusters, dynamic routing algorithms, and floating courier pools. Demand concentrates in Amsterdam's canal districts and Rotterdam's medical corridor where premium pricing offsets density challenges. The EU Green Deal's zero-emission zone expansion forces electric van and cargo bike fleet investments that compress margins.
- Next-Day Delivery:Anchored by automated hub sortation in Eindhoven and Rotterdam with line-haul optimization across the Randstad quadrangle. PostNL leverages its universal service obligation infrastructure to sustain route economics. This tier absorbs the majority of Dutch e-commerce parcel volume.
- Standard Delivery:Multi-day transit with consolidated line-haul and flexible sortation windows. Lower capital requirements permit subcontractor fleet utilization.
- Scheduled Delivery:Appointment-based windows for B2B manufacturing parts and healthcare equipment. Requires customer communication platforms and narrow-slot precision.
Most installed capacity flows through Next-Day Delivery. Expansion is steepest in Same-Day Delivery.
Delivery Method:
Modal choice in the Netherlands tracks geography compactness against emissions compliance urgency and payload requirements.
- Ground Shipping:Dominates volumes through the Netherlands' dense highway network and short inter-city distances. Electric van conversion is accelerating under municipal zero-emission zones in Amsterdam, Rotterdam, and Utrecht. DHL Group and DPD Group anchor European cross-border flows through Maastricht and Rotterdam hubs.
- Air Freight:Reserved for time-critical international express and pharmaceutical cold chain. Concentrated at Schiphol's cargo facilities with temperature-controlled handling for EU REACH compliance.
- Ocean Freight:Limited to bulk parcel consolidation for intercontinental flows. Rotterdam port integration supports sea-air transitions.
- Drone Delivery:Regulatory sandbox pilots operate between Leiden and Rotterdam hospital clusters for medical specimen transport. Bypasses ground congestion entirely but restricted by aviation authority approvals.
Ground Shipping carries the heaviest infrastructure investment. Drone Delivery is gaining share fastest despite regulatory constraints.
End User:
Customer type determines service level requirements, return logistics complexity, and sustainability reporting obligations under EU CSRD.
- E-commerce:Marketplace platform fragmentation disperses order volumes across thousands of sellers, generating parcel density that sustains automated sortation investments. Return volumes create secondary revenue streams through consolidated pickup point networks.
- Retail:Omnichannel fulfillment demands inventory visibility across store networks and dark stores. PostNL's dense pickup point network supports click-and-collect integration.
- Healthcare:Temperature-controlled pharmaceutical corridors between Leiden and Rotterdam require validated cold chain with F-Gas Regulation compliance on refrigerant leakage. Premium pricing offsets compliance overhead.
- Manufacturing:Scheduled delivery windows for just-in-time parts with penalty clauses for missed slots. Concentrated in Eindhoven's high-tech cluster and Rotterdam's port industrial zone.
E-commerce commands the largest fulfillment infrastructure. Healthcare shows the steepest margin expansion trajectory.
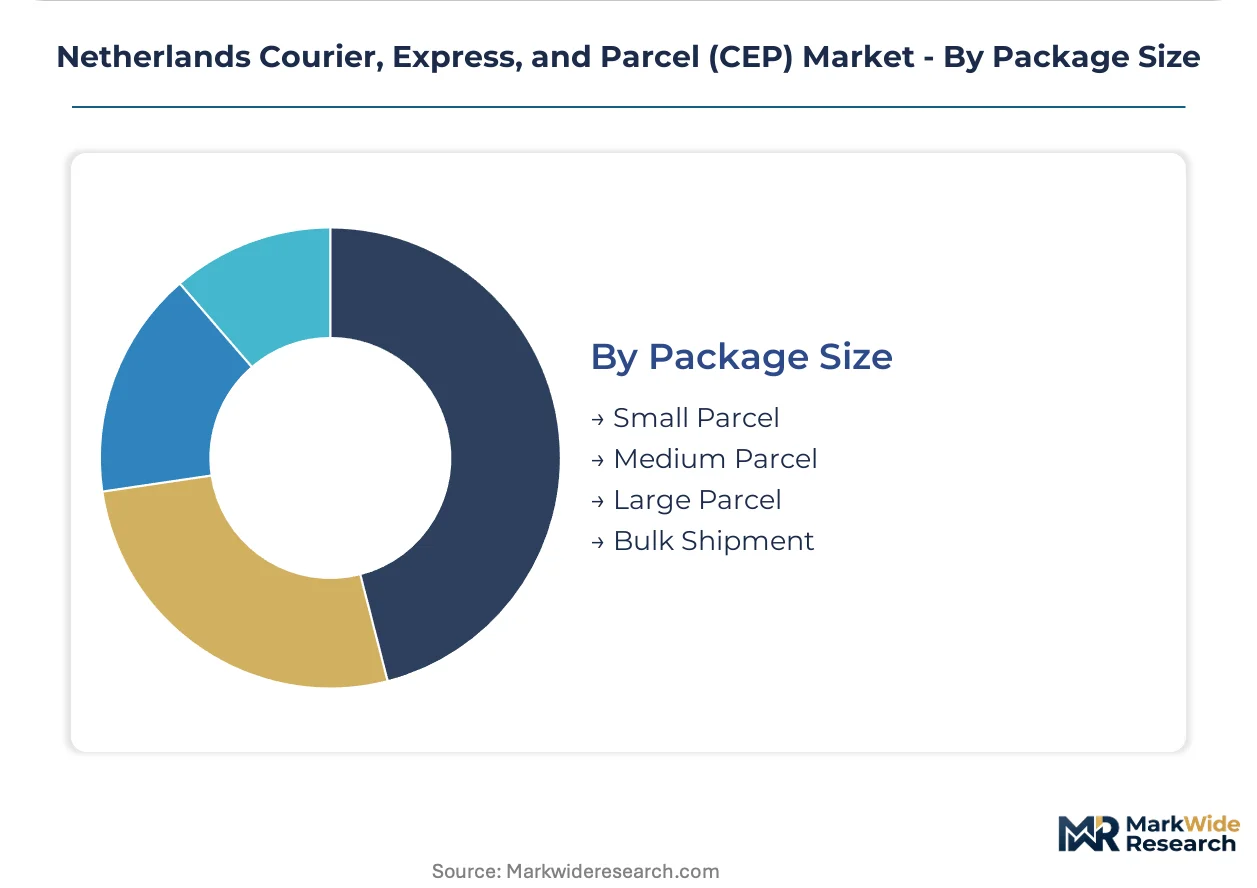
Package Size:
Dimensional weight and handling automation requirements scale non-linearly across size tiers, driving divergent capital allocation.
- Small Parcel:Standardized dimensions enable automated belt sortation and locker delivery. Dominates Dutch e-commerce apparel and electronics flows.
- Medium Parcel:Requires flexible sortation handling and two-person delivery protocols for furniture and appliances. Growing share from online home goods retail.
- Large Parcel:White-glove delivery with assembly services for bulky items. Constrained by last-mile vehicle capacity and urban access restrictions.
- Bulk Shipment:Palletized B2B flows between manufacturing clusters and distribution centers. Integrated with ocean freight for international legs.
Small Parcel moves through the most automated handling capacity. Medium Parcel is expanding most quickly from home goods e-commerce penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany anchors European cross-border parcel flows through its dense autobahn network, while the Netherlands concentrates last-mile innovation in its compact urban corridors. Belgium and Luxembourg serve as logistics bridges, with France and the United Kingdom developing distinct regulatory responses to emissions compliance.
Germany
Automotive parts distribution and pharmaceutical cold chain drive express volumes across Bavaria and Baden-Württemberg. The KBA enforces fleet emissions standards that accelerate electric van procurement for urban delivery zones. DHL Group anchors European parcel flows through its Leipzig hub and Cologne/Bonn airport facilities.
Belgium
Brussels' international institutions generate document courier demand, while Antwerp port consolidation supports sea-air parcel transitions. EU REACH frameworks govern chemical transport compliance across Flanders and Wallonia. Bpost Group leverages dense pickup point networks in Brussels and Ghent to compete on last-mile accessibility.
France
Luxury goods e-commerce from Paris and Lyon generates premium express volumes requiring white-glove handling. ANSM pharmaceutical regulations impose validated cold chain standards on medical specimen transport. GEODIS operates major sorting hubs in Île-de-France and Rhône-Alpes serving cross-border flows into the Benelux.
United Kingdom
London's financial district sustains same-day document courier demand, while Midlands distribution centers handle e-commerce returns volumes. DVSA operator licensing requirements constrain driver availability and push wage inflation. DPD and GLS maintain automated sorting investments in the West Midlands to serve next-day delivery guarantees.
Luxembourg
Cross-border commuter flows between Luxembourg City and neighboring regions generate B2B parcel density for just-in-time manufacturing. EU CSRD disclosure requirements headquartered here mandate granular emissions reporting across subcontractor networks. FedEx and UPS anchor European air freight operations at Findel airport for time-critical pharmaceutical exports.
Netherlands Courier, Express, and Parcel (CEP) Market Competitive Landscape
Dutch carriers anchor one tier through dense pickup point networks and universal service infrastructure; German and Belgian specialists hold cross-border consolidation advantages through hub-and-spoke air freight operations. The market structures around three archetypes: incumbent postal operators with last-mile density, global integrators with air freight dominance, and regional specialists with speed-focused automation. Competitive moves concentrate on fleet electrification under EU Green Deal mandates and automated sorting investments to absorb e-commerce volume surges without proportional labor expansion.
Among postal incumbents, PostNL exemplifies the universal service obligation model with nationwide pickup point density. DHL Group and DPD occupy positions as cross-border specialists leveraging automated hub investments in Rotterdam and Eindhoven. These three represent distinct strategic responses to Dutch municipal zero-emission zone expansion and Randstad urban corridor concentration.
| Leading Market Players |
|---|
| PostNL |
| DHL Group |
| UPS |
| FedEx |
| DPD |
| GLS |
| Bpost Group |
| GEODIS |
| TNT |
| Others |
Pricing and Supply Chain Analysis
Diesel futures and battery metal indices cascade through Dutch CEP carrier cost structures, compressing margins on standard delivery tiers while premium same-day services absorb upstream volatility through dynamic surcharge mechanisms. The EU Green Deal's zero-emission mandates force fleet conversion timelines that reshape capital recovery models across Randstad operations.
Pricing Analysis
Capacity additions in Rotterdam and Eindhoven are reshaping price floors for next-day delivery tiers as automated sortation investments absorb labor inflation. Three-tier pricing structure across premium same-day, standard next-day, and economy multi-day levels stratifies by speed guarantee and emissions compliance certification. Pricing pressure stems from ACM-mandated tariff transparency on universal service obligations, constraining peak-period surge flexibility. E-commerce marketplace sellers exhibit highest price sensitivity, while healthcare cold chain clients accept premium positioning for validated EU REACH and F-Gas Regulation compliance.
Supply Chain Analysis
Reverse logistics flows from e-commerce returns create secondary revenue streams through consolidated pickup point networks and automated refurbishment channels. Vehicle manufacturing concentrates in Germany, Belgium, and the Netherlands for electric van and cargo bike procurement. Lithium-ion battery cells, semiconductor components, and carbon fiber frames constitute critical input dependencies. Single-source vulnerability in battery cell supply from East Asian producers threatens fleet electrification timelines. Distribution runs through hub-and-spoke networks anchored at Rotterdam, Eindhoven, and Maastricht with last-mile density in Amsterdam's canal districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dutch CEP markets have entered late-cycle quality differentiation as buyer tolerance for delivery precision compresses to single-hour windows and EU CSRD disclosure requirements elevate sustainability reporting to competitive table stakes.
For Market Incumbents: Extend zero-emission fleet conversion timelines through lease financing structures that preserve capital flexibility against battery supply volatility. Consolidate subcontractor networks under unified telematics platforms to satisfy EU CSRD Scope 3 emissions auditing requirements. PostNL's universal service obligation infrastructure provides defensive moat density, but DHL Group and DPD Group threaten cross-border volume capture through Maastricht and Rotterdam hub automation. For New Entrants and Emerging Players: Autonomous routing algorithms offer technology-first wedge positioning against legacy dispatch systems struggling with real-time traffic integration. White-space targets concentrate in temperature-controlled pharmaceutical corridors between Leiden and Rotterdam, where F-Gas Regulation compliance barriers deter generalist carriers. Drone delivery medical applications in regulatory sandbox approvals bypass ground congestion entirely. Go-to-market positioning should anchor on validated cold chain certification with premium pricing power. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists commanding automated sortation investments in Randstad urban corridors. Long-term viability over a multi-year horizon favors carriers with captive electric fleet procurement and dense pickup point networks satisfying EU Green Deal mandates. Acquisition target archetype: mid-scale operators with micro-fulfillment node proximity to Amsterdam, Rotterdam, The Hague, and Utrecht. Signal to monitor: ACM expansion of municipal zero-emission zones beyond Amsterdam into additional Randstad cities.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Program | EU Green Deal compliance unlocks priority access to Amsterdam's zero-emission delivery zones. |
| Automated Hub Sortation Deployment | Eindhoven and Rotterdam facilities absorb e-commerce volume surges without proportional labor expansion. |
| Micro-Fulfillment Network Expansion | 15-kilometer proximity to Randstad urban clusters enables same-day delivery economics. |
| Temperature-Controlled Certification | EU REACH and F-Gas Regulation compliance captures premium pharmaceutical corridor pricing. |
| Reverse Logistics Integration | Consolidated pickup point networks monetize e-commerce return volumes through refurbishment channels. |
Research Methodology
Multiple input streams — carrier operations executives, e-commerce logistics procurement leads, municipal transport planners, and EU regulatory affairs specialists — were reconciled against ACM enforcement records, EU emissions disclosure filings, and Dutch customs parcel flow data. Bottom-up volume modeling from automated sortation throughput capacities and top-down macro validation from e-commerce penetration benchmarks were triangulated to constrain estimate variance.
Data-stream reconciliation across primary stakeholder interviews and secondary source validation informed the analytical framework throughout the projection horizon. Segmentation dimensions modeled include service type tier, delivery method modality, end-user industry vertical, and package size category. CAGRs were derived from trend extrapolation of fleet electrification investment cycles and e-commerce order density growth curves. Industry-specific forecast inputs incorporated EU Green Deal mandate implementation timelines and ACM zero-emission zone expansion schedules.
The model holds under stable EU regulatory enforcement and continued e-commerce platform fragmentation; deviation in battery supply chain disruption or ACM tariff transparency expansion would shift carrier margin projections. Practitioners should monitor semiconductor availability for electric van production and municipal zero-emission zone announcements for early signals of competitive repositioning requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Logistics Outsourcing Market
Logistics and Shipping
Mexico Freight Forwarding Market
Logistics and Shipping
UAE Logistics Market
Logistics and Shipping
United Kingdom Cold Chain Logistics Market
Logistics and Shipping
Spain Third-Party Logistics (3PL) Market
Logistics and Shipping
US Dangerous-Hazardous Goods Logistics Market
Logistics and Shipping
France Last Mile Delivery Market
Logistics and Shipping
Peru Road Freight Transport Market
Logistics and Shipping
Europe Sea Freight Forwarding Market
Logistics and Shipping
Mexico Containerized Shipping Market
Logistics and Shipping
Air Freight Market
Logistics and Shipping
North America Last Mile Delivery Market
Logistics and Shipping
Saudi Arabia Integrated Cold Chain Logistics Market
Logistics and Shipping
Egypt Third Party Logistics (3PL) Market
Logistics and Shipping
Vietnam Express Delivery Services Market
Logistics and Shipping
Total Logistics Market