
 Peru Freight and Logistics Market | 2026-2036
Peru Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Peru Freight and Logistics Market Analytics
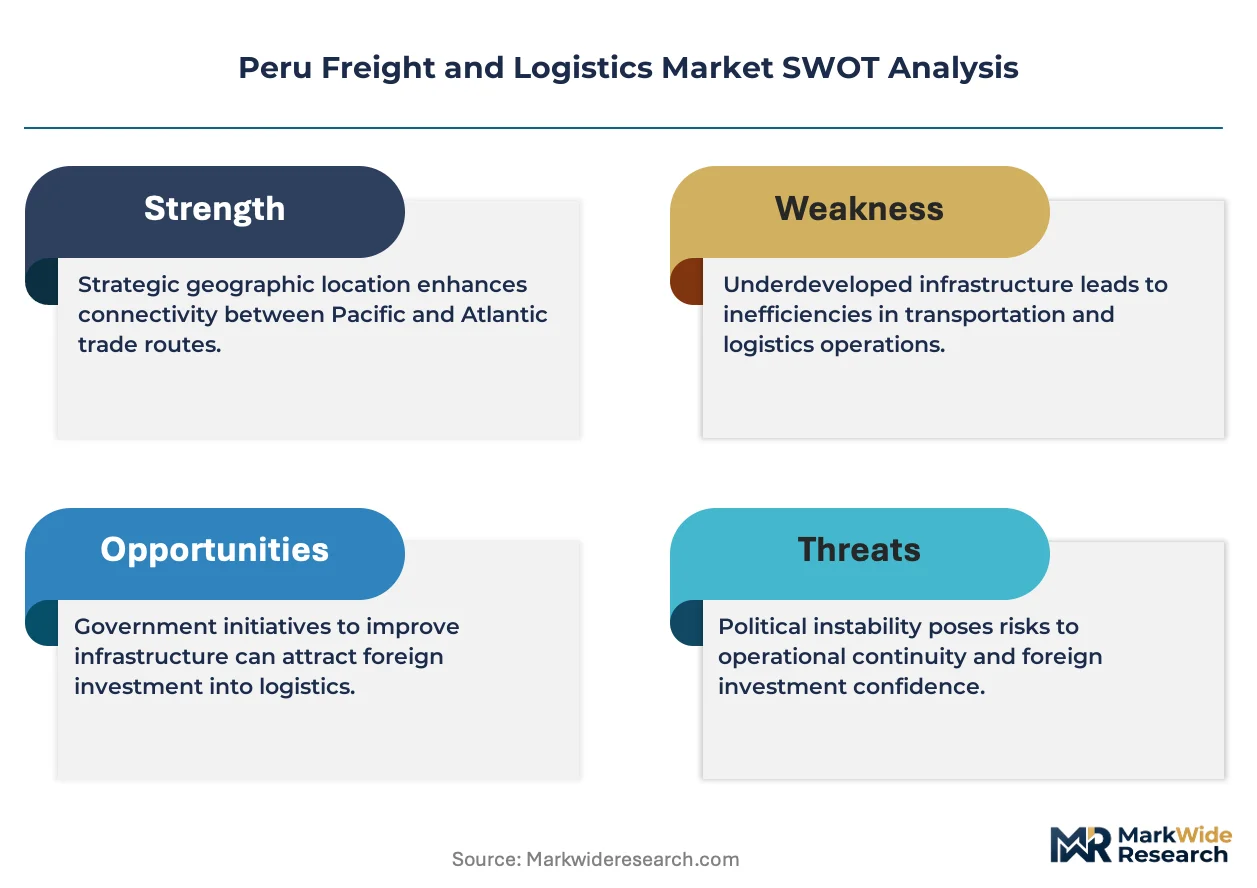
Asset-light leasing models for container fleets and warehousing are reshaping competitive entry barriers across Peruvian logistics. DHL Group leverages its bonded warehouse network to control pharmaceutical cold chain corridors. Kuehne+Nagel anchors European-Peruvian trade lanes with specialized perishables expertise. PeruRail SA dominates mineral freight from the Andes to Pacific ports through its captive rail infrastructure.
Peru freight and logistics encompasses the planning, execution, and management of goods movement across multimodal networks spanning elevations from sea level to over 4,000 meters, requiring altitude-adjusted engine calibrations and pressure-sealed cargo protocols. The sector primarily enables copper concentrate exports, agricultural perishables, and consumer goods distribution through the Pacific corridor. Road freight absorbs the majority of tonnage given the Andean topography, while air cargo captures premium pharmaceutical and electronics shipments where temperature integrity and velocity command margin premiums. E-commerce customer segments expand fastest as digital retail penetration drives last-mile infrastructure investment across Lima and secondary cities.
Peru's Ministry of Transport and Communications (MTC) mandates axle-load limits and corridor concession standards that shape fleet renewal cycles and road infrastructure pricing. The National Port Authority (APN) enforces terminal efficiency metrics at Callao, Matarani, and Ilo that determine maritime access costs for exporters. The Superintendency of Land Transport (SUTRAN) monitors carrier compliance with safety and emissions protocols. Stakeholders must weigh concession tenure lengths against electrification timelines when committing capital to Andean corridor upgrades.
Market Dynamics
The MTC's corridor modernization program is compressing infrastructure access timelines and forcing fleet operators toward axle-compliant vehicles before concession tenures expire.
Growth Catalysts
- MTC Concession Standards:The Ministry of Transport and Communications mandates axle-load limits that accelerate fleet renewal cycles and open bidding for Andean corridor upgrades to compliant operators.
- Mining Export Volumes:Copper concentrate shipments through the Port of Callao generate steady bulk freight demand that anchors container utilization rates for Pacific corridor logistics providers.
- Telematics Integration:GPS-enabled fleet monitoring systems allow carriers to optimize routes across elevation gradients from sea level to 4,000 meters, reducing fuel consumption on mountain passes.
Market Restraints
- Diesel Price Volatility:Road freight operators face margin compression when petroleum import costs spike, as diesel dominates Andean trucking where electrification remains impractical.
- Rail Infrastructure Concentration:PeruRail SA controls captive mineral corridors from the Andes to Pacific ports, limiting third-party access to the lowest-cost bulk transport mode.
- Altitude-Adjusted Equipment Costs:Engine calibrations and pressure-sealed cargo protocols for high-elevation routes add capital intensity that smaller fleet operators cannot absorb.
Strategic Opportunities
- Amazon Basin Last-Mile Expansion:Iquitos and secondary riverine cities lack integrated distribution networks, creating first-mover advantage for barge-truck intermodal operators.
- Pharmaceutical Cold Chain Certification:SUTRAN safety protocols for temperature-controlled transport open bonded warehouse positioning for vaccine and biologics distributors.
- Digital Freight Matching:Mobile platforms connecting shippers with underutilized truck capacity are compressing broker margins and expanding market access for owner-operators.
Industry Challenges
- High-Altitude Driver Certification:Operators struggle to recruit personnel trained in hypoxia response and emergency protocols for routes exceeding 3,500 meters elevation.
- Legacy Warehouse Management Integration:Bonded facilities in Callao run on incompatible software systems that fragment inventory visibility across pharmaceutical and perishables segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peru Freight and Logistics Market |
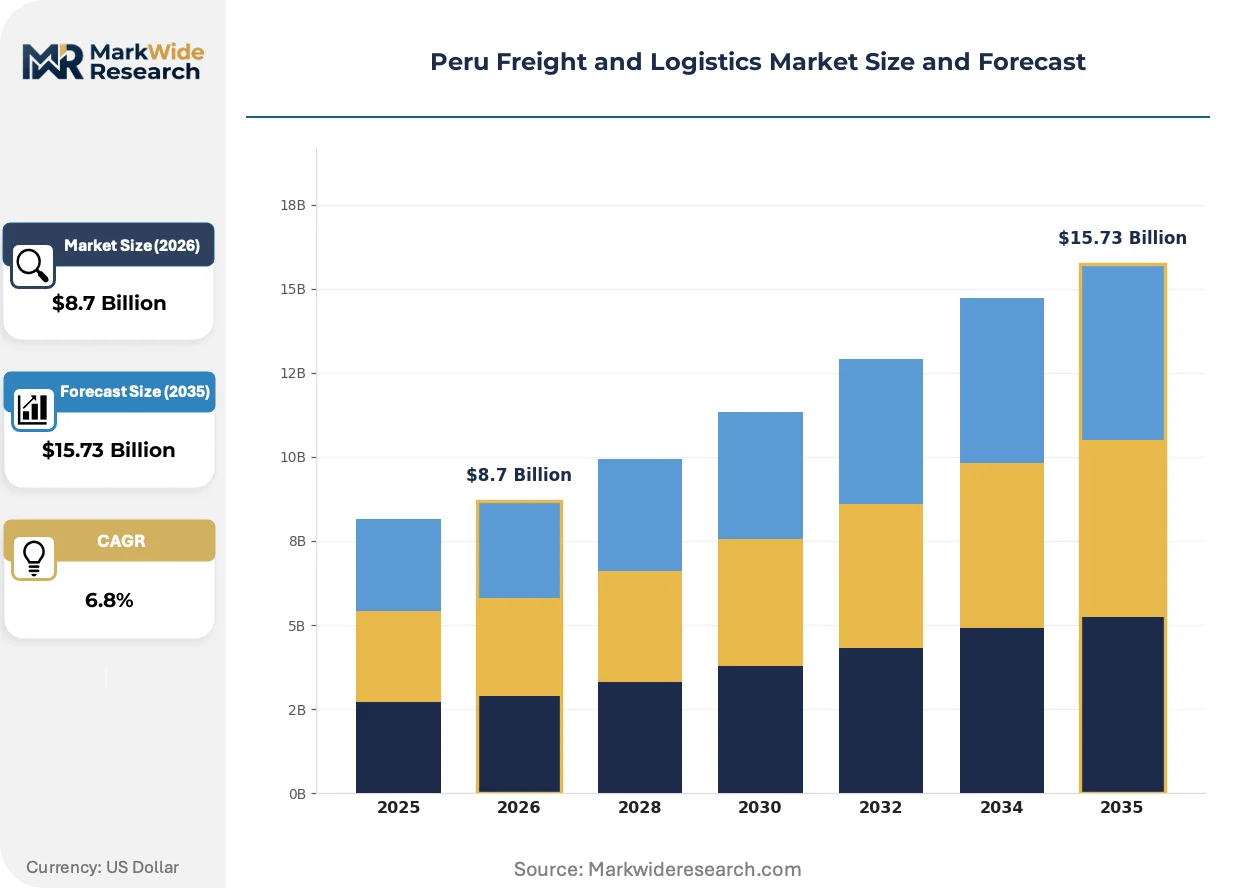
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Road Freight, Air Cargo, Sea Freight, Rail Transport Customer Type: Manufacturers, Retailers, E-commerce, Wholesalers Transportation Mode: Intermodal, Trucking, Shipping, Air Transport Industry Vertical: Automotive, Pharmaceuticals, Food & Beverage, Consumer Goods |
| Companies Covered | A.P. Moller-Maersk, Kuehne+Nagel, DHL Group, UPS, FedEx, DP World, Ransa, PeruRail SA, DSV A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peru Freight and Logistics Market Evolving Landscape
Telematics, regulatory enforcement digitization, and e-commerce fulfillment models are restructuring how cargo moves across Peru's elevation-extreme topography.
Blockchain-enabled cargo documentation is rendering obsolete paper-based customs clearance at Andean border crossings. Agricultural exporters in the Sierra region are adopting the technology fastest to accelerate perishables throughput. The shift compresses dwell time at Matarani and Ilo terminals where manual processing previously added days to transit.
SUTRAN's digitized safety monitoring mandates now require real-time driver hour logging through connected onboard units. The regulation forces fleet operators to retire non-compliant vehicles or retrofit legacy trucks with telematics hardware. Long-haul carriers serving the Lima-Arequipa corridor face the steepest compliance costs as enforcement tightens on the Pan-American Highway.
E-commerce retailers now demand four-hour delivery windows in metropolitan Lima, compressing traditional distribution center-to-store replenishment cycles. Dark stores and micro-fulfillment nodes in San Isidro and Miraflores are displacing centralized warehousing for consumer electronics and apparel. The pattern concentrates infrastructure investment in coastal urban zones while interior regions remain served by conventional hub-and-spoke models.
Peru Freight and Logistics Market Segmentation
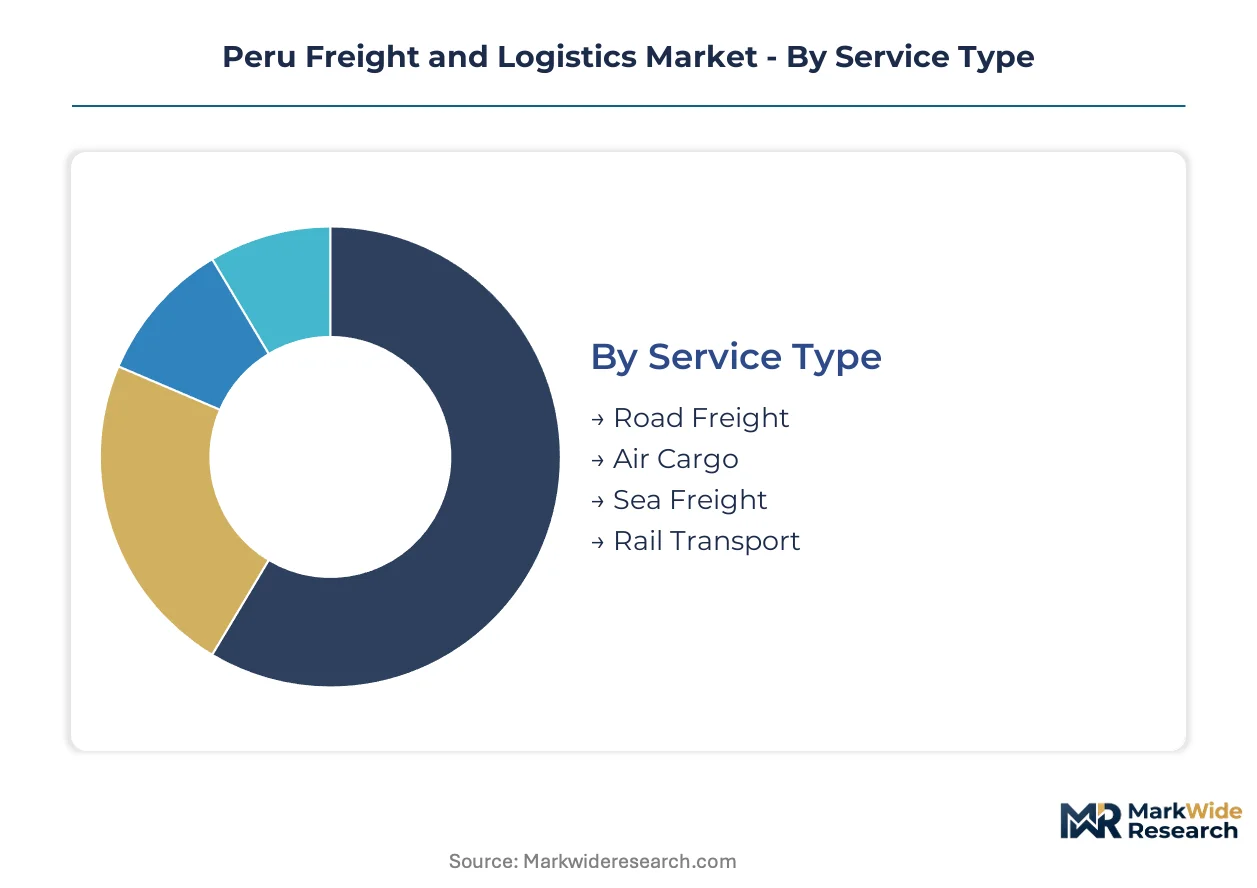
Peru's elevation-extreme topography and multimodal corridor structure fragment service requirements across distinct operational profiles. Each segment demands specialized equipment calibrations, from pressure-sealed containers for Andean passes to cold-chain protocols for Pacific port transshipment.
Service Type:
After-sales service intensity varies sharply across transport modes, with high-altitude road operations requiring continuous maintenance partnerships versus standardized maritime service intervals.
- Road Freight:Diesel-powered fleets with altitude-adjusted engine mappings dominate tonnage movement across the Andean spine. Mining exporters in the central highlands anchor demand for heavy-haul configurations on the Lima-La Oroya corridor.
- Air Cargo:Temperature-controlled jet freighters handle pharmaceutical and electronics shipments where velocity commands premium pricing. Jorge Chávez International Airport processes the majority of high-value perishables bound for North American markets.
- Sea Freight:Containerized bulk moves through the Port of Callao under APN terminal efficiency mandates.
- Rail Transport:PeruRail SA controls captive mineral corridors with limited third-party access.
By volume, Road Freight leads. By growth pace, Air Cargo is ahead.
Customer Type:
Cost tier differentiation separates capital-intensive mining shippers from margin-sensitive retail distributors across the Lima metropolitan zone.
- E-commerce:Digital retailers demand four-hour delivery windows in San Isidro and Miraflores, compressing traditional hub-and-spoke cycles. Dark store networks and micro-fulfillment nodes displace centralized warehousing for consumer electronics.
- Manufacturers:Copper concentrate exporters and automotive assemblers require dedicated fleet contracts with guaranteed capacity through the Port of Callao. MTC concession standards force these shippers toward axle-compliant carriers.
- Retailers:Department store chains operate bonded warehouse networks for imported consumer goods.
- Wholesalers:Agricultural aggregators in the Sierra region coordinate perishables consolidation for Matarani terminal access.
By revenue concentration, Manufacturers dominate. By expansion trajectory, E-commerce is climbing the fastest.
Transportation Mode:
Application-specific routing separates time-definite pharmaceutical movements from bulk mineral flows on shared corridor infrastructure.
- Intermodal:Barge-truck combinations serve the Amazon Basin where riverine access connects Iquitos to Pacific ports. SUTRAN safety protocols govern transloading operations at Pucallpa and Yurimaguas transfer terminals.
- Trucking:GPS-enabled fleet monitoring optimizes routes across elevation gradients from sea level to 4,000 meters, reducing fuel consumption on mountain passes where diesel price volatility squeezes margins.
- Shipping:Maritime containers handle copper concentrate exports under APN efficiency metrics.
- Air Transport:Cold-chain certified freighters move vaccines and biologics through bonded pharmaceutical corridors.
By tonnage share, Trucking dominates. By infrastructure investment, Intermodal is gaining share fastest.
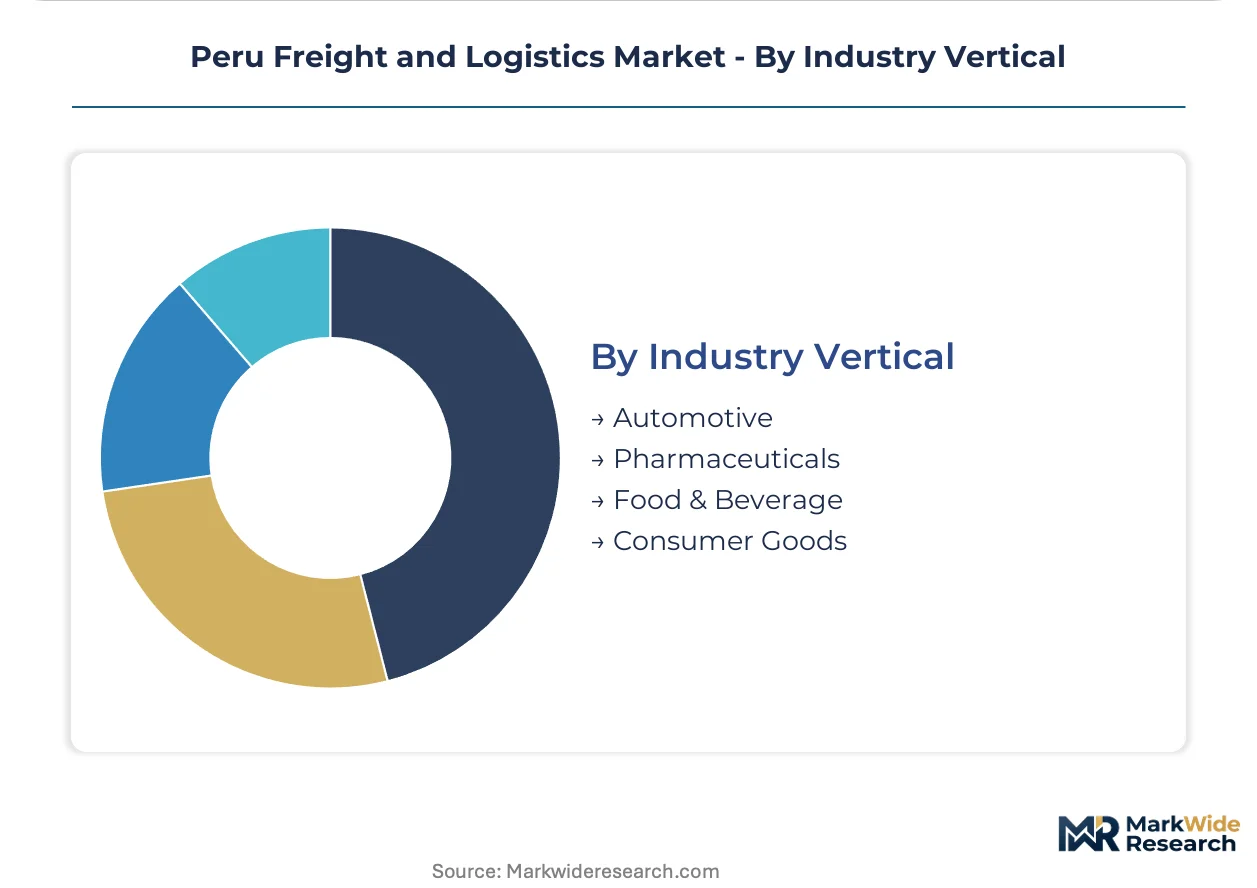
Industry Vertical:
Margin structure separates premium pharmaceutical cold chains from commoditized automotive parts distribution across shared warehousing networks.
- Pharmaceuticals:Temperature-controlled transport with real-time monitoring satisfies SUTRAN safety mandates for vaccine distribution. Bonded warehouse positioning in Callao captures biologics transit with specialized certification requirements.
- Food & Beverage:Agricultural exporters in the Sierra adopt blockchain-enabled documentation to accelerate perishables throughput at Matarani and Ilo terminals where manual processing previously added dwell time.
- Automotive:Finished vehicle logistics and parts distribution run through dedicated port terminals with manufacturer-specific handling protocols.
- Consumer Goods:Apparel and electronics move through e-commerce fulfillment networks with compressed replenishment cycles.
By facility investment, Pharmaceuticals leads. By volume expansion, Food & Beverage is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peru's export-import balance tilts heavily toward mining outbound flows, with copper concentrate dominating Pacific port throughput while consumer goods and machinery comprise the bulk of inbound maritime volumes. The coastal corridor from Callao to Lima anchors national logistics capacity, while Andean and Amazonian sub-regions present divergent infrastructure challenges.
Lima Metropolitan Area
E-commerce fulfillment demand and pharmaceutical cold chain certification concentrate in San Isidro and Miraflores, driving dark store proliferation. The MTC enforces axle-load compliance on the Pan-American Highway corridor, accelerating fleet renewal cycles. Bonded warehouse networks in Callao handle the majority of import consolidation for electronics and apparel distribution.
Central Highlands
Copper concentrate extraction in the La Oroya corridor generates heavy-haul road freight demand with altitude-adjusted engine requirements. PeruRail SA controls captive mineral rail corridors descending from Cerro de Pasco elevations. Mining exporters anchor container utilization rates through dedicated port arrangements at Callao.
Southern Coast
Agricultural perishables from Ica and Arequipa feed Matarani terminal exports under APN efficiency mandates. Blockchain-enabled documentation adoption accelerates dwell time reduction for Sierra region produce. The Lima-Arequipa highway corridor faces SUTRAN digitized enforcement of driver hour logging.
Amazon Basin
Iquitos and riverine secondary cities lack integrated distribution networks, creating intermodal gaps for barge-truck combinations. SUTRAN safety protocols govern transloading at Pucallpa and Yurimaguas transfer terminals. First-mover positioning in pharmaceutical cold chain certification remains underdeveloped relative to coastal infrastructure.
Peru Freight and Logistics Market Competitive Landscape
On the supply side, the industry is bifurcated between global integrated logistics providers with bonded warehouse networks and regional specialists controlling captive infrastructure. The competitive terrain separates asset-heavy rail and port operators from asset-light freight forwarders and digital matching platforms. Three archetypes dominate: integrated global forwarders with pharmaceutical certification, captive mineral rail operators, and last-mile e-commerce specialists. Capacity expansion in cold chain certification and strategic partnerships for Amazon Basin intermodal coverage represent the dominant competitive vectors.
Among European-anchored integrated forwarders, Kuehne+Nagel and DSV A/S occupy positions emphasizing perishables expertise and pharmaceutical corridor control. DHL Group exemplifies the certification-heavy archetype through its bonded warehouse network dominance in temperature-controlled segments. PeruRail SA anchors the captive infrastructure tier with mineral corridor exclusivity from Andean elevations to Pacific ports.
| Leading Market Players |
|---|
| A.P. Moller-Maersk |
| Kuehne+Nagel |
| DHL Group |
| UPS |
| FedEx |
| DP World |
| Ransa |
| PeruRail SA |
| DSV A/S |
| Others |
Value Network & Pricing Analysis
Container utilization compression at the Port of Callao signals overcapacity in Pacific corridor bulk handling, forcing logistics providers toward axle-compliant fleet renewal and compressing margins for non-compliant operators bidding on MTC concession corridors.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures for copper concentrate shipments, with pricing stratifying across certification grade, volume scale, and guaranteed capacity commitments. Cost compression in standard freight tiers intensifies as diesel price volatility squeezes road operators on Andean passes. E-commerce retailers exhibit highest price sensitivity due to four-hour delivery window demands, while pharmaceutical distributors accept premium positioning for SUTRAN-certified cold chain corridors.
Supply Chain Analysis
Extended payment terms from mining exporters feed working capital intensity for fleet operators serving the La Oroya corridor. Equipment manufacturing draws from China, Germany, and the United States for altitude-adjusted engine systems and telematics hardware. Single-source vulnerability concentrates in PeruRail SA's captive mineral corridors, where third-party rail access remains restricted. Distribution runs through bonded warehouse networks in Callao for import consolidation, with last-mile fragmentation across Lima's dark store nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telematics integration and SUTRAN digitized enforcement are compressing traditional broker margins and accelerating fleet compliance investments across the analysis window.
For Market Incumbents: Insulate pharmaceutical corridor positioning through bonded warehouse certification expansion in Callao, defending against asset-light digital freight platforms. Backward integration into captive rail infrastructure or exclusive port terminal arrangements creates moats against PeruRail SA's mineral corridor dominance. Prioritize axle-compliant fleet renewal ahead of MTC concession expirations to maintain Andean corridor bidding eligibility. For New Entrants and Emerging Players: The Amazon Basin's intermodal gaps offer first-mover positioning for barge-truck operators serving Iquitos and riverine secondary cities. Pharmaceutical cold chain certification in Pucallpa and Yurimaguas transfer terminals remains underdeveloped relative to coastal infrastructure. Partner with regional agricultural aggregators in the Sierra to consolidate perishables throughput for Matarani terminal access. For Investors and Strategic Acquirers: Capital is best deployed toward asset-light digital freight matching platforms with mobile capacity aggregation capabilities, as broker margin compression accelerates across the projection horizon. Vertically integrated cold chain specialists with SUTRAN certification and bonded warehouse positioning in Lima present consolidation targets. Watch for MTC concession renewal announcements as inflection indicators for compliant fleet operator valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Axle-Compliant Fleet Renewal | MTC concession standards force pre-emptive capital deployment to maintain corridor access. |
| Pharmaceutical Cold Chain Certification | SUTRAN safety mandates open bonded warehouse positioning for vaccine and biologics distributors. |
| Amazon Basin Intermodal Expansion | Barge-truck combinations address distribution gaps in Iquitos and riverine secondary cities. |
| Telematics Platform Integration | GPS-enabled fleet monitoring optimizes fuel consumption across elevation gradients from sea level to 4,000 meters. |
| Dark Store Network Proliferation | Micro-fulfillment nodes in San Isidro and Miraflores compress traditional hub-and-spoke cycles for e-commerce. |
Research Methodology
Cross-validation between carrier operations data and APN terminal efficiency metrics anchors the qualitative findings on Pacific corridor throughput patterns. Primary interviews with fleet operations managers, MTC concession administrators, pharmaceutical logistics directors, and agricultural export coordinators combine with secondary validation from customs records, SUTRAN compliance filings, and mining export documentation. Bottom-up capacity modeling and top-down trade flow analysis triangulate volume estimates across service type and customer segments.
Calibration against historical concession award patterns and fleet renewal cycles shapes the projection framework across the analysis window. Segmentation dimensions include service type, customer archetype, transportation mode, and industry vertical, with elevation-specific operational requirements modeled as an additional dimension. CAGRs derive from trend extrapolation of mining export volumes, e-commerce penetration trajectories, and regulatory compliance cost curves, incorporating diesel price volatility assumptions and telematics adoption curves as industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by global integrated forwarders or state-backed infrastructure investors would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
LAOS Freight and Logistics Market
Logistics and Shipping
Russia Freight and Logistics Market
Logistics and Shipping
Peru Cold Chain Logistics Market
Logistics and Shipping
Asia-Pacific Courier Market
Logistics and Shipping
Saudi Arabia Third-Party Logistics (3PL) Market
Logistics and Shipping
Australia Last Mile Delivery Market
Logistics and Shipping
Sustainable Logistics Market
Logistics and Shipping
Global 3PL Market
Logistics and Shipping
Australia Freight Forwarding Market
Logistics and Shipping
Airfreight Forwarding Market
Logistics and Shipping
US Retail Logistics Market
Logistics and Shipping
China less than-Truck-Load (LTL) Market
Logistics and Shipping
Latin America Container Terminal Operations Market
Logistics and Shipping
Europe Full Container Load (FCL) Market
Logistics and Shipping
Chile Cold Chain Logistics Market
Logistics and Shipping
Saudi Arabia Integrated Cold Chain Logistics Market