
 Last Mile Delivery Transportation Market | 2026-2036
Last Mile Delivery Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
Last Mile Delivery Transportation Market Outlook
A widening capital-intensity divergence between asset-heavy and platform-native operators is redrawing competitive boundaries in last mile delivery. Amazon Logistics leverages its captive e-commerce volume to sustain vertically integrated fulfillment networks. Deutsche Post DHL Group anchors European operations through dense parcel locker infrastructure and electric fleet commitments. JD Logistics dominates same-day fulfillment in Chinese megacities through proprietary warehouse-to-door robotics.
Last mile delivery transportation encompasses the final leg of supply chain movement where goods travel from distribution nodes to end recipients, typically spanning distances under 100 miles using vehicles ranging from cargo bicycles to medium-duty trucks with payload capacities between 1,000 and 26,000 pounds. This segment functions as the cost apex of logistics, consuming up to 53 percent of total shipping expenditure while serving as the primary customer touchpoint for delivery satisfaction. Road-based delivery methods retain structural dominance due to infrastructure ubiquity, though drone vehicle types are capturing premium-margin niches in medical and urgent document verticals. Same-day and on-demand service types now command disproportionate investment as retailers absorb fulfillment costs to protect conversion rates, while subscription models concentrate predictable volume with dedicated fleet operators.
The EPA tailpipe standards and EU Green Deal emission benchmarks are accelerating fleet electrification timelines across North America and Europe, compelling operators to renegotiate capital deployment cycles. China's MIIT new-energy vehicle mandates and NMPA drone certification pathways are reshaping vehicle procurement and autonomous delivery pilots in the world's largest e-commerce market. Stakeholders must weigh regulatory compliance timelines against route-density economics when allocating capital between electric van deployment and emerging autonomous vehicle infrastructure.
Market Dynamics
EPA tailpipe standards and EU Green Deal emission benchmarks are forcing fleet operators to compress electrification timelines while renegotiating capital deployment cycles around route-density economics.
Growth Catalysts
- E-commerce fulfillment compression:Same-day delivery expectations from digital retail platforms are pulling investment into micro-fulfillment networks and urban warehouse densification.
- EPA heavy-duty vehicle standards:The agency's phase-down of internal combustion engine allowances is mandating zero-emission vehicle procurement for Class 3-7 delivery fleets.
- Drone certification pathways:China's NMPA regulatory framework for unmanned aerial vehicles is enabling autonomous medical and urgent document delivery pilots in dense urban corridors.
Market Restraints
- Lithium-ion supply concentration:Cathode material processing and cell manufacturing cluster in China, exposing fleet operators to input cost volatility and geopolitical supply risk.
- Last mile cost apex:The segment consumes up to 53 percent of total shipping expenditure, compressing margins regardless of volume scale.
- Autonomous vehicle technical limitation:Edge-case navigation in unstructured urban environments delays unmanned ground vehicle deployment beyond controlled campus settings.
Strategic Opportunities
- Parcel locker network expansion:Dense locker infrastructure in Germany and the Netherlands reduces failed delivery rates while enabling electric cargo bicycle feeder operations.
- EU Green Deal fleet incentives:Member state purchase subsidies and toll exemptions for zero-emission commercial vehicles accelerate payback periods for electric van deployment.
- Subscription model concentration:Predictable volume commitments from e-commerce platforms allow dedicated fleet operators to optimize asset utilization against demand curves.
Industry Challenges
- Electric vehicle technician scarcity:High-voltage systems diagnostics and battery management module repair require specialized training pipelines that lag fleet electrification schedules.
- Capex intensity for charging infrastructure:Depot-based fast-charging installations demand electrical grid upgrades and utility coordination timelines that extend deployment horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Last Mile Delivery Transportation Market |
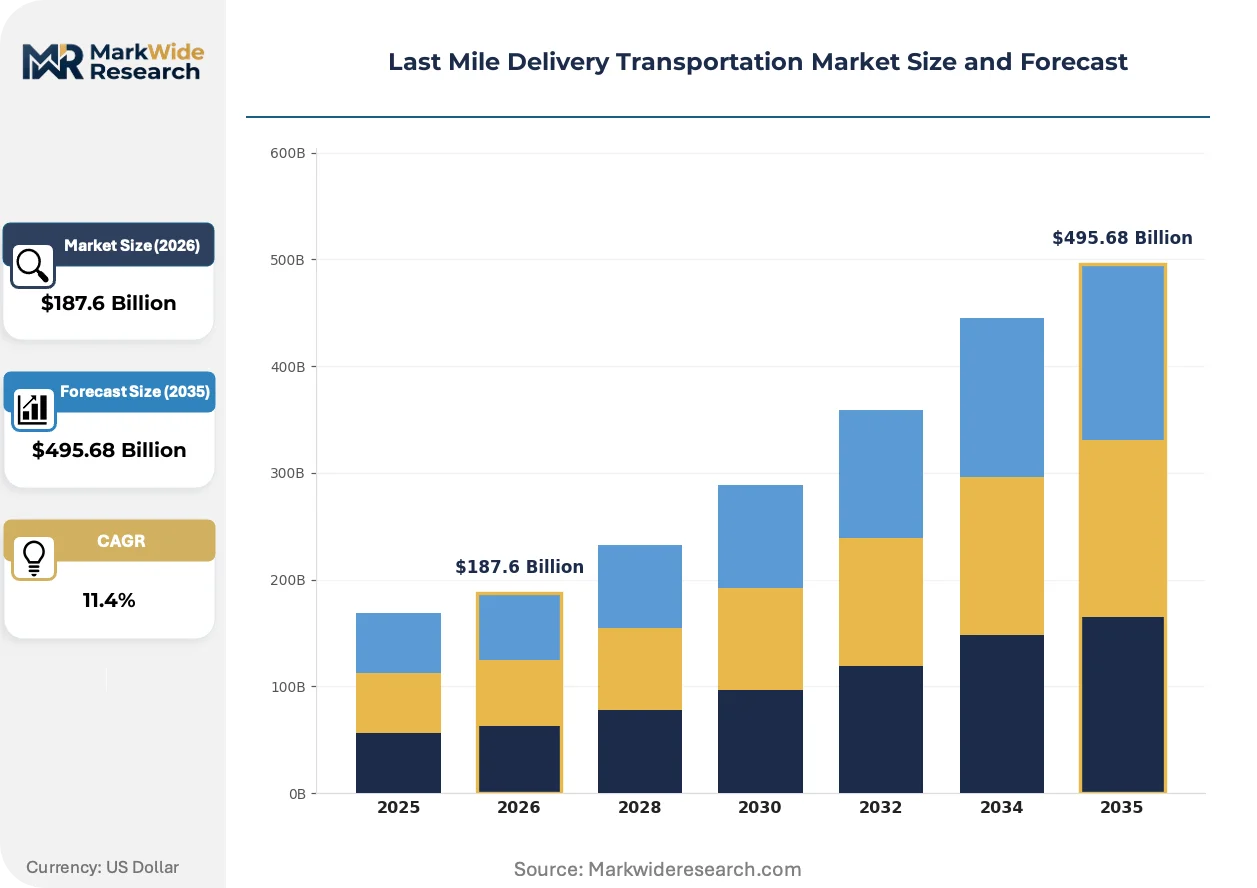
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $495.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Method: Road, Air, Rail, Water Vehicle Type: Trucks, Vans, Motorcycles, Drones Service Type: Same-Day, Scheduled, On-Demand, Subscription End User: Retailers, E-Commerce, Businesses, Consumers |
| Companies Covered | Amazon Logistics, FedEx Corporation, United Parcel Service (UPS), Deutsche Post DHL Group, XPO Logistics, JD Logistics, ZTO Express, DPD Group, DB Schenker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Last Mile Delivery Transportation Market Strategic Shifts
Delivery robotics hardware and autonomous navigation software are converging to reshape urban fulfillment economics, with regulatory frameworks racing to catch deployment velocity.
Autonomous delivery robots are miniaturizing from sidewalk-scale units to compact curb-to-door devices capable of navigating apartment complex interiors. Grocery and pharmacy chains are piloting these systems in controlled suburban environments before urban density scaling. The technology is miniaturizing last mile labor exposure while compressing per-stop cost structures below human courier economics.
The EU Green Deal's emission benchmarks are mandating carbon intensity disclosures across logistics value chains. Fleet operators must now report Scope 3 emissions from subcontracted delivery services, reshaping procurement criteria. European parcel networks are responding by consolidating electric vehicle commitments and locker-based delivery to reduce route mileage.
Buyer expectations for delivery window precision are compressing switching thresholds between competing platforms. Retailers now absorb fulfillment costs to protect conversion rates, unbundling shipping from product pricing. This behavioral shift is most visible in Chinese megacities where same-day fulfillment has become the baseline competitive requirement.
Last Mile Delivery Transportation Market Segmentation
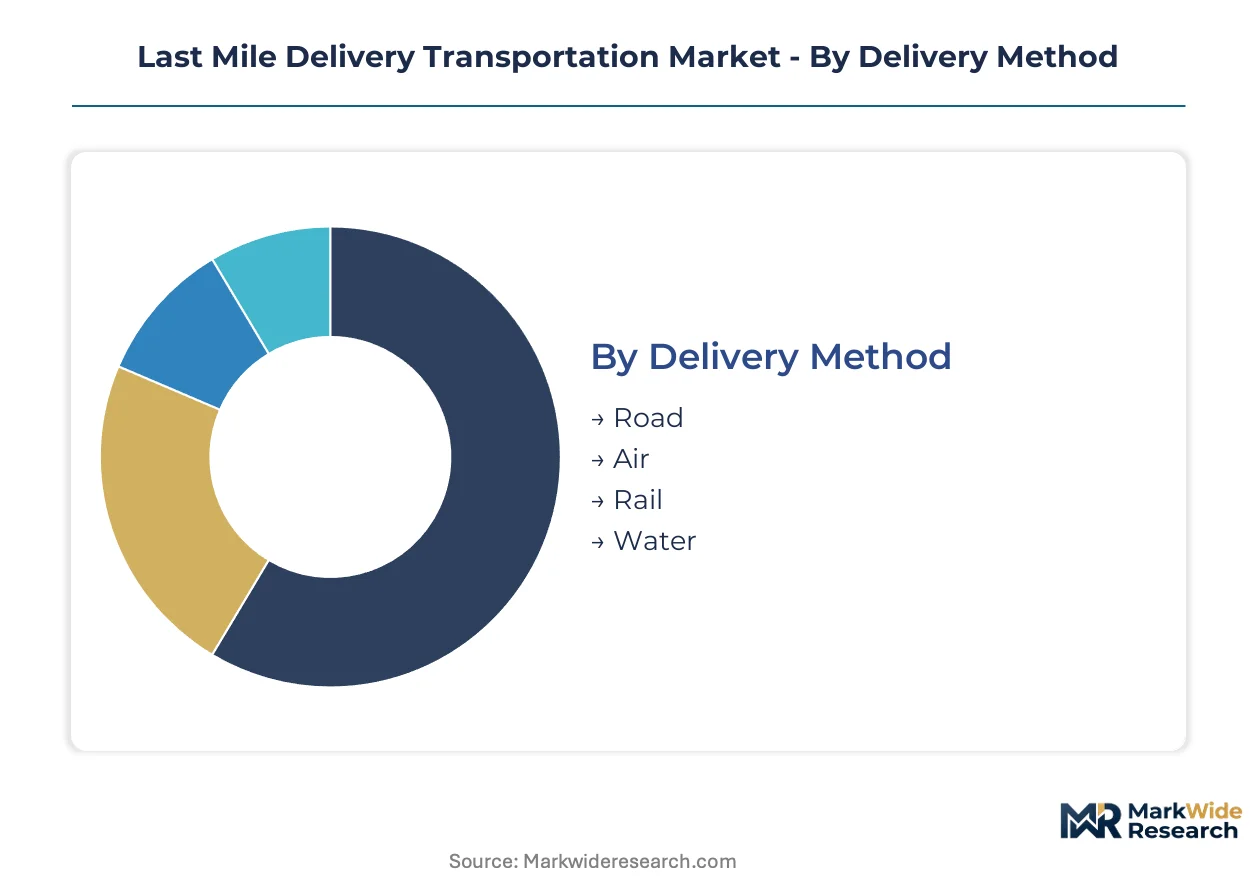
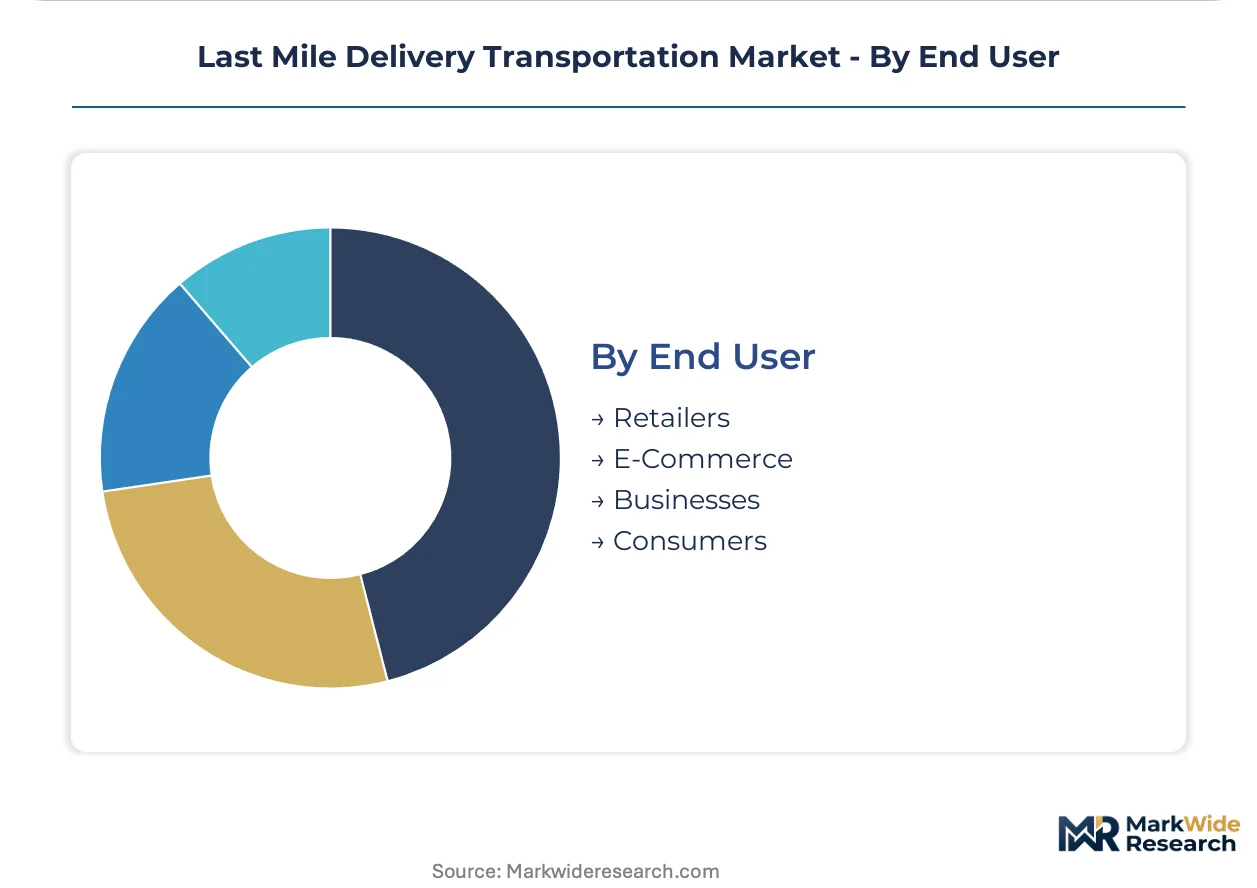
Last mile delivery transportation segments fragment across operational modality, vehicle technology, service commitment, and buyer category. Each dimension carries distinct regulatory exposure and capital intensity profiles that reshape procurement priorities for fleet operators and platform investors.
Delivery Method:
EPA tailpipe standards and EU Green Deal benchmarks apply asymmetric pressure across transport modes, accelerating modal shift economics in urban corridors.
- Road:Dominant modality utilizing asphalt infrastructure for parcel and freight movement from distribution hubs to final destinations. Dense urban networks in China and Germany concentrate investment here as operators optimize route density against diesel phase-out timelines.
- Air:Unmanned aerial systems and traditional cargo aircraft serve time-critical medical and document verticals. China's NMPA drone certification framework enables pilot programs in Shenzhen and Shanghai megacorridors where ground congestion erodes speed premiums.
- Rail:Urban light rail and freight spurs support bulk container movement to neighborhood distribution nodes. Japanese METI infrastructure subsidies sustain limited deployment for high-volume retail replenishment.
- Water:Canal and riverine freight serves low-density coastal and riparian markets with minimal infrastructure investment. Dutch port-to-city barge networks demonstrate viability where waterway access aligns with fulfillment node placement.
Established volume favors Road; emerging adoption favors Air.
Vehicle Type:
Procurement patterns cluster around payload capacity, electrification readiness, and autonomy integration potential.
- Trucks:Medium-duty Class 3-7 vehicles with 10,000-26,000 pound GVWR handle bulk retail and B2B freight. EPA heavy-duty standards now mandate zero-emission procurement timelines for urban delivery fleets operating in California and New York corridors.
- Vans:Compact commercial vehicles dominate parcel density optimization in European and North American suburbs. EU member state purchase subsidies compress payback periods for electric van deployment against diesel equivalents.
- Motorcycles:Two-wheelers navigate congestion in Southeast Asian and Latin American megacities where infrastructure constraints limit four-wheeled access. India's FAME-II subsidies support electric two-wheeler adoption for hyperlocal food and grocery platforms.
- Drones:Autonomous aerial systems under 25kg payload serve urgent medical and premium document segments. FAA Part 107 waivers and China's NMPA pathways enable controlled airspace operations with expanding beyond-visual-line-of-sight permissions.
Fleet concentration favors Vans; steepest expansion trajectory favors Drones.
Service Type:
Customer commitment structures determine asset utilization models and margin compression exposure.
- Same-Day:Fulfillment commitment within 24 hours demanding micro-warehouse proximity and dynamic routing algorithms. Chinese e-commerce platforms absorb fulfillment costs to protect conversion rates in Beijing and Shanghai markets.
- Scheduled:Pre-arranged delivery windows optimizing route consolidation and driver productivity. German parcel locker networks enable scheduled pickup alternatives that reduce failed delivery rates.
- On-Demand:Immediate fulfillment triggered by real-time demand signals with premium pricing. Food and pharmacy chains deploy this model in dense urban cores where speed commands margin recovery.
- Subscription:Recurring volume commitments from e-commerce platforms enabling dedicated fleet optimization. Predictable demand curves allow operators to amortize electric vehicle capital across utilization guarantees.
Margin stability favors Subscription; volume expansion favors Same-Day.
End User:
Buyer category dictates route density, packaging requirements, and regulatory compliance scope.
- Retailers:Brick-and-mortar chains utilizing delivery as omnichannel fulfillment extension. Store-based inventory positioning supports same-day service in suburban markets with established parking and loading infrastructure.
- E-Commerce:Digital platforms driving fulfillment compression through captive logistics networks. JD Logistics and Amazon Logistics vertically integrate warehouse-to-door operations to control customer experience.
- Businesses:B2B freight requiring palletized handling and scheduled dock access. Manufacturing and wholesale buyers prioritize reliability over speed, sustaining traditional carrier relationships.
- Consumers:Individual recipients with fragmented demand patterns and high failed-delivery rates. Parcel locker density and alternative pickup points reduce last-mile cost exposure for this segment.
Volume concentration favors E-Commerce; margin protection favors Businesses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes last mile delivery capacity through vertically integrated e-commerce fulfillment networks, while Germany and the United States rely more heavily on parcel locker infrastructure and subcontracted carrier relationships to manage urban density.
China
JD Logistics and ZTO Express operate hyper-dense urban networks serving same-day delivery expectations in Beijing and Shanghai. MIIT new-energy vehicle mandates accelerate electric van procurement timelines for fleet operators. Shenzhen and Hangzhou anchor autonomous delivery robot pilots through NMPA drone certification pathways.
Germany
Deutsche Post DHL Group maintains Europe's densest parcel locker infrastructure across Berlin, Hamburg, and Munich metropolitan corridors. EU Green Deal emission benchmarks mandate carbon intensity disclosures across subcontracted delivery services. The Rhine-Ruhr industrial cluster concentrates electric cargo bicycle feeder operations linked to locker networks.
United States
Amazon Logistics leverages captive e-commerce volume to sustain vertically integrated fulfillment networks in Los Angeles, New York, and Chicago. EPA heavy-duty vehicle standards phase down internal combustion engine allowances for Class 3-7 delivery fleets. California's Advanced Clean Trucks regulation forces zero-emission procurement timelines ahead of federal mandates.
India
Hyperlocal food and grocery platforms deploy electric two-wheelers through congested Mumbai and Bengaluru street networks. FAME-II subsidies support electric motorcycle adoption for last mile operators navigating infrastructure constraints. The Delhi-NCR corridor experiments with cargo bicycle consolidation hubs for dense urban cores.
Netherlands
Port-to-city barge networks serve Amsterdam and Rotterdam fulfillment nodes with minimal road infrastructure investment. EU member state purchase subsidies compress payback periods for electric van deployment against diesel equivalents. The Randstad megalopolis integrates waterborne freight with electric last mile feeder systems.
Last Mile Delivery Transportation Market Competitive Environment
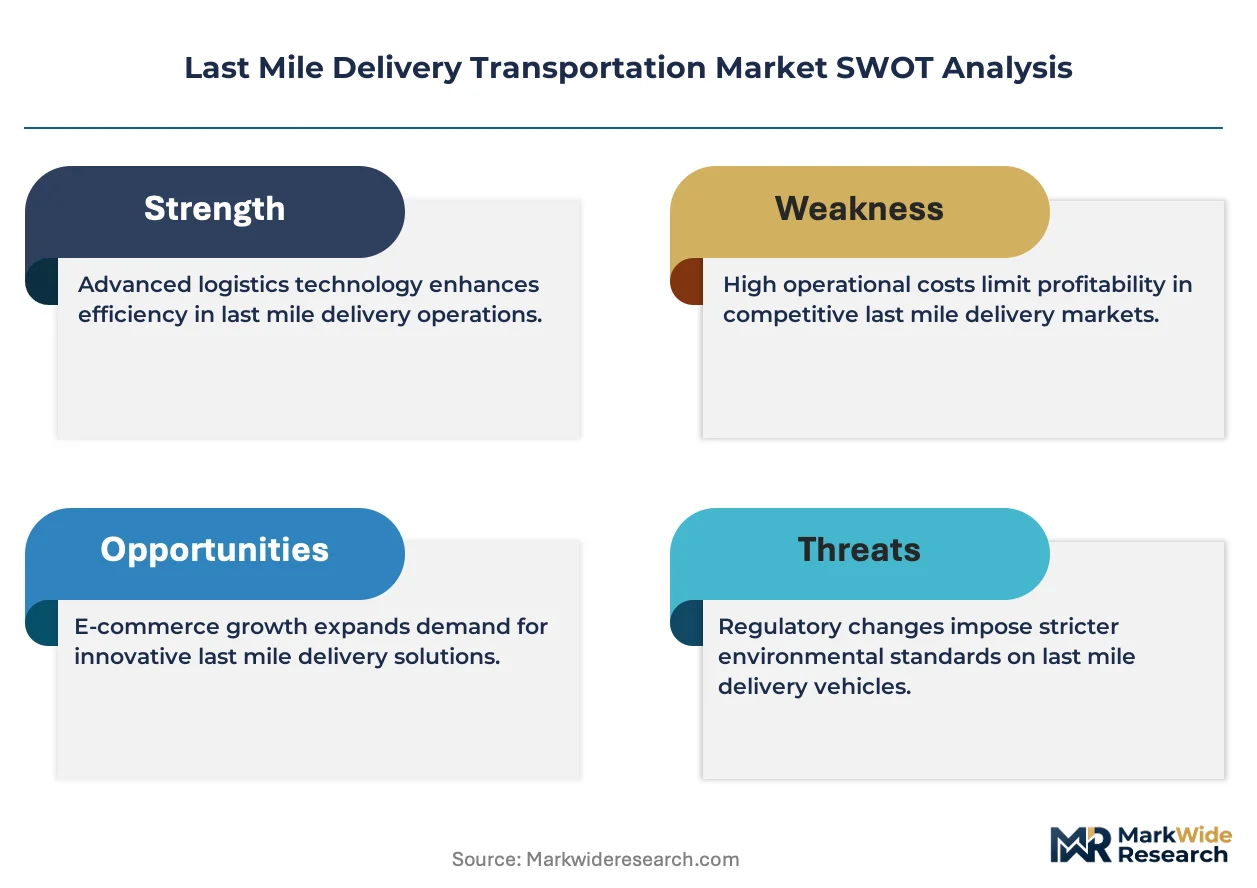
A small set of integrated leaders sits above a broader specialist tier, with captive e-commerce logistics networks controlling volume flows while pure-play carriers compete on route density and locker infrastructure. The market structure separates vertically integrated platforms from asset-heavy postal incumbents and emerging autonomous technology specialists. Dominant competitive moves include fleet electrification commitments tied to regulatory compliance timelines and micro-fulfillment network densification in urban cores.
Among integrated platform operators, Amazon Logistics and JD Logistics exemplify the captive-volume archetype, while Deutsche Post DHL Group occupies a position bridging postal infrastructure with electric fleet transformation. These three anchors represent divergent strategic postures: e-commerce-native vertical integration, state-linked logistics scale, and incumbent infrastructure adaptation.
| Leading Market Players |
|---|
| Amazon Logistics |
| FedEx Corporation |
| United Parcel Service (UPS) |
| Deutsche Post DHL Group |
| XPO Logistics |
| JD Logistics |
| ZTO Express |
| DPD Group |
| DB Schenker |
| Others |
Value Chain & Pricing Dynamics
Fleet utilization rates above 80 percent in Chinese megacity corridors anchor pricing power for asset-heavy operators while compressing margins for fragmented subcontractors. This density-driven scale advantage concentrates procurement leverage among vertically integrated platforms and reshapes price floors across subscription and on-demand service tiers.
Pricing Analysis
After-sales service contracts and extended maintenance agreements drive lifetime value for electric fleet operators facing battery degradation risks. Three-tier pricing structure across premium, standard, and economy levels separates same-day fulfillment from scheduled and subscription-based delivery commitments. Pricing pressure stems from lithium-ion cathode cost volatility concentrated in Chinese processing facilities. E-commerce platforms exhibit lowest price sensitivity as they absorb fulfillment costs to protect conversion rates, while independent retailers face acute margin compression.
Supply Chain Analysis
Panama Canal transit constraints and Red Sea routing disruptions expose just-in-time battery cell deliveries to cascading delays. Lithium carbonate processing draws from Chilean and Australian mining operations, with cathode manufacturing concentrated in China and South Korea. Single-source vulnerability in semiconductor-based battery management systems creates procurement risk for fleet electrification timelines. Distribution runs through regional hub-and-spoke networks anchored by micro-fulfillment centers in dense urban cores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across last mile delivery creates entry niches as e-commerce fulfillment expectations splinter across same-day, scheduled, and subscription service tiers. This demand-side divergence rewards specialists who anchor around single commitment structures rather than competing for full-spectrum coverage.
For Market Incumbents: Compound route density advantages through parcel locker network expansion in German and Dutch metropolitan corridors. Defend against autonomous delivery robot pilots by accelerating electric cargo bicycle feeder operations linked to fixed infrastructure. Invest in high-voltage technician training pipelines to close the skills gap widening against fleet electrification schedules.
For New Entrants and Emerging Players: Rural and semi-urban coverage gaps in North American and European markets offer white-space expansion where incumbent networks optimize for urban density. Target pharmaceutical and urgent document verticals where drone certification pathways enable premium pricing above ground-based alternatives. Pursue hospital system partnerships as anchor demand for medical delivery specialization.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-model fleet operators with e-commerce platform volume guarantees. Long-term viability favors asset-light technology enablers over capital-intensive vehicle ownership models. Monitor FAA Part 107 waiver expansion and EU Green Deal subsidy renewal schedules as inflection indicators for autonomous and electric deployment economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Network Densification | Urban warehouse proximity compresses same-day delivery cost structures below human courier economics in Beijing and Shanghai corridors. |
| Electric Fleet Procurement Commitment | EPA heavy-duty standards and EU Green Deal benchmarks mandate zero-emission vehicle transitions ahead of diesel phase-out timelines. |
| Autonomous Delivery Pilot Expansion | NMPA drone certification and FAA Part 107 waivers enable beyond-visual-line-of-sight operations for medical and document verticals. |
| Parcel Locker Infrastructure Buildout | German and Dutch locker density reduces failed delivery rates while enabling electric cargo bicycle feeder operations. |
| Technician Training Pipeline Investment | High-voltage systems diagnostics and battery management module repair capabilities lag fleet electrification schedules across North America. |
Study Parameters
Operator-level perspectives from fleet managers, e-commerce logistics directors, electric vehicle procurement leads, and last mile technology vendors anchored the qualitative base. These primary inputs combined with secondary validation from EPA regulatory filings, EU Green Deal implementation documents, MIIT new-energy vehicle mandate disclosures, and customs trade data for lithium-ion cell imports. Bottom-up route-density modeling and top-down market sizing triangulated volume estimates across delivery method, vehicle type, and service commitment dimensions.
Sensitivity analysis tested forecast outputs against variable electrification timelines, autonomous vehicle regulatory acceleration scenarios, and e-commerce penetration rate assumptions across the projection horizon. Segmentation dimensions modeled include delivery method, vehicle type, service commitment, and end user category, with regional regulatory cluster and urban density tier as cross-cutting variables. CAGRs derived from logistic curve fitting against historical adoption patterns, incorporating fleet turnover rates and charging infrastructure deployment curves as industry-specific inputs.
Material uncertainties — lithium supply chain disruptions, autonomous vehicle safety certification delays, and subsidy regime changes — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory compliance timelines and route-density economics. Practitioners should keep alternative scenarios live as EPA tailpipe standard enforcement intensity and EU member state purchase subsidy renewal schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Freight Forwarding Market
Logistics and Shipping
Europe Courier, Express and Parcel (CEP) Market
Logistics and Shipping
Carrier-Agnostic Parcel and Freight Visibility Aggregation Market
Logistics and Shipping
UAE Logistics Market
Logistics and Shipping
Vietnam Freight and Logistics Market
Logistics and Shipping
Global Sea Air Logistics Market
Logistics and Shipping
Mexico 3PL Market
Logistics and Shipping
Malaysia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Internet of Things (IoT) in Logistics Market
Logistics and Shipping
Russia 3PL Market
Logistics and Shipping
Tennessee Freight and Logistics Market
Logistics and Shipping
GCC Contract Logistics Market
Logistics and Shipping
Global Load Planning Services and Solutions Market
Logistics and Shipping
Vehicle Routing and Scheduling Market
Logistics and Shipping
GCC Secure Logistics Market
Logistics and Shipping
China International Courier, Express, and Parcel (CEP) Market