
 US Air Freight Transport Market | 2026-2036
US Air Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
US Air Freight Transport Market Insights
The US air freight sector is recalibrating around a widening split between premium express services and deferred commodity movements, as shippers trade speed against inventory carrying costs. FedEx Corp. dominates the integrated express segment through its Memphis superhub and controlled fleet operations. Atlas Air Worldwide Holdings anchors long-haul international capacity with dedicated freighter aircraft serving e-commerce and logistics providers. DHL Group competes through its Cincinnati/Northern Kentucky hub, leveraging European network connectivity into US domestic distribution.
Air freight transport encompasses the commercial movement of goods via fixed-wing aircraft, operating within weight-and-balance limits typically ranging from narrow-body belly cargo below twenty tons to wide-body freighters exceeding one hundred tons payload, with primary purpose being time-definite delivery for supply chains where inventory velocity outweighs surface transport economics. Express service commands premium pricing through guaranteed delivery windows, while perishable goods payload types are expanding fastest as pharmaceutical cold chain and fresh food logistics deepen temperature-controlled air capacity requirements. Charter delivery models capture episodic demand surges that scheduled networks cannot accommodate, concentrating margin pools in peak season retail and automotive production recovery scenarios.
FAA regulations govern aircraft certification, crew rest, and route operations, while TSA cargo screening mandates shape facility investments and throughput economics at origin airports. EPA emissions standards for ground support equipment and aircraft auxiliary power units are pressuring fleet renewal timelines and airport infrastructure spending. Stakeholders must monitor how FAA NextGen implementation progresses against congestion at Chicago O'Hare, Atlanta Hartsfield-Jackson, and Los Angeles International, as slot constraints determine which carriers can scale scheduled freighter operations.
Market Dynamics
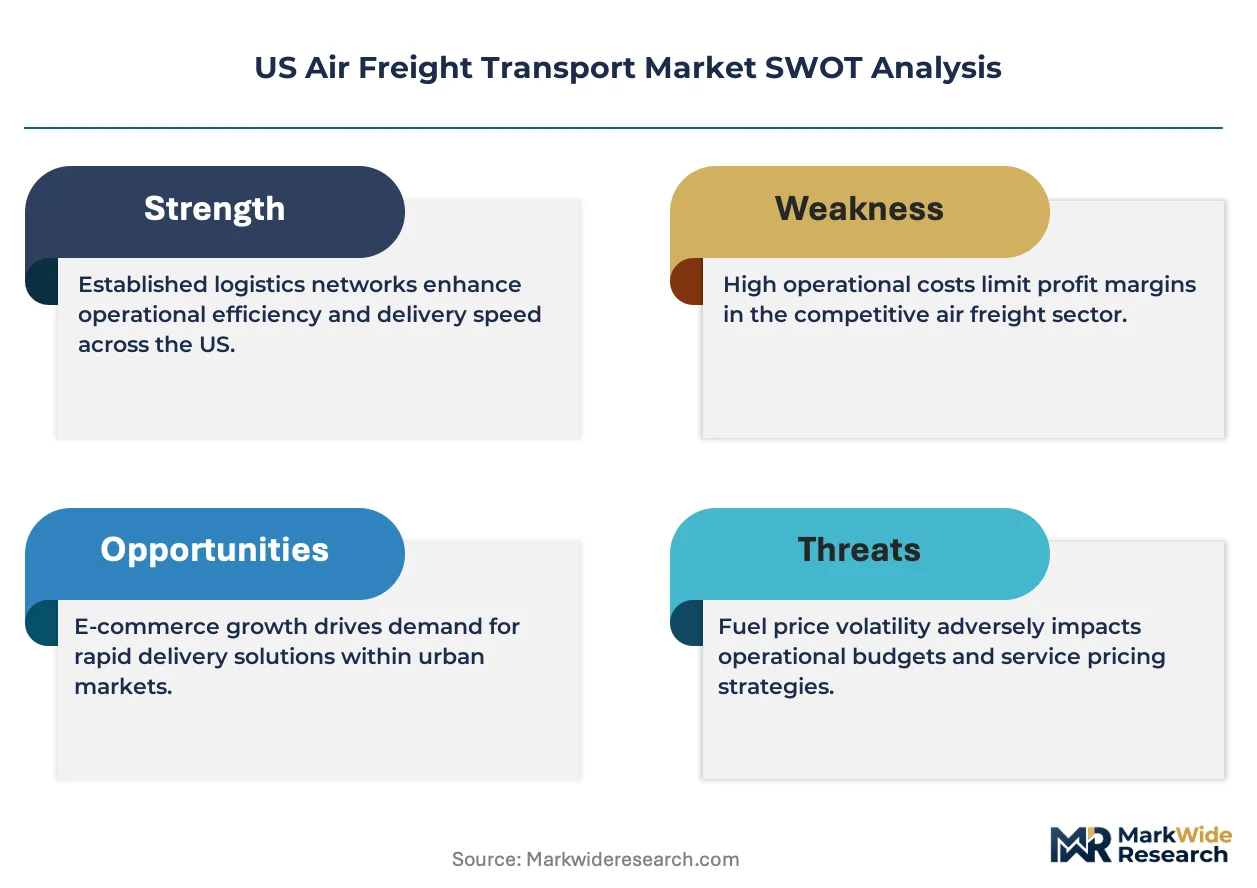
FAA NextGen air traffic modernization is compressing route times and slot capacity at congested hubs, forcing carriers to reoptimize fleet deployment around time-definite service guarantees rather than pure tonnage economics.
Growth Catalysts
- E-commerce fulfillment velocity:Amazon and Shopify merchants are locking multi-year contracts for next-day air capacity, pulling wide-body freighter demand into the Texas-California corridor.
- Pharmaceutical cold chain mandates:FDA temperature validation requirements for biologics are expanding certified refrigerated air transport volumes at Cincinnati and Memphis hubs.
- Memphis superhub slot expansion:Tennessee airport authority infrastructure investments are adding controlled-environment cargo gates dedicated to express parcel throughput.
Market Restraints
- Pilot shortage constraints:FAA Part 121 crew rest regulations are limiting available flight hours per aircraft, capping effective freighter utilization rates below theoretical maximums.
- Jet fuel price volatility:Kerosene derivatives constitute 35-45% of operating costs for scheduled freighter operators, compressing margins when crude benchmarks spike.
- Ground handling concentration:Three major service providers control 70% of US airport cargo terminal operations, creating chokepoint risk during peak retail seasons.
Strategic Opportunities
- Midwest distribution hub gap:Ohio and Indiana lack sufficient wide-body freighter capacity relative to their manufacturing density, creating white space for new scheduled services.
- Blockchain documentation convergence:Smart contract integration with customs filing systems is reducing clearance friction for cross-border e-commerce parcels.
- IRA clean energy incentives:Federal tax credits for sustainable aviation fuel production are lowering net fuel costs for early-adopting cargo carriers.
Industry Challenges
- Certified aircraft mechanic scarcity:FAA Airframe and Powerplant license holders are retiring faster than training programs replenish, extending maintenance turnaround times.
- Legacy warehouse management integration:Older cargo terminals at Chicago O'Hare and Newark Liberty require multimillion-dollar retrofits to interface with real-time tracking APIs demanded by large shippers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Air Freight Transport Market |
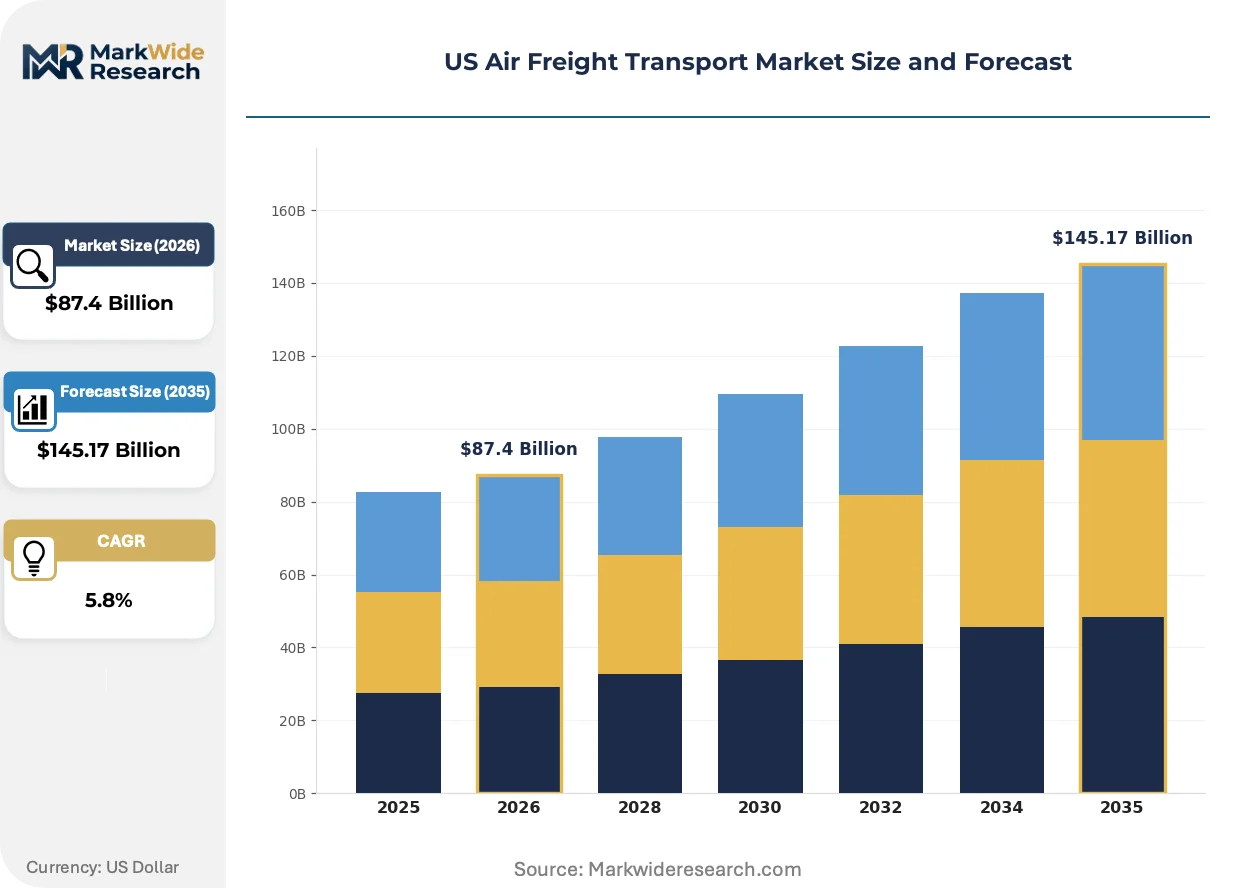
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $145.17 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express, Standard, Charter, Deferred Payload Type: General Cargo, Hazardous Materials, Live Animals, Perishable Goods Delivery Model: Door-to-Door, Airport-to-Airport, Hub-and-Spoke, Direct Shipment Customer Type: Enterprises, Retailers, E-commerce, Logistics Providers |
| Companies Covered | United Parcel Service Inc., FedEx Corp., DHL Group, Atlas Air Worldwide Holdings, Kuehne + Nagel, DSV A/S, C.H. Robinson Worldwide Inc., Expeditors International, DB Schenker, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Air Freight Transport Market Trends and Innovations
Digital freight matching platforms and autonomous ground support equipment are compressing the time between arrival and departure, reshaping how carriers monetize aircraft hours.
Autonomous cargo drones are rewriting last-mile economics for high-value parcels. Medical device distributors and luxury goods retailers are piloting 50-pound-payload electric vertical-takeoff systems for hospital-to-hospital and boutique-to-customer delivery. The technology is rewriting the boundary between air and ground transport by eliminating driver labor and airport access constraints.
FAA Reauthorization Act mandates for unmanned aircraft system integration are forcing cargo terminals to designate drone corridors and vertiport space. The industrial consequence is reduced tarmac availability for conventional freighter parking. Express carriers operating at Dallas-Fort Worth and Phoenix Sky Harbor are responding by negotiating exclusive drone zone leases with airport authorities.
Shippers are unbundling expedited transport from full logistics contracts, preferring spot-market procurement through digital freight platforms for non-contract volumes. Large retail procurement teams are displacing annual rate agreements with dynamic pricing algorithms that source capacity across multiple carriers. This pattern is most visible in California inbound freight from Asia-Pacific manufacturing clusters.
US Air Freight Transport Market Segmentation
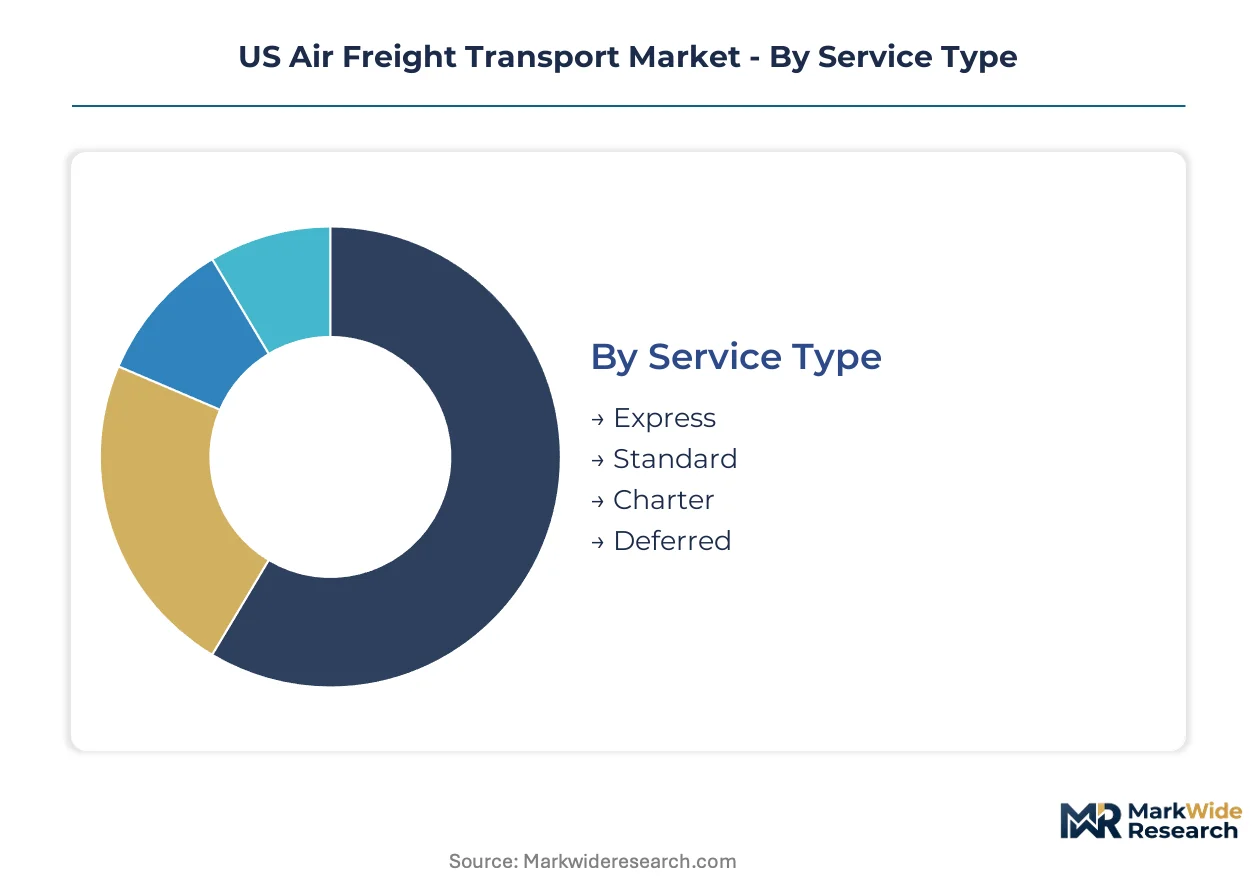
Segmentation in US air freight reveals how capital deployment and operational complexity fragment across service tiers. Carriers must match aircraft configuration, ground infrastructure, and network topology to each segment's velocity requirements and margin structure.
Service Type:
Capital intensity peaks in segments requiring dedicated freighter fleets and controlled hub infrastructure, with overnight networks demanding the heaviest fixed-asset commitment.
- Express:Time-definite delivery guarantees within 24-48 hours using controlled freighter networks and automated sortation hubs. Memphis and Louisville superhubs concentrate this capacity for pharmaceutical and high-value electronics shippers facing stockout costs.
- Standard:Scheduled belly cargo and deferred freighter space operating on 3-5 day transit windows. Texas-California corridor manufacturers leverage this tier for inventory replenishment where air cost still undercuts expedited ocean plus safety stock carrying charges.
- Charter:Episodic whole-aircraft deployment for automotive production recovery and peak retail surges. Demand concentrates in Q4 from California inbound Asia-Pacific freight when scheduled capacity saturates.
- Deferred:Lowest-priority belly space on passenger flights, filling load factors during off-peak periods. Consolidators aggregate this capacity for price-sensitive apparel and footwear distribution to Midwest distribution centers.
Most installed capacity flows through Standard services. Expansion is steepest in Express as e-commerce merchants lock multi-year next-day contracts.
Payload Type:
Regulatory compliance and handling infrastructure drive cost tiering, with temperature-validated segments commanding specialized equipment investments.
- Perishable Goods:Temperature-controlled transport for pharmaceuticals, fresh seafood, and floral products requiring continuous cold chain documentation. FDA validation mandates at Cincinnati and Miami International are expanding certified refrigerated gate capacity for biologics distributors.
- General Cargo:Non-specialized freight including machinery components, automotive parts, and consumer electronics. Midwest manufacturing clusters generate the densest demand flows for this segment through Chicago O'Hare and Detroit Metropolitan.
- Hazardous Materials:ICAO-classified dangerous goods requiring segregated loading, fire suppression systems, and specialized crew training. Oilfield chemicals from Texas and lithium battery shipments from California dominate this constrained capacity pool.
- Live Animals:Equine transport and breeding stock movements with veterinary oversight and climate-controlled compartments. Kentucky-Thoroughbred corridor and Florida breeding operations sustain this niche.
Perishable Goods absorb the highest infrastructure spending per ton. General Cargo retains the largest volume base.
Delivery Model:
Network topology determines asset utilization rates, with hub-dependent models requiring more aircraft and ground equipment than point-to-point alternatives.
- Hub-and-Spoke:Centralized sortation through Memphis, Louisville, or Cincinnati with feeder aircraft radiating to origin markets. FedEx and UPS dominate this topology where density economics justify massive fixed-hub investment.
- Door-to-Door:Integrated pickup and delivery using ground fleet extensions from airport facilities. E-commerce fulfillment networks in Dallas-Fort Worth and Los Angeles are expanding last-mile air-ground connectivity.
- Airport-to-Airport:Terminal-to-terminal service where consignees arrange ground transport. Freight forwarders aggregate this capacity for Los Angeles-Anchorage-Asia transpacific lanes.
- Direct Shipment:Non-stop freighter operations bypassing intermediate hubs. Automotive suppliers use this model for Mexico City-Detroit production line feed when just-in-sequence tolerance tightens.
Hub-and-Spoke moves the highest tonnage volumes. Direct Shipment is climbing fastest as manufacturers compress supply chain nodes.
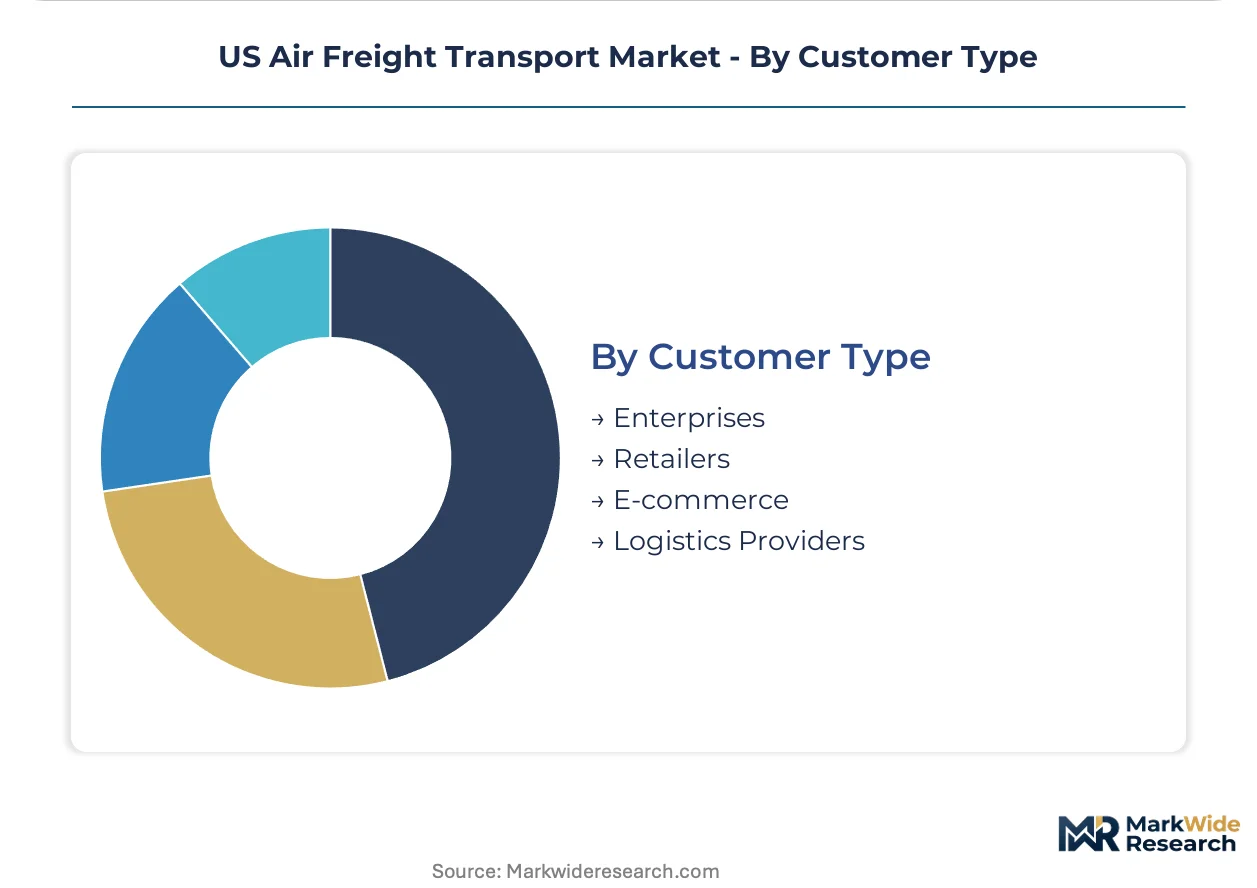
Customer Type:
Procurement scale and contract structure differentiate segments, with enterprise accounts driving scheduled capacity commitments and spot-market liquidity.
- E-commerce:Platform merchants and marketplace sellers requiring velocity-competitive delivery promises. Amazon's air network expansion in Kentucky and Texas is pulling dedicated freighter capacity from traditional carriers.
- Enterprises:Large manufacturers with annual contracted lanes and volume guarantees. Aerospace and medical device producers in California and Massachusetts anchor this segment with predictable demand profiles.
- Logistics Providers:Third-party forwarders and NVOCCs aggregating fragmented shipper demand. These intermediaries concentrate in Chicago and New York-JFK, arbitraging capacity across carrier networks.
- Retailers:Department stores and specialty chains with seasonal demand spikes and inventory repositioning needs. Peak season surges from West Coast ports to Ohio distribution centers strain this segment's access to wide-body lift.
Enterprises lock the longest-term capacity contracts. E-commerce is gaining share fastest as merchant fulfillment networks deepen air dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pilot training academies and FAA-certified maintenance schools cluster disproportionately in the South and Midwest, anchoring workforce supply for freighter operations. This talent concentration shapes where carriers expand hub capacity and where MRO providers locate heavy maintenance facilities.
Texas
Amazon Air and traditional carriers compete for apron space at Dallas-Fort Worth International, where e-commerce fulfillment demand exceeds dedicated freighter gate availability. Texas Commission on Environmental Quality emissions rules for ground support equipment are accelerating electric baggage tractor procurement. The Dallas-Fort Worth-Arlington metroplex hosts the densest concentration of air cargo handlers outside Memphis, with new cold chain facilities breaking ground in 2024.
California
Los Angeles International and Ontario International absorb transpacific freighter volume from Asia-Pacific manufacturing clusters, with pharmaceutical distributors expanding temperature-controlled warehousing near runways. California Air Resources Board truck electrification mandates are reshaping last-mile ground connectivity from airport cargo terminals. The Inland Empire distribution corridor—Riverside and San Bernardino counties—generates the highest outbound deferred air freight tonnage for Midwest retail replenishment.
Tennessee
Memphis anchors the integrated express network through FedEx's superhub operations, where automated sortation systems process millions of packages nightly. Tennessee Department of Transportation infrastructure grants are funding controlled-environment cargo gate expansion. Nashville International is emerging as a secondary pharmaceutical distribution node, with cold chain investments from biologics manufacturers clustering near the airport perimeter.
Kentucky
Louisville's UPS Worldport processes the highest pure-parcel tonnage of any US airport, with workforce pipelines feeding from regional aviation maintenance programs. Kentucky Economic Development Finance Authority tax incentives are attracting e-commerce fulfillment warehouse construction. The Cincinnati/Northern Kentucky airport complex—spanning the Ohio River—concentrates DHL's US pharmaceutical cold chain operations under FDA-validated temperature controls.
Ohio
Cleveland Hopkins and Rickenbacker International serve automotive and industrial machinery shippers with scheduled freighter connections to European manufacturing hubs. Ohio Environmental Protection Agency diesel emissions regulations are pressuring older ground fleet replacement at cargo terminals. The Columbus region—leveraging its central location—hosts expanding air-ground intermodal facilities for retail distribution to East Coast population centers.
US Air Freight Transport Market Competitive Landscape
Top-tier vendors anchor integrated express networks, while asset-light forwarders and specialized freighter operators occupy distinct competitive tiers. The market structure concentrates around three strategic archetypes: carriers with controlled freighter fleets and hub infrastructure, logistics providers aggregating capacity across multiple airlines, and charter specialists serving episodic demand surges. Consolidation pressure is accelerating through hub slot scarcity and pilot availability constraints, while sustainable aviation fuel partnerships are emerging as a secondary competitive dimension.
Within the integrated carrier tier, FedEx Corp. and United Parcel Service Inc. exemplify the hub-and-spoke model through Memphis and Louisville superhub dominance. DHL Group occupies a position bridging European network connectivity with US domestic distribution. Atlas Air Worldwide Holdings anchors the dedicated freighter specialist archetype, providing long-haul international capacity to e-commerce and logistics platforms lacking owned fleet assets.
| Leading Market Players |
|---|
| United Parcel Service Inc. |
| FedEx Corp. |
| DHL Group |
| Atlas Air Worldwide Holdings |
| Kuehne + Nagel |
| DSV A/S |
| C.H. Robinson Worldwide Inc. |
| Expeditors International |
| DB Schenker |
| Others |
Pricing and Supply Chain Analysis
Amazon and Shopify merchants locking multi-year next-day capacity contracts are forcing carriers to unbundle express services from standard freight, compressing margins on deferred tiers while premium slots command scarcity rents at Memphis and Louisville superhubs.
Pricing Analysis
Bundled long-term contracts against unbundled spot-market procurement now defines the pricing landscape. Three-tier pricing structure across express, standard, and deferred levels segments buyers by velocity tolerance, with pharmaceutical shippers least sensitive and apparel consolidators most price-elastic. Cost compression in standard belly cargo is intensifying as passenger airlines prioritize high-yield freight over low-margin deferred space. Spot-market liquidity pools concentrate in California inbound lanes from Asia-Pacific manufacturing clusters.
Supply Chain Analysis
Regional distribution centers in the Inland Empire and Dallas-Fort Worth metroplex anchor hub-and-spoke patterns radiating through Memphis and Louisville. Wide-body freighter manufacturing draws from Boeing in Washington state and Airbus in France, while jet fuel supply rests on Gulf Coast refining and sustainable aviation fuel pilots in Montana. Single-source vulnerability concentrates in certified airframe mechanic training programs. Distribution runs through controlled-environment cargo gates at Cincinnati and Miami International for pharmaceutical cold chain validation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US air freight operates as a geographic-arbitrage play where Tennessee's absence of state income tax on aviation fuel against California's CARB ground fleet electrification mandates creates cost differentials for hub placement decisions.
For Market Incumbents: To counter Amazon Air's captive fleet expansion in Kentucky and Texas, FedEx and UPS must deepen controlled-environment gate investments at Memphis and Louisville while securing exclusive drone corridor leases at Dallas-Fort Worth under FAA Reauthorization Act mandates. Backward integration into sustainable aviation fuel offtake agreements with Montana biorefineries locks in cost advantages as IRA tax credits phase down. For New Entrants and Emerging Players: Begin with the Midwest distribution hub gap in Ohio and Indiana, where manufacturing density exceeds wide-body freighter capacity. White space exists in pharmaceutical cold chain services between Cleveland Hopkins and European manufacturing hubs. A go-to-market angle targeting automotive just-in-sequence suppliers with direct Mexico City-Detroit non-stop capacity bypasses incumbent hub congestion. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized freighter operators holding long-term ACMI contracts with e-commerce platforms, insulated from spot-market volatility. Long-term viability hinges on sustainable aviation fuel transition economics and NextGen slot allocation advantages. The signal to watch is FAA certification timelines for autonomous cargo drone corridors at Phoenix Sky Harbor and Dallas-Fort Worth.| Strategic Initiative | Industry Significance |
|---|---|
| Sustainable Aviation Fuel offtake agreements | IRA tax credits lower net fuel costs for early-adopting cargo carriers operating from Montana biorefineries. |
| Controlled-environment cargo gate expansion | FDA-validated temperature controls at Cincinnati capture pharmaceutical cold chain volume from biologics distributors. |
| Autonomous drone corridor leasing | FAA-mandated UAS integration forces exclusive vertiport negotiations at Dallas-Fort Worth and Phoenix Sky Harbor. |
| Midwest distribution hub development | Ohio and Indiana manufacturing density creates white space for scheduled wide-body services to European hubs. |
| Blockchain customs documentation integration | Smart contract convergence with CBP filing systems reduces clearance friction for cross-border e-commerce parcels. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cargo airline network planners, pharmaceutical logistics directors, airport authority infrastructure officers, and e-commerce fulfillment operations managers with secondary validation against FAA NextGen implementation reports, TSA cargo screening mandates, EPA emissions compliance filings, and Bureau of Transportation Statistics freight data. Bottom-up tonnage estimates from individual carrier route filings triangulated against top-down market sizing from national trade flow analysis.
Segment-weighting across service type, payload category, delivery model, and customer archetype shaped the analytical framework across the analysis window. CAGRs derived from carrier fleet deployment schedules, e-commerce fulfillment network expansion timelines, and pharmaceutical cold chain infrastructure investment pipelines. Forecast inputs incorporated FAA slot allocation projections and sustainable aviation fuel production capacity buildout under IRA incentives.
Several conditions sit outside the modeled scope, including sudden jet fuel price spikes exceeding historical volatility bands, pilot shortage constraints accelerating beyond FAA Part 121 crew rest regulation adjustments, and autonomous cargo drone certification delays. Forecasts reflect assumptions about NextGen implementation pace and e-commerce contract renewal rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Latin America Fourth Party Logistics (4PL) Market
Logistics and Shipping
US Fourth-Party Logistics (4PL) Market
Logistics and Shipping
Flat Rack Containers Market
Logistics and Shipping
Cambodia Freight and Logistics Market
Logistics and Shipping
Europe Container Terminal Operations Market
Logistics and Shipping
Singapore Last Mile Delivery Market
Logistics and Shipping
Peru Cold Chain Logistics Market
Logistics and Shipping
Vietnam Logistics Market
Logistics and Shipping
Car Carrier Market
Logistics and Shipping
North America Refrigerated Container Shipping Market
Logistics and Shipping
Jordan Freight and Logistics Market
Logistics and Shipping
Autonomous Last Mile Delivery Market
Logistics and Shipping
Brazil 3PL Market
Logistics and Shipping
South Korea Parcel Delivery Market
Logistics and Shipping
Pharmaceutical Logistics Market
Logistics and Shipping
Turkey Freight and Logistics Market