
 United Kingdom Surveillance Analog Camera Market | 2026-2036
United Kingdom Surveillance Analog Camera Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Surveillance Analog Camera Market Insights
GDPR is rebalancing liability exposure for operators maintaining analog surveillance estates across Britain. Bosch Sicherheitssysteme GmbH leverages its European manufacturing footprint to sustain competitive delivery timelines for UK integrators. Hikvision anchors its position through deep inventory of HD-TVI-compatible recorders that bridge legacy coaxial infrastructure. Axis Communications AB differentiates by steering commercial clients toward hybrid migration paths rather than wholesale analog replacement.
United Kingdom surveillance analog cameras capture video signals through charge-coupled device or complementary metal-oxide-semiconductor sensors, transmitting uncompressed footage over coaxial cable to digital video recorders with typical resolutions reaching 1080p via HD-TVI modulation. Bullet cameras dominate exterior perimeter deployments across British industrial estates and transport corridors where weatherproof housings and infrared illumination address low-light conditions. Dome cameras sustain stronger margin pools in retail security applications across UK shopping centers, where vandal-resistant enclosures and discreet positioning reduce replacement frequency. CMOS technology segments are gaining ground over CCD variants as sensor costs decline and power efficiency improves for continuous recording environments.
The Information Commissioner's Office enforces GDPR and the Data Protection Act 2018, mandating explicit signage, retention limits, and secure erasure protocols that increase operational overhead for analog system operators. BSI standards for electromagnetic compatibility and environmental testing shape product certification requirements for cameras deployed in UK public spaces. Stakeholders must weigh incremental HD-TVI upgrades against full IP migration timelines as coaxial infrastructure ages and compliance costs escalate.
Market Dynamics
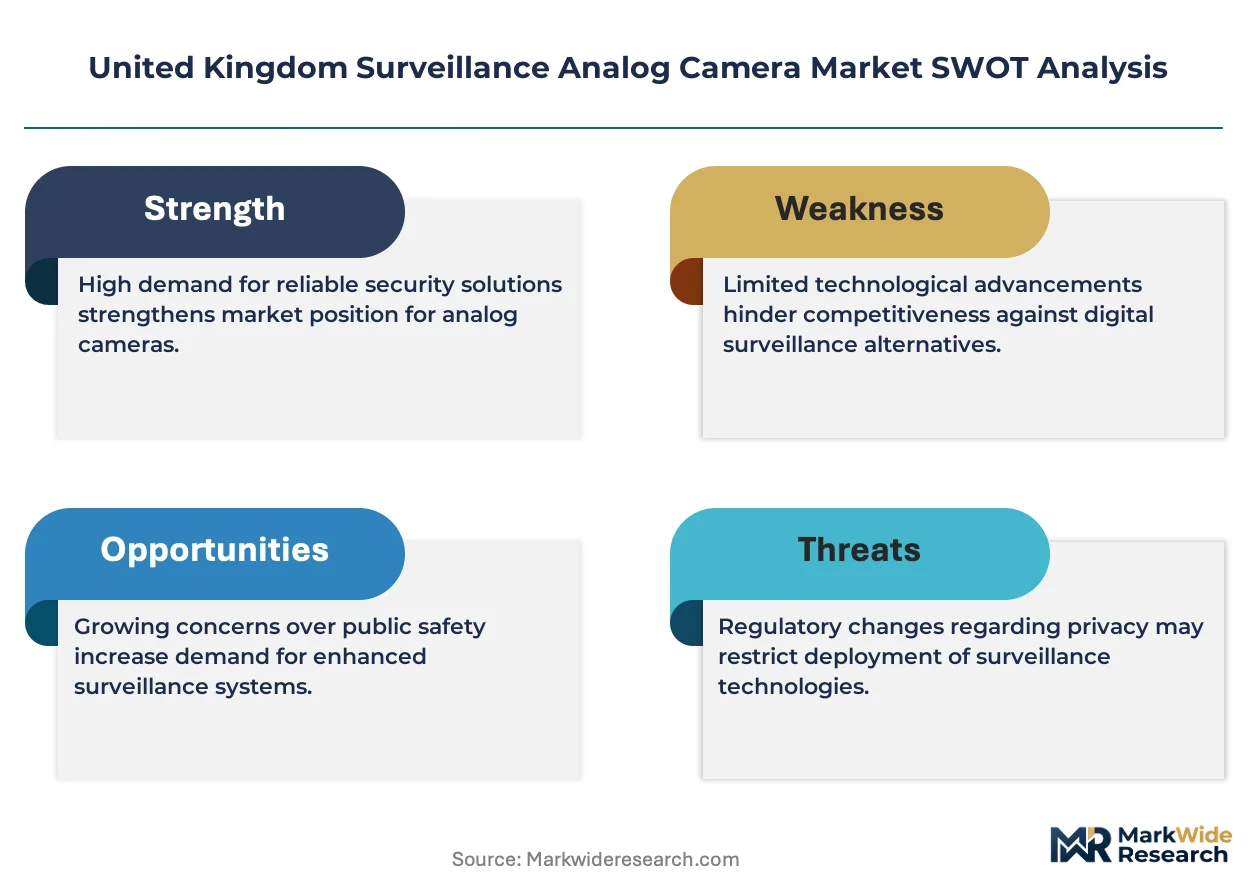
GDPR compliance obligations are forcing UK surveillance operators to reengineer analog storage and access protocols, creating a structural drag on legacy system economics while extending equipment replacement cycles through incremental HD-TVI upgrades.
Growth Catalysts
- Transport Authority Modernization:Greater London's borough councils and transport bodies are refreshing coaxial estates to extend infrastructure lifecycles rather than undertake wholesale IP migration, sustaining demand for compatible recording equipment.
- Data Protection Act Enforcement:The Information Commissioner's Office mandates explicit signage, retention limits, and secure erasure protocols that compel operators to upgrade analog storage systems to meet audit-ready compliance standards.
- HD-TVI Modulation:HD-TVI-compatible recorders enable 1080p resolution transmission over existing coaxial cable, allowing British industrial estates and retail security teams to defer full network infrastructure replacement.
Market Restraints
- Coaxial Infrastructure Depreciation:Aging copper cable installations across UK public housing and municipal estates require continuous maintenance, elevating total cost of ownership for analog system operators relative to fiber-ready IP alternatives.
- IP Substitution Pressure:Power-over-Ethernet cameras and cloud-managed surveillance platforms offer remote accessibility and analytics integration that coaxial-based systems cannot natively support, eroding analog's competitiveness in new-build projects.
- GDPR Operational Overhead:The Data Protection Act 2018 imposes explicit retention limits and subject access request fulfillment obligations that increase administrative burden for analog operators lacking automated metadata tagging.
Strategic Opportunities
- Hybrid Migration Pathways:Encoders and video management software bridging analog and IP domains allow British integrators to phase infrastructure replacement while preserving existing camera investments, opening margin pools in retrofit services.
- Retail Security Refresh Cycles:UK shopping centers face insurance-driven pressure to maintain visible surveillance coverage, creating replacement demand for vandal-resistant dome cameras even where full IP migration is capital-constrained.
- BSI Certification Differentiation:Electromagnetic compatibility and environmental testing standards for public space deployment create compliance barriers that certified suppliers can leverage to defend positioning against uncertified imports.
Industry Challenges
- Coaxial-to-IP Integration Complexity:British security integrators must manage heterogeneous estates where analog recorders, hybrid encoders, and native IP cameras coexist, requiring specialized troubleshooting skills that strain technical workforce availability.
- GDPR Evidence Chain Integrity:Analog footage lacks embedded timestamp and integrity verification metadata, forcing operators to implement parallel audit trails to satisfy Information Commissioner's Office scrutiny of evidentiary reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Surveillance Analog Camera Market |
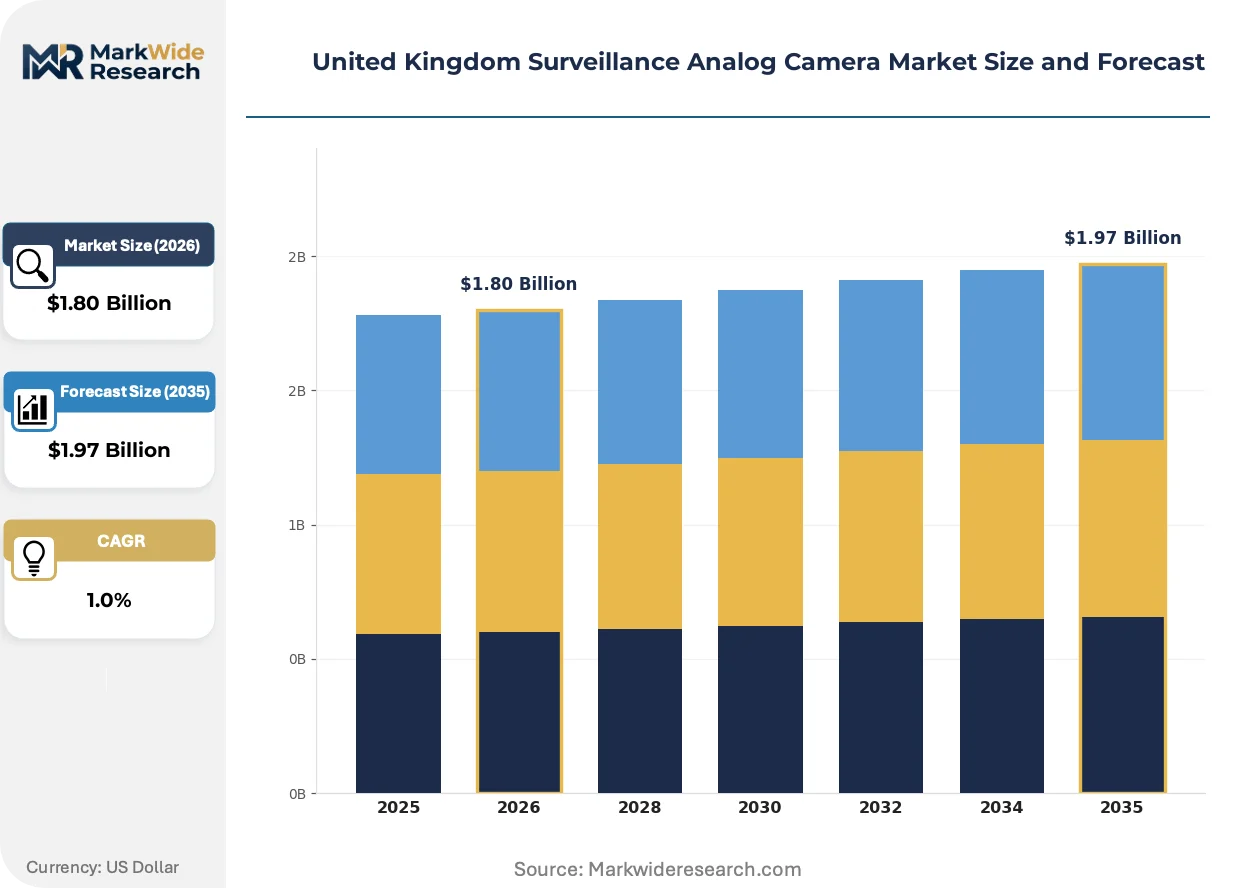
| Market Size in 2026 | $1.80 Billion |
| Market Size in 2035 | $1.97 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bullet Cameras, Dome Cameras, PTZ Cameras, Covert Cameras Technology: CCD, CMOS, Infrared, HD-TVI Application: Retail Security, Public Surveillance, Traffic Monitoring, Home Security End User: Government, Retailers, Enterprises, Residential Users |
| Companies Covered | Teledyne FLIR LLC, Bosch Sicherheitssysteme GmbH, Axis Communications AB, Hanwha Vision Europe, Johnson Controls Inc., Hikvision, Dahua Technology, Honeywell International Inc, Motorola Solutions, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Surveillance Analog Camera Market Trends and Innovations
Surveillance technology trajectories in Britain are converging on bridge solutions that defer infrastructure replacement while regulatory pressure accelerates compliance investment in legacy estates.
CMOS sensor technology is absorbing market share from CCD variants across UK analog camera deployments. British transport authorities and industrial security teams are specifying CMOS-equipped bullet and dome cameras for new installations and replacement cycles. The technology is absorbing cost-sensitive demand segments as sensor pricing declines and power efficiency improves for continuous recording environments.
The Data Protection Act 2018 and GDPR retention mandates are tightening operational protocols for analog system operators. The Information Commissioner's Office enforces explicit signage requirements, data minimization periods, and secure erasure procedures that elevate compliance tooling expenditure. Retail and municipal surveillance estates across England and Wales are most affected, with operators deploying automated deletion workflows and access logging systems to satisfy audit requirements.
British procurement patterns for surveillance infrastructure are compressing replacement cycles in high-liability verticals while extending them in capital-constrained segments. Insurance underwriters are demanding refreshed coverage documentation from London transport operators and large retail chains, accelerating equipment refresh. Public sector buyers in Northern England and Scottish local authorities are prioritizing incremental HD-TVI upgrades over full IP migration, stretching vendor engagement timelines and service contract durations.
United Kingdom Surveillance Analog Camera Market Segmentation
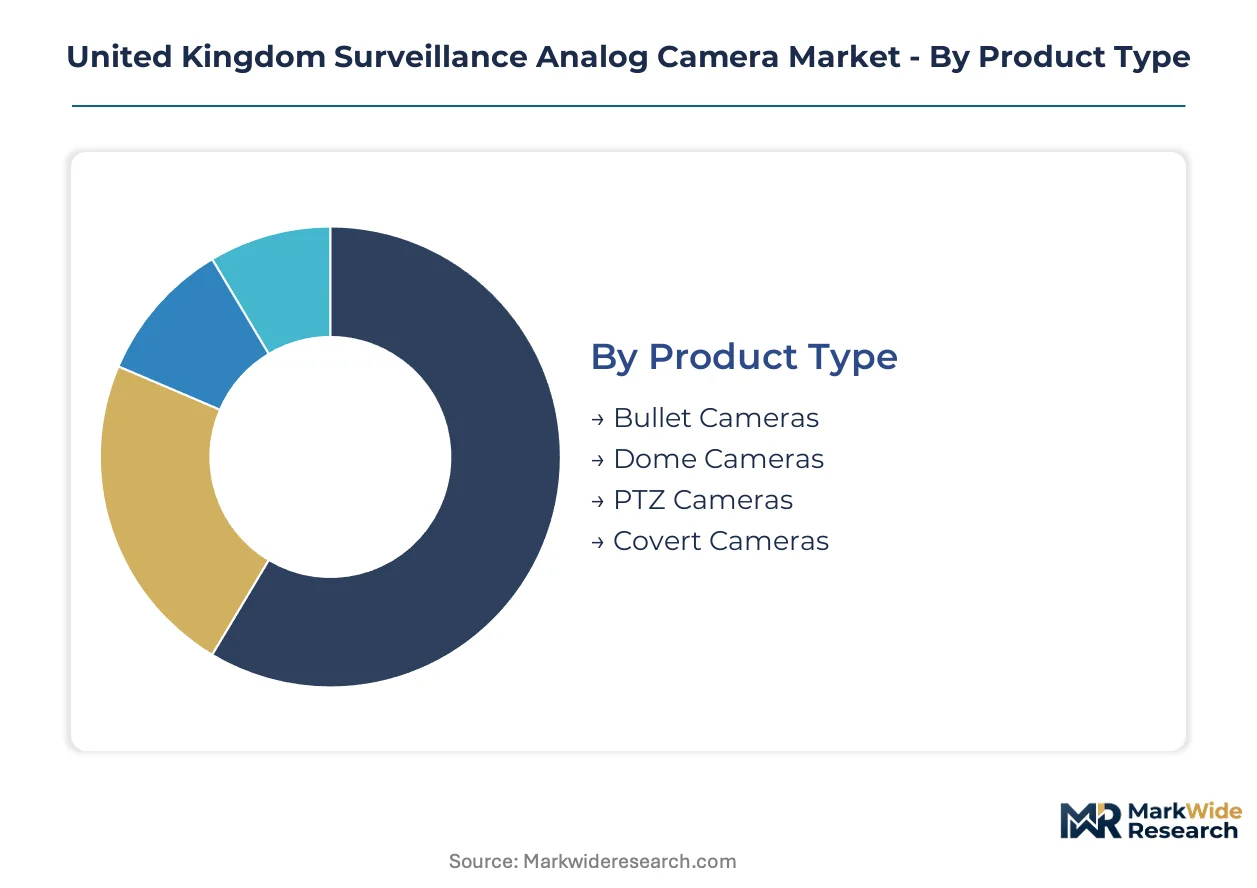
Segmentation in the United Kingdom surveillance analog camera market reveals how coaxial infrastructure constraints and compliance obligations reshape procurement patterns across distinct technical specifications and buyer categories. British operators balance incremental upgrade paths against full system replacement, fragmenting demand across sensor technologies, form factors, and end-use verticals with divergent capital cycles.
Product Type:
Form factor selection in British analog deployments tracks environmental exposure requirements and vandalism risk profiles across exterior and interior surveillance estates.
- Bullet Cameras:Weatherproof housings with infrared illumination dominate perimeter deployments across British industrial estates and transport corridors. Greater London's borough councils specify these for exterior infrastructure where coaxial cable runs already exist along motorway verges and rail sidings.
- Dome Cameras:Vandal-resistant enclosures sustain stronger margin pools in UK shopping centers and retail security applications. Insurance underwriters drive replacement demand for discreet positioning that reduces tampering frequency and extends equipment lifecycles in high-footfall environments.
- PTZ Cameras:Motorized pan-tilt-zoom mechanisms serve traffic monitoring applications across British arterial roads where operator-controlled coverage flexibility offsets higher unit costs.
- Covert Cameras:Disguised housings address discrete surveillance requirements in loss prevention scenarios within UK retail banking and high-value merchandise environments.
Bullet cameras lead on scale across municipal and transport estates; dome cameras lead on momentum in insurance-driven retail refresh cycles.
Technology:
Sensor and modulation specifications determine power consumption, resolution ceiling, and backward compatibility with aging coaxial infrastructure across British installations.
- CCD:Charge-coupled device sensors retain presence in legacy maintenance contracts where operators prioritize proven reliability over efficiency metrics. Declining sensor costs and power demands are compressing CCD's addressable market to replacement-only scenarios in Northern England and Scottish local authority estates.
- CMOS:Complementary metal-oxide-semiconductor technology is displacing CCD variants across new installations and refresh cycles. British transport authorities specify CMOS-equipped cameras for continuous recording environments where power efficiency improvements reduce operational overhead.
- Infrared:Dedicated IR illumination modules address low-light performance requirements in exterior British deployments where street lighting coverage is inconsistent.
- HD-TVI:High-definition transport video interface modulation enables 1080p resolution transmission over existing coaxial cable, allowing HD-TVI-compatible recorders to bridge legacy infrastructure toward compliance-ready storage without full IP migration.
HD-TVI leads on scale as the dominant bridge technology; CMOS leads on momentum as sensor pricing declines accelerate specification shifts.
Application:
End-use verticals in the UK analog camera market diverge sharply between compliance-driven public sector refresh and capital-constrained private sector extension of equipment lifecycles.
- Retail Security:UK shopping centers face insurance-mandated coverage documentation requirements that accelerate equipment refresh in Greater London and Southeast England. Vandal-resistant dome configurations dominate this vertical where visible surveillance deters theft and supports liability defense.
- Public Surveillance:Municipal CCTV estates across England and Wales confront GDPR retention mandates and Information Commissioner's Office audit protocols. Public sector buyers prioritize incremental HD-TVI upgrades over full IP migration, stretching vendor engagement timelines.
- Traffic Monitoring:British transport authorities manage large-scale coaxial estates along motorway networks and urban arterials where PTZ functionality enables operator-directed incident response.
- Home Security:Residential analog demand concentrates in retrofit scenarios where existing coaxial infrastructure defers full smart home migration costs.
Public surveillance leads on scale through municipal estate refresh; retail security leads on momentum from insurance underwriting pressure.
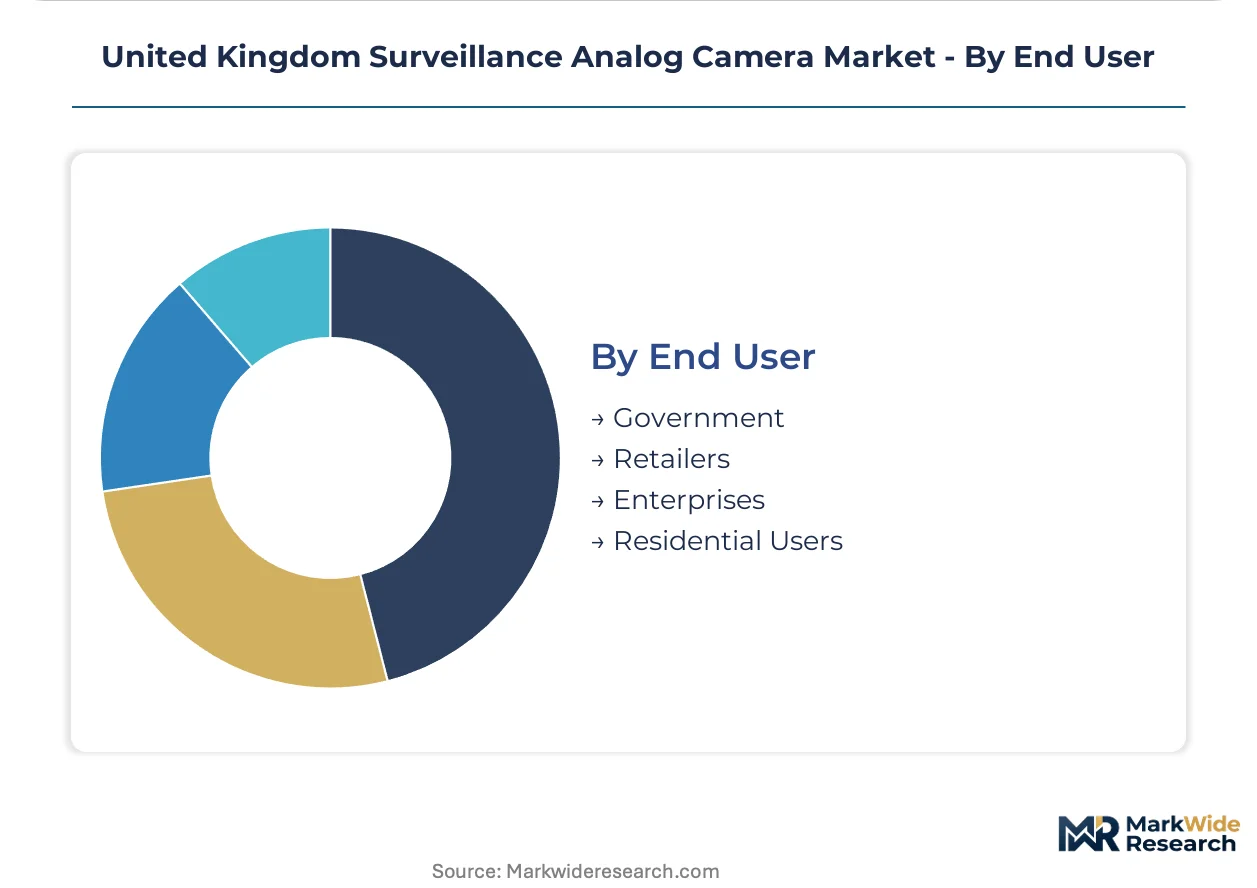
End User:
Buyer categories in the British analog camera market separate between compliance-obligated public procurement and margin-sensitive private sector capital allocation.
- Government:Central and local government bodies across Greater London boroughs and transport authorities manage the largest coaxial CCTV estates. GDPR and Data Protection Act enforcement compels these operators to upgrade storage and access protocols while deferring full infrastructure replacement.
- Retailers:UK shopping centers and high-street chains balance insurance-driven coverage requirements against capital constraints. This segment generates replacement demand for vandal-resistant dome cameras even where full IP migration timelines extend.
- Enterprises:British industrial estates and logistics facilities specify bullet cameras for perimeter coverage where weatherproofing and infrared performance address operational security requirements.
- Residential Users:Homeowners with existing coaxial infrastructure represent a shrinking addressable market as IP alternatives capture new-build and full-renovation scenarios.
Government procurement leads on scale through transport and municipal estate management; retailers lead on momentum from insurance documentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom's surveillance infrastructure traces its modern lineage to the 1990s expansion of municipal CCTV networks, with coaxial-based systems now concentrated in legacy public sector estates across England, Scotland, Wales, and Northern Ireland.
Greater London and Southeast England
Transport for London and borough councils manage the nation's largest coaxial CCTV estates along motorway verges and rail corridors. The Information Commissioner's Office enforces GDPR retention mandates that compel these operators to upgrade storage protocols while deferring full IP migration. Westminster and Camden councils exemplify this pattern, refreshing HD-TVI recorders to extend infrastructure lifecycles.
Midlands
Birmingham and Coventry industrial estates sustain demand for weatherproof bullet cameras in perimeter security applications. The Data Protection Act 2018 imposes audit-ready compliance standards on manufacturing facilities operating legacy analog systems. West Midlands transport authorities are incrementally upgrading coaxial infrastructure rather than undertaking wholesale network replacement.
North England
Manchester and Liverpool municipal estates face capital constraints that stretch vendor engagement timelines for surveillance refresh cycles. Northern local authorities prioritize HD-TVI modulation upgrades to preserve existing camera investments. GDPR operational overhead is reshaping procurement patterns across Yorkshire and Lancashire public housing CCTV networks.
Scotland
Edinburgh and Glasgow transport bodies specify CMOS-equipped cameras for continuous recording environments where power efficiency reduces operational costs. Scottish local government procurement follows UK-wide Data Protection Act enforcement patterns. Strathclyde Partnership for Transport exemplifies the regional preference for incremental coaxial infrastructure extension.
Wales
Cardiff and Swansea retail security applications generate replacement demand for vandal-resistant dome cameras despite capital constraints on full IP migration. Welsh local authorities confront GDPR retention limits and secure erasure obligations that elevate compliance tooling expenditure. South Wales industrial corridors sustain bullet camera deployments for exterior perimeter coverage.
United Kingdom Surveillance Analog Camera Market Competitive Landscape
The competitive structure tilts toward diversified security conglomerates with European manufacturing footprints and specialized video surveillance pure-plays with deep HD-TVI inventory positions. Bosch Sicherheitssysteme GmbH anchors the continental supplier tier, while Hikvision and Dahua Technology exemplify the scale-driven Asian manufacturing archetype. Strategic moves concentrate on hybrid migration pathway development and BSI certification differentiation for public sector eligibility.
Within the European-integrated tier, Bosch Sicherheitssysteme GmbH and Axis Communications AB occupy positions shaped by proximity to UK integrators and compliance-centric product positioning. Hikvision represents the inventory-depth archetype, with Hanwha Vision Europe and Dahua Technology sitting within the same manufacturing-scale category. These groupings reflect divergent responses to GDPR operational overhead and coaxial infrastructure aging patterns across British municipal and retail estates.
| Leading Market Players |
|---|
| Teledyne FLIR LLC |
| Bosch Sicherheitssysteme GmbH |
| Axis Communications AB |
| Hanwha Vision Europe |
| Johnson Controls Inc. |
| Hikvision |
| Dahua Technology |
| Honeywell International Inc |
| Motorola Solutions, Inc. |
| Others |
Pricing and Supply Chain Analysis
Copper cable and CMOS sensor costs cascade through British analog camera pricing tiers, with raw material volatility in Asian semiconductor fabs compressing margins at the economy end while BSI certification premiums sustain pricing power for public sector suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments British procurement patterns, with BSI electromagnetic compatibility certification and HD-TVI recorder bundling as primary differentiation drivers. Pricing pressure stems from HD-TVI bridge solutions commoditizing mid-tier recorder functionality. Retail security buyers exhibit highest price sensitivity due to capital constraints, while Greater London transport authorities prioritize compliance-grade premiums over unit cost.
Supply Chain Analysis
Post-Brexit rules of origin requirements are reshaping sourcing patterns for UK surveillance integrators, compelling inventory repositioning toward European distribution hubs. Manufacturing concentrates in China, South Korea, and Taiwan for CMOS sensors and HD-TVI chipsets. Supply chains draw from copper cable producers in Germany and Belgium, coaxial connector specialists in Japan, and infrared LED foundries in Taiwan. Single-source vulnerability sits with Taiwanese CMOS foundry concentration. Distribution runs through Manchester and London-based security integrators serving municipal and retail estates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in compliance-certified premium tiers and hybrid migration service contracts, as GDPR operational overhead shifts buyer willingness-to-pay toward audit-ready system architectures.
For Market Incumbents: Acquire hybrid encoder and video management software capabilities to defend against IP-native substitution threats. Deepen backward integration into CMOS sensor sourcing to offset Taiwanese foundry concentration risk. Capture recurring revenue through extended service contracts on HD-TVI bridge deployments across Northern England municipal estates. For New Entrants and Emerging Players: GDPR in the United Kingdom opens a window for compliance-focused software vendors targeting automated deletion workflow gaps in legacy analog estates. White-space concentrates in Scottish and Welsh local authority CCTV networks where capital constraints delay full IP migration. A direct-to-integrator channel model bypasses established distributor markups in Manchester and Birmingham industrial corridors. For Investors and Strategic Acquirers: Consolidation pressure builds where GDPR compliance tooling requirements outpace small integrator technical capacity. Long-term viability favors hybrid-architecture specialists bridging analog and IP domains over pure-play legacy equipment distributors. The signal to watch is Transport for London procurement shifting from HD-TVI refresh toward full IP migration timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Migration Pathway Development | BSI-certified encoders capture retrofit demand across Greater London borough councils extending coaxial infrastructure lifecycles. |
| GDPR Compliance Tooling Investment | Automated retention and erasure workflows address Information Commissioner's Office audit requirements for municipal CCTV operators. |
| CMOS Sensor Supply Agreement | Direct foundry relationships with Taiwanese and South Korean producers reduce exposure to single-source concentration risk. |
| Retail Security Service Contract Expansion | Insurance-mandated coverage documentation drives recurring maintenance revenue from UK shopping center dome camera estates. |
| Scottish Transport Authority Partnership | Strathclyde Partnership for Transport procurement patterns favor incremental upgrade vendors over full-system replacement specialists. |
Research Methodology
Coverage spans Greater London, Midlands, North England, Scotland, and Wales, with primary inputs from each region triangulated against secondary validation. Security integrators, municipal procurement officers, retail loss prevention directors, and BSI certification specialists contributed field perspectives. Secondary sources include Information Commissioner's Office enforcement notices, Transport for London asset management disclosures, British Security Industry Association membership data, and customs import records for surveillance equipment.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions encompass form factor, sensor technology, application vertical, and end-user category, with hybrid migration adoption curves modeled as a cross-cutting behavioral dimension. CAGRs derive from bottom-up equipment replacement cycle analysis and top-down municipal capital expenditure trajectories. HD-TVI modulation penetration and GDPR compliance tooling expenditure serve as industry-specific forecast anchors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated IP migration timelines or escalated Brexit-related tariff restructuring. Forecasts reflect assumptions regarding Transport for London refresh pacing and Scottish local authority capital allocation continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Global Trade Surveillance Systems Market
Video Surveillance Systems
Aircraft Video Surveillance Systems Market
Video Surveillance Systems
Night Vision Camera Market
Video Surveillance Systems
Latin America Video Surveillance Storage Market
Video Surveillance Systems
Smart Doorbell Camera Market
Video Surveillance Systems
Inspection Camera System Market
Video Surveillance Systems
North America Crawler Camera System Market
Video Surveillance Systems
US Video Surveillance Market
Video Surveillance Systems
United Kingdom Video Surveillance Market
Video Surveillance Systems
Global CCTV Market
Video Surveillance Systems
People Counting System Market
Video Surveillance Systems
United States Surveillance Storage Market
Video Surveillance Systems
Middle East and Africa Surveillance IP Cameras Market
Video Surveillance Systems
Wireless Video Surveillance Market
Video Surveillance Systems
Mexico Surveillance IP Camera Market
Video Surveillance Systems
Germany Surveillance IP Camera Market