
 Farm Video Surveillance System Market | 2026-2036
Farm Video Surveillance System Market Size, Share, and Industry Trends Forecast 2026-2036
Farm Video Surveillance System Market Analysis
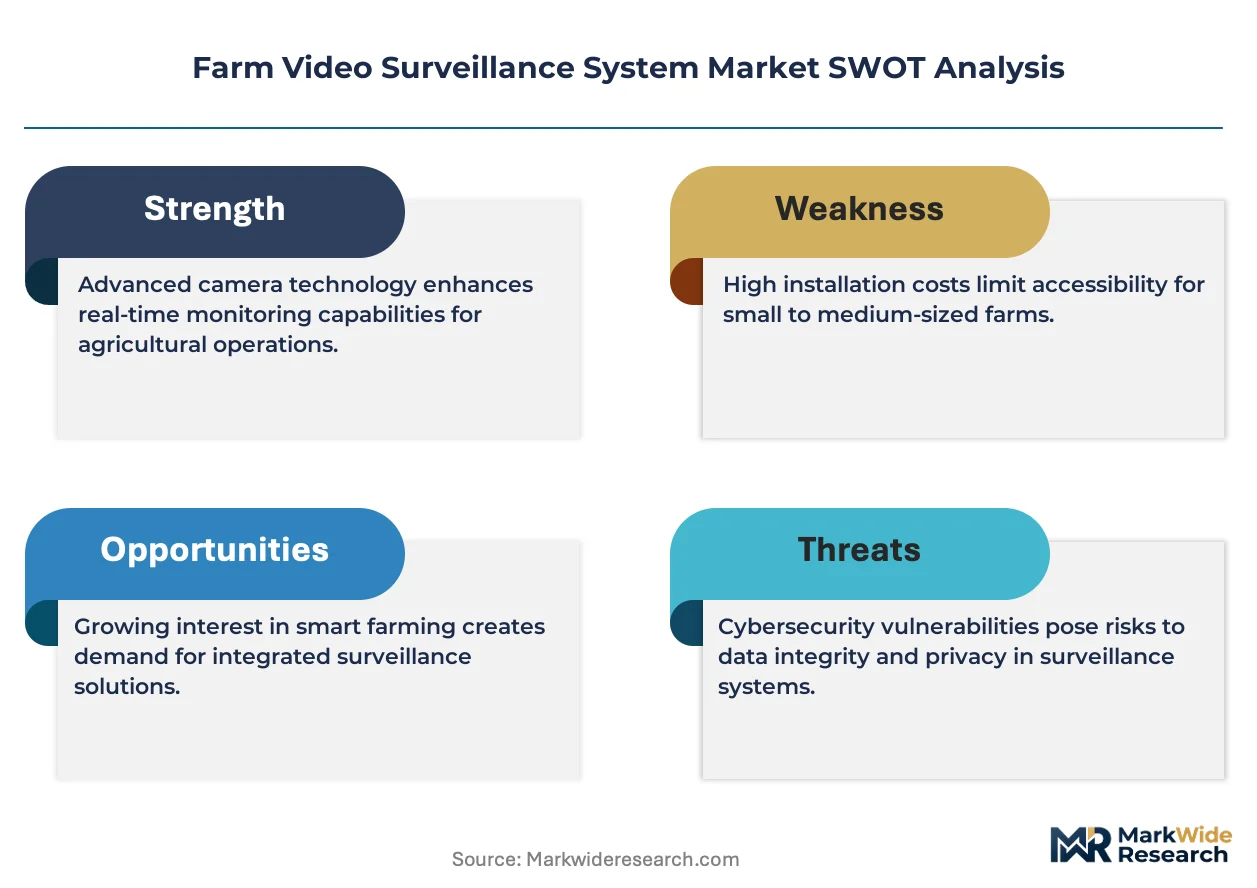
Shortage of agricultural technicians with networking expertise is unwinding deployment timelines across commercial farm operations. FLIR Systems leverages its thermal imaging heritage to anchor premium livestock health monitoring contracts in temperate dairy regions. Reolink competes on cost-optimized wireless kits that extend penetration among mid-scale vegetable growers.
Farm video surveillance systems integrate fixed and pan-tilt cameras with environmental sensors to deliver continuous visual oversight of agricultural assets, typically operating across IP networks with resolution thresholds starting at 1080p for actionable crop-level detail. The primary commercial purpose centers on loss prevention, labor substitution, and compliance documentation for food safety audits. IP Cameras dominate capital allocation where existing fiber infrastructure permits, while Wireless Cameras capture fastest growth in remote pastoral zones lacking trenching feasibility. AI-Enhanced technology concentrates margin pools through subscription-based behavioral analytics for early disease detection.
FDA food safety modernization requirements and EPA agricultural runoff monitoring protocols in the United States shape product specifications toward timestamped, geotagged footage with multi-year retention. The EU Green Deal and GDPR cross-cut demand in Europe, pushing vendors toward on-premise storage architectures that limit cross-border data transfer. Stakeholders must weigh edge-AI processing investments against cloud-dependent recurring revenue models as connectivity asymmetries deepen between irrigated and rain-fed farming belts.
Market Dynamics
Edge-AI processing is compressing hardware procurement cycles as dairy cooperatives and row-crop operators demand real-time behavioral analytics without cloud latency penalties. This compute migration is redrawing vendor margins and forcing infrastructure reconfiguration across temperate and arid farming belts alike.
Growth Catalysts
- FDA Food Safety Modernization Act audit trails:Timestamped, geotagged footage requirements are mandating multi-camera deployments across processing-adjacent operations in the United States.
- Thermal imaging integration:Early mastitis and respiratory distress detection protocols in large-scale dairy herds are pulling capital toward multi-spectral systems.
- California Central Valley water stress:Labor shortages and irrigation monitoring needs are accelerating remote infrastructure investment among nut and vegetable growers.
Market Restraints
- Fiber trenching costs in remote pastoral zones:Rain-fed rangelands lack the capital density to justify wired IP camera backbones, capping addressable market penetration.
- GDPR data residency mandates:European operators face architectural constraints that inflate on-premise storage capex versus cloud-dependent alternatives.
- Silicon supply concentration in East Asian foundries:Edge-AI chip availability bottlenecks are elongating lead times for embedded analytics modules.
Strategic Opportunities
- EU Green Deal agricultural monitoring incentives:Carbon footprint verification protocols are creating demand for automated livestock counting and feed-efficiency documentation systems.
- Drone-camera convergence for broadacre monitoring:Battery-swapping autonomous docking stations are opening aerial surveillance to grain operations previously served only by fixed mounts.
- Subscription behavioral analytics:Disease-early-warning algorithms are shifting revenue models from hardware sales toward recurring software licensing in North American dairy.
Industry Challenges
- Agricultural technician networking skills gap:Commercial farm operations lack personnel capable of VLAN segmentation and cybersecurity hardening, unwinding deployment timelines.
- Multi-year footage retention compliance:FDA and EPA audit requirements are forcing storage architecture decisions that strain capital budgets and IT integration capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Farm Video Surveillance System Market |
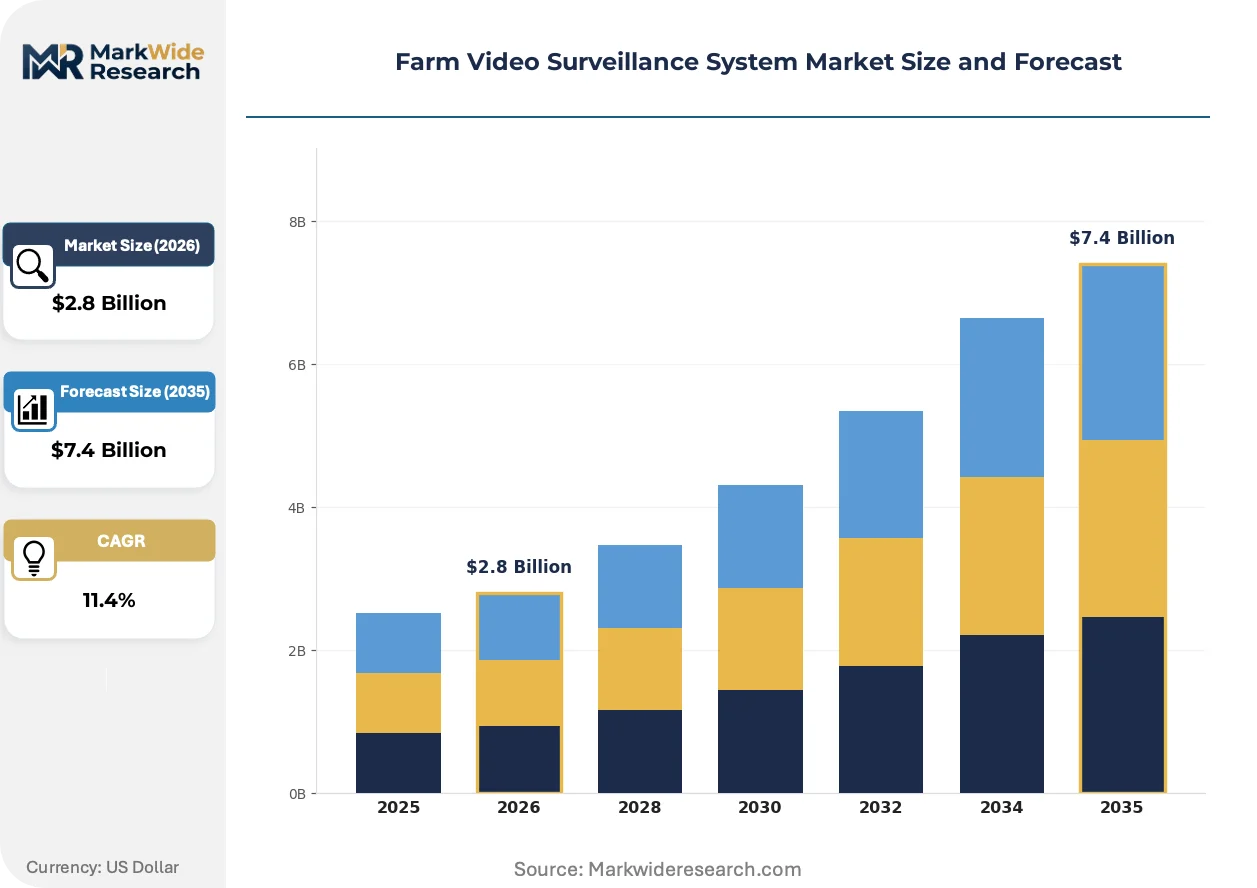
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CCTV Cameras, IP Cameras, Wireless Cameras, Cloud Solutions Technology: Analog, Digital, Remote Access, AI-Enhanced Application: Crop Monitoring, Livestock Management, Security, Equipment Protection End User: Farmers, Agribusiness Companies, Cooperative Societies, Agricultural Institutes |
| Companies Covered | Avigilon, FLIR Systems, Reolink, Genetec, Honeywell International, Hikvision, Eufy, Canon, Hanwha Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Farm Video Surveillance System Market Emerging Trajectories
Compute migration toward the network edge is redistributing value capture between hardware OEMs and analytics software providers. Three concurrent developments are reshaping competitive positioning and procurement patterns across the farm surveillance value chain.
Edge-AI inference chips with sub-10-watt thermal envelopes are fragmenting the traditional NVR-centric architecture. Mid-scale vegetable growers in water-stressed regions are deploying solar-powered camera poles with onboard behavior classification, bypassing fiber trenching entirely. This silicon migration is compressing cloud-dependent recurring revenue models while expanding addressable geography into rain-fed belts previously deemed uneconomical.
EPA agricultural runoff monitoring protocols are tightening visual documentation requirements for concentrated animal feeding operations. Timestamped discharge event correlation with livestock positioning data is becoming standard in watershed-critical zones. Large integrators in the Chesapeake Bay and Mississippi River basins are retrofitting existing mounts with higher-resolution sensors to satisfy nutrient management plan audits.
Consolidated dairy cooperatives are unbundling after-sales service from hardware procurement, pressuring integrators toward fixed-fee maintenance contracts. Third-party remote monitoring desks are displacing on-farm IT personnel for tier-one troubleshooting. This service model rotation is most visible in Wisconsin and New York, where cooperative bargaining power concentrates procurement decisions and compresses vendor margins on installation and training.
Farm Video Surveillance System Market Segmentation
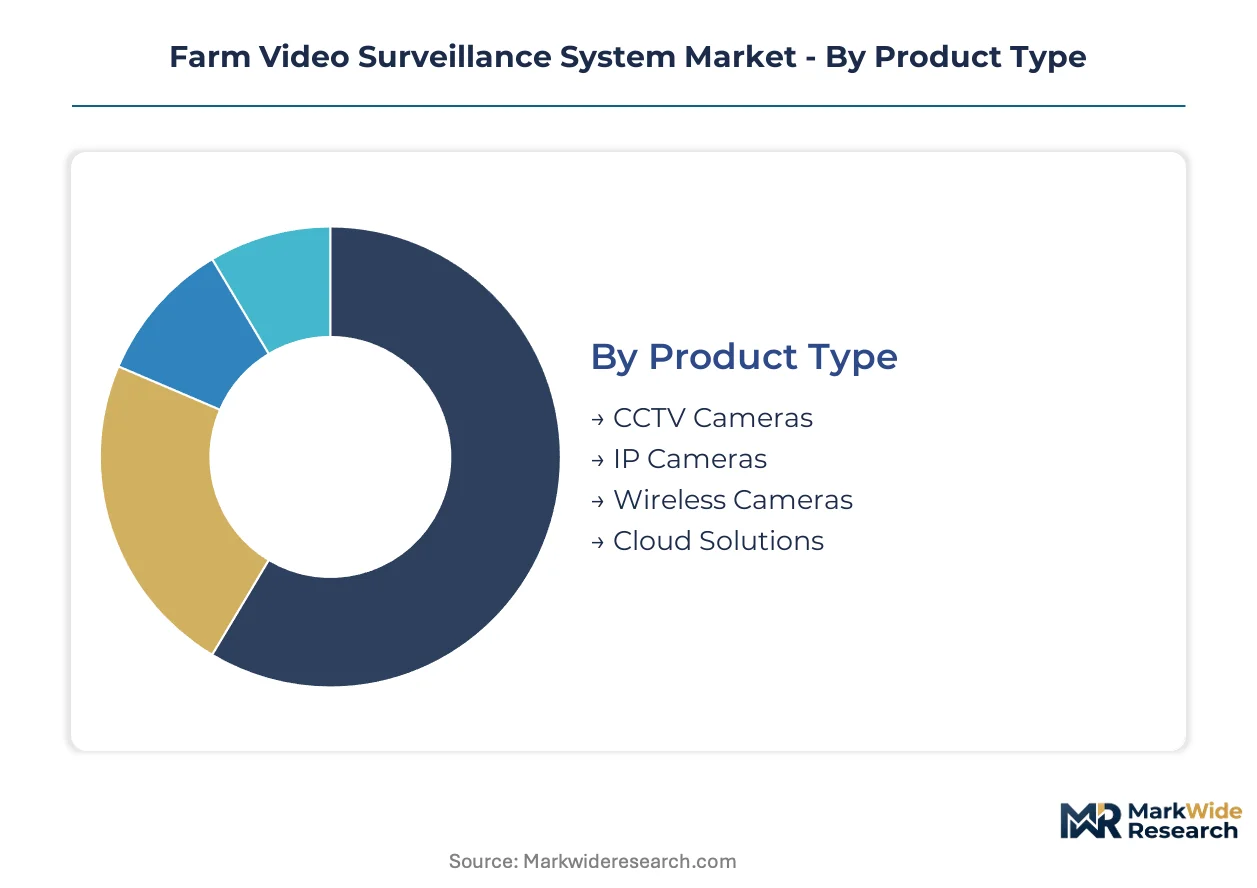
Procurement patterns in farm video surveillance diverge sharply across infrastructure maturity, regulatory exposure, and operational scale. Technology choices cascade into recurring cost structures and compliance capabilities that reshape vendor relationships over multi-year deployment cycles.
Product Type:
Margin pools concentrate in systems that minimize trenching labor and extend serviceable geography beyond fiber backbones.
- IP Cameras:These systems transmit uncompressed video over Ethernet infrastructure with Power-over-Ethernet delivery eliminating separate electrical runs. Demand clusters in California's Central Valley nut operations and Florida citrus processors where existing fiber plant supports multi-camera audit trails for FDA compliance. Capital allocation here reflects confidence in IT integration capacity and multi-year retention architectures.
- Wireless Cameras:Solar-powered poles with mesh networking bypass trenching entirely, opening rain-fed pastoral zones in Texas and Montana previously deemed uneconomical. Battery-swapping maintenance contracts and signal redundancy requirements inflate lifetime cost but compress upfront capex barriers for mid-scale row-crop operators.
- CCTV Cameras:Coaxial-based analog heritage systems persist in legacy dairy barn retrofits where copper infrastructure remains serviceable.
- Cloud Solutions:Subscription storage and remote access portals attract operators lacking on-premise IT personnel for cybersecurity hardening.
The dominant share belongs to IP Cameras, while Wireless Cameras is closing the gap fastest.
Technology:
Adoption velocity tracks regulatory pressure intensity and labor substitution economics across temperate and arid farming belts.
- AI-Enhanced:Onboard inference chips with sub-10-watt thermal envelopes enable real-time behavioral classification without cloud latency penalties. Wisconsin dairy cooperatives and Dutch greenhouse operators deploy these for early mastitis detection and feed-efficiency documentation, shifting revenue models toward recurring analytics licensing. Edge-AI module availability bottlenecks from East Asian foundry concentration elongate procurement timelines.
- Remote Access:Browser-based and mobile-optimized portals satisfy labor shortage-driven demand for off-site oversight in Australia's remote wheat belts and Spain's La Mancha vineyards. Cellular backhaul costs and data residency constraints under GDPR limit European penetration relative to North American deployment.
- Digital:IP-native compression and storage architectures standardize procurement for new-build operations with fiber infrastructure.
- Analog:Coaxial signal transmission persists only where legacy copper replacement economics fail.
AI-Enhanced systems command premium positioning, though Remote Access is expanding most quickly among capital-constrained operators.
Application:
Compliance documentation requirements reshape feature prioritization across food safety audit exposure tiers.
- Livestock Management:Thermal imaging integration for respiratory distress and calving detection anchors procurement in Wisconsin, New York, and Denmark's Jutland Peninsula dairy belts. Timestamped behavioral footage satisfies animal welfare audit protocols while reducing night patrol labor. Multi-spectral sensor fusion inflates hardware cost but compresses veterinary intervention response times.
- Crop Monitoring:Irrigation timing and pest pressure documentation concentrate demand in California's water-stressed vegetable operations and Israel's Negev Desert precision agriculture clusters. Drone-camera convergence with autonomous docking stations is opening broadacre grain surveillance in Ukraine's Black Earth region and Argentina's Pampas previously served only by fixed mounts.
- Security:Perimeter breach detection and theft deterrence standardize procurement for high-value equipment and input storage.
- Equipment Protection:Tractor and combine monitoring against vandalism and unauthorized use attracts remote pastoral operators.
Livestock Management retains the largest installed base, yet Crop Monitoring is gaining share fastest as water stress intensifies irrigation documentation requirements.
End User:
Purchasing sophistication and cooperative bargaining power fragment procurement patterns across operational scale.
- Agribusiness Companies:Large integrators in the Chesapeake Bay watershed and Mississippi River basin deploy enterprise-grade systems with EPA nutrient management plan correlation capabilities. Centralized procurement desks extract volume discounts and fixed-fee maintenance contracts, compressing vendor margins on installation and training. Multi-site standardization requirements favor established integrators with national service footprints.
- Cooperative Societies:Consolidated dairy and grain co-ops in the Netherlands' Friesland and France's Brittany regions aggregate member demand to negotiate behavioral analytics subscriptions at scale. Shared infrastructure investments distribute edge-AI capex across hundreds of member farms.
- Farmers:Owner-operators prioritize cost-optimized wireless kits with minimal IT integration requirements.
- Agricultural Institutes:Research stations and extension services drive pilot deployments for emerging sensor fusion technologies.
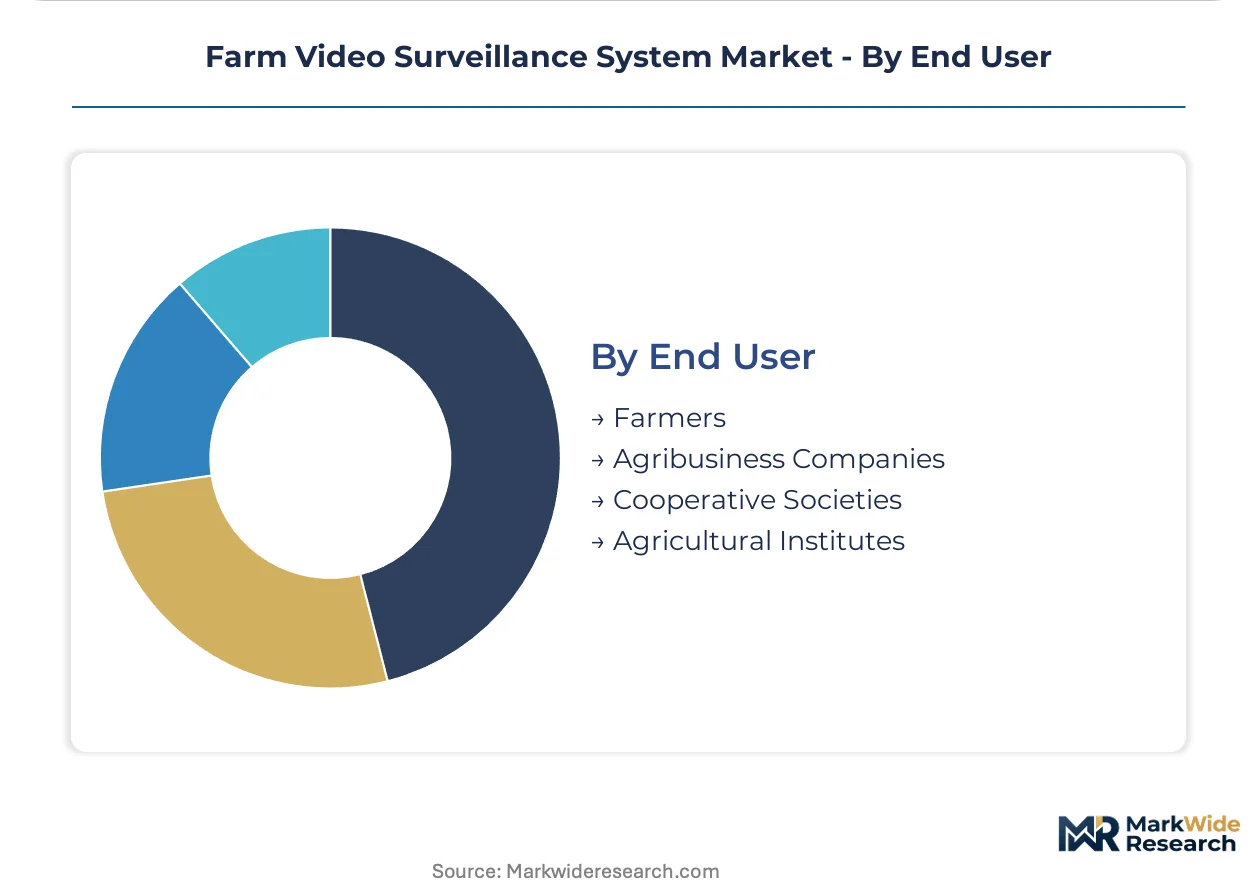
Agribusiness Companies dominate capital deployment, though Cooperative Societies are climbing the fastest as procurement aggregation models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA audit trail mandates anchor procurement intensity in the United States, while EU Green Deal incentives and GDPR constraints fragment deployment architectures across European dairy belts. Water stress and labor shortages in arid farming zones pull capital toward solar-powered wireless infrastructure.
United States
Dairy cooperatives in Wisconsin and New York deploy thermal imaging for mastitis detection protocols. FDA Food Safety Modernization Act timestamped footage requirements mandate multi-camera installations across processing-adjacent operations. California's Central Valley nut and vegetable growers accelerate edge-AI procurement to document irrigation timing amid chronic water scarcity.
Germany
Precision livestock farming adoption concentrates in Lower Saxony's dense dairy corridors. GDPR data residency mandates force on-premise storage architectures that inflate capex versus cloud alternatives. Bavarian cooperative societies aggregate member demand to negotiate behavioral analytics subscriptions at scale across hundreds of farms.
Netherlands
Greenhouse operators in Westland deploy AI-enhanced systems for feed-efficiency documentation and carbon footprint verification. EU Green Deal agricultural monitoring incentives reward automated livestock counting infrastructure. Friesland dairy cooperatives share edge-AI hardware investments across member farms to distribute procurement burdens.
Australia
Remote wheat belt operators prioritize wireless camera poles with cellular backhaul to offset technician scarcity. The country's national agricultural regulator enforces biosecurity audit trails requiring geotagged visual documentation. Queensland broadacre grain producers pilot drone-camera convergence with autonomous docking stations for previously uneconomical aerial surveillance.
Brazil
Large integrators in São Paulo state retrofit existing mounts for nutrient management plan compliance in watershed-critical zones. ANVISA food safety protocols shape timestamped footage retention specifications. Minas Gerais dairy regions import thermal imaging architectures from temperate climate suppliers to address emerging animal welfare audit requirements.
Farm Video Surveillance System Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the farm surveillance value chain. The vendor base stratifies into three tiers: thermal imaging heritage specialists commanding premium livestock health contracts, cost-optimized wireless kit providers penetrating mid-scale vegetable operations, and enterprise-grade integrators serving multi-site agribusiness standardization requirements. Dominant competitive moves include M&A to acquire edge-AI inference capabilities and strategic partnerships to secure silicon supply from East Asian foundries.
Within the thermal imaging tier, FLIR Systems exemplifies heritage positioning anchored in livestock health monitoring contracts. Reolink occupies a position representing cost-optimized wireless penetration among capital-constrained growers. Hikvision sits within the scale-driven archetype serving enterprise-grade multi-site deployments.
| Leading Market Players |
|---|
| Avigilon |
| FLIR Systems |
| Reolink |
| Genetec |
| Honeywell International |
| Hikvision |
| Eufy |
| Canon |
| Hanwha Corporation |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at East Asian foundries producing sub-10-watt edge-AI inference chips creates scale economies that compress module costs for embedded analytics while simultaneously concentrating supply risk. This manufacturing density shapes price floors across hardware tiers and forces procurement desks to weigh inventory depth against silicon availability timelines.
Pricing Analysis
North American deployments command 15-25% premiums over Latin American equivalent configurations due to FDA audit trail compliance bundling and cybersecurity hardening requirements. Three-tier pricing structure across premium, standard, and economy levels separates thermal imaging livestock health systems from wireless solar-pole kits and legacy CCTV retrofits. Cost compression in mid-scale vegetable grower segments is intensifying because Reolink and Eufy compete on cellular-backhaul camera pole kits with minimal installation service. Cooperative societies exhibit lowest price sensitivity due to aggregated procurement volumes, while owner-operator farmers prioritize upfront capex minimization over lifetime cost optimization.
Supply Chain Analysis
Inventory cycles for edge-AI inference modules currently stretch 18-24 weeks as Taiwan and South Korea foundries prioritize automotive and consumer electronics allocation. Farm surveillance hardware draws from Chinese lens and sensor assembly, Vietnamese cable and enclosure fabrication, and Malaysian PCB integration. Single-source vulnerability concentrates in advanced node semiconductor supply where TSMC and Samsung anchor global edge-AI chip output. Distribution runs through national integrators serving agribusiness accounts, direct-to-farmer e-commerce for wireless kits, and cooperative procurement desks aggregating member demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drone-based autonomous surveillance platforms threaten fixed-mount camera incumbents by opening broadacre grain monitoring previously deemed uneconomical, forcing established vendors to defend installed base through service bundling and analytics retention.
For Market Incumbents: Secure silicon supply commitments from East Asian foundries through multi-year offtake agreements to insulate against edge-AI module availability bottlenecks. Anchor customer retention by unbundling hardware from subscription behavioral analytics, creating switching costs for dairy cooperatives already integrated into disease-early-warning algorithms. Threat: drone-camera convergence with autonomous docking stations displacing fixed-mount value propositions in grain belts. For New Entrants and Emerging Players: After-sales service gaps in remote pastoral zones present white-space opportunity where incumbent integrators lack technician density for battery-swapping maintenance contracts. Target rain-fed rangelands in Texas and Montana with solar-powered mesh camera poles bypassing fiber trenching entirely. Go-to-market angle: cellular-optimized kits with simplified mobile provisioning that owner-operators deploy without VLAN configuration expertise. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among AI-enhanced behavioral analytics providers serving North American dairy cooperatives, where subscription licensing shifts value capture from transactional hardware toward multi-year software relationships. Long-term viability favors vendors with edge-AI inference capabilities and established cooperative channel relationships. Acquisition target archetype: thermal imaging specialists with livestock health monitoring heritage and embedded analytics roadmaps. Signal to watch: EPA nutrient management plan audits expanding visual documentation mandates to watershed-critical zones beyond current Chesapeake Bay and Mississippi River basin concentrations.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Chip Supply Agreement | Multi-year foundry commitments insulate against Taiwan and South Korea allocation bottlenecks. |
| Drone-Camera Platform Integration | Autonomous docking stations open broadacre grain surveillance previously served only by fixed mounts. |
| Cooperative Procurement Partnership | Friesland and Brittany dairy co-ops aggregate member demand to negotiate behavioral analytics at scale. |
| On-Premise Storage Architecture | GDPR-compliant data residency configurations capture European procurement desk attention. |
| Subscription Analytics Licensing | Recurring revenue models shift value capture from hardware transactions toward disease-early-warning algorithms. |
Methodological Framework
Initial hypotheses were tested against primary input from dairy cooperative procurement managers, agribusiness IT directors, surveillance integrators serving watershed-critical operations, and edge-AI semiconductor supply planners, then refined through secondary validation against EPA nutrient management plan documentation, FDA Food Safety Modernization Act audit guidelines, EU Green Deal agricultural monitoring incentive structures, and customs records tracking camera module trade flows. Bottom-up farm-level deployment estimates and top-down vendor revenue analysis were triangulated to constrain variance.
Variance decomposition across the projection horizon isolates growth contributions from technology substitution rates, regulatory compliance phase-ins, and cooperative procurement aggregation trends. Segmentation dimensions modeled include product type, technology tier, application exposure to audit requirements, and end-user purchasing sophistication. CAGRs were derived from logistic diffusion curves fitted to historical deployment patterns and elasticity-adjusted for water stress and labor shortage intensification. Industry-specific forecast inputs incorporate California Central Valley irrigation documentation mandates and Wisconsin dairy cooperative standardization timelines.
Underlying assumptions cover FDA audit trail enforcement continuity, East Asian foundry capacity expansion trajectories, and cellular backhaul cost trajectories in remote agricultural zones, with deviation risk concentrated in GDPR regulatory evolution and drone autonomy regulatory clearance timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
North America Crawler Camera System Market
Video Surveillance Systems
India Surveillance Analog Camera Market
Video Surveillance Systems
Central Monitoring Station Market
Video Surveillance Systems
Smart Doorbell Camera Market
Video Surveillance Systems
AI in Video Surveillance Market
Video Surveillance Systems
Latin America Video Surveillance Storage Market
Video Surveillance Systems
Brazil Video Surveillance Market
Video Surveillance Systems
India Surveillance Storage Market
Video Surveillance Systems
Asia-Pacific Surveillance Camera Market
Video Surveillance Systems
North America Surveillance Analog Camera Market
Video Surveillance Systems
AI Surveillance System Market
Video Surveillance Systems
Night Vision System (NVS) Market
Video Surveillance Systems
United States Surveillance IP Camera Market
Video Surveillance Systems
Brazil Surveillance IP Cameras Market
Video Surveillance Systems
United Kingdom Surveillance IP Camera Market
Video Surveillance Systems
China Surveillance Storage Market