
 People Counting System Market | 2026-2036
People Counting System Market Size, Share, and Industry Trends Forecast 2026-2036
People Counting System Market Analysis
The sensor-to-software capability gap is reorganizing competitive hierarchies in people counting systems. Axis Communications AB leverages its end-to-end video analytics stack to dominate enterprise deployments. Hikvision Digital Technology Co., Ltd. sustains manufacturing scale advantages across infrared and laser sensor lines. RetailNext Inc. specializes in cloud-native retail analytics, anchoring its position in brick-and-mortar digitization.
People counting systems integrate optical sensors, thermal imagers, and machine-vision algorithms to detect, track, and enumerate individuals traversing defined spatial zones, typically achieving accuracy thresholds above 95% in controlled indoor environments. These systems serve commercial and institutional operators seeking occupancy intelligence for security, energy optimization, and customer-flow management. Video analytics and Wi-Fi tracking segments command expanding share as multi-sensor fusion replaces single-modality legacy installations. Edge computing deployment is accelerating fastest where latency constraints and data sovereignty requirements limit cloud dependency.
The EU AI Act, GDPR, and FDA guidance on computer-vision medical devices collectively tighten algorithmic transparency and biometric data handling standards, raising compliance costs for vendors serving European and North American buyers. China's SAMR and GB standards enforce separate cybersecurity and data-localization protocols for installations within its jurisdiction. Stakeholders must monitor regulatory divergence between jurisdictions when architecting product roadmaps and localization strategies.
Market Dynamics
Multi-sensor fusion architectures are compressing hardware margins while elevating software licensing value, forcing vendors to restructure revenue models around analytics subscriptions rather than device sales.
Growth Catalysts
- EU AI Act compliance mandates:European commercial real estate operators face mandatory algorithmic transparency requirements, accelerating replacement of legacy single-modality systems with auditable edge-AI platforms that embed compliance by design.
- Smart building retrofit programs:Corporate campuses in Germany, Japan, and the United States deploy occupancy intelligence for HVAC optimization, with sensor networks feeding directly into building management systems to achieve energy reduction targets.
- Wi-Fi beacon triangulation:Retailers integrate passive device detection with video analytics to unify online-offline customer journey mapping, eliminating blind spots in footfall attribution.
Market Restraints
- CMOS image sensor supply concentration:Taiwan and South Korean foundries control advanced sensor wafer output, exposing system integrators to allocation risk during semiconductor demand spikes.
- GDPR biometric data classification:European data protection authorities classify gait analysis and facial geometry extraction as special category data, imposing consent infrastructure costs that deter trial deployments.
- Thermal sensor price volatility:Germanium and vanadium oxide substrate costs fluctuate with defense sector demand cycles, compressing gross margins on infrared-based counting modules.
Strategic Opportunities
- India smart city infrastructure:Municipal corporations in Mumbai, Delhi, and Bangalore issue tenders for pedestrian analytics in transit hubs, with local production incentives under PLI schemes favoring domestic-assembly partnerships.
- Edge-AI chip convergence:Neural processing units from Qualcomm and Ambarella enable on-device model inference without cloud dependency, opening sovereign-data installations in Middle Eastern and Southeast Asian government facilities.
- CSRD reporting requirements:European corporate sustainability directives mandate granular occupancy data for Scope 3 emissions calculations, creating pull-through demand for certified measurement systems.
Industry Challenges
- Embedded systems firmware expertise:Vendors struggle to recruit engineers proficient in real-time operating systems and low-power computer vision pipelines, delaying product roadmaps by 6-12 months.
- Legacy analog CCTV integration:Enterprise customers demand backward compatibility with coaxial infrastructure, forcing hybrid architectures that complicate firmware maintenance and security patching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | People Counting System Market |
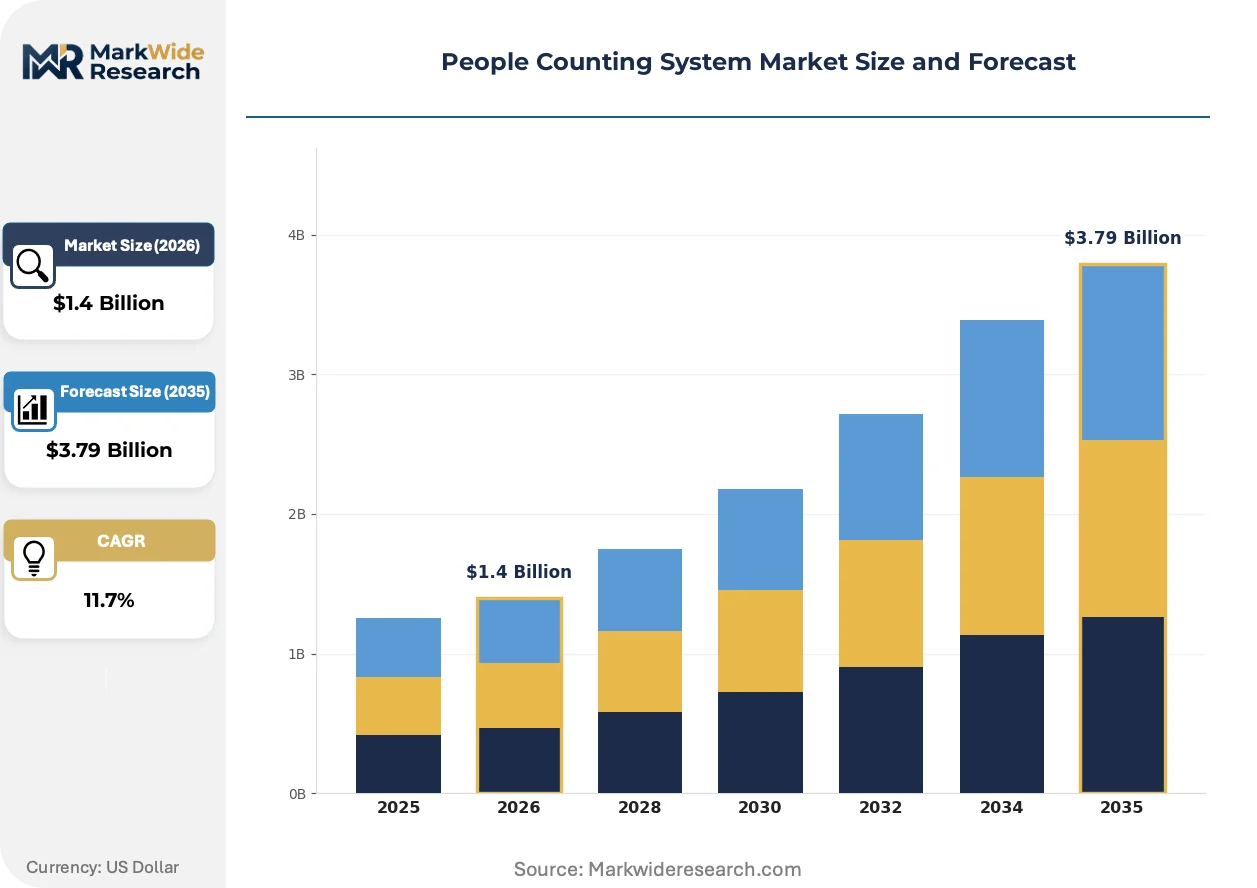
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.79 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Infrared Sensors, Video Analytics, Laser Sensors, Wi-Fi Tracking Application: Retail Analytics, Event Management, Public Transport, Smart Buildings End User: Retail Stores, Airports, Museums, Corporate Offices Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Axis Communications AB, Hikvision Digital Technology Co., Ltd., RetailNext Inc., Sensormatic Solutions, DILAX Intelcom GmbH, Teledyne FLIR LLC, InfraRed Integrated Systems Ltd, Xovis AG, V-Count, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
People Counting System Market Emerging Trajectories
Sensor modality unbundling is fragmenting vendor value chains, with specialized chip designers, edge-AI framework providers, and vertical analytics platforms competing to capture margin from traditional integrated system suppliers.
Time-of-flight depth sensors are decomposing the stereo camera's historical dominance in high-accuracy counting applications. Airport operators in Dubai, Singapore, and Amsterdam deploy solid-state lidar modules for queue management, achieving sub-5cm precision without ambient lighting dependency. The technology is decomposing hardware refresh cycles from seven years to three as semiconductor photonics costs decline.
The EU AI Act's risk-based classification system imposes conformity assessment requirements on biometric identification functions. System vendors serving European retail and transport sectors must maintain technical documentation, human oversight protocols, and accuracy benchmarking against standardized test datasets. German facility managers now specify CE-marked AI components with explicit non-biometric operating modes to preserve deployment flexibility.
Building operators increasingly unbundle hardware procurement from analytics licensing, treating counting infrastructure as a metered utility rather than capital equipment. Japanese commercial developers favor subscription contracts with guaranteed accuracy SLAs, transferring algorithm performance risk to vendors. This model concentrates in premium office developments in Tokyo's Minato ward and Osaka's Umeda district where occupancy volatility demands continuous calibration.
People Counting System Market Segmentation
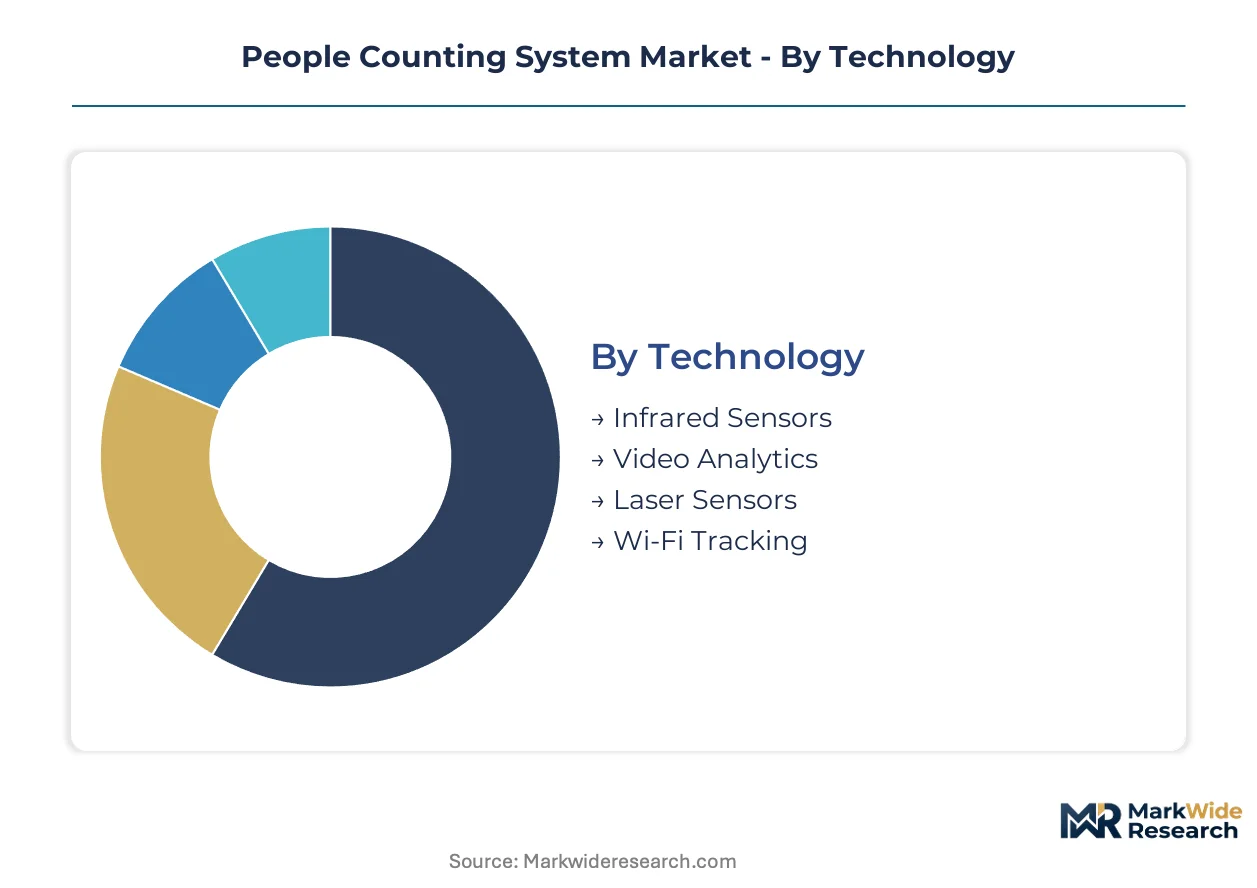
People counting system architectures diverge sharply across regulatory jurisdictions. GDPR and EU AI Act compliance requirements in Europe favor edge-AI modalities that process data locally, while North American and Asian deployments tolerate greater cloud dependency for centralized analytics.
Technology:
Regulatory differentiation shapes technology selection most acutely in European deployments, where biometric data classification rules penalize certain sensing modalities.
- Video Analytics:Computer-vision pipelines using CMOS sensors and convolutional neural networks achieve accuracy above 95% in controlled indoor environments. German facility managers now specify CE-marked components with explicit non-biometric operating modes to preserve deployment flexibility under EU AI Act risk classifications.
- Wi-Fi Tracking:Passive beacon detection triangulates device positions without optical capture, sidestepping GDPR special-category data triggers. Retailers in France and the Netherlands integrate this modality with video feeds to unify online-offline customer journey mapping without consent infrastructure penalties.
- Infrared Sensors:Thermal imaging arrays detect body heat signatures independent of ambient lighting.
- Laser Sensors:Time-of-flight depth modules deliver sub-5cm precision for queue management in Dubai and Singapore airports.
Video analytics handles the majority of throughput; Wi-Fi tracking is gaining share fastest as privacy-conscious retailers seek biometric-free alternatives.
Application:
Cost tier stratification separates premium integrated suites from single-purpose counting modules.
- Smart Buildings:Multi-sensor networks feed directly into building management systems for HVAC optimization and energy reduction targeting. Corporate campuses in Germany, Japan, and the United States anchor demand as ESG reporting mandates tighten.
- Retail Analytics:Footfall attribution and dwell-time measurement drive brick-and-mortar digitization. Japanese commercial developers in Tokyo's Minato ward favor subscription contracts with guaranteed accuracy SLAs, transferring algorithm performance risk to vendors.
- Public Transport:Pedestrian analytics for crowd density and safety monitoring in transit hubs.
- Event Management:Temporary deployments for capacity monitoring and emergency egress planning.
Smart buildings absorbs the largest capital allocation; retail analytics shows the steepest expansion trajectory as merchants close the attribution gap between digital and physical channels.
End User:
Customer type determines procurement sophistication and contract structure more than technical specification.
- Airports:Queue management and passenger flow optimization demand sub-5cm precision. Amsterdam Schiphol and Singapore Changi deploy solid-state lidar modules that decompose hardware refresh cycles from seven years to three as semiconductor photonics costs decline.
- Corporate Offices:Occupancy intelligence for hot-desking optimization and space utilization analytics. CSRD reporting requirements in Europe mandate granular occupancy data for Scope 3 emissions calculations, pulling through certified measurement system demand.
- Retail Stores:Single-location merchants to multinational chains seeking unified analytics dashboards.
- Museums:Visitor flow management and exhibit popularity measurement for curatorial planning.
Airports command the highest per-unit pricing; corporate offices are expanding most quickly on unit volume as hybrid work patterns force space reconfiguration.
Deployment:
Supply concentration in edge-AI silicon is compressing hardware margins while elevating software licensing value.
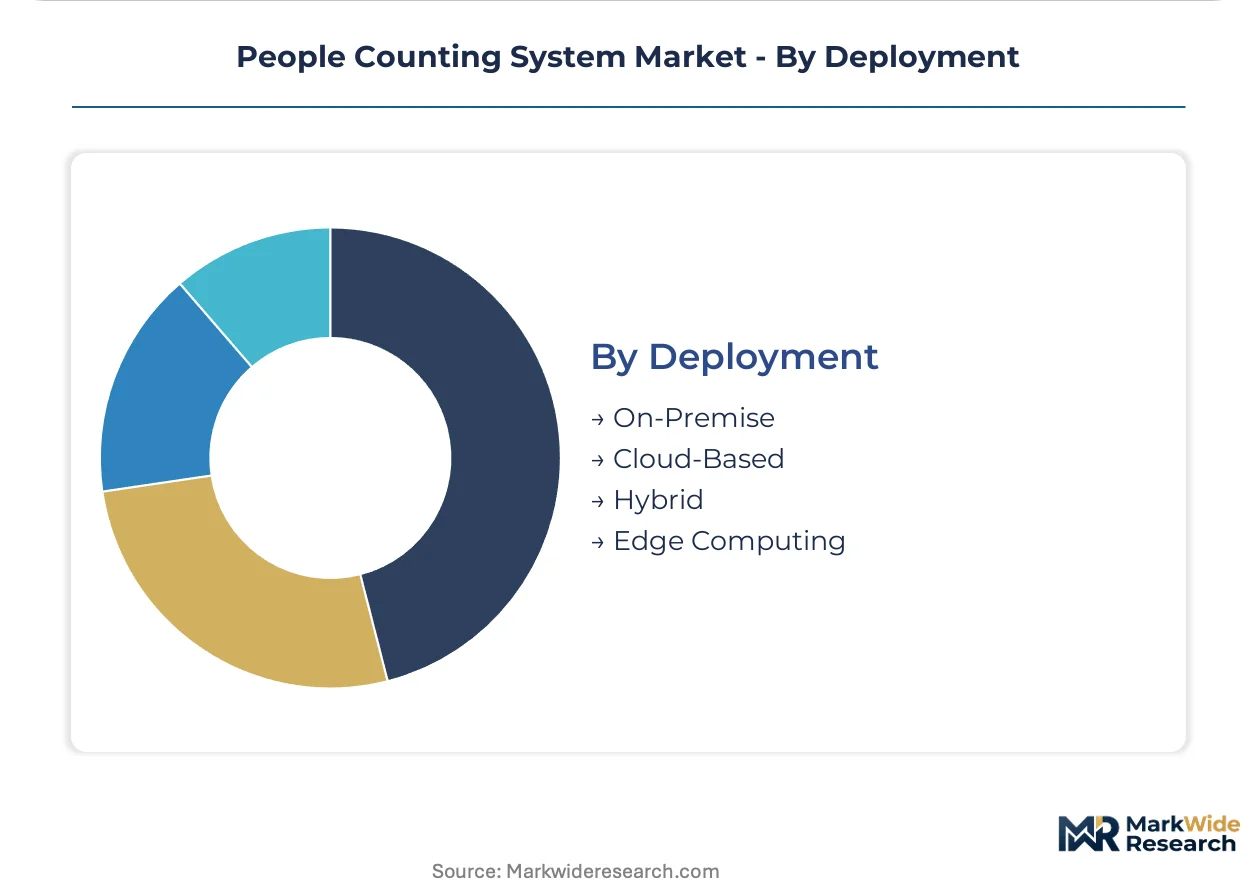
- Edge Computing:Neural processing units from Qualcomm and Ambarella enable on-device model inference without cloud dependency. Middle Eastern and Southeast Asian government facilities specify sovereign-data architectures that prohibit external data transmission.
- Cloud-Based:Centralized model training and cross-location analytics for retail chains with distributed footprints. Scales efficiently but faces latency constraints and data localization requirements in China's jurisdiction under SAMR and GB standards.
- On-Premise:Legacy server-room installations with full local data custody.
- Hybrid:Edge inference with cloud aggregation for multi-site reporting.
Edge computing captures the fastest-growing deployment mode; cloud-based retains the largest installed base among multinational retail operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. European buyers absorb compliance premiums for edge-AI systems, while Indian municipal tenders prioritize unit economics over accuracy specifications.
Germany
Corporate campus retrofits and ESG reporting mandates drive demand for occupancy intelligence systems. The EU AI Act and CSRD impose algorithmic transparency requirements on building operators. Munich and Frankfurt facility managers specify CE-marked components with non-biometric operating modes.
United States
Smart building deployments concentrate in corporate headquarters seeking HVAC optimization and hot-desking analytics. FDA guidance on computer-vision medical devices intersects with commercial applications in healthcare-adjacent facilities. Silicon Valley and Manhattan commercial developments anchor premium-tier procurement.
Japan
Hybrid work patterns force space reconfiguration in Tokyo's Minato ward and Osaka's Umeda district, pulling through subscription-based counting contracts. METI efficiency standards incentivize building energy management integration. Corporate developers favor guaranteed accuracy SLAs over capital purchases.
India
Municipal corporations in Mumbai, Delhi, and Bangalore tender for pedestrian analytics in transit hubs with stringent cost constraints. PLI schemes favor domestic-assembly partnerships for foreign vendors. Price competition intensifies as local system integrators bid against imported equipment.
United Arab Emirates
Sovereign-data requirements in government facilities prohibit external cloud transmission, favoring edge-computing architectures. Dubai airport operators deploy solid-state lidar for queue management with sub-5cm precision. MOHAP and local regulators enforce data localization for biometric-adjacent installations.
People Counting System Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. The vendor base spans integrated video analytics stacks, sensor hardware specialists, and cloud-native software platforms. Three archetypes dominate: end-to-end system suppliers, component-scale manufacturers, and vertical analytics specialists. M&A activity concentrates on edge-AI capability acquisition, while geographic expansion through local assembly partnerships secures public-sector access.
Among the named suppliers, Axis Communications AB and Hikvision Digital Technology Co., Ltd. exemplify contrasting scale positions—one anchoring enterprise software integration, the other representing manufacturing volume advantages. RetailNext Inc. occupies a position within the cloud-native tier, specializing in retail vertical applications. These three represent the strategic archetypes that competitors must navigate: integrated platform dominance, hardware scale efficiency, or vertical software specialization.
| Leading Market Players |
|---|
| Axis Communications AB |
| Hikvision Digital Technology Co., Ltd. |
| RetailNext Inc. |
| Sensormatic Solutions |
| DILAX Intelcom GmbH |
| Teledyne FLIR LLC |
| InfraRed Integrated Systems Ltd |
| Xovis AG |
| V-Count |
| Others |
Supply Flow & Price Mechanics
CE marking and EU AI Act conformity assessment requirements simultaneously gate vendor qualification and stratify price tiers in European deployments, forcing system integrators to absorb compliance premiums or cede share to certified competitors. German facility managers now specify CE-marked edge-AI components with explicit non-biometric operating modes, creating a two-speed market where compliant architectures command sustained premiums against uncertified alternatives.
Pricing Analysis
Analytics subscriptions and extended service contracts now drive lifetime value, displacing transactional hardware margins as the dominant revenue stream. Three-tier pricing structure across premium, standard, and economy levels separates integrated platform vendors from modular sensor suppliers and white-label assemblers. Cost compression in economy-tier infrared modules is intensifying because Chinese foundries are flooding basic thermal sensor output. Retail chains in India exhibit the highest price sensitivity, while Japanese corporate developers in Tokyo's Minato ward absorb premium pricing for guaranteed accuracy SLAs.
Supply Chain Analysis
Taiwan Strait transit underwrites advanced CMOS image sensor availability, exposing system integrators to allocation risk during semiconductor demand spikes. Taiwan and South Korean foundries control wafer output for neural processing units, while Germanium and vanadium oxide for thermal arrays sources from specialized refiners in China and Russia. Single-source vulnerability concentrates in edge-AI silicon design, where Qualcomm and Ambarella architectures dominate on-device inference. Distribution runs through building automation integrators in developed markets and domestic-assembly partnerships in India under PLI schemes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The people counting system market is exiting a cyclical trough driven by smart building retrofit acceleration and ESG reporting mandate expansion. Corporate capital allocation to occupancy intelligence is recovering as hybrid work patterns stabilize and facility managers seek operational efficiency gains.
For Market Incumbents: Secure firmware differentiation through embedded systems talent acquisition, as real-time operating systems expertise scarcity delays competitor roadmaps by 6-12 months. Lock in CMOS sensor allocation agreements with Taiwan foundries before capacity constraints tighten. Vertical integration into edge-AI chip design, via Qualcomm or Ambarella partnership structures, defends margin position against modular software entrants.
For New Entrants and Emerging Players: CE marking fast-track through notified body pre-submission offers the most penetrable path into German and French corporate campus deployments. Municipal tenders in Mumbai, Delhi, and Bangalore present white-space volume with cost-engineered Wi-Fi beacon solutions that sidestep optical sensor supply constraints. Target domestic-assembly partnerships under India's PLI scheme to meet local content thresholds without capital-intensive manufacturing buildout.
For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape toward edge-AI capability portfolios with embedded compliance documentation. Mid-cycle viability favors vendors with recurring analytics revenue exceeding 40% of total mix and established accuracy benchmarking protocols. Monitor CSRD reporting adoption rates among European corporate real estate operators as the inflection signal for certified measurement system demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Chip Partnership | Qualcomm neural processing unit integration enables sovereign-data installations in UAE government facilities. |
| CE Marking Fast-Track | Notified body pre-submission accelerates EU AI Act conformity assessment for biometric-adjacent functions. |
| Domestic Assembly Partnership | PLI scheme compliance in India unlocks municipal tender access in Mumbai and Bangalore transit hubs. |
| Analytics Subscription Conversion | Japanese developers in Osaka's Umeda district now demand guaranteed accuracy SLAs over capital purchases. |
| Multi-Sensor Fusion Platform | Time-of-flight depth modules from solid-state lidar suppliers displace stereo cameras in Dubai airport queues. |
Methodological Framework
Operator-level perspectives from facility managers, building automation integrators, edge-AI chip procurement leads, and municipal tender officers anchored the qualitative base. Primary interviews with CTOs at corporate campus developers and regulatory affairs specialists at video analytics vendors combined with secondary validation from SEC filings of listed sensor manufacturers, EIA building energy consumption data, EU AI Act implementation guidance documents, and PLI scheme tender databases. Bottom-up unit deployment estimates triangulated against top-down building stock analytics across the analysis window.
Sensitivity analysis framed volume and value outputs across technology modality, deployment architecture, end-use vertical, and regional regulatory cluster dimensions. Modeled segmentation captured video analytics, Wi-Fi tracking, infrared, and laser sensor lines against edge, cloud, on-premise, and hybrid deployment modes. CAGRs derived from regression against smart building retrofit program announcements, CSRD adoption curves, and semiconductor photonics cost decline trajectories. Neural processing unit price elasticity and thermal sensor Germanium cost volatility served as key forecast inputs.
Decision-makers should treat outputs as directional under base assumptions of sustained EU AI Act enforcement and PLI scheme continuity; material deviation in regulatory implementation pace or foundry capacity allocation would warrant model refresh. Practitioners should keep alternative scenarios live as GDPR biometric data classification interpretations and Taiwan semiconductor supply conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
United States Surveillance Camera Market
Video Surveillance Systems
Europe Video Surveillance As a Service Market
Video Surveillance Systems
Japan Surveillance IP Cameras Market
Video Surveillance Systems
Privacy Filters Market
Video Surveillance Systems
AI Surveillance Camera Market
Video Surveillance Systems
Video Surveillance As a Service Market
Video Surveillance Systems
Integrated Video Surveillance Systems Market
Video Surveillance Systems
Latin America Surveillance IP Cameras Market
Video Surveillance Systems
Latin America Surveillance Camera Market
Video Surveillance Systems
China Surveillance Camera Market
Video Surveillance Systems
United Kingdom Surveillance Camera Market
Video Surveillance Systems
United Arab Emirates Surveillance Camera Market
Video Surveillance Systems
Canada Surveillance Storage Market
Video Surveillance Systems
Global Night Vision System and Driver Monitoring System Market
Video Surveillance Systems
Canada Surveillance Camera Market
Video Surveillance Systems
Smart Doorbell Camera Market