
 Night Vision (IR) Surveillance Cameras Market | 2026-2036
Night Vision (IR) Surveillance Cameras Market Size, Share, and Industry Trends Forecast 2026-2036
Night Vision (IR) Surveillance Cameras Market Insights
4K-resolution and thermal-fusion spec tiers is unwinding legacy analog replacement cycles across municipal and defense procurement channels. Hikvision leverages vertical integration in sensor manufacturing to control cost curves across dome and bullet form factors. Axis Communications differentiates through open-platform architecture that sustains third-party analytics integration. Teledyne FLIR specializes in thermal core miniaturization, anchoring its position in perimeter monitoring and critical infrastructure verticals.
Night Vision (IR) Surveillance Cameras integrate infrared illuminators, image sensors with enhanced photon sensitivity, and digital signal processors to capture actionable video under zero-lux conditions for security and situational awareness applications. The technology dimension shows IP and thermal variants capturing margin pools as analog systems enter terminal decline, while wireless deployments accelerate in retrofit residential and retail environments. PTZ configurations lead in traffic surveillance and public safety due to operator-controllable coverage, whereas fixed turret designs dominate cost-sensitive commercial installations where wide static fields suffice.
The EU AI Act and GDPR constrain facial recognition capabilities in public-facing IR deployments, while the US FAA and FCC govern drone-mounted surveillance frequencies and airspace integration. India's BIS certification mandates electromagnetic compatibility testing for imported IP camera assemblies, directly shaping supplier market access timelines. Stakeholders must monitor evolving encryption standards and cross-border data localization rules as procurement specifications harden around cybersecurity resilience rather than image quality alone.
Market Dynamics
The migration from analog to IP-based thermal surveillance infrastructure is compressing replacement cycles and redrawing vendor competitive boundaries across defense, municipal, and commercial procurement channels.
Growth Catalysts
- Smart City Infrastructure Mandates:India's urban renewal programs are embedding IR surveillance into traffic management and public safety networks, creating sustained municipal demand for dome and bullet configurations.
- EU AI Act Compliance Pathways:Biometric-capable IR deployments in European public spaces must now satisfy algorithmic transparency requirements, accelerating procurement of analytics-ready camera platforms with embedded edge processing.
- Critical Infrastructure Protection Directives:Energy utilities and transportation authorities in Japan and South Korea are mandating thermal perimeter monitoring, pulling uncooled microbolometer cores into mainstream commercial specifications.
Market Restraints
- Sensor Supply Concentration:Uncooled vanadium oxide microbolometer production concentrates among a handful of foundries, exposing procurement timelines to single-source risk.
- GDPR-Driven Facial Recognition Friction:European data protection authorities are constraining biometric analytics in public-facing IR systems, limiting feature monetization for integrated software platforms.
- Silicon Germanium Cost Volatility:Wafer pricing fluctuations for short-wave infrared sensors are compressing margins on high-sensitivity night vision modules targeting scientific and defense applications.
Strategic Opportunities
- Drone-Mounted Surveillance Integration:FAA frequency allocations and airspace rulemaking in the United States are opening regulatory pathways for gimbal-stabilized thermal payloads on unmanned platforms.
- Edge AI Convergence:On-camera neural processing is enabling real-time threat classification without cloud dependency, creating differentiation for vendors with in-house silicon design capabilities.
- Retail Loss Prevention Modernization:Big-box operators in Brazil and Mexico are retrofitting analog CCTV networks with wireless IR cameras, bypassing cabling constraints in legacy building stock.
Industry Challenges
- Cybersecurity Certification Bottlenecks:BIS electromagnetic compatibility testing in India and FCC equipment authorization in the United States are extending product launch timelines by six to nine months.
- Thermal-Optical Fusion Engineering Talent Scarcity:The specialized skill set required for multi-spectral image registration and real-time sensor fusion is concentrating among defense-contractor alumni pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Night Vision (IR) Surveillance Cameras Market |
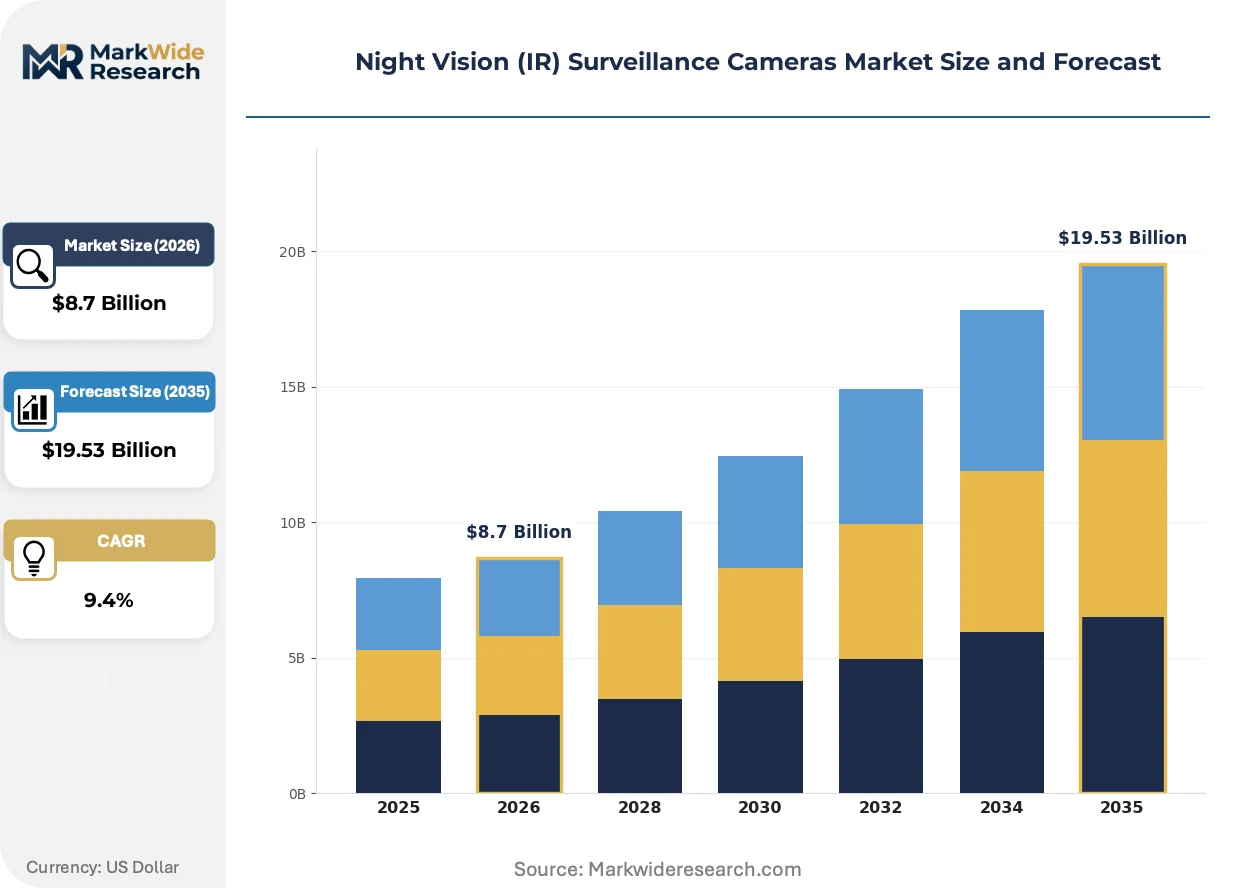
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed, PTZ, Bullet, Dome, Turret Technology: Analog, IP, Thermal, Digital, Wireless Application: Perimeter Monitoring, Traffic Surveillance, Public Safety, Critical Infrastructure, Retail Security End User: Government Facilities, Commercial Establishments, Educational Institutes, Transportation Hubs, Residential Complexes |
| Companies Covered | HANGZHOU HIKVISION DIGITAL TECHNOLOGY CO. LTD, Dahua Technology Co., Ltd, Axis Communications AB, Teledyne FLIR LLC, Bosch Sicherheitssysteme GmbH, Honeywell International Inc., Canon Inc., Panasonic Holdings Corporation, Hanwha Vision Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Night Vision (IR) Surveillance Cameras Market Trends and Innovations
Thermal core miniaturization and on-device analytics are collapsing the traditional separation between sensing hardware and software intelligence, forcing vendors to recalibrate R&D allocation across optical, thermal, and computational domains.
Uncooled microbolometer arrays with pixel pitches below 12 micrometers are fragmenting the historical trade-off between thermal sensitivity and form factor. Defense integrators are embedding these sensors into helmet-mounted and weapon-sighted configurations, while municipal buyers are specifying them for covert urban surveillance. The technology is fragmenting vendor tiering, as mid-tier suppliers now access resolution parity with premium thermal specialists.
The EU AI Act's risk classification framework is reshaping procurement specifications for biometric-capable IR systems deployed in European public spaces. Algorithmic impact assessments and conformity marking requirements are extending sales cycles but creating competitive moats for vendors with established compliance infrastructure. Traffic management authorities in Germany and France are prioritizing vendors with pre-certified edge analytics platforms.
Equipment-as-a-service contracting is displacing capital purchase models in North American commercial security. Integrators are bundling installation, maintenance, and cloud storage into per-camera monthly fees, compressing upfront buyer commitment. This shift is most visible among multi-site retail chains and logistics operators seeking operational expenditure predictability across distributed facility footprints.
Night Vision (IR) Surveillance Cameras Market Segmentation
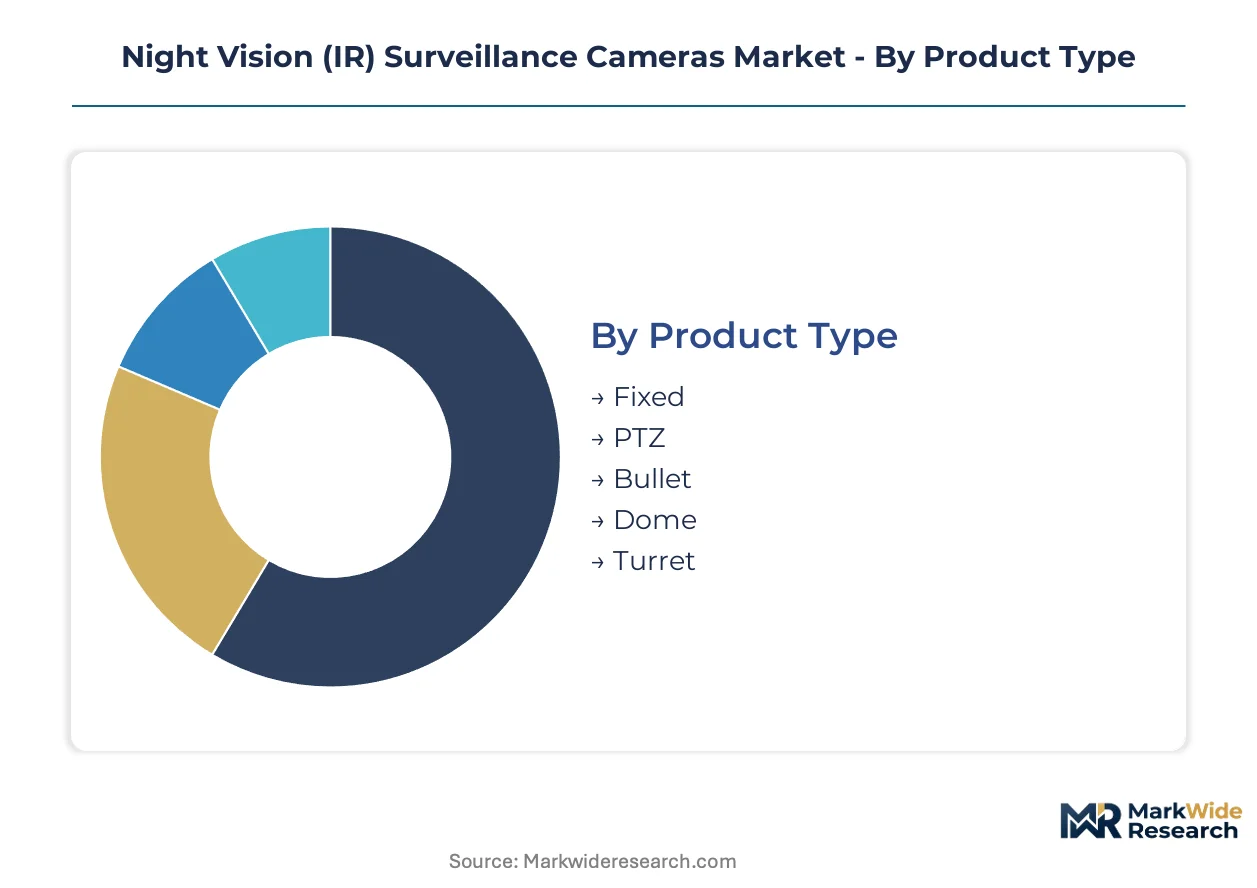
Segmentation in night vision surveillance reveals how procurement channels fragment across defense integrators, municipal authorities, and commercial security providers. Each dimension—product form, connectivity protocol, use case, and buyer type—carries distinct margin profiles and certification requirements that reshape vendor go-to-market strategies.
Product Type:
Fixed cameras flow through commercial distributors and direct OEM contracts, while PTZ configurations concentrate in systems integrator channels serving government and critical infrastructure verticals.
- Fixed:Static-mount housings with fixed focal lengths dominate cost-sensitive commercial installations. Warehouse operators in India and Brazil specify these for wide-area coverage where operator intervention is unnecessary, compressing unit economics through volume procurement.
- PTZ:Pan-tilt-zoom mechanisms with motorized positioning enable operator-controllable surveillance across dynamic perimeters. Border control agencies in the United States and traffic management authorities in Germany drive specification of these units for real-time threat tracking.
- Bullet:Weather-sealed cylindrical housings with integrated IR illuminators suit outdoor perimeter applications. Logistics parks and manufacturing facilities in Mexico favor bullet form factors for their directional coverage and vandal-resistant construction.
- Dome:Hemispherical enclosures with discreet positioning capabilities serve retail and hospitality environments where aesthetic integration matters. Casino operators and upscale commercial developments in Singapore and Dubai specify vandal-resistant dome variants.
- Turret:Ball-and-socket mounting with flexible positioning combines bullet-like performance with dome-like adjustability. Small-to-medium enterprises in South Korea and Taiwan adopt turret designs for their installation flexibility and competitive price positioning.
Fixed cameras dominate installed base across commercial and residential channels. PTZ configurations are where expansion concentrates as defense and smart city budgets prioritize operator-controllable coverage.
Technology:
Technology tiering separates legacy analog replacement demand from premium thermal and edge-AI IP deployments, with cost structures and channel margins diverging sharply across the stack.
- Analog:Coaxial-cable transmission with standard-definition resolution persists in legacy infrastructure where full-network replacement is capital-constrained. Aging CCTV networks in Brazil and Mexico continue analog maintenance cycles despite terminal decline in new procurement.
- IP:Ethernet-based digital transmission with Power-over-Ethernet capability enables centralized management and analytics integration. Municipal smart city programs in India and enterprise campus deployments in Japan anchor IP camera volume.
- Thermal:Uncooled microbolometer or cooled photodetector arrays capturing long-wave infrared radiation enable zero-illumination detection. Perimeter security at power substations in Japan and airport runways in France drives thermal specification for intruder detection beyond visible-light range.
- Digital:Enhanced signal processing with wide dynamic range and noise reduction algorithms improves low-light performance without thermal hardware. Scientific research facilities and wildlife monitoring stations in Australia specify digital enhancement for sub-lux imaging.
- Wireless:Wi-Fi or cellular backhaul eliminating structured cabling requirements suits retrofit environments and temporary deployments. Retail chains in Brazil and construction site operators in South Africa adopt wireless IR cameras to bypass legacy building infrastructure constraints.
Analog systems retain residual installed base in emerging economies with constrained infrastructure budgets. Thermal and IP variants are where expansion concentrates as defense and critical infrastructure procurement hardens around detection reliability.
Application:
Application segmentation maps directly to buyer procurement sophistication, with perimeter and critical infrastructure buyers demanding thermal fusion while retail security operates at standard IP price points.
- Perimeter Monitoring:Continuous boundary surveillance with intrusion detection analytics protects energy, transportation, and defense assets. Nuclear facilities in France and data centers in Germany specify thermal-optical fusion for 24-hour perimeter integrity.
- Traffic Surveillance:License plate recognition and incident detection across roadway networks requires high-frame-rate capture and environmental sealing. Highway authorities in India and tollway operators in Italy drive PTZ and fixed dome procurement for automated violation detection.
- Public Safety:Urban surveillance with facial recognition and crowd analytics capabilities serves law enforcement and emergency response coordination. City police departments in the United Kingdom and Singapore deploy edge-AI enabled cameras for real-time threat classification.
- Critical Infrastructure:Protection of power generation, water treatment, and telecommunications facilities against sabotage and terrorism. Electric utilities in South Korea and oil terminals in Saudi Arabia mandate thermal perimeter monitoring under national security directives.
- Retail Security:Loss prevention and customer flow analysis in commercial environments prioritizes discrete positioning and cost efficiency. Big-box retailers in Mexico and shopping mall operators in Brazil retrofit analog networks with wireless IP alternatives.
Perimeter monitoring commands premium pricing through thermal and analytics integration. Retail security is where expansion concentrates as loss prevention modernization accelerates across Latin American and Southeast Asian markets.
End User:
End user type determines procurement channel structure, with government facilities transacting through defense integrators and commercial establishments purchasing via security distributors and managed service providers.
- Government Facilities:Defense installations, embassies, and administrative buildings requiring cybersecurity-hardened systems with classified data handling protocols. Military bases in the United States and ministry compounds in India specify NDAA-compliant and BIS-certified equipment respectively.
- Commercial Establishments:Corporate campuses, manufacturing plants, and logistics facilities balancing security coverage with operational expenditure predictability. Multi-site operators in Germany and Japan favor equipment-as-a-service contracting to compress upfront capital commitment.
- Educational Institutes:K-12 schools and university campuses requiring scalable coverage with emergency lockdown integration. Campus security directors in Australia and Canada prioritize open-platform cameras compatible with third-party access control systems.
- Transportation Hubs:Airports, seaports, and railway terminals with high-throughput passenger screening and baggage handling security. Aviation authorities in the United Arab Emirates and rail operators in France specify PTZ and fixed dome arrays for platform and concourse coverage.
- Residential Complexes:Gated communities, apartment buildings, and private estates with consumer-grade or prosumer surveillance requirements. Homeowner associations in the United States and villa compounds in Saudi Arabia drive demand for wireless bullet and turret configurations with mobile app integration.
Government facilities anchor premium thermal and PTZ procurement through defense budgeting cycles. Commercial establishments are where expansion concentrates as equipment-as-a-service models displace capital purchase structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The export-import balance for night vision surveillance hardware tilts toward net importers across emerging economies, while established manufacturing bases in China and South Korea supply thermal core components to defense integrators in NATO-aligned markets. Customs data reveals concentrated component flows from East Asian sensor foundries to European and North American system integrators.
United States
Defense procurement from the Department of Homeland Security and Customs and Border Protection drives thermal-enabled PTZ deployments along the southern frontier. The FAA governs drone-mounted surveillance frequencies under Part 107 rulemaking, opening pathways for gimbal-stabilized thermal payloads. Defense contractors in the Virginia-Maryland corridor integrate uncooled microbolometers into perimeter monitoring systems for critical infrastructure.
Germany
Traffic management authorities in Bavaria and North Rhine-Westphalia specify edge-AI enabled cameras for automated violation detection on the Autobahn network. The EU AI Act mandates algorithmic impact assessments for biometric-capable IR deployments in public spaces, extending sales cycles for municipal procurement. Industrial security clusters around Stuttgart and Munich favor thermal-optical fusion for manufacturing facility protection.
India
Smart city initiatives in Mumbai, Delhi, and Bangalore embed IP-based night vision into traffic management and public safety networks. BIS certification mandates electromagnetic compatibility testing for imported camera assemblies, directly shaping supplier market access timelines. Municipal corporations in Maharashtra and Karnataka accelerate dome and bullet configuration procurement for urban surveillance modernization.
Japan
Critical infrastructure protection directives from METI mandate thermal perimeter monitoring for power utilities and transportation authorities. Electric utilities in the Kanto and Kansai regions specify uncooled microbolometer cores for substation security under national security frameworks. Security integrators in the Tokyo-Osaka corridor deploy PTZ configurations for railway terminal coverage.
Saudi Arabia
Oil terminal operators and petrochemical facilities in the Eastern Province mandate thermal surveillance under national security directives for critical infrastructure protection. The SFDA and national cybersecurity authority impose data localization requirements on biometric-capable systems. Giga-project developments at NEOM and the Red Sea coast specify dome and bullet configurations for integrated security networks.
Night Vision (IR) Surveillance Cameras Market Competitive Landscape
Listed leaders compete with private specialists across sensor manufacturing and system integration dimensions. The vendor base separates into three tiers: vertically integrated conglomerates controlling upstream sensor production, open-platform specialists enabling third-party analytics integration, and thermal core miniaturization experts serving defense and perimeter verticals. Dominant competitive moves include backward integration into uncooled microbolometer foundry capacity and strategic partnerships for edge-AI silicon co-development.
Among Chinese manufacturers, HANGZHOU HIKVISION DIGITAL TECHNOLOGY CO. LTD and Dahua Technology Co., Ltd exemplify the vertically integrated archetype with captive sensor production. Axis Communications AB represents the open-platform specialist model, while Teledyne FLIR LLC anchors the thermal core miniaturization tier. Bosch Sicherheitssysteme GmbH and Honeywell International Inc. occupy diversified industrial conglomerate positions with security divisions.
| Leading Market Players |
|---|
| HANGZHOU HIKVISION DIGITAL TECHNOLOGY CO. LTD |
| Dahua Technology Co., Ltd |
| Axis Communications AB |
| Teledyne FLIR LLC |
| Bosch Sicherheitssysteme GmbH |
| Honeywell International Inc. |
| Canon Inc. |
| Panasonic Holdings Corporation |
| Hanwha Vision Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
BIS electromagnetic compatibility certification for Indian market entry gates both supplier qualification timelines and price stratification across import-dependent versus locally-assembled product tiers. This regulatory threshold simultaneously filters out low-margin competitors and creates tiered margin pools for vendors with established compliance infrastructure versus those absorbing extended certification cycles.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the night vision surveillance market. Price differentiation hinges on thermal core resolution grade and BIS/FCC certification tier, with premium thermal-fusion configurations commanding substantial markups over standard IP variants. Pricing pressure stems from silicon germanium wafer cost volatility compressing margins on short-wave infrared modules. Municipal procurement authorities exhibit highest price sensitivity due to budget-constrained smart city mandates, while defense integrators demonstrate lowest sensitivity given mission-critical reliability requirements.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for uncooled vanadium oxide microbolometers, while China dominates final camera assembly and IR illuminator component manufacturing. The supply chain draws from germanium substrates, precision optical lenses, and edge-AI processor silicon as critical inputs. Single-source vulnerability concentrates in microbolometer foundry capacity, with procurement timelines exposed to concentrated production among a handful of East Asian facilities. Distribution runs through defense systems integrators for government verticals and security distributors for commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The night vision surveillance market sits in early-cycle expansion as analog-to-IP migration accelerates replacement demand across municipal and critical infrastructure verticals. Smart city infrastructure mandates in India and thermal perimeter protection directives in Japan provide sustained adoption tailwinds through the projection horizon.
For Market Incumbents: Compound defensive positioning through backward integration into uncooled microbolometer foundry capacity and pre-certification of edge-AI platforms under EU AI Act algorithmic transparency requirements. The threat of mid-tier suppliers achieving resolution parity through sub-12-micrometer pixel pitch access demands rapid R&D allocation toward thermal-optical fusion engineering talent retention.
For New Entrants and Emerging Players: Anchor in wireless retrofit deployments across Brazilian and Mexican retail chains where legacy analog infrastructure constraints create white-space opportunity. The most penetrable segment lies in equipment-as-a-service contracting for multi-site commercial operators seeking operational expenditure predictability. A direct go-to-market angle through managed security service providers bypasses entrenched distributor relationships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed thermal core specialists possessing defense-contractor alumni engineering pools and established BIS/FCC certification infrastructure. Long-term viability over a 5-10 year window favors targets with edge-AI silicon co-development partnerships and municipal smart city reference contracts. The signal to watch is FAA Part 107 rulemaking progression for drone-mounted thermal payload frequency allocations as inflection indicator for aerial surveillance market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Silicon Co-Development | Partnerships with neural processor vendors enable real-time threat classification without cloud dependency for municipal buyers. |
| Backward Integration into Microbolometer Foundry | In-house vanadium oxide sensor production insulates margins from single-source supply concentration risk. |
| EU AI Act Pre-Certification | Algorithmic impact assessment readiness creates competitive moats for biometric-capable deployments in German and French public spaces. |
| Equipment-as-a-Service Platform Launch | Per-camera monthly fee structures compress upfront capital commitment for North American multi-site retail chains. |
| Drone-Mounted Thermal Payload Development | Gimbal-stabilized integration aligns with FAA Part 107 frequency allocation pathways for unmanned aerial surveillance. |
Research Methodology
Operator-level perspectives from municipal procurement officers, defense systems integrators, critical infrastructure security directors, and commercial security distributors anchored the qualitative base. Primary interviews combined with secondary validation from BIS certification databases, FCC equipment authorization filings, EU AI Act implementation guidance, and customs trade data for thermal sensor component flows. Bottom-up demand modeling across product form factors and top-down macroeconomic triangulation informed volume estimates.
Sensitivity analysis tested forecast robustness across alternative adoption scenarios for thermal-fusion specifications and edge-AI penetration rates over the projection horizon. The analytical framework modeled segmentation across product type, technology tier, application vertical, and end-user category, with additional dimensioning by certification regime cluster. CAGRs derived from regression analysis of historical procurement cycles and forward projection of smart city budget allocations, with defense spending patterns and silicon wafer pricing trends as industry-specific inputs.
Decision-makers should treat outputs as directional under assumptions of sustained municipal infrastructure investment and stable East Asian sensor foundry capacity; material deviation in either driver would warrant model refresh. Forecasts reflect base-case assumptions regarding regulatory timeline adherence for BIS and EU AI Act compliance pathways. Recalibration cycles align with material shifts in defense procurement appropriations and FAA drone integration rulemaking milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Japan Surveillance IP Cameras Market
Video Surveillance Systems
North America Video Surveillance Systems Market
Video Surveillance Systems
Security and Surveillance Storage Market
Video Surveillance Systems
Middle East and Africa Video Surveillance Storage Market
Video Surveillance Systems
Concealed Weapon Detection Systems Market
Video Surveillance Systems
United Kingdom Surveillance IP Camera Market
Video Surveillance Systems
Smart Camera System Market
Video Surveillance Systems
Germany Surveillance IP Camera Market
Video Surveillance Systems
Global Trade Surveillance Systems Market
Video Surveillance Systems
Japan Surveillance Storage Market
Video Surveillance Systems
Mexico Video Surveillance Market
Video Surveillance Systems
Asia-Pacific Surveillance Storage Market
Video Surveillance Systems
Canada Video Surveillance Market
Video Surveillance Systems
India Surveillance Storage Market
Video Surveillance Systems
Camera Alarm System Market
Video Surveillance Systems
Latin America Video Surveillance Market