
 Canada Video Surveillance Market | 2026-2036
Canada Video Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Video Surveillance Market Insights
Multi-source procurement among municipal and provincial agencies is repositioning vendor relationships across the Canadian security landscape. Avigilon Corporation leverages its domestic manufacturing footprint to anchor large-scale transit deployments. Genetec competes through open-architecture software platforms that integrate third-party hardware. Bosch Sicherheitssysteme GmbH sustains its position via specialized thermal imaging systems for northern climate applications.
Video surveillance encompasses the capture, transmission, storage, and analysis of visual data through camera systems operating at resolutions from 720p to 4K and beyond, with frame rates typically between 15-30 fps for standard monitoring and up to 60 fps for motion-critical environments. These systems serve primarily to deter criminal activity, enable forensic investigation, and support real-time operational decision-making in commercial and public settings. IP Cameras dominate product type revenue due to PoE installation economics and software upgrade paths, while Cloud-based technology segments expand fastest as Canadian enterprises shift capital expenditure to operational models. Thermal Imaging occupies a premium niche where perimeter detection must function through fog, snow, and zero-light conditions common across Prairie and Northern territories.
Health Canada privacy guidelines, PIPEDA federal privacy law, and provincial freedom of information statutes collectively mandate encrypted storage, access logging, and data retention limits that elevate product compliance costs. The Canadian Security Intelligence Service and RCMP operational requirements further shape specifications for federal and critical infrastructure installations. Stakeholders must monitor evolving provincial privacy commissioner rulings on facial recognition to anticipate technology deployment boundaries.
Market Dynamics
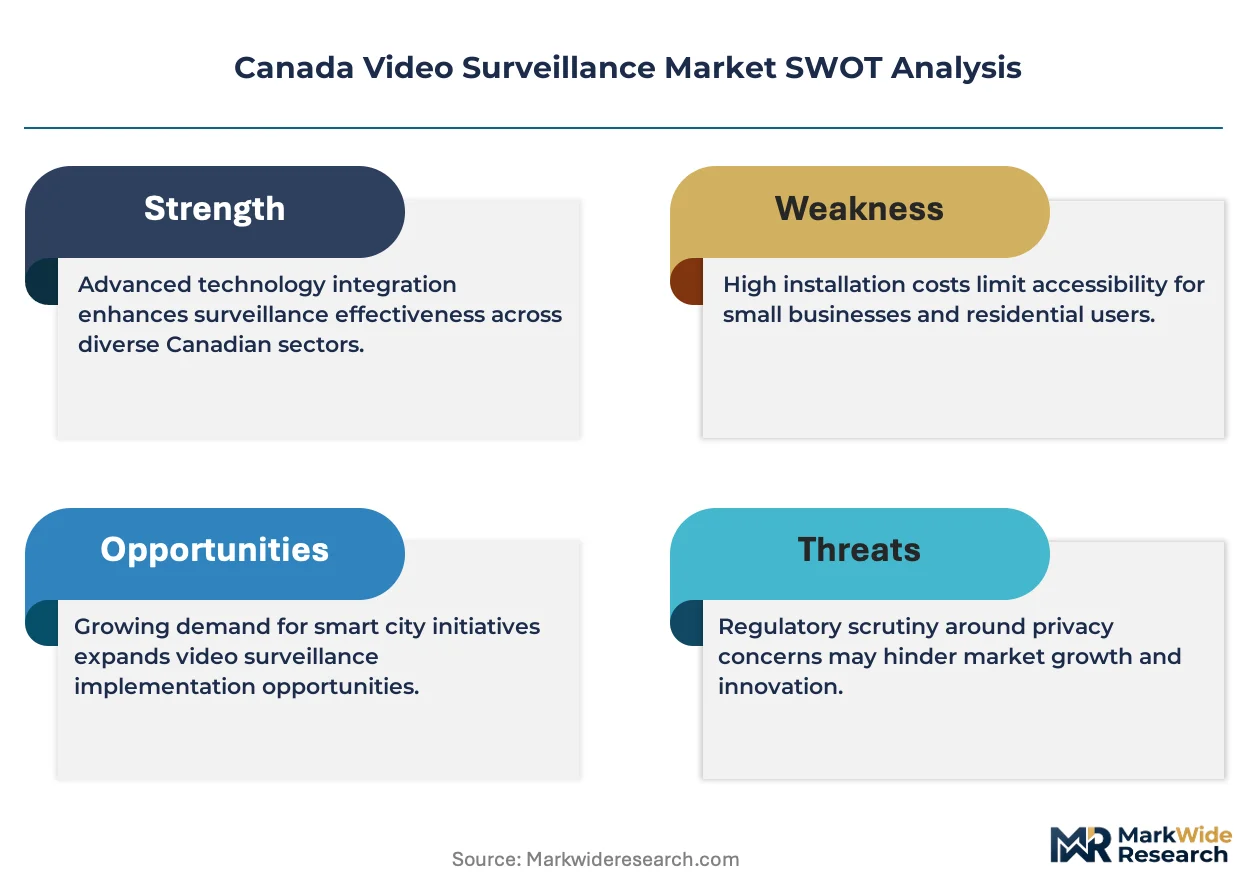
Municipal transit authorities and critical infrastructure operators across Ontario, British Columbia, and Alberta are consolidating procurement into multi-year framework agreements that favor vendors with domestic manufacturing and Health Canada privacy certification capabilities.
Growth Catalysts
- PIPEDA Compliance Mandates:Federal privacy law amendments require encrypted storage and access logging for all public-sector deployments, creating mandatory upgrade cycles across provincial agencies.
- Urban Transit Expansion:Toronto Transit Commission and TransLink Vancouver are adding platform-edge and vehicle-interior camera density to meet operational safety targets.
- PoE Installation Economics:Power-over-Ethernet cabling reduces labor costs and enables incremental camera additions without electrical contractor involvement.
Market Restraints
- Semiconductor Supply Concentration:Image sensor fabrication concentrates in Taiwan and South Korea, exposing Canadian integrators to lead-time volatility for 4K and thermal modules.
- Provincial Privacy Friction:Ontario and British Columbia privacy commissioners have issued divergent guidance on facial recognition deployment, complicating national product roadmaps.
- Cloud Connectivity Costs:Northern Prairie and Arctic territories lack fiber backbone density, forcing expensive satellite backhaul for remote perimeter monitoring.
Strategic Opportunities
- RCMP Federal Modernization:Royal Canadian Mounted Police national security infrastructure refresh creates demand for CSIS-compliant, domestically hosted video management platforms.
- Healthcare Facility Integration:Hospital networks in Quebec and Alberta are converging surveillance with nurse-call and access control systems onto unified IP networks.
- Indigenous Community Partnerships:First Nations policing agreements in Northern Ontario and Manitoba specify local data sovereignty, opening niche deployment channels.
Industry Challenges
- Cybersecurity Certification Timelines:Canadian Centre for Cyber Security evaluation for federal deployments adds 8-14 months to product qualification, compressing vendor R&D windows.
- Legacy Analog Migration Complexity:Municipalities with 2000s-era coaxial infrastructure face disruptive rip-and-replace decisions versus hybrid encoder bridging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Video Surveillance Market |
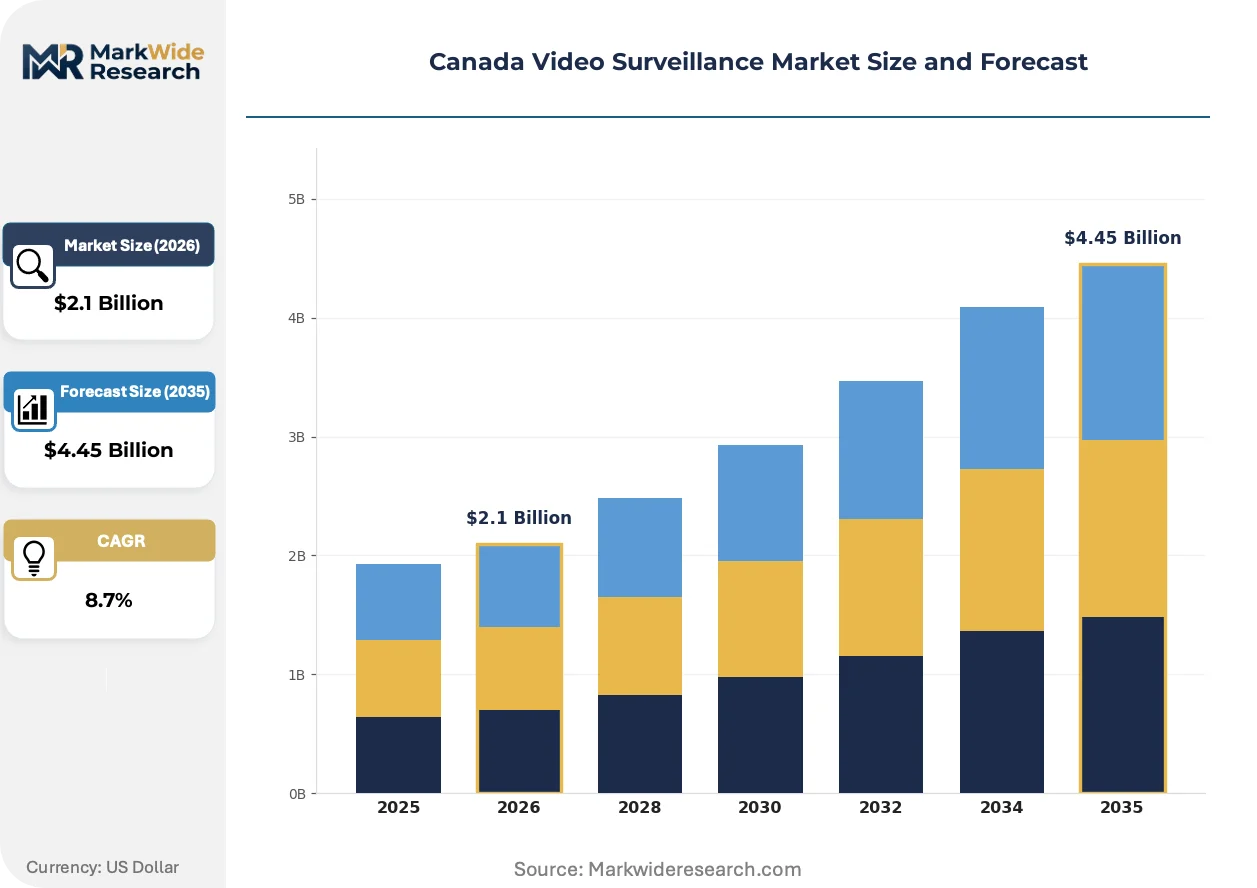
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Cameras, IP Cameras, DVRs, NVRs End User: Retail, Government, Transportation, Healthcare Technology: HD-SDI, PTZ, Thermal Imaging, Cloud-based Installation Type: Indoor, Outdoor, Wireless, Wired |
| Companies Covered | GardaWorld, SecurTek, Avigilon Corporation, A.p.i. Alarm Inc., Telus, Genetec, Sirix, Bosch Sicherheitssysteme GmbH, March Networks, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Video Surveillance Market Trends and Innovations
Artificial intelligence inference at the network edge is compressing response times for anomaly detection while shifting computational load away from centralized servers. This architectural pivot demands new hardware form factors and reskilling among installation technicians.
Edge-based video analytics is automating real-time threat classification without human operator review. Toronto Transit Commission and Calgary Transit are deploying these systems platform-wide to reduce control-room staffing ratios. The technology is automating incident escalation workflows that previously required manual verification, compressing emergency response protocols from minutes to seconds.
Health Canada and provincial privacy commissioners are tightening guidance on biometric data retention and cross-border cloud storage. The PMRA is coordinating with federal cybersecurity agencies to mandate encryption standards for video streams transiting public networks. Critical infrastructure operators in Ontario and British Columbia are responding by specifying on-premises storage with air-gapped backup architectures.
Buying committees at municipal agencies are unbundling hardware, software, and maintenance into separate competitive solicitations. This disaggregation favors specialized vendors with open-API platforms over vertically integrated suppliers. The pattern is most visible in Quebec and Alberta, where provincial procurement frameworks now mandate component-level pricing transparency.
Canada Video Surveillance Market Segmentation
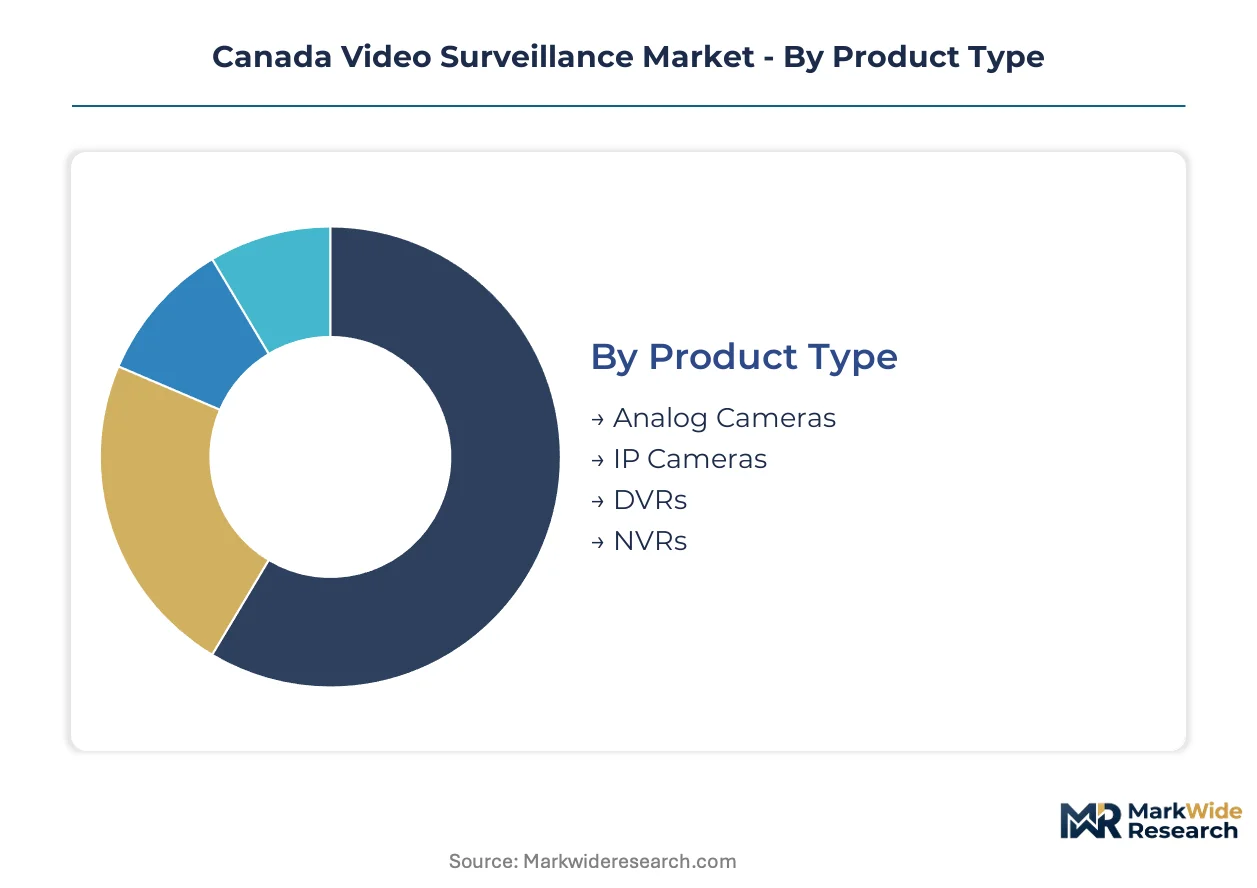
Canadian procurement patterns fragment across four distinct segmentation axes, each commanding separate specification requirements from vendors. Health Canada privacy mandates and provincial transit authority frameworks create divergent technical priorities that reshape product positioning across product type, end user, technology, and installation configurations.
Product Type:
Standardization dominates at the infrastructure layer while software-defined flexibility accelerates at the camera tier, creating a bifurcated procurement landscape for Canadian integrators.
- IP Cameras:Network-addressable devices leverage Power-over-Ethernet for single-cable installation and support firmware upgrades that extend operational lifespan. Toronto Transit Commission and TransLink Vancouver specify these units for platform-edge density programs driven by PIPEDA encrypted storage mandates.
- Analog Cameras:Coaxial-based systems persist in legacy municipal infrastructure where rip-and-replace budgets remain constrained. Northern Ontario and Manitoba First Nations policing agreements specify these for cost-containment in low-density deployments.
- NVRs:Network video recorders consolidate IP camera streams with embedded analytics processing.
- DVRs:Digital video recorders bridge analog camera investments for hybrid migration scenarios.
Most installed capacity flows through IP Cameras. Expansion is steepest in NVRs.
End User:
Customer type determines compliance tier, with federal and critical infrastructure operators facing the most stringent certification requirements.
- Government:Federal agencies and provincial ministries require Canadian Centre for Cyber Security evaluation and domestic data residency. RCMP national security infrastructure refresh programs concentrate demand in Ottawa and regional command centers.
- Transportation:Transit authorities prioritize real-time edge analytics for platform safety and vehicle-interior coverage. Calgary Transit and Toronto Transit Commission framework agreements specify multi-year deployment schedules with performance-based maintenance clauses.
- Healthcare:Hospital networks in Quebec and Alberta converge surveillance with nurse-call and access control systems.
- Retail:Loss prevention and liability documentation drive deployment in urban commercial corridors.
Government captures the largest procurement volume. Healthcare is climbing the fastest.
Technology:
Maturity gradients separate proven HD transmission from emerging cloud architectures that demand new connectivity investments.
- Cloud-based:Subscription models shift capital expenditure to operational budgets with centralized management portals. Prairie and Arctic territories face satellite backhaul cost penalties that slow adoption outside fiber-served urban cores.
- Thermal Imaging:Infrared sensors detect perimeter intrusion through fog, snow, and zero-light conditions. Alberta oil sands operators and northern critical infrastructure sites specify these for climate-resilient detection.
- PTZ:Pan-tilt-zoom mechanisms enable operator-directed coverage of dynamic incident zones.
- HD-SDI:High-definition serial digital interface delivers uncompressed video over coaxial for legacy upgrade paths.
HD-SDI retains the largest installed base. Cloud-based architectures gain share fastest.
Installation Type:
Physical deployment constraints vary dramatically across Canadian climate zones and building vintage.
- Outdoor:Weather-sealed housings with heater elements and vandal-resistant domes withstand temperature swings from Prairie winters to coastal humidity. British Columbia municipal camera networks specify IP67-rated enclosures for coastal salt exposure.
- Wireless:Radio-frequency links bypass trenching costs in heritage districts and temporary deployment scenarios. Toronto heritage commercial corridors use these to avoid facade penetration restrictions.
- Indoor:Climate-controlled environments enable standard dome and bullet form factors with simplified mounting.
- Wired:Fiber and copper infrastructure delivers guaranteed bandwidth for high-resolution multi-camera sites.
Wired infrastructure carries the majority of traffic. Wireless deployment shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's Golden Horseshoe corridor anchors Canadian video surveillance procurement, with municipal transit authorities and critical infrastructure operators driving multi-year framework agreements across the province.
Ontario
Toronto Transit Commission platform-edge camera density programs and Ottawa federal security infrastructure refresh create concentrated demand for PIPEDA-compliant encrypted storage systems. Health Canada privacy guidelines mandate access logging for all public-sector deployments. The Greater Toronto Area hosts the country's largest transit security procurement cluster.
British Columbia
TransLink Vancouver vehicle-interior coverage expansion and coastal municipal network upgrades prioritize IP67-rated weather sealing for salt exposure resilience. Provincial privacy commissioner rulings on facial recognition deployment shape technology boundaries for vendors. Metro Vancouver concentrates healthcare facility convergence projects unifying surveillance with nurse-call systems.
Alberta
Calgary Transit edge analytics deployment and oil sands perimeter monitoring sustain demand for thermal imaging systems functioning through Prairie winter conditions. Provincial procurement frameworks mandate component-level pricing transparency in competitive solicitations. Edmonton and Fort McMurray anchor critical infrastructure operator consolidation into multi-year agreements.
Quebec
Hospital network convergence of surveillance with access control systems drives unified IP network investments in Montreal and Quebec City. Provincial freedom of information statutes mandate data retention limits that elevate compliance costs for vendors. The Montreal metropolitan area hosts specialized healthcare security integration clusters.
Canada Video Surveillance Market Competitive Landscape
Global majors compete with regional champions across technology integration and domestic certification capabilities, producing a tiered structure where federal compliance requirements filter out smaller integrators. The vendor base separates into three strategic archetypes: vertically integrated hardware-software platforms, specialized thermal and edge analytics developers, and security service operators bundling monitoring with equipment deployment. Dominant competitive moves include strategic partnerships for Health Canada privacy certification and geographic expansion through provincial framework agreement qualification.
Within the domestic manufacturing tier, Avigilon Corporation and March Networks exemplify vendors leveraging Canadian production footprints to anchor large-scale transit deployments. Genetec occupies a position among open-architecture software specialists competing through third-party hardware integration capabilities. Bosch Sicherheitssysteme GmbH represents the European industrial conglomerate archetype sustaining market presence via climate-specialized thermal imaging systems. These three company types collectively span the certification-heavy federal procurement segment, the software-flexible municipal transit vertical, and the harsh-environment critical infrastructure niche.
| Leading Market Players |
|---|
| GardaWorld |
| SecurTek |
| Avigilon Corporation |
| A.p.i. Alarm Inc. |
| Telus |
| Genetec |
| Sirix |
| Bosch Sicherheitssysteme GmbH |
| March Networks |
| Others |
Pricing and Supply Chain Analysis
Image sensor fabrication costs in Taiwan and South Korea cascade through three distinct pricing tiers for Canadian integrators, with 4K and thermal modules commanding premiums that compress margins for municipal transit authorities operating under fixed framework budgets.
Pricing Analysis
Input-cost pass-through from semiconductor foundries drives subscription-based SaaS pricing for cloud-managed camera networks, while project-based procurement persists for federal installations requiring Canadian Centre for Cyber Security certification. Price differentiation separates Health Canada-compliant encrypted storage tiers from standard commercial offerings, with after-sales service bundling widening spreads. Cost compression in mid-tier IP camera segments intensifies as PoE installation economics standardize, making provincial transit authorities most price-sensitive while critical infrastructure operators absorb premiums for thermal resilience.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based image sensor foundries and South Korean memory fabrication, exposing Canadian integrators to lead-time volatility that ripples through Prairie and Arctic deployment schedules. Component dependencies center on CMOS sensors, edge AI processing units, and hardened storage arrays. Tariff exposure on Chinese-manufactured camera housings compounds logistics chokepoints at Vancouver and Montreal ports. Distribution runs through specialized security integrators holding provincial framework qualifications, with direct OEM relationships reserved for federal and critical infrastructure accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada video surveillance market represents a late-cycle quality story as procurement committees unbundle hardware and software into separate competitive solicitations, elevating vendors with open-API platforms and domestic privacy certification over vertically integrated suppliers.
For Market Incumbents: Deploy Health Canada privacy certification as a defensive moat against emerging cloud-native entrants lacking federal evaluation timelines. Anchor large-scale transit deployments through multi-year framework agreements with Toronto Transit Commission and TransLink Vancouver. Deepen backward integration into edge AI processing modules to offset semiconductor supply concentration risks from Taiwan and South Korea. For New Entrants and Emerging Players: Direct-to-government SaaS platforms offer the most penetrable route for bypassing incumbent integrator relationships, particularly in Quebec and Alberta where provincial procurement mandates component-level pricing transparency. Target healthcare facility convergence projects unifying surveillance with nurse-call systems. Lead with subscription models that shift municipal capital expenditure to operational budgets. For Investors and Strategic Acquirers: Consolidation pressure builds where open-architecture software specialists lack domestic manufacturing footprints to qualify for federal procurement. Long-term viability favors vendors bridging Health Canada compliance capabilities with edge analytics development. Acquisition target archetypes include thermal imaging developers with Prairie climate specialization and Indigenous community data sovereignty expertise. Watch for inflection signals in provincial privacy commissioner rulings on facial recognition deployment boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Privacy Certification Investment | Qualifies vendors for RCMP and federal infrastructure refresh programs requiring encrypted storage mandates. |
| Edge AI Analytics Platform Development | Enables Toronto Transit Commission and Calgary Transit to compress emergency response protocols through automated threat classification. |
| Indigenous Community Data Sovereignty Partnership | Opens niche deployment channels under First Nations policing agreements in Northern Ontario and Manitoba. |
| Thermal Imaging Climate Specialization | Secures perimeter monitoring contracts with Alberta oil sands operators through fog and zero-light detection capabilities. |
| Open-API Ecosystem Integration | Aligns with Quebec and Alberta provincial frameworks mandating component-level pricing transparency in competitive solicitations. |
Research Methodology
Direct dialogue with municipal transit procurement officers, critical infrastructure security directors, Health Canada compliance consultants, and provincial privacy commission staff anchored the qualitative foundation, cross-referenced against Canadian Security Intelligence Service operational requirements, PIPEDA amendment tracking, Toronto Transit Commission framework documentation, and British Columbia municipal procurement records. Bottom-up installation volume estimates from transit authority capital plans triangulated with top-down vendor revenue attribution across product type and technology segments.
Segment-level CAGRs emerged from modeled deployment trajectories across IP camera density programs, cloud migration curves, and thermal imaging penetration in northern climate applications, with provincial procurement framework timelines and federal infrastructure refresh schedules serving as primary demand anchors. The analytical framework incorporated technology substitution dynamics between analog legacy systems and PoE-enabled IP networks, as well as compliance cost pass-through from encrypted storage mandates.
Semiconductor supply disruptions, divergent provincial privacy commissioner rulings on facial recognition, and satellite backhaul cost volatility in Prairie territories are the dominant revision risks that could compress or extend deployment timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Europe Video Surveillance As a Service Market
Video Surveillance Systems
Central Monitoring Station Market
Video Surveillance Systems
Japan Surveillance Camera Market
Video Surveillance Systems
Canada Surveillance Storage Market
Video Surveillance Systems
Middle East and Africa Video Surveillance Storage Market
Video Surveillance Systems
United States Surveillance IP Camera Market
Video Surveillance Systems
Canada Surveillance Camera Market
Video Surveillance Systems
Global CCTV Market
Video Surveillance Systems
City Surveillance Market
Video Surveillance Systems
Italy Video Surveillance Market
Video Surveillance Systems
North America Surveillance IP Camera Market
Video Surveillance Systems
Smart Outdoor Cameras Market
Video Surveillance Systems
Europe Surveillance IP Camera Market
Video Surveillance Systems
AI in Video Surveillance Market
Video Surveillance Systems
Europe Surveillance Camera Market
Video Surveillance Systems
Mini Security Camera Market