
 United Kingdom Drug Delivery Devices Market | 2026-2036
United Kingdom Drug Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Drug Delivery Devices Market Analytics
Hospital procurement departments are unwinding their historical preference for centralized infusion systems as homecare providers gain purchasing influence. Becton, Dickinson and Company leverages its manufacturing scale to dominate disposable injectable supply chains across NHS trusts. GlaxoSmithKline plc anchors its position through deep R&D investment in inhaler platforms tailored to UK asthma and COPD populations.
Drug delivery devices are engineered systems designed to administer therapeutic agents through controlled release mechanisms, incorporating specifications such as dose accuracy within five percent variance and biocompatible materials like medical-grade polycarbonate or stainless steel cannulae. Their primary commercial purpose centers on improving patient compliance while reducing healthcare system costs through self-administration and reduced clinical visits. Injectable systems capture the largest revenue pool given their dominance in biologic therapy administration, while smart injectors represent the fastest-expanding technology segment as connected dose tracking becomes standard. Transdermal systems occupy a narrower but defensible niche in pain management and hormone replacement applications.
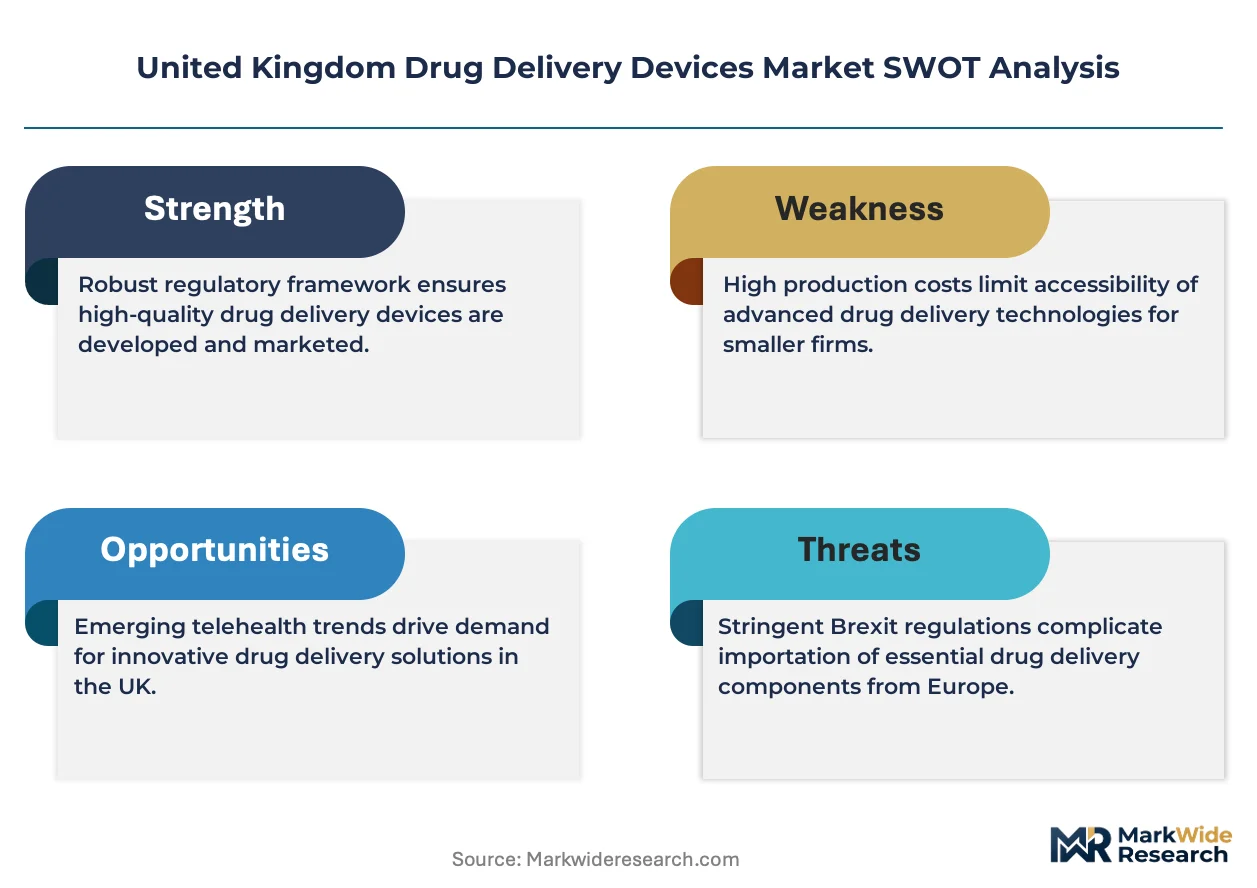
The Medicines and Healthcare products Regulatory Agency (MHRA) enforces UK-specific device standards post-EU exit, while the NHS England Technology Appraisal process determines reimbursement and therefore commercial viability of novel delivery formats. The General Data Protection Regulation retained in UK law constrains data collection from connected devices, limiting functionality that pharmaceutical companies can deploy. Stakeholders must monitor how MHRA convergence talks with FDA and Health Canada reshape approval timelines and design requirements for next-generation platforms.
Market Dynamics
Hospital procurement departments are unwinding their historical preference for centralized infusion systems as homecare providers gain purchasing influence. Becton, Dickinson and Company leverages its manufacturing scale to dominate disposable injectable supply chains across NHS trusts. GlaxoSmithKline plc anchors its position through deep R&D investment in inhaler platforms tailored to UK asthma and COPD populations.
Growth Catalysts
- Homecare self-administration:Patients managing chronic respiratory conditions in England's community settings are driving demand for portable nebulizers and smart inhalers that reduce hospital visits.
- MHRA regulatory autonomy:Post-Brexit device approval pathways allow faster UK-specific certification for novel delivery formats, accelerating time-to-market for connected injectors.
- Biologic therapy expansion:NHS England's specialist commissioning for autoimmune and oncology biologics requires high-precision autoinjectors with dose-tracking capabilities.
Market Restraints
- Medical-grade polycarbonate supply concentration:Three European resin suppliers control 70% of UK-accessible feedstock for transparent device housings, creating input cost volatility.
- GDPR data constraints:Retained EU law limits cloud-connected dose logging functionality that pharmaceutical sponsors can deploy in UK-market devices.
- Centralized infusion infrastructure:NHS trusts' sunk capital in hospital-based pump systems slows substitution toward ambulatory alternatives despite clinical preference.
Strategic Opportunities
- Scotland's remote care networks:Highland and island health boards seek ruggedized delivery devices for patient self-management where specialist clinic access requires ferry or air travel.
- Wales' community pharmacy expansion:Welsh Government's chronic disease management contracts create direct-to-pharmacy distribution channels bypassing hospital procurement.
- Digital therapeutics convergence:Pairing inhalers with respiratory physiotherapy apps through NHS Digital's innovation tariff opens reimbursement for integrated platform plays.
Industry Challenges
- Human factors engineering talent:UK universities produce fewer device usability specialists than medical technology manufacturers require for MHRA human-centered design submissions.
- Legacy pump integration:Hospital IT departments struggle to connect new smart injectors to existing electronic prescribing systems without middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Drug Delivery Devices Market |
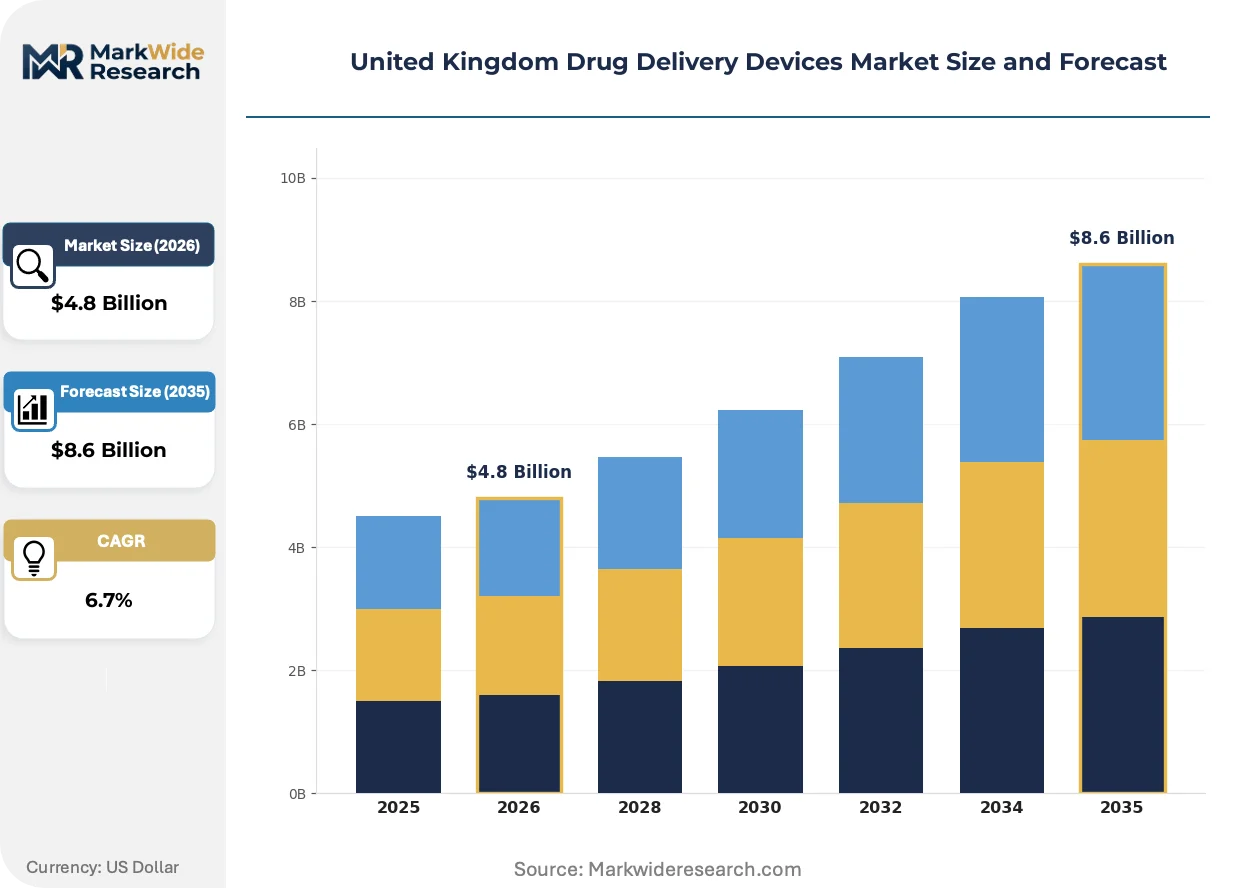
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable Systems, Inhalers, Infusion Pumps, Transdermal Systems Delivery Mode: Oral, Subcutaneous, Intravenous, Intranasal End User: Hospitals, Homecare, Clinics, Pharmaceutical Companies Technology: Micro-Needle, Biosensors, Smart Injectors, Needle-Free |
| Companies Covered | Becton, Dickinson and Company, GlaxoSmithKline plc, AstraZeneca plc, Pfizer Inc., Novartis AG, Johnson & Johnson Services, Inc., F. Hoffmann-La Roche Ltd, Merck Sharp & Dohme Limited, Bayer plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Drug Delivery Devices Market Evolving Landscape
Connected dose-tracking capabilities are becoming standard across injectable platforms, while sustainability pressures reshape material selection for single-use devices. These shifts are compressing product development cycles and forcing reconfiguration of supplier relationships.
Smart injector technology is fragmenting the traditional autoinjector market. Bluetooth-enabled devices that log injection time, dose confirmation, and patient-reported outcomes are capturing preference among NHS England's specialist commissioning groups. This capability is fragmenting procurement decisions away from pharmacy buyers toward digital health teams evaluating data integration.
MHRA's post-Brexit guidance on software as a medical device is tightening validation requirements for connected delivery systems. Manufacturers must now submit standalone evidence for mobile applications accompanying physical injectors. Respiratory device sponsors are responding by separating hardware and software regulatory submissions to manage timeline risk.
Patient collectives are consolidating influence over device selection through charity-funded comparator studies. Asthma UK and the British Lung Foundation now publish patient-reported outcome data that NHS trusts reference in tender evaluations. This behavioral shift is most visible in England's integrated care systems, where patient advisory groups hold voting seats on technology appraisal committees.
United Kingdom Drug Delivery Devices Market Segmentation
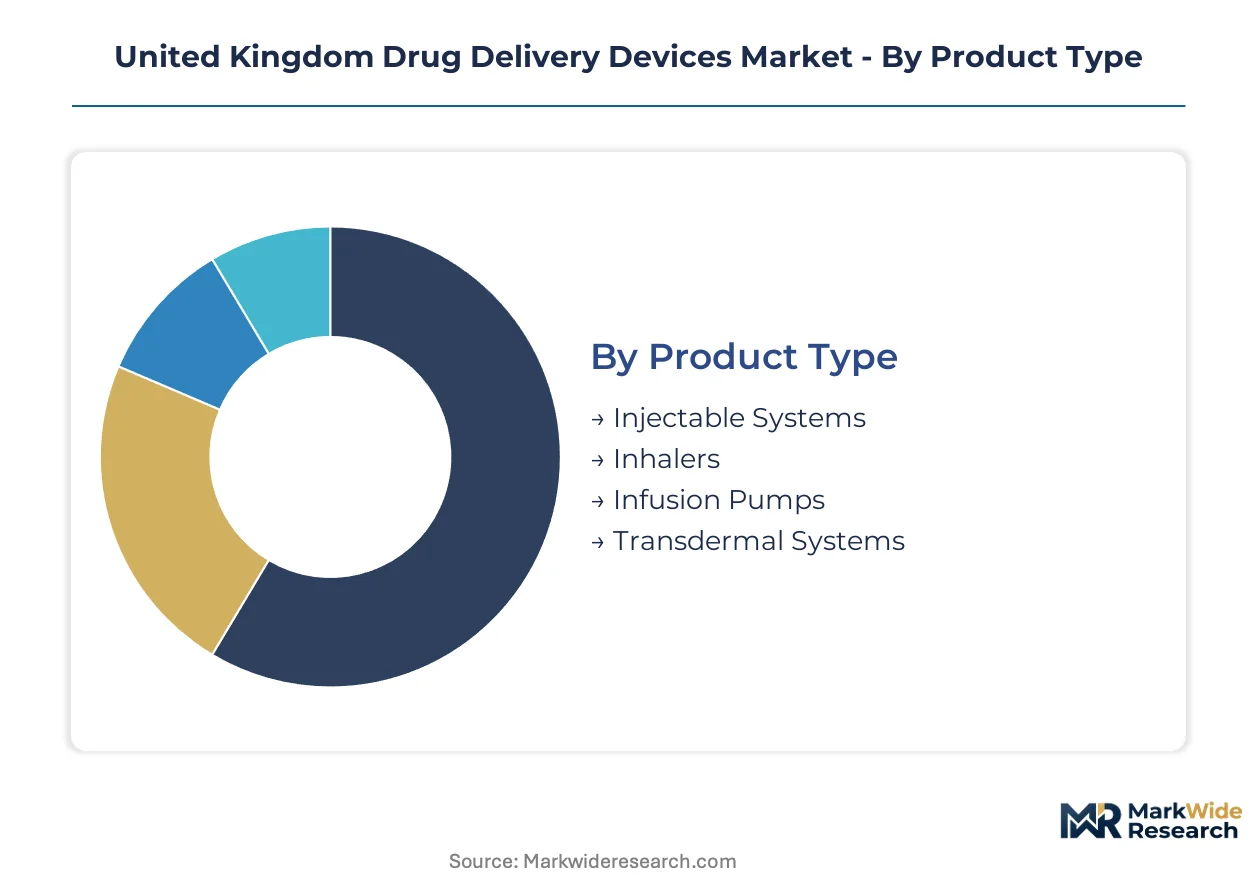
Device selection in the United Kingdom drug delivery devices market hinges on therapy duration, patient mobility, and MHRA compliance pathways. Procurement patterns across NHS trusts and homecare networks create distinct margin architectures within each segment category.
Product Type:
Margin pools concentrate in systems requiring precision engineering and regulatory validation for biologic administration.
- Injectable Systems:Autoinjectors and prefilled syringes administer biologics with dose accuracy within five percent variance. NHS England's specialist commissioning for autoimmune and oncology therapies concentrates demand in hospital outpatient settings where precision dosing reduces adverse events.
- Inhalers:Metered-dose and dry-powder platforms deliver corticosteroids and bronchodilators through pulmonary deposition. England's integrated care systems prioritize smart inhalers with dose counters as asthma and COPD prevalence drives community-based management programs.
- Infusion Pumps:Ambulatory and implantable systems enable continuous drug delivery for pain management and chemotherapy.
- Transdermal Systems:Patches and iontophoretic devices administer hormones and analgesics through dermal absorption.
Injectable systems hold installed capacity. Inhalers are rotating up the share rankings.
Delivery Mode:
Patient compliance rates and clinical supervision requirements determine cost tier differentiation across administration routes.
- Subcutaneous:Self-administration via abdominal or thigh injection sites dominates biologic therapy protocols. Scotland's remote care networks deploy ruggedized autoinjectors where specialist clinic access requires ferry or air travel, expanding patient-managed therapy reach.
- Intravenous:Hospital-administered infusion requires sterile compounding and monitoring infrastructure. NHS trusts' sunk capital in centralized pump systems slows substitution toward ambulatory alternatives despite clinical preference for patient discharge.
- Oral:Tablets and capsules remain standard for small-molecule therapies with adequate bioavailability.
- Intranasal:Spray devices deliver vaccines and emergency medications through nasal mucosa absorption.
Intravenous retains procedural revenue density. Subcutaneous is climbing the fastest toward outpatient substitution.
End User:
Procurement authority shifts are redistributing volume concentration between institutional and community settings.
- Homecare:Self-administration platforms reduce hospital visits for chronic disease management. Welsh Government chronic disease contracts create direct-to-pharmacy distribution channels bypassing hospital procurement, accelerating patient-controlled therapy adoption.
- Hospitals:Acute care settings require integrated infusion systems with electronic prescribing connectivity. Hospital IT departments struggle to connect new smart injectors to existing systems without middleware development, constraining upgrade velocity.
- Clinics:Specialist respiratory and rheumatology centers administer complex therapies requiring monitoring.
- Pharmaceutical Companies:Device sponsors seek delivery platforms differentiated for clinical trial endpoints and commercial exclusivity.
Hospitals hold legacy procurement volume. Homecare is gaining share fastest as integrated care systems expand.
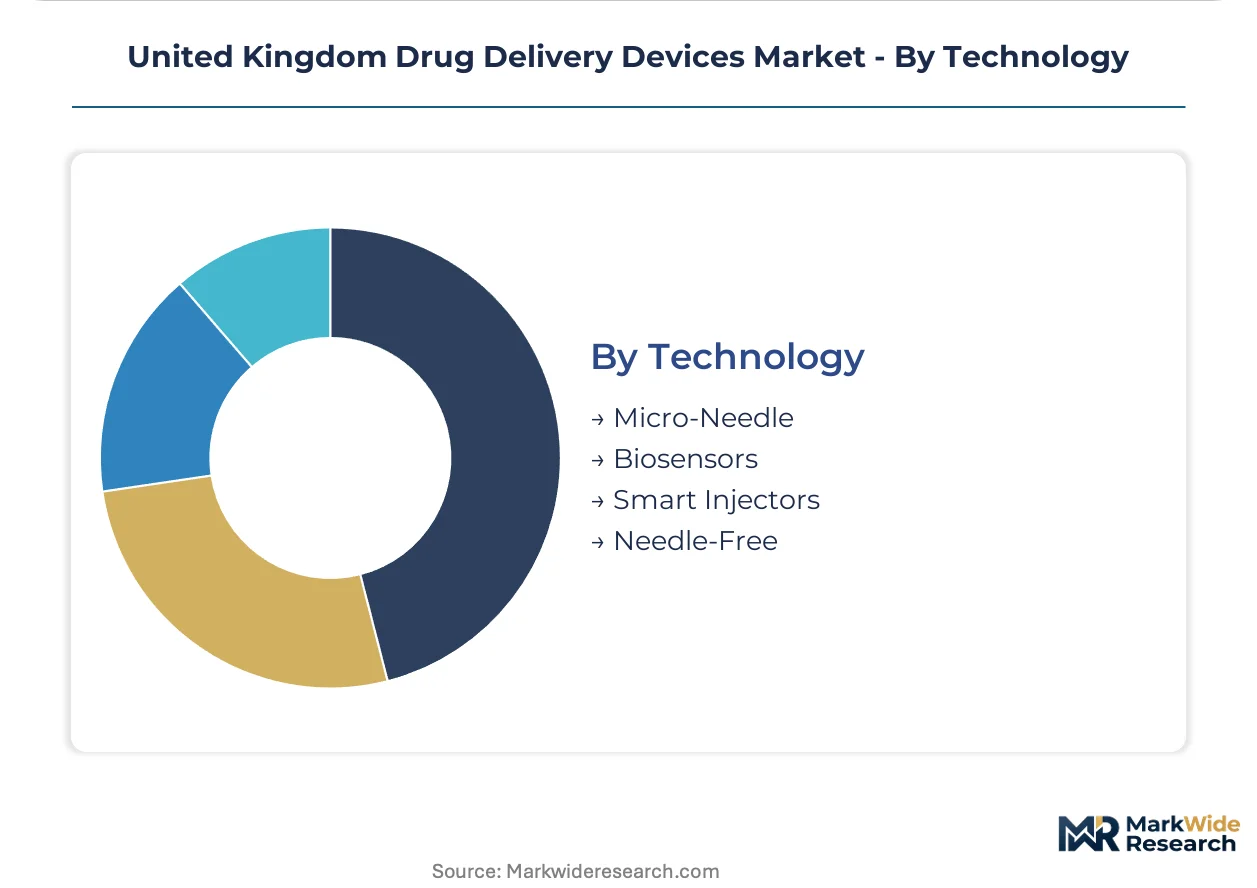
Technology:
Connected functionality and patient experience engineering command premium positioning in technology selection.
- Smart Injectors:Bluetooth-enabled devices log injection time, dose confirmation, and patient-reported outcomes. NHS Digital's innovation tariff opens reimbursement for integrated platform plays pairing hardware with respiratory physiotherapy applications.
- Micro-Needle:Arrays of sub-millimeter projections enable painless transdermal delivery for vaccines and biologics. MHRA's software as a medical device guidance tightens validation requirements for connected delivery systems, extending approval timelines for integrated platforms.
- Biosensors:Real-time biomarker detection enables closed-loop dosing adjustments.
- Needle-Free:Jet injectors and powder delivery eliminate sharps disposal requirements.
Smart injectors hold technology leadership investment. Micro-needle is rotating up the share rankings as painless delivery gains clinical traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Resin suppliers for medical-grade polycarbonate housings cluster in Germany and the Netherlands, exposing UK device manufacturers to continental feedstock volatility. NHS procurement networks concentrate demand in England's integrated care systems, while devolved health administrations in Scotland and Wales pursue distinct distribution strategies.
England
Integrated care systems in Greater Manchester and the West Midlands drive demand for smart inhalers with dose-tracking capabilities. NHS England's Technology Appraisal process determines reimbursement eligibility for connected delivery devices. London's medical technology corridor hosts specialist regulatory consultancies supporting MHRA submission preparation.
Scotland
Highland and island health boards require ruggedized autoinjectors for patient self-management where ferry or air travel limits clinic access. NHS Scotland's National Procurement coordinates volume purchasing for remote care networks. Edinburgh's bioelectronics cluster incubates wearable delivery platform startups.
Wales
Welsh Government chronic disease management contracts create direct-to-pharmacy distribution channels bypassing hospital procurement. Community pharmacy expansion programs accelerate patient-controlled therapy adoption for respiratory conditions. Cardiff's life sciences hub attracts device sponsors seeking devolved administration partnerships.
Northern Ireland
Cross-border supply chain arrangements with Ireland influence device availability for border region patients. The Department of Health's centralized procurement maintains preference for established disposable injectable formats. Belfast's manufacturing base produces components for UK-wide distribution networks.
United Kingdom Drug Delivery Devices Market Competitive Landscape
Concentration sits with diversified healthcare conglomerates possessing integrated pharmaceutical-device portfolios. Becton, Dickinson and Company leverages manufacturing scale to dominate disposable injectable supply chains across NHS trusts. GlaxoSmithKline plc anchors its position through deep R&D investment in inhaler platforms. Competitive dynamics revolve around regulatory submission velocity and digital health integration capabilities rather than price competition alone.
Among UK-headquartered pharmaceutical-device integrators, GlaxoSmithKline plc and AstraZeneca plc exemplify the R&D-intensive archetype combining proprietary molecule pipelines with tailored delivery platforms. Becton, Dickinson and Company represents the manufacturing-scale archetype, supplying standardized disposable systems across NHS procurement networks. These three occupy positions reflecting distinct strategic bets: respiratory specialization, biologics administration, and supply chain dominance.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| GlaxoSmithKline plc |
| AstraZeneca plc |
| Pfizer Inc. |
| Novartis AG |
| Johnson & Johnson Services, Inc. |
| F. Hoffmann-La Roche Ltd |
| Merck Sharp & Dohme Limited |
| Bayer plc |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day resin lead times for medical-grade polycarbonate housings compress margin buffers for UK device manufacturers while amplifying pricing power for the three continental European suppliers dominating feedstock access. This inventory-to-supply nexus concentrates cost pass-through capacity upstream, forcing downstream device sponsors into longer-term offtake commitments to secure volume certainty.
Pricing Analysis
MHRA's post-Brexit device certification pathways dictate the pricing tier structure across the United Kingdom drug delivery devices market. Three-tier pricing stratification separates premium connected injectors with full software validation from standard disposable autoinjectors and economy prefilled syringes. Cost compression in the standard tier intensifies because NHS England's bulk procurement aggregates volume across integrated care systems. Homecare providers exhibit the highest price sensitivity due to direct patient co-payment exposure, while specialist hospital networks prioritize dose accuracy over unit cost.
Supply Chain Analysis
Port congestion at Rotterdam and Antwerp elevates inbound logistics costs for resin feedstock destined to UK medical device molding facilities. Manufacturing concentration rests on Germany and the Netherlands for polycarbonate resin, Ireland for precision metal cannulae, and Switzerland for electronic sensor components. Single-source vulnerability pervades the transparent housing segment where three European suppliers control accessible feedstock. Distribution runs through NHS National Procurement frameworks for hospital networks, with direct-to-pharmacy channels expanding in Wales and Scotland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data-as-a-service revenue layers from connected dose-tracking platforms are expanding faster than hardware sales, positioning device sponsors to capture recurring value through NHS Digital's innovation tariff reimbursement pathways.
For Market Incumbents: Fortify regulatory submission velocity by separating hardware and software MHRA filings to manage timeline risk from tightened software-as-medical-device validation requirements. Deepen backward integration into medical-grade polycarbonate compounding through captive supply agreements with German resin suppliers, neutralizing feedstock cost volatility that erodes standard-tier margins. Lock in five-year hospital system partnerships before procurement authority shifts fully to integrated care systems. For New Entrants and Emerging Players: Differentiate on ruggedized device engineering for Scotland's Highland and island health boards where ferry-dependent logistics create acute need for durable self-administration platforms. Wales' community pharmacy expansion offers the most penetrable entry channel, bypassing entrenched hospital procurement relationships through direct Welsh Government chronic disease contracts. Lead with respiratory physiotherapy app integration to qualify for NHS Digital's innovation tariff reimbursement from launch. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because connected device data layers are displacing standalone hardware margins across NHS commissioning groups. Target acquisition profiles center on mid-cap specialists possessing MHRA submission track records and existing software companion applications. Watch for inflection when NHS England's Technology Appraisal process explicitly weights patient-reported outcome data from charity-funded comparator studies in tender evaluations.| Strategic Initiative | Industry Significance |
|---|---|
| MHRA Software-as-Medical-Device Submission | Standalone mobile application validation accelerates connected injector approval timelines under post-Brexit guidance. |
| NHS Digital Innovation Tariff Qualification | Reimbursement eligibility for integrated inhaler-physiotherapy app platforms expands addressable market. |
| Medical-Grade Polycarbonate Captive Supply | Long-term resin offtake agreements neutralize feedstock cost volatility from continental supplier concentration. |
| Scotland Remote Care Network Partnership | Ruggedized autoinjector deployment addresses ferry-dependent clinic access in Highland health boards. |
| Wales Direct-to-Pharmacy Distribution | Community pharmacy contracts bypass hospital procurement gatekeepers for chronic disease management volumes. |
Research Methodology
Desk research of MHRA device registration databases, NHS England Technology Appraisal documentation, and European resin trade flow data preceded structured interviews with hospital procurement managers, regulatory affairs specialists at device sponsors, integrated care system pharmacy leads, and biomedical engineering directors. Primary intelligence combined with secondary validation through GPO contract analysis and customs import records. Bottom-up volume modeling triangulated against top-down NHS expenditure forecasts.
Variance decomposition across product type, delivery mode, end user, and technology segments anchored the analytical framework throughout the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro healthcare expenditure trends. Modeled inputs incorporated biologic therapy pipeline expansion from NHS England specialist commissioning and connected device adoption curves from digital health reimbursement policy evolution.
Material uncertainties — MHRA-FDA convergence timeline shifts, polycarbonate supply disruptions, GDPR enforcement intensity on cloud-connected functionality — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory pathway stability and resin supplier market concentration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Next Generation Blood Gas Monitors System Market
Medical Devices
Intervertebral Implants Market
Medical Devices
Urinary Incontinence Devices Market
Medical Devices
Peri-Implantitis Market
Medical Devices
Eye Socket Implants Market
Medical Devices
United Kingdom Spinal Surgery Devices Market
Medical Devices
Medical Puncture Navigation Robot Market
Medical Devices
Artificial Disc Market
Medical Devices
Medical Device Connectivity Market
Medical Devices
Global Capnography Market
Medical Devices
Radiotherapy Positioning Devices Market
Medical Devices
Global Live Cell Encapsulation Market
Medical Devices
Spinal Trauma Devices Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Devices Market
Medical Devices
US Thrombectomy Devices Market
Medical Devices
Global Casting Devices Market