
 Middle East and Africa Frozen Snacks Market | 2026-2036
Middle East and Africa Frozen Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Frozen Snacks Market Foresight
Plant-based coating formulations are decoupling from traditional wheat-flour breading in frozen snack production, trimming input costs and extending fryer life for manufacturers. McCain Foods Limited anchors its regional position through potato backward integration from farms in South Africa and Egypt. BRF SA leverages its poultry processing scale to dominate frozen chicken snack supply into the Gulf. Americana Group specializes in halal-certified formulations that sustain premium placement across Saudi and UAE retail channels.
Frozen snacks comprise pre-cooked or par-fried food items stored below minus eighteen degrees Celsius, typically incorporating battered or breaded exteriors that crisp under convection or deep-fry reheating to achieve target core temperatures within four to eight minutes. Frozen meat snacks lead value contribution due to higher protein input costs and halal certification premiums, while frozen fries competes on volume through quick-service restaurant procurement contracts. Retail consumers represent the fastest-growing end-user channel as home freezer penetration deepens in Moroccan and Egyptian urban households.
Saudi Food and Drug Authority and Emirates Authority for Standardization and Metrology enforce cold-chain compliance and halal labeling standards that determine import clearance and retail access across the Gulf. South Africa's National Regulator for Compulsory Specifications mandates frozen food safety protocols that shape manufacturing investments by domestic processors. Stakeholders must monitor evolving Gulf Cooperation Council technical regulations on trans-fat limits and packaging recyclability mandates that will filter supplier qualification criteria before the decade closes.
Market Dynamics
Quick-service restaurant chains across Gulf Cooperation Council states are compressing kitchen footprints and outsourcing frozen snack preparation to centralized suppliers, restructuring procurement relationships and cold-chain infrastructure requirements throughout the region.
Growth Catalysts
- SFDA Cold-Chain Mandates:Saudi Food and Drug Authority storage and transport standards for frozen imports are forcing distributor consolidation and professionalizing logistics networks.
- Urban Freezer Penetration:Moroccan and Egyptian households are acquiring home refrigeration units at accelerating rates, creating pull-through demand for retail-packaged frozen snacks.
- Plant-Based Coating Chemistry:Non-wheat breading formulations are trimming input costs and extending commercial fryer life for manufacturers serving quick-service restaurant accounts.
Market Restraints
- Poultry Input Volatility:Frozen meat snack margins compress when Brazilian and Argentine poultry feed costs spike, given BRF SA's regional dominance in chicken-based products.
- Halal Certification Friction:Emirates Authority for Standardization and Metrology labeling requirements create clearance delays for European and Asian suppliers lacking pre-certified production lines.
- Substitution by Fresh Prepared:In-store bakery and deli counters at South African supermarket chains are capturing snacking occasions with ambient-temperature alternatives.
Strategic Opportunities
- Underpenetrated East African Corridors:Kenya and Ethiopia's urban retail freezer infrastructure remains sparse relative to North African benchmarks, offering first-mover positioning for cold-chain investors.
- Recyclable Packaging Mandates:Gulf Cooperation Council technical regulations on packaging recyclability will filter supplier qualification criteria and reward early compliance investments.
- E-Commerce Frozen Logistics:Last-mile cold delivery networks are emerging in Cairo and Casablanca, enabling direct-to-consumer frozen snack subscription models previously constrained by temperature integrity.
Industry Challenges
- Cold-Chain Technician Scarcity:Refrigeration maintenance and HACCP compliance expertise pools are shallow across secondary Egyptian and Nigerian cities, elevating equipment downtime risk.
- Trans-Fat Reformulation Timelines:Gulf regulators are advancing limits on partially hydrogenated oils, forcing recipe redevelopment without compromising fry-crisp texture that consumers expect.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Frozen Snacks Market |
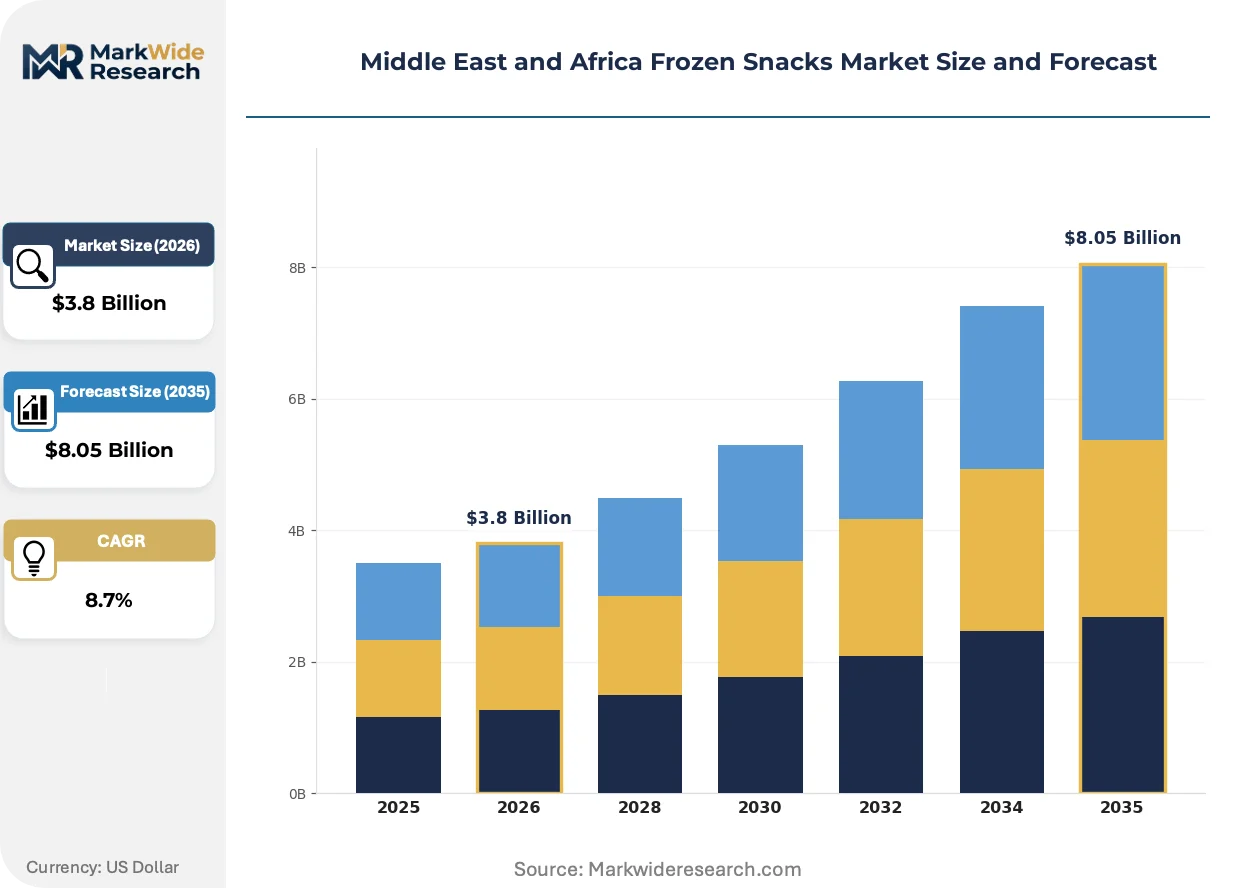
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Fries, Frozen Vegetables, Frozen Meat, Frozen Desserts End User: Restaurants, Catering Services, Retail Consumers, Food Distributors Ingredient: Potato, Chicken, Fish, Vegetables Packaging Type: Bags, Boxes, Pouches, Bulk Packaging |
| Companies Covered | Al Kabeer Group ME, BRF SA, McCain Foods Limited, AlKaramah Dough, JBS SA, Sunbulah Group, Avi Ltd, General Mills, Americana Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Frozen Snacks Market Shifts & Advancements
Automation of production lines and reformulation of coating systems are compressing cost structures while regulatory pressure on ingredient transparency is reshaping supplier qualification protocols across Middle Eastern and African markets.
Air-impingement freezing technology is automating the transition from blast freezing to continuous-flow processing in South African and Egyptian manufacturing plants. McCain Foods Limited and domestic processors are retrofitting potato and poultry lines to reduce cryogen consumption and labor touchpoints. This capital deployment is automating throughput scaling without proportional headcount expansion, tightening unit economics for exporters serving Gulf buyers.
Saudi Food and Drug Authority and Emirates Authority for Standardization and Metrology are synchronizing trans-fat limit proposals ahead of formal rulemaking anticipated later this decade. Frozen snack importers must pre-validate reformulated oil blends and submit compositional data for clearance. Premium-positioned halal-certified suppliers are responding fastest, leveraging existing technical documentation pipelines to maintain shelf placement.
Home-meal replacement behavior is rotating frozen snack demand toward multi-portion family packs in Saudi and UAE retail channels. Single-serve impulse formats are losing velocity as consumers stockpile for convenience and cost control. Quick-service restaurant procurement teams are mirroring this shift, negotiating larger frozen fry and nugget contracts with extended delivery windows to match their own inventory rationalization.
Middle East and Africa Frozen Snacks Market Segmentation
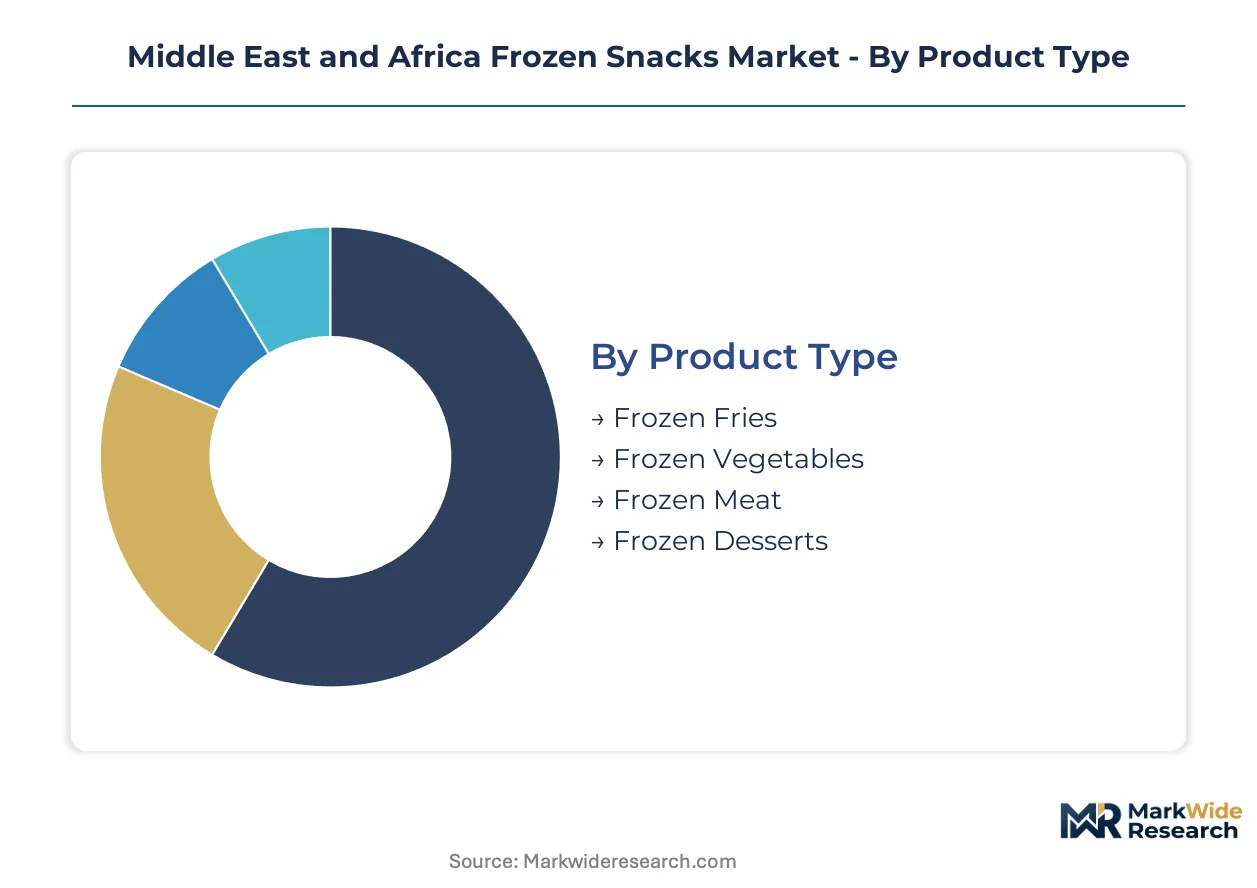
Frozen snack procurement patterns diverge sharply across buyer types and product formats in this region. Cold-chain infrastructure maturity and halal certification requirements reshape which segments capture value.
Product Type:
Margin profiles separate buyers seeking volume throughput from those prioritizing protein premiums.
- Frozen Meat:Breaded poultry and beef items command higher unit economics due to halal certification overhead and protein input costs. Quick-service restaurants across Saudi Arabia and the UAE anchor procurement volumes for this segment.
- Frozen Fries:Par-fried potato strips dominate quick-service restaurant procurement contracts through standardized sizing and fryer compatibility. McCain Foods Limited's backward integration into Egyptian and South African potato supply secures cost advantages for Gulf buyers.
- Frozen Vegetables:Battered vegetable appetizers serve catering channels seeking vegetarian options within halal-compliant menus.
- Frozen Desserts:Chilled confectionery items target retail freezers in Moroccan and Egyptian urban households with expanding home refrigeration.
Frozen fries leads volumes today; frozen meat is gaining share fastest.
End User:
Kitchen footprint compression and labor cost trajectories determine outsourcing intensity.
- Restaurants:Quick-service chains across Gulf Cooperation Council states are shrinking back-of-house space and centralizing frozen snack prep through supplier contracts. This restructuring elevates cold-chain reliability requirements for distributors.
- Retail Consumers:Home freezer penetration in Cairo and Casablanca is accelerating demand for retail-packaged formats. E-commerce frozen logistics networks are emerging to serve direct-to-consumer subscription models.
- Catering Services:Event and institutional foodservice providers source bulk frozen appetizers for consistency across high-volume occasions.
- Food Distributors:Intermediary wholesalers consolidate procurement for smaller foodservice accounts lacking direct supplier relationships.
Restaurants anchor current procurement volumes; retail consumers show the steepest expansion trajectory.
Ingredient:
Input cost volatility and sourcing geography differentiate supplier stability.
- Chicken:Poultry-based snacks depend on Brazilian and Argentine feed cost cycles. BRF SA's regional processing scale buffers Gulf buyers from spot price spikes.
- Potato:Tuber-based products leverage localized cultivation in Egypt and South Africa to reduce import dependency.
- Fish:Battered seafood items face supply concentration in specific coastal processing zones.
- Vegetables:Plant-based inputs enable reformulation flexibility as trans-fat regulations tighten across Gulf markets.
Chicken dominates value contribution; vegetable-based formulations are climbing the fastest.
Packaging Type:
Recyclability mandates and portion-size economics reshape format selection.
- Bulk Packaging:Large-format cases serve quick-service restaurant procurement teams rationalizing inventory through extended delivery windows.
- Bags:Flexible pouches dominate retail freezer placement for family-pack formats.
- Boxes:Rigid cartons protect premium-positioned items through Gulf retail channels.
- Pouches:Stand-up flexible formats target convenience-oriented retail segments.
Bulk packaging leads institutional volumes; bags are expanding most quickly in retail channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Cooperation Council quick-service restaurant chains anchor procurement volumes for frozen snacks across the Middle East and Africa, with cold-chain infrastructure investments concentrating in Saudi Arabia, UAE, South Africa, Egypt, and Morocco.
Saudi Arabia
Riyadh and Jeddah quick-service restaurants are compressing kitchen footprints and outsourcing frozen snack preparation to centralized suppliers. Saudi Food and Drug Authority cold-chain mandates are forcing distributor consolidation and professionalizing logistics networks. The Eastern Province industrial corridor hosts expanding cold storage facilities serving Gulf export routes.
United Arab Emirates
Dubai's hospitality and foodservice sectors drive premium frozen snack procurement for halal-certified formulations. Emirates Authority for Standardization and Metrology labeling requirements create clearance protocols that favor pre-certified suppliers. Abu Dhabi is emerging as a cold-chain logistics hub connecting African and Asian supply sources.
South Africa
Cape Town and Johannesburg urban retail corridors are multiplying supermarket freezer space for processed snacks faster than other African markets. National Regulator for Compulsory Specifications frozen food safety protocols shape manufacturing investments by domestic processors. The Western Cape potato belt supports backward integration for fry production serving regional quick-service restaurant contracts.
Egypt
Cairo and Alexandria households are acquiring home refrigeration units at accelerating rates, creating pull-through demand for retail-packaged frozen snacks. Egyptian cultivation of processing-grade potatoes reduces import dependency for regional fry manufacturers. The Nile Delta corridor hosts expanding production lines retrofitted with air-impingement freezing technology.
Morocco
Casablanca's urban retail freezer infrastructure is deepening penetration of family-pack frozen snack formats among middle-income households. E-commerce frozen logistics networks are emerging to serve direct-to-consumer subscription models previously constrained by temperature integrity. The Tangier-Mediterranean port complex facilitates European import clearance for specialty frozen formulations.
Middle East and Africa Frozen Snacks Market Competitive Landscape
Backward integration into raw material supply dominates the current landscape as manufacturers secure cost advantages against feed price volatility. The vendor base clusters around three strategic archetypes: multinational processors with regional production assets, domestic specialists leveraging halal certification premiums, and diversified food conglomerates with poultry or potato supply control. Capacity expansion in Egyptian and South African manufacturing plants and strategic partnerships with Gulf distributors constitute the dominant competitive moves reshaping procurement relationships.
Within the multinational processor tier, McCain Foods Limited and BRF SA exemplify scale-driven positioning through captive agricultural supply. McCain Foods Limited anchors regional fry production through potato cultivation control in Egypt and South Africa. BRF SA occupies a central position in poultry-based frozen snacks through Brazilian processing scale serving Gulf import demand. Americana Group represents the halal-specialist archetype with premium placement across Saudi and UAE retail channels.
| Leading Market Players |
|---|
| Al Kabeer Group ME |
| BRF SA |
| McCain Foods Limited |
| AlKaramah Dough |
| JBS SA |
| Sunbulah Group |
| Avi Ltd |
| General Mills |
| Americana Group |
| Others |
Supply & Pricing Matrix
Backward integration into Egyptian and South African potato cultivation anchors McCain Foods Limited's cost position and pricing power against import-dependent competitors serving Gulf buyers. This captive supply structure compresses input volatility for fry production while elevating margin buffers when Brazilian poultry feed costs spike.
Pricing Analysis
Input-cost pass-through from Brazilian and Argentine poultry feed cycles compresses frozen meat snack margins when commodity markets tighten. Three-tier pricing structure across halal-certified premium, standard commercial, and economy private-label levels separates Americana Group's retail placement from BRF SA's volume contracts and unbranded distributor offerings. Price differentiation hinges on halal certification grade and cold-chain reliability guarantees. Cost compression in economy tiers is intensifying because South African supermarket chains are expanding private-label freezer space. Quick-service restaurant procurement teams show lowest price sensitivity due to kitchen footprint outsourcing imperatives.
Supply Chain Analysis
Single-source vulnerability sits with Brazilian poultry processing concentration for Gulf-bound frozen chicken snacks. Manufacturing draws from Egypt and South Africa for potato-based products, Brazil for poultry, and European coastal zones for battered seafood inputs. Feed commodity price volatility remains the dominant structural risk. Distribution runs through Dubai's Jebel Ali port complex and Riyadh's Eastern Province cold storage corridor for Gulf penetration, with Tangier-Mediterranean serving Moroccan retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Egyptian potato cultivation costs undercut European import pricing by eliminating currency-hedged procurement for fry manufacturers.
For Market Incumbents: Cement Gulf distributor relationships through extended delivery window contracts that match quick-service restaurant inventory rationalization. Lock in cold-chain technician training partnerships before SFDA mandates deepen compliance requirements. Defensive priority rests on pre-validating trans-fat reformulation pipelines ahead of Emirates Authority for Standardization and Metrology rulemaking. For New Entrants and Emerging Players: Capture Kenya and Ethiopia's sparse urban retail freezer infrastructure before incumbent cold-chain investments arrive. Target family-pack retail formats in Casablanca and Cairo where home-meal replacement behavior accelerates fastest. Go-to-market angle centers on direct-to-consumer subscription models enabled by emerging last-mile frozen logistics networks. For Investors and Strategic Acquirers: Consolidation pressure builds where halal certification documentation pipelines create technical barriers for European and Asian suppliers lacking pre-certified production lines. Five-to-ten year viability favors processors with captive agricultural supply or established Gulf retail placement. Signal to watch: SFDA trans-fat limit finalization triggering forced reformulation costs for uncertified competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Air-Impingement Freezing Retrofit | McCain Foods Limited deploys continuous-flow processing to reduce cryogen consumption at Egyptian plants. |
| Halal Certification Pre-Validation | Americana Group leverages existing technical documentation pipelines to maintain Saudi retail shelf placement. |
| Cold-Chain Logistics Partnership | BRF SA secures distributor consolidation gains as SFDA mandates professionalize Gulf storage networks. |
| Recyclable Packaging Compliance | Early Gulf Cooperation Council mandate alignment filters supplier qualification criteria before decade closes. |
| E-Commerce Frozen Delivery Buildout | Cairo and Casablanca last-mile networks enable direct-to-consumer subscription models previously temperature-constrained. |
Research Methodology
Coverage spans Gulf Cooperation Council states, North Africa, and Sub-Saharan Africa, with primary inputs from each territory triangulated against secondary validation. Interviews with quick-service restaurant procurement directors, cold-chain logistics operators, frozen food manufacturing plant managers, and Saudi Food and Drug Authority compliance officers combined with customs trade records, SFDA regulatory filings, Emirates Authority for Standardization and Metrology technical standards, and retail freezer space audit data. Bottom-up volume modeling and top-down value reconciliation cross-validated segment outputs.
Granularity-level framing applied country-specific cold-chain maturity indices, halal certification tier differentiation, and quick-service restaurant kitchen footprint compression rates across the projection horizon. Product type, end user channel, ingredient sourcing geography, and packaging format dimensions were modeled with regional regulatory cluster overlays. CAGRs derived from trend extrapolation of freezer penetration curves and outsourcing intensity metrics. Industry-specific inputs included poultry feed cost cycle correlation and air-impingement technology adoption curves.
Feed commodity volatility, trans-fat regulatory finalization timing, and cold-chain technician availability are the dominant revision risks that could alter trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Veggie Chips Market
Snacks
North America Extruded Snack Food Market
Snacks
Savory Snacks Market
Snacks
Low Calorie Snack Foods Market
Snacks
Low Fat Protein Snacks Market
Snacks
Dairy Snacks Market
Snacks
Italy Energy Bar Market
Snacks
RTE Popcorn Market
Snacks
Europe Frozen Snacks Market
Snacks
Saudi Arabia Snack Bar Market
Snacks
Low Calorie Snacks Market
Snacks
North America Baked Chips Market
Snacks
Low Fat Crackers Market
Snacks
Europe Snacks Market
Snacks
Europe Snack Pellets Market
Snacks
Middle East and Africa Snack Pellets Market